
 Vacuum Contactor Market | 2026-2036
Vacuum Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Contactor Market Analysis
The EU Ecodesign Directive is shifting procurement criteria for medium-voltage switching equipment across European heavy industry. ABB leverages its installed base in Nordic hydropower to sustain service-contract renewals. Siemens anchors German grid modernization through localized vacuum interrupter production. Mitsubishi Electric dominates Japanese railway electrification with specialized contactor assemblies for Shinkansen feeder systems.
A vacuum contactor is an electrically operated switching device that uses a vacuum envelope to extinguish arcs between contacts, typically rated for 1 kV to 36 kV with interrupting capacities up to 63 kA; its hermetic seal eliminates oxidation and enables maintenance-free operation across millions of mechanical cycles. Medium voltage contactors command the largest revenue pool due to their lock-in within utility-scale transformer substations and mining load centers. Low voltage variants compete on price in motor-control centers where IEC 60947-4-1 compliance has become table stakes. Automatic operation mode is gaining share as remote SCADA integration replaces manual field switching in water treatment and oil & gas distribution networks.
EMA's MDR framework pressures manufacturers to document vacuum envelope integrity over full design life, while REACH compliance restricts beryllium-copper contact alloys in EU-sold units. IEC 62271-106 and GB standards in China diverge on short-circuit withstand testing protocols, fragmenting certification costs for exporters. Stakeholders must track how carbon-border adjustment mechanisms reshape sourcing economics for copper-chromium contact materials before committing to regional capacity expansion.
Market Dynamics
Vacuum contactor procurement is tightening around lifecycle cost documentation as EMA's MDR framework forces manufacturers to prove envelope integrity across multi-decade service intervals, compressing supplier qualification timelines and favoring incumbents with installed telemetry infrastructure.
Growth Catalysts
- Mining electrification:Australia's haul-truck charging infrastructure is pulling medium-voltage vacuum contactors into mobile substation deployments for autonomous electric fleets.
- EU Ecodesign Directive:Tightening energy-efficiency thresholds for industrial switching equipment are forcing replacement cycles across Germany's Ruhr industrial cluster coal-to-renewables conversions.
- Copper-chromium sintering:Advanced contact material fabrication is extending electrical endurance ratings, reducing maintenance intervals in utility-scale transformer substations.
Market Restraints
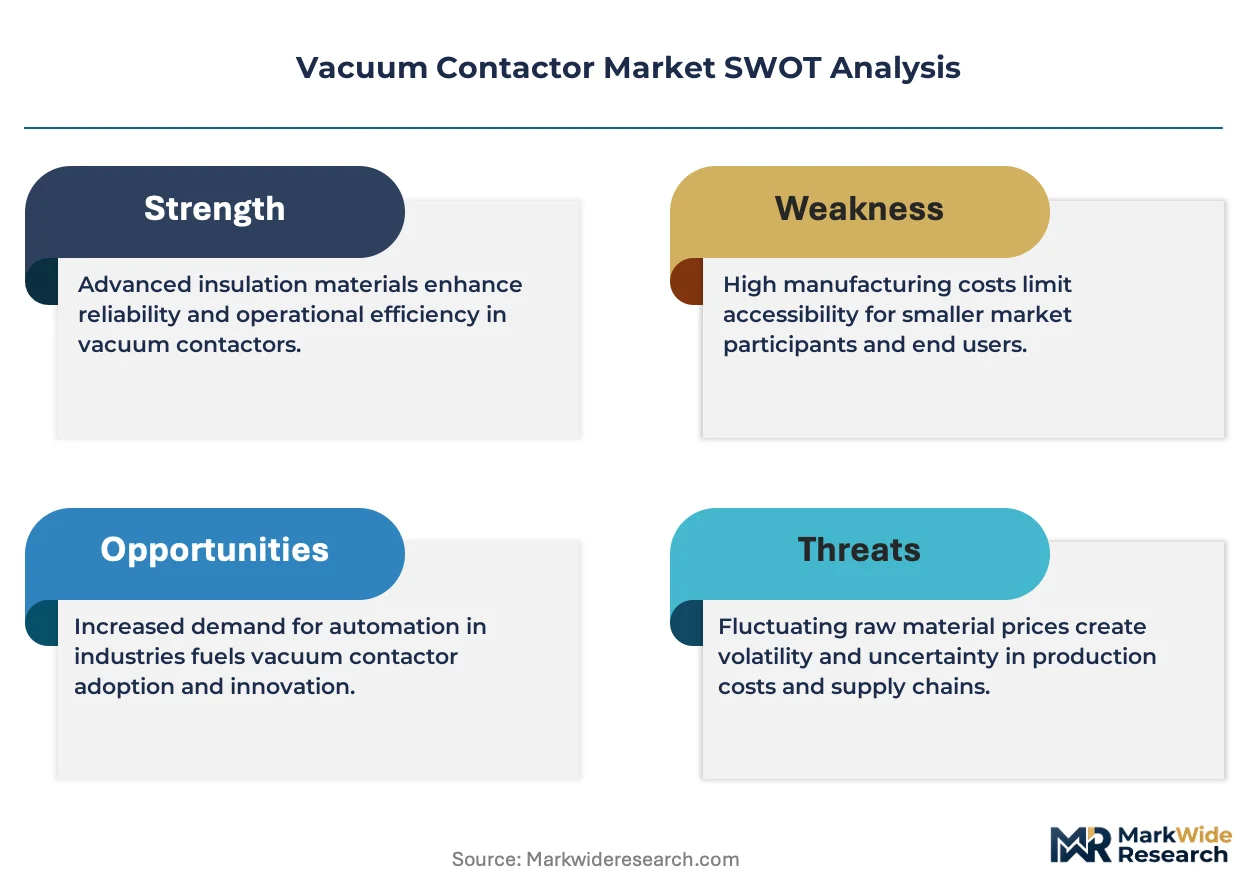
- Beryllium-copper alloy restrictions:REACH compliance is eliminating legacy contact materials from EU-sold units, forcing costly metallurgical redesigns.
- Certification fragmentation:IEC 62271-106 and China's GB standards diverge on short-circuit withstand testing protocols, multiplying validation costs for exporters.
- Solid-state circuit breaker substitution:Silicon carbide-based alternatives are encroaching on low-voltage motor-control applications where maintenance-free operation is paramount.
Strategic Opportunities
- Shinkansen feeder modernization:Japanese railway electrification programs require specialized contactor assemblies with ultra-fast reclosing capabilities.
- Carbon-border adjustment mechanisms:EU CBAM implementation is reshaping sourcing economics for copper-chromium contact materials, creating first-mover advantages for vertically integrated European producers.
- Remote SCADA integration:Automatic operation mode adoption in water treatment networks is displacing manual field switching, opening aftermarket software-service revenue streams.
Industry Challenges
- Vacuum envelope integrity verification:Non-destructive testing protocols for hermetic seals require specialized helium mass spectrometry capabilities scarce outside established manufacturing hubs.
- Legacy electromechanical integration:Retrofitting vacuum contactors into existing motor-control centers with electromechanical interlocks demands custom engineering that stretches project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Contactor Market |
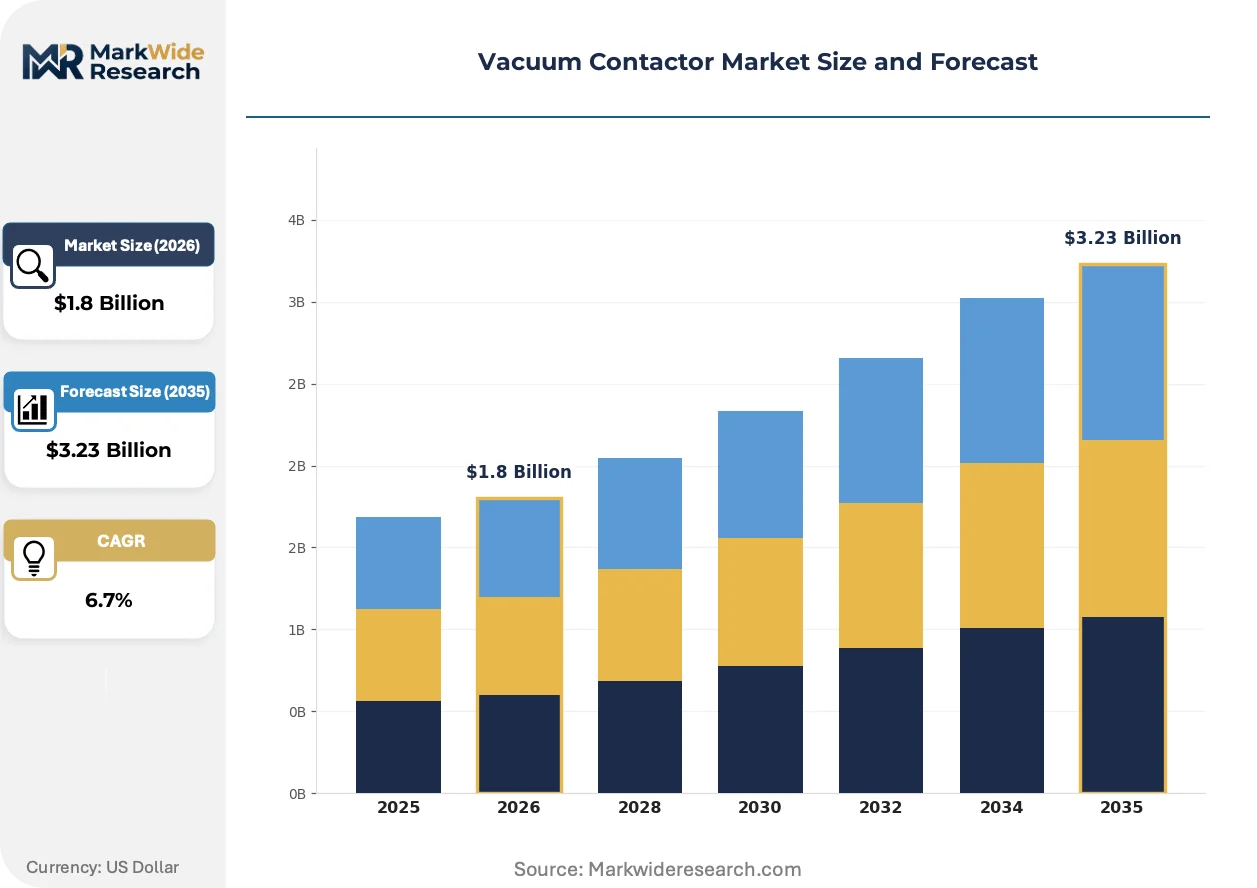
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, Low Voltage, High Voltage, Miniature End User: Industrial Automation, Power Generation, Oil & Gas, Water Treatment Installation: Indoor, Outdoor, Switchgear, Control Panel Operation Mode: Manual, Automatic, Remote, Hybrid |
| Companies Covered | Toshiba Corporation, Larsen & Toubro Limited, ABB, Mitsubishi Electric Corporation, Fuji Electric Co., Ltd., Siemens, Rockwell Automation, LS Electric, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Contactor Market Emerging Trajectories
Electrification of heavy transport and grid modernization are compressing product development cycles while forcing convergence between power electronics and traditional switching architectures.
Vacuum interrupter technology is consolidating around modular ceramic-brazed envelope designs that standardize contact gap geometry across voltage classes. Mining operators in Australia are specifying these platforms for haul-truck charging substations to reduce spare parts proliferation. The standardization is consolidating supplier tiers as smaller manufacturers lack electron beam welding capacity for ceramic-metal seals.
EU Ecodesign Directive revisions are mandating minimum electrical endurance thresholds for medium-voltage switching equipment deployed in industrial settings. German grid operators are accelerating replacement of air-break contactors in transformer substations to meet 2030 efficiency benchmarks. The regulation is concentrating procurement authority among utilities with capital reserves for fleet-wide upgrades.
Service contract unbundling is separating hardware supply from predictive maintenance analytics in water treatment and oil & gas distribution networks. System integrators are capturing margin previously held by contactor manufacturers by offering SCADA-integrated lifecycle management. The shift is most pronounced in Nordic hydropower markets where remote asset monitoring infrastructure already exists.
Vacuum Contactor Market Segmentation
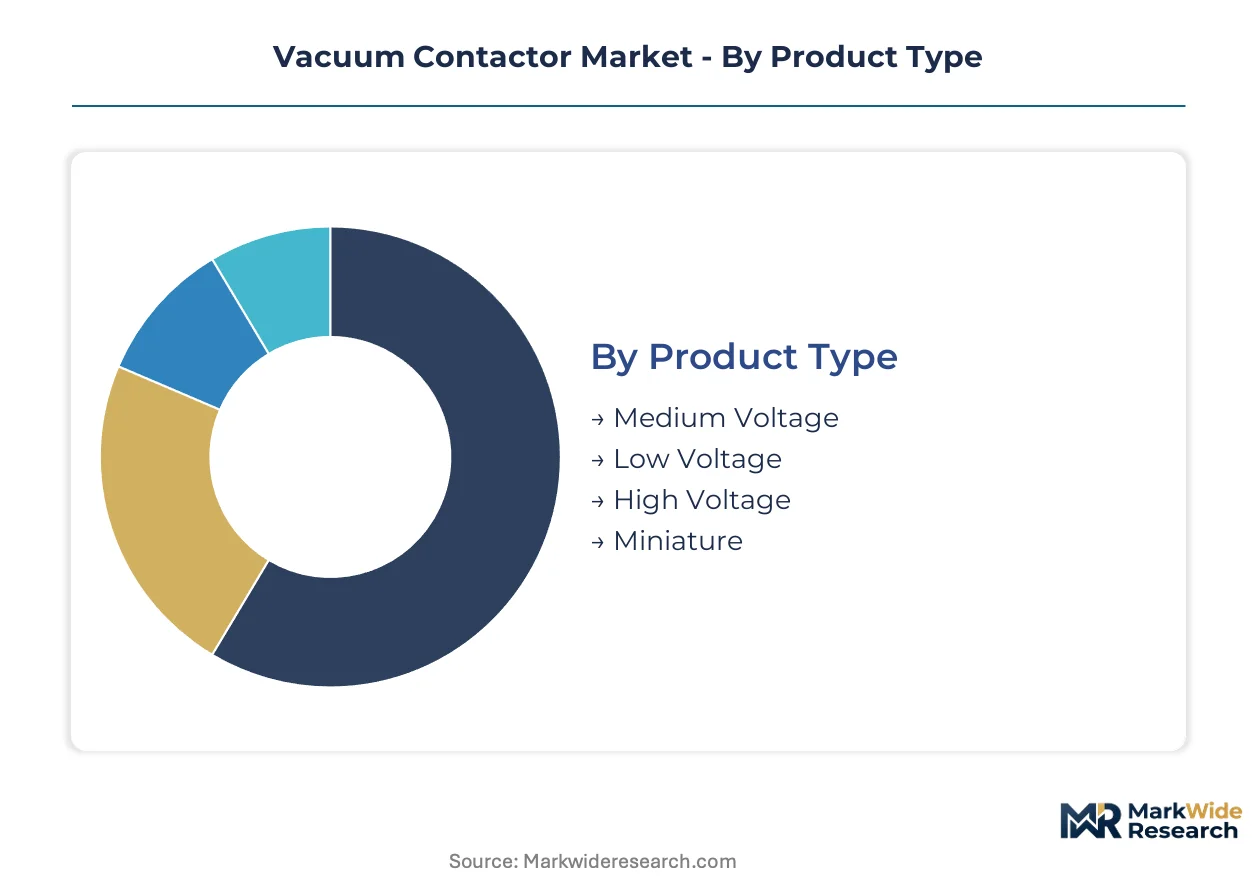
Vacuum contactor segmentation reveals how technical specifications and deployment contexts fragment procurement requirements across heavy industry. Buyers prioritize interrupting capacity, environmental sealing, and SCADA compatibility based on voltage class and operational setting.
Product Type:
Voltage rating determines capital intensity, maintenance cycles, and regulatory compliance burden for procurement teams.
- Medium Voltage:Rated 1 kV to 36 kV with interrupting capacities up to 63 kA, these units deploy in utility-scale transformer substations and mining load centers where hermetic vacuum envelopes eliminate oxidation across millions of cycles. Demand concentrates in Germany's Ruhr industrial cluster as coal-to-renewables grid conversions accelerate under EU Ecodesign Directive thresholds.
- Low Voltage:Competing on price in motor-control centers, these contactors face substitution pressure from silicon carbide-based solid-state breakers where maintenance-free operation commands premium positioning. IEC 60947-4-1 compliance has become table stakes for vendor qualification.
- High Voltage:Deployed in transmission-level switching applications requiring specialized ceramic-brazed envelope designs and electron beam welding capacity.
- Miniature:Compact form factors for space-constrained control panels and distributed automation nodes.
Medium voltage leads volumes today; low voltage is gaining share fastest as motor-control center retrofits proliferate.
End User:
Application environment dictates contact material selection, reclosing speed requirements, and telemetry integration depth.
- Industrial Automation:Motor-control centers and process manufacturing lines specify vacuum contactors for repetitive switching duty with minimal arc erosion. Australia's mining electrification programs are pulling medium-voltage units into haul-truck charging infrastructure for autonomous electric fleets.
- Power Generation:Grid-scale transformer substations require extended electrical endurance ratings enabled by advanced copper-chromium sintering techniques.
- Oil & Gas:Distribution networks prioritize automatic operation mode with remote SCADA integration to displace manual field switching.
- Water Treatment:Predictive maintenance analytics and service contract unbundling are reshaping procurement toward lifecycle management platforms.
Industrial automation anchors current demand; power generation is climbing the fastest on grid modernization timelines.
Installation:
Physical deployment context determines enclosure ratings, thermal management, and accessibility for non-destructive testing protocols.
- Indoor:Climate-controlled environments in manufacturing facilities and control rooms where standard IP ratings suffice.
- Outdoor:Substations and remote infrastructure exposed to temperature cycling, moisture, and particulate contamination requiring enhanced sealing validation.
- Switchgear:Integrated assemblies in utility and industrial distribution systems demanding modular ceramic-brazed envelope standardization.
- Control Panel:Compact integrations where miniature contactors compete on form factor and wiring density.
Switchgear dominates installed base; outdoor installations are expanding most quickly on distributed energy resource growth.
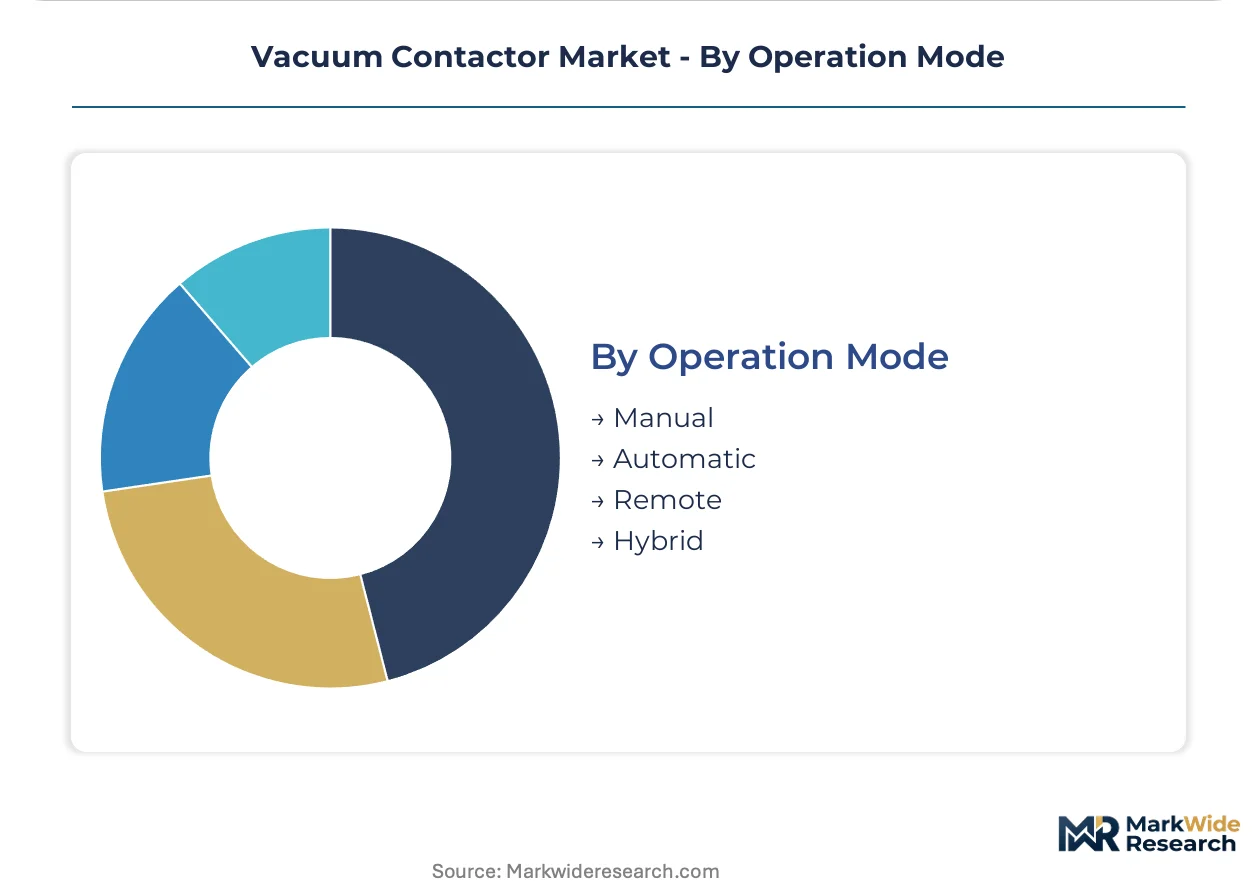
Operation Mode:
Control architecture selection reflects workforce availability, safety protocols, and telemetry infrastructure maturity.
- Manual:Direct operator actuation for maintenance procedures and emergency override functions in legacy facilities.
- Automatic:Gaining share as remote SCADA integration replaces manual field switching in water treatment and oil & gas distribution networks, opening aftermarket software-service revenue streams.
- Remote:Centralized dispatch control for geographically dispersed assets with existing fiber or wireless telemetry backbones.
- Hybrid:Configurable architectures allowing seamless transition between local manual, automatic sequence, and remote supervisory modes.
Automatic mode leads new procurement; hybrid configurations are gaining share fastest on flexibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electron beam welding technicians cluster in established manufacturing hubs where ceramic-metal sealing capabilities anchor vacuum interrupter production. Foundry-level metallurgists concentrate in copper-chromium sintering centers serving utility-scale transformer substations. Field service engineers with helium mass spectrometry expertise distribute unevenly across industrial corridors.
Germany
Ruhr industrial cluster utilities are accelerating coal-to-renewables grid conversions, pulling medium-voltage vacuum contactors into transformer substation modernization programs. EU Ecodesign Directive tightening of energy-efficiency thresholds forces replacement cycles across legacy air-break installations. Siemens anchors localized vacuum interrupter production in Bavaria to serve domestic grid operators.
China
State Grid Corporation's ultra-high voltage expansion drives procurement of specialized ceramic-brazed envelope designs for transmission-level switching. GB standards divergence from IEC 62271-106 on short-circuit withstand testing multiplies validation costs for exporters. Yangtze River Delta manufacturers concentrate electron beam welding capacity for hermetic seal production.
Australia
Mining electrification programs specify medium-voltage vacuum contactors for autonomous electric haul-truck charging infrastructure. TGA-equivalent electrical safety frameworks govern mobile substation deployments in Western Australia. Queensland mining load centers concentrate demand for maintenance-free switching equipment in remote operations.
Japan
Shinkansen feeder system modernization requires specialized contactor assemblies with ultra-fast reclosing capabilities. METI railway electrification standards mandate performance thresholds for high-speed line reliability. Kanto region manufacturers dominate domestic supply for Tokyo-Osaka corridor upgrades.
United States
FERC grid reliability directives pressure utilities to document vacuum envelope integrity across multi-decade service intervals. Appalachian coal-to-gas transition projects specify medium-voltage contactors for substation reconfiguration. Texas ERCOT market operators concentrate procurement for renewable integration switching infrastructure.
Vacuum Contactor Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the vacuum contactor value chain. Electron beam welding and ceramic-brazed envelope fabrication demand fixed-asset intensity that favors incumbents with captive metallurgical capabilities. Three strategic archetypes dominate: integrated electrical equipment conglomerates, specialized vacuum interrupter foundries, and system integrators capturing lifecycle service margins. Competitive moves concentrate on backward integration into copper-chromium contact material supply and predictive maintenance analytics unbundling.
Within the integrated conglomerate tier, Toshiba Corporation and Mitsubishi Electric Corporation exemplify producers with captive vacuum interrupter manufacturing. Fuji Electric Co., Ltd. occupies a position bridging heavy electrical equipment and precision ceramic sealing. Among European-based fabricators, ABB and Siemens anchor regional supply through localized production and service infrastructure. These archetypes represent the structural divide between vertically integrated manufacturers and component specialists dependent on external envelope sourcing.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Larsen & Toubro Limited |
| ABB |
| Mitsubishi Electric Corporation |
| Fuji Electric Co., Ltd. |
| Siemens |
| Rockwell Automation |
| LS Electric |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Copper-chromium contact material costs cascade from Yangtze River Delta sintering facilities through three distinct pricing tiers, with electron beam welding capacity scarcity concentrating premium positioning among Bavarian and Kanto region manufacturers serving grid operators and railway electrification programs.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware-only transactions from predictive maintenance analytics subscriptions in water treatment and Nordic hydropower markets. Pricing stratifies across premium, standard, and economy tiers based on certification grade—EMA MDR documentation versus basic IEC compliance—and volume scale for utility fleet deployments. Cost compression in low-voltage motor-control segments is intensifying because silicon carbide solid-state breakers erode maintenance-free positioning. Mining operators in Western Australia exhibit lowest price sensitivity due to remote operations downtime costs, while Asian distributors serving motor-control centers face acute margin pressure.
Supply Chain Analysis
Electron beam welding equipment rests on German, Japanese, and Chinese precision machinery producers, with ceramic-brazed envelope fabrication drawing from captive metallurgical capabilities in Bavaria and the Kanto region. Raw material dependencies center on copper-chromium sintered contacts, high-purity alumina ceramics, and hermetic sealing alloys. Single-source vulnerability concentrates in helium mass spectrometry validation services scarce outside established manufacturing hubs. Distribution runs through authorized electrical equipment distributors serving utility procurement departments and mining EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in service contract unbundling and copper-chromium backward integration, with premium-tier shifts toward predictive maintenance platforms capturing lifecycle value previously held by hardware-only vendors.
For Market Incumbents: Anchor service contract renewals through installed telemetry infrastructure in Nordic hydropower and German grid operator accounts. Defend against silicon carbide substitution in low-voltage motor-control by accelerating SCADA-integrated automatic operation mode certification. Prioritize captive electron beam welding capacity expansion in Bavaria to exploit EU CBAM first-mover positioning on vertically integrated copper-chromium sourcing. For New Entrants and Emerging Players: Australian mining electrification contractors represent an underserved buyer archetype seeking mobile substation contactor assemblies for autonomous haul-truck charging infrastructure. White-space targets include Queensland load centers and Western Australian TGA-equivalent mobile deployment frameworks. A specialized fast-reclosing contactor assembly for Shinkansen feeder modernization offers the most penetrable entry point, with go-to-market leverage through Japanese railway EPC partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where electron beam welding technicians and helium mass spectrometry capabilities cluster in established manufacturing hubs. Long-term viability favors vertically integrated producers with captive ceramic-brazed envelope fabrication and predictive maintenance software platforms. Acquisition targets include specialized vacuum interrupter foundries lacking service contract analytics capabilities. Watch EU carbon-border adjustment mechanism implementation timing as inflection indicator for European copper-chromium sourcing economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Materials | Captive copper-chromium sintering secures supply continuity against EU CBAM sourcing disruptions. |
| Predictive Maintenance Platform Launch | SCADA-integrated lifecycle analytics capture service margins from system integrators in water treatment networks. |
| Mobile Substation Certification | TGA-equivalent frameworks for Australian mining electrification open autonomous haul-truck charging infrastructure. |
| Ceramic-Brazed Envelope Standardization | Modular designs reduce spare parts proliferation for mining operators and consolidate supplier tiers. |
| Helium Mass Spectrometry Capability Buildout | Non-destructive vacuum envelope testing infrastructure defends against quality verification bottlenecks. |
Methodological Framework
Coverage spans Germany, China, Australia, Japan, and the United States, with primary inputs from each combining interviews with utility planning officers, mining maintenance directors, railway electrification engineers, and vacuum interrupter manufacturing plant managers alongside secondary validation from IEC standards documentation, SEC filings of listed electrical equipment producers, FERC grid reliability directives, and EU Ecodesign Directive regulatory texts. Bottom-up and top-down triangulation cross-validated segment-level demand against aggregate market sizing.
Granularity-level modeling deployed voltage class, end-use application, installation environment, and operation mode as core segmentation dimensions across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles, regulatory mandate timelines, and electrification program commitments. Industry-specific forecast inputs incorporated State Grid Corporation ultra-high voltage expansion schedules and German coal-to-renewables grid conversion acceleration under EU Ecodesign thresholds.
Inputs from utility procurement databases and railway electrification program disclosures were available through the study window; gaps in autonomous mining fleet deployment timelines introduce uncertainty bands around Australian demand projections. Forecasts reflect assumptions on copper-chromium material cost trajectories, electron beam welding capacity expansion rates, and solid-state breaker substitution velocity in low-voltage segments. A small set of named triggers—EU CBAM implementation timing, EMA MDR enforcement stringency, and Shinkansen feeder modernization contract awards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Global Dehydrating Breather Market