
 High Voltage Electric Capacitor Market | 2026-2036
High Voltage Electric Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Electric Capacitor Market Insights
The capability gap between vertically integrated film specialists and assembly-dependent competitors is unwinding competitive stability across the high voltage electric capacitor landscape. TDK Corporation leverages in-house polypropylene film extrusion to sustain margin control across pulse power applications. KEMET anchors its position through ceramic dielectric expertise for military systems requiring MIL-PRF reliability grades. Vishay Intertechnology competes by dominating niche high-voltage ceramic segments where custom geometries command premium positioning.
High voltage electric capacitors store and release electrical energy at ratings typically exceeding 1 kV, employing dielectric materials such as polypropylene film, aluminum oxide, or barium titanate ceramic to withstand intense electric field stress without breakdown; their primary purpose centers on power conditioning, energy buffering, and transient suppression in heavy electrical infrastructure. Film capacitors occupy the dominant volume position across DC link installations in renewable power plants where polypropylene's self-healing properties extend operational life under cyclic thermal loads. Ceramic variants lead in snubber applications across high voltage equipment due to their low equivalent series resistance and compact footprint at elevated frequencies. Electrolytic technology retains cost advantages in power factor correction deployments for utility providers managing legacy grid stabilization assets.
FERC grid interconnection standards and the EPA's evolving efficiency mandates for power transmission infrastructure shape product certification requirements and procurement timelines across North American utility markets. IEC 61071 and IEEE 1036 establish dielectric withstand and thermal cycling benchmarks that manufacturers must satisfy for access to railway traction and defense contractor supply chains. Stakeholders must weigh dielectric material transitions against established qualification cycles when allocating R&D resources across emerging wide-bandgap power electronics platforms.
Market Dynamics
Polypropylene film supply concentration in East Asian extrusion facilities is forcing European and North American capacitor manufacturers to renegotiate long-term feedstock contracts or accelerate backward integration programs.
Growth Catalysts
- GB Standard Alignment:China's dual carbon goals and updated GB standards for power electronics are accelerating domestic film capacitor production for renewable inverter systems.
- Rail Electrification Surge:Germany's industrial corridor is concentrating procurement of DC link capacitors as federal rail modernization programs expand traction power infrastructure.
- IEC 61071 Certification:Railway traction suppliers are expanding qualified component inventories to meet dielectric withstand benchmarks for high-voltage equipment deployment.
Market Restraints
- Polypropylene Resin Volatility:Feedstock costs for biaxially oriented polypropylene film fluctuate with propylene monomer pricing tied to Asian petrochemical capacity.
- East Asian Supply Concentration:Over 70% of metallized film substrate production resides in China, South Korea, and Japan, creating geographic risk for Western assemblers.
- Aluminum Electrolytic Substitution Ceiling:Wet aluminum technology retains cost advantages in utility-scale power factor correction, limiting film capacitor penetration in legacy grid assets.
Strategic Opportunities
- Indian Renewable Buildout:The country's solar park and wind corridor expansions under CEA grid codes are creating demand for DC link capacitors in inverter systems.
- Wide-Bandgap Convergence:Silicon carbide power modules operating at elevated switching frequencies require ceramic capacitor pairing for snubber applications.
- US IRA Manufacturing Credits:Domestic content bonuses for clean energy infrastructure are incentivizing North American capacitor assembly investment.
Industry Challenges
- Metallization Process Expertise Gap:Thin-film vacuum deposition technicians with pulse power experience command premium compensation across defense and medical equipment sectors.
- MIL-PRF Qualification Timelines:Military reliability grade certification cycles extend 18-24 months, compressing product development windows for defense contractors.
- Legacy Grid Integration Friction:Film capacitor banks replacing oil-filled units in aging substations require custom buswork and thermal management retrofit engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Electric Capacitor Market |
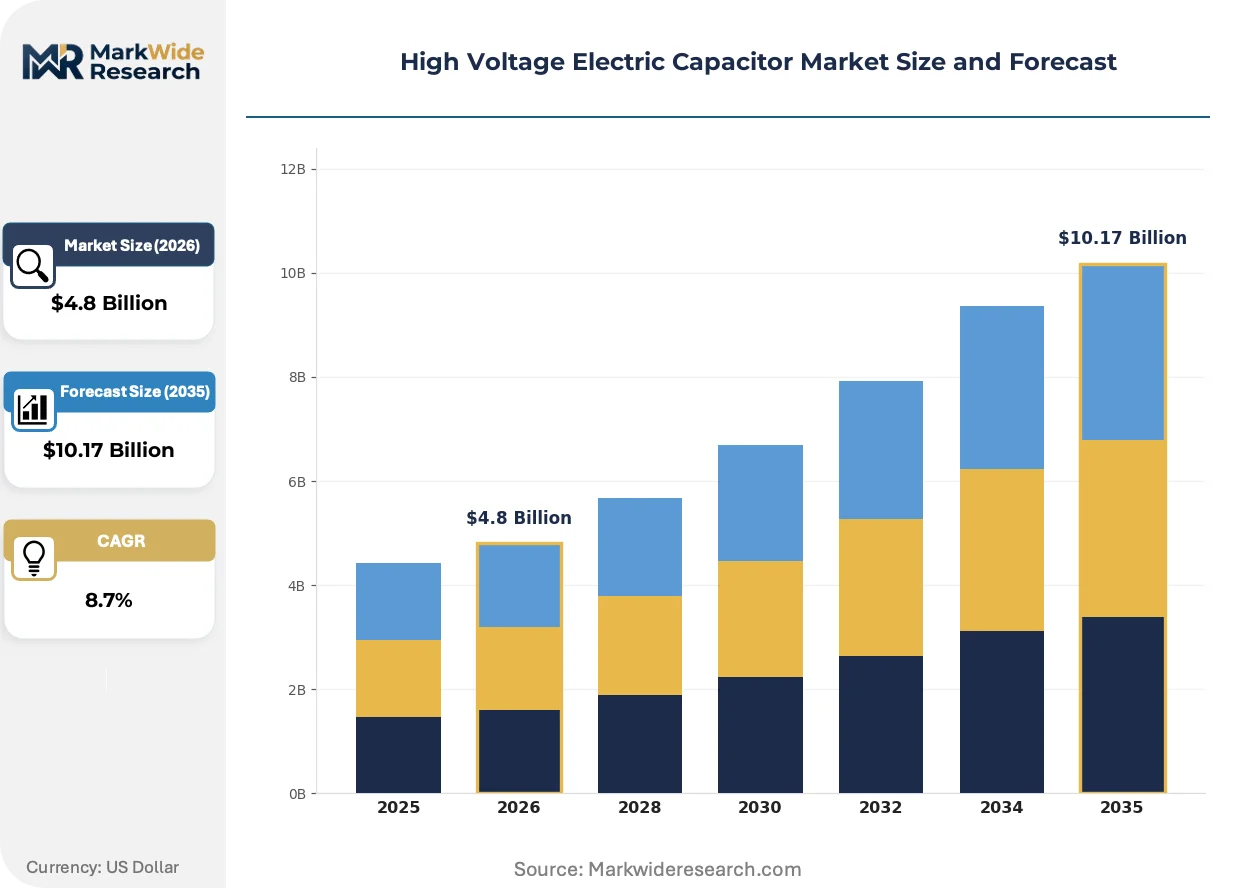
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Capacitors, Ceramic Capacitors, Electrolytic Capacitors, Paper Capacitors Technology: Pulse Power, DC Link, Snubber, Power Factor Correction, Filter Capacitors Application: Power Transmission, Renewable Power Plants, Railway Traction, Military Systems, High Voltage Equipment End User Industry: Energy Producers, Rail Operators, Defense Contractors, Electronics Manufacturers, Utility Providers |
| Companies Covered | TDK Corporation, Murata Manufacturing, Panasonic Holdings, KYOCERA AVX Components, Nichicon Corporation, Rubycon Corporation, KEMET, Vishay Intertechnology, Cornell Dubilier Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Electric Capacitor Market Trends and Innovations
Dielectric material science and power electronics architecture are converging to redefine performance benchmarks across heavy electrical infrastructure. Manufacturers are repositioning around thermal cycling durability and frequency response characteristics.
Self-healing metallized polypropylene film is displacing conventional foil electrode construction in DC link applications for renewable inverters. Wind and solar developers are specifying this technology for 100,000-hour operational life targets. The shift is compressing warranty reserve requirements and enabling longer service intervals for offshore wind platforms.
REACH substance restrictions on perfluorinated compounds are forcing reformulation of capacitor impregnation fluids used in high-voltage power factor correction units. European manufacturers are accelerating bio-based synthetic ester adoption to maintain CE marking compliance. Railway traction suppliers face the steepest reformulation timelines given IEC 61071 thermal cycling validation requirements.
Power plant developers are consolidating procurement through engineering-procurement-construction contractors rather than component distributors. Tier-one EPCs are negotiating frame agreements directly with capacitor manufacturers for multi-gigawatt renewable portfolios. This channel compression is most visible in Germany and Spain where utility-scale solar auctions concentrate buyer power.
High Voltage Electric Capacitor Market Segmentation
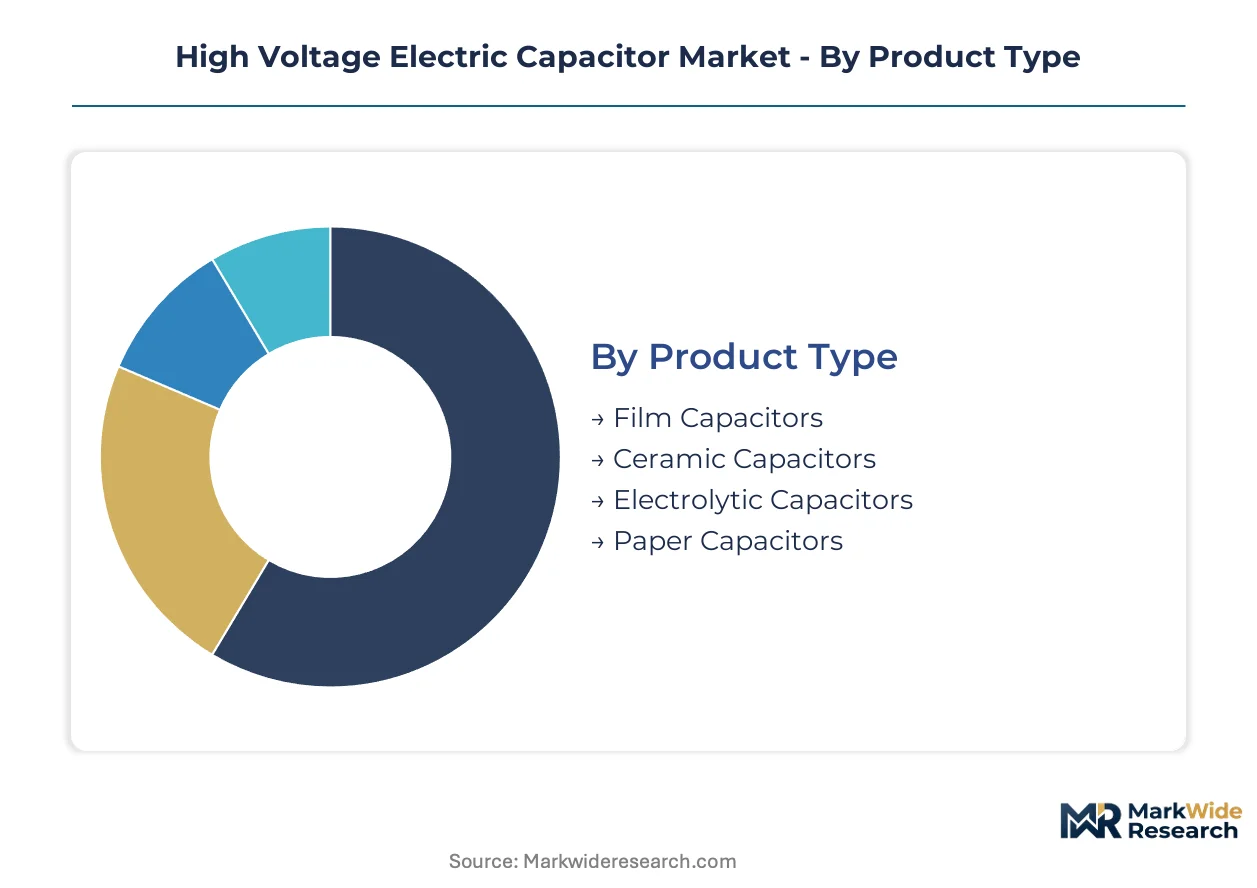
Segmentation in the high voltage electric capacitor market reveals how dielectric material choices, application architectures, and end-use reliability requirements fragment procurement patterns. Manufacturers configure production lines around specific certification grades rather than attempting universal coverage.
Product Type:
Margin pools concentrate in film and ceramic technologies where material science expertise creates defendable positioning against commodity assemblers.
- Film Capacitors:Polypropylene dielectric layers with metallized or foil electrodes dominate DC link installations across renewable inverter systems. Wind developers in Germany specify self-healing metallized film for offshore platforms where maintenance access is severely constrained.
- Ceramic Capacitors:Barium titanate formulations achieve compact footprints with low equivalent series resistance for high-frequency snubber applications. Silicon carbide power module deployments in railway traction are accelerating procurement of Class 2 ceramic dielectrics rated above 3 kV.
- Electrolytic Capacitors:Aluminum oxide dielectric with liquid electrolyte retains cost advantages in utility-scale power factor correction banks.
- Paper Capacitors:Oil-impregnated kraft paper construction persists in legacy high-voltage equipment where replacement cycles extend decades.
The dominant share belongs to Film Capacitors, while Ceramic Capacitors is closing the gap fastest.
Technology:
Application-specific thermal and electrical stress profiles determine which technology families capture design wins in heavy electrical infrastructure.
- DC Link:Energy buffering between rectifier and inverter stages in variable-frequency drives and renewable power conversion. China's solar park buildouts under GB/T 37408 standards are specifying DC link capacitors with 100,000-hour life targets.
- Snubber:Transient voltage suppression across semiconductor switching devices to limit dv/dt stress. Wide-bandgap silicon carbide modules operating above 50 kHz switching frequencies demand ceramic snubber pairing for thermal management.
- Pulse Power:Rapid energy discharge for medical equipment, defense systems, and scientific applications requiring microsecond response times.
- Power Factor Correction:Reactive power compensation for grid stability and utility demand charge reduction.
- Filter Capacitors:Harmonic attenuation in power conditioning equipment for sensitive industrial loads.
DC Link technology commands the largest installed base, though Snubber applications are expanding most quickly alongside wide-bandgap semiconductor adoption.
Application:
End-use environments range from controlled indoor substations to severe marine and traction conditions, fragmenting qualification requirements.
- Renewable Power Plants:Inverter systems for solar and wind generation require DC link capacitors with cyclic thermal durability. Indian solar park developers under CEA grid codes are consolidating procurement through EPC contractors for multi-gigawatt portfolios.
- Railway Traction:Traction power supplies and onboard converter systems demand IEC 61071-certified components with dielectric withstand validation. Germany's federal rail modernization is concentrating procurement in the industrial corridor around Munich and Nuremberg.
- Power Transmission:Grid interconnection and substation equipment for utility infrastructure.
- Military Systems:MIL-PRF reliability grade components for defense electronics with extended qualification cycles.
- High Voltage Equipment:General industrial and scientific applications above 1 kV operating voltage.
Renewable Power Plants hold the dominant application share, with Railway Traction gaining share fastest on electrification program expansion.
End User Industry:
Customer concentration and procurement channel structure vary sharply across defense, utility, and industrial buyer segments.
- Energy Producers:Wind and solar developers specifying long-life components for remote installations with limited maintenance access.
- Rail Operators:Federal and regional railway authorities with standardized traction power specifications.
- Defense Contractors:Prime contractors requiring 18-24 month MIL-PRF qualification cycles for mission-critical systems.
- Electronics Manufacturers:Industrial drive and power supply OEMs integrating capacitors into finished equipment.
- Utility Providers:Grid operators managing legacy power factor correction assets and new interconnection infrastructure.
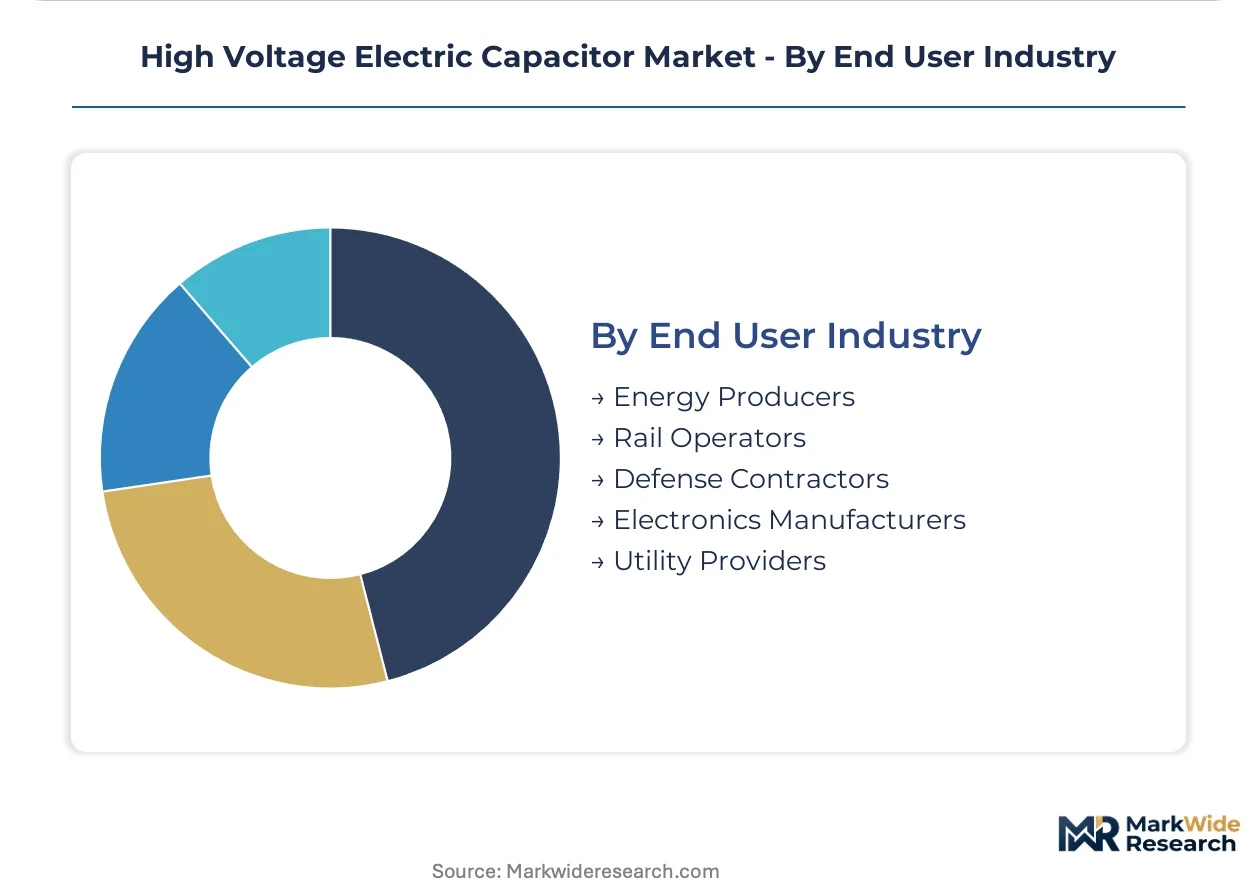
Energy Producers represent the largest demand concentration, while Defense Contractors show the steepest expansion trajectory on electrification of military platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in Germany and China demonstrate low price elasticity for certified DC link capacitors, while Indian solar developers prioritize cost compression in procurement negotiations. Renewable auction mechanics and rail electrification timelines are fragmenting demand responsiveness across national markets.
China
Domestic film capacitor production is accelerating under GB/T 37408 standards for power electronics and national dual carbon targets. MIIT industrial policy directs capacity expansion toward renewable inverter supply chains. The Yangtze River Delta cluster around Shanghai concentrates metallized film substrate manufacturing for both captive use and export.
Germany
Federal rail modernization programs are concentrating DC link capacitor procurement in the Munich-Nuremberg industrial corridor. KBA traction certification requirements and EU Green Deal infrastructure funding shape supplier qualification timelines. Bavarian capacitor assemblers are negotiating long-term polypropylene feedstock contracts to offset East Asian supply concentration.
United States
IRA domestic content bonuses for clean energy infrastructure are incentivizing North American assembly investment. FERC grid interconnection standards and EPA transmission efficiency mandates compress product certification cycles. Texas and California utility-scale solar buildouts are consolidating procurement through engineering-procurement-construction contractors.
India
Solar park and wind corridor expansions under CEA grid codes are creating demand for DC link capacitors in inverter systems. PLI scheme incentives for power electronics manufacturing attract component assembly investment. Gujarat and Tamil Nadu industrial zones are emerging as procurement concentration points for renewable EPCs.
Japan
Railway traction suppliers are expanding qualified component inventories to meet IEC 61071 dielectric withstand benchmarks. METI energy efficiency standards for power electronics drive ceramic capacitor pairing with silicon carbide modules. Kansai and Chubu manufacturing belts maintain specialized metallization process expertise for pulse power applications.
High Voltage Electric Capacitor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the high voltage electric capacitor landscape. Vertically integrated film specialists with captive polypropylene extrusion capabilities command margin control in pulse power segments. Assembly-dependent competitors compete on volume scale and distributor channel access. Strategic moves concentrate on backward integration into metallized film production and direct EPC contractor frame agreements for multi-gigawatt renewable portfolios.
Among Japanese and European component manufacturers, TDK Corporation and KEMET occupy positions representing dielectric material expertise archetypes. Vishay Intertechnology anchors a niche positioning vector where custom geometries command premium placement. These three exemplify how geographic origin and corporate structure suffixes signal strategic orientation without requiring operational specificity.
| Leading Market Players |
|---|
| TDK Corporation |
| Murata Manufacturing |
| Panasonic Holdings |
| KYOCERA AVX Components |
| Nichicon Corporation |
| Rubycon Corporation |
| KEMET |
| Vishay Intertechnology |
| Cornell Dubilier Electronics |
| Others |
Pricing and Supply Chain Analysis
Self-healing metallized polypropylene film displacing conventional foil electrode construction simultaneously concentrates supply geography in East Asian extrusion clusters and compresses pricing economics for Western assemblers lacking backward integration. This substitution dynamic rewards capacitor manufacturers with captive film production while forcing contract-dependent competitors into margin-eroding feedstock renegotiations.
Pricing Analysis
After-sales service contracts and extended warranty coverage now drive lifetime value more than unit hardware margins. Three-tier pricing structure across MIL-PRF certified premium, IEC 61071 industrial standard, and economy unqualified tiers separates defense contractors from railway traction suppliers from commodity distributors. Cost compression in the economy tier intensifies because Indian solar developers prioritize capital expenditure minimization over life-cycle cost. Defense contractors show least price sensitivity given mission-critical reliability requirements and 18-24 month qualification lock-in.
Supply Chain Analysis
Strategic stockpiling of metallized film substrates dominates inventory strategy over just-in-time approaches given propylene monomer volatility and geographic concentration risk. Over 70 percent of biaxially oriented polypropylene film production resides in China, South Korea, and Japan, while aluminum foil for electrolytic electrodes draws from Chinese smelters and Russian feedstock. Single-source vulnerability in East Asian extrusion capacity exposes Western assemblers to disruption from regional energy rationing or trade restriction. Distribution runs through engineering-procurement-construction contractors consolidating multi-gigawatt renewable procurement rather than traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and field replacement programs expand faster than hardware unit sales. Remote monitoring subscriptions for offshore wind capacitor banks now outpace original equipment pricing growth in developer procurement negotiations.
For Market Incumbents: Secure captive polypropylene film extrusion capacity or long-term offtake agreements with Yangtze River Delta suppliers before feedstock contract renewal cycles. Defend margin position by accelerating IEC 61071 certification pipelines for railway traction qualification. Channel control through direct EPC frame agreements compresses distributor intermediation and locks out assembly-dependent competitors lacking metallization process expertise.
For New Entrants and Emerging Players: Certification fast-track partnerships with German KBA or Indian CEA testing laboratories compress 18-24 month qualification windows for railway traction and renewable inverter segments. White-space concentration in Indian solar park procurement under PLI scheme incentives offers penetrable volume without entrenched incumbent relationships. Go-to-market execution through EPC contractor direct solicitation rather than distributor channel buildout bypasses established competitive blockades.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated film specialists with captive extrusion and defense qualification heritage. Long-term viability over the next decade hinges on positioning upstream of propylene monomer volatility while capturing service-attach recurring revenue. Acquisition target archetype: mid-cap metallized film producers with pulse power technician benches and existing MIL-PRF grade production lines. The signal to watch is German federal rail electrification budget allocation crossing thresholds that trigger multi-year frame agreement negotiations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Extrusion | Captive film production insulates margin control from East Asian feedstock volatility and propylene monomer pricing swings. |
| IEC 61071 Fast-Track Certification Investment | Compressed qualification timelines capture railway traction procurement waves from German federal modernization programs. |
| Direct EPC Contractor Frame Agreements | Channel compression bypasses distributor markups and locks multi-gigawatt renewable portfolios against competitor access. |
| Predictive Maintenance Service Platform Launch | Recurring revenue attachment for offshore wind capacitor banks extends customer lifetime value beyond hardware margins. |
| Wide-Bandgap Snubber Ceramic Development | Silicon carbide power module pairing requirements create premium positioning in railway traction and industrial drive segments. |
Research Methodology
A spread of perspectives from capacitor manufacturing executives, renewable EPC procurement directors, railway traction system engineers, and defense contractor reliability specialists converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation from IEC standards documentation, FERC grid interconnection filings, and MIIT industrial policy releases. Customs data on polypropylene film trade flows and SEC filings from listed component manufacturers anchored bottom-up and top-down triangulation.
Segmentation dimensions modeled span dielectric material family, application technology architecture, end-use environment severity, and regional regulatory framework cluster. Value outputs across the projection horizon reflect installed base replacement cycles, renewable capacity addition trajectories, and rail electrification program timelines. CAGRs were derived from regression against historical capacitor procurement patterns correlated with inverter shipment data and traction power infrastructure investment disclosures.
Decision-makers should treat outputs as directional under assumptions of sustained GB standard alignment in China, continued IRA domestic content bonus availability, and stable propylene monomer pricing; material deviation would warrant model refresh. Revision becomes warranted when East Asian supply concentration triggers trade restriction or when wide-bandgap semiconductor adoption crosses inflection thresholds accelerating ceramic snubber demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Vacuum Circuit Breaker Market