
 Smart Circuit Breaker Market | 2026-2036
Smart Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Circuit Breaker Market Insights
Modular breaker configurations bundled with energy management software is broadening buyer choice beyond standalone hardware purchases. Schneider Electric leverages its integrated EcoStruxure platform to anchor premium positioning in commercial deployments. ABB Ltd competes through specialized marine and data center breaker variants that sustain technical differentiation. Siemens AG dominates European utility tenders with manufacturing scale that controls regional supply timelines.
A smart circuit breaker is an electromechanical switching device rated between 6A and 6300A that integrates sensors, microprocessors, and communication modules to enable remote monitoring, fault diagnostics, and automated load management in low- and medium-voltage power distribution systems. Miniature circuit breakers with embedded current transformers and wireless transceivers represent the most technically advanced product tier, while residual current circuit breakers command margin pools in residential safety applications due to mandatory installation codes. IoT-enabled technology segments are displacing basic electronic trip units as utilities prioritize predictive maintenance architectures, and smart grid deployments in infrastructure applications lead volume absorption.
The US Federal Energy Regulatory Commission and the EU F-Gas Regulation shape product standards through mandates on switchgear environmental performance and grid interconnection protocols. China's MIIT enforces GB standards that restrict foreign data protocols in domestically installed smart breakers, creating localized certification barriers. Stakeholders must monitor how cybersecurity requirements from IEC 62351 and national regulators redefine firmware update obligations across installed bases.
Market Dynamics
IoT-enabled predictive maintenance architectures are compressing replacement cycles for electromechanical breakers while forcing vendors to restructure around recurring software revenue rather than discrete hardware sales.
Growth Catalysts
- Grid Modernization Mandates:Distribution network operators in Germany face binding digitization requirements for medium-voltage switching equipment, accelerating procurement of intelligent breaker systems with embedded sensors and remote monitoring capabilities.
- F-Gas Regulation:The EU F-Gas Regulation is phasing down sulfur hexafluoride use in switchgear, creating technical pull for vacuum-interrupter smart breakers with lower global warming potential and integrated gas-monitoring telemetry.
- Inflation Reduction Act:The US IRA channels investment tax credits toward smart grid infrastructure upgrades, directing utility capital expenditure toward IoT-enabled distribution automation including intelligent circuit protection.
Market Restraints
- Copper and Rare Earth Volatility:Embedded current transformers and wireless transceivers depend on copper windings and neodymium magnets, exposing manufacturers to commodity price swings that compress hardware margins.
- Semiconductor Supply Concentration:Microprocessor and communication module fabrication concentrates in Taiwan and South Korea, creating single-source vulnerability for breaker firmware and connectivity subsystems.
- Cybersecurity Certification Friction:IEC 62351 compliance requirements for firmware integrity and encrypted telemetry extend product approval timelines by 8-14 months in multiple jurisdictions.
Strategic Opportunities
- Data Center Power Density:Hyperscale facilities in Virginia and Texas are specifying marine-grade breaker variants with arc-flash containment and sub-cycle fault isolation for 400V bus architectures.
- Residential Solar Integration:Net metering reforms in California and Arizona are mandating grid-interactive inverters with coordinated smart breaker control, opening retrofit demand for panel-integrated intelligent protection.
- Digital Twin Convergence:Real-time breaker telemetry fused with building energy management software is enabling predictive load balancing services that command recurring subscription revenue.
Industry Challenges
- Firmware Talent Scarcity:Embedded systems engineering for real-time power algorithms competes with automotive and aerospace sectors, elongating product development cycles and inflating compensation costs.
- Legacy Protocol Integration:DNP3 and Modbus installations in existing utility substations require protocol translation gateways that add cost, latency points, and cybersecurity attack surfaces to smart breaker deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Circuit Breaker Market |
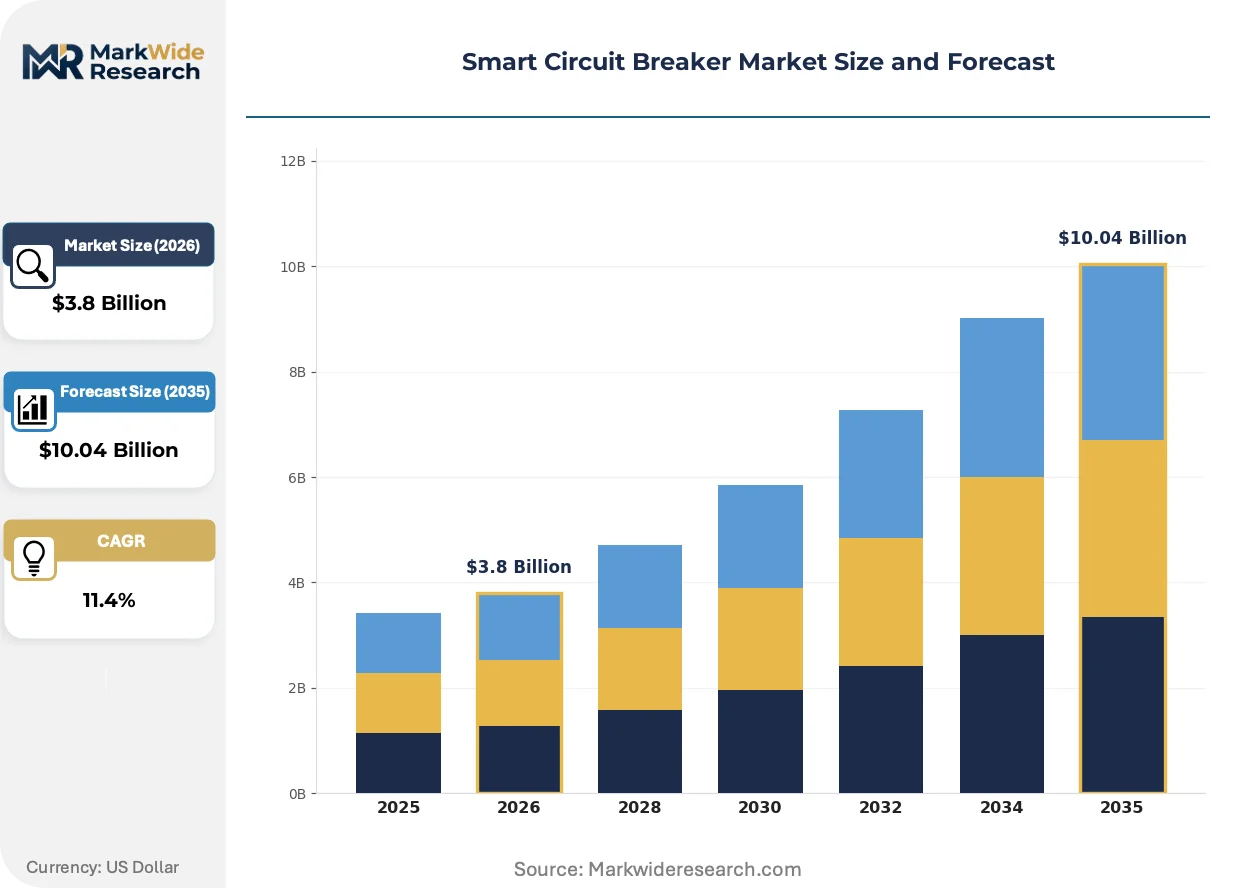
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breaker, Residual Current Circuit Breaker, Double Pole Circuit Breaker, Earth Leakage Circuit Breaker Technology: Smart Grid, IoT-Enabled, Keyless, Wireless Application: Residential, Commercial, Industrial, Infrastructure End User: Homeowners, Facility Managers, Contractors, Utilities |
| Companies Covered | Eaton Corporation, Rockwell Automation, Inc, Schneider Electric SE, Leviton Manufacturing Co., Inc., Mitsubishi Electric Corporation, ABB Ltd, Legrand SA, Honeywell International Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Circuit Breaker Market Trends and Innovations
Edge computing architectures are relocating breaker intelligence from centralized SCADA systems to device-level microprocessors, collapsing response latency while generating operational data streams that enable new service revenue models.
Miniature circuit breakers with embedded current transformers and wireless transceivers are absorbing substation-grade fault analysis into residential and commercial panelboards. Data center operators in Northern Virginia and Dallas-Fort Worth are specifying these units for 400V three-phase distribution, accepting premium pricing for sub-100ms arc-fault detection. The technology is absorbing functions previously performed by separate power quality analyzers and relay protection systems.
The EU F-Gas Regulation's phase-down of SF6 insulating gas is forcing switchgear redesign toward vacuum interrupters with integrated pressure monitoring and predictive wear algorithms. German distribution network operators now require medium-voltage smart breakers with 30-year maintenance intervals and real-time contact erosion telemetry. Manufacturers are responding with sealed-for-life vacuum bottles married to IoT-enabled spring-charge monitoring.
Utility procurement departments are unbundling hardware purchases from software licensing and field commissioning services, compressing vendor margins on initial sale while extending customer lifetime value for firms with service infrastructure. European tenders now specify outcome-based availability contracts with penalty clauses for unplanned outage duration. This model is most visible in German and French distribution grid modernization programs, where operators prioritize total cost of ownership over capital expenditure minimization.
Smart Circuit Breaker Market Segmentation
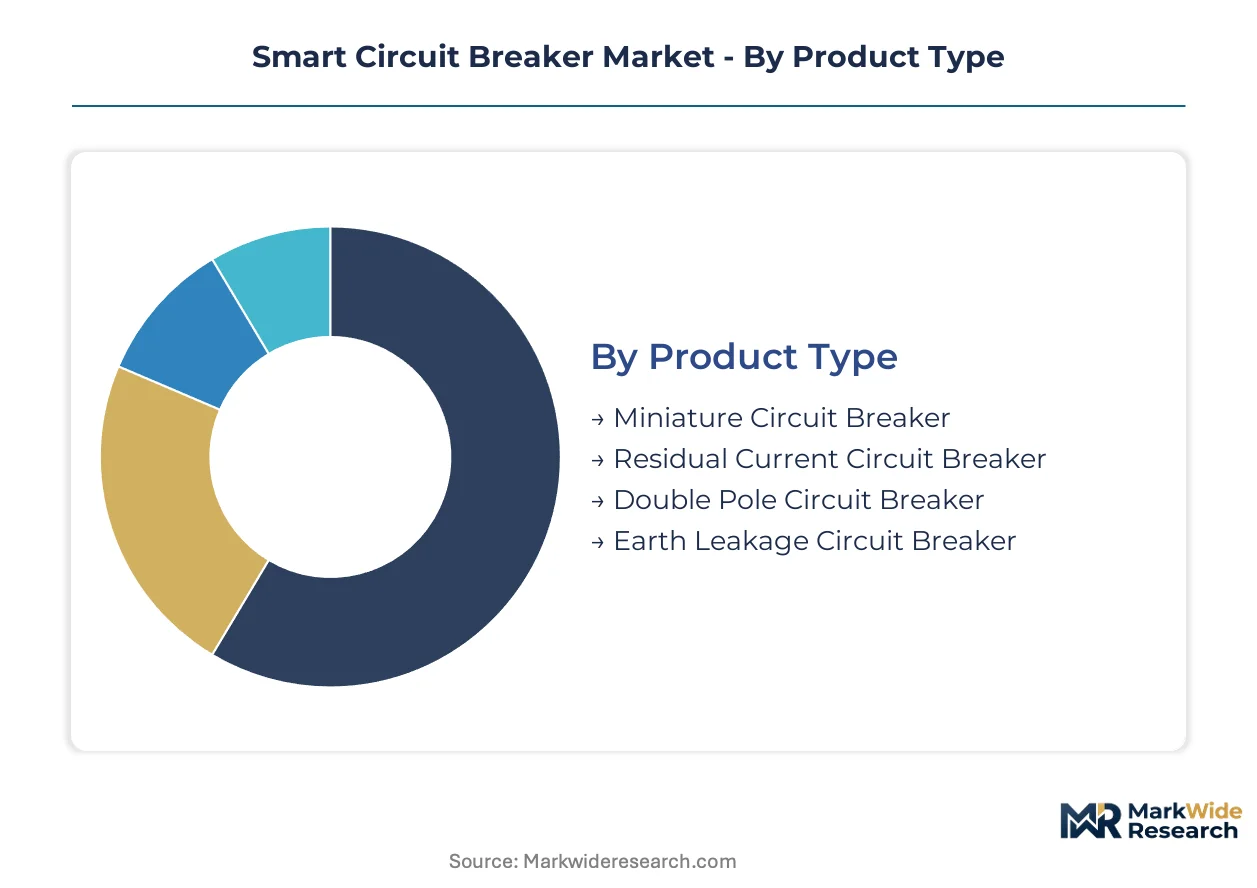
Smart circuit breaker procurement patterns diverge sharply across product architectures, connectivity protocols, and end-use voltage requirements. Certification burdens from IEC 62351 and national grid codes fragment vendor strategies, forcing specialization rather than broad portfolio coverage.
Product Type:
IEC 60947-2 and UL 489 certifications impose divergent testing protocols across breaker form factors, with miniature variants facing stricter thermal cycling requirements than earth leakage units.
- Miniature Circuit Breaker:Rated 6A to 125A with embedded current transformers and wireless transceivers, these units absorb substation-grade fault analysis into panelboard-level installations. Demand concentrates in Northern Virginia and Dallas-Fort Worth data centers specifying sub-100ms arc-fault detection for 400V three-phase distribution. The F-Gas Regulation accelerates vacuum-interrupter variants with integrated pressure monitoring.
- Residual Current Circuit Breaker:Integrating fault current detection with electromechanical tripping mechanisms, these devices command premium positioning in residential safety applications. Germany's mandatory installation codes for medium-voltage switching equipment digitization drive procurement of intelligent variants with real-time contact erosion telemetry.
- Double Pole Circuit Breaker:Simultaneous line-neutral protection for single-phase loads with synchronized trip mechanics.
- Earth Leakage Circuit Breaker:Ground fault interruption with millisecond response thresholds for wet-environment installations.
Leading the category by volume: Miniature Circuit Breaker. Growing fastest: Residual Current Circuit Breaker.
Technology:
Connectivity protocol selection determines firmware update architectures and recurring revenue potential for breaker vendors.
- IoT-Enabled:Microprocessor-controlled units with encrypted telemetry streams and predictive maintenance algorithms displace basic electronic trip units as utilities prioritize asset health monitoring. German distribution network operators mandate these for medium-voltage digitization programs.
- Smart Grid:SCADA-integrated breakers with DNP3 and Modbus protocol support enable centralized load management and demand response participation. The US Inflation Reduction Act channels investment tax credits toward these infrastructure upgrades.
- Wireless:Zigbee and LoRaWAN transceivers eliminate conduit costs in retrofit applications.
- Keyless:Biometric and NFC authentication for authorized operational access in critical facilities.
Dominating installed value: Smart Grid. Expanding most quickly: IoT-Enabled.
Application:
Voltage tier and duty cycle requirements shape breaker specification, with infrastructure deployments demanding 30-year maintenance intervals unavailable in residential products.
- Infrastructure:Medium-voltage switchgear for utility substations and grid interconnection points requiring sealed-for-life vacuum bottles with spring-charge monitoring. German and French tenders specify outcome-based availability contracts with penalty clauses for unplanned outage duration.
- Industrial:Motor protection and arc-flash containment for manufacturing facilities with high inrush current tolerance.
- Commercial:Building automation integration for load shedding and peak demand management.
- Residential:Panelboard-integrated units for solar inverter coordination under California and Arizona net metering reforms.
Highest specification intensity: Infrastructure. Steepest expansion trajectory: Residential.
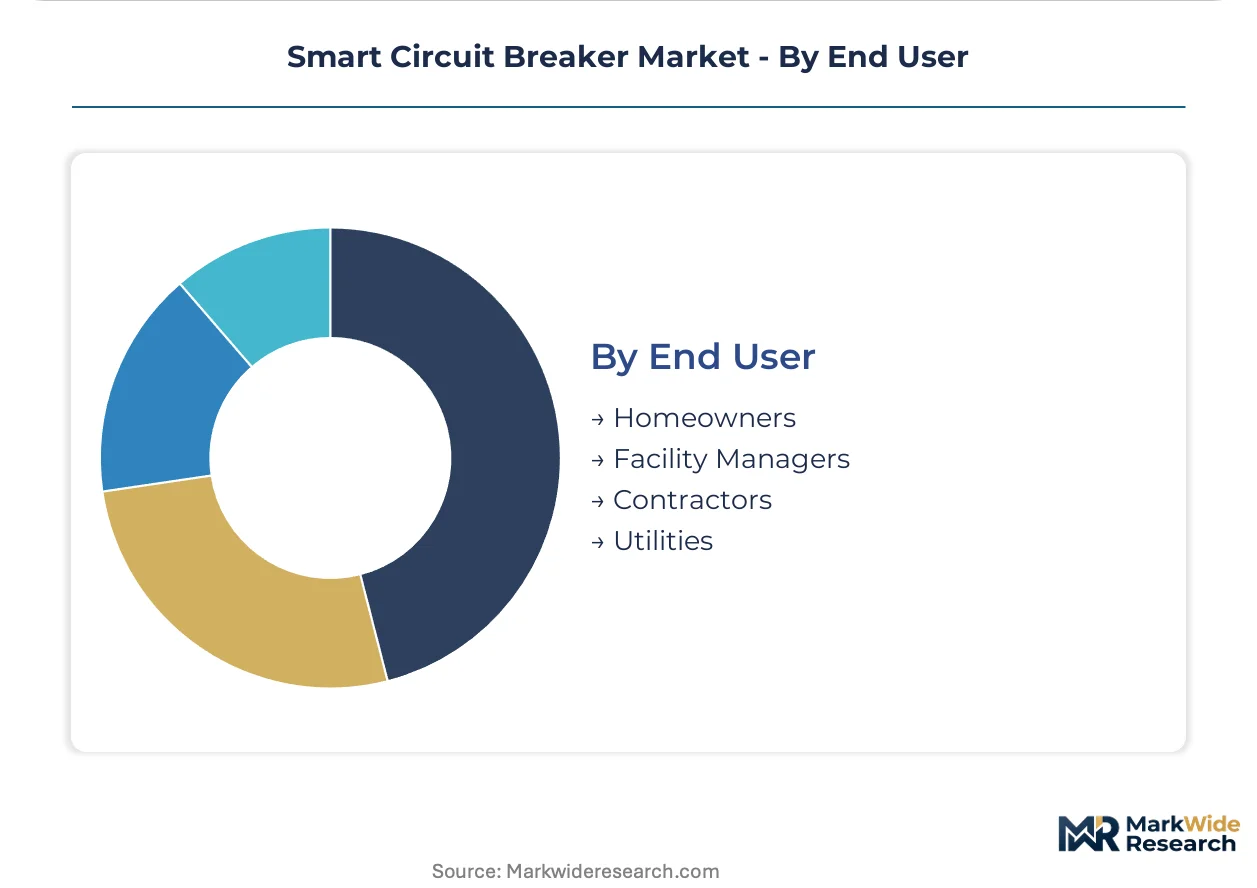
End User:
Procurement authority and technical specification capability vary dramatically across buyer types, fragmenting sales channel requirements.
- Utilities:Distribution network operators in Germany and France unbundle hardware from software licensing and field commissioning, compressing vendor margins on initial sale while extending customer lifetime value through service infrastructure. Outcome-based contracts prioritize total cost of ownership over capital expenditure minimization.
- Facility Managers:Commercial building operators specifying digital twin convergence with energy management software for predictive load balancing subscriptions.
- Contractors:Installation firms selecting protocol translation gateways for legacy DNP3 and Modbus integration.
- Homeowners:Retail purchasers of panel-integrated intelligent protection for solar retrofit projects.
Controlling procurement volume: Utilities. Gaining share fastest: Facility Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of smart circuit breakers concentrates in Germany, the United States, and China, while consumption patterns diverge based on grid modernization timelines and regulatory enforcement intensity across utility sectors.
United States
The US Inflation Reduction Act channels investment tax credits toward smart grid infrastructure upgrades, accelerating utility procurement of IoT-enabled distribution automation. FERC interconnection standards shape product certification requirements for medium-voltage switchgear deployments. Northern Virginia and Dallas-Fort Worth data center clusters specify marine-grade breaker variants with sub-100ms arc-fault detection for 400V three-phase bus architectures.
Germany
Distribution network operators face binding mandates to digitize medium-voltage switching equipment, driving sealed-for-life vacuum bottle specifications with 30-year maintenance intervals. The EU F-Gas Regulation phases down sulfur hexafluoride use, forcing vacuum-interrupter redesigns with integrated gas-monitoring telemetry. Industrial procurement in Bavaria and North Rhine-Westphalia unbundles hardware from software licensing, compressing vendor margins while extending service revenue potential.
China
MIIT enforces GB standards that restrict foreign data protocols in domestically installed smart breakers, creating localized certification barriers for imported equipment. Dual carbon goals accelerate grid digitization investments across state-owned distribution utilities. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta produce embedded current transformers and wireless transceivers for regional supply chains.
Japan
METI efficiency standards drive replacement of electromechanical breakers with microprocessor-controlled units in commercial building retrofits. JIS certification requirements fragment product specifications from IEC and UL standards. Tokyo and Osaka metropolitan areas concentrate demand for panelboard-integrated intelligent protection coordinated with building energy management systems.
India
CEA grid codes mandate communication-enabled protection devices for new substation installations, opening procurement channels for IoT-enabled breakers. The PLI scheme for power sector equipment manufacturing attracts domestic assembly investment. Maharashtra and Gujarat industrial corridors specify arc-flash containment systems for manufacturing facilities with high inrush current tolerance.
Smart Circuit Breaker Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product tiers, creating a tiered structure where scale advantages in utility tenders clash with agility in residential retrofit segments. The vendor base separates into integrated platform providers, component specialists, and regional system integrators. M&A activity concentrates on firmware capabilities and cybersecurity certifications, while capacity expansion targets vacuum interrupter fabrication for F-Gas-compliant switchgear.
Among diversified European electrical equipment manufacturers, Schneider Electric SE, ABB Ltd, and Siemens AG exemplify contrasting strategic positions. The French multinational anchors premium commercial deployments through integrated energy management platforms. The Swiss-Swedish conglomerate occupies a position in specialized industrial variants requiring technical differentiation. The German engineering group dominates European utility tenders through manufacturing scale that controls regional supply timelines. These three represent the dominant archetypes shaping competitive dynamics across infrastructure and commercial segments.
| Leading Market Players |
|---|
| Eaton Corporation |
| Rockwell Automation, Inc |
| Schneider Electric SE |
| Leviton Manufacturing Co., Inc. |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Legrand SA |
| Honeywell International Inc. |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Vacuum interrupter adoption for F-Gas compliance simultaneously compresses manufacturing cost curves and concentrates supply among German and Chinese fabricators with sealed-for-life production lines. This technology transition rewards scale players while squeezing margin pools for component assemblers without captive interrupter capacity.
Pricing Analysis
Margin tightening in utility-grade segments reflects unbundled procurement models that separate hardware from software licensing and field commissioning services. Three-tier pricing structure across premium IoT-enabled, standard electronic trip, and economy electromechanical levels stratifies by certification grade and after-sales bundling. Pricing pressure stems from copper and rare earth commodity volatility that compresses hardware margins. Residential retrofit buyers exhibit highest price sensitivity, while German distribution network operators prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale procurement tenders, while distributor networks serve commercial retrofit demand. Manufacturing concentrates in Germany, China, and the United States, with Taiwan and South Korea anchoring microprocessor and communication module fabrication. Raw material dependencies center on copper windings for current transformers, neodymium magnets for wireless transceivers, and specialized ceramics for vacuum interrupter bottles. Single-source vulnerability in semiconductor fabrication creates supply chain risk. Distribution runs through authorized system integrators for complex infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on backward integration into vacuum interrupter manufacturing and captive firmware development capacity. Players without upstream control over sealed-for-life bottle production face persistent margin compression.
For Market Incumbents: Extend service infrastructure to capture recurring revenue from outcome-based availability contracts. German and French utility tenders now penalize unplanned outage duration, favoring vendors with field commissioning networks. Invest in IEC 62351 cybersecurity certification to compress approval timelines. Capacity expansion in vacuum interrupter fabrication defends against F-Gas-driven supply bottlenecks. For New Entrants and Emerging Players: Edge computing architectures for device-level fault analysis offer a technology-first wedge against centralized SCADA incumbents. Target residential solar integration in California and Arizona, where net metering reforms mandate grid-interactive breaker coordination. Panel-integrated intelligent protection remains underpenetrated by established utility-focused vendors. Pursue direct-to-installer digital channels that bypass traditional distributor markups. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified electrical equipment conglomerates seeking firmware capabilities. Long-term viability favors vertically integrated specialists with captive vacuum interrupter production and certified cybersecurity stacks. Acquisition target archetype: mid-cap breaker manufacturers with German utility relationships and incomplete IoT platform coverage. Watch German distribution network operator tender volumes as inflection indicator for European modernization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Interrupter Backward Integration | Captive production of sealed-for-life bottles insulates margin from F-Gas supply constraints. |
| IEC 62351 Certification Investment | Pre-validated firmware integrity accelerates utility approval timelines by 8-14 months. |
| Outcome-Based Service Contracting | Availability guarantees with penalty clauses lock in decade-long customer relationships. |
| Edge Computing Architecture Development | Device-level intelligence collapses response latency below centralized SCADA thresholds. |
| Residential Solar Channel Partnership | Net metering compliance requirements in California and Arizona open retrofit demand. |
Research Methodology
Document review covered regulatory filings from FERC and EU F-Gas implementing bodies, complemented by interviews with utility planning officers, distribution network operators, smart breaker product managers, and EPC contractors specifying medium-voltage switchgear. Secondary sources included IEC standards documentation, SEC 10-K filings from listed electrical equipment manufacturers, and customs data on vacuum interrupter trade flows. Bottom-up triangulation across procurement databases and top-down validation against grid modernization budget disclosures anchored volume estimates.
Cross-reference between historical installation rates and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, connectivity protocol, voltage tier, and end-user procurement authority. CAGRs derived from regression against grid digitization investment trajectories and F-Gas phase-down timelines. Industry-specific forecast inputs encompassed German distribution network operator tender schedules and US IRA tax credit utilization patterns.
Several conditions sit outside the modeled scope, including potential cybersecurity mandate acceleration, rare earth export restriction scenarios, and breakthrough solid-state breaker commercialization. Forecasts reflect assumptions about sustained utility capital expenditure commitment and stable semiconductor fabrication capacity. Periodic stress-testing of base assumptions is recommended against copper price volatility and evolving national data sovereignty requirements for grid-connected equipment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Matrix Switches Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Touchpad Market
Switches
Asia Pacific Safety Switches Market
Switches
Static Transfer Switches Market
Switches
Temperature and Pressure Switches Market
Switches
Intelligent Power Switches Market
Switches
Smart Home Switches Market
Switches
Oil Level Switches Market
Switches
Cross Point Switch Market
Switches
Low Voltage Disconnect Switch Market
Switches
ASEAN Switchgear Market
Switches
Australia Switchgear Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
India Switchgear Market
Switches
Electric Switch Market