
 MCB and MCCB Market | 2026-2036
MCB and MCCB Market Size, Share, and Industry Trends Forecast 2026-2036
MCB and MCCB Market Outlook
The divergence between premium and commodity tiers is hardening in the MCB and MCCB market. Schneider Electric leverages its integrated energy management portfolio to command premium positioning in electronic trip-unit systems. Chint Group sustains cost leadership through captive manufacturing scale across Asia. Siemens differentiates via digital twin integration in its circuit protection platforms.
Miniature circuit breakers and molded case circuit breakers are electromechanical or electronic protective devices that interrupt fault currents when thermal or magnetic thresholds exceed rated limits, typically calibrated between 6 kA and 150 kA breaking capacity depending on frame size. MCB products dominate residential and light commercial installation volumes due to standardized DIN rail mounting and cost efficiency. MCCB units with electronic trip technology capture disproportionate margin pools in industrial and utility segments where selective coordination and remote monitoring justify specification premiums. The electromechanical segment retains volume leadership across developing markets, while electronic technology is displacing thermal-magnetic units in data center and renewable energy applications.
The US National Electrical Code and OSHA electrical safety standards mandate arc-fault and ground-fault protection in commercial installations, directly expanding addressable demand for compliant MCB configurations. China's GB 10963 and GB 14048 standards enforced by SAMR shape import eligibility and domestic procurement specifications for low-voltage breakers. Stakeholders must monitor regulatory divergence between IEC harmonized frameworks and country-specific certification requirements when configuring regional product portfolios.
Market Dynamics
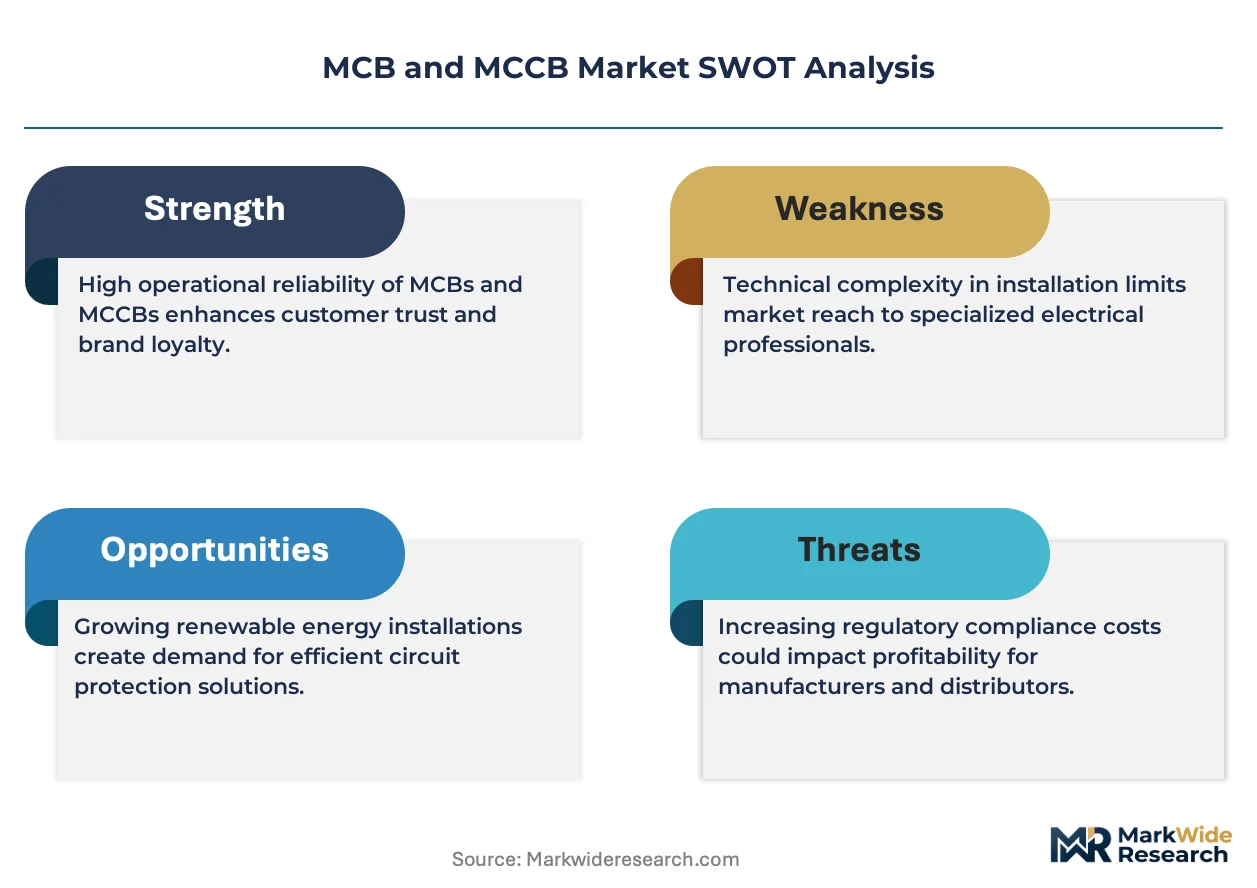
Electronic trip-unit technology is compressing margins for thermal-magnetic MCCB suppliers while concentrating procurement power among hyperscale data center operators in North America and Europe. The shift toward selective coordination and remote monitoring capabilities is forcing electromechanical specialists to defend position through cost engineering rather than specification premiums.
Growth Catalysts
- Data center rack densification:Hyperscale operators in Virginia and Frankfurt are mandating electronic trip-unit MCCBs to manage fault isolation at 50+ kW per rack without cascading failures.
- India's PLI-linked manufacturing incentives:Industrial corridor developers in Gujarat and Tamil Nadu are specifying MCB and MCCB infrastructure for new semiconductor and automotive plants.
- EU Ecodesign Directive tightening:Short-circuit breaking capacity requirements are expanding addressable demand for high-interrupting-capacity units in commercial building retrofits.
Market Restraints
- Copper and silver price volatility:Contact and conductor material costs represent 35-40% of BOM for electromechanical breakers, compressing margin stability for commodity-tier producers.
- Supply concentration in East Asian semiconductor components:Microcontroller and sensor sourcing for electronic trip units depends on Taiwan and South Korea foundry capacity.
- IEC 60947-2 certification timeline:Six-to-nine-month approval cycles for new MCCB frame sizes delay product launches and freeze development capital.
Strategic Opportunities
- Underpenetrated African commercial construction:Nigeria and Kenya are adopting DIN-rail MCB standards without legacy fuse infrastructure to displace.
- Renewable energy integration:Solar and battery storage installations require DC-rated MCCBs with electronic trip coordination, opening specification premiums outside traditional utility channels.
- Digital twin convergence:Siemens and ABB are bundling circuit protection with predictive maintenance software, creating recurring revenue attachment to hardware sales.
Industry Challenges
- Embedded firmware talent scarcity:Electronic trip-unit development requires power systems engineers with arc-fault algorithm expertise, a skill set concentrated among former relay protection specialists.
- Legacy panelboard integration friction:Retrofit contractors face physical incompatibility between new electronic MCCBs and 1980s-era busbar configurations in industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MCB and MCCB Market |
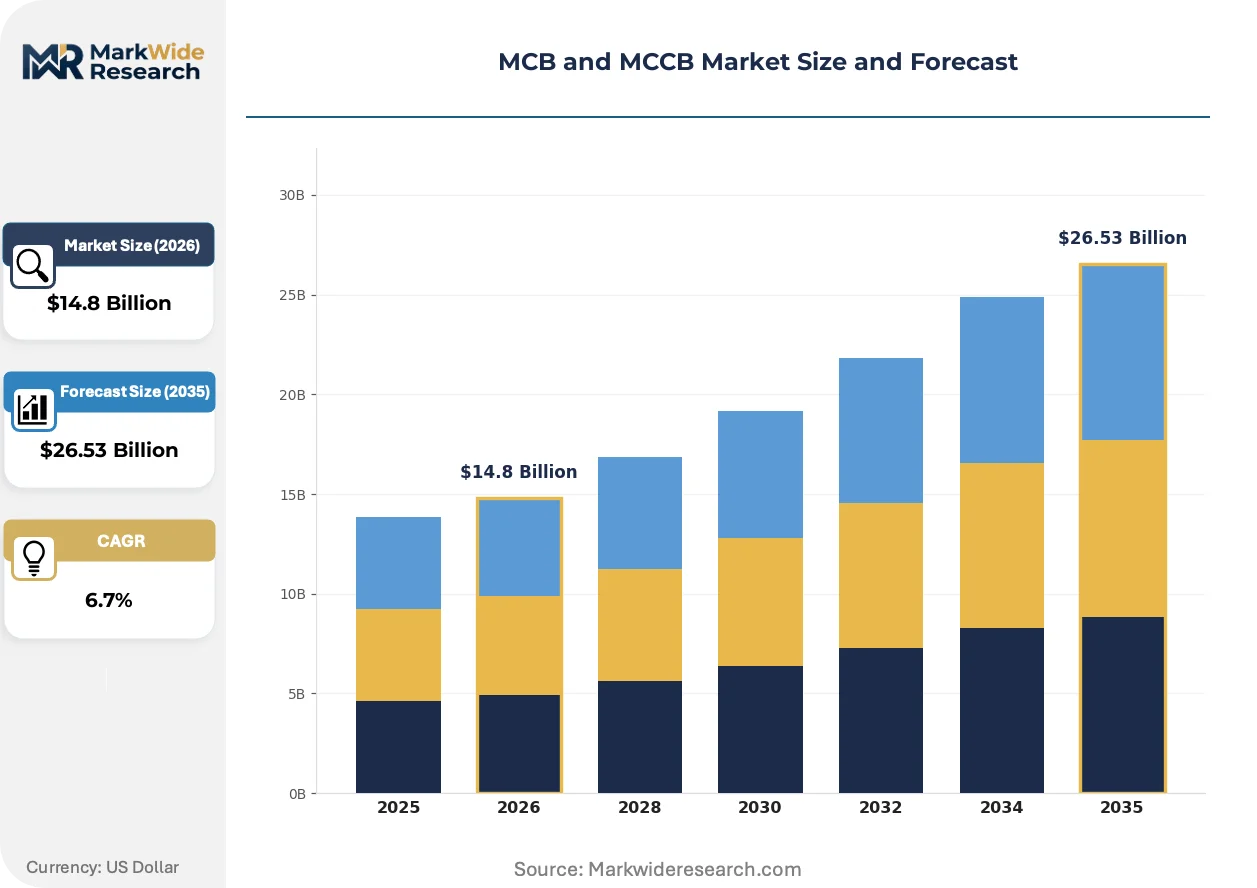
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
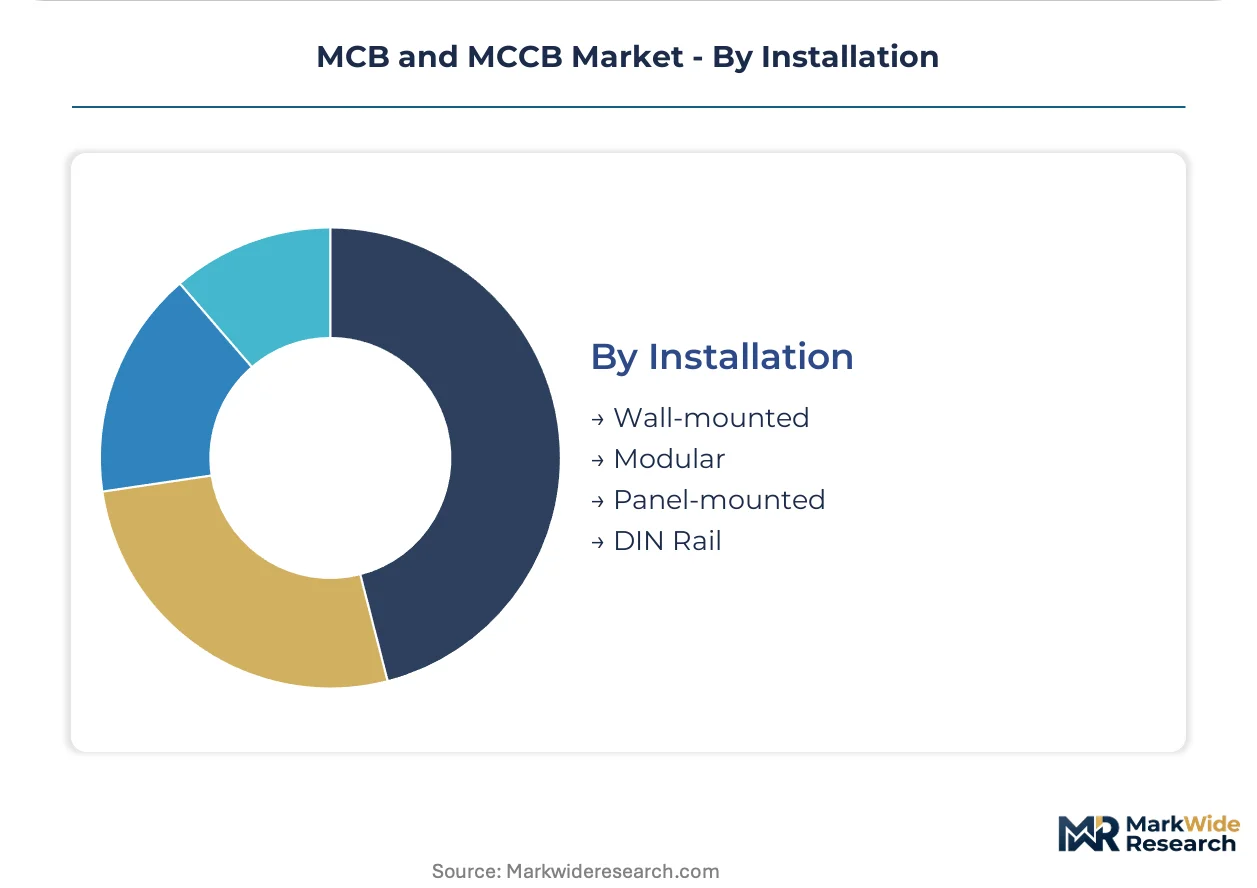
| Segmentation | Product Type: MCB, MCCB, Miniature Circuit Breakers, Motor Circuit Protectors End User: Residential, Commercial, Industrial, Utilities Technology: Electromechanical, Electronic, Thermal, Magnetic Installation: Wall-mounted, Modular, Panel-mounted, DIN Rail |
| Companies Covered | Eaton, Fuji Electric, Schneider Electric, NOARK Electric, Chint Group, Siemens, Mitsubishi Electric, Nader Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MCB and MCCB Market Strategic Shifts
Arc-fault detection intelligence is migrating from standalone devices into integrated MCB platforms, compressing the traditional separation between branch circuit protection and fire safety systems. This convergence is redrawing competitive boundaries between pure-play breaker manufacturers and building safety specialists.
Modular arc-fault circuit interrupter technology is decentralizing fire protection responsibility from centralized panels to individual branch circuits. Residential builders in California and Massachusetts are specifying AFCI-enabled MCBs to preempt NEC inspection failures. The technology is compressing demand for separate arc-fault breakers and combination AFCI-GFCI devices.
China's GB 14048.2-2020 amendments enforced by SAMR are mandating electromagnetic compatibility testing for all electronic trip-unit MCCBs above 250A frame size. Domestic manufacturers in Jiangsu and Zhejiang are absorbing six-month recertification delays. Export-oriented producers are bifurcating product lines to isolate China-specific SKUs from IEC-harmonized platforms.
Specification authority is concentrating among electrical engineering consultants for data center and healthcare verticals, displacing traditional distributor influence. Contractors in Northern Virginia and Frankfurt are accepting pre-engineered breaker coordination packages rather than assembling components independently. The shift is compressing price transparency and favoring suppliers with integrated software specification tools.
MCB and MCCB Market Segmentation
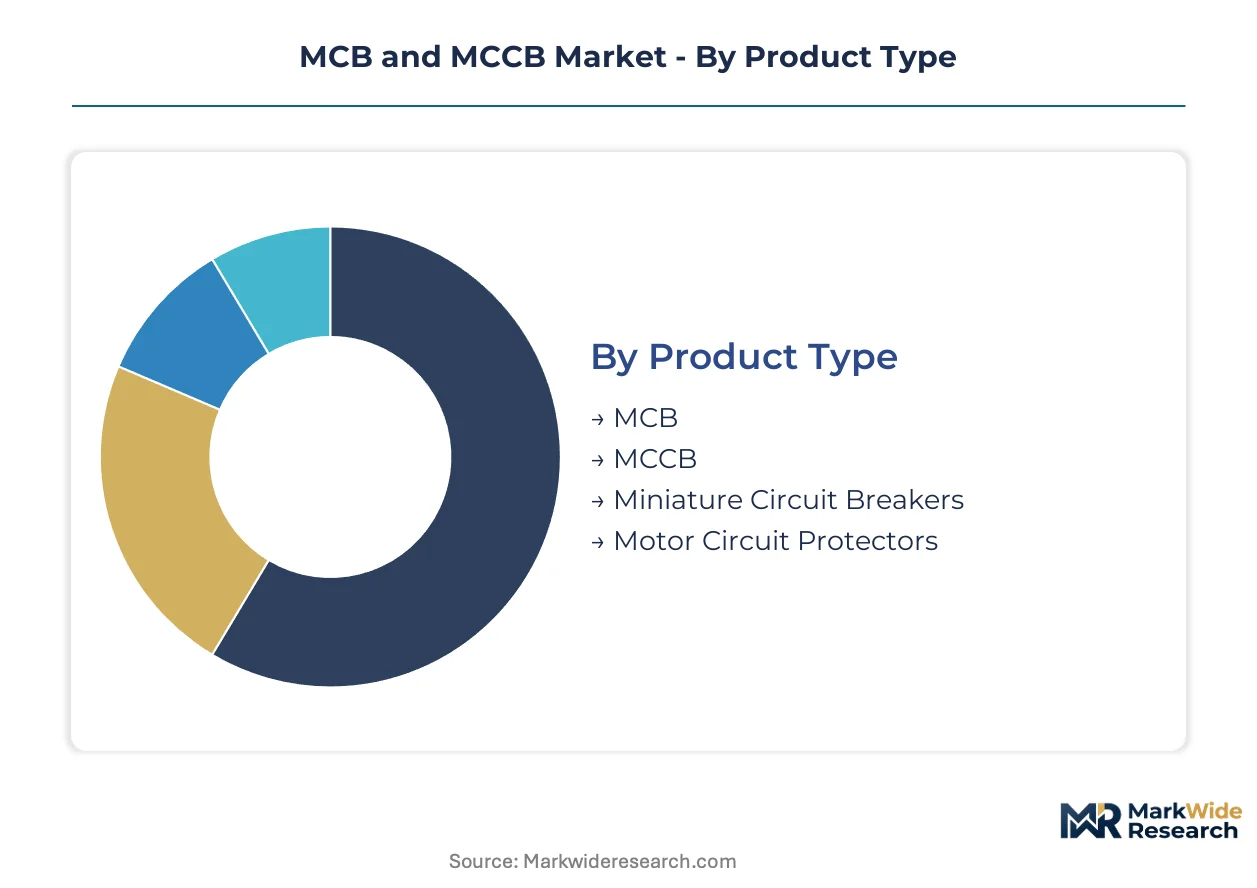
MCB and MCCB procurement decisions diverge sharply across voltage ratings, fault interruption methods, and coordination complexity. Specification authority concentrates with electrical engineering consultants in data centers and healthcare, while residential contractors prioritize cost-per-pole and DIN rail compatibility. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditizes.
Product Type:
Frame size and interrupting capacity drive buyer segmentation more than brand preference in specification-heavy verticals.
- MCB:Miniature circuit breakers with 6-10 kA breaking capacity dominate residential and light commercial installations through standardized DIN rail mounting and cost efficiency per pole. Demand concentrates in India's industrial corridors and African commercial construction where greenfield electrical infrastructure bypasses legacy fuse systems.
- MCCB:Molded case circuit breakers with 25-150 kA interrupting ratings capture specification premiums in industrial and utility applications where selective coordination prevents cascading failures. Hyperscale data center operators in Virginia and Frankfurt mandate electronic trip-unit configurations to isolate faults at 50+ kW rack densities without downstream disruption.
- Miniature Circuit Breakers:Compact 1-4 pole configurations with thermal-magnetic trip mechanisms serve branch circuit protection in multi-unit residential and small commercial retrofits across underpenetrated African markets.
- Motor Circuit Protectors:Specialized magnetic-only trip units coordinate with motor starters to protect against locked-rotor conditions in automotive and semiconductor manufacturing plants qualifying under India's PLI-linked incentives.
Volume sits with MCB; growth tilts toward MCCB.
End User:
Application environment dictates coordination complexity, remote monitoring requirements, and regulatory compliance burden.
- Residential:Single-phase and three-phase MCB installations serve branch circuit protection in new construction and electrical panel upgrades, with California and Massachusetts builders specifying AFCI-enabled units to preempt NEC inspection failures.
- Commercial:Mixed-load electrical distribution in office buildings and retail centers requires MCCB mains with MCB subfeeders, with EU Ecodesign Directive tightening driving high-interrupting-capacity retrofits across commercial building stock.
- Industrial:Motor control centers and power distribution units in automotive, semiconductor, and heavy manufacturing specify MCCBs with electronic trip units for selective coordination and arc-flash hazard reduction.
- Utilities:Substation feeder protection and renewable energy interconnection points demand high-reliability MCCBs with communications-capable trip units for SCADA integration and predictive maintenance protocols.
Commercial generates the largest addressable base; industrial commands the steepest expansion trajectory.
Technology:
Trip mechanism architecture separates commodity electromechanical supply from premium electronic specification.
- Electromechanical:Thermal-magnetic bimetallic and solenoid mechanisms provide reliable overcurrent protection at lowest unit cost, retaining volume leadership across developing markets and price-sensitive residential segments.
- Electronic:Microprocessor-based trip units with adjustable time-current curves and communications interfaces displace thermal-magnetic units in data center and renewable energy applications where selective coordination and remote monitoring justify specification premiums.
- Thermal:Bimetallic strip elements respond to sustained overload conditions with inverse-time characteristics, serving motor protection and cable derating applications in legacy industrial installations.
- Magnetic:Instantaneous solenoid trip mechanisms respond to short-circuit currents without intentional delay, protecting against fault damage in coordination with upstream devices in multi-tier protection schemes.
Electromechanical holds installed base dominance; electronic gains share fastest in specification-driven verticals.
Installation:
Mounting configuration determines panelboard compatibility, wiring labor, and retrofit feasibility.
- Wall-mounted:Surface-mounted enclosures with external operating handles serve outdoor distribution and isolated equipment protection in utility and heavy industrial environments.
- Modular:Stackable units with common busbar systems enable scalable power distribution in data center white space and prefabricated electrical skids.
- Panel-mounted:Bolted-in MCCB configurations integrate with switchgear lineups and motor control centers in industrial facilities, though legacy 1980s-era busbar dimensions create retrofit friction for new electronic trip units.
- DIN Rail:Standardized 35mm rail mounting dominates MCB installation in residential and commercial panels across IEC-aligned markets, with Nigeria and Kenya adopting this standard without legacy fuse infrastructure to displace.
DIN Rail captures residential and light commercial volume; modular configurations climb fastest in hyperscale data center buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors hyperscale data center construction, mandating electronic trip-unit MCCBs for fault isolation at 50+ kW rack densities without cascading failures.
United States
Virginia's data center corridor drives procurement of high-interrupting-capacity MCCBs as operators expand beyond 50 kW per rack. OSHA electrical safety standards and the National Electrical Code mandate arc-fault and ground-fault protection in commercial installations. Northern Virginia contractors now accept pre-engineered breaker coordination packages rather than assembling components independently.
Germany
Industrial automation and renewable energy integration fuel demand for DC-rated MCCBs with electronic trip coordination. The EU Ecodesign Directive tightens short-circuit breaking capacity requirements across commercial building retrofits. Siemens leverages digital twin integration from its Bavaria operations to bundle circuit protection with predictive maintenance software.
China
Domestic manufacturing scale and GB standards enforcement by SAMR reshape import eligibility for low-voltage breakers. GB 14048.2-2020 amendments mandate electromagnetic compatibility testing for electronic trip-unit MCCBs above 250A frame size. Jiangsu and Zhejiang manufacturers absorb six-month recertification delays while export-oriented producers bifurcate product lines.
India
PLI-linked incentives draw semiconductor and automotive manufacturing to Gujarat and Tamil Nadu industrial corridors. Central Electricity Authority regulations shape procurement specifications for new industrial electrical infrastructure. Manufacturing capacity relocation under production-linked incentive schemes concentrates MCB and MCCB demand in these coastal states.
MCB and MCCB Market Competitive Environment
Premium-margin players sit above commodity-margin players across electronic trip-unit sophistication and software integration depth. The vendor base stratifies between integrated energy management portfolios, captive manufacturing scale, and digital twin capabilities. Three archetypes dominate: full-stack electrification platforms, cost-engineered volume producers, and predictive maintenance bundlers. Consolidation pressure intensifies through strategic partnerships for semiconductor component access and selective acquisitions of arc-fault algorithm specialists.
Within the integrated platform tier, Schneider Electric and Siemens occupy positions exemplifying premium specification authority through software-anchored offerings. Chint Group anchors the scale-driven commodity segment with manufacturing concentration across Asia. ABB sits within the predictive maintenance bundler archetype, converging circuit protection hardware with digital service revenue models.
| Leading Market Players |
|---|
| Eaton |
| Fuji Electric |
| Schneider Electric |
| NOARK Electric |
| Chint Group |
| Siemens |
| Mitsubishi Electric |
| Nader Electric |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Hyperscale data center operators mandating electronic trip-unit MCCBs for 50+ kW rack densities are forcing suppliers to absorb six-to-nine-month IEC 60947-2 certification cycles and Taiwan-foundry microcontroller dependencies, compressing margin stability for commodity-tier producers while concentrating pricing power among integrated platform vendors.
Pricing Analysis
Selective coordination guarantees anchor value-based pricing for electronic trip-unit MCCBs in data center and utility applications, with Siemens and Schneider Electric capturing premiums through digital twin integration and predictive maintenance bundling. Price differentiation separates IEC-certified platforms from GB-isolated China SKUs and uncertified commodity electromechanical units. Pricing pressure stems from copper and silver contact material volatility representing 35-40% of electromechanical breaker BOM. Residential contractors in India and Africa exhibit highest price sensitivity; hyperscale operators in Virginia and Frankfurt demonstrate lowest.
Supply Chain Analysis
IEC 60947-2 and GB 14048.2-2020 electromagnetic compatibility certifications gate market access for electronic trip-unit MCCBs above 250A frame size, with six-month recertification delays bifurcating product lines. Manufacturing concentrates in China, Germany, and India. Raw material dependencies center on copper conductors, silver alloy contacts, and Taiwan-sourced microcontrollers. Single-source vulnerability in East Asian semiconductor components creates supply chain risk. Distribution runs through electrical engineering consultants for data center and healthcare verticals, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor component sourcing bottlenecks for electronic trip-unit microcontrollers are propping pricing premiums for suppliers with captive foundry relationships or strategic inventory positions.
For Market Incumbents: Acquire arc-fault algorithm specialist firms to defend against firmware talent scarcity threatening electronic trip-unit development timelines. Deepen backward integration into silver alloy contact manufacturing to offset copper price volatility compressing electromechanical margins. Certification investment in dual IEC-GB compliance accelerates product launches versus competitors absorbing bifurcated SKU delays. For New Entrants and Emerging Players: Begin with DIN-rail MCB supply to Nigeria and Kenya commercial construction markets adopting IEC standards without legacy fuse displacement costs. Underpenetrated African electrical infrastructure offers white-space expansion outside incumbent distribution lock-in. Direct contractor relationships through prefabricated panel skids bypass consultant-dominated specification channels in mature markets. For Investors and Strategic Acquirers: Re-rating potential sits with predictive maintenance bundlers given digital twin convergence creating recurring revenue attachment to hardware sales. Long-term viability favors suppliers converging circuit protection with software service models over pure-play electromechanical manufacturers. Watch arc-fault detection intelligence migration into integrated MCB platforms as inflection indicator for fire safety system competitive boundary redraw.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Dual-Tracking | Parallel IEC and GB compliance investment accelerates product launches amid SAMR enforcement tightening. |
| Semiconductor Supply Agreement | Long-term foundry contracts with Taiwan and South Korea producers secure microcontroller allocation for electronic trip units. |
| Predictive Maintenance Platform Launch | Software bundling with circuit protection hardware creates recurring revenue streams displacing transactional breaker sales. |
| Arc-Fault Algorithm Acquisition | Specialist firm purchase addresses embedded firmware talent scarcity concentrated among former relay protection engineers. |
| African Distribution Partnership | Local electrical contractor relationships in Nigeria and Kenya bypass DIN-rail specification channels dominated by European incumbents. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrical engineering consultants, data center procurement officers, industrial plant maintenance directors, and electrical contractor project managers. Secondary sources included IEC certification databases, SAMR GB standard enforcement records, CEA procurement specifications, and EIA electrical infrastructure expenditure reports. Bottom-up volume modeling across MCB and MCCB frame sizes triangulated against top-down market sizing from trade association aggregate data.
Segment-level granularity modeled product type, trip mechanism technology, end-use vertical, and installation configuration across the projection horizon. Voltage rating and interrupting capacity tiers were projected separately for electronic and electromechanical platforms. CAGRs derived from regression analysis of historical procurement patterns against data center rack density trajectories, PLI-linked manufacturing incentive disbursement timelines, and commercial building retrofit regulatory compliance deadlines. Copper and silver price scenarios informed electromechanical segment cost assumptions; foundry capacity utilization rates shaped electronic trip-unit supply constraints.
Underlying measurement precision varies by segment; electronic trip-unit MCCBs in data center applications carry tighter precision than commodity electromechanical MCBs in residential construction. Forecasts reflect assumptions on IEC-GB regulatory divergence persistence, semiconductor supply normalization trajectories, and PLI incentive geographic concentration. A model refresh is warranted upon material change in hyperscale data center construction permitting velocity or SAMR electromagnetic compliance enforcement scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Europe Electric Insulator Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global EMC Filtration Market