
 Electric Enclosure Market | 2026-2036
Electric Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Enclosure Market Intelligence
The IEC 60529 standard, which defines Ingress Protection (IP) ratings for enclosures, is redrawing the landscape for market access in demanding industrial applications. Schneider Electric leverages its extensive portfolio of IP-rated enclosures to serve the process automation sector. Rittal specializes in modular enclosure systems for data centers and IT infrastructure. Meanwhile, Hammond Manufacturing sustains a strong position in North America through its deep catalog of NEMA-rated products.
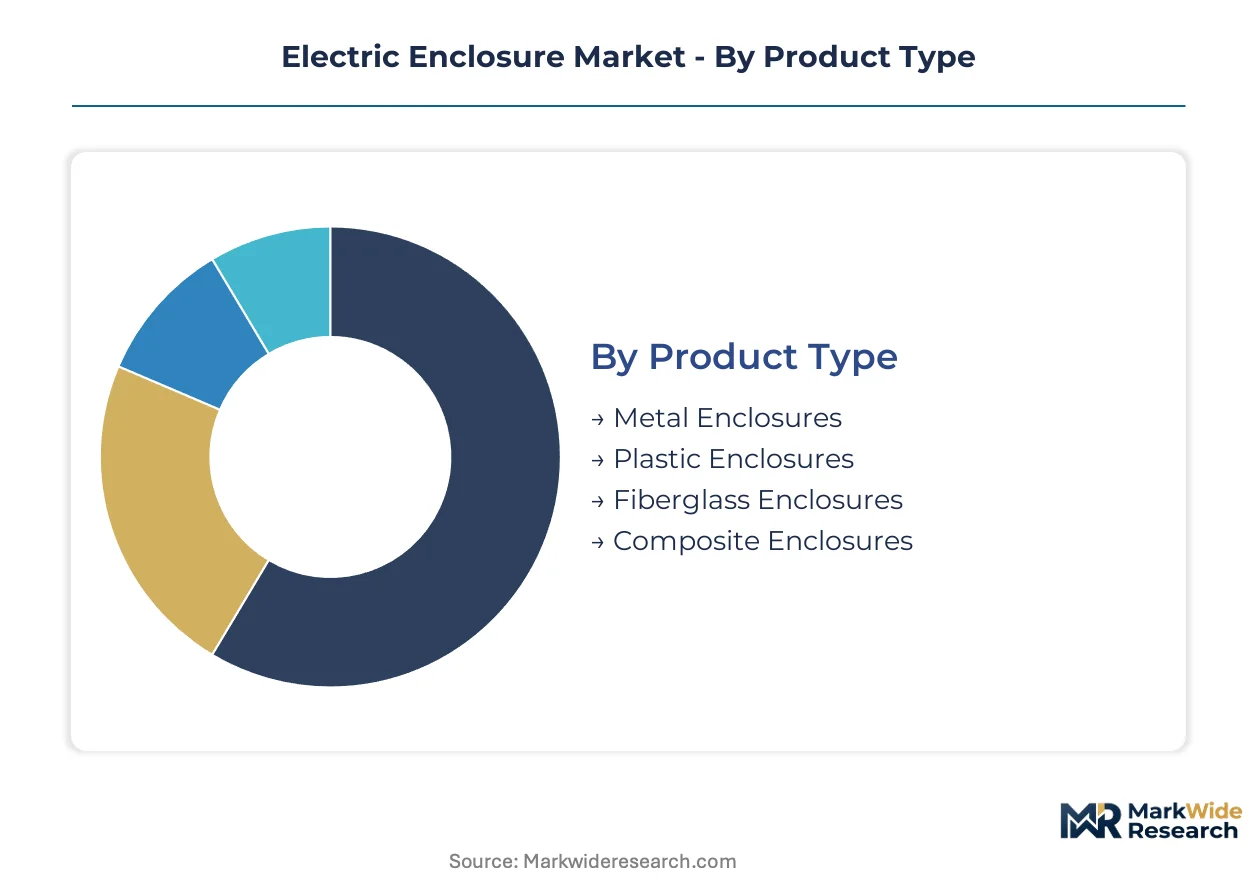
An electric enclosure is a cabinet or box designed to house electrical or electronic equipment, protecting it from environmental conditions and preventing electric shock. These structures are typically fabricated from materials like stainless steel or polycarbonate to achieve specific Ingress Protection (IP) and NEMA ratings. Within product types, metal enclosures command the largest share due to their durability, while composite enclosures represent the fastest-growing segment. Demand from renewable energy systems and data centers is outpacing that from traditional manufacturing facilities.
Compliance with regional electrical safety standards is non-negotiable for market participants. The CE marking in Europe, UL certification in the United States, and GB standards in China dictate material, design, and testing protocols. These regulations directly influence manufacturing costs and market entry barriers. Consequently, vendor selection will increasingly hinge on the ability to provide globally certified products that meet diverse end-user specifications for hazardous and non-hazardous locations.
Market Dynamics
The electric enclosure market is defined by the fundamental tension between the need for globally standardized products and the reality of fragmented, region-specific electrical safety regulations. This dynamic forces manufacturers to balance the economies of scale from unified designs against the high costs of multi-jurisdictional certification.
Growth Catalysts
- Renewable Energy Infrastructure:Government mandates for decarbonization are accelerating the build-out of solar and wind farms, creating sustained demand for durable, weather-resistant enclosures rated for outdoor and often harsh environmental conditions.
- Data Center Expansion:Investment in new data centers, particularly in China and the United States, requires high-density, thermally managed enclosure systems to protect sensitive IT and power distribution equipment.
- Higher Protection Standards:The industry-wide adoption of stricter Ingress Protection (IP) ratings, as defined by the IEC 60529 standard, is compelling end-users in industrial automation and food processing to upgrade their existing enclosure fleets.
Market Restraints
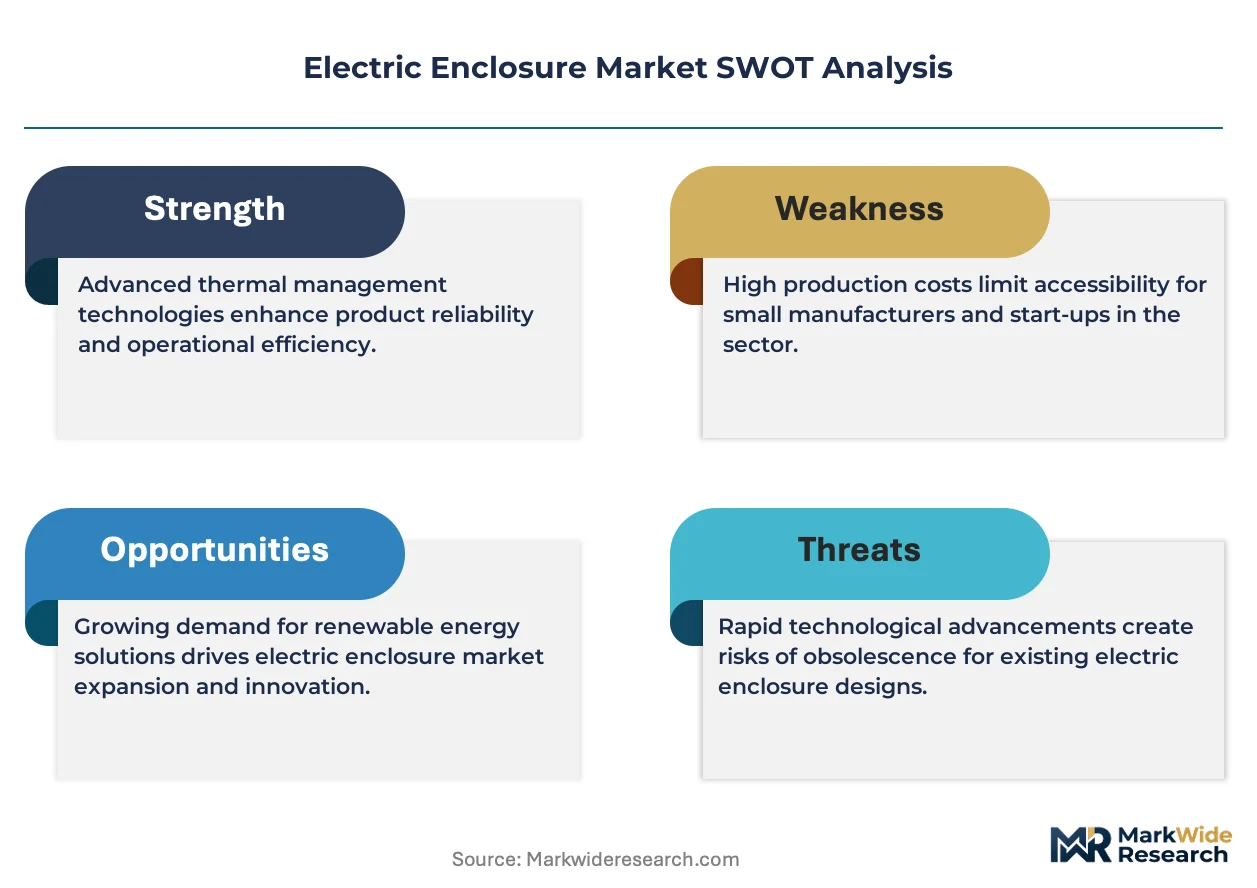
- Raw Material Price Volatility:Fluctuations in the cost of core materials, especially stainless steel, aluminum, and polycarbonate resins, directly impact manufacturer margins and create pricing instability for end-users.
- Regulatory Fragmentation:The lack of harmonization between major electrical codes, such as UL standards in the US, CE marking requirements in Europe, and GB standards in China, increases testing complexity and market entry costs.
- Substitution from Integrated Equipment:Some industrial equipment is now designed with integrated, pre-certified enclosures, reducing the addressable market for standalone third-party enclosure manufacturers in certain niche applications.
Strategic Opportunities
- EV Charging Networks:The global expansion of electric vehicle charging infrastructure presents a significant opportunity for specialized enclosures designed for public, commercial, and residential charging stations.
- Smart Enclosure Development:Integrating IoT sensors for monitoring temperature, humidity, and unauthorized access allows for the creation of value-added "smart" enclosures that support predictive maintenance and enhance security.
- Hazardous Location Expertise:Developing deep expertise and certified product lines for hazardous locations (HAZLOC) in oil and gas or chemical processing provides a defensible, high-margin market segment.
Industry Challenges
- Certification Lead Times:The lengthy and expensive process of securing multiple global certifications for a single product family can delay market entry and consume significant engineering resources, acting as a barrier to innovation. *Legacy System Integration: In brownfield industrial upgrades, ensuring that modern enclosures with different mounting systems and dimensions can integrate seamlessly with decades-old plant infrastructure is a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Enclosure Market |
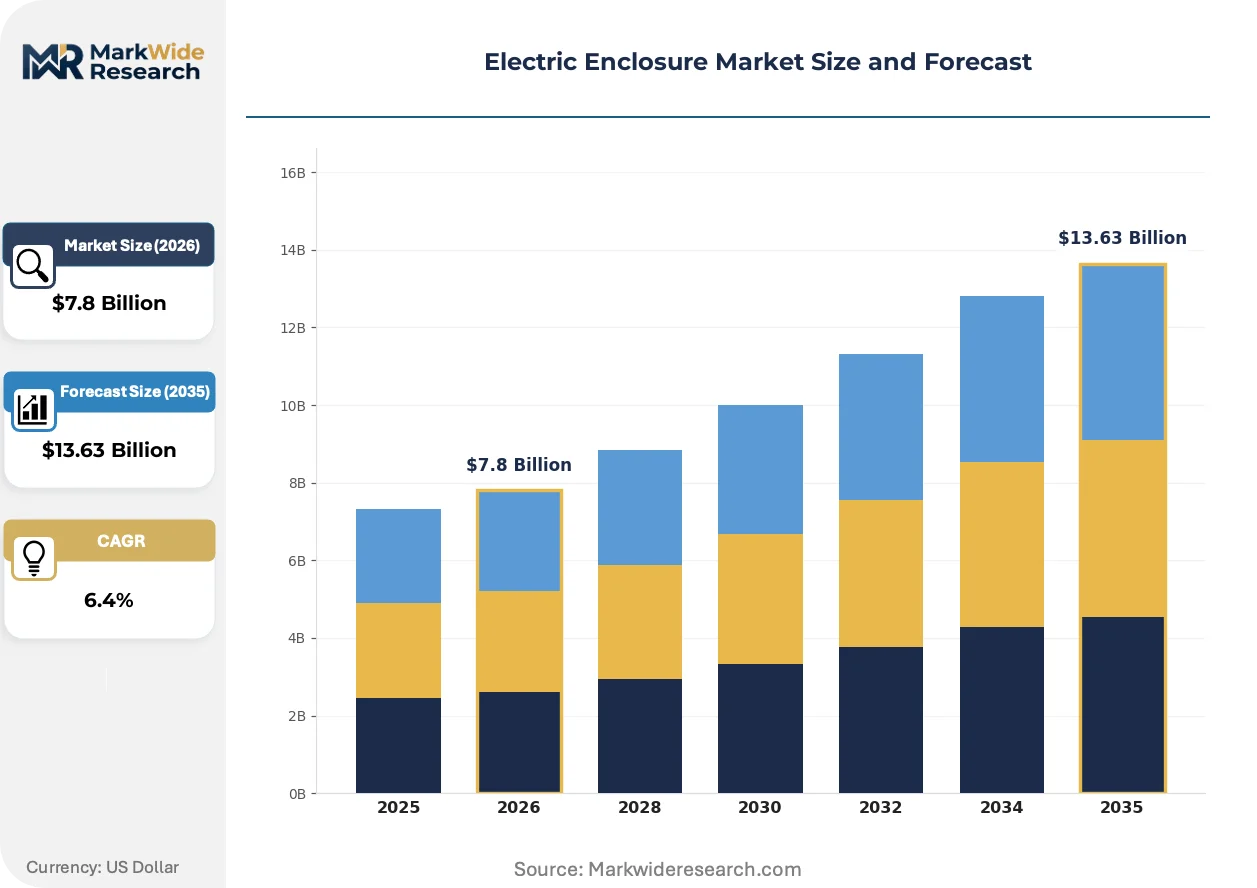
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Enclosures, Plastic Enclosures, Fiberglass Enclosures, Composite Enclosures Technology: Wall-Mount, Floor-Standing, Modular, Portable, Rack-Mount Application: Process Automation, Power Distribution, Renewable Energy Systems, Telecommunications Equipment End User Industry: Energy Generation, Data Centers, Manufacturing Facilities, Transportation Infrastructure |
| Companies Covered | ABB, Legrand, Schneider Electric, Hammond Manufacturing, Emerson Electric, Rittal, Eaton, Siemens, nVent HOFFMAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Enclosure Market Strategic Shifts & Innovations
Product development is shifting from passive containment to active environmental management. This evolution is driven by advances in material science that offer superior protection and by the integration of digital technologies that provide real-time operational intelligence, transforming enclosures into active system components.
Advanced Composite Materials
Advanced composites like fiberglass-reinforced polyester (FRP) provide high corrosion resistance and impact strength at a lower weight than traditional steel. These materials are being adopted rapidly in wastewater treatment plants and coastal renewable energy installations where corrosion is a primary failure mode. The availability of these specialized non-metallic options is fragmenting the market away from a historical reliance on metal, creating distinct material preferences based on specific application environments.
Evolving Safety and Environmental Directives
The European Union’s RoHS directive, which restricts hazardous substances in electrical equipment, directly influences enclosure manufacturing and material selection. This regulation forces a redesign of components within the enclosure, such as terminals and internal wiring, to eliminate lead and other restricted materials. Manufacturers exporting to Europe must ensure their entire supply chain is compliant, affecting everything from metal coatings to plastic additives to maintain market access.
Total Cost of Ownership as a Metric
End-user evaluation criteria are shifting from initial purchase price to a more sophisticated analysis of Total Cost of Ownership (TCO). This change disrupts the traditional commodity-based procurement model, favoring enclosures that offer longer service life, reduced maintenance, and superior protection that prevents costly equipment downtime. This trend is most visible in critical sectors like data centers and pharmaceuticals, where the cost of failure far outweighs any initial savings on the enclosure itself.
Electric Enclosure Market Segmentation
The electric enclosure market exhibits varied demands across product types, technologies, applications, and end-user industries. Understanding these segments is critical for manufacturers to tailor offerings and navigate complex regulatory landscapes. This detailed segmentation analysis illuminates specific growth pockets and competitive battlegrounds.
Product Type:
Different product types demonstrate varying degrees of geographic market penetration, with some favored in domestic markets due to cost or local manufacturing capabilities.
- Metal Enclosures:These structures, primarily stainless steel or aluminum, offer superior durability and electromagnetic shielding. Demand concentrates in industrial automation in Germany and critical infrastructure projects in the United States, driven by stringent safety and longevity requirements.
- Plastic Enclosures:These lightweight and cost-effective options find widespread use in residential and light commercial applications, particularly in emerging markets like India.
- Fiberglass Enclosures:Offering good chemical resistance, fiberglass is preferred for outdoor utility and telecommunications infrastructure in regions with harsh weather, such as Australia.
- Composite Enclosures:Fabricated from advanced materials like fiberglass-reinforced polyester (FRP), these enclosures provide excellent corrosion resistance and lightweight properties. Renewable energy installations in coastal regions like the Netherlands and wastewater treatment plants in Canada increasingly adopt composite solutions.
Metal Enclosures hold the largest share; momentum sits with Composite Enclosures.
Technology:
Each enclosure technology addresses specific operational requirements, ranging from space constraints to accessibility needs across various industrial settings.
- Wall-Mount:Compact solutions for confined spaces, commonly found in commercial buildings and light industrial settings across Europe.
- Floor-Standing:Larger units accommodating extensive electrical components, essential for power distribution in manufacturing facilities in China.
- Modular:These systems allow for flexible configuration and expansion, enabling rapid deployment and scalability in large-scale industrial control rooms. Data centers in Singapore leverage modular designs for efficient power distribution units.
- Portable:Designed for temporary setups or mobile applications, these enclosures support field testing equipment in the US construction sector.
- Rack-Mount:Standardized for IT and telecommunications equipment, these enclosures optimize space utilization and airflow within server cabinets. Cloud computing facilities in Ireland deploy rack-mount solutions for high-density network hardware.
Floor-Standing solutions manage substantial power infrastructure, while Modular designs are experiencing the steepest expansion trajectory.
Application:
Application segments highlight where the primary demand for electric enclosures originates, reflecting diverse industry needs and environmental challenges.
- Process Automation:Critical for protecting programmable logic controllers (PLCs) and human-machine interface (HMI) systems in manufacturing plants, especially in Germany's automotive sector.
- Power Distribution:These enclosures house switchgear, transformers, and circuit breakers, ensuring reliable electricity supply to industrial and commercial facilities. Infrastructure upgrades in India are fueling substantial procurement of robust power distribution enclosures.
- Renewable Energy Systems:Enclosures in this segment protect sensitive electrical components in solar inverters and wind turbine control panels. Government decarbonization mandates in the United Kingdom drive significant demand for weather-resistant outdoor enclosures.
- Telecommunications Equipment:Safeguards networking hardware and signal processing units for cellular towers and broadband infrastructure across South Korea.
Power Distribution applications historically consume the largest volume, yet Renewable Energy Systems are gaining share fastest.
End User Industry:
End-user industries dictate enclosure specifications based on their unique operating environments, from high-temperature data centers to outdoor energy generation sites.
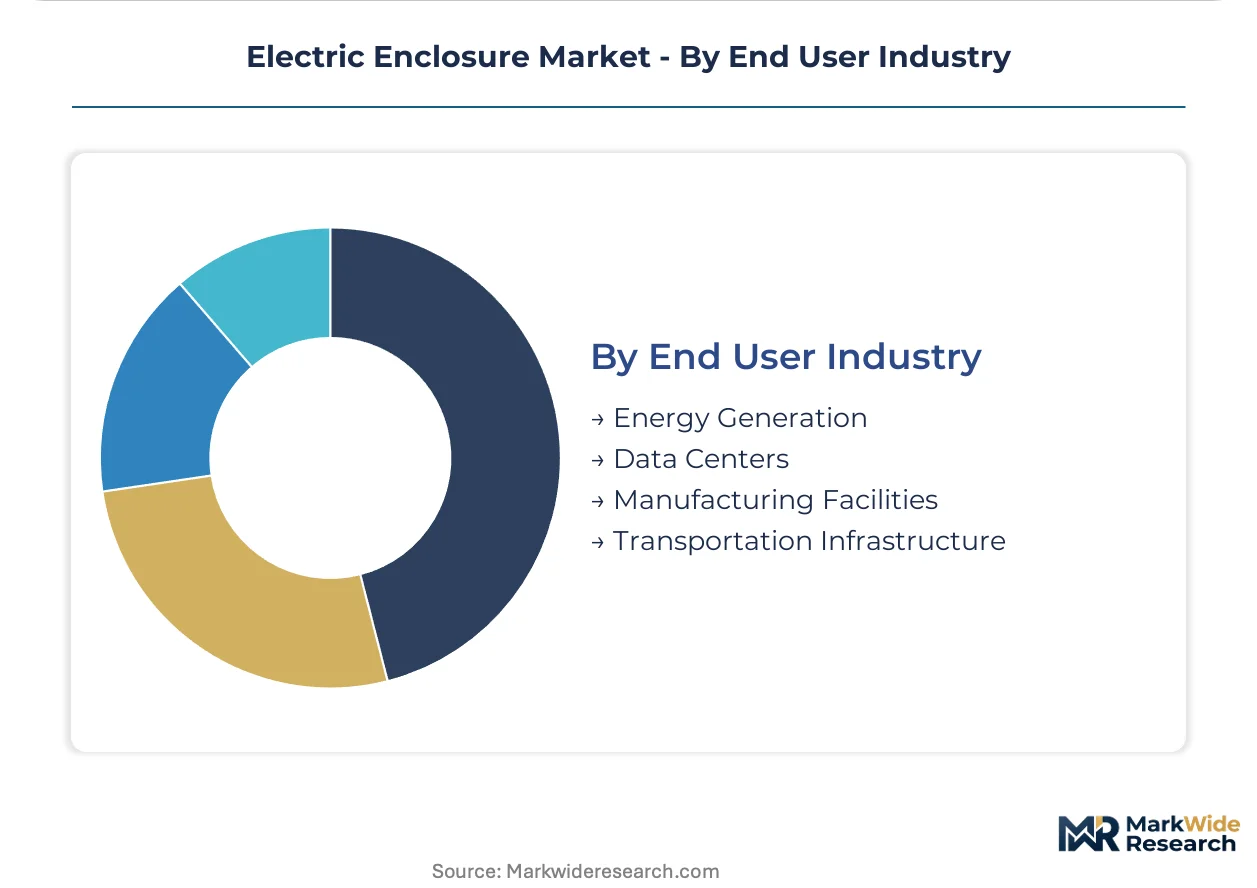
- Energy Generation:This segment includes enclosures for conventional power plants and renewable energy installations, demanding robust protection against harsh environmental factors. The expansion of wind farms in Denmark drives consistent demand for specialized outdoor enclosures.
- Data Centers:These facilities require enclosures for servers, networking gear, and power supply units, often with advanced thermal management. Extensive investments in new data centers in China necessitate high-density, secure enclosure solutions.
- Manufacturing Facilities:Enclosures protect control panels and machinery electronics in various production environments, particularly in advanced manufacturing hubs in Japan.
- Transportation Infrastructure:Used in traffic control systems, railway signaling, and smart highway applications, ensuring operational reliability in urban centers like Paris.
Manufacturing Facilities represent a stable, mature segment, while Data Centers are demonstrating the most significant market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electric enclosures concentrates in regions with high industrial activity and significant infrastructure development, driven by the need to protect sensitive electrical equipment. These regional dynamics are shaped by varying regulatory frameworks and specific industry requirements, influencing material selection and design specifications across different markets.
China
China's extensive investment in new data centers and advanced manufacturing facilities drives significant electric enclosure demand. Compliance with GB standards dictates material and design protocols for market participants. The Yangtze River Delta region, a hub for high-tech manufacturing, experiences strong procurement for floor-standing and modular enclosures.
United States
The United States sees sustained demand for durable enclosures in critical infrastructure and data center expansion projects. UL certification is non-negotiable for market access, influencing design and testing protocols. In Texas, the build-out of renewable energy projects and oil and gas facilities generates substantial requirements for hazardous location enclosures.
Germany
Germany's robust industrial automation sector and advanced manufacturing facilities require high-quality metal enclosures. The CE marking ensures products meet European safety, health, and environmental protection requirements. Bavaria's automotive industry drives procurement of specialized enclosures for process automation and control systems.
India
India's rapid infrastructure upgrades and expanding renewable energy systems fuel substantial demand for electric enclosures. Adherence to national electrical safety standards, like those from BIS, is crucial for market entry. Maharashtra, a key industrial state, shows strong growth in demand for plastic and power distribution enclosures.
Japan
Japan's advanced manufacturing facilities and growing data center investments drive specialized enclosure requirements. Conformity with JIS standards ensures product quality and safety across various applications. The Kanto region, home to numerous high-tech industries, necessitates rack-mount and modular systems for IT infrastructure.
Electric Enclosure Market Key Industry Players
Player mix skews toward global industrial conglomerates alongside specialized enclosure manufacturers. The market structure exhibits a tiered consolidation, with a few large entities holding significant share while numerous regional players serve niche demands. Strategic archetypes include diversified electrical equipment providers, focused modular system specialists, and local NEMA-rated product suppliers. Competitive moves center on portfolio diversification to meet varied IP and NEMA standards, geographic expansion into high-growth regions, and strategic partnerships to enhance market reach.
Within the global industrial conglomerate tier, Schneider Electric represents comprehensive solution providers, leveraging its extensive portfolio of IP-rated enclosures for diverse applications. Rittal exemplifies specialized modular system providers, focusing on highly configurable enclosure systems tailored for data centers and IT infrastructure. Hammond Manufacturing anchors the regional NEMA-rated product suppliers, sustaining a strong position in North America through its deep catalog of locally compliant products. These companies collectively demonstrate the market's demand for both globally certified products and region-specific solutions that meet diverse end-user specifications.
| Leading Market Players |
|---|
| ABB |
| Legrand |
| Schneider Electric |
| Hammond Manufacturing |
| Emerson Electric |
| Rittal |
| Eaton |
| Siemens |
| nVent HOFFMAN |
Cost & Logistics Intelligence
Advanced composite materials displacing traditional metals are reshaping the electric enclosure supply chain and pricing dynamics. This shift influences manufacturing locations and cost structures for diverse end-user applications.
Pricing Analysis
Cost-plus contract patterns, often indexed to stainless steel, aluminum, or polycarbonate resin prices, govern many long-term procurement agreements. Price differentiation stems from the specific certification level required, such as UL or CE marking, and the degree of customization for specialized applications. Pricing softness reflects raw material price volatility, particularly for metals and resins. Residential and light commercial applications exhibit the highest price sensitivity, while data centers and hazardous location installations prioritize performance and reliability over initial cost.
Supply Chain Analysis
China anchors global production of standard metal and plastic enclosures, leveraging extensive manufacturing capabilities for volume. Germany and the United States contribute specialized, high-performance enclosures for industrial automation and hazardous locations. The sector draws from global sources for stainless steel, polycarbonate resins, and specialized sealing components. Regulatory fragmentation across regions presents a structural supply chain risk, increasing complexity for manufacturers. Downstream distribution primarily occurs through direct sales to large OEMs and project integrators, supplemented by specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric enclosure market is experiencing a cyclical recovery, primarily driven by renewed global investment in critical infrastructure and renewable energy projects. This rebound offers strategic opportunities for various market participants.
For Market Incumbents:Compound expertise in globally certified products by investing in advanced material science and smart enclosure R&D. Diversify product portfolios to cover a broader spectrum of IP and NEMA ratings, addressing the threat of substitution from integrated equipment. Leverage existing market presence to deepen channel relationships and offer value-added services, ensuring continued relevance in evolving end-user requirements. Prioritize certification investment across UL, CE, and GB standards to maintain market access.
For New Entrants and Emerging Players:Service-layer gaps exist in specialized applications requiring deep technical expertise, such as hazardous location enclosures for chemical processing. Target the rapidly expanding EV charging networks and renewable energy systems in emerging markets like India, which demand cost-effective, weather-resistant solutions. Develop application-specific product lines with rapid certification turnaround times, offering tailored solutions that larger incumbents may overlook. Focus on modular designs to enable quick deployment and scalability for project-based opportunities.
For Investors and Strategic Acquirers:The market sits at a re-industrialization phase that favors specialized technology providers with strong intellectual property and certified product lines. Long-term viability appears robust over the next five to ten years, driven by electrification and digitalization trends. Seek acquisition targets that are niche specialists in hazardous location enclosures or developers of smart enclosure technologies integrating IoT sensors. The signal to watch is the accelerating adoption rate of integrated monitoring solutions in new data center and industrial automation projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Material R&D | Developing lighter, more durable composite enclosures enhances protection against corrosion in coastal renewable energy sites. |
| Expand Global Certification Portfolio | Securing UL, CE, and GB certifications enables manufacturers to access diverse markets like the US, Europe, and China. |
| Develop Smart Enclosure Solutions | Integrating IoT sensors provides real-time operational intelligence, supporting predictive maintenance in data centers. |
| Target EV Charging Infrastructure | Designing specialized enclosures for public charging stations addresses a significant growth opportunity for new applications. |
| Deepen Hazardous Location Expertise | Offering certified HAZLOC products provides a defensible, high-margin segment in oil and gas processing. |
Research Approach
A standing panel of plant managers, OEM procurement leads, electrical engineers, and regulatory compliance officers provided ongoing calibration for primary insights. This was combined with secondary validation from sources including IEC standards, NEMA publications, national electrical codes, and trade association reports. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market sizing.
All volume and value outputs underwent consistency checks against external benchmarks, ensuring model robustness across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and specific IP/NEMA rating requirements. Compound Annual Growth Rates were derived from historical trends and projected forward based on anticipated renewable energy build-out rates and data center investment.
Forecasts assume regulatory continuity in key regimes like the EU, US, and China; material policy shifts would require re-modeling. The analysis reflects current market assumptions, but raw material price shocks or global trade policy changes present specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Low Voltage Motor Control Centers Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Low Voltage Circuit Breakers Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Vacuum Circuit Breaker Market