
 Sensor Data Analytics Market | 2026-2036
Sensor Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Data Analytics Market Outlook
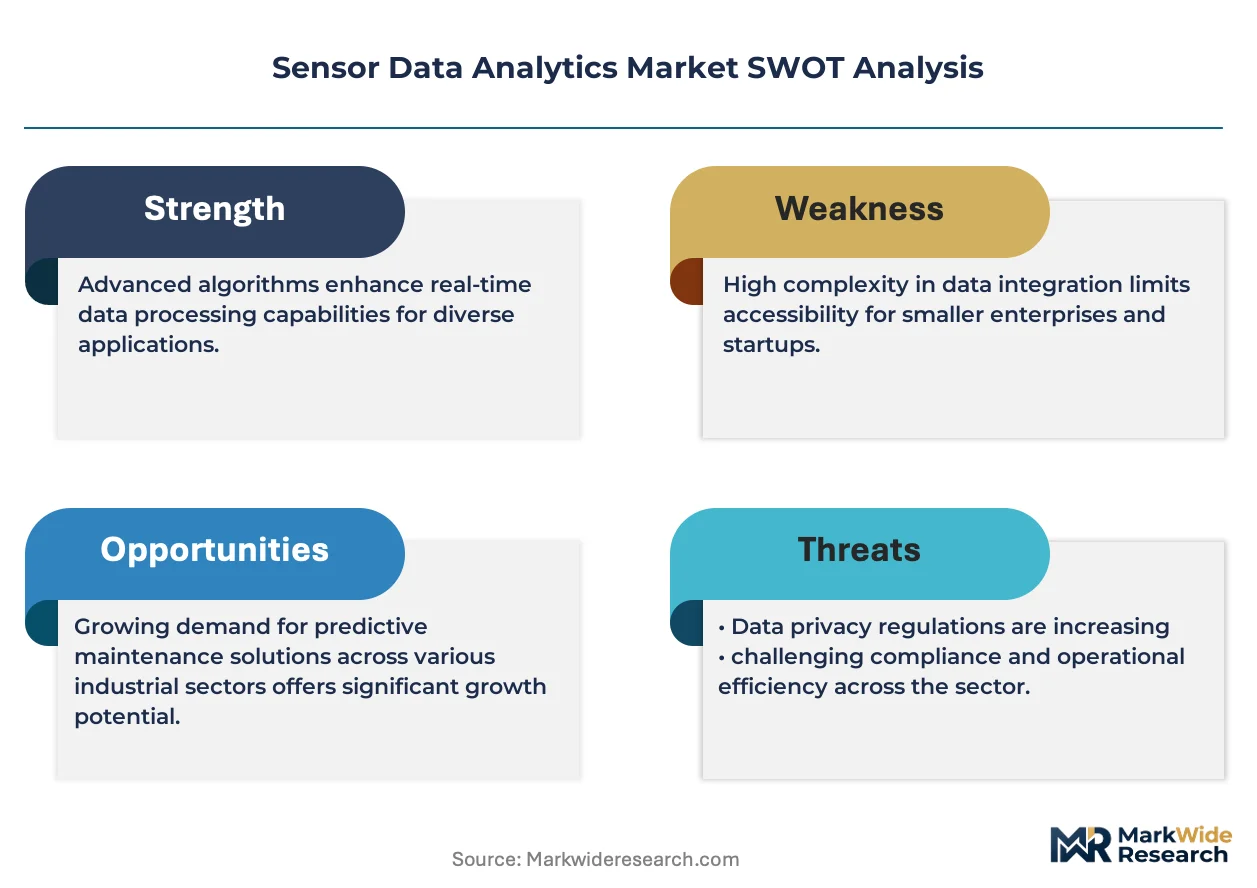
Smart manufacturing is consolidating as the dominant demand vector for sensor data analytics platforms. IBM Corporation leverages its hybrid cloud architecture to serve industrial clients requiring on-premise data sovereignty. Microsoft Corporation anchors its position through Azure IoT integration with edge analytics capabilities. Schneider Electric SE specializes in energy management applications, extending its software stack into predictive asset monitoring for utilities and grid operators.
Sensor data analytics encompasses the algorithmic processing of time-series signals from physical transducers to extract operational intelligence, typically involving sampling rates from kilohertz to megahertz and noise-filtering pipelines before pattern recognition. The discipline serves industrial automation, autonomous systems, and infrastructure monitoring by converting raw voltage or current signals into actionable state estimates. Machine Learning applications command premium pricing due to model training complexity and specialized talent requirements. Edge Computing deployments are expanding fastest where milliseconds of latency determine safety outcomes in transportation and robotics. Cloud Analytics retains volume leadership in non-time-sensitive use cases such as historical trend analysis and regulatory reporting.
The US FDA governs sensor analytics in connected medical devices through software validation requirements, while the EU AI Act imposes risk-classification obligations on automated decision systems processing biometric or safety-critical sensor streams. China's MIIT enforces GB standards for industrial data interfaces, shaping interoperability requirements for equipment sold into its manufacturing base. Stakeholders must weigh jurisdictional compliance burdens against latency and data residency specifications when architecting multi-national deployment strategies.
Market Dynamics
Edge computing architectures are compressing latency thresholds for mission-critical sensor analytics, forcing infrastructure reconfiguration across industrial automation and autonomous systems deployments. This shift redistributes computational load from centralized cloud nodes toward distributed edge gateways, altering hardware procurement patterns and vendor selection criteria.
Growth Catalysts
- Predictive Maintenance Mandates:Automotive OEMs in Germany are embedding sensor analytics into production workflows to minimize unplanned downtime. Regulatory pressure from the EU AI Act accelerates validation protocols for automated decision systems.
- Industrial IoT Proliferation:Manufacturing facilities are deploying multi-sensor arrays for real-time equipment monitoring. Edge analytics integration enables millisecond-response safety systems in robotics and transportation.
- Machine Learning Premium Services:Specialized talent requirements and model training complexity create high-margin service opportunities. Pattern recognition pipelines for time-series signals command pricing premiums from utilities and grid operators.
Market Restraints
- Semiconductor Supply Concentration:Edge gateway chip fabrication concentrates in East Asian foundries, exposing deployment timelines to geopolitical disruption and capacity constraints.
- Data Sovereignty Compliance Costs:China's MIIT enforces GB standards for industrial data interfaces, forcing multinational vendors to maintain separate architecture stacks for Chinese manufacturing clients.
- Legacy System Integration Friction:Brownfield facilities with decades-old SCADA infrastructure face prohibitive retrofit costs for sensor analytics compatibility.
Strategic Opportunities
- Energy Management Convergence:Schneider Electric's software stack extension demonstrates predictive asset monitoring potential for utilities. Grid operators seek integrated voltage signal processing with demand forecasting algorithms.
- Medical Device Analytics:US FDA software validation requirements for connected devices create a regulated channel for biometric sensor processing. Risk-classification obligations under EU AI Act similarly structure European opportunities.
- Autonomous System Safety:Transportation and robotics applications require sub-millisecond latency thresholds that cloud analytics cannot satisfy. Edge-native architectures capture this performance-critical segment.
Industry Challenges
- Specialized Talent Scarcity:Time-series signal processing and noise-filtering pipeline engineering require hybrid hardware-software expertise that outpaces academic program output.
- Cross-Jurisdictional Certification Burden:Multi-national deployments must simultaneously satisfy FDA validation, EU AI Act risk classification, and MIIT GB standards, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Data Analytics Market |
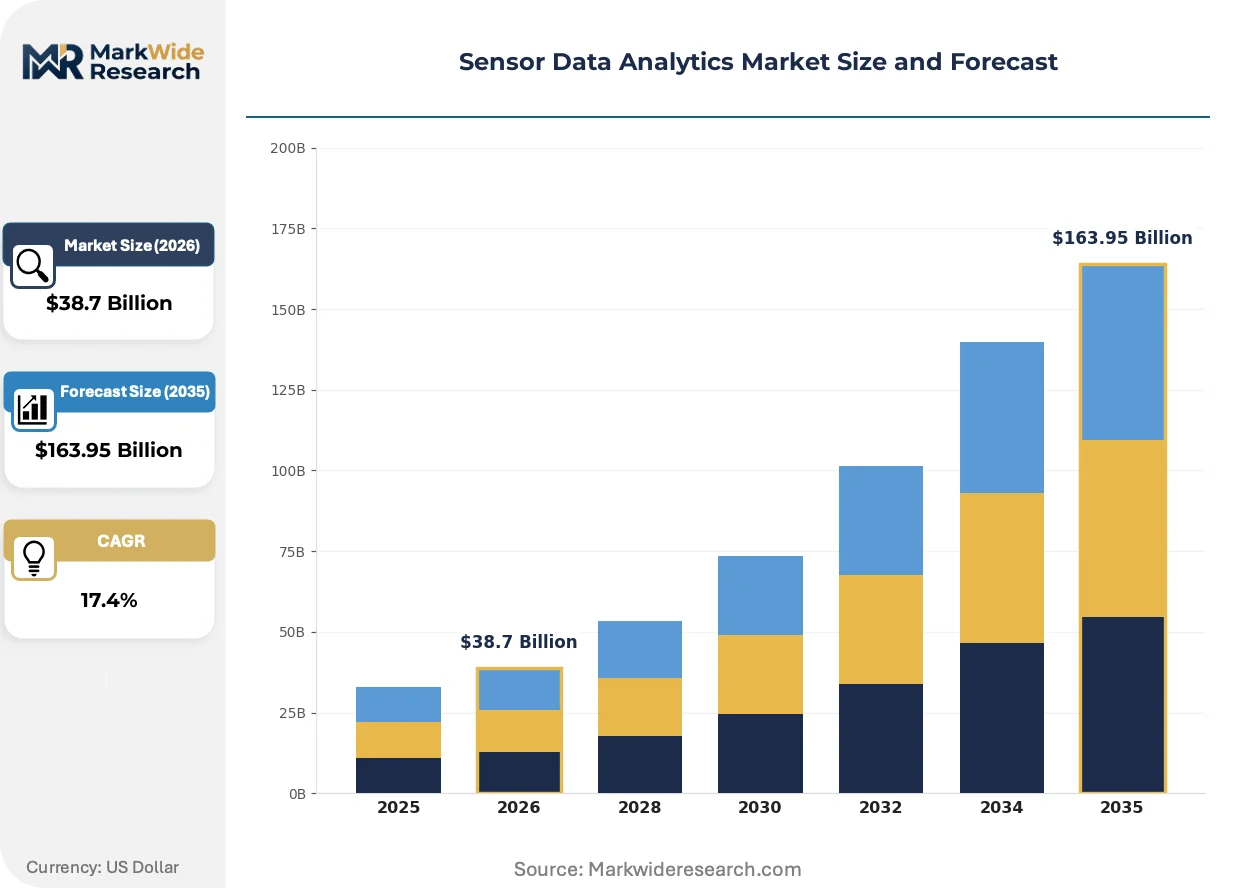
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Quality Monitoring, Supply Chain Optimization, Asset Management Technology: Machine Learning, Big Data Analytics, Edge Computing, Cloud Analytics End User: Manufacturing, Transportation, Healthcare, Energy Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | IBM Corporation, Tata Consultancy Services, Microsoft Corporation, Cisco Systems Inc., SAP SE, Hewlett Packard Enterprise Company, Qualcomm Inc., Schneider Electric SE, Verizon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Data Analytics Market Strategic Shifts
Sensor fusion architectures are consolidating heterogeneous signal streams into unified inference pipelines, compressing hardware footprints while expanding analytical depth. This convergence eliminates redundant preprocessing layers and enables real-time cross-modal pattern detection previously requiring batch processing.
Digital twin technology is unifying physical asset modeling with live sensor feeds for predictive state estimation. Heavy machinery producers in Germany are deploying these integrated systems to simulate wear patterns before mechanical failure manifests. The technology is unifying design-phase simulation with operational-phase monitoring, collapsing the traditional separation between R&D and field service engineering.
The EU AI Act imposes mandatory risk-classification obligations on automated decision systems processing safety-critical sensor streams. Industrial automation vendors must now document algorithmic transparency and human oversight protocols before European deployment. Medical device manufacturers face the steepest compliance burden, with high-risk biometric processing requiring notified body intervention and continuous post-market surveillance.
Buyers are consolidating vendor relationships around integrated platform providers capable of spanning edge-to-cloud deployment spectra. Discrete point solutions for signal processing, storage, and visualization are losing procurement share to unified analytics stacks. This preference shift concentrates most visibly in German automotive supply chains, where Tier-1 suppliers demand single-contract accountability for full-stack sensor infrastructure.
Sensor Data Analytics Market Segmentation
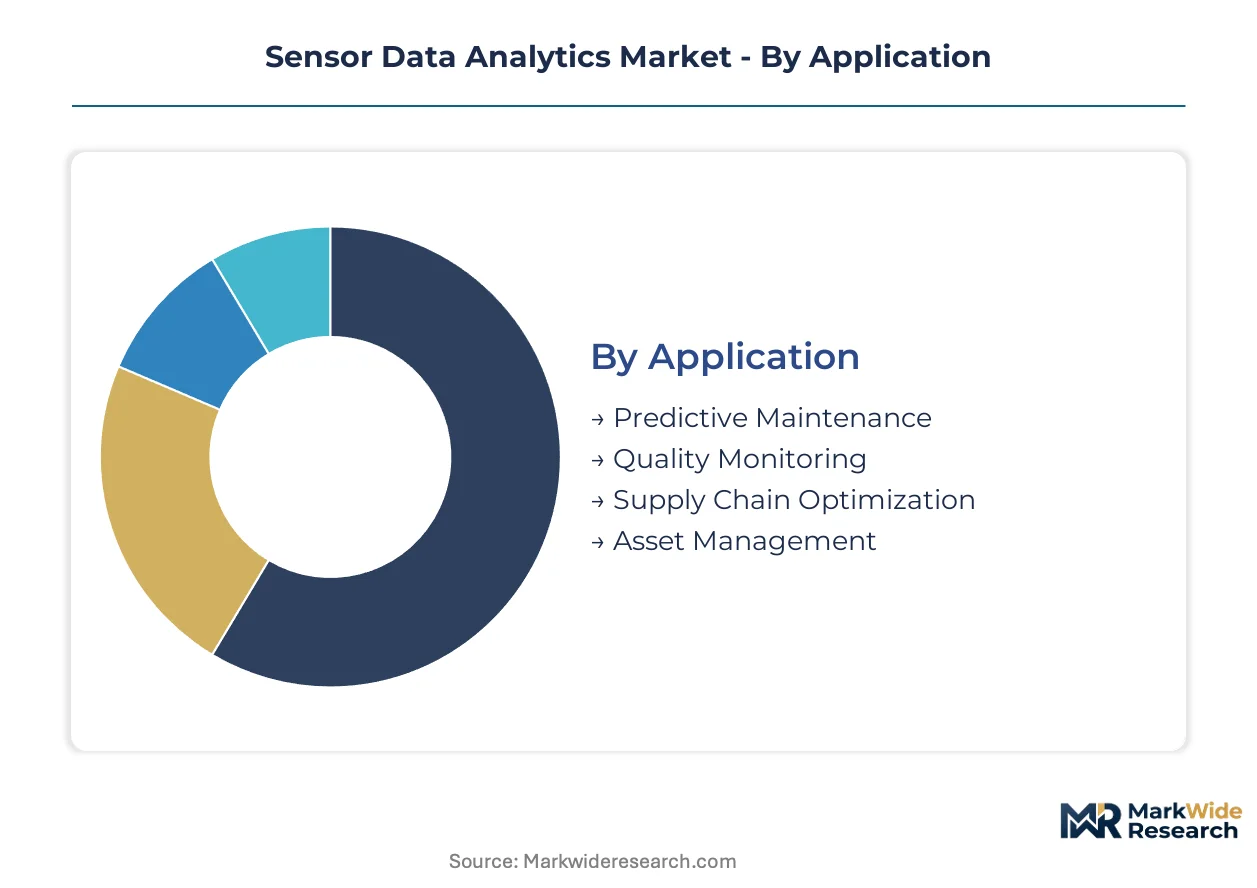
Sensor data analytics platforms serve heterogeneous operational environments where signal processing requirements, latency thresholds, and compliance obligations diverge sharply across use cases. Segmentation reveals how vendors must architect differentiated solution stacks rather than one-size-fits-all offerings.
Application:
FDA validation protocols govern predictive maintenance in connected medical devices, while EU AI Act risk classification applies to quality monitoring systems making automated pass-fail determinations on safety-critical components.
- Predictive Maintenance:Algorithms process vibration, thermal, and acoustic signatures from rotating machinery to forecast bearing failures and lubrication degradation. German automotive OEMs embed these systems into stamping and welding lines to eliminate unplanned downtime during just-in-sequence production.
- Quality Monitoring:Real-time vision and force-torque sensors detect dimensional deviations and surface defects during machining operations. MIIT GB standards for industrial data interfaces shape how multinational vendors configure quality analytics for Chinese manufacturing clients, forcing separate architecture stacks.
- Supply Chain Optimization:Cold-chain logistics deploy temperature and humidity sensors with geolocation tracking to prevent pharmaceutical spoilage.
- Asset Management:Grid operators integrate voltage signal processing with demand forecasting for transformer health monitoring.
Leading the category by volume: Predictive Maintenance. Growing fastest: Quality Monitoring.
Technology:
Cost tiering separates enterprise deployments from mid-market adoption, with machine learning commanding premium pricing due to specialized talent requirements and model training complexity.
- Machine Learning:Deep learning architectures for time-series forecasting require GPU clusters and months of labeled training data. Pattern recognition pipelines for multi-sensor fusion command pricing premiums from utilities and grid operators seeking predictive asset monitoring.
- Edge Computing:Distributed inference engines compress latency to sub-millisecond thresholds for robotics collision avoidance and autonomous vehicle emergency braking. Transportation and safety-critical applications drive fastest expansion where cloud latency proves unacceptable.
- Big Data Analytics:Batch processing of historical sensor archives supports regulatory reporting and long-term trend analysis.
- Cloud Analytics:Centralized storage and visualization suits non-time-sensitive use cases with relaxed data sovereignty requirements.
Dominant by revenue: Machine Learning. Climbing the fastest: Edge Computing.
End User:
Customer maturity varies dramatically, with manufacturing facilities possessing decades-old SCADA infrastructure facing prohibitive retrofit friction compared to greenfield deployments.
- Manufacturing:Brownfield facilities with legacy SCADA systems require protocol gateways and edge middleware for sensor analytics compatibility. Multi-sensor arrays for real-time equipment monitoring proliferate as industrial IoT deployments multiply.
- Healthcare:Connected medical devices face FDA software validation requirements and EU AI Act high-risk classification for biometric processing. Notified body intervention and continuous post-market surveillance impose the steepest compliance burden.
- Transportation:Sub-millisecond latency requirements for autonomous systems favor edge-native architectures over cloud-dependent alternatives.
- Energy:Schneider Electric's software stack extension demonstrates predictive asset monitoring potential for utilities integrating voltage signal processing.
Highest penetration: Manufacturing. Steepest expansion trajectory: Healthcare.
Deployment:
Data residency specifications and jurisdictional compliance burdens dictate architecture selection, with hybrid models gaining traction among multinationals navigating China's MIIT GB standards alongside European GDPR constraints.
- On-Premise:Air-gapped installations satisfy data sovereignty mandates for defense contractors and critical infrastructure operators. IBM Corporation leverages hybrid cloud architecture to serve industrial clients requiring strict on-premise data containment.
- Hybrid:Edge gateways handle real-time inference while cloud nodes manage model retraining and historical analytics. Microsoft Corporation anchors its position through Azure IoT integration spanning edge-to-cloud deployment spectra.
- Cloud-Based:Fully managed SaaS offerings reduce capital expenditure for mid-market manufacturers with standardized requirements.
- Managed Services:Outsourced monitoring and maintenance appeals to facilities lacking specialized time-series signal processing expertise.
Volume leader: Hybrid. Gaining share fastest: On-Premise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing consumption concentrates in Germany while cloud infrastructure production dominates the United States. Edge hardware fabrication clusters in East Asian foundries. Data residency requirements fragment deployment architectures across jurisdictions.
Germany
Automotive OEMs and machinery producers embed sensor analytics into stamping and welding lines for just-in-sequence production. The EU AI Act imposes risk-classification obligations on automated quality monitoring systems. Stuttgart and Munich host dense clusters of Tier-1 suppliers demanding single-contract accountability for full-stack sensor infrastructure.
United States
Defense contractors and critical infrastructure operators require air-gapped installations with strict data sovereignty compliance. The FDA governs connected medical devices through software validation protocols. Silicon Valley and Seattle anchor cloud-native development for hybrid edge-to-cloud architectures serving industrial clients.
China
Smart manufacturing initiatives drive multi-sensor array deployment across automotive and electronics facilities. MIIT enforces GB standards for industrial data interfaces, forcing separate architecture stacks for multinational vendors. Shenzhen and Shanghai concentrate domestic platform development for captive supply chain integration.
Japan
Precision machinery and robotics manufacturers demand sub-millisecond latency for collision avoidance systems. METI industrial standards shape interoperability requirements for sensor data interfaces. Nagoya and Osaka host concentrated development of edge-native inference engines for transportation safety applications.
India
IT services providers build predictive maintenance platforms for export to European and North American manufacturing clients. BIS standards for industrial automation equipment create compliance pathways for domestic deployment. Bangalore and Hyderabad concentrate software development for time-series signal processing and noise-filtering pipelines.
Sensor Data Analytics Market Competitive Environment
Top-tier vendors anchor hybrid cloud and edge integration, while mid-tier specialists concentrate on vertical application stacks. The market structure tilts toward platform consolidation as buyers demand unified analytics stacks spanning signal processing through visualization. Three archetypes dominate: industrial automation incumbents extending software portfolios, cloud hyperscalers integrating IoT services, and telecom operators leveraging network infrastructure for edge deployment. Competitive moves center on strategic partnerships for sensor hardware integration and geographic expansion through localized data residency compliance.
Within the cloud-hyperscaler tier, Microsoft Corporation exemplifies platform breadth through Azure IoT integration, while IBM Corporation represents hybrid architecture specialization for data-sovereign industrial clients. Schneider Electric SE occupies a position exemplifying vertical extension from energy management into predictive asset monitoring. These three anchors demonstrate how vendor selection criteria increasingly favor full-stack accountability over discrete point solutions.
| Leading Market Players |
|---|
| IBM Corporation |
| Tata Consultancy Services |
| Microsoft Corporation |
| Cisco Systems Inc. |
| SAP SE |
| Hewlett Packard Enterprise Company |
| Qualcomm Inc. |
| Schneider Electric SE |
| Verizon Communications |
| Others |
Value Chain & Pricing Dynamics
Machine learning premium tiers diverge sharply from commodity analytics subscriptions, with GPU cluster access and specialized talent bundling commanding threefold markups over standardized edge inference packages. This bifurcation reshapes procurement patterns as German automotive OEMs demand fixed-price validation contracts while mid-market manufacturers gravitate toward consumption-based SaaS tiers.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations, with validated edge gateway configurations for EU AI Act compliance commanding immediate-delivery surcharges over standard four-week procurement cycles. Pricing stratifies across premium machine learning pipelines, standard edge analytics subscriptions, and economy cloud storage tiers, with FDA certification grade and customization depth as primary differentiation levers. Cost compression in commodity cloud analytics is intensifying because hyperscaler price wars erode per-gigabyte storage margins. Mid-market manufacturers exhibit highest price sensitivity, while defense contractors and critical infrastructure operators demonstrate minimal elasticity due to data sovereignty mandates.
Supply Chain Analysis
Freight cost volatility from East Asian foundries to European assembly plants is compressing margin structures for edge hardware vendors dependent on just-in-time component flows. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with advanced GPU and FPGA supply drawing from TSMC and Samsung foundry capacity. Raw material dependencies span silicon wafers, rare earth magnets for sensor housings, and specialized analog-to-digital converters. Single-source vulnerability around TSMC's leading-edge nodes poses structural risk. Distribution runs through authorized industrial automation distributors with field engineering support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-stack platform providers as buyer procurement committees penalize point-solution fragmentation with exclusion from Tier-1 supplier rosters.
For Market Incumbents: Hedge against margin erosion in commoditized cloud analytics by deepening backward integration into edge hardware design and captive sensor calibration services. Incumbents must acquire specialized time-series signal processing boutiques before talent scarcity inflates compensation premiums beyond sustainable levels. Vertical integration into GPU cluster operations represents the priority defensive lever against hyperscaler encroachment. For New Entrants and Emerging Players: Launch via managed service partnerships with Indian IT services providers to bypass upfront certification burdens for FDA and EU AI Act compliance. White-space targets include predictive asset monitoring for utilities seeking Schneider Electric alternatives and quality monitoring for Chinese manufacturing clients requiring MIIT GB standard configurations. The most penetrable segment is brownfield manufacturing facilities lacking internal edge computing expertise. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid architecture specialists given accelerating data sovereignty mandates across European and North American jurisdictions. Long-term viability favors vendors with demonstrated cross-jurisdictional certification capabilities spanning FDA validation, EU AI Act risk classification, and MIIT GB standards. The acquisition target archetype is mid-tier edge analytics firms with established automotive OEM relationships. The signal to watch is Tier-1 supplier consolidation of vendor rosters toward single-contract accountability models.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Platform Integration | Unifies inference pipelines for German automotive OEMs demanding millisecond latency with centralized model retraining. |
| Regulatory Certification Fast-Track | Accelerates EU AI Act compliance for predictive maintenance algorithms deployed in safety-critical welding operations. |
| Specialist Talent Acquisition | Secures scarce time-series signal processing expertise ahead of academic program output constraints. |
| Geographic Data Residency Compliance | Enables Chinese manufacturing contracts through MIIT GB standard architecture stacks. |
| Sensor Hardware Partnership | Integrates multi-sensor arrays from established industrial automation vendors into unified analytics stacks. |
Study Parameters
Independent corroboration across industrial IoT platform engineers, predictive maintenance directors at German automotive OEMs, and edge computing procurement officers underwrites the qualitative findings. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads were combined with secondary validation from SEC filings, hyperscaler capex disclosures, customs records, and EU regulatory submissions. Bottom-up sensor deployment estimates and top-down market sizing triangulate volume and value outputs.
Comparable-period anchoring to historical industrial IoT adoption curves and edge computing infrastructure buildouts structured the projection horizon. The analytical framework models deployment mode, organization size, vertical application, integration complexity, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level growth trajectory synthesis. Forecast inputs include industrial IoT sensor shipment data and edge gateway procurement patterns from manufacturing facilities.
Semiconductor supply disruption, regulatory timeline acceleration, and talent scarcity inflation are the dominant revision risks. Forecasts reflect assumptions about sustained industrial IoT deployment momentum and stable geopolitical conditions for East Asian foundry access. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Europe Electric Vehicle Sensor Market