
 Connected Sensors Market | 2026-2036
Connected Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Sensors Market Outlook
The EU Green Deal is pivoting building automation requirements across European industrial estates. Robert Bosch GmbH leverages its MEMS fabrication depth to dominate automotive and industrial sensor supply. Honeywell International Inc. anchors North American demand through building management system integration. Siemens AG competes on factory-floor digital twin deployments with ruggedized sensor arrays.
Connected sensors integrate transduction elements, signal conditioning circuitry, and communication modules to capture physical or chemical variables and transmit data across networks, typically operating at sub-milliwatt power budgets for battery-constrained nodes. Pressure and temperature variants lead product type revenue due to ubiquity in process industries, while proximity sensors register the fastest expansion through robotics and autonomous system integration. IoT technology commands the largest technology segment share as cloud-native architectures displace legacy wired fieldbus installations, though Bluetooth Low Energy is concentrating in wearable health and smart home application tiers where pairing simplicity outweighs mesh complexity.
The EPA enforces emissions monitoring standards that mandate calibrated sensor networks at industrial facilities, while the FCC governs wireless spectrum allocation for unlicensed IoT transmissions. ECHA REACH compliance restricts hazardous substances in sensor substrates, reshaping material selection for European market access. Stakeholders must weigh certification breadth against regional fragmentation when configuring product portfolios for cross-border deployment.
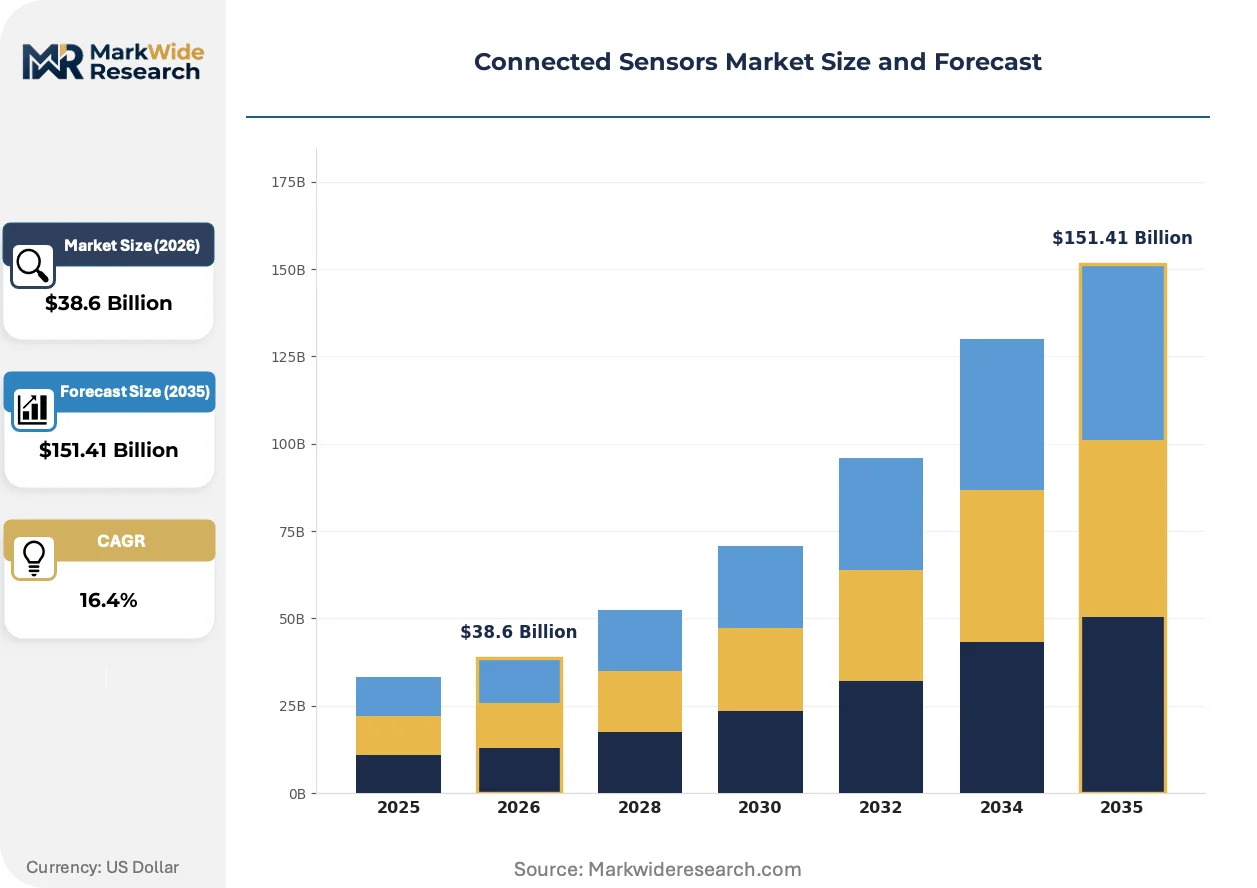
Market Dynamics
The EU Green Deal is compressing building retrofit timelines and mandating calibrated sensor networks across industrial estates, while MEMS fabrication consolidation in Germany and Taiwan is tightening supply availability for automotive and industrial buyers.
Growth Catalysts
- EU Green Deal mandates:Energy-efficient building retrofit requirements are expanding sensor deployment across European industrial corridors and residential estates.
- Smart home acceleration:Cloud-native architectures are displacing legacy wired fieldbus installations in residential automation systems.
- Robotics integration:Proximity sensors are registering fastest expansion through autonomous system and factory-floor digital twin deployments.
Market Restraints
- MEMS wafer supply concentration:Foundry capacity in Taiwan and Germany creates bottleneck risk for pressure and temperature sensor substrates.
- ECHA REACH compliance costs:Hazardous substance restrictions in European market access are reshaping material selection and certification timelines.
- Sub-milliwatt power constraints:Battery-constrained node designs limit signal conditioning circuitry complexity and transmission range.
Strategic Opportunities
- Bluetooth Low Energy concentration:Pairing simplicity in wearable health and smart home tiers creates white space where mesh complexity is prohibitive.
- EPA emissions monitoring standards:Calibrated sensor network mandates at US industrial facilities expand addressable market for certified suppliers.
- Digital twin convergence:Factory-floor sensor arrays combined with cloud analytics enable predictive maintenance service models.
Industry Challenges
- Cross-border certification fragmentation:FCC wireless spectrum allocation, EPA calibration standards, and ECHA REACH compliance create portfolio configuration complexity for multi-region deployment.
- Legacy system integration friction:Fieldbus replacement cycles and brownfield automation retrofits demand backward-compatible communication modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Sensors Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature, Pressure, Proximity, Infrared Application: Industrial Automation, Smart Home, Healthcare Monitoring, Agriculture Technology: IoT, Wireless, Bluetooth, Zigbee End User: Manufacturers, Consumers, Healthcare Providers, Researchers |
| Companies Covered | Robert Bosch GmbH, Honeywell International Inc., Analog Devices, NXP Semiconductors, Infineon Technologies, Texas Instruments, STMicroelectronics, TE Connectivity, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Sensors Market Strategic Shifts
Sensor architectures are converging with cloud-native platforms and low-power wireless protocols, compressing installation costs and enabling battery-constrained deployments previously requiring wired infrastructure.
Edge AI inference engines are integrating directly into sensor nodes, enabling localized anomaly detection without cloud round-trips. Process industries with latency-sensitive safety systems are adopting these modules fastest. This compression of decision-making to the device layer is integrating predictive capabilities into hardware previously limited to raw data transmission.
REACH substance restrictions are forcing substrate material substitutions for European market access. Industrial sensor manufacturers are reformulating encapsulants and conductor traces to maintain certification. Automotive and medical device segments are absorbing the highest compliance costs while awaiting standardized alternative material qualification protocols.
Facility operators are unbundling sensor procurement from building management system contracts, creating direct vendor relationships for calibration and replacement services. This disintermediation of traditional system integrators is most visible in German and Dutch commercial estate markets where technical buyer sophistication supports direct specification.
Connected Sensors Market Segmentation
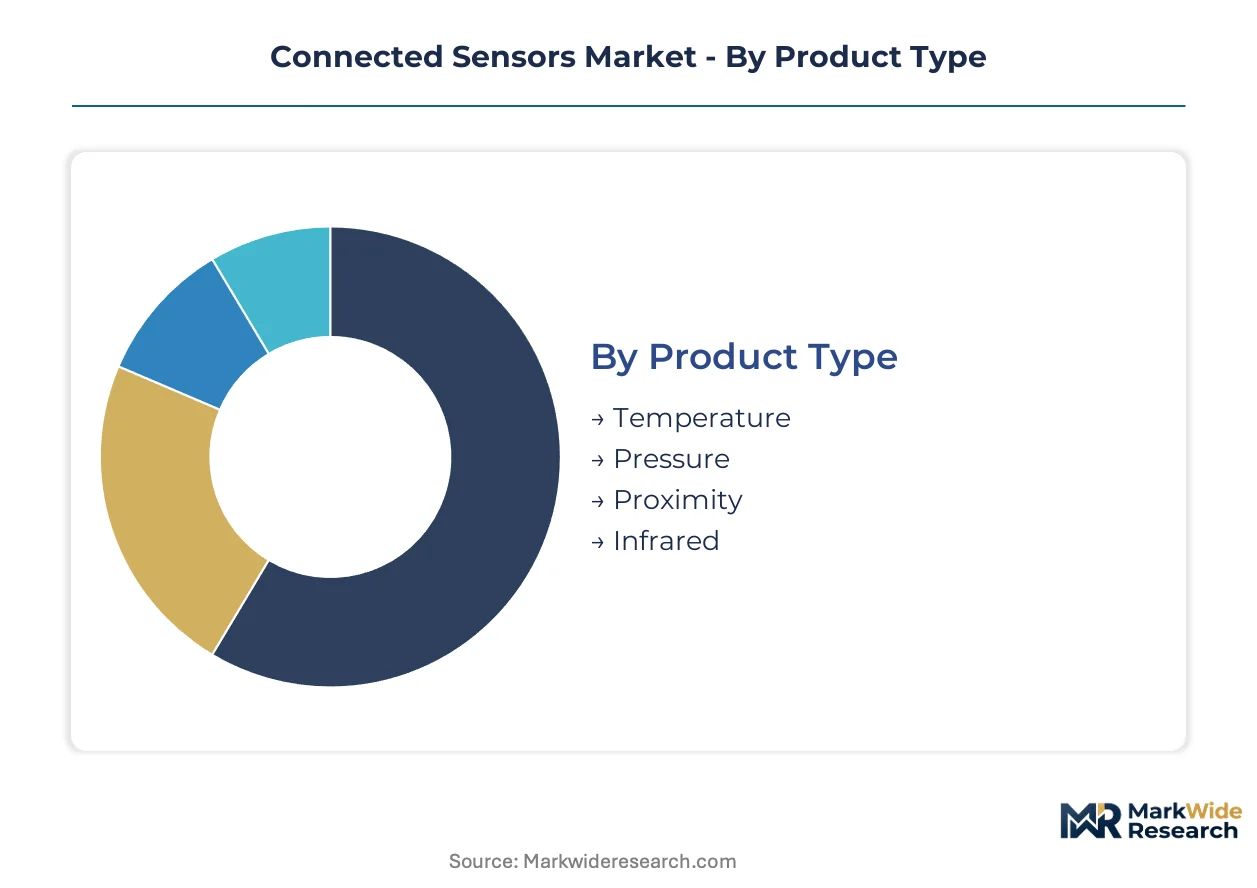
Connected sensors fragment across multiple technical and commercial dimensions, with upgrade cycles varying dramatically by installation environment. Retrofit timelines in building automation compress replacement windows, while industrial fieldbus displacement creates wholesale architecture shifts.
Product Type:
Replacement cycles diverge sharply between process-critical industrial variants and consumer-facing modules, with calibration requirements driving upgrade decisions.
- Temperature:Thermocouple and RTD elements combined with signal conditioning ASICs dominate process control installations. Refinery and chemical plant operators in Germany and Texas mandate annual recalibration, sustaining steady replacement demand.
- Pressure:MEMS capacitive and piezoresistive transducers measure fluid and gas states across automotive, HVAC, and industrial pipelines. Automotive OEMs in Stuttgart and Detroit specify AEC-Q100 qualified variants, tightening supplier qualification timelines.
- Proximity:Inductive and capacitive detection modules enable non-contact position sensing. Robotics integrators and warehouse automation deploy these most aggressively.
- Infrared:Thermal imaging arrays and motion detection elements capture heat signatures. Building security and fever-screening applications concentrate procurement.
Volume placements concentrate in Pressure; the faster expansion belongs to Proximity.
Application:
Cost tiers separate mission-critical industrial deployments from consumer installations where price sensitivity dominates specification.
- Industrial Automation:Ruggedized sensor arrays with IP67+ sealing and SIL-rated safety outputs monitor production lines and process vessels. German automotive suppliers and Korean semiconductor fabs drive specification complexity.
- Smart Home:Battery-operated environmental and occupancy modules integrate with cloud-native platforms. Installation growth concentrates in Dutch and Californian residential estates with aggressive electrification mandates.
- Healthcare Monitoring:Wearable and bedside devices capture vital signs with FDA and MDR regulatory overlays. Continuous glucose monitors and pulse oximeters absorb the highest unit volumes.
- Agriculture:Soil moisture and microclimate sensors enable precision irrigation. Israeli and Australian farming cooperatives lead adoption amid water scarcity pressures.
Revenue gravity sits with Industrial Automation; Smart Home climbs the fastest.
Technology:
Customer sophistication separates enterprise buyers demanding interoperability from consumers prioritizing setup simplicity.
- IoT:Cloud-native architectures with MQTT and CoAP protocols displace legacy SCADA installations. Industrial buyers in Michigan and Bavaria specify OPC-UA compatibility for digital twin integration.
- Wireless:Sub-GHz and 2.4 GHz proprietary radios serve long-range agricultural and utility applications. FCC and ETSI spectrum compliance shapes regional product variants.
- Bluetooth:Low Energy 5.x stacks dominate wearable health and residential automation where smartphone pairing streamlines onboarding.
- Zigbee:Mesh networking protocols concentrate in commercial building automation where self-healing topologies justify complexity.
Deployment scale favors IoT; Bluetooth gains share fastest.
End User:
Procurement authority and technical specification capability fragment the buyer landscape across direct OEM relationships and retail channels.
- Manufacturers:Automotive, chemical, and electronics producers specify sensors at the BOM level with multi-year supply agreements. Siemens and Bosch procurement teams enforce strict qualification protocols.
- Consumers:Retail purchasers drive smart home and personal health categories through Amazon and direct-to-brand channels. Installation simplicity outweighs calibration precision.
- Healthcare Providers:Hospital systems and clinics demand FDA-cleared devices with clinical evidence packages. Group purchasing organizations consolidate procurement for IDN networks.
- Researchers:Academic and government laboratories specify calibrated reference-grade instruments. National metrology institutes in Gaithersburg and Teddington set traceability standards.
Contract value concentrates with Manufacturers; Healthcare Providers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors concentrated sensor demand through automotive OEM procurement corridors. The EU Green Deal mandates energy-efficient building retrofits across German industrial estates, compressing deployment timelines for calibrated networks.
United States
Michigan and Texas industrial corridors drive factory-floor sensor specifications for automotive and chemical process monitoring. The EPA enforces emissions monitoring standards requiring certified networks at petrochemical facilities. Detroit automakers specify AEC-Q100 qualified pressure variants, tightening supplier qualification protocols.
Germany
Bavarian and Baden-Württemberg manufacturing clusters dominate European MEMS fabrication capacity for automotive pressure sensors. ECHA REACH compliance restricts hazardous substances in sensor substrates, forcing material substitutions for encapsulants. Stuttgart OEM procurement teams enforce multi-year supply agreements with MEMS foundries.
China
Yangtze River Delta electronics manufacturing concentrates IoT module assembly for export markets. MIIT governs wireless spectrum allocation for unlicensed industrial transmissions. Shenzhen ecosystem suppliers compress lead times for Bluetooth Low Energy stacks targeting smart home exports.
Japan
Kanto and Kansai industrial belts specialize in precision thermocouple and infrared sensor production for process control. METI promotes factory automation adoption through subsidy programs for SME digital transformation. Nagoya automotive suppliers integrate proximity modules into robotic welding lines.
South Korea
Seoul Capital Area semiconductor fabs supply MEMS wafers for smartphone and wearable sensor integration. MFDS regulates medical device sensor submissions for continuous glucose monitors. Suwon electronics conglomerates specify sub-milliwatt power budgets for battery-constrained health monitoring nodes.
Connected Sensors Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive MEMS fabrication. Robert Bosch GmbH and Siemens AG anchor European supply through integrated manufacturing depth. Three archetypes dominate: MEMS foundry-integrated conglomerates, building management system integrators, and fabless IoT module specialists. Capacity expansion in Taiwanese wafer facilities and strategic partnerships for cloud-native platform access represent the primary competitive vectors.
Within the MEMS-integrated tier, Robert Bosch GmbH exemplifies automotive and industrial sensor supply dominance through captive fabrication. Honeywell International Inc. occupies a position in North American building automation integration. Siemens AG sits within the factory-floor digital twin deployment segment with ruggedized sensor array offerings. These three entities represent distinct geographic and application anchoring strategies across automotive OEM specification, commercial estate management, and industrial predictive maintenance service models.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Honeywell International Inc. |
| Analog Devices |
| NXP Semiconductors |
| Infineon Technologies |
| Texas Instruments |
| STMicroelectronics |
| TE Connectivity |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal retrofit mandates are compressing procurement timelines for calibrated sensor networks across German industrial estates, forcing foundries to prioritize AEC-Q100 qualified MEMS capacity and compressing margins on non-automotive grades.
Pricing Analysis
Outcome-based pricing tied to energy savings realization dominates smart home and building automation tiers, with Siemens and Honeywell bundling sensor hardware into long-term facility management contracts. Price differentiation separates SIL-rated safety variants for process industries from consumer-grade environmental modules, with certification tier commanding premium multiples. Cost compression in Bluetooth Low Energy stacks reflects Shenzhen ecosystem competition and commoditized protocol licensing. Healthcare providers exhibit lowest price sensitivity due to FDA clearance requirements and liability exposure, while agricultural buyers drive hardest bargain on soil moisture sensor volumes.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart automotive procurement teams and Detroit Tier 1 suppliers, while distribution partners serve fragmented smart home and agricultural segments. MEMS wafer supply concentrates in Taiwan, Germany, and South Korea, drawing from silicon substrate and specialized photoresist inputs. Single-source vulnerability at TSMC and Bosch foundries creates allocation risk during automotive demand surges. Calibration service networks run through authorized regional laboratories to maintain EPA and ECHA traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected sensors are transitioning from wired fieldbus architectures to cloud-native IoT platforms, with MQTT and CoAP protocols displacing legacy SCADA installations across industrial estates.
For Market Incumbents: Cement captive MEMS fabrication advantage through backward integration into 200mm wafer capacity expansion in Baden-Württemberg. Lock in multi-year supply agreements with Stuttgart OEM procurement teams before ECHA REACH compliance costs escalate substrate reformulation expenses. Prioritize OPC-UA certification investment to defend against cloud-native platform entrants. For New Entrants and Emerging Players: Agricultural cooperatives in water-stressed regions represent underserved buyer archetype with unmet demand for sub-milliwatt soil moisture arrays. Target Israeli and Australian precision irrigation deployments where technical buyer sophistication supports direct specification bypassing traditional system integrators. Lead with Bluetooth Low Energy simplicity against mesh-complexity incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with fabless IoT module specialists given cloud-native platform convergence and digital twin service model expansion. Long-term viability favors entities with software recurring revenue attachment rather than hardware-only transactional exposure. Watch EPA emissions monitoring standard enforcement velocity as inflection indicator for industrial sensor network upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Captive wafer supply secures AEC-Q100 qualification timelines for Stuttgart automotive procurement. |
| Cloud-Native Platform Integration | MQTT protocol adoption displaces legacy SCADA in Michigan and Bavarian industrial corridors. |
| REACH-Compliant Material Reformulation | ECHA substance restrictions force encapsulant substitutions for European market access retention. |
| Calibration Service Network Buildout | EPA-mandated traceability requirements expand recurring revenue attachment at Texas petrochemical facilities. |
| Edge AI Module Development | Localized inference engines enable predictive maintenance contracts with Korean semiconductor fabs. |
Study Parameters
SEC 10-K filings, ECHA REACH substance databases, and EPA emissions compliance records formed the secondary backbone, supplemented by customs data tracking MEMS wafer trade flows. Primary interviews with MEMS foundry operations managers, building automation procurement directors, and agricultural cooperative technical buyers validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across product type and technology segments.
Historical trendline analysis of automotive sensor content per vehicle and building automation retrofit penetration rates anchored the projection framework. Segmentation modeling incorporated product type, application tier, communication protocol, and end-user procurement authority dimensions. CAGRs derived from curve-fitting observed replacement cycles against regulatory mandate timelines, with EU Green Deal compliance deadlines and EPA monitoring standard enforcement schedules as key forecast inputs.
Revisions become necessary when MEMS foundry allocation shocks, REACH substance restriction expansions, or wireless spectrum reallocation decisions materialize outside base-case assumptions. Forecasts reflect documented expectations regarding cloud-native platform adoption velocity and battery-constrained node cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Confocal Displacement Sensor Market