
 Electrical Bushings Market | 2026-2036
Electrical Bushings Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Bushings Market Intelligence
The proliferation of composite materials, particularly silicone, is reconfiguring design and performance standards for electrical bushings. ABB leverages its portfolio in high-voltage direct current (HVDC) applications to lead in advanced segments. Siemens specializes in developing SF6-free bushings to align with environmental regulations in Europe. Separately, Hitachi Energy sustains a strong market position through its established global supply chain for transformer components, anchoring its presence in the high-volume market.
An electrical bushing is an insulated device allowing a conductor to pass safely through a grounded barrier like a transformer tank. It provides critical dielectric insulation and mechanical support, using materials like porcelain or composite silicone. Composite bushings are gaining share from traditional porcelain types, especially for high voltage applications due to their lightweight and anti-pollution properties. The power transmission and renewable energy end-use sectors are primary consumers, particularly for medium and high voltage ratings.
Product standards are heavily influenced by international bodies like the IEC, with regional adherence to specifications like IEEE in the United States and GB standards in China. In Europe, environmental directives including the F-Gas Regulation are pushing manufacturers toward developing alternatives to SF6-insulated bushings. The key decision for asset owners revolves around balancing the higher upfront cost of advanced composite bushings against their lower lifecycle maintenance costs and improved grid reliability.
Market Dynamics
Grid modernization, driven by the integration of large-scale renewable energy projects and the adoption of HVDC transmission, is the central force reshaping the electrical bushings market. This transition demands higher-performance components capable of handling new electrical stresses.
Growth Catalysts
- Grid Expansion Projects:National infrastructure initiatives in countries like India and Brazil, aimed at enhancing grid capacity and connecting remote renewable energy sources, directly fuel demand for medium and high-voltage bushings.
- Composite Material Adoption:The superior performance of silicone composite bushings in polluted environments and seismic zones, coupled with their lighter weight, accelerates their use in high-voltage direct current (HVDC) transmission lines.
- Electrification Policies:Government mandates for transport and industrial electrification, such as those within the EU Green Deal, necessitate significant upgrades to substation and distribution networks, boosting component demand.
Market Restraints
- High Initial Cost:The higher upfront investment for advanced composite and HVDC bushings versus traditional porcelain can deter adoption in price-sensitive projects or economies with constrained capital.
- Porcelain Supply Concentration:The supply of high-quality electrical porcelain is concentrated in specific regions, creating potential vulnerabilities to logistical disruptions or trade policy shifts for manufacturers dependent on these inputs.
- Long-Term Reliability Data:While promising, newer composite materials lack the multi-decade, in-field operational history of porcelain, leading some conservative utility operators to defer adoption pending more extensive long-term performance validation.
Strategic Opportunities
- Energy Storage Systems:The global build-out of battery energy storage systems (BESS) creates a new application category for specialized bushings designed for the unique duty cycles of grid-scale batteries.
- Grid Modernization Funding:Programs like the US Inflation Reduction Act (IRA) provide substantial funding for grid upgrades, creating a direct opportunity for suppliers of high-performance bushings that enhance grid resilience.
- African Grid Development:Underpenetrated markets in sub-Saharan Africa present growth potential as nations build out national transmission and distribution backbones to support economic development.
Industry Challenges
- Specialized Skill Gaps:A shortage of technicians and engineers skilled in the installation and maintenance of advanced UHV and HVDC bushing technologies can slow project execution and increase operational risks.
- Complex Compliance Pathways:Manufacturers face long and costly certification processes to meet varying standards, such as IEC, IEEE, and China's GB standards, which can delay market entry for new products.
- Legacy System Integration:Integrating modern composite bushings, especially for HVDC, with aging substation infrastructure and legacy AC equipment presents significant technical hurdles for asset owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Bushings Market |
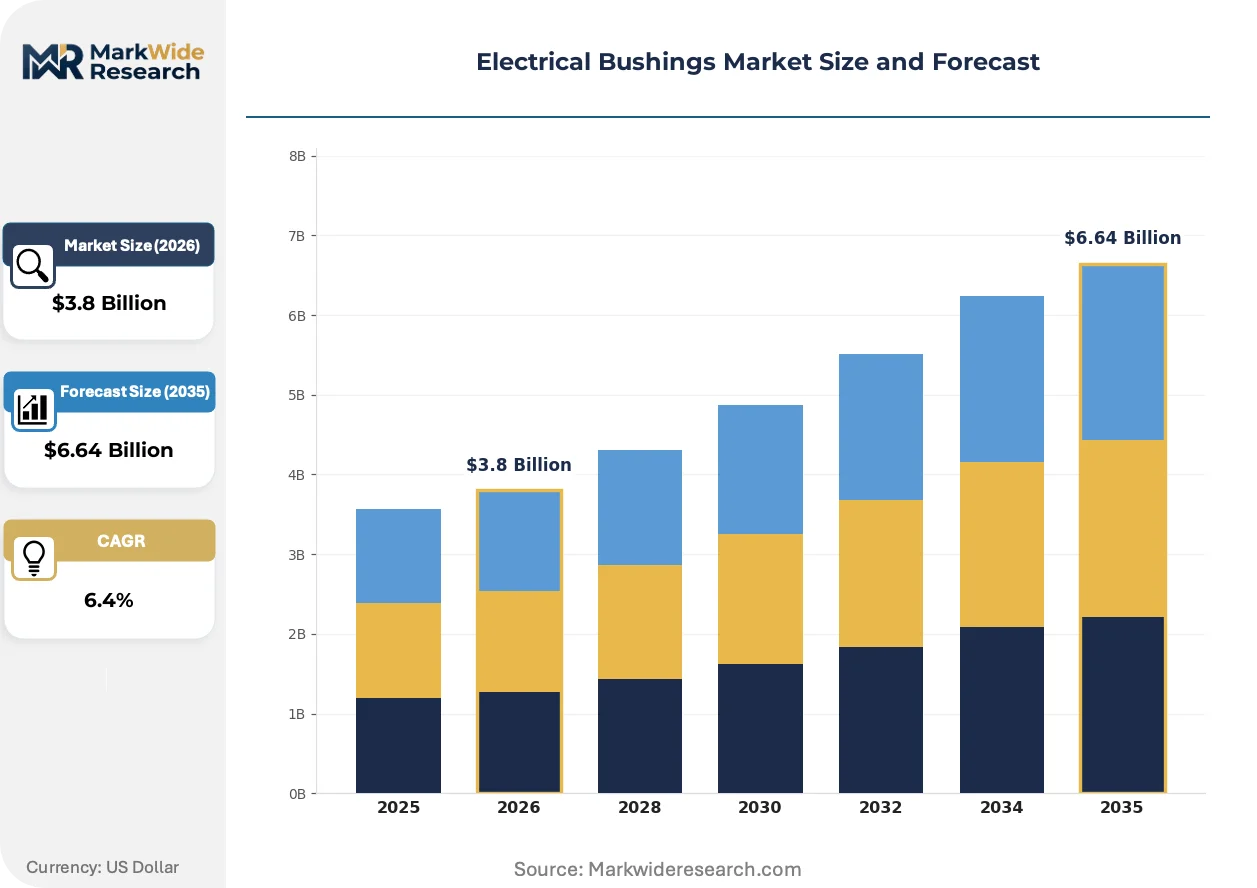
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porcelain Bushings, Composite Bushings, Silicone Bushings, Resin Bushings Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage End Use: Power Generation, Power Transmission, Renewable Energy, Industrial Applications Installation Type: Indoor Installation, Outdoor Installation, Substation Installation, Transformer Installation |
| Companies Covered | Hitachi Energy Ltd., Eaton, ABB, Toshiba, Nexans, Siemens, Trench Group, RHM International, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Bushings Market Strategic Shifts & Innovations
Material science advancements and stringent environmental regulations are accelerating development cycles for electrical bushings. These forces are compelling a move toward more sophisticated, reliable components designed for a decarbonized and decentralized power grid.
Composite bushings use a fiberglass core with silicone rubber sheds for insulation. Transmission system operators are rapidly adopting this technology for high-voltage lines due to its superior anti-pollution and seismic performance. This trend is collapsing the long-held trade-off between mechanical durability and lightweight design, a compromise inherent in heavier porcelain insulators.
The European Union's F-Gas Regulation mandates a phasedown of potent greenhouse gases, including sulfur hexafluoride (SF6). This directly impacts the design of gas-insulated equipment, which has historically relied on SF6 for its dielectric properties. The high-voltage bushing segment is responding by commercializing SF6-free alternatives that utilize dry air or alternative gas mixtures to meet environmental targets.
A notable shift in purchasing criteria emphasizes total cost of ownership and grid reliability over initial unit price. The traditional procurement model focused on low-cost porcelain components is being challenged by utility specifications that favor bushings with lower lifecycle maintenance needs. This behavior is most evident in North American and European markets where performance-based regulations penalize grid outages.
Electrical Bushings Market Segmentation
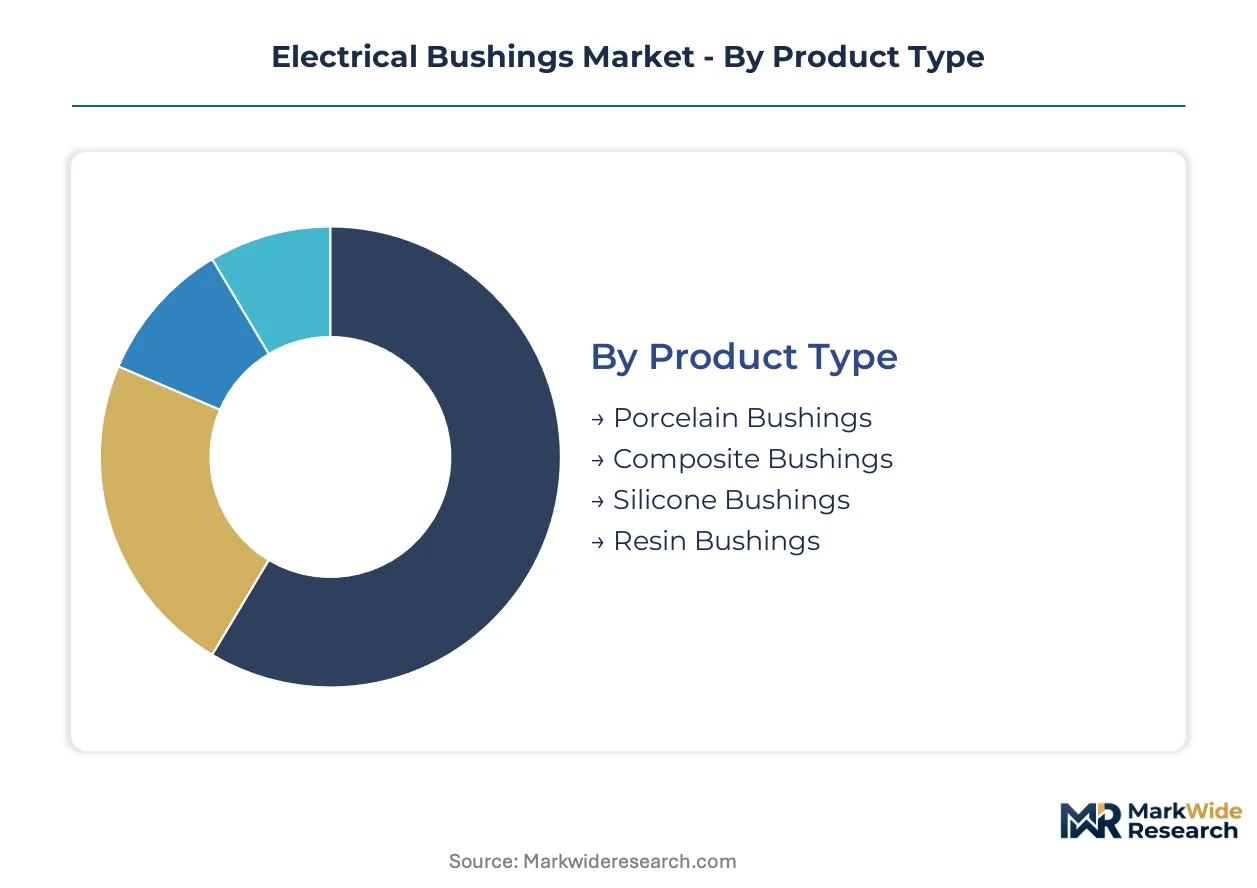
The electrical bushings market segments across various product types, voltage ratings, end-use applications, and installation environments. Understanding these distinct segments provides clarity on demand drivers, technological preferences, and operational challenges for grid operators. Each category reflects unique requirements for insulation, mechanical integrity, and environmental resilience.
Product Type:
After-sales-service intensity for electrical bushings varies significantly by product type, impacting long-term operational expenditures for utilities.
- Porcelain Bushings:Traditional ceramic insulators provide dielectric strength, prevalent in older grid infrastructure and price-sensitive markets like India.
- Composite Bushings:Fiberglass core with silicone rubber sheds offers superior anti-pollution performance and lightweight properties. Demand concentrates in HVDC transmission projects across Europe and North America.
- Silicone Bushings:Utilizing silicone rubber, these bushings excel in polluted or seismic regions, providing robust dielectric properties. Adoption accelerates in renewable energy connections in Brazil.
- Resin Bushings:Epoxy resin is the insulating medium, used in GIS and indoor applications. Resin bushings offer compact designs for constrained substation spaces.
By volume, Porcelain Bushings lead the established market. By growth pace, Composite Bushings are ahead.
Voltage Rating:
The application landscape for electrical bushings dictates specific voltage rating requirements, from local distribution to ultra-high-power transmission.
- Low Voltage:Bushings below 1 kV serve residential and commercial distribution panels, crucial for local power delivery in US urban centers.
- Medium Voltage:Devices from 1 kV to 72.5 kV, common in industrial facilities and substation distribution. Essential for connecting distributed generation in Germany.
- High Voltage:Bushings operating between 72.5 kV and 300 kV, forming regional transmission networks. Demand concentrates in grid modernization initiatives in China.
- Extra High Voltage:Components above 300 kV, critical for long-distance power transmission and HVDC interconnections. Deployment accelerates in cross-border energy projects in Scandinavia.
High Voltage applications command the largest market share. Extra High Voltage demonstrates the steepest expansion trajectory due to HVDC deployment.
End Use:
The total cost of ownership for electrical bushings varies significantly across end-use sectors, influenced by operational demands and environmental exposure.
- Power Generation:Bushings integrated into generators and power plant transformers, designed for continuous operation, vital for thermal and hydropower facilities in Canada.
- Power Transmission:Components in high-voltage lines and substations transfer electricity over long distances. Demand concentrates in national grid expansion programs in India.
- Renewable Energy:Specialized bushings for connecting wind farms, solar plants, and intermittent sources to the grid. Adoption accelerates in large-scale offshore wind projects in the UK.
- Industrial Applications:Bushings in heavy industrial settings like mining and manufacturing often require bespoke designs. Critical for process industries in Japan.
Power Transmission represents the largest end-use segment. Renewable Energy projects drive substantial new demand for specialized components.
Installation Type:
Supply concentration for specific installation types reflects specialized manufacturing processes and logistical requirements for large-scale grid components.
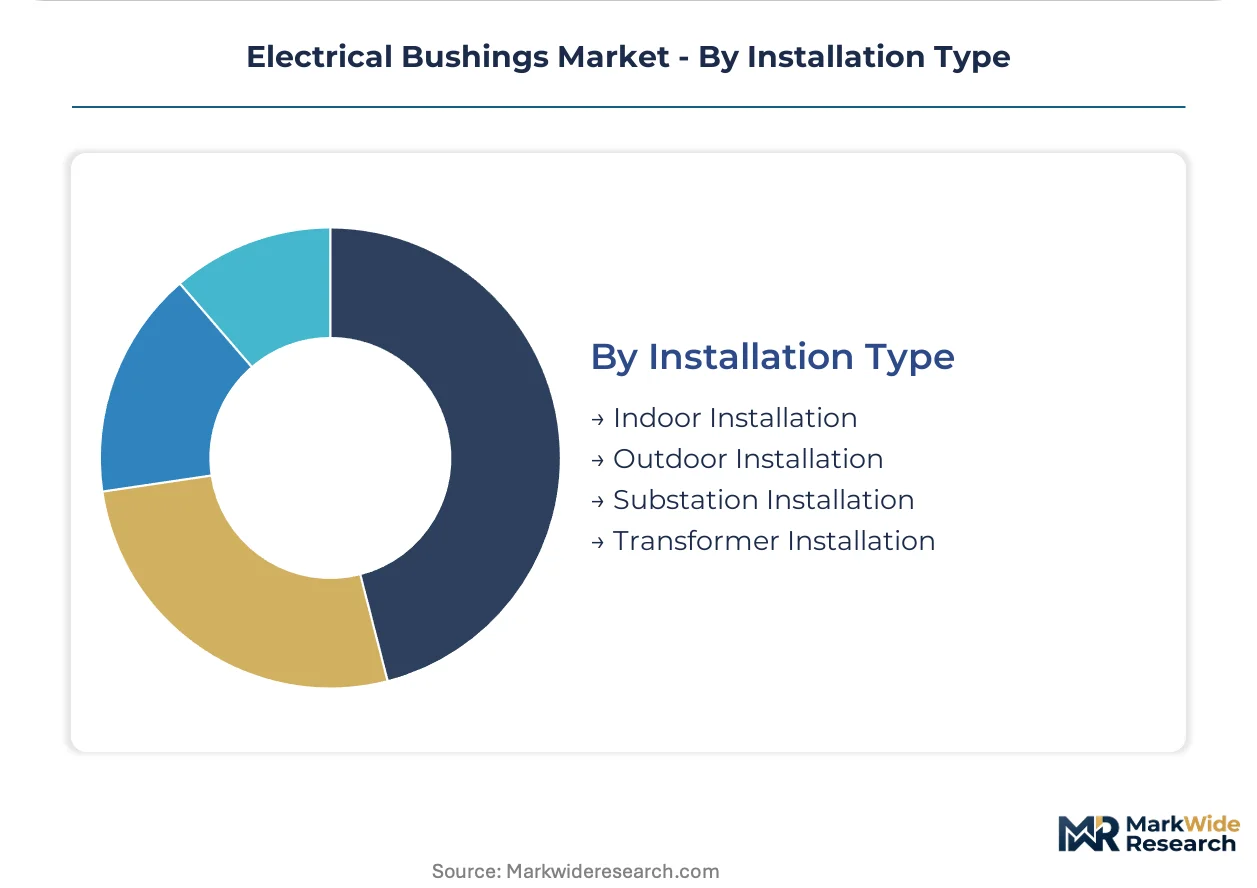
- Indoor Installation:Bushings for controlled environments within buildings or enclosed switchgear, prioritizing compactness and safety, common in urban substations in France.
- Outdoor Installation:Components exposed to varying weather conditions, requiring robust insulation and UV resistance. Demand concentrates in extensive transmission line projects across Australia.
- Substation Installation:Bushings forming critical interfaces within electrical substations, connecting transformers, circuit breakers, and busbars. Deployment accelerates in new substation builds in Saudi Arabia.
- Transformer Installation:Bushings designed to pass conductors through transformer tanks, providing insulation and mechanical support. Foundational for power transformers globally.
Outdoor Installation accounts for the majority of installations. Transformer Installation remains a steady, foundational segment for grid infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust export of electrical components to emerging markets underpins significant regional demand. The global electrical bushings market experiences varied growth patterns driven by regional infrastructure investments. Each continent presents distinct regulatory landscapes and electrification priorities for grid development.
India
National infrastructure initiatives and large-scale grid modernization projects drive substantial demand for medium and high-voltage bushings in India. The government's PLI scheme for advanced energy components encourages domestic manufacturing capabilities. Major transmission corridor projects across the Delhi-NCR region and other industrial hubs require significant bushing deployment.
Brazil
Continued expansion of renewable energy capacity, particularly for connecting wind and solar farms, accelerates bushing adoption in Brazil. The country's energy sector benefits from policies supporting grid expansion and modernization efforts. São Paulo and other urban centers are experiencing significant upgrades to substation infrastructure.
Germany
Environmental regulations, including the F-Gas Regulation, compel a shift towards SF6-free bushing alternatives in Germany and across Europe. The EU Green Deal mandates extensive grid upgrades to integrate renewable energy sources. Research and development clusters in Bavaria and North Rhine-Westphalia focus on advanced composite materials.
China
Large-scale grid modernization and expansion projects, especially in HVDC transmission, fuel demand for high-performance bushings in China. Adherence to GB standards ensures product quality and safety across the national grid. State Grid Corporation projects in the Yangtze River Delta region are driving significant new installations.
United States
Substantial funding through the US Inflation Reduction Act (IRA) supports grid upgrades and the build-out of battery energy storage systems, creating new bushing applications. FERC regulations emphasize grid reliability and resilience, favoring advanced composite solutions. Extensive transmission line projects across California and the Southwest require specialized components.
Electrical Bushings Market Key Industry Players
On the supply side, the industry is moderately concentrated, with a few large, diversified players alongside numerous specialized regional manufacturers. This structure creates distinct archetypes: integrated power technology conglomerates and focused bushing specialists. Dominant competitive moves include strategic partnerships for advanced material development and geographical expansion into high-growth grid modernization markets. Companies also focus on portfolio diversification into HVDC-specific componentry.
Integrated power technology conglomerates like ABB and Siemens exemplify the diversified approach, leveraging extensive engineering capabilities across multiple grid components. These firms often lead in advanced segments, such as high-voltage direct current applications, and actively respond to environmental regulations. Hitachi Energy Ltd. represents a major player with a strong market position, anchoring its presence through an established global supply chain for transformer components. Such entities focus on long-term partnerships and comprehensive solution provisioning for national grid operators.
| Leading Market Players |
|---|
| Hitachi Energy Ltd. |
| Eaton |
| ABB |
| Toshiba |
| Nexans |
| Siemens |
| Trench Group |
| RHM International |
| General Electric |
| Others |
Cost & Logistics Intelligence
Porcelain supply concentration in specific regions like China and India directly influences the cost structure of traditional bushings, impacting overall project margins for grid operators. This concentration also affects the availability and pricing of raw materials for manufacturers globally.
Pricing Analysis
The pricing gap between advanced composite and traditional porcelain bushings drives procurement decisions across utilities. Project-based pricing dominates for high-voltage installations, reflecting custom engineering requirements. Price differentiation stems from material quality, such as silicone versus porcelain, and adherence to international certification standards like IEC or IEEE. Pricing softness affects the established porcelain segment due to high volume production and intense competition. Utility operators are highly price-sensitive for initial unit costs in brownfield projects, while HVDC project developers prioritize long-term value and grid reliability.
Supply Chain Analysis
Contract manufacturing for electrical bushings concentrates in countries like China, India, and Germany, leveraging established industrial bases. The industry relies heavily on specialized inputs such as high-grade electrical porcelain, silicone rubber, and epoxy resins. A key supply chain risk involves the vulnerability of porcelain supply to geopolitical shifts or trade policy changes affecting specific regions. Distribution primarily runs through direct sales channels to large utility companies and EPC contractors for major infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical bushings market is experiencing high-growth disruption, driven by the rapid shift to HVDC transmission and renewable energy integration.
For Market Incumbents: Entrench market leadership by investing in advanced composite material research and development for HVDC applications. Consolidate regional supply chains to mitigate risks from porcelain supply concentration and ensure input security. The threat of SF6-free mandates from regulations like the EU F-Gas Regulation requires proactive portfolio diversification into alternative dielectric solutions. Leverage existing customer relationships to cross-sell new technology upgrades.
For New Entrants and Emerging Players: Underpenetrated markets in sub-Saharan Africa offer significant growth opportunities for specialized bushing solutions. Target grid modernization projects in India and Brazil with cost-effective, high-performance composite offerings tailored to local environmental conditions. Focus on value-added services like installation, commissioning, and long-term maintenance for new HVDC interconnections. Develop expertise in specific voltage ratings or end-use applications to differentiate.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized specialists in composite and SF6-free bushing technologies with proven track records. Long-term viability hinges on companies capable of navigating complex international standards and providing solutions for enhanced grid reliability. Watch for increasing utility specifications prioritizing total cost of ownership over initial unit price as a key inflection signal. Target firms with strong intellectual property in advanced materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop SF6-free HVDC bushings | Siemens and other manufacturers address environmental regulations and utility demand in Germany. |
| Expand composite bushing manufacturing capacity | ABB can meet the growing demand from renewable energy projects in the United States. |
| Form strategic partnerships for grid integration | Hitachi Energy can offer comprehensive solutions for complex substation upgrades in China. |
| Invest in specialized training for installation | Companies can bridge skilled labor gaps for advanced UHV and HVDC technologies globally. |
| Acquire battery energy storage system bushing specialists | Diversified players can capture new application categories in the US energy market. |
Research Approach
Operator-level perspectives from utility planning officers, EPC contractors, transformer manufacturers, and material scientists anchored the qualitative base. This involved combining primary interviews with extensive secondary data validation. Secondary sources included national grid expansion reports, IEC and IEEE standards documents, and corporate sustainability filings. Bottom-up market sizing was cross-referenced with top-down industry reports to ensure data accuracy.
Scenario-bracketing across optimistic and conservative growth trajectories informed the forecast framework over the projection horizon. The analytical approach integrated segmentation across product type, voltage rating, end-use, and installation environment, alongside regional electrification policies. Compound annual growth rates were derived from historical data and projected adoption curves for new technologies. Key forecast inputs included planned grid modernization investments and renewable energy deployment targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated power technology conglomerates or specialized material science firms would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Quarterly review of major grid project announcements and material science breakthroughs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
Air Circuit Breaker Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Global Copper Clad Steel (CCS) Wire Market