
 United Kingdom Thermal Protector Market | 2026-2036
United Kingdom Thermal Protector Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Thermal Protector Market Insights
Commercial HVAC contractors is collapsing as the dominant buyer archetype while data center operators and electric vehicle charging infrastructure deployers gain procurement share. Sensata Technologies Holdings PLC leverages its bi-metallic protector portfolio to anchor relationships with UK white goods manufacturers. Schneider Electric competes through integrated thermal management within building automation systems. ABB Ltd. dominates industrial motor protection through direct specification by OEM engineering teams.
A thermal protector is a temperature-sensitive safety device that interrupts electrical circuits when operational thresholds exceed design limits, typically employing bimetallic strip deflection, positive temperature coefficient ceramic resistance escalation, or fusible alloy melting to achieve cutoff. These devices safeguard motors, transformers, and heating elements from fire risk and insulation degradation across continuous-duty industrial environments. Bi-metallic variants lead volume shipments into home appliances and power tools where cycling durability matters, while electronic sensors capture margin pools in data center cooling and telecommunications infrastructure demanding precise reset capability and remote monitoring integration. Thermal fuse applications mature within lighting fixtures as LED driver architectures reduce overall protector count per installation.
The UK's BEIS enforces ecodesign regulations through the Office for Product Safety and Standards that mandate thermal protection integration in higher-efficiency motor classes, while Building Regulations Part L drives protector specification in new HVAC and lighting retrofits across commercial stock. BSI standards for electrical equipment safety create compliance baselines that favor certified suppliers with established UKCA marking pathways. Stakeholders must monitor how the UK's divergence from EU harmonized standards post-Brexit reshapes certification costs and supplier qualification timelines for imported protector assemblies.
Market Dynamics
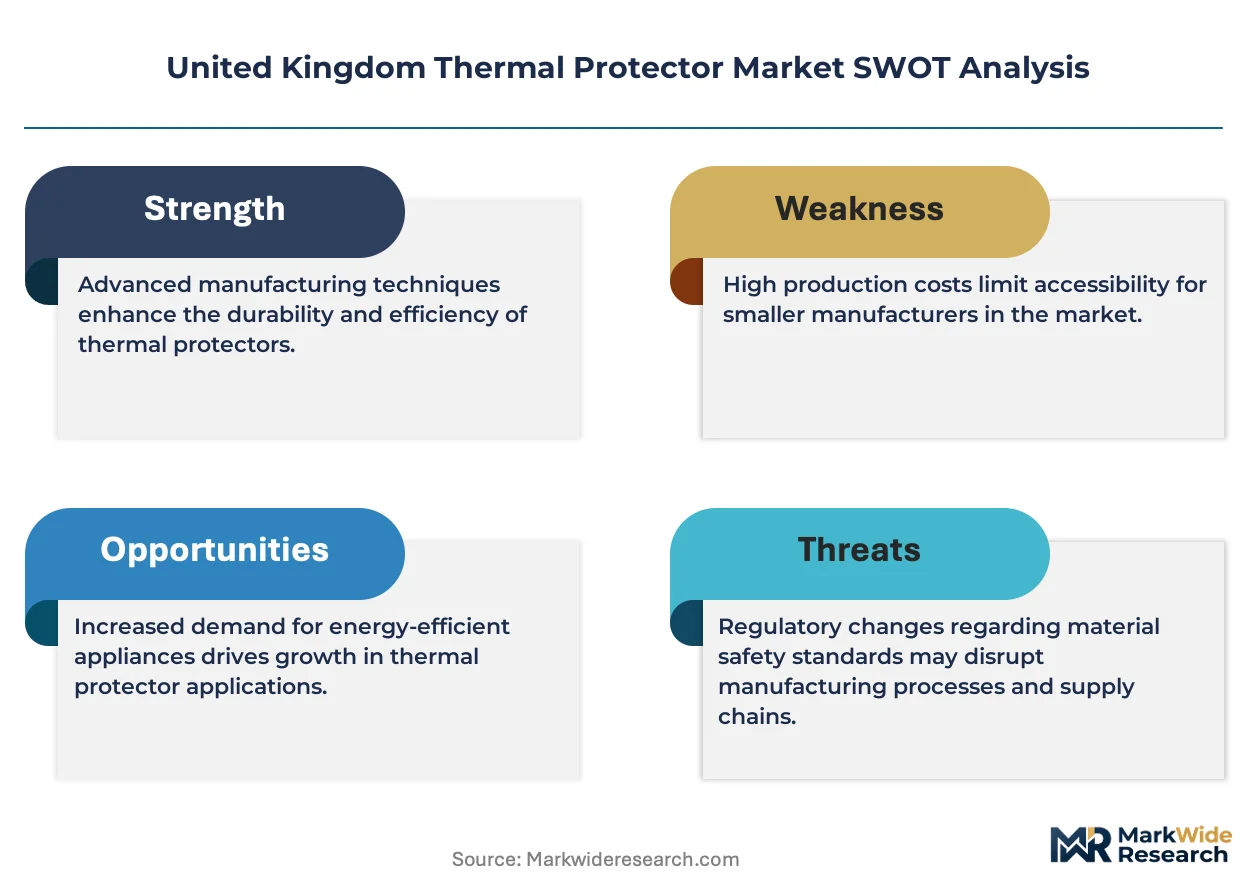
The UK's Net Zero Strategy and tightening Building Regulations Part L are compressing replacement cycles across HVAC and lighting stock, while domestic appliance manufacturers accelerate procurement of bi-metallic and electronic sensor variants to meet ecodesign mandates.
Growth Catalysts
- Building Regulations Part L:The UK's tightening energy efficiency standards for new and retrofitted commercial buildings mandate thermal protector integration in HVAC systems, accelerating specification rates across England's commercial retrofit sector.
- Data center cooling infrastructure:Hyperscale operators in Slough, London, and Manchester are deploying electronic thermal sensors with remote monitoring capabilities to protect critical server environments from thermal runaway.
- Electric vehicle charging hardware:Rapid charger deployers across the Midlands and Southeast England require high-reset-precision protectors to safeguard power electronics under variable load cycling.
Market Restraints
- UKCA marking transition costs:Post-Brexit divergence from EU harmonized standards forces protector suppliers to maintain dual certification pathways, elevating compliance overhead for imported assemblies.
- Copper and silver price volatility:Bi-metallic strip production depends on these base metals, exposing manufacturers to commodity swings that compress margin pools on high-volume appliance contracts.
- Electronic sensor substitution:Solid-state temperature monitoring with integrated microcontrollers threatens discrete thermal protector volumes in premium industrial motor applications.
Strategic Opportunities
- Scottish renewable energy clusters:Offshore wind turbine nacelle manufacturers in Aberdeen and Glasgow represent underpenetrated demand for ruggedized thermal protection in generator and converter systems.
- Smart building convergence:Integration of thermal protectors with BACnet and Modbus protocols creates white space for sensor suppliers to capture recurring software revenue alongside hardware sales.
- Net Zero Strategy retrofit incentives:Government-backed financing for commercial building decarbonization accelerates protector replacement cycles in aging HVAC infrastructure across Northern England.
Industry Challenges
- UKCA technical documentation gaps:Third-party conformity assessment body capacity constraints delay certification timelines for new protector variants, compressing product launch windows.
- Legacy motor stock incompatibility:Industrial end-users in Yorkshire and the West Midlands face integration complexity when retrofitting electronic sensors onto pre-2000 motor frames lacking standardized mounting configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Thermal Protector Market |
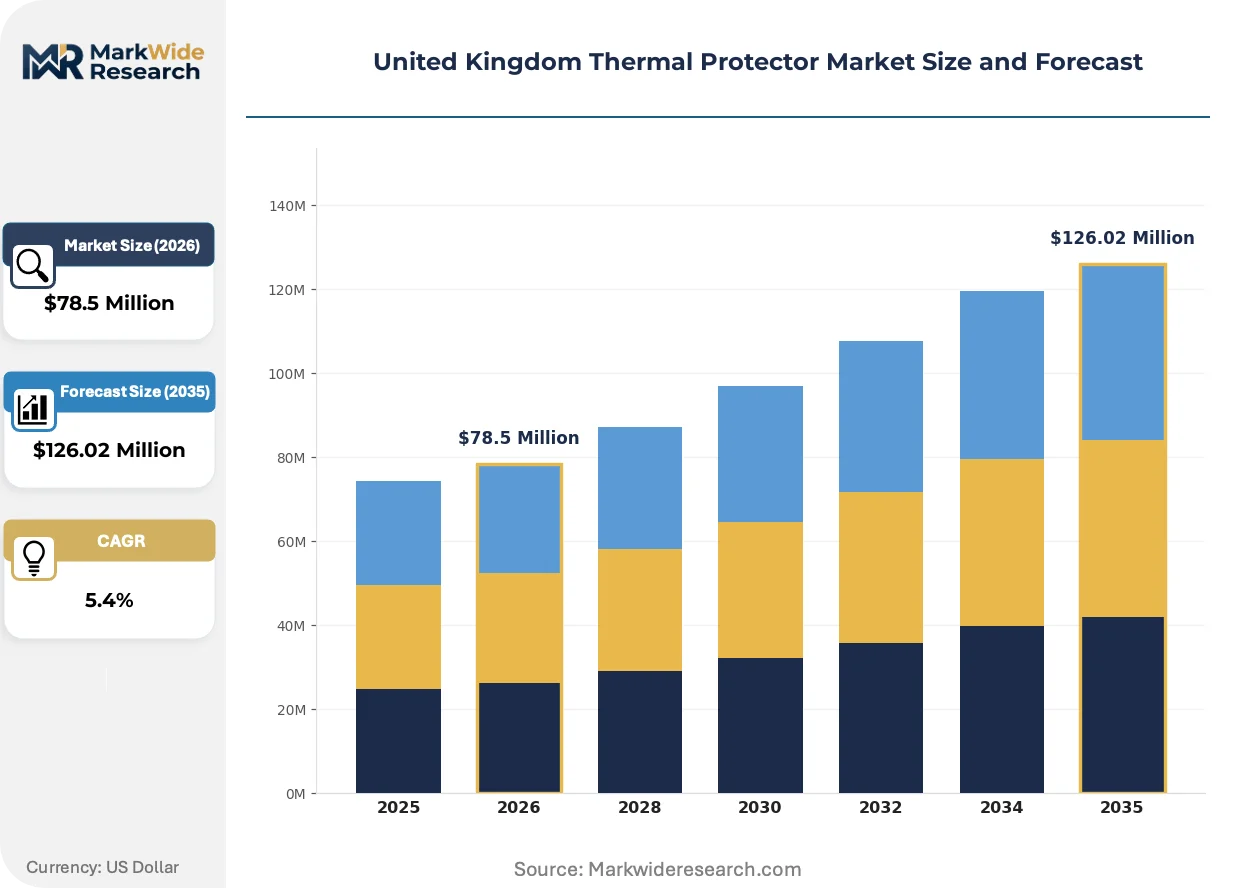
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $126.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bi-metallic, PTC Thermistor, Thermal Fuse, Electronic Sensor, Electric Reset Application: Home Appliances, HVAC Systems, Office Equipment, Power Tools, Lighting Fixtures End User Industry: Manufacturing Plants, Data Centers, Construction Firms, Transportation Services, Telecommunications Distribution Channel: Direct Sales, Online Retail, Authorized Distributors, Industrial Suppliers, Electrical Wholesalers |
| Companies Covered | Sensata Technologies Holdings PLC, Portage Electric Products, Inc., Thermtrol Corporation, Calco Electric Corp., ABB Ltd., Schneider Electric, Haier Smart Home Co., Ltd., Changshu Tianyin Electromechanical Co., Ltd., Seki Controls Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Thermal Protector Market Trends and Innovations
Digital sensing architectures and wireless connectivity protocols are reconfiguring how thermal protection integrates with building automation and predictive maintenance systems across UK industrial and commercial estates.
Surface-mount positive temperature coefficient thermistors are miniaturizing thermal protection footprints in LED driver modules and compact power tool motors. Domestic appliance OEMs in the West Midlands are adopting these ceramic sensors at accelerating pace to free PCB real estate for additional smart features. This dimensional compression is miniaturizing protector assemblies while maintaining trip precision, enabling slimmer product form factors that command shelf-space premiums in retail channels.
The Office for Product Safety and Standards enforces ecodesign regulations through BEIS that mandate thermal protection in higher-efficiency motor classes sold into the UK market. These rules disqualify uncertified imports from procurement shortlists and elevate documentation burdens on non-UK suppliers. Industrial motor OEMs respond by pre-qualifying protector vendors with established UKCA marking pathways, consolidating specification authority around domestic distributors with regulatory expertise.
Direct procurement contracts between data center operators and sensor manufacturers are disintermediating traditional electrical wholesale channels for high-specification electronic protectors. Tier-1 cloud infrastructure deployers in London and Manchester now negotiate multi-year supply agreements with resettable sensor specialists, bypassing distributors to secure volume pricing and custom firmware integration. This channel compression concentrates margin capture with manufacturers capable of delivering application-engineered solutions at scale.
United Kingdom Thermal Protector Market Segmentation
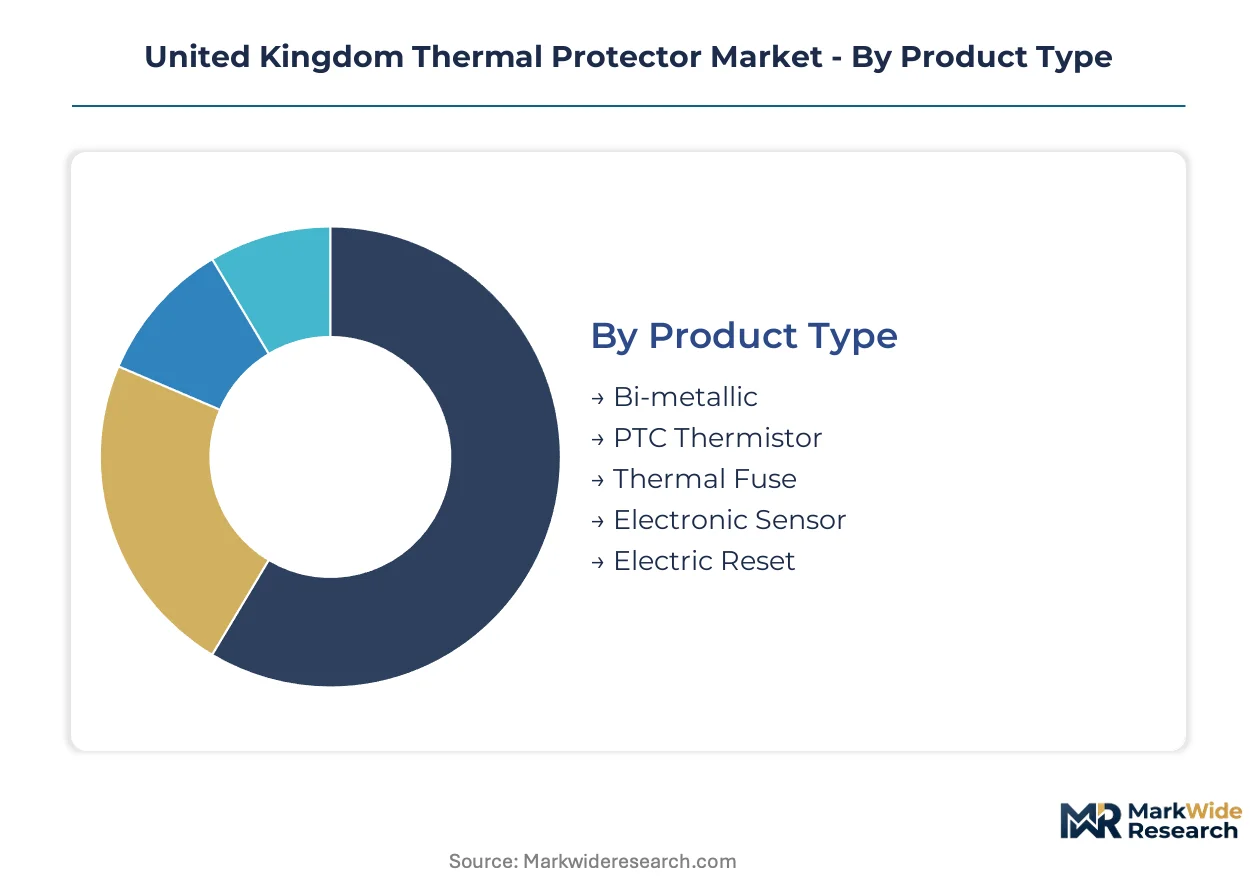
Thermal protector procurement patterns diverge sharply across product architectures and end-use environments, with channel strategies varying by technical complexity and volume scale. Understanding these segment boundaries clarifies where specification authority concentrates and how suppliers must configure their go-to-market approaches.
Product Type:
Channel mix varies by reset capability and precision requirements, with bi-metallic variants flowing through industrial suppliers while electronic sensors move via direct manufacturer relationships.
- Bi-metallic:These electromechanical devices employ bonded copper-steel strips that deflect with temperature change to break circuits. Manufacturing plants across England's Midlands corridor specify these for motor protection in continuous-duty industrial environments where cycling durability outweighs precision needs.
- Electronic Sensor:Solid-state temperature monitors with microcontroller integration enable remote diagnostics and programmable thresholds. Data centers in Slough and Manchester procure these directly from sensor specialists, bypassing wholesale channels to secure custom firmware and multi-year supply agreements.
- PTC Thermistor:Ceramic positive temperature coefficient devices self-limit current by resistance escalation at threshold temperatures, finding growing specification in West Midlands appliance OEMs seeking PCB space efficiency.
- Thermal Fuse:Single-use fusible alloy devices provide irreversible cutoff protection, dominating lighting fixture applications where LED driver architectures demand compact, cost-optimized safety integration.
- Electric Reset:Manual or automatic reset mechanisms allow service restoration without component replacement, appealing to transportation services and remote telecommunications infrastructure where maintenance access is constrained.
Bi-metallic variants dominate installed base across legacy industrial motor stock. Electronic sensors are where expansion concentrates as building automation and predictive maintenance architectures proliferate.
Application:
Cost tier stratification separates specification-driven commercial retrofits from price-sensitive consumer goods manufacturing, with margin pools concentrating where regulatory mandates enforce thermal protection integration.
- HVAC Systems:Compressor and fan motor protection in commercial heating, ventilation, and air conditioning equipment. Building Regulations Part L enforcement across Greater London's commercial retrofit sector accelerates replacement cycles and elevates specification rates for certified protector assemblies.
- Home Appliances:Washing machines, refrigerators, and cooking equipment requiring cycling durability under intermittent load patterns. West Midlands white goods manufacturers represent concentrated procurement volume, though margin compression from commodity metal exposure limits supplier profitability.
- Power Tools:Compact motor protection in handheld and benchtop equipment where miniaturization trends favor surface-mount thermistor integration over discrete bi-metallic assemblies.
- Lighting Fixtures:LED driver thermal management where traditional fuse counts decline per installation as driver architectures consolidate protection functions, maturing this application segment.
- Office Equipment:Printer and copier thermal safeguards in commercial building deployments, typically procured through authorized distributors serving facilities management contractors.
HVAC systems command premium pricing tiers due to regulatory compliance burdens. Home appliances represent the highest volume trajectory though with thinner margins.
End User Industry:
Customer type differentiation separates specification-authority buyers with engineering integration capabilities from procurement-driven purchasers relying on distributor technical support.
- Data Centers:Hyperscale operators and colocation providers protecting critical server and cooling infrastructure. These buyers possess in-house thermal engineering expertise and negotiate direct supply agreements with sensor manufacturers, disintermediating traditional electrical wholesale channels.
- Manufacturing Plants:Industrial motor and transformer protection in continuous-process environments across Yorkshire and West Midlands manufacturing belts. Maintenance departments typically procure through established industrial supplier relationships with technical field support.
- Construction Firms:New build and retrofit commercial projects where M&E contractors specify protectors during HVAC and lighting system installation, influenced by Part L compliance requirements and developer sustainability targets.
- Transportation Services:Electric vehicle charging infrastructure and rail electrification systems requiring high-reset-precision protection under variable load cycling, with procurement concentrated among rapid charger deployers across the Midlands and Southeast England.
- Telecommunications:Base station and exchange equipment thermal management where remote monitoring integration and extended service intervals drive electronic sensor preference over electromechanical alternatives.
Manufacturing plants retain the largest installed base of legacy bi-metallic protectors. Data centers are climbing the fastest as a demand segment through direct procurement channel expansion.
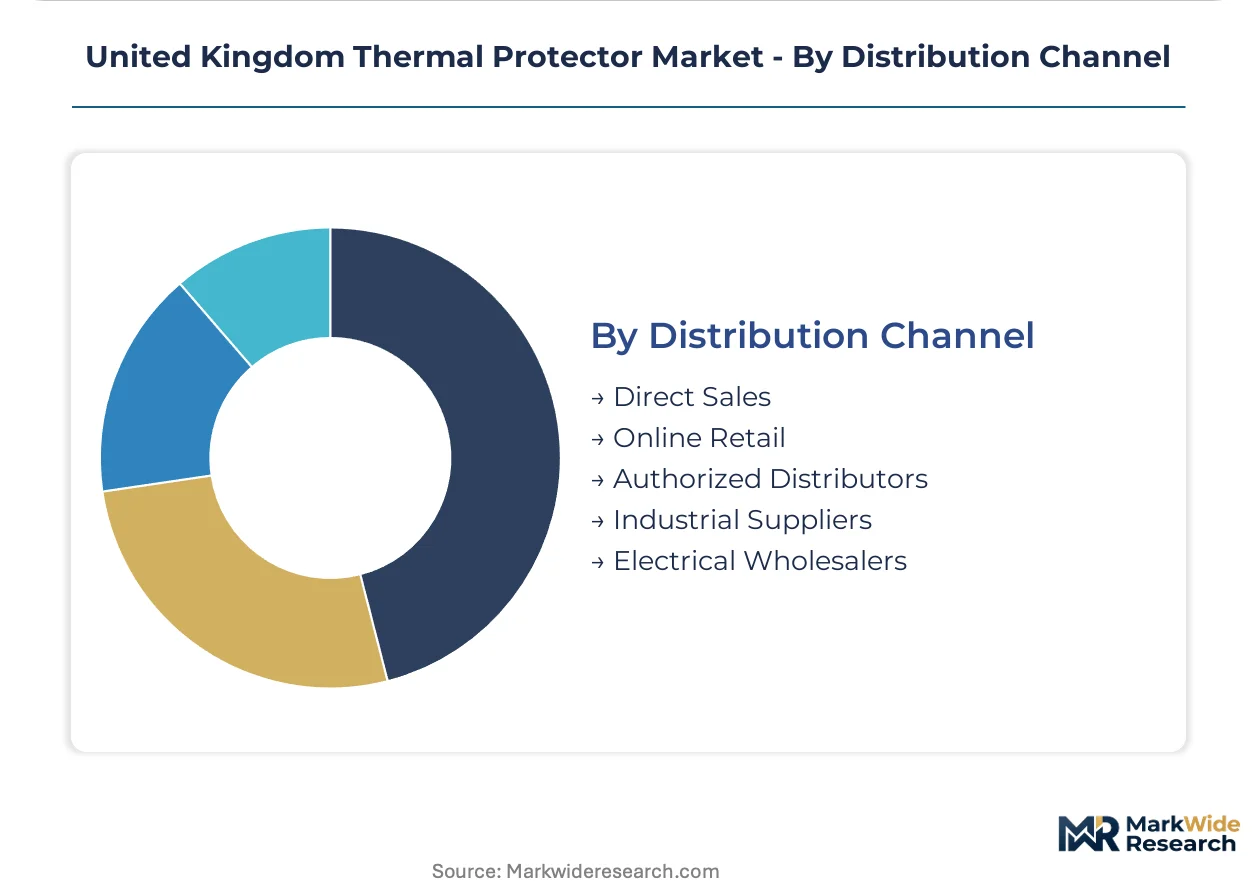
Distribution Channel:
Volume concentration determines channel efficiency, with high-volume appliance contracts favoring direct manufacturer engagement while fragmented maintenance, repair, and operations demand flows through distributor networks.
- Direct Sales:Manufacturer-to-OEM relationships for high-volume, specification-driven procurement. Domestic appliance manufacturers in the West Midlands and data center operators in London and Manchester leverage these channels for volume pricing and application engineering support.
- Electrical Wholesalers:Traditional branch-based distribution serving M&E contractors and maintenance departments across England's commercial retrofit sector, though losing share in high-specification electronic sensor categories.
- Authorized Distributors:Value-added resellers with UKCA marking expertise and technical documentation capabilities, capturing specification authority where regulatory compliance complexity elevates service requirements.
- Industrial Suppliers:Integrated maintenance, repair, and operations distributors serving manufacturing plants with consolidated electrical and mechanical component procurement, strong in Yorkshire and West Midlands industrial corridors.
- Online Retail:E-commerce platforms capturing price-sensitive, low-complexity transactions for standard bi-metallic protectors in replacement and small-project applications, with limited penetration in certified or engineered product categories.
Electrical wholesalers retain broadest reach across fragmented buyer bases. Direct sales are gaining share fastest as specification authority concentrates with large OEM and infrastructure deployers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M6 motorway corridor and its freight arteries underpin England's dominance in thermal protector procurement, connecting West Midlands manufacturing clusters with distribution hubs serving Greater London's commercial retrofit sector.
England's Midlands Manufacturing Corridor
West Midlands appliance OEMs drive bi-metallic protector volume through washing machine and refrigerator production lines. BEIS ecodesign regulations mandate thermal protection integration in higher-efficiency motor classes, disqualifying uncertified imports. Birmingham and Coventry manufacturing plants consolidate specification authority around domestic distributors with UKCA marking expertise.
Greater London Commercial Retrofit Sector
Part L compliance enforcement accelerates HVAC protector replacement cycles across office and retail stock. The Greater London Authority's net zero targets compress payback periods for building efficiency investments. Slough data center operators negotiate direct supply agreements with electronic sensor specialists, bypassing traditional electrical wholesale channels.
Scotland Renewable Energy Clusters
Offshore wind turbine nacelle manufacturers in Aberdeen and Glasgow generate underpenetrated demand for ruggedized thermal protection. Scottish Government offshore wind leasing rounds attract supply chain investment to the northeast coast. Port of Nigg and Port of Dundee fabrication yards require generator and converter system protection for turbine assembly.
Northern England Industrial Belt
Yorkshire manufacturing plants maintain legacy bi-metallic protector installed bases across continuous-process motor applications. Government-backed retrofit financing for commercial building decarbonization accelerates replacement cycles in aging HVAC infrastructure. Sheffield and Leeds industrial suppliers capture maintenance procurement through consolidated electrical component relationships.
Southeast England EV Charging Infrastructure
Rapid charger deployers across Kent and Surrey require high-reset-precision protectors for power electronics under variable load cycling. Office for Zero Emission Vehicles grant schemes expand charging point deployment along major road corridors. Milton Keynes and Brighton charging hub construction concentrates procurement among infrastructure deployers with direct manufacturer relationships.
United Kingdom Thermal Protector Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates and specialized thermal protection manufacturers serving distinct procurement channels. The vendor base separates into three tiers: global industrial automation suppliers with integrated thermal management portfolios, mid-scale sensor specialists capturing direct data center contracts, and regional fabricators supplying high-volume appliance contracts. Competitive dynamics center on UKCA certification capability and application engineering support rather than price alone. M&A activity targets sensor technology capabilities, while capacity expansion concentrates on electronic protector variants for infrastructure deployers.
Among UK and European-based industrial automation suppliers, Sensata Technologies Holdings PLC, ABB Ltd., and Schneider Electric occupy positions across the competitive spectrum. Sensata anchors relationships with domestic appliance manufacturers through bi-metallic protector portfolios. ABB exemplifies specification authority capture via direct OEM engineering team relationships in industrial motor protection. Schneider Electric represents building automation convergence, competing through integrated thermal management systems rather than discrete components. These three entities illustrate how competitive positioning diverges between component supply and system-level integration strategies.
| Leading Market Players |
|---|
| Sensata Technologies Holdings PLC |
| Portage Electric Products, Inc. |
| Thermtrol Corporation |
| Calco Electric Corp. |
| ABB Ltd. |
| Schneider Electric |
| Haier Smart Home Co., Ltd. |
| Changshu Tianyin Electromechanical Co., Ltd. |
| Seki Controls Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
UKCA marking pathways gate both supplier qualification and price differentiation simultaneously, compressing margin pools for uncertified imports while elevating premium tiers for domestic distributors with regulatory expertise. Bi-metallic strip production costs hinge on copper and silver commodity exposure, forcing volume-discount tiering that separates West Midlands appliance OEM contracts from fragmented maintenance procurement.
Pricing Analysis
Volume-discount tiering structures separate high-volume appliance contracts from low-volume replacement orders across the UK market. Three-tier pricing stratification across certified-premium, standard-UKCA, and economy-import levels reflects documentation burden and after-sales technical support bundling. Pricing pressure stems from commodity metal volatility in bi-metallic strip production, compressing margins on long-term appliance supply agreements. Data center operators exhibit lowest price sensitivity due to thermal runaway risk premiums, while small M&E contractors in Northern England retrofit projects drive economy-tier volume.
Supply Chain Analysis
Inbound logistics costs from East Asian manufacturing hubs through Felixstowe and Southampton ports expose UK distributors to container availability swings and customs processing delays. Protector assembly draws from China, Germany, and Japan for precision bi-metallic strip fabrication, microcontroller integration, and ceramic thermistor substrates. Single-source vulnerability concentrates in copper-steel alloy strip supply from German specialty metal producers. Distribution runs through authorized distributors with UKCA technical documentation capabilities, bypassing traditional electrical wholesalers in high-specification electronic sensor categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK thermal protector market sits in early-cycle expansion as Net Zero Strategy retrofit incentives accelerate replacement cycles in aging HVAC infrastructure ahead of regulatory enforcement curves.
For Market Incumbents: Secure UKCA marking pathway dominance by acquiring third-party conformity assessment body relationships, insulating against certification timeline compression that threatens product launch windows. Deepen captive supply of copper-steel alloy strip through backward integration into German or Japanese specialty metal sourcing, hedging commodity volatility that erodes appliance contract profitability. Electronic sensor substitution in industrial motor applications demands firmware development investment to defend specification authority against solid-state temperature monitoring alternatives. For New Entrants and Emerging Players: Differentiate on ruggedized thermal protection architectures for Scottish offshore wind nacelle manufacturers, where underpenetrated demand in Aberdeen and Glasgow fabrication yards lacks established supplier relationships. Target data center direct procurement channels in Slough and Manchester with BACnet-integrated sensor platforms, bypassing electrical wholesale intermediaries that incumbent distributors control. White space concentrates in predictive maintenance software bundling alongside hardware sales, capturing recurring revenue streams that component-only suppliers cannot match. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic sensor sub-segments as firmware development and wireless protocol integration demands expand R&D headcount. Long-term viability over the next decade hinges on sensor-to-software convergence capabilities rather than discrete component manufacturing scale. Acquisition target archetypes include mid-scale sensor specialists with existing data center direct relationships and UKCA certification infrastructure. Watch for BEIS ecodesign regulation expansion into additional motor efficiency classes as the inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Infrastructure Investment | Third-party conformity assessment body partnerships compress certification timelines for new protector variants entering the UK market. |
| Backward Integration into Specialty Metal Supply | Captive copper-steel alloy strip production insulates margin pools from commodity volatility in high-volume appliance contracts. |
| Sensor-to-Software Platform Convergence | BACnet and Modbus protocol integration captures recurring revenue from building automation systems beyond hardware-only sales. |
| Direct Procurement Channel Development | Bypassing electrical wholesalers with data center operators concentrates margin capture and enables custom firmware integration. |
| Scottish Renewable Energy Supply Chain Entry | Offshore wind turbine nacelle manufacturers in Aberdeen and Glasgow represent underpenetrated demand for ruggedized thermal protection. |
Research Methodology
Cross-validation between primary interviews with thermal protection engineering directors, HVAC contractor procurement leads, data center facilities managers, and UKCA certification consultants anchors the qualitative findings against secondary validation. Trade data from HM Revenue and Customs, BEIS ecodesign regulation filings, BSI standards documentation, and Office for Product Safety and Standards enforcement records provide demand-side triangulation. Bottom-up segmentation modeling across product architectures and top-down macroeconomic scenario testing ensure internal consistency.
Sensitivity analysis around copper and silver price trajectories, UKCA marking transition timelines, and Net Zero Strategy retrofit incentive funding levels stress-tests projection robustness across the analysis window. Segmentation dimensions include reset capability tier, application environment, end-user industry technical sophistication, and distribution channel structure. CAGRs derive from installed base replacement cycle modeling and new-build specification rate analysis, incorporating Part L compliance enforcement intensity and data center construction pipelines as industry-specific demand drivers.
Forecasts assume regulatory continuity in UKCA marking requirements and BEIS ecodesign enforcement; material policy shifts toward EU harmonization or divergence would require re-modeling. Commodity price volatility, third-party conformity assessment body capacity constraints, and electronic sensor substitution acceleration represent specific risk factors that could revise demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Portable Fan Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Electrical Enclosures Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Electric Enclosure Market