
 Circuit Breaker and Fuses Market | 2026-2036
Circuit Breaker and Fuses Market Size, Share, and Industry Trends Forecast 2026-2036
Circuit Breaker and Fuses Market Outlook
The EU Green Deal is realigning procurement criteria across European power distribution networks. ABB Ltd leverages its digital breaker portfolio to capture utility upgrade cycles. Siemens AG anchors its position through in-house semiconductor production for electronic trip units. Schneider Electric SE differentiates via integrated energy management software bundled with protection hardware.
Circuit breakers and fuses are electromechanical safety devices engineered to interrupt fault currents within milliseconds, utilizing bimetallic strips, magnetic coils, or solid-state sensors to prevent thermal damage to conductors and equipment. Their primary purpose is protecting generation, transmission, and end-use infrastructure from overloads and short circuits. The circuit breaker segment dominates value pools due to higher unit prices and recurring maintenance revenue, while electronic technology leads growth as microprocessor-based protection replaces thermal-magnetic mechanisms. Industrial application demand outpaces residential expansion, driven by factory automation and data center power density requirements.
The US National Electrical Code, IEC 60947 standards, and EU F-Gas Regulation collectively shape product certification requirements and material constraints across major markets. China's GB standards and India's BIS certification create additional compliance layers for multinational suppliers. Stakeholders must monitor evolving arc-energy limits and digital interoperability mandates to preserve market access.
Market Dynamics
Smart grid digitization is compressing replacement cycles for electromechanical protection equipment as utilities prioritize real-time fault isolation and predictive maintenance capabilities over traditional thermal-magnetic systems.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for sulfur hexafluoride in medium-voltage switchgear are accelerating R&D into vacuum interrupter and solid-state alternatives across European distribution networks.
- Data center power density:Hyperscale facilities in Ashburn, Frankfurt, and Singapore are specifying electronic trip units with sub-cycle interruption to protect high-density server racks from cascading failures.
- India's PLI scheme:Domestic manufacturing incentives for electrical equipment are drawing component suppliers to Gujarat and Tamil Nadu, reducing import dependency for critical protection devices.
Market Restraints
- Silver price volatility:Contact material costs in low-voltage breakers fluctuate with precious metal markets, squeezing margin stability for standard-grade product lines.
- Semiconductor supply concentration:Microprocessor shortages from Taiwanese foundries have extended lead times for electronic trip units by 8-14 months, constraining smart breaker deployment.
- IEC 60947-2 certification friction:Multi-jurisdiction testing requirements delay product launches by 18-24 months, particularly for manufacturers seeking simultaneous EU and Gulf state approvals.
Strategic Opportunities
- Vietnam industrial electrification:Northern manufacturing zones around Hai Phong lack adequate medium-voltage protection infrastructure, creating first-mover advantage for integrated solution providers.
- Digital twin convergence:Integration of breaker telemetry with asset management software enables subscription-based condition monitoring revenue streams distinct from hardware sales.
- US Inflation Reduction Act:Domestic content bonuses for grid modernization projects favor local assembly of protection equipment, rewarding reshoring investments in Texas and Ohio.
Industry Challenges
- Embedded firmware talent scarcity:Shortage of engineers proficient in IEC 61850 communication protocols limits development velocity for interoperable smart protection systems.
- Legacy substation integration:Retrofitting digital breakers into 1970s-era air-insulated switchgear requires custom mechanical adapters, inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circuit Breaker and Fuses Market |
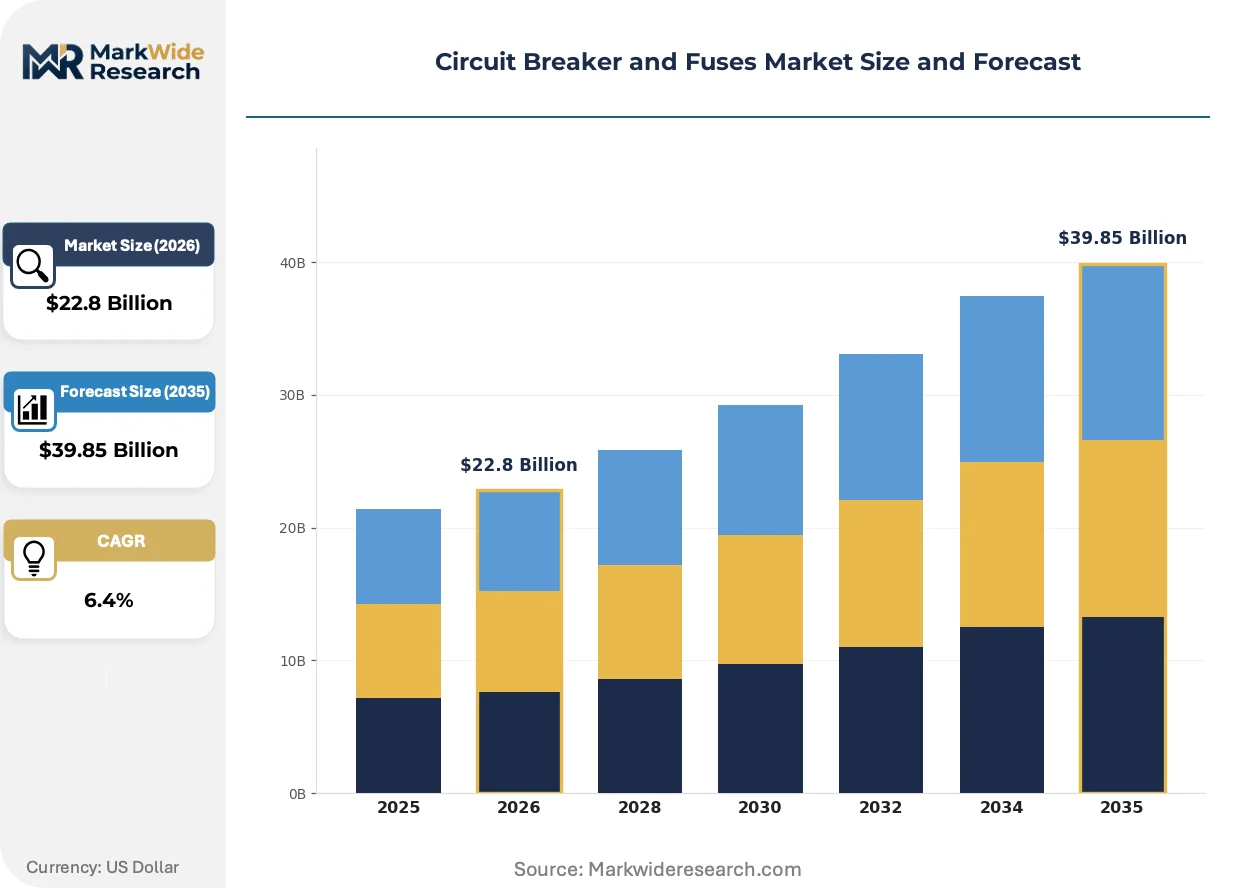
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Fuses, Surge Protectors, Isolators Application: Power Generation, Residential, Commercial, Industrial Technology: Hydraulic, Thermal, Electronic, Magnetic End User: Manufacturers, Contractors, Utilities, Distributors |
| Companies Covered | ABB Ltd, Schneider Electric SE, Siemens AG, Eaton Corporation plc, Mitsubishi Electric Corporation, General Electric Company, Rockwell Automation Inc, Larsen & Toubro Limited, LS Electric Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circuit Breaker and Fuses Market Strategic Shifts
Silicon carbide power semiconductors and edge-computing architectures are redefining protection device architecture, shifting competitive advantage from mechanical precision to software-defined fault algorithms and thermal management.
Solid-state circuit breakers utilizing silicon carbide MOSFETs are electrifying fault current interruption by eliminating mechanical arc quenching entirely. Data center operators and marine electrical system designers are piloting these devices for their microsecond-level response times. The technology is electrifying expectations for equipment lifespan, compressing the traditional 20-year replacement assumption toward 30-year asset horizons.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of molded case breaker housings and arc chute materials across European supply chains. Manufacturers must validate halogen-free thermoplastic alternatives without compromising flame-retardant ratings or tracking resistance. Medium-voltage original equipment manufacturers in Germany and Italy face the steepest reformulation timelines as their installed base renewal contracts specify full material traceability.
Utility procurement committees now mandate native IEC 61850 interoperability as a table-stakes qualification, displacing proprietary communication protocols that locked buyers into single-vendor ecosystems. This specification shift favors suppliers with in-house protocol stack development over those relying on licensed third-party implementations. The transformation is most visible in Scandinavian distribution utilities, where multi-vendor substation automation projects have become standard practice.
Circuit Breaker and Fuses Market Segmentation
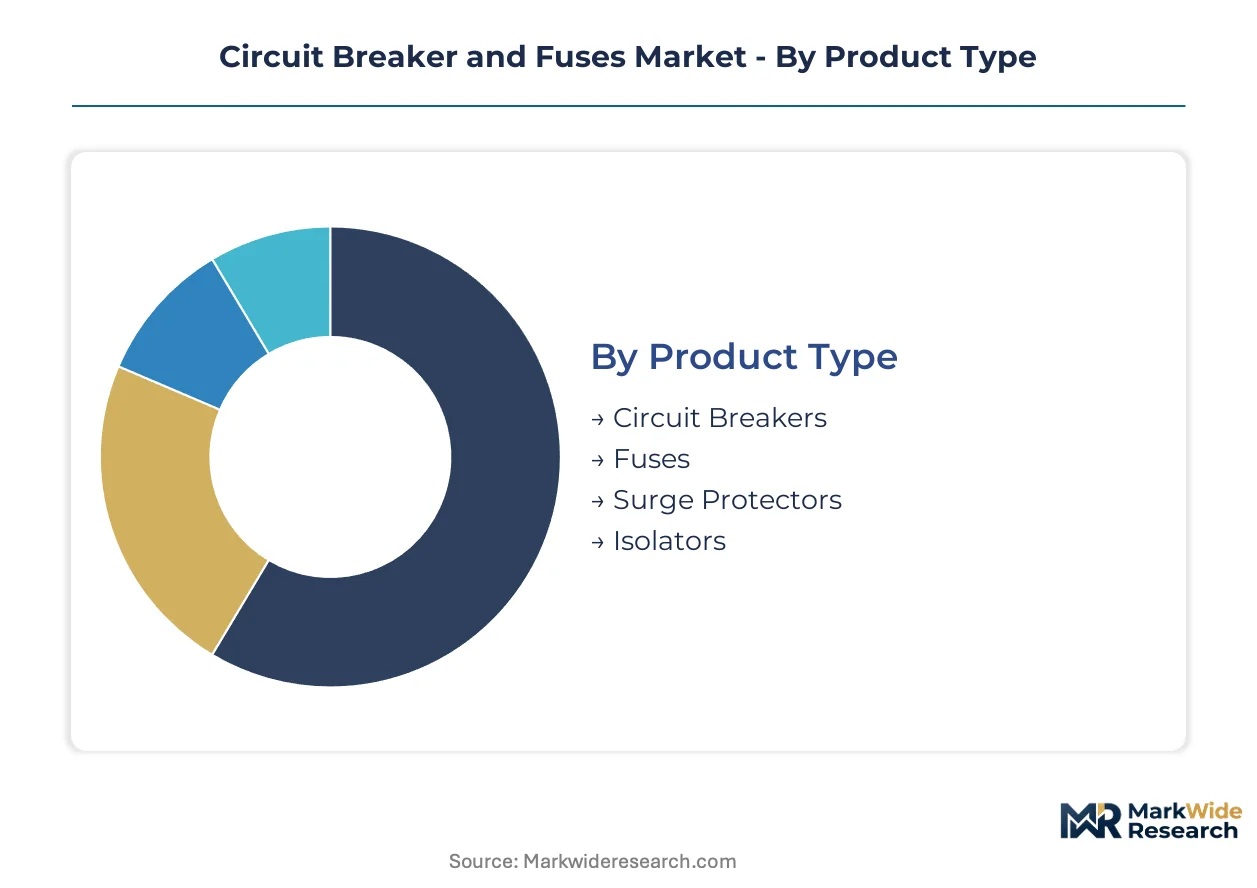
Segmentation in the Circuit Breaker and Fuses Market reveals divergent margin structures and replacement cycles across protection technologies. Product architecture choices determine whether suppliers capture recurring service revenue or one-time hardware sales.
Product Type:
Circuit breakers deploy as standalone panel-mounted devices requiring field service access, while fuses and surge protectors embed more deeply into OEM equipment with limited user interaction.
- Circuit Breakers:Electromechanical and solid-state devices with resettable interruption capability, utilizing thermal-magnetic or electronic trip mechanisms. Demand clusters in Germany's industrial automation corridors where IEC 60947-2 certified breakers protect variable frequency drives and motor control centers. Factory automation retrofits in Stuttgart and Munich are specifying electronic trip units with Modbus connectivity.
- Fuses:Single-use overcurrent protection elements employing silver or copper fuse elements within ceramic or fiberglass bodies. Procurement concentrates in India's solar inverter manufacturing hubs around Pune and Bengaluru, driven by BIS certification requirements for photovoltaic string protection. The PLI scheme is accelerating domestic fuse production for utility-scale installations.
- Surge Protectors:Voltage clamping devices safeguarding sensitive electronics from transient overvoltages.
- Isolators:Mechanical disconnect switches providing visible circuit separation for maintenance lockout procedures.
Volume placements concentrate in Circuit Breakers; the faster expansion belongs to Surge Protectors.
Application:
Cost tier differentiation separates mission-critical industrial specifications from price-sensitive residential installations, with commercial applications occupying the mid-tier specification band.
- Industrial:Heavy-duty protection for manufacturing equipment, data centers, and process industries requiring coordinated discrimination and arc-flash containment. Demand is accelerating in Singapore's Tuas data center cluster where hyperscale operators specify sub-cycle electronic trip coordination for 50MW+ facilities.
- Power Generation:Generator and transformer protection for conventional and renewable generation assets. Procurement is intensifying in China's eastern manufacturing corridor where industrial electrification projects require medium-voltage vacuum interrupters for substation integration.
- Residential:Standard-grade thermal-magnetic breakers for dwelling unit distribution panels.
- Commercial:Mid-specification devices for office buildings, retail, and institutional facilities.
Industrial captures the dominant revenue share; Power Generation is climbing the fastest on renewable buildouts.
Technology:
Maturity curves separate century-old thermal mechanisms from emerging solid-state architectures, with customer type determining acceptable technology risk profiles.
- Electronic:Microprocessor-based protection with programmable trip curves, communication interfaces, and predictive diagnostics. Adoption is accelerating in Scandinavian distribution utilities where IEC 61850 interoperability mandates favor digital-native suppliers. Stockholm and Oslo grid operators now require native protocol stacks over licensed implementations.
- Thermal:Bimetallic strip mechanisms providing time-delayed overcurrent response through resistive heating. Demand persists in France's residential renovation market where ANSM electrical safety inspections favor proven mechanical reliability over digital complexity.
- Magnetic:Instantaneous trip solenoids responding to short-circuit currents.
- Hydraulic:Time-delay mechanisms utilizing fluid dashpots for motor starting applications.
Thermal mechanisms retain the largest installed base; Electronic is gaining share fastest on smart grid mandates.
End User:
Supply concentration varies by procurement sophistication, with utilities and manufacturers driving specification complexity while contractors and distributors compete on availability and logistics.
- Utilities:Grid operators and distribution companies specifying medium-voltage protection with lifecycle cost optimization and predictive maintenance integration. Procurement is accelerating across Asia-Pacific smart grid programs where real-time fault isolation capabilities displace electromechanical relay systems.
- Contractors:Electrical installation firms selecting standard-grade devices based on availability and local code compliance. Activity concentrates in Vietnam's northern manufacturing zones around Hai Phong where industrial electrification projects outpace adequate protection infrastructure.
- Manufacturers:OEMs embedding protection into switchgear, appliances, and industrial equipment.
- Distributors:Channel intermediaries stocking breadth for contractor and MRO demand.
Contractors move the highest unit volumes; Utilities are expanding most quickly on infrastructure modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of circuit breakers and fuses concentrates in China's eastern manufacturing corridor, while consumption spreads across industrial electrification projects in Asia-Pacific, data center clusters in Northern Europe, and utility modernization programs in North America.
China
Industrial electrification drives procurement of medium-voltage vacuum interrupters across Jiangsu and Zhejiang provinces. GB standards compliance requirements shape product specifications for domestic grid operators. Shanghai and Suzhou host manufacturing clusters where local suppliers serve both domestic utilities and export markets.
Germany
Factory automation retrofits in Stuttgart and Munich specify electronic trip units with Modbus connectivity for motor control centers. EU F-Gas Regulation accelerates R&D into SF6-free alternatives across Bavarian and North Rhine-Westphalian distribution networks. Siemens AG anchors semiconductor production for electronic trip units in Erlangen.
United States
Data center power density requirements in Ashburn and Dallas-Fort Worth drive demand for sub-cycle electronic trip coordination. US Inflation Reduction Act domestic content bonuses favor local assembly in Texas and Ohio. OSHA arc-flash safety mandates shape industrial procurement specifications.
India
Domestic manufacturing incentives under the PLI scheme draw component suppliers to Gujarat and Tamil Nadu. BIS certification requirements concentrate fuse procurement around Pune and Bengaluru solar inverter manufacturing hubs. CEA grid code revisions accelerate smart protection adoption across state distribution companies.
Sweden
Multi-vendor substation automation projects in Stockholm and Gothenburg require native IEC 61850 interoperability. Scandinavian utilities displace proprietary communication protocols through open-stack procurement mandates. Stockholm grid operators specify digital-native suppliers over licensed protocol implementations.
Circuit Breaker and Fuses Market Competitive Environment
The competitive structure tilts toward diversified electrical conglomerates with captive semiconductor and software capabilities. Three tiers separate premium integrated solution providers from mid-market hardware specialists and regional component fabricators. Strategic moves center on backward integration into semiconductor production and forward integration into energy management software subscriptions.
Among diversified European electrical conglomerates, ABB Ltd, Schneider Electric SE, and Siemens AG exemplify the integrated archetype combining protection hardware with digital platforms. ABB Ltd leverages its digital breaker portfolio. Schneider Electric SE differentiates through bundled software. Siemens AG anchors positions through in-house semiconductor production. These three occupy positions where mechanical precision converges with software-defined protection algorithms.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Siemens AG |
| Eaton Corporation plc |
| Mitsubishi Electric Corporation |
| General Electric Company |
| Rockwell Automation Inc |
| Larsen & Toubro Limited |
| LS Electric Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Backward integration into semiconductor production anchors both supply security and pricing power for electronic trip unit manufacturers, while outsourced contact material sourcing exposes standard-grade breaker suppliers to silver price volatility across Asian manufacturing corridors.
Pricing Analysis
Margin tightening in standard-grade thermal-magnetic breakers reflects silver price volatility and Taiwanese foundry bottlenecks. Three-tier pricing structure across premium electronic trip units, mid-specification industrial breakers, and economy residential panels separates IEC 61850-certified smart protection from basic code-compliant hardware. Pricing pressure intensifies in the economy tier as Indian PLI scheme domestic production expands. Contractor channels exhibit highest price sensitivity; data center operators demonstrate lowest sensitivity due to cascading failure risk costs.
Supply Chain Analysis
US Inflation Reduction Act domestic content bonuses and India's PLI scheme are reshaping sourcing patterns toward Texas, Ohio, Gujarat, and Tamil Nadu assembly. Raw material dependencies center on Taiwanese semiconductor foundries, Chilean copper cathodes, and Mexican silver concentrates. Single-source vulnerability in microprocessor supply creates 8-14 month lead time exposure for electronic trip unit production. Distribution runs through authorized electrical distributors serving contractor and industrial MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state circuit breakers utilizing silicon carbide MOSFETs are displacing thermal-magnetic mechanisms, compressing replacement cycles and redefining competitive advantage around software-defined protection algorithms.
For Market Incumbents: Hedge semiconductor supply exposure through captive production or long-term foundry offtake agreements with Taiwanese suppliers. Accelerate IEC 61850 protocol stack development in-house to escape licensed third-party dependency. Prioritize vacuum interrupter R&D to meet EU F-Gas Regulation phase-down timelines. For New Entrants and Emerging Players: Vietnam's northern manufacturing zones around Hai Phong present contractor-channel white space where medium-voltage protection infrastructure lags industrial electrification. Target solar inverter fuse supply to Pune and Bengaluru under India's PLI scheme. Enter through digital twin subscription bundling rather than hardware-only positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electrical conglomerates seeking semiconductor and software capabilities. Five-to-ten year viability favors suppliers with in-house silicon carbide competency and native IEC 61850 stacks. Monitor Taiwanese foundry utilization rates as inflection indicator for electronic trip unit supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Production | In-house silicon carbide MOSFET fabrication eliminates Taiwanese foundry dependency for ABB and Siemens. |
| Native IEC 61850 Protocol Stack Development | Scandinavian utilities mandate open-stack procurement, displacing licensed third-party implementations. |
| Vacuum Interrupter R&D Acceleration | EU F-Gas Regulation phase-down forces SF6-free alternatives across German and Italian distribution networks. |
| Digital Twin Platform Integration | Breaker telemetry subscription revenue creates recurring income distinct from hardware sales for Schneider. |
| PLI Scheme Manufacturing Localization | Domestic fuse and breaker assembly in Gujarat reduces import dependency for Indian solar installations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, OEM procurement teams, electrical contractor principals, and aftermarket service heads. NEMA and IEC publications, SEC 10-K disclosures from listed electrical conglomerates, and EU F-Gas Regulation implementation reports provided demand-side validation. Bottom-up unit shipment estimates triangulated against top-down utility capex and industrial automation spending aggregates.
Granularity-level modeling disaggregated volume and value across product type, application, technology, and end user dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, regulatory mandate timelines, and technology substitution curves. Semiconductor supply elasticity and silver price volatility served as scenario-weighting inputs for electronic versus thermal-magnetic technology splits.
Revisions become necessary when Taiwanese foundry utilization shifts, EU F-Gas phase-down accelerates, or India's PLI scheme expands beyond current component coverage. Forecasts reflect documented assumptions regarding smart grid procurement cycles and data center power density trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Global Medium Voltage Surge Arresters Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Modular Contactor Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Electric Motors for Conveyor System Market