
 Magnetic Shielding Device Market | 2026-2036
Magnetic Shielding Device Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Shielding Device Market Insights
Advancements in nanocrystalline alloy fabrication is reconfiguring performance benchmarks for high-frequency magnetic shielding across precision instrumentation. Vacuumschmelze leverages proprietary rapid-solidification casting to dominate supply of ultra-low coercivity ribbon for medical imaging cores. Hitachi Metals anchors Asia-Pacific demand through integrated control of amorphous alloy melt-spinning capacity and downstream lamination services. MuShield specializes in custom-fabricated Mu-metal enclosures for scientific instruments, competing on engineering turnaround rather than commodity volume.
Magnetic shielding devices are engineered enclosures or coatings that attenuate electromagnetic interference through high-permeability alloys such as Mu-metal or nanocrystalline structures, typically achieving attenuation ratios exceeding 80 dB at frequencies below 100 kHz to protect sensitive signal pathways. These systems serve primarily to isolate precision measurement equipment, medical diagnostic scanners, and aerospace navigation sensors from ambient magnetic fields that would otherwise corrupt data fidelity or destabilize control loops. Passive shielding occupies the largest installed base due to its reliability and absence of power requirements, though hybrid configurations combining passive alloys with active cancellation coils are capturing margin pools in next-generation MRI installations. Nanocrystalline alloys represent the fastest-expanding technology segment as manufacturers substitute them for conventional Mu-metal in applications demanding superior thermal stability and reduced weight.
The FDA's electromagnetic compatibility requirements for diagnostic imaging equipment and the EU Medical Device Regulation's material biocompatibility standards directly shape product certification pathways and qualification timelines for shielding suppliers entering healthcare supply chains. Japan's METI enforces JIS standards for electromagnetic disturbance limits in automotive and industrial electronics, creating compliance barriers for non-domestic alloy processors. Germany's KBA applies analogous EMC thresholds to aerospace sensor assemblies, reinforcing regional specialization among European shielding fabricators. Stakeholders must monitor divergence between FDA and EMA electromagnetic safety protocols as hybrid shielding architectures proliferate across multi-jurisdictional medical device platforms.
Market Dynamics
Nanocrystalline alloy fabrication is reconfiguring procurement priorities across precision instrumentation, compressing qualification timelines for suppliers while elevating thermal stability specifications in medical imaging and semiconductor equipment.
Growth Catalysts
- EU F-Gas Regulation:Tightened material traceability mandates for shielding components bound for healthcare applications are accelerating substitution toward nanocrystalline alloys with lower embodied carbon.
- Electron-beam lithography:South Korean foundries in Pyeongtaek are expanding nanocrystalline enclosure procurement to isolate next-generation EUV toolsets from ambient field interference.
- Hybrid shielding architectures:German and Japanese medical imaging OEMs are integrating passive alloys with active cancellation coils to meet stricter electromagnetic compatibility thresholds in MRI suite installations.
Market Restraints
- Nickel and cobalt price volatility:Raw material cost swings in high-permeability alloy feedstocks compress margin predictability for lamination fabricators serving scientific instrument markets.
- Amorphous alloy melt-spinning concentration:Asia-Pacific control over rapid-solidification casting capacity creates supply vulnerability for European shielding assemblers dependent on imported ribbon feedstock.
- Mu-metal weight penalty:Thermal stability limitations in conventional alloys restrict deployment in aerospace sensor platforms where gram-level mass budgets govern design acceptance.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fab construction creates first-mover advantage for shielding suppliers establishing local nanocrystalline lamination capability ahead of 2025-2026 equipment commissioning.
- Quantum computing cryogenic enclosures:Superconducting qubit architectures require multi-layer magnetic shielding with sub-millikelvin compatibility, opening premium specification tiers.
- Japan METI carbon-neutral industrial targets:Incentives for low-emission manufacturing processes favor shielding fabricators deploying hydrogen-reduced alloy processing over conventional carbon-intensive smelting.
Industry Challenges
- Rapid-solidification metallurgy expertise:Scarcity of process engineers capable of tuning melt-spinning parameters for sub-20-micron ribbon thickness constrains capacity expansion at emerging alloy producers.
- FDA-EMA electromagnetic safety divergence:Misaligned certification pathways for hybrid shielding architectures force dual-track qualification, extending time-to-revenue for medical device component suppliers.
- Legacy MRI retrofit compatibility:Field upgrade of active cancellation systems into installed passive-shielding suites demands site-specific engineering without standardized interface protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Shielding Device Market |
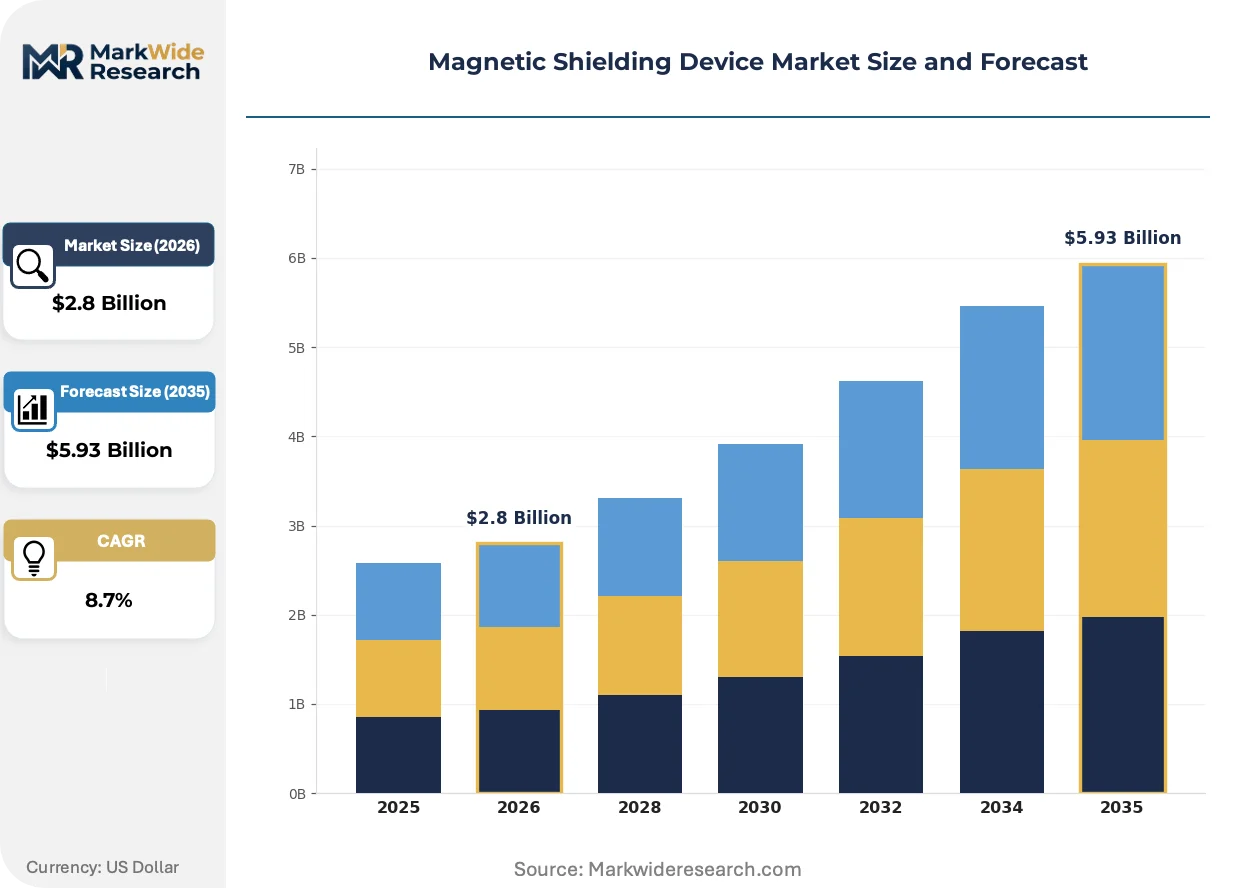
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Shielding, Passive Shielding, Hybrid Shielding, Superconducting Shielding Technology: Mu-metal, Metglas, Nanocrystalline Alloys, Ferrite, Amorphous Alloys Application: Medical Imaging, Aerospace Sensors, Consumer Electronics, Scientific Instruments End User: Research Laboratories, Defense Equipment Manufacturers, Electronic Device Producers, Automotive Suppliers |
| Companies Covered | Vacuumschmelze, Magnetic Shield Corporation, MuShield, Magnetic Metals Corporation, Eagle Magnetics, Ad-Vance Magnetics, Matsumoto Yushi-Seiyaku, Hitachi Metals, Tohoku Metal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Shielding Device Market Trends and Innovations
Active field cancellation systems are penetrating shielding architectures that historically relied solely on passive alloys, compressing the performance gap between commodity enclosures and precision-engineered assemblies.
Nanocrystalline FINEMET-type alloys is migrating from niche aerospace navigation sensors into mainstream medical imaging cores. Siemens Healthineers and Canon Medical Systems have accelerated qualification of these materials for 3.0 Tesla MRI gradient coil shielding. The technology is migrating from high-cost defense applications into volume healthcare procurement, forcing Mu-metal suppliers to defend position through price compression or specialty geometry fabrication.
Europe's F-Gas Regulation and the EU AI Act are tightening electromagnetic compatibility certification requirements for shielding components bound for healthcare and defense applications. Manufacturers must now document alloy provenance and field attenuation performance across operating temperature ranges. Medical imaging OEMs in Germany are responding by consolidating supplier bases to partners with integrated testing laboratories and ECHA-registered material streams.
Long-term service contracts bundling shielding replacement with predictive field monitoring are displacing transactional component sales in MRI suite procurement. Hospital procurement departments in Japan and South Korea are favoring vendors offering ten-year total-cost-of-ownership guarantees over upfront capital expenditure minimization. This behavioral shift concentrates margin capture with shielding fabricators capable of remote flux density telemetry and scheduled annealing service deployment.
Magnetic Shielding Device Market Segmentation
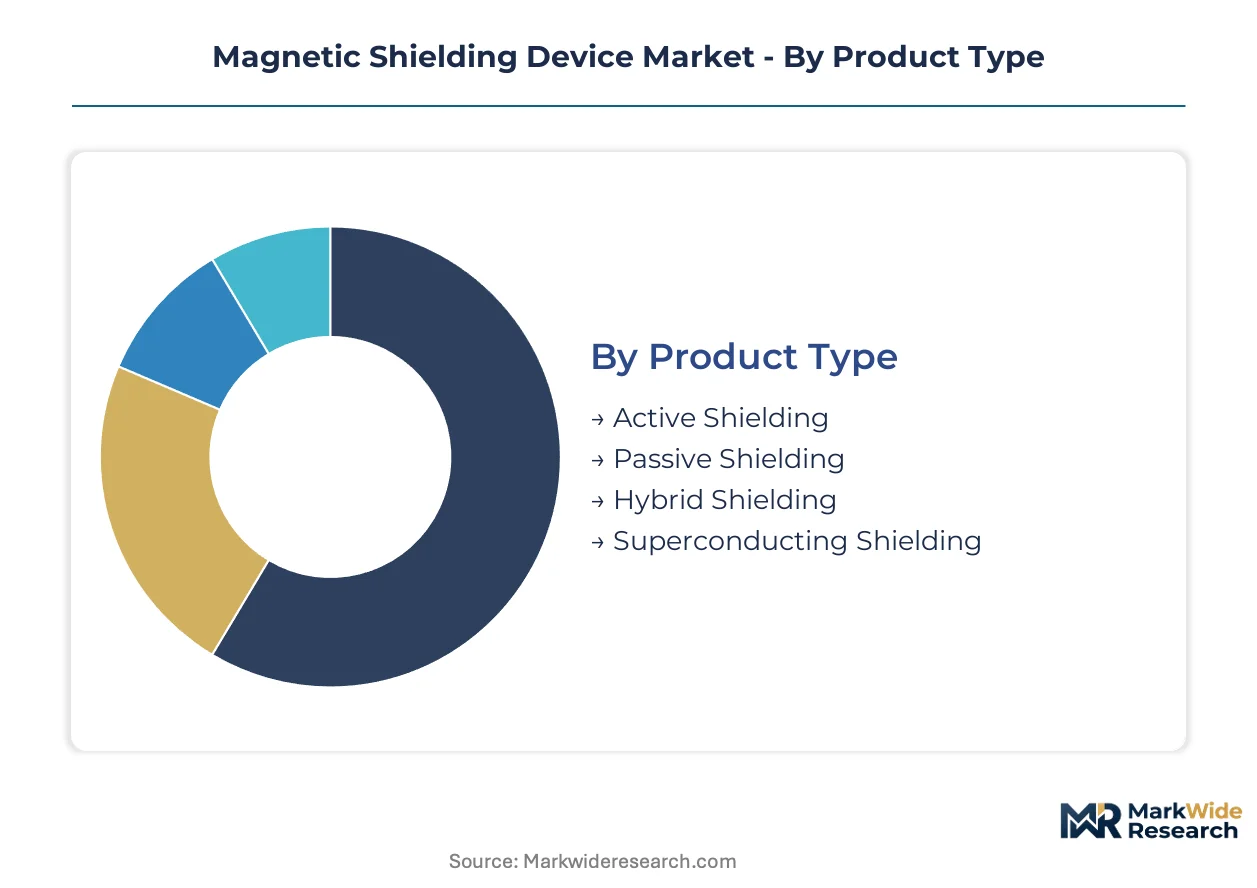
Segmentation in magnetic shielding reveals how procurement cycles and technical specifications diverge across end-use environments. Replacement intervals stretch from annual calibration in scientific instruments to decade-long installations in MRI infrastructure, reshaping vendor engagement models.
Product Type:
Cycle times vary dramatically — passive assemblies outlast active systems by factors of five to ten, while hybrid architectures demand synchronized refresh schedules across mechanical and electronic subsystems.
- Passive Shielding:Solid-state Mu-metal or nanocrystalline enclosures require no power input and tolerate decades of continuous operation. German medical imaging OEMs specify these for MRI suite foundations where access for maintenance is prohibitively expensive.
- Active Shielding:Electromagnetic cancellation coils with real-time flux sensors demand annual calibration cycles and five-year electronics replacement. South Korean foundries deploy these around electron-beam lithography tools where ambient field conditions fluctuate hourly.
- Hybrid Shielding:Layered passive-active configurations combine alloy baselines with dynamic compensation. Japanese OEMs are expanding procurement for next-generation MRI installations under METI electromagnetic compatibility mandates.
- Superconducting Shielding:Cryogenic lead or niobium enclosures operating below critical temperatures. Quantum computing laboratories in Japan and Germany represent primary demand concentration.
Passive shielding dominates installed base. Hybrid shielding is where expansion concentrates.
Technology:
Material selection tracks application temperature windows and mass constraints — aerospace platforms prioritize thermal stability, while medical imaging emphasizes field attenuation density per unit cost.
- Nanocrystalline Alloys:FINEMET-type structures fabricated through rapid-solidification casting achieve permeability exceeding Mu-metal with superior thermal stability. Siemens Healthineers and Canon Medical Systems have accelerated qualification for 3.0 Tesla MRI gradient coil applications.
- Mu-metal:Nickel-iron alloys with 75-80% nickel content remain the cost benchmark for sub-100 kHz shielding. Weight penalties restrict deployment in aerospace sensor platforms where gram-level mass budgets govern acceptance.
- Metglas:Amorphous metal ribbons produced by melt-spinning. Hitachi Metals anchors Asia-Pacific supply through integrated control of casting capacity and downstream lamination services.
- Ferrite:Ceramic iron oxide compounds for high-frequency interference suppression. Consumer electronics manufacturers specify these for cost-sensitive smartphone and tablet applications.
- Amorphous Alloys:Non-crystalline metallic glasses with soft magnetic properties. Vacuumschmelze leverages proprietary rapid-solidification casting to dominate supply of ultra-low coercivity ribbon.
Mu-metal commands volume share. Nanocrystalline alloys are climbing the fastest as manufacturers substitute for thermal-critical applications.
Application:
End-use concentration determines specification stringency — medical and aerospace segments impose multi-jurisdictional certification burdens absent in consumer electronics procurement.
- Medical Imaging:MRI and CT scanner shielding must satisfy FDA electromagnetic compatibility requirements and EU Medical Device Regulation material biocompatibility standards. German OEMs are consolidating supplier bases to partners with integrated testing laboratories.
- Aerospace Sensors:Navigation and attitude control systems require shielding with sub-ppm thermal expansion coefficients. Germany's KBA applies stringent EMC thresholds to sensor assemblies.
- Consumer Electronics:Hearing aids, smartphones, and wearables demand miniaturized shielding at commodity cost structures. Specifications prioritize manufacturability over ultimate attenuation performance.
- Scientific Instruments:Electron microscopes and mass spectrometers require site-specific shielding engineering. MuShield competes in this segment on engineering turnaround rather than commodity volume.
Medical imaging anchors revenue concentration. Aerospace sensors deliver premium margin tiers.
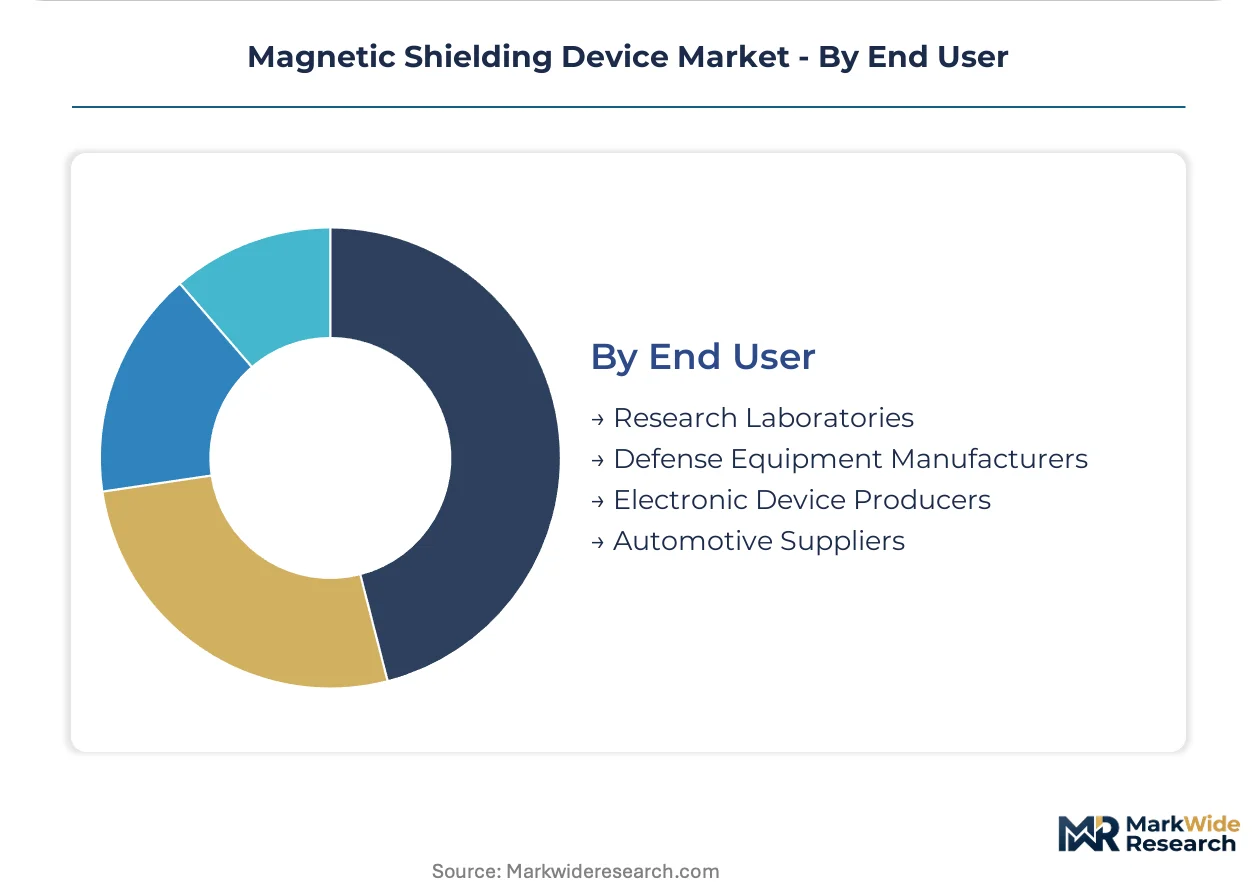
End User:
Procurement sophistication varies — defense and research laboratories specify attenuation performance with acceptance testing protocols, while automotive suppliers prioritize supply assurance and cost predictability.
- Research Laboratories:National physics institutes and university facilities demand custom-engineered enclosures with documented field mapping. Ten-year total-cost-of-ownership guarantees are displacing transactional component sales in Japanese and South Korean procurement.
- Defense Equipment Manufacturers:Military sensor platforms require shielding with provenance documentation and electromagnetic pulse hardening. EU AI Act and F-Gas Regulation tighten material traceability mandates for components bound for defense applications.
- Electronic Device Producers:High-volume manufacturers of smartphones, tablets, and wearables specify ferrite and thin-film shielding. Cost minimization dominates supplier selection criteria.
- Automotive Suppliers:ADAS sensor and electric powertrain component manufacturers. Japan's METI enforces JIS standards for electromagnetic disturbance limits in automotive electronics.
Research laboratories concentrate premium specification demand. Electronic device producers drive volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical imaging OEMs in Germany and Japan drive premium procurement, while South Korean semiconductor foundries anchor volume demand for nanocrystalline enclosures.
Germany
Siemens Healthineers and Canon Medical Systems accelerate qualification of FINEMET-type alloys for 3.0 Tesla MRI gradient coil shielding. The EU F-Gas Regulation and EU AI Act tighten material traceability mandates for healthcare-bound components. Bavarian medical device clusters around Munich consolidate supplier bases toward partners with integrated ECHA-registered testing laboratories.
Japan
Canon Medical Systems and domestic OEMs expand hybrid shielding procurement combining passive alloys with active cancellation coils. METI enforces JIS standards for electromagnetic disturbance limits across automotive and industrial electronics. Tokyo-Osaka medical imaging corridors favor vendors offering ten-year total-cost-of-ownership guarantees with remote flux density telemetry.
South Korea
Samsung and SK Hynix foundries in the Pyeongtaek semiconductor cluster scale nanocrystalline enclosure procurement for EUV lithography tool isolation. MFDS alignment with international electromagnetic compatibility standards shapes qualification pathways for imported shielding components. Seoul Capital Area procurement departments displace transactional sales with long-term service contracts bundling replacement and predictive field monitoring.
United States
FDA electromagnetic compatibility requirements for diagnostic imaging equipment compress supplier qualification timelines for MRI suite shielding. EPA material sourcing disclosures intersect with healthcare procurement sustainability mandates. Greater Boston and Pacific Northwest quantum computing laboratories drive demand for cryogenic superconducting enclosures with sub-millikelvin compatibility.
India
Domestic fab construction under the PLI scheme for semiconductors creates first-mover opportunity for shielding suppliers establishing local nanocrystalline lamination capability. BIS standards for electromagnetic compatibility certification govern import acceptance of high-permeability alloy assemblies. Karnataka and Telangana electronics manufacturing clusters anticipate 2025-2026 equipment commissioning timelines.
Magnetic Shielding Device Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. Vacuumschmelze and Hitachi Metals anchor upstream rapid-solidification casting capacity, while MuShield and Magnetic Shield Corporation occupy downstream custom-fabrication niches. The structure stratifies between scale-driven ribbon producers, integrated lamination service providers, and engineering-centric enclosure specialists. Competitive moves concentrate on backward integration into melt-spinning capacity and geographic expansion through local lamination joint ventures.
Among German-based specialists, Vacuumschmelze GmbH exemplifies the upstream archetype controlling proprietary rapid-solidification metallurgy. Hitachi Metals Ltd. anchors Asia-Pacific supply chain positioning through integrated casting and downstream services. MuShield Company, LLC occupies the custom-engineering tier competing on turnaround velocity rather than commodity volume. These three represent distinct competitive positions: captive technology control, integrated regional scale, and specialist fabrication agility.
| Leading Market Players |
|---|
| Vacuumschmelze |
| Magnetic Shield Corporation |
| MuShield |
| Magnetic Metals Corporation |
| Eagle Magnetics |
| Ad-Vance Magnetics |
| Matsumoto Yushi-Seiyaku |
| Hitachi Metals |
| Tohoku Metal Industries |
| Others |
Pricing and Supply Chain Analysis
Asia-Pacific control over rapid-solidification casting capacity for nanocrystalline ribbon feedstock concentrates margin capture with German and Japanese shielding assemblers who command premium pricing through integrated lamination services and certification documentation.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and cobalt benchmarks dominate procurement between ribbon producers and lamination fabricators. Three-tier pricing structure across medical-grade certified, industrial-standard, and consumer-economy tiers reflects divergence in electromagnetic compatibility documentation depth. Cost compression in industrial-standard tier is intensifying because South Korean foundries are consolidating purchase volumes around qualified suppliers. Electronic device producers exhibit highest price sensitivity due to ferrite substitution options; research laboratories show lowest sensitivity where attenuation performance governs acceptance.
Supply Chain Analysis
Export control regimes limiting dual-use magnetic alloy technology flows between Germany, Japan, and South Korea constrain non-domestic access to sub-20-micron rapid-solidification ribbon. Germany, Japan, and South Korea anchor primary melt-spinning capacity. Downstream lamination draws from nickel-iron alloy feedstock, copper winding wire, and cryogenic-compatible insulation substrates. Single-source vulnerability concentrates in rapid-solidification metallurgy expertise scarcity. Distribution runs through direct OEM supply agreements for medical imaging and semiconductor equipment tiers, with scientific instrument channels utilizing specialized engineering distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic shielding incumbents face substitution defense against active field cancellation systems penetrating architectures historically reliant on passive alloys, compressing the performance gap between commodity enclosures and precision-engineered assemblies.
For Market Incumbents: Build certification moats around FDA-EMA dual-track electromagnetic safety documentation to extend qualification timelines that deter entrants. Deepen backward integration into rapid-solidification casting capacity in Germany or Japan to secure ribbon feedstock against Asia-Pacific supply vulnerability. METI carbon-neutral manufacturing incentives favor hydrogen-reduced alloy processing investments that emerging competitors cannot replicate without capital scale.
For New Entrants and Emerging Players: Pursue India's PLI scheme for semiconductors as first-mover shielding supplier establishing local nanocrystalline lamination capability ahead of Karnataka and Telangana fab commissioning. Target quantum computing cryogenic enclosure segment where superconducting qubit architectures require multi-layer magnetic shielding with sub-millikelvin compatibility and premium specification tiers remain underpenetrated. Lead with ten-year total-cost-of-ownership service contracts bundling replacement and predictive field monitoring to displace transactional component sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed custom-fabrication specialists holding scientific instrument relationships but lacking upstream melt-spinning control. Long-term viability across the analysis window hinges on nanocrystalline alloy substitution velocity against Mu-metal legacy base. Monitor FDA-EMA electromagnetic safety protocol divergence as inflection indicator forcing dual-track qualification investments that favor consolidated players with integrated testing laboratories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rapid-Solidification Casting | Captive ribbon supply secures margin pools against nickel-cobalt price volatility and Asia-Pacific concentration risk. |
| Dual FDA-EMA Certification Investment | Integrated testing laboratories compress qualification timelines for hybrid shielding architectures in medical imaging. |
| Long-Term Service Contract Bundling | Ten-year total-cost-of-ownership guarantees with remote flux density telemetry displace transactional MRI suite sales in Japan and South Korea. |
| Hydrogen-Reduced Alloy Processing Deployment | METI carbon-neutral incentives favor low-emission manufacturing over conventional smelting for healthcare-bound components. |
| Local Lamination Joint Venture in India | PLI scheme fab construction creates first-mover advantage ahead of 2025-2026 equipment commissioning timelines. |
Research Methodology
Cross-validation between primary interviews with rapid-solidification metallurgy engineers, MRI suite procurement managers at German OEMs, semiconductor fab facilities planners in South Korea, and biomedical equipment certification specialists anchors the qualitative findings. Secondary validation draws from FDA electromagnetic compatibility guidance documents, ECHA-registered material stream databases, METI JIS standards publications, and SEC filings of publicly traded alloy processors. Bottom-up demand modeling across medical imaging, semiconductor lithography, and quantum computing laboratory installations triangulates against top-down market sizing from trade flow analysis of high-permeability alloy ribbon and laminated enclosure shipments.
Calibration against historical substitution rates from Mu-metal to nanocrystalline alloys in aerospace navigation sensors informs penetration assumptions across the projection horizon. Segmentation dimensions modeled include shielding architecture type, alloy technology, application vertical, and end-user procurement sophistication tier. CAGRs derive from installed base replacement cycles, new equipment procurement pipelines, and technology substitution elasticities. Industry-specific forecast inputs incorporate EU F-Gas Regulation material traceability compliance timelines and South Korean foundry EUV lithography tool commissioning schedules.
Macroeconomic conditions sit as an overlay; deviation in nickel-cobalt commodity price trajectories or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization between FDA and EMA electromagnetic safety protocols. Material shifts in rapid-solidification metallurgy process yields or export control regime expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Capacitor Bank Controllers Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
North America Circuit Breakers Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Waveguide Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Vacuum Interrupter Market