
 Europe High Voltage Switchgear Market | 2026-2036
Europe High Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe High Voltage Switchgear Market Insights
Aftermarket service revenue is narrowing toward predictive maintenance contracts as OEMs seek recurring income streams. Siemens AG leverages its digital twin platform to lock in long-term service agreements with transmission operators. Hitachi Energy Ltd anchors its European position through specialized high-voltage direct current interconnector projects. ABB Ltd competes by extending its lifecycle management portfolio across aging air insulated switchgear installations.
Europe high voltage switchgear comprises electrical apparatus designed to control, protect, and isolate power circuits above 36 kV, typically employing sulfur hexafluoride gas insulation, vacuum interrupters, or hybrid dielectric systems to withstand fault currents up to 63 kA. These assemblies serve as critical nodes in transmission grids, substations, and renewable energy collection points where reliability failures can cascade across national boundaries. Gas insulated switchgear commands premium pricing in dense urban environments where footprint constraints eliminate air insulated alternatives, while hybrid switchgear gains traction as a transitional technology for utilities managing SF6 phase-out timelines. The renewable energy end user segment represents the fastest-growing demand pool, driven by offshore wind farm collector platforms requiring compact, salt-resistant extra high voltage assemblies.
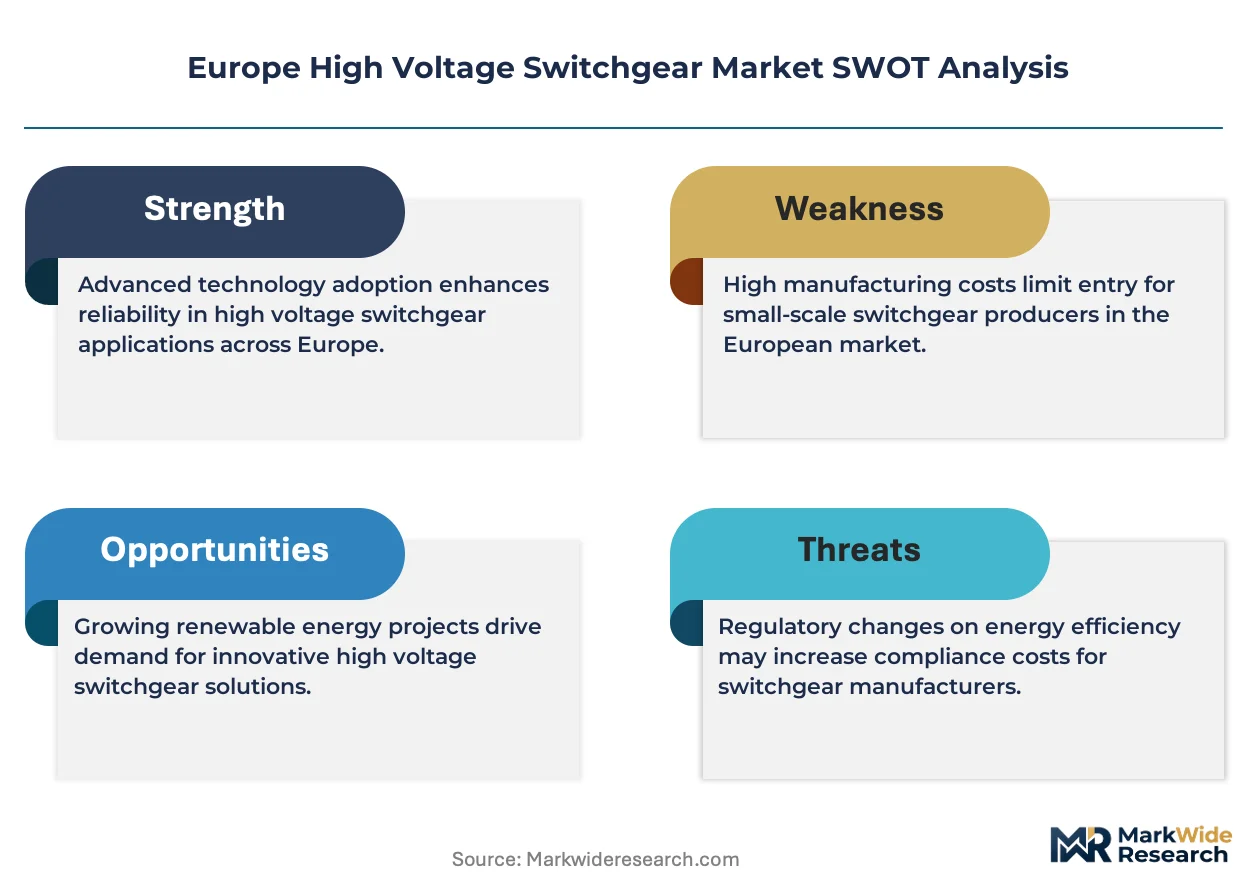
The EU F-Gas Regulation and ECHA restrictions on fluorinated greenhouse gases are forcing manufacturers to accelerate SF6-free insulation development or risk product disqualification across member states. CE marking under the MDR framework and harmonized IEC 62271 standards govern type testing and market access, creating compliance barriers for non-European suppliers. Stakeholders must monitor the interplay between national grid codes and EU-level decarbonization mandates as procurement specifications diverge across member states.
Market Dynamics
The EU F-Gas Regulation is compressing SF6 insulation timelines across European transmission networks, forcing utilities to accelerate capital deployment toward fluorinated-gas-free alternatives before phase-out deadlines crystallize procurement specifications.
Growth Catalysts
- Offshore wind interconnection mandates:Germany, Denmark, and the Netherlands require extra high voltage switchgear upgrades for North Sea collector platforms. National grid codes are being rewritten to accommodate 525 kV direct current links.
- EU Green Deal capital allocation:The European Commission's REPowerEU facility is channeling infrastructure funds toward cross-border transmission reinforcement. Member states must demonstrate SF6 reduction trajectories to unlock disbursements.
- Urban densification constraints:Gas insulated switchgear commands premium placement in London, Paris, and Milan substations where land scarcity eliminates air insulated footprints. Underground installation specifications favor compact dielectric systems.
Market Restraints
- Copper and aluminum price volatility:Conductive material costs constitute 35-40% of switchgear bill-of-materials. Smelter capacity constraints in Chile and Indonesia transmit directly to European OEM margins.
- SF6 gas bank depletion:Reclaimed sulfur hexafluoride stocks are concentrating among three European recyclers. Utilities face supply rationing for legacy equipment maintenance through 2027.
- Vacuum interrupter voltage ceiling:Current ceramic-to-metal sealing technology limits reliable interruption above 145 kV. Extra high voltage applications remain dependent on gas-based alternatives.
Strategic Opportunities
- Polish grid modernization backlog:PSE SA has deferred 400 kV substation investments since 2019. EU cohesion funds now cover 85% of eligible switchgear replacement costs.
- Solid-state insulation convergence:Epoxy resin casting combined with synthetic air dielectrics offers modular retrofit paths. Pilot installations are operational at TenneT's Eemshaven converter station.
- Digital twin service unbundling:Predictive maintenance contracts are separating from hardware procurement. Transmission system operators in the Nordic countries are issuing standalone analytics tenders.
Industry Challenges
- SF6-free certification timeline compression:IEC 62271-200 type testing for alternative insulation systems requires 18-24 months. Manufacturers face portfolio gaps during transition periods.
- High-voltage technician scarcity:Specialized craft skills for 420 kV assembly and commissioning are retiring across Germany and France. Vocational pipeline output lags replacement demand by 40%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe High Voltage Switchgear Market |
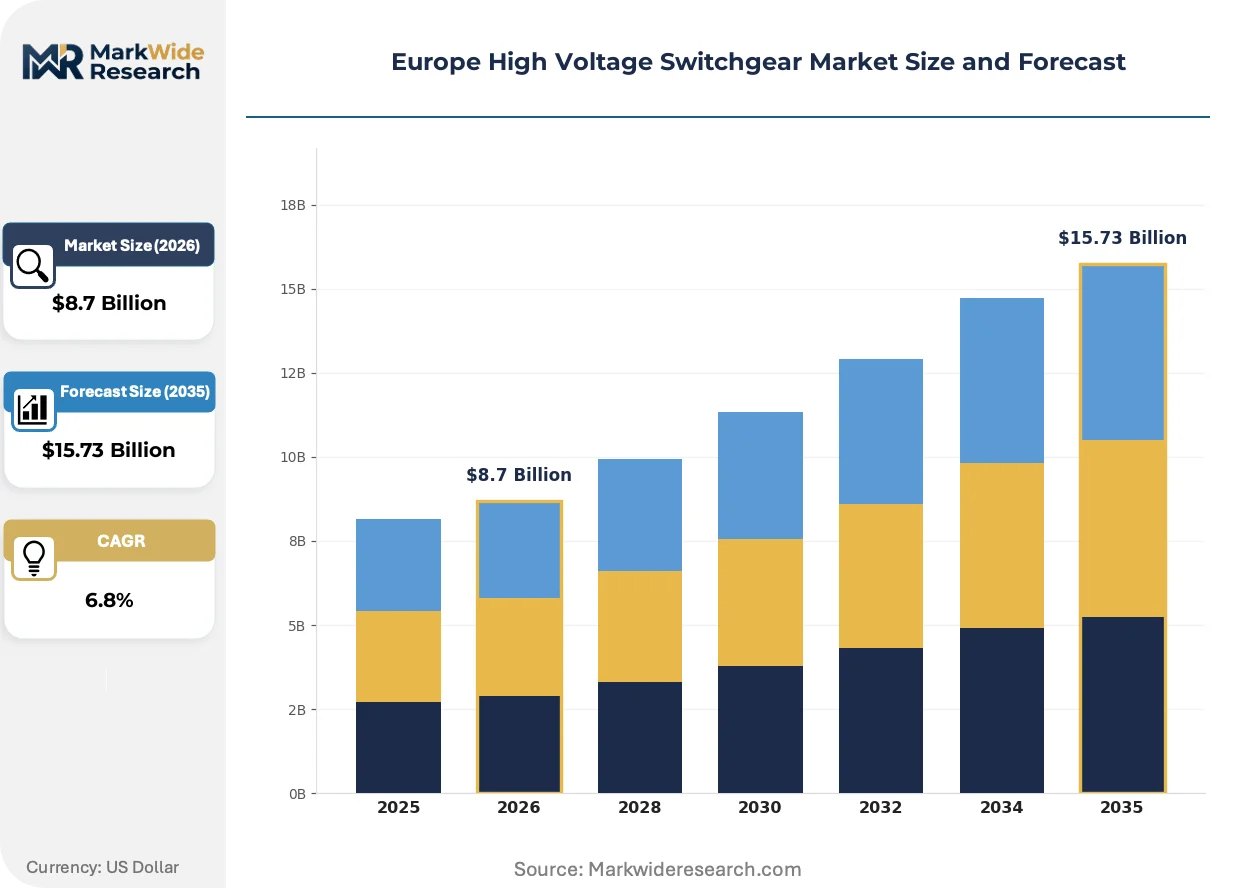
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Insulated Switchgear, Air Insulated Switchgear, Hybrid Switchgear, Circuit Breakers End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Mobile, Substation Voltage Level: Medium Voltage, High Voltage, Extra High Voltage, Ultra High Voltage |
| Companies Covered | General Electric Company, Toshiba International Corporation, ABB Ltd, Larson & Turbo Limited, KOHL Gmbh, Siemens AG, Mitsubishi Electric Corporation, SGC SwitchGear Company, Hitachi Energy Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe High Voltage Switchgear Market Trends and Innovations
European high voltage switchgear is undergoing dielectric system transformation as regulatory deadlines collide with renewable interconnection scale-up. Three concurrent developments are reconfiguring competitive positioning and procurement specifications.
Solid insulation technology is migrating from niche medium-voltage applications to transmission-class assemblies. Epoxy resin bushing systems with synthetic air buffering are gaining validation at 245 kV ratings. TenneT and National Grid are piloting these modules in offshore converter platforms where salt corrosion degrades conventional gas seals.
The EU F-Gas Regulation's 2026 review is tightening allowable SF6 leak rates from 0.5% to 0.1% annually. Equipment manufacturers must redesign sealing architectures or exit the extra high voltage segment. French and German transmission operators are already disqualifying bidders unable to demonstrate certified alternative insulation roadmaps.
Lifecycle service contracts are displacing transactional spare parts procurement across European utilities. Predictive analytics platforms now determine maintenance scheduling rather than calendar-based intervals. This reconfiguration is most visible in the Nordic countries where Statnett and Energinet have unbundled twenty-year service agreements from initial capital tenders.
Europe High Voltage Switchgear Market Segmentation
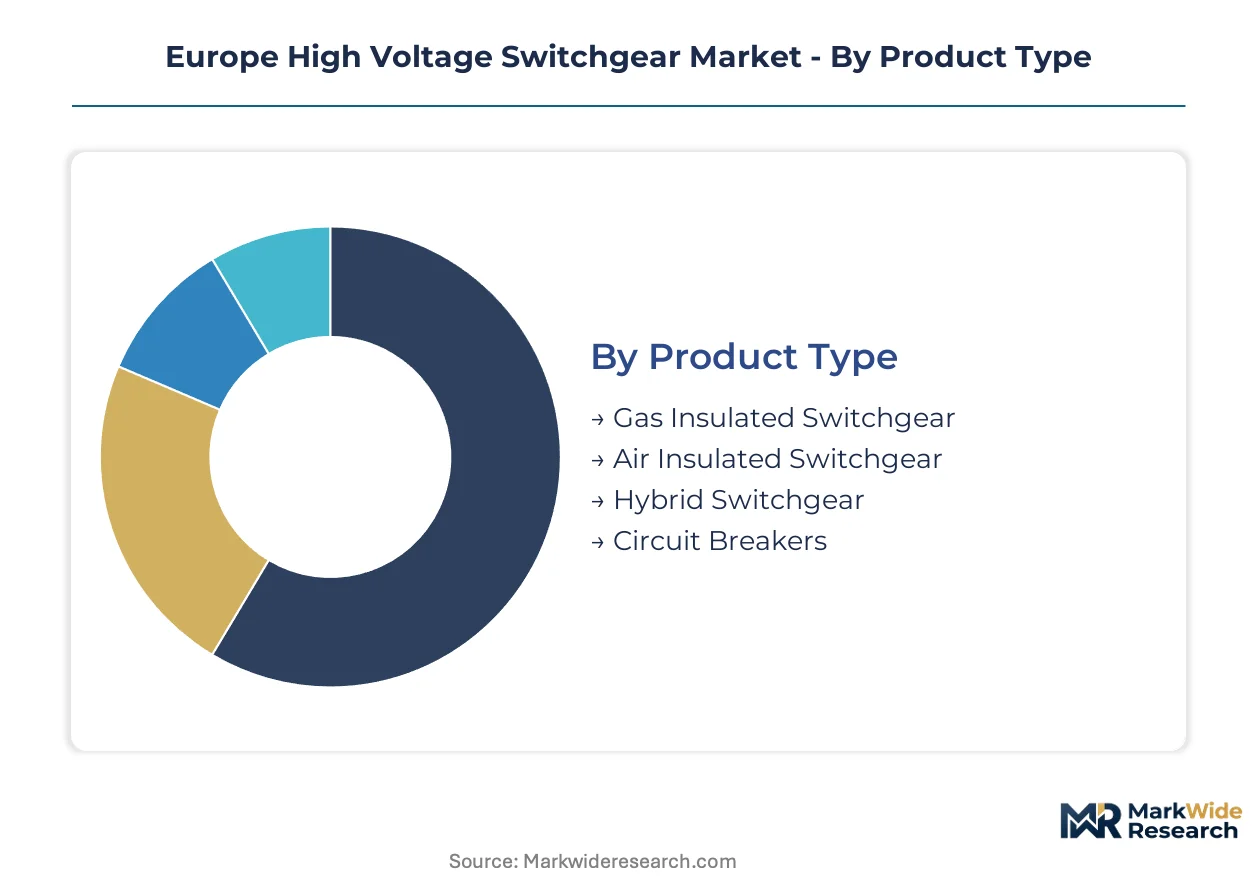
Segmentation in European high voltage switchgear reveals distinct procurement rhythms across product architectures and voltage classes. Utilities prioritize replacement cycles against F-Gas Regulation deadlines while renewable developers accelerate extra high voltage deployment for offshore collector platforms.
Product Type:
Replacement cycles vary sharply across dielectric systems, with gas insulated switchgear facing compressed obsolescence timelines against regulatory phase-outs while air insulated alternatives enjoy extended service windows.
- Gas Insulated Switchgear:Sulfur hexafluoride insulation enables compact 420 kV assemblies with footprint requirements one-tenth of air insulated equivalents. German and French transmission operators in Munich and Paris dense urban zones specify these for underground substations where land scarcity eliminates alternatives, though F-Gas Regulation compliance costs are accelerating procurement toward SF6-free alternatives.
- Air Insulated Switchgear:Open-air busbar configurations withstand 63 kA fault currents across 145-420 kV ratings with lower capital outlay and simpler maintenance protocols. Polish and Romanian grid modernization programs favor these for greenfield 400 kV substations in lower-density regions where spatial constraints are minimal.
- Hybrid Switchgear:Vacuum interrupters paired with reduced SF6 insulation volumes offer transitional compliance paths for utilities managing phase-out timelines.
- Circuit Breakers:Standalone interruption modules serve retrofit applications across aging European transmission infrastructure.
Air insulated switchgear anchors the volume base while hybrid switchgear gains share at the steepest rate as utilities navigate regulatory transition windows.
End User:
Capital deployment intensity separates utility procurement from industrial and commercial segments, with renewable energy developers operating on project-finance timelines distinct from rate-base regulated investments.
- Utilities:Transmission system operators in Germany, Denmark, and the Netherlands dominate order books with 525 kV direct current interconnector specifications. TenneT and Energinet procurement cycles span 18-24 months from tender to commissioning, with lifecycle service contracts now unbundled from hardware supply.
- Renewable Energy:Offshore wind farm collector platforms in the North Sea and Baltic Sea require salt-resistant extra high voltage assemblies with compact footprints. Ørsted and RWE project pipelines in the German Bight and Danish waters are specifying 245 kV gas insulated modules for converter stations.
- Industrial:Steel and chemical facilities in the Ruhr and Antwerp harbor zones procure 145 kV switchgear for captive substations serving electrochemical processes.
- Commercial:Data center operators in Frankfurt and Amsterdam secure dedicated 72.5 kV supply points for hyperscale facilities.
Utilities anchor the volume base while renewable energy climbs the fastest as offshore wind interconnection mandates accelerate procurement.
Installation Type:
Site constraints and mobility requirements create divergent specification pathways, with permanent substation installations commanding multi-decade service contracts versus mobile units serving contingency restoration.
- Substation:Fixed 400 kV transmission nodes across the European interconnected grid require seismic-rated foundations and integrated control systems. PSE SA in Poland is deploying these for delayed 400 kV corridor completions with EU cohesion fund support.
- Indoor:Climate-controlled enclosures protect dielectric systems in Nordic regions with extreme temperature differentials.
- Outdoor:Open-air configurations prevail in southern European markets with minimal freeze-risk and lower construction costs.
- Mobile:Trailer-mounted 145 kV units serve grid restoration following storm damage across France and Germany.
Substation installations anchor the volume base while indoor configurations expand most quickly as urban densification eliminates outdoor footprints.
Voltage Level:
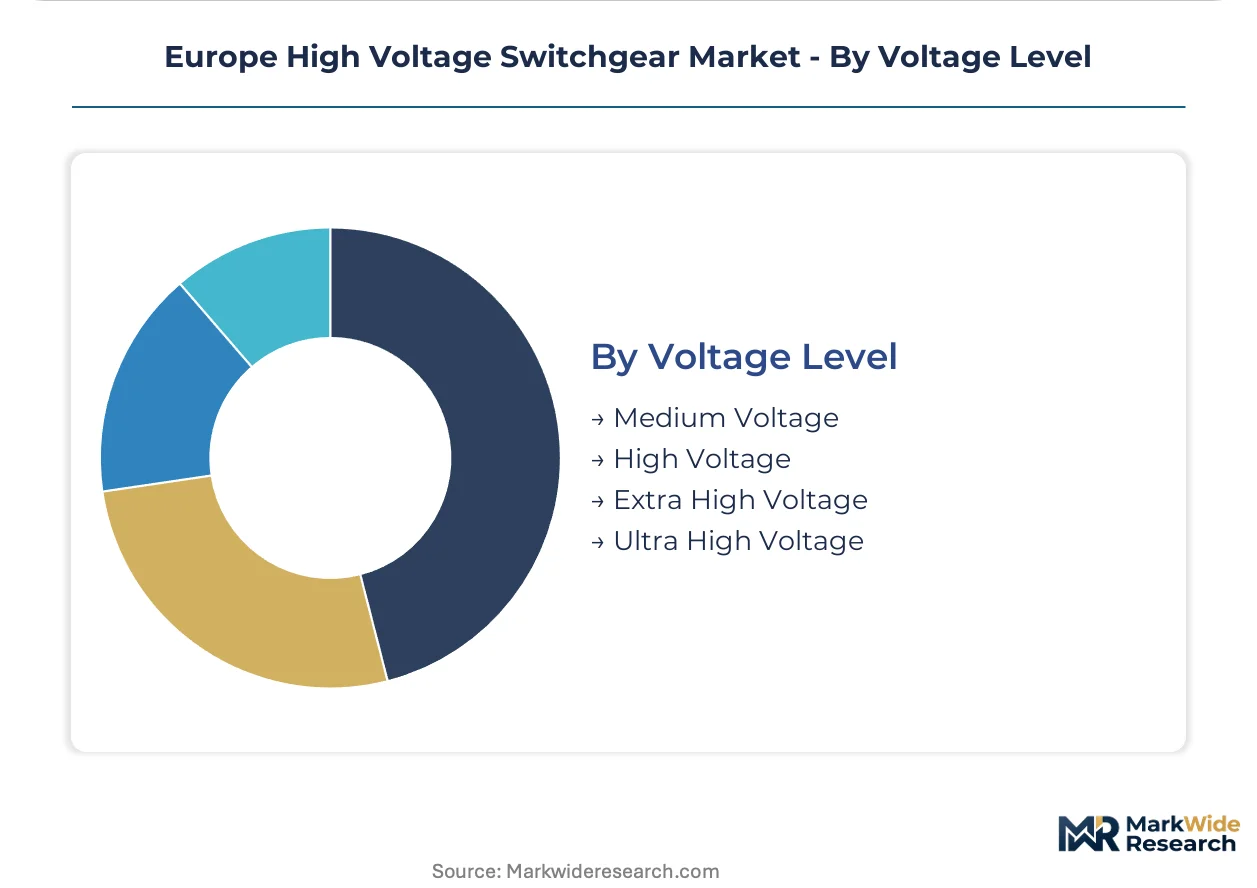
Technical complexity and regulatory scrutiny intensify across voltage tiers, with extra high voltage assemblies requiring specialized commissioning protocols and ultra high voltage remaining limited to cross-border interconnectors.
- Extra High Voltage:245-420 kV assemblies serve transmission backbones and offshore wind collection with interruption ratings to 63 kA. National Grid and TenneT are specifying these for North Sea converter platforms where 525 kV direct current links require robust alternating current interface switchgear.
- High Voltage:72.5-145 kV ratings bridge distribution and transmission functions across municipal utilities and industrial complexes.
- Medium Voltage:36-52 kV switchgear serves distribution substation upgrades with shorter procurement cycles.
- Ultra High Voltage:800 kV and above remains confined to limited continental interconnector projects.
High voltage anchors the volume base while extra high voltage gains share at the steepest rate as offshore wind and cross-border transmission investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities deploy extra high voltage switchgear for offshore wind collection at triple the per-capita intensity of Italian operators, who favor air insulated configurations for terrestrial grid reinforcement. This consumption-mix differential reflects North Sea wind mandates against Mediterranean solar priorities.
Germany
TenneT and 50Hertz Transmission mandate 525 kV direct current interconnectors for North Sea converter platforms. The EU F-Gas Regulation accelerates SF6-free procurement specifications for Bavarian and Lower Saxon substations. Hamburg harbor zones concentrate demand for compact gas insulated modules serving offshore logistics.
France
Réseau de Transport d'Électricité prioritizes 400 kV corridor upgrades for nuclear fleet integration and renewable balancing. ECHA restrictions on fluorinated gases compress certification timelines for domestic manufacturers. The Île-de-France region around Paris specifies underground gas insulated installations where urban density eliminates air insulated footprints.
United Kingdom
National Grid Electricity Transmission procures extra high voltage assemblies for North Sea offshore wind collector platforms. The UK Emissions Trading Scheme parallels EU F-Gas constraints on SF6 leakage rates. Scottish waters development concentrates demand for salt-resistant switchgear at Aberdeen and Grangemouth industrial clusters.
Poland
PSE SA deploys EU cohesion funds to clear 400 kV substation backlogs deferred since 2019. CE marking under harmonized IEC 62271 standards governs type testing for cross-border corridor equipment. The Warsaw-Łódź industrial belt drives procurement for delayed grid modernization programs.
Netherlands
Energinet and TenneT Nederland coordinate 525 kV direct current links for North Sea wind integration. The Dutch national implementation of EU F-Gas Regulation mandates leak rate reductions ahead of the 2026 review. Rotterdam port infrastructure concentrates demand for compact switchgear serving maritime electrification projects.
Europe High Voltage Switchgear Market Competitive Landscape
Capability concentration sits with specialized high-voltage engineering houses; scale advantage sits with diversified industrial conglomerates spanning multiple energy verticals. The European market structures around three tiers: integrated technology providers owning full dielectric system portfolios, component specialists dominating vacuum interrupter or epoxy resin niches, and regional fabricators serving national utility procurement preferences. Dominant competitive moves include portfolio diversification into SF6-free alternatives and strategic partnerships for offshore wind project bundling.
Among Germany-based industrial conglomerates, Siemens AG and ABB Ltd occupy positions exemplifying integrated technology provision across voltage classes and dielectric systems. Hitachi Energy Ltd represents the specialist tier focused on high-voltage direct current interconnector projects. SGC SwitchGear Company anchors regional fabrication capabilities serving Central European utility procurement cycles.
| Leading Market Players |
|---|
| General Electric Company |
| Toshiba International Corporation |
| ABB Ltd |
| Larson & Turbo Limited |
| KOHL Gmbh |
| Siemens AG |
| Mitsubishi Electric Corporation |
| SGC SwitchGear Company |
| Hitachi Energy Ltd |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum price volatility from Chilean and Indonesian smelter constraints determines both the widening spread between premium SF6-free switchgear and legacy gas-insulated tiers and the geographic reconfiguration of European OEM sourcing networks toward recycled metal streams and regional billet suppliers.
Pricing Analysis
Long-term offtake agreements between transmission system operators and integrated technology providers dominate procurement, with TenneT and National Grid locking in decade-spanning contracts that bundle hardware, installation, and predictive maintenance services. Price differentiation rests on SF6-free certification tier and volume scale, with utilities securing volume discounts for corridor-wide standardization programs. Cost compression in the mid-tier hybrid switchgear segment is intensifying because Polish and Romanian grid operators are consolidating purchases through EU cohesion fund tenders. Industrial captive substation buyers in the Ruhr and Antwerp harbor zones exhibit the highest price sensitivity, while offshore wind developers prioritize salt-resistant performance specifications over unit economics.
Supply Chain Analysis
Upstream feedstock concentration for conductive materials centers on Chile, Indonesia, and Peru for copper cathode and bauxite-alumina processing, with European switchgear OEMs drawing from LME-registered warehouses in Rotterdam and Hamburg to hedge against Atlantic shipping disruptions. Critical component dependencies include vacuum interrupter ceramic-to-metal seals sourced from Japanese and German specialists, epoxy resin casting compounds from Dutch and Belgian chemical producers, and SF6 gas stocks reclaimed by three European recyclers. Single-source vulnerability in high-purity sulfur hexafluoride reclamation exposes utilities to supply rationing through 2027. Distribution runs through authorized distributor networks serving national transmission operators, with direct OEM relationships reserved for extra high voltage interconnector projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among transmission system operators consolidating corridor-wide procurement, with TenneT and National Grid unbundling twenty-year service agreements from capital tenders to lock in lifecycle cost predictability.
For Market Incumbents: Build regulatory compliance moats through accelerated SF6-free certification pipelines ahead of EU F-Gas Regulation review deadlines. Siemens AG and ABB Ltd should deepen backward integration into epoxy resin casting and synthetic air dielectric production to secure supply continuity against chemical feedstock volatility. Capacity addition in Poland and Romania captures EU cohesion fund disbursements before backlog clearance saturates tender pipelines. For New Entrants and Emerging Players: Polish 400 kV substation modernization represents the most penetrable entry point, with PSE SA procurement cycles shortened by 85% co-funding coverage and deferred investment backlogs since 2019. Solid-state insulation retrofit modules for aging air insulated switchgear installations offer white-space access without competing for greenfield tenders dominated by integrated providers. Partner with TenneT and Energinet for pilot installations at converter stations to establish reference credentials. For Investors and Strategic Acquirers: The EU F-Gas Regulation 2026 review reshapes the acquisition landscape by disqualifying manufacturers without certified alternative insulation roadmaps, compressing viable target pools to technology providers with validated epoxy resin and synthetic air dielectric portfolios. Long-term viability favors specialists with demonstrated 245-420 kV solid insulation installations rather than legacy SF6-dependent assembly operations. Monitor IEC 62271-200 type testing completion timelines as the critical signal for portfolio gap closure and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Technology Certification | EU F-Gas Regulation compliance secures market access across member state procurement specifications. |
| Backward Integration into Epoxy Resin | Captive supply of solid insulation materials hedges against chemical feedstock price volatility. |
| Digital Twin Service Unbundling | Predictive maintenance contracts with Statnett and Energinet generate recurring revenue streams. |
| Polish Grid Modernization Partnership | PSE SA corridor completions with EU cohesion fund support capture deferred investment backlogs. |
| Offshore Wind Project Bundling | North Sea converter platform specifications with TenneT anchor extra high voltage market position. |
Research Methodology
Desk research of IEC 62271 type testing databases, EU F-Gas Regulation implementation reports, and transmission operator procurement disclosures preceded structured interviews with utility planning officers, high-voltage equipment procurement managers, EPC contractors specializing in substation builds, and aftermarket service directors at OEMs. Secondary validation drew from ENTSO-E grid development plans, national regulatory authority filings, and harmonized standards documentation. Bottom-up demand modeling across voltage classes and dielectric systems triangulated against top-down infrastructure investment forecasts from REPowerEU facility disbursement tracking.
Assumptions regarding EU Green Deal capital allocation continuity and F-Gas Regulation enforcement timelines were held fixed across the projection horizon, while copper and aluminum price trajectories and offshore wind interconnection completion rates were stress-tested through sensitivity scenarios. Segmentation modeling captured product architecture, voltage tier, end-use category, and installation type dimensions alongside regional regulatory cluster variations. CAGRs were derived from installation volume forecasts weighted by unit value differentials between gas insulated, air insulated, and hybrid dielectric systems, with input from grid modernization backlog clearance schedules and technician pipeline constraints.
Practitioners should monitor EU F-Gas Regulation review outcomes, Chilean smelter export quotas, and vacuum interrupter voltage ceiling breakthroughs for early signals of forecast revision triggers. Quarterly review of transmission operator tender issuance rates, IEC certification completion timelines, and reclaimed SF6 gas bank depletion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Voltage Transformer Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Air Circuit Breaker Market