
 Room Pressure Monitor Market | 2026-2036
Room Pressure Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Room Pressure Monitor Market Analytics
The room pressure monitor supply base is consolidating around two distinct tiers: premium digital platforms with BACnet integration and calibrated accuracy below 0.001 inches of water column, versus commodity analog units serving basic compliance needs. TSI Incorporated leverages its aerosol science heritage to anchor high-precision differential pressure measurement for critical healthcare environments. Setra Systems competes through capacitive sensing technology leadership that sustains long-term stability in variable humidity conditions. Johnson Controls extends its building automation footprint to occupy integrated pressure monitoring within unified facility management platforms.
A room pressure monitor is an instrument that measures and displays the differential pressure between an enclosed space and an adjacent area, typically achieving resolution of 0.0001 inches of water column to verify directional airflow in containment applications. These devices serve the primary commercial purpose of protecting patients, personnel, and sensitive processes from airborne contamination by ensuring negative or positive pressure integrity per engineering standards. Fixed monitors dominate hospital infrastructure budgets where permanent installation aligns with continuous compliance documentation, while wireless monitors represent the fastest-expanding category as facilities retrofit aging buildings without dedicated conduit runs. Differential pressure sensors command the largest technology share due to direct measurement reliability, though digital sensor adoption accelerates where IoT-enabled predictive maintenance reduces manual calibration labor.
The US Centers for Medicare and Medicaid Services enforce airborne infection isolation room standards through facility certification surveys, while the Joint Commission accredits hospitals based on documented pressure differential performance in protective environments. The American Society of Heating, Refrigerating and Air-Conditioning Engineers publishes design guidelines that manufacturers must reference for product specification legitimacy. Stakeholders should monitor evolving fusion of pressure monitoring with real-time location systems and access control, as integrated platforms redefine procurement criteria beyond standalone instrument sales.
Market Dynamics
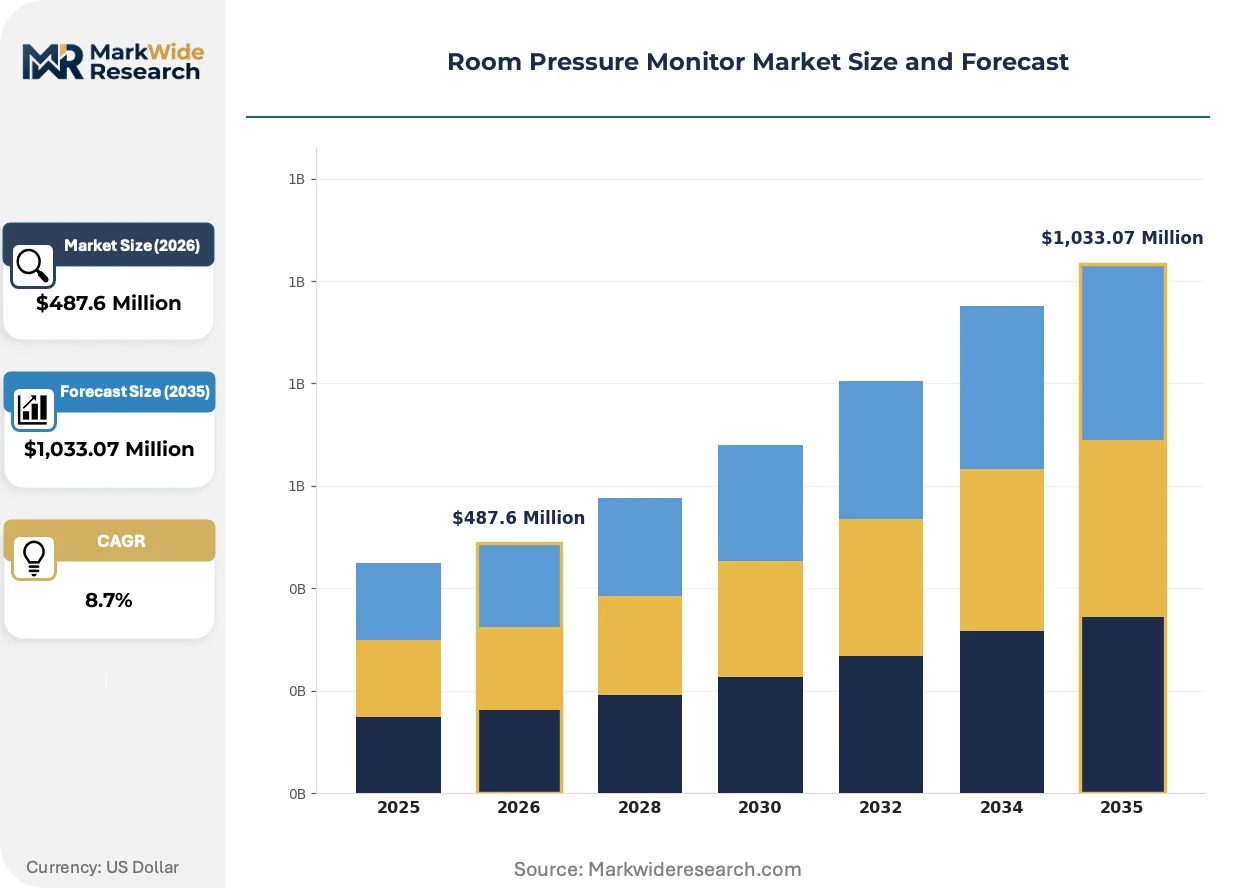
The room pressure monitor market is consolidating around BACnet-enabled digital platforms as healthcare facilities replace aging analog infrastructure to meet tightening airborne infection isolation compliance documentation requirements.
Growth Catalysts
- CMS Mandate Intensification:The US Centers for Medicare and Medicaid Services now require continuous pressure differential logging for airborne infection isolation room certification, forcing hospital capital expenditure toward permanent monitoring installations.
- Sensor Miniaturization:MEMS-based differential pressure sensors achieve calibration stability below 0.001 inches of water column, enabling wireless retrofit deployments in aging healthcare infrastructure without dedicated conduit runs.
- Operating Theater Expansion:Ambulatory surgical centers in the United States are adding positive pressure suites for orthopedic implant procedures, creating dedicated demand for calibrated precision monitors with real-time alarm integration.
Market Restraints
- Capacitive Sensor Supply Concentration:High-stability ceramic capacitive sensing elements for humidity-resistant applications depend on a concentrated supplier base in East Asian semiconductor foundries, exposing lead times to geopolitical friction.
- Calibration Labor Intensity:Analog units require manual zero-point adjustment every six months under ASHRAE guidelines, creating recurring operational cost burdens that compress margins for basic compliance-grade products.
- Building Automation Substitution:Integrated HVAC control platforms from Johnson Controls and Siemens embed pressure sensing as a module rather than standalone instrument, threatening discrete monitor unit volumes in new construction.
Strategic Opportunities
- India Healthcare Infrastructure:The country's PLI scheme for medical device manufacturing incentivizes local assembly of pressure monitors, creating first-mover advantage for firms establishing calibration laboratories in Hyderabad and Bengaluru.
- Predictive Maintenance Convergence:Machine learning algorithms applied to pressure trend data can anticipate filter loading and damper degradation before containment failure, creating subscription revenue streams beyond hardware sale.
- Pharmaceutical Cleanroom Expansion:Sterile injectable manufacturing facilities in Ireland and Switzerland require continuous pressure monitoring for EU GMP Annex 1 compliance, opening premium digital platform demand in European pharmaceutical clusters.
Industry Challenges
- ASHRAE 170 Interpretation Variance:Local inspectors apply conflicting thresholds for acceptable pressure differential alarm delay intervals, forcing manufacturers to maintain region-specific firmware configurations that complicate inventory management.
- Legacy BMS Integration Friction:BACnet protocol version mismatches between 1995-era hospital building management systems and modern pressure monitors require protocol gateway hardware that extends project timelines and strains IT security review capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Room Pressure Monitor Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Monitors, Wireless Monitors, Analog Monitors Use Case: Hospitals, Laboratories, Cleanrooms, Pharmaceutical Facilities Technology: Differential Pressure Sensors, Digital Sensors, Mechanical Sensors, Electronic Sensors End User: Healthcare Providers, Research Institutions, Manufacturing Plants, Educational Facilities |
| Companies Covered | TSI Incorporated, Setra Systems, Johnson Controls, Greystone Energy Systems, Dwyer Instruments, Primex Wireless, Antec Controls, OMEGA Engineering, Modern Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Room Pressure Monitor Market Evolving Landscape
Wireless retrofit architectures are displacing hardwired installations as the dominant deployment model, while sensor fusion with access control and real-time location systems redefines competitive positioning around integrated platform value rather than standalone instrument accuracy.
MEMS-based differential pressure transducers with integrated temperature compensation are modularizing the traditional monitor architecture, separating the sensing element from the display and alarm module. Hospital facilities managers in the United States are adopting these split configurations for phased renovation projects where conduit access is restricted. This modularity is compressing the addressable market for fully integrated analog units while expanding the retrofit opportunity for wireless sensor nodes.
ASHRAE Guideline 36 for high-performance building sequences of operation is tightening documentation requirements for pressure differential maintenance logs, forcing manufacturers to embed timestamped data logging with tamper-evident digital signatures. The industrial consequence is a certification gap between legacy analog monitors and new construction specifications. Pharmaceutical manufacturing facilities in Switzerland and Ireland are responding fastest, specifying only digital platforms with BACnet/IP connectivity for cleanroom applications.
Buying committees at US hospital systems are consolidating vendor relationships around single-source building automation contracts that bundle pressure monitoring with HVAC controls, access control, and fire safety. The independent instrument distributor channel is losing share to direct manufacturer relationships with Johnson Controls, Siemens, and Honeywell. This concentration is most visible in the Southeast United States, where health system mergers have created purchasing entities covering forty-plus hospitals under unified engineering standards.
Room Pressure Monitor Market Segmentation
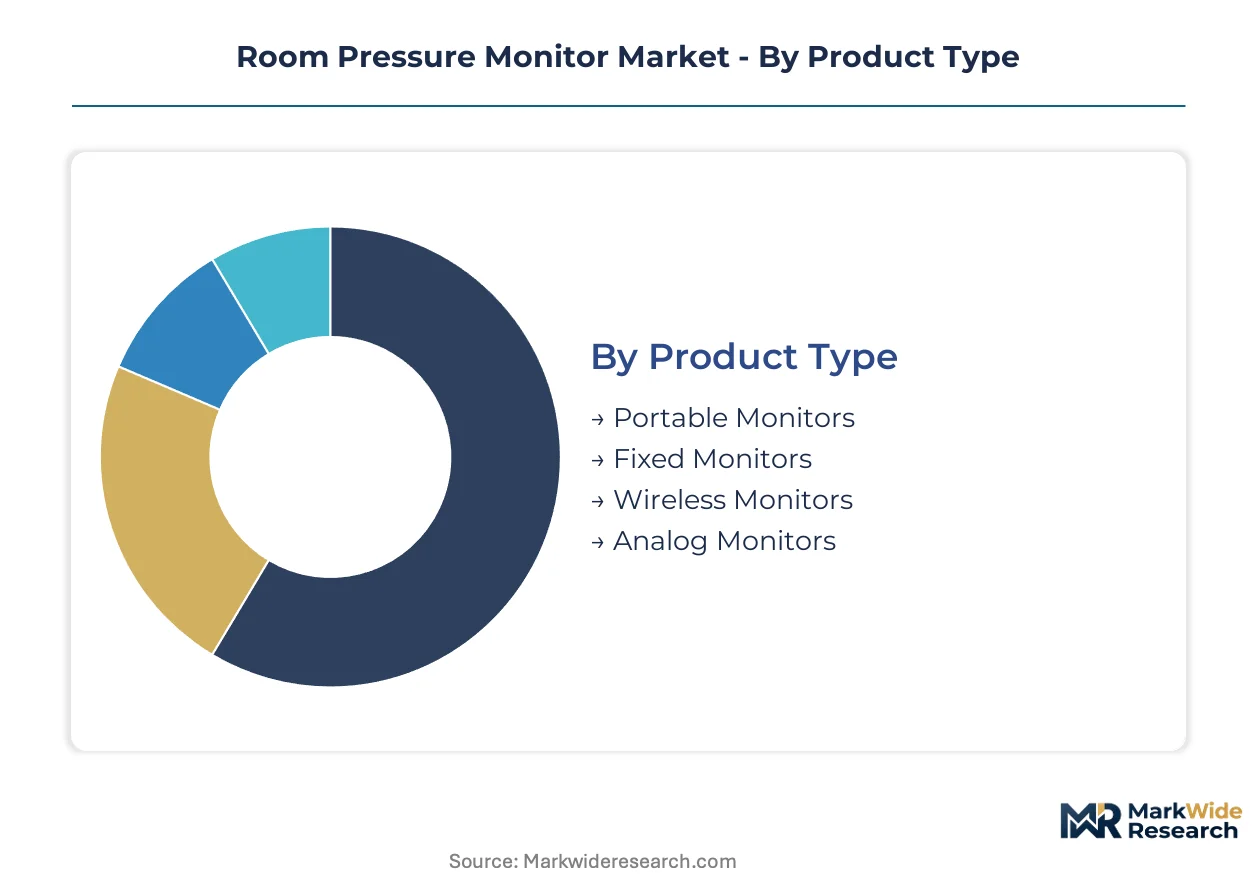
Room pressure monitor procurement diverges sharply between permanent infrastructure commitments and flexible retrofit solutions. Facilities managers weigh calibration labor against wireless convenience when allocating capital across these segment categories.
Product Type:
Upgrade cycles dominate this dimension as hospitals replace analog units with BACnet-enabled platforms to satisfy CMS documentation mandates.
- Fixed Monitors:Permanent installations with hardwired power and data connections deliver continuous compliance logging for airborne infection isolation rooms. United States hospital construction budgets prioritize these units for new ICU wings and operating theater complexes where infrastructure planning permits dedicated conduit runs.
- Wireless Monitors:Battery-powered sensor nodes with LoRaWAN or Wi-Fi backhaul eliminate retrofit wiring costs in aging healthcare facilities. Demand concentrates in the Northeast United States where century-old hospital buildings require pressure verification without structural modification.
- Portable Monitors:Handheld units with rechargeable batteries serve temporary containment verification during construction or emergency surge capacity.
- Analog Monitors:Dial-display units with mechanical pressure sensing persist in budget-constrained educational facilities and small ambulatory clinics.
Fixed monitors sit at the top of the volume ranking, with wireless monitors climbing the fastest.
Use Case:
Application-driven specifications create distinct performance tiers across clinical and industrial environments.
- Hospitals:Operating theaters and isolation suites demand 0.001 inch water column resolution with real-time alarm integration. United States health systems under Joint Commission accreditation drive specification stringency for negative pressure verification in infectious disease wards.
- Pharmaceutical Facilities:Sterile injectable manufacturing requires continuous monitoring for EU GMP Annex 1 and FDA aseptic processing guidelines. Facilities in Ireland and Switzerland specify only digital platforms with tamper-evident data logging for regulatory submission.
- Cleanrooms:Semiconductor and aerospace manufacturing apply ISO 14644-1 pressure cascade requirements with multi-point sensor arrays.
- Laboratories:Biosafety level containment suites combine pressure monitoring with access control interlocks for personnel protection.
Hospitals command the largest installed base, though pharmaceutical facilities are expanding most aggressively.
Technology:
Sensor architecture determines calibration stability and integration depth with building management systems.
- Differential Pressure Sensors:Capacitive and piezoresistive transducers measure air pressure variance directly across room envelopes. These devices anchor hospital infrastructure deployments where measurement reliability outweighs initial cost considerations.
- Digital Sensors:MEMS-based elements with integrated temperature compensation and IoT connectivity enable predictive maintenance algorithms. Adoption accelerates in pharmaceutical cleanrooms where filter loading anticipation prevents costly contamination events.
- Electronic Sensors:Solid-state designs with voltage-output signals interface with legacy BMS protocols through gateway hardware.
- Mechanical Sensors:Bourdon tube and diaphragm mechanisms persist in basic compliance applications without data logging requirements.
Differential pressure sensors retain dominant share, while digital sensors gain ground fastest on predictive maintenance value.
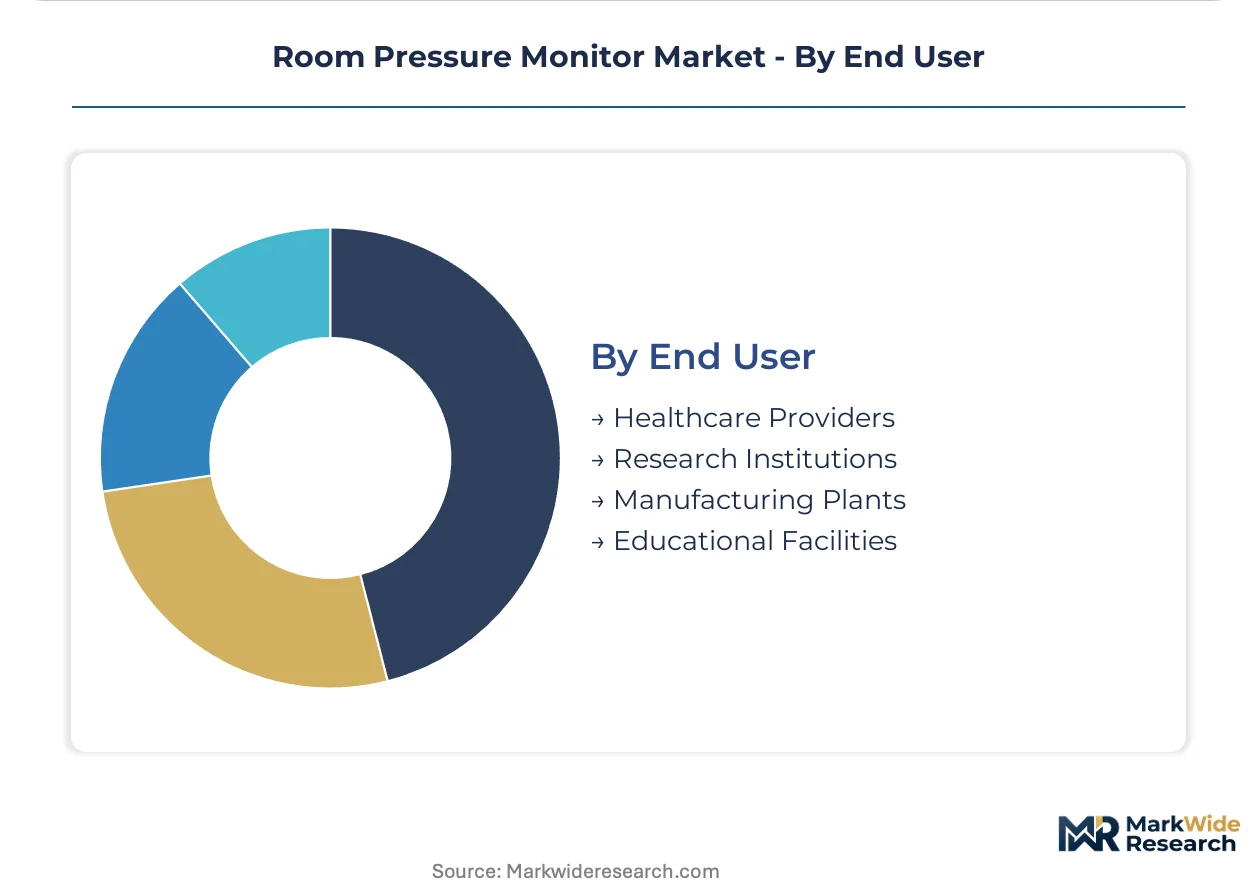
End User:
Procurement authority and technical sophistication vary dramatically across buyer categories.
- Healthcare Providers:Hospital systems and ambulatory surgical centers purchase through consolidated building automation contracts. United States health system mergers have created purchasing entities covering forty-plus facilities under unified engineering standards.
- Manufacturing Plants:Pharmaceutical and biotechnology producers specify monitors as part of validated facility qualification packages. These buyers demand IQ/OQ/PQ documentation and calibration certificate traceability to NIST standards.
- Research Institutions:University laboratories and government research centers balance grant-funded capital constraints against biosafety officer requirements.
- Educational Facilities:Medical and nursing schools train students on operational monitors without requiring regulatory-grade documentation.
Healthcare providers represent the largest procurement volume, with manufacturing plants showing steepest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys room pressure monitors at triple the per-capita density of Germany, reflecting divergent healthcare infrastructure maturity and regulatory enforcement intensity across developed markets.
United States
Hospital construction budgets for airborne infection isolation rooms and ambulatory surgical centers drive procurement volume. CMS mandates continuous pressure differential logging for Medicare certification, tightening compliance documentation requirements. Texas Medical Center in Houston and the Mayo Clinic network in Minnesota anchor large-scale retrofit programs for wireless monitor deployment.
Germany
Pharmaceutical manufacturing expansion and hospital modernization programs sustain monitor demand. The country's national pharmaceutical regulator enforces EU GMP Annex 1 standards for sterile production environments. The Rhine-Main cluster around Frankfurt and the Basel-adjacent Baden-Württemberg region host cleanroom construction projects specifying BACnet-integrated digital platforms.
India
Government hospital upgrades and private healthcare infrastructure investment accelerate monitor adoption. The PLI scheme for medical device manufacturing incentivizes local assembly and calibration laboratory establishment. Hyderabad and Bengaluru emerge as production hubs where domestic firms establish testing facilities for differential pressure sensors.
Switzerland
Pharmaceutical sterile injectable manufacturing and precision medical device production command premium monitor specifications. Swissmedic enforces strict facility qualification protocols requiring tamper-evident data logging. The Basel biotech corridor and Zurich pharmaceutical clusters specify only digital platforms with NIST-traceable calibration certificates.
Japan
Aging hospital infrastructure replacement and semiconductor cleanroom expansion create dual demand streams. METI promotes smart hospital initiatives that integrate pressure monitoring with building automation systems. The Osaka-Kobe manufacturing belt and Tokyo metropolitan hospital networks pilot MEMS-based wireless sensor deployments for predictive maintenance applications.
Room Pressure Monitor Market Competitive Landscape
Top-tier vendors anchor BACnet-integrated digital platforms with sub-0.001 inch water column accuracy, while commodity analog suppliers serve basic compliance segments with mechanical sensing architectures. The supply base consolidates around aerosol science heritage firms, capacitive sensing specialists, and building automation conglomerates extending into unified facility management. Strategic archetypes include precision instrumentation laboratories, sensor technology pure-plays, and diversified controls integrators. Dominant competitive moves encompass backward integration into MEMS fabrication and strategic partnerships with hospital system purchasing consortia.
Among North American instrumentation specialists, TSI Incorporated and Setra Systems occupy positions representing distinct technology lineages—TSI exemplifying aerosol measurement heritage applied to differential pressure, Setra representing capacitive sensing stability leadership. Johnson Controls anchors the building automation integrator archetype, extending HVAC controls expertise into unified pressure monitoring platforms. These three firms collectively represent the competitive vectors defining procurement criteria across healthcare and pharmaceutical end markets.
| Leading Market Players |
|---|
| TSI Incorporated |
| Setra Systems |
| Johnson Controls |
| Greystone Energy Systems |
| Dwyer Instruments |
| Primex Wireless |
| Antec Controls |
| OMEGA Engineering |
| Modern Automation |
| Others |
Value Network & Pricing Analysis
Backward integration into MEMS fabrication anchors both supply security and pricing power for premium digital platform manufacturers, while outsourced ceramic capacitive sensing element procurement leaves commodity analog suppliers exposed to East Asian foundry lead time volatility and margin compression.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for standard-grade monitors, forcing legacy analog suppliers toward cost compression. Three-tier pricing structure across premium BACnet-integrated platforms, mid-range digital units, and economy analog dial displays separates calibration-intensive healthcare specifications from basic educational facility compliance. Price differentiation hinges on NIST-traceable certification documentation and humidity-resistant ceramic capacitive sensing stability. Margins are tightening in the analog tier due to manual calibration labor intensity per ASHRAE guidelines, while pharmaceutical facilities in Switzerland and Ireland show lowest price sensitivity for tamper-evident data logging platforms.
Supply Chain Analysis
Dual-sourcing qualification mandates from US hospital systems and European pharmaceutical manufacturers require redundant MEMS foundry relationships and backup calibration laboratory accreditation. High-stability ceramic capacitive sensing elements concentrate in Taiwan and South Korea semiconductor foundries, while MEMS differential pressure transducer fabrication draws from US and Japanese specialty manufacturers. Raw material dependencies span silicon wafers, ceramic substrates, and precision-machined brass reference ports. Single-source vulnerability in East Asian ceramic capacitive element supply exposes lead times to geopolitical friction. Distribution runs through building automation direct manufacturer relationships and independent instrument distributors serving retrofit wireless deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where CMS mandate intensification and ASHRAE 170 documentation requirements shift procurement toward premium BACnet-integrated platforms with sub-0.001 inch water column accuracy.
For Market Incumbents: Hedge against building automation substitution by embedding pressure monitoring within unified facility management platforms through HVAC controls integration partnerships. Deepen backward integration into MEMS temperature-compensated transducer fabrication to secure calibration stability leadership against emerging capacitive sensing specialists. Defensive patent positioning around predictive maintenance algorithms for filter loading anticipation protects recurring subscription revenue streams from software-native entrants. For New Entrants and Emerging Players: Launch via wireless retrofit distribution partnerships targeting century-old Northeast US hospital infrastructure where conduit access restrictions favor battery-powered LoRaWAN sensor nodes. White-space concentration sits in Indian government hospital upgrade programs under PLI scheme incentives, where domestic calibration laboratory establishment creates first-mover regulatory qualification advantage. Target ambulatory surgical center positive pressure suite additions with portable monitor rental models for temporary orthopedic implant procedure verification. For Investors and Strategic Acquirers: Roll-up economics work for aerosol science heritage laboratories with dormant healthcare channel relationships because hospital system purchasing consolidation creates vendor rationalization pressure. Long-term viability centers on platform-integrated digital monitor suppliers with BACnet/IP protocol depth and NIST-traceable calibration certificate libraries. Acquisition target archetype: MEMS sensing pure-plays with humidity-stable temperature compensation IP. Signal to watch is Joint Commission accreditation survey failure rates for airborne infection isolation room pressure differential documentation gaps.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Backward Integration | In-house transducer production secures calibration stability below 0.001 inches water column for critical healthcare environments. |
| BACnet-Enabled Platform Launch | Digital integration with Johnson Controls and Siemens building automation systems captures hospital construction specification share. |
| Wireless Retrofit Distribution Partnership | LoRaWAN sensor node deployment bypasses conduit installation barriers in aging Northeast US hospital infrastructure. |
| Predictive Maintenance Algorithm Development | Machine learning on pressure trend data creates subscription revenue beyond hardware sale for pharmaceutical cleanroom applications. |
| Indian PLI Scheme Manufacturing Localization | Hyderabad and Bengaluru calibration laboratory establishment qualifies domestic production for government hospital procurement mandates. |
Research Methodology
Direct dialogue with hospital biomedical engineers, pharmaceutical facility qualification managers, GPO contracts administrators, and HVAC controls integration specialists grounded qualitative findings in procurement authority dynamics and technical specification evolution. Secondary validation drew from CMS Medicare certification survey data, ASHRAE guideline documentation, FDA aseptic processing guidance, and EU GMP Annex 1 facility inspection records. Bottom-up unit deployment estimates triangulated against top-down healthcare construction spending and pharmaceutical cleanroom capital expenditure patterns.
Segment-level outputs across fixed, wireless, portable, and analog product types combined with hospital, pharmaceutical, cleanroom, and laboratory use case dimensions calibrated the analytical framework over the projection horizon. Technology tier modeling incorporated differential pressure, digital MEMS, electronic, and mechanical sensor architectures against end user procurement sophistication variations. CAGRs derived from facility construction pipeline analysis, regulatory mandate implementation timelines, and replacement cycle acceleration in analog-to-digital upgrade programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ASHRAE 170 interpretation variance by local inspectors and BACnet protocol version mismatch friction in legacy building management system integration. Deviation in East Asian ceramic capacitive sensing element supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Smart Thermometer Market