
 Europe Electric Drives Market | 2026-2036
Europe Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Drives Market Foresight
Software-defined maintenance contracts is realigning how European vendors monetize electric drive systems beyond hardware shipments. Siemens leverages its digital service platform to extend recurring revenue from predictive analytics on installed motor control bases. ABB anchors its competitive stance through integrated drive-motor-service bundles that reduce total cost of ownership for industrial buyers. SEW-EURODRIVE specializes in modular retrofit packages that allow legacy manufacturing lines to upgrade without full replacement.
Europe Electric Drives encompass electromechanical systems that regulate motor speed, torque, and rotational direction through power electronic converters typically operating at 230V to 690V input ranges with switching frequencies between 2 kHz and 16 kHz, serving primarily to optimize energy consumption and process precision in industrial machinery. AC Drives dominate installed capacity across European manufacturing floors due to their compatibility with standard induction motors and mature supply chains, while Servo Drives capture expanding share in robotics and high-precision positioning applications where dynamic response requirements exceed conventional variable frequency capabilities. Intelligent Drive technology incorporating edge computing and condition monitoring is emerging as the fastest-growing segment as OEMs embed diagnostics directly into power conversion hardware.
The EU Ecodesign Directive and ECHA REACH frameworks mandate minimum efficiency classes and restrict hazardous substances in drive electronics, compelling manufacturers to redesign power modules and thermal management systems. CE marking under the Machinery Directive governs functional safety integration, particularly for servo systems deployed in collaborative robot cells. Stakeholders must evaluate how pending F-Gas Regulation amendments on refrigerant-based cooling will reshape thermal design choices for high-power drive enclosures.
Market Dynamics
EU Ecodesign Directive efficiency mandates are compressing the upgrade cycle for industrial motor systems as manufacturers face 2025 compliance deadlines for IE4 premium efficiency requirements. German automotive clusters are accelerating full-line electrification to preempt regulatory penalties.
Growth Catalysts
- IE4 Motor Mandates:Ecodesign Directive 2019/1781 requires premium efficiency classes for motors above 0.75kW, forcing replacement of installed bases across Italian metalworking and French food processing facilities.
- Automotive Electrification:German OEMs are converting internal combustion engine production lines to battery electric vehicle assembly, driving demand for precision servo systems in welding and battery pack integration stations.
- Industrial Edge Computing:Embedded condition monitoring is automating predictive maintenance workflows, reducing unplanned downtime for Polish logistics centers and Czech manufacturing plants.
Market Restraints
- Silicon Carbide Supply Concentration:Wide bandgap semiconductor substrates for next-generation inverters depend on a concentrated supply base in East Asia, exposing European drive manufacturers to input cost volatility and allocation risk.
- Copper and Rare Earth Magnet Costs:Permanent magnet servo motors require neodymium-iron-boron materials where price swings compress margin structures for mid-tier drive vendors serving Spanish packaging machinery OEMs.
- Legacy System Interoperability:Fieldbus protocol fragmentation across PROFIBUS, PROFINET, EtherCAT, and Modbus TCP creates technical friction in brownfield retrofit projects at Italian textile manufacturers.
Strategic Opportunities
- CEE Manufacturing Expansion:Hungary, Romania, and Slovakia are attracting automotive supplier investments where electrified production lines require localized drive system integration support.
- F-Gas Thermal Design Pivot:Pending amendments to the F-Gas Regulation on refrigerant-based cooling create white space for liquid-cooled and air-cooled drive enclosure architectures in high-power metal processing applications.
- Remanufacturing and Retrofit Services:Modular drive-motor replacement packages allow Czech and Polish industrial buyers to upgrade efficiency without full line reconstruction, opening recurring revenue streams for service-anchored vendors.
Industry Challenges
- Power Electronics Engineering Talent:Shortages of specialists in wide bandgap device integration and thermal management design are extending product development timelines for mid-sized drive manufacturers in Northern Italy.
- CE Marking and Functional Safety Certification:Machinery Directive compliance for servo systems deployed in collaborative robot cells requires extended validation cycles, compressing time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Drives Market |
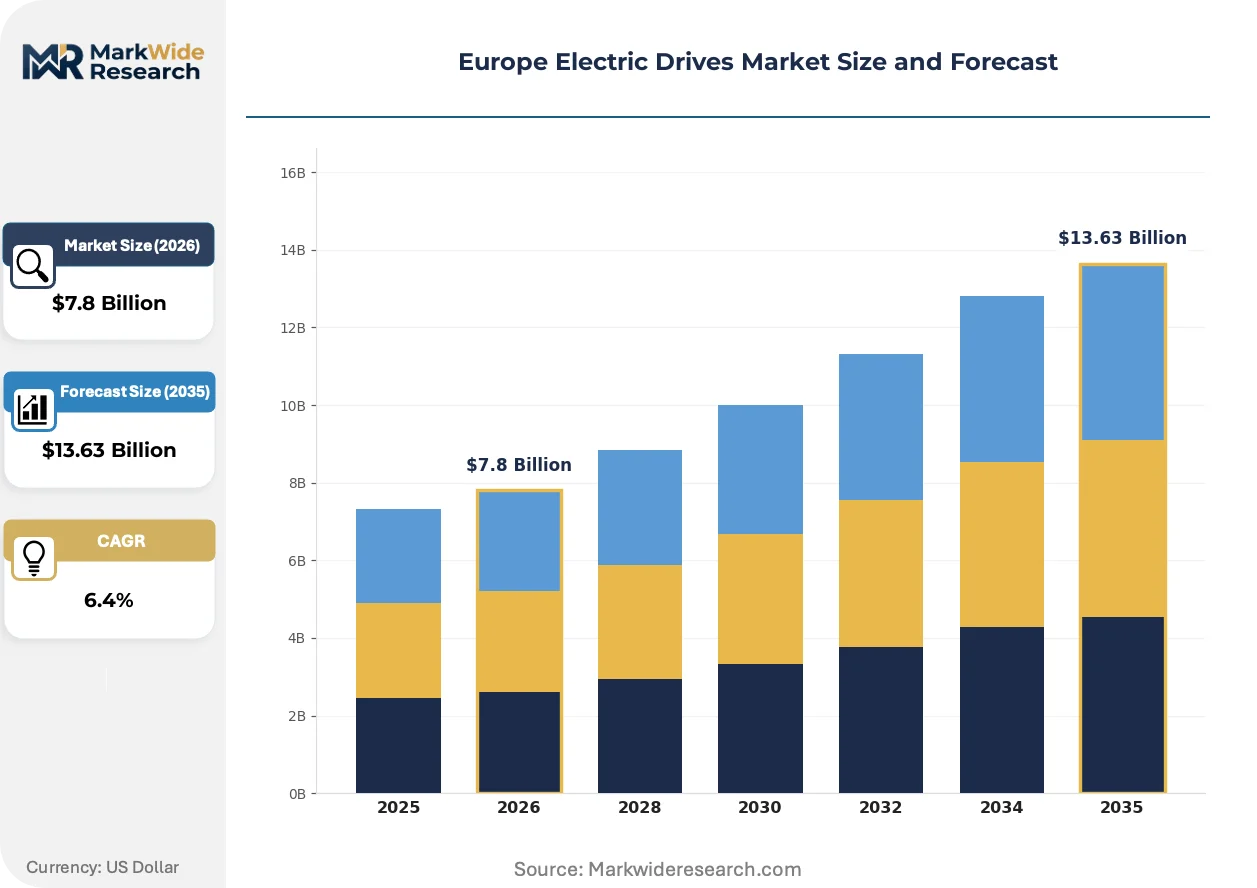
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Stepper Drives End User: Manufacturing, Automotive, Renewable Energy, Commercial Technology: Variable Frequency Drive, Direct On-Line, Soft Starter, Intelligent Drive Application: Conveyor Systems, Pumps, Fans, Compressors |
| Companies Covered | Schneider Electric, Rockwell Automation, ABB, SEW-EURODRIVE, Yaskawa Europe, Siemens, Danfoss, CEDS DURADRIVE, Robert Bosch, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Drives Market Shifts & Advancements
Edge-native drive architectures are embedding intelligence directly at the motor control layer, compressing the traditional separation between automation hardware and analytics software. This convergence is redefining how European industrial buyers evaluate total system economics.
Silicon carbide-based power modules are automating efficiency gains in variable frequency drives by enabling higher switching frequencies with reduced thermal losses. German machine tool builders are adopting these devices for spindle control applications where precision and energy recovery matter. The technology is automating the displacement of traditional IGBT architectures in power ratings above 75kW.
EU F-Gas Regulation amendments are tightening refrigerant-based cooling restrictions for industrial equipment, forcing thermal design innovation in high-power drive enclosures. Manufacturers are responding with liquid-cooled and advanced air-cooled architectures for metal processing and heavy machinery segments. The regulation is accelerating adoption in German steel processing and Italian ceramics manufacturing where enclosure power densities exceed 500kW.
Service contract unbundling is fragmenting how industrial buyers procure drive system lifecycle support. German automotive tier-one suppliers are separating hardware purchase from predictive maintenance subscriptions, creating new channel economics for digitally enabled vendors. This pattern is most visible in Baden-Württemberg and Bavaria where multi-site fleet management demands centralized diagnostics platforms.
Europe Electric Drives Market Segmentation
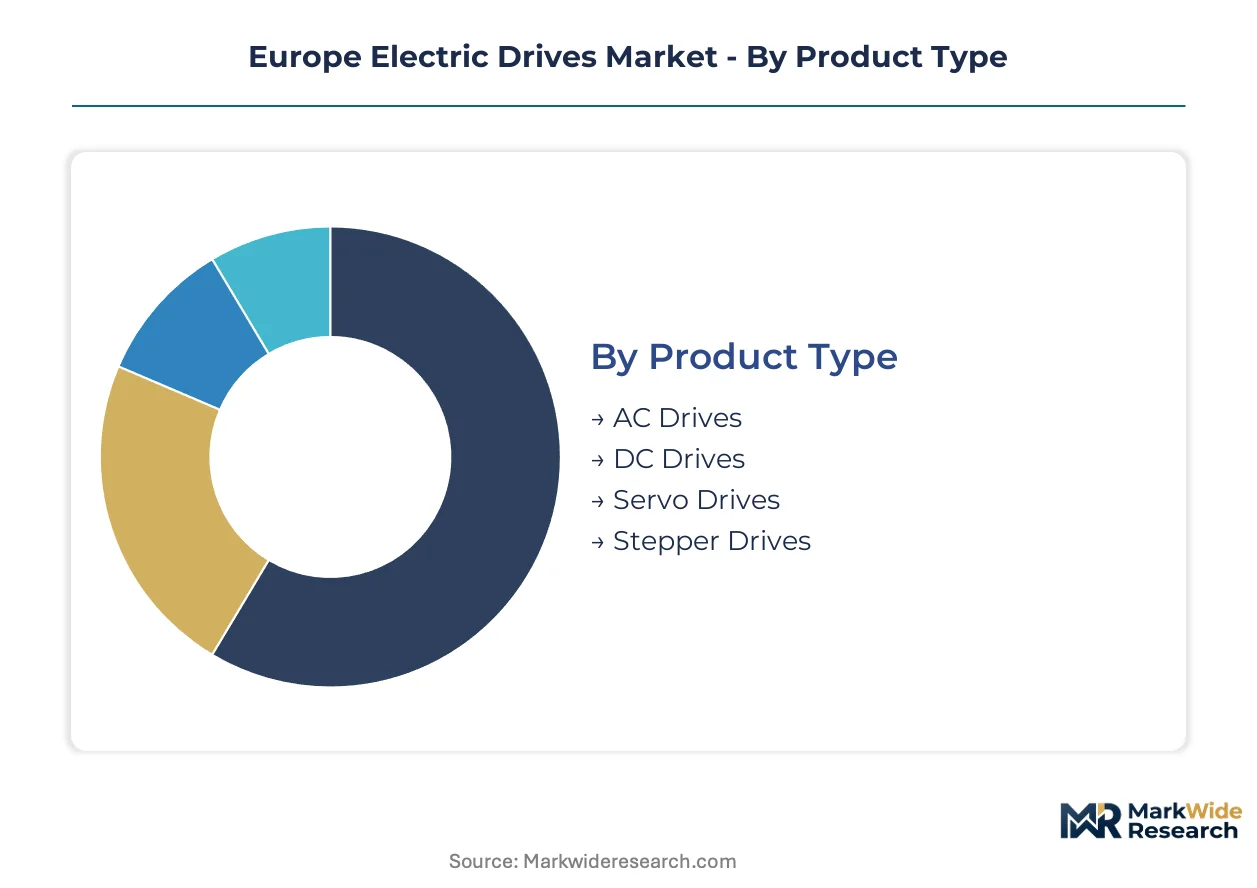
Segmentation reveals how European electric drive demand fragments across power conversion technologies, end-use sectors, and control methodologies. Each axis exposes distinct procurement patterns and regulatory exposure profiles that shape vendor positioning strategies.
Product Type:
Power conversion architecture determines efficiency ceiling, dynamic response capability, and integration complexity with legacy motor bases.
- AC Drives:Variable frequency drives operating between 230V and 690V input ranges dominate installed capacity across European manufacturing floors. German automotive plants and Italian metalworking facilities prioritize AC drive retrofits to meet Ecodesign IE4 motor mandates without full line replacement.
- Servo Drives:Closed-loop position control systems with sub-millisecond response times enable precision robotics and battery pack assembly operations. Demand concentrates in Bavarian automotive clusters and Stuttgart-area machine tool builders where collaborative robot cells require Machinery Directive-compliant functional safety integration.
- DC Drives:Ward-Leonard and thyristor-based architectures persist in legacy crane and hoist applications across Polish steel mills and Romanian heavy industry where complete electrification remains capital-constrained.
- Stepper Drives:Open-loop positioning systems serve low-cost automation in Czech packaging machinery and Spanish textile equipment where absolute precision is secondary to cost minimization.
Mature deployment sits with AC Drives across general industrial applications. Newer deployment is concentrated in Servo Drives for electrified automotive production lines.
End User:
End-use sector dictates performance specifications, duty cycle requirements, and service contract structures.
- Manufacturing:Metalworking, food processing, and material handling operations across Northern Italy and Eastern France require drives with continuous duty ratings and predictive maintenance integration. EU Ecodesign Directive compliance deadlines are accelerating replacement cycles in this segment.
- Automotive:Battery electric vehicle assembly lines in Baden-Württemberg and Lower Saxony demand servo-grade precision for welding, gluing, and battery module integration stations. OEMs unbundle hardware procurement from predictive maintenance subscriptions.
- Renewable Energy:Wind turbine pitch control and solar tracking systems in Denmark and Spain utilize ruggedized drives with extended temperature ranges and grid-code compliance features.
- Commercial:HVAC and building automation applications across French and Benelux commercial real estate prioritize compact form factors and BACnet integration over industrial-grade durability.
Volume concentration remains heaviest in Manufacturing. Steepest expansion trajectory is visible in Automotive as combustion engine lines convert to electrified assembly.
Technology:
Control methodology determines energy recovery capability, starting current limitation, and embedded intelligence depth.
- Variable Frequency Drive:Pulse-width modulation inverters with IGBT or silicon carbide power stages enable precise speed control and regenerative braking. German machine tool builders adopt SiC-based variants for spindle applications above 75kW.
- Intelligent Drive:Edge-native architectures embedding condition monitoring and predictive analytics directly at the motor control layer. Polish logistics centers and Czech manufacturing plants automate maintenance workflows through these systems.
- Soft Starter:Reduced-voltage starting methods limit inrush current for centrifugal pumps and fans in Italian water treatment and French HVAC infrastructure where full variable speed is unnecessary.
- Direct On-Line:Across-the-line starting persists in low-complexity fan and pump applications where capital cost minimization outweighs energy efficiency gains.
Established penetration characterizes Variable Frequency Drive deployment. Technology transition is accelerating toward Intelligent Drive architectures as predictive maintenance becomes standard procurement criteria.
Application:
Mechanical load profile determines torque requirements, acceleration demands, and duty cycle specifications.
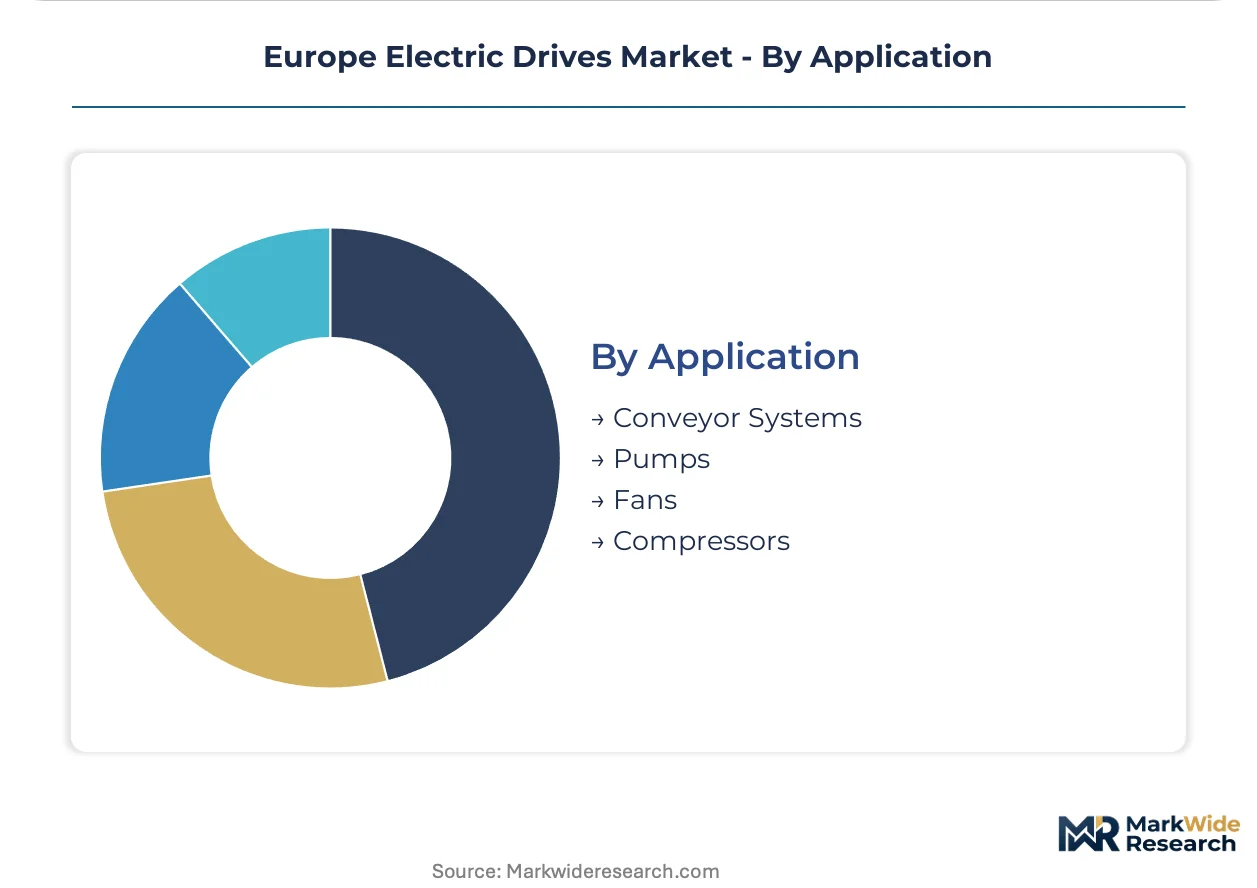
- Pumps:Centrifugal and positive displacement pumping across water treatment, chemical processing, and oil and gas infrastructure requires constant torque or variable torque control profiles. Ecodesign efficiency mandates are forcing upgrades in Spanish desalination and Dutch petrochemical facilities.
- Fans:HVAC and process ventilation systems in German commercial buildings and Italian ceramics manufacturing present high-volume, lower-precision opportunities where energy recovery features justify premium pricing.
- Conveyor Systems:Material handling networks in Polish distribution centers and Romanian automotive supplier parks demand coordinated multi-axis control with precise speed synchronization.
- Compressors:Air compression and refrigeration systems face F-Gas Regulation thermal design constraints that favor liquid-cooled drive enclosures in high-power metal processing applications.
Installed base concentration favors Pumps across municipal and industrial fluid handling. Application growth is shifting toward Conveyor Systems as Central and Eastern European logistics infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European electric drive demand through its concentration of automotive OEMs and precision machinery manufacturers converting combustion engine lines to battery electric vehicle assembly.
Germany
Baden-Württemberg and Bavaria host the densest clusters of servo drive deployment for welding robotics and battery pack integration stations. The EU Ecodesign Directive 2019/1781 compels IE4 motor upgrades across metalworking facilities in North Rhine-Westphalia. Siemens and SEW-EURODRIVE maintain headquarters proximity to Stuttgart and Heidelberg, enabling rapid response to automotive tier-one supplier technical requirements.
France
Île-de-France food processing and Auvergne-Rhône-Alpes metalworking operations drive AC drive retrofit demand ahead of efficiency compliance deadlines. The French Environment and Energy Management Agency (ADEME) co-funds industrial electrification projects through its investment programs. Schneider Electric anchors its European operations in Rueil-Malmaison, supplying drive-motor bundles to Paris Basin manufacturing facilities.
Italy
Lombardy and Emilia-Romagna textile and packaging machinery OEMs source mid-tier variable frequency drives for export-oriented equipment production. Ecodesign Directive implementation compresses replacement cycles for installed motor bases above 0.75kW. SEW-EURODRIVE operates its Italian headquarters in Milan, serving the Po Valley industrial corridor with modular retrofit packages.
Poland
Łódź and Wrocław distribution centers automate conveyor networks with intelligent drive architectures embedding edge-based condition monitoring. The National Fund for Environmental Protection and Water Management (NFOSiGW) subsidizes energy efficiency investments in industrial machinery. Polish logistics operators prioritize predictive maintenance integration to minimize unplanned downtime across multi-site material handling operations.
Czech Republic
Automotive supplier parks in Mladá Boleslav and Ostrava deploy servo systems for precision assembly operations serving German OEM supply chains. EU cohesion funds channel investment into manufacturing modernization, accelerating drive system electrification. Local industrial buyers favor modular drive-motor replacement packages that upgrade efficiency without full production line reconstruction.
Europe Electric Drives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Europe's electric drive sector, creating a tiered structure where integrated conglomerates face specialized regional vendors. The market consolidates around three strategic archetypes: full-stack automation houses bundling hardware, software, and services; component specialists focusing on power conversion modules; and retrofit service providers targeting legacy system upgrades. Dominant competitive moves include portfolio diversification into predictive maintenance subscriptions and geographic expansion through Central and Eastern European distribution partnerships.
Among Germany-based industrial conglomerates, Siemens and SEW-EURODRIVE exemplify the integrated automation archetype, occupying positions that span drive hardware manufacturing through digital service platform deployment. ABB represents the cross-border diversified model, anchoring competitive positioning through its Swiss-Swedish operational footprint and integrated drive-motor-service offerings. Schneider Electric sits within the French-led energy management tier, extending its historical strength in electrical distribution into motor control applications.
| Leading Market Players |
|---|
| Schneider Electric |
| Rockwell Automation |
| ABB |
| SEW-EURODRIVE |
| Yaskawa Europe |
| Siemens |
| Danfoss |
| CEDS DURADRIVE |
| Robert Bosch |
| Others |
Supply & Pricing Matrix
Silicon carbide power module adoption is compressing cost curves for variable frequency drives above 75kW while simultaneously concentrating procurement leverage among German and Japanese substrate suppliers. This dual effect elevates pricing power for integrated vendors with captive SiC sourcing while squeezing margin structures for mid-tier competitors dependent on spot market procurement.
Pricing Analysis
Outcome-based pricing anchored to energy savings guarantees dominates German automotive tier-one procurement, with contracts tying vendor compensation to verified efficiency gains against baseline consumption. Three-tier pricing structure across premium, standard, and economy levels separates IE4-certified servo bundles from basic AC drive retrofits and unbranded replacement units. Pricing pressure stems from rare earth magnet cost volatility in permanent magnet servo motors, compressing margins for vendors serving Spanish packaging machinery OEMs. Mid-tier industrial buyers in Italian textile manufacturing exhibit highest price sensitivity, while Baden-Württemberg automotive clusters prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive clusters, while distribution partners serve fragmented metalworking and food processing facilities across France and Italy. Silicon carbide substrates draw from concentrated Japanese and German supply bases, with copper windings and neodymium-iron-boron magnets sourcing from Chilean mining operations and Chinese rare earth refiners. Single-source vulnerability in wide bandgap semiconductor substrates exposes European drive manufacturers to allocation risk during capacity constraints. Distribution runs through authorized system integrators in Central and Eastern Europe, with SEW-EURODRIVE and Siemens maintaining direct sales presence in Stuttgart and Munich corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide substrate capacity constraints prop pricing power for integrated vendors, creating a supply-constrained market structure where captive sourcing becomes the primary defensive moat.
For Market Incumbents: Deepen backward integration into SiC power module manufacturing or secure long-term offtake agreements with Japanese substrate suppliers to defend against margin compression from rare earth cost volatility. Prioritize certification investment for Machinery Directive-compliant servo systems deployed in collaborative robot cells, as CE marking validation cycles create barriers for emerging competitors. Channel control through direct technical service presence in Baden-Württemberg automotive corridors reinforces pricing power against distributor-dependent challengers. For New Entrants and Emerging Players: Regional system integrators in Hungary and Romania represent the most penetrable channel partners, as automotive supplier investments in CEE manufacturing clusters outpace localized drive system integration support. Target modular retrofit packages for Czech and Polish brownfield installations where full line replacement remains capital-constrained, leveraging predictive maintenance subscriptions as the primary go-to-market wedge against hardware-centric incumbents. White space exists in liquid-cooled drive enclosures for high-power metal processing applications facing F-Gas Regulation thermal design constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial automation conglomerates seeking predictive maintenance platform capabilities, with secondary buyout interest from private equity firms consolidating mid-tier European drive vendors. Long-term viability favors vendors with software-defined service revenue exceeding thirty percent of total mix, as hardware commoditization accelerates across standard AC drive segments. Monitor silicon carbide substrate allocation announcements from German and Japanese suppliers as the critical inflection signal for margin expansion or compression across the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Power Module Integration | Enables efficiency gains above 75kW for German machine tool spindle applications. |
| Predictive Maintenance Platform Launch | Extends recurring revenue from installed motor control bases at Polish logistics centers. |
| CEE Distribution Partnership Expansion | Captures automotive supplier investments in Hungarian and Romanian electrified production lines. |
| Liquid-Cooled Envelope Development | Addresses F-Gas Regulation constraints for Italian ceramics and German steel processing. |
| Modular Retrofit Package Introduction | Opens service-anchored revenue streams in Czech brownfield manufacturing upgrades. |
Research Methodology
Document review covered EU Ecodesign Directive implementation guidance, ECHA REACH substance restriction databases, and F-Gas Regulation amendment drafts, complemented by interviews with plant engineers at German automotive facilities, procurement leads at Italian metalworking OEMs, aftermarket service heads at French distribution partners, and technical R&D directors at power electronics manufacturers. Secondary validation drew from SEC filings of listed industrial conglomerates, customs trade data for silicon carbide substrate imports, and Machinery Directive certification records. Bottom-up demand modeling across power rating tiers and end-use sectors was triangulated against top-down macroeconomic indicators for European manufacturing investment.
Unit shipment and revenue estimates were generated through multi-dimensional segmentation across product type, end user industry, control technology, and mechanical application, with growth trajectories calibrated to IE4 motor mandate compliance deadlines and automotive electrification capital expenditure cycles. CAGRs were derived from regression analysis of historical replacement patterns projected against regulatory forcing functions and technology substitution curves. Forecast inputs incorporated silicon carbide adoption rates in high-power drives, edge computing penetration in condition monitoring systems, and Central and Eastern European manufacturing capacity expansion timelines.
Caveats apply where F-Gas Regulation final amendments, rare earth export restrictions, or wide bandgap semiconductor supply disruptions could materially shift the outlook for thermal design choices and cost structures. Periodic stress-testing of base assumptions against regulatory implementation schedules and substrate capacity announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Busbar Trunking System Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
High Voltage PTC Heater Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Industrial Plugs and Sockets Market
Electrical Equipment
Insulator Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Fiberglass Electrical Enclosure Market