
 Pad-Mounted Transformer Market | 2026-2036
Pad-Mounted Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Pad-Mounted Transformer Market Analysis
Capital-intensity divergence between integrated manufacturers and assembly-focused competitors is redrawing competitive boundaries in pad-mounted transformer supply. ABB Ltd. leverages captive core-steel processing and in-house insulation systems to sustain margin structures that smaller rivals cannot replicate. Eaton Corporation Plc. anchors its position through extensive North American channel control and utility-direct relationships. Siemens Energy AG competes on liquid-immersed design leadership for high-reliability urban installations.
A pad-mounted transformer is a ground-level, tamper-resistant electrical distribution device housed in a locked steel cabinet, typically oil-filled or dry-type, designed to step down medium-voltage utility power to low-voltage levels suitable for commercial and residential consumption. These units operate with power ratings spanning 10 kVA to 100 kVA and incorporate mineral oil or ester-based coolants to manage thermal loads in confined enclosures. Three-phase configurations dominate utility-scale deployments due to higher load-handling capacity, while single-phase variants retain strong positions in residential subdivision applications where cost minimization governs procurement. Custom-built designs are capturing expanding share from data center and renewable interconnection projects requiring non-standard impedance characteristics.
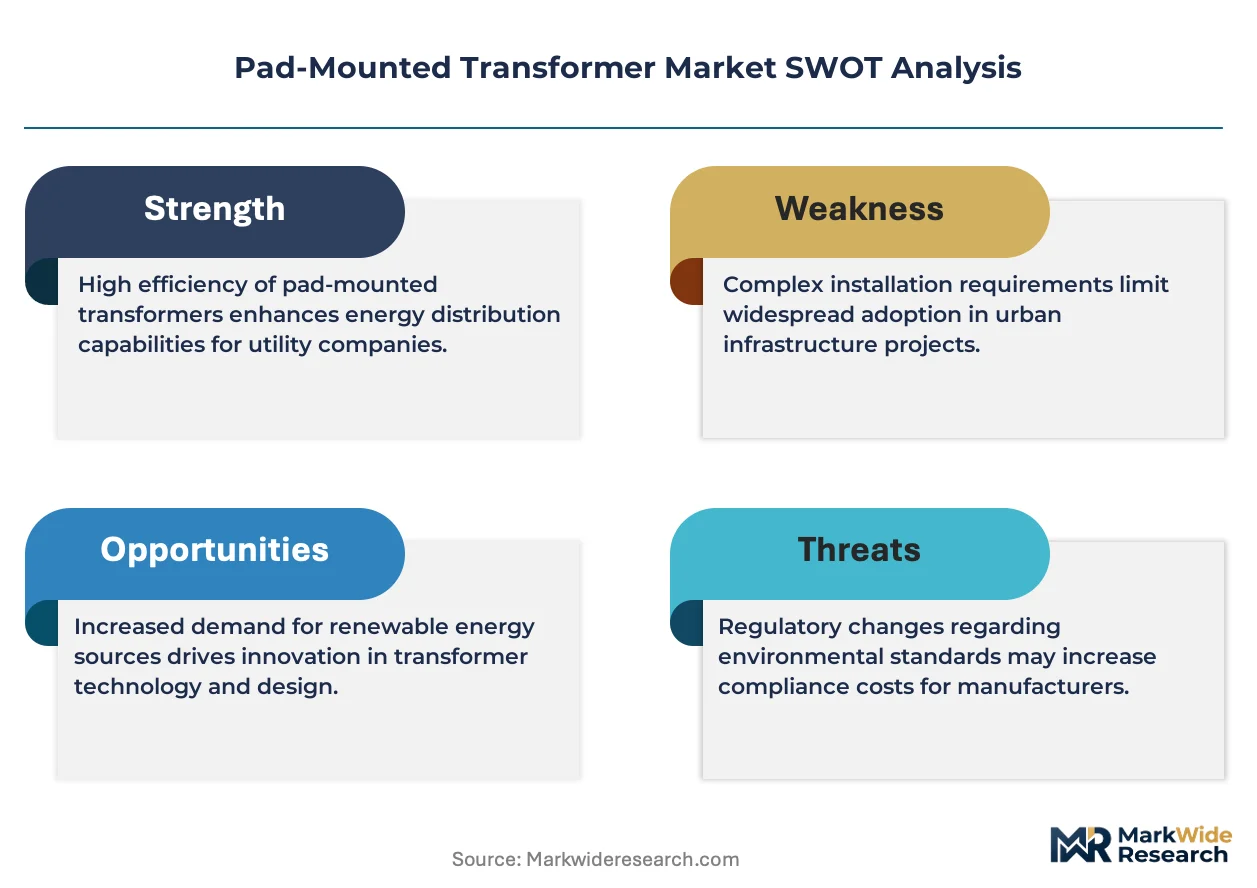
Utilities face compliance pressure from IEEE C57.12.00 insulation standards, NEMA TP-1 efficiency requirements, and EPA spill prevention rules governing oil-filled installations. These frameworks elevate material costs but simultaneously restrict market access for uncertified suppliers, concentrating procurement among validated vendors. Stakeholders must monitor evolving state-level interconnection standards and utility procurement shifts toward ester fluid alternatives as decisive variables for manufacturing strategy and capacity planning.
Market Dynamics
Data center operators are consolidating procurement around ester-fluid pad-mounted units, forcing legacy oil-filled manufacturers to requalify designs under tightened EPA spill-prevention frameworks.
Growth Catalysts
- IEEE C57.12.00 insulation standards:Revised dielectric testing protocols are mandating upgraded winding systems across utility-scale deployments, accelerating replacement cycles for pre-2015 installed base.
- Texas and Virginia utility zones:Hyperscale data center construction is concentrating demand for 2,500 kVA+ custom configurations with non-standard impedance tolerances.
- Ester-based coolants:Synthetic and natural ester fluids are penetrating renewable interconnection projects where fire-safety codes restrict mineral oil installations.
Market Restraints
- Grain-oriented electrical steel:Core material pricing volatility is compressing margins for assembly-focused competitors lacking captive steel processing.
- NEMA TP-1 efficiency requirements:Compliance testing costs are excluding uncertified regional suppliers from utility procurement shortlists.
- Dry-type air-cooled units:Indoor substation applications are substituting liquid-immersed designs where space constraints and indoor fire codes apply.
Strategic Opportunities
- Renewable interconnection standards:State-level solar and wind farm codes are mandating pad-mounted step-up configurations with extended temperature rise ratings.
- Direct utility channel partnerships:Bypassing electrical distributors through cooperative procurement agreements is capturing margin from specification-to-delivery workflows.
- Digital monitoring integration:Embedded dissolved-gas analysis sensors and thermal imaging ports are creating premium pricing tiers for predictive maintenance contracts.
Industry Challenges
- Transformer design engineering:Shortage of specialists proficient in finite-element thermal modeling and electromagnetic field simulation is extending product development timelines.
- EPA SPCC compliance documentation:Oil containment system certification and spill-response plan filing are adding 8-14 weeks to project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pad-Mounted Transformer Market |
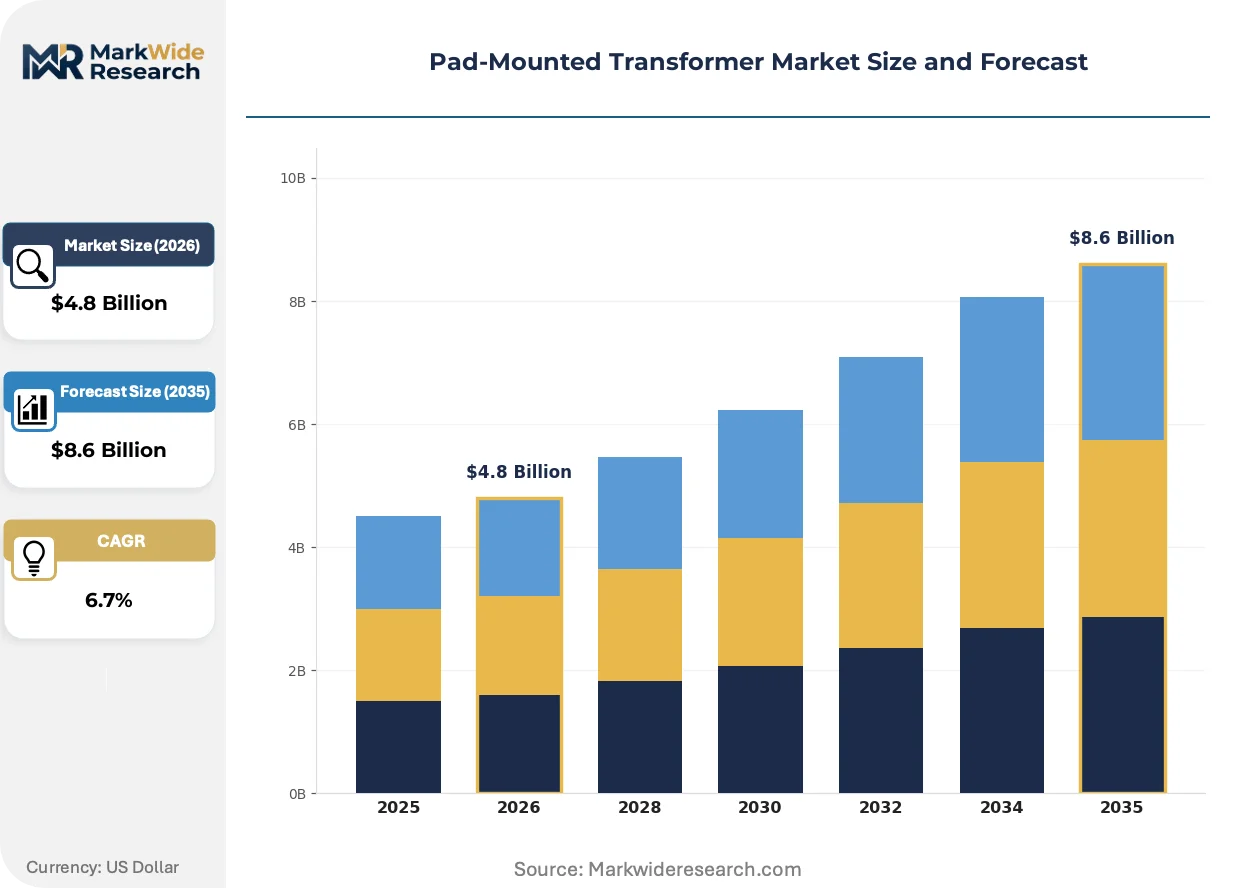
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Miniature, Custom-Built Installation Type: Underground, Above Ground, Hybrid, Pole-Mounted End User: Utilities, Commercial, Residential, Industrial Power Rating: 10 kVA, 25 kVA, 50 kVA, 100 kVA |
| Companies Covered | ABB Ltd., Eaton Corporation Plc., Schneider Electric, Siemens Energy AG, General Electric, Hitachi Energy, ERMCO, Toshiba Corporation, Howard Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pad-Mounted Transformer Market Emerging Trajectories
Ester fluid technology, digital monitoring integration, and consolidated buyer procurement are restructuring competitive positioning across pad-mounted transformer supply chains.
Natural ester dielectric fluids derived from seed oils are displacing mineral oil in fire-sensitive installations. Data center operators in Virginia and Texas are specifying these formulations for outdoor campus distribution. The shift is compressing addressable market for conventional oil-filled designs in high-reliability segments.
EPA spill prevention rules under the Clean Water Act are tightening secondary containment specifications for pad-mounted installations. Manufacturers must now engineer integral containment basins and leak-detection systems into standard enclosures. Utilities in coastal and flood-prone zones are accelerating procurement of compliant units ahead of enforcement deadlines.
Specification authority is migrating from electrical contractors to utility engineering departments and data center facility teams. Direct manufacturer-utility technical collaboration is replacing distributor-mediated transactions for large-project procurement. This channel compression is most visible in Texas ERCOT zones and Northern Virginia utility territories where procurement volumes justify dedicated vendor engineering support.
Pad-Mounted Transformer Market Segmentation
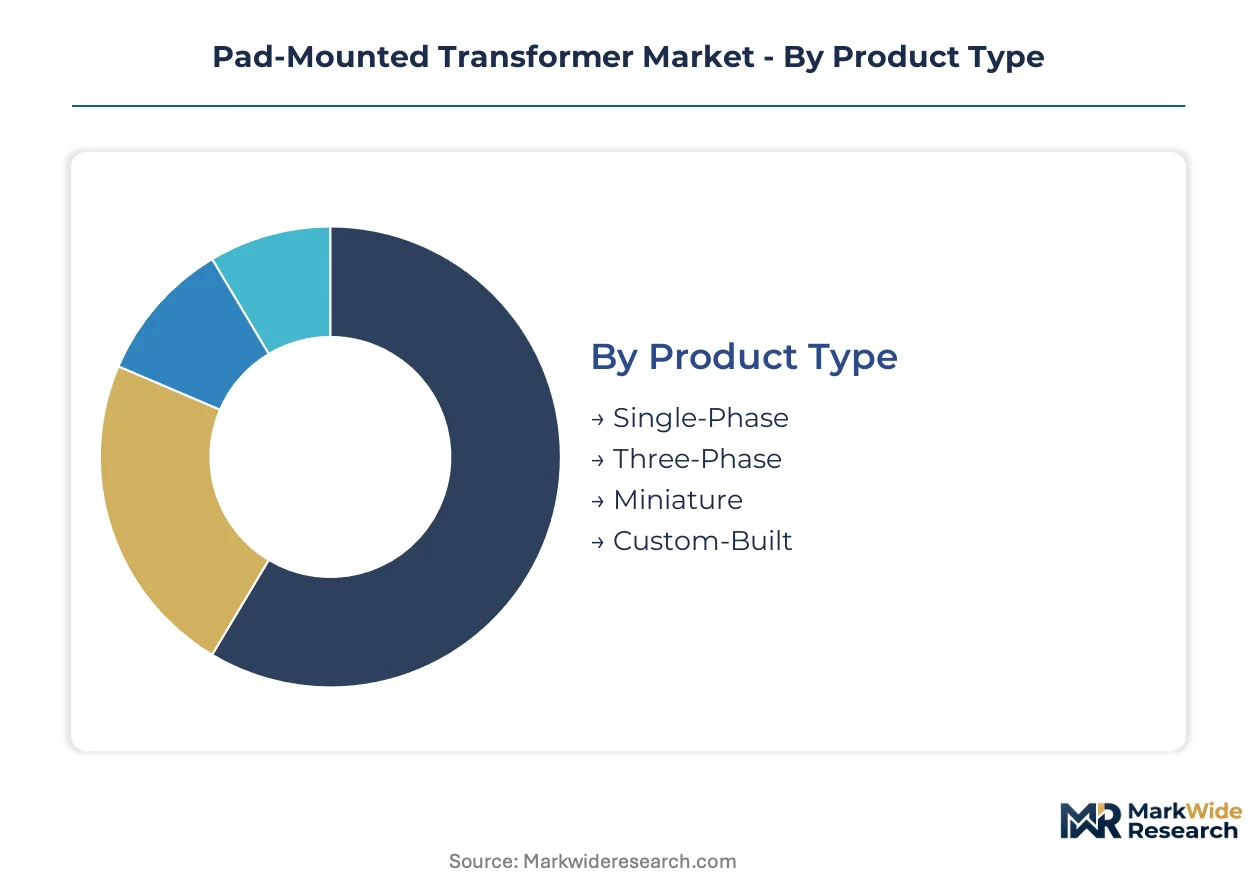
Pad-mounted transformer procurement patterns diverge sharply across installation environments and load requirements. IEEE dielectric standards and EPA containment rules create compliance tiers that reshape vendor selection within each segment.
Product Type:
Regulatory differentiation separates oil-immersed designs from ester-fluid alternatives under evolving fire-safety codes.
- Three-Phase:These units handle medium-voltage distribution for utility-scale deployments and data center campuses. Demand concentrates in Texas and Virginia utility zones where hyperscale facilities require 2,500 kVA+ configurations with non-standard impedance tolerances.
- Single-Phase:Designed for residential subdivision applications with ratings typically below 100 kVA. Procurement in United States utility territories prioritizes cost minimization over custom specifications, though NEMA TP-1 efficiency testing now filters supplier pools.
- Miniature:Compact enclosures serve space-constrained urban installations and renewable interconnection points.
- Custom-Built:Non-standard impedance characteristics address data center and solar farm projects requiring extended temperature rise ratings.
Three-Phase handles the majority of throughput; Custom-Built is the fastest mover on share.
Installation Type:
Cost tier separation emerges between buried infrastructure and surface-mounted alternatives due to excavation and containment expenses.
- Underground:Buried cable connections with integral containment basins dominate urban and campus environments. EPA SPCC spill-prevention documentation adds 8-14 weeks to commissioning schedules in flood-prone United States coastal zones.
- Above Ground:Surface pad installations with locked steel cabinets serve suburban and industrial parks. Lower installation costs sustain strong positions in Texas ERCOT territories where rapid deployment timelines outweigh aesthetic constraints.
- Hybrid:Mixed underground feed with above-ground termination accommodates retrofit scenarios.
- Pole-Mounted:Overhead line connections persist in rural distribution networks with limited underground infrastructure.
Underground commands premium pricing tiers; Above Ground maintains volume leadership across utility procurement cycles.
End User:
Customer type dictates specification authority, with direct manufacturer relationships replacing distributor channels for large-scale buyers.
- Utilities:Cooperative procurement agreements and engineering-direct specifications govern medium-voltage distribution investments. United States investor-owned utilities filter vendors through IEEE C57.12.00 insulation compliance and NEMA TP-1 efficiency certification.
- Commercial:Data center operators in Northern Virginia and Texas consolidate procurement around ester-fluid units with embedded dissolved-gas monitoring. Facility engineering teams now bypass electrical distributors for campus-scale deployments.
- Residential:Subdivision developers prioritize single-phase cost minimization over custom features.
- Industrial:Manufacturing facilities specify robust enclosures for heavy-load machinery connections.
Utilities anchor procurement volume; Commercial buyers are climbing the fastest on specification influence.
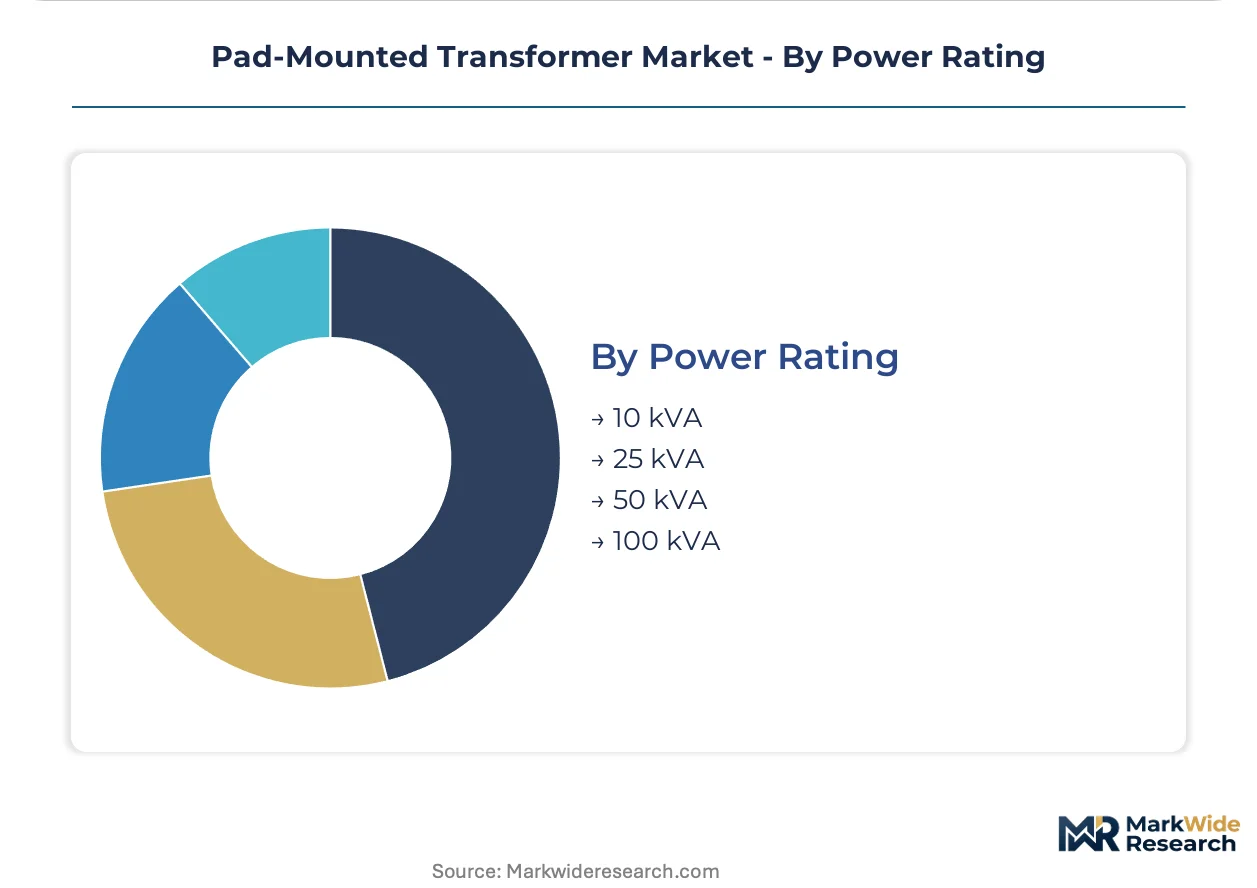
Power Rating:
Application scale determines thermal management requirements and coolant selection across the rating spectrum.
- 100 kVA:Largest standard rating serves commercial campuses and light industrial loads. United States data center operators specify these units with synthetic ester fluids to satisfy fire-safety codes restricting mineral oil.
- 50 kVA:Mid-range capacity dominates residential subdivision and small commercial deployments. Grain-oriented electrical steel pricing volatility compresses margins for assembly-focused suppliers lacking captive core processing.
- 25 kVA:Compact rating serves individual residential connections and remote equipment.
- 10 kVA:Smallest standard rating addresses isolated loads and temporary power applications.
100 kVA captures the steepest expansion trajectory; 50 kVA sustains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States utility zones where data center procurement commands premium specifications, while cost-sensitive residential markets in emerging economies compress margins for standardized units. Regional divergence reflects divergent regulatory stringency and infrastructure investment cycles.
United States
Hyperscale data center construction in Northern Virginia and Texas ERCOT territories drives demand for 2,500 kVA+ custom configurations with non-standard impedance tolerances. EPA spill prevention rules under the Clean Water Act mandate integral containment basins and leak-detection systems, extending commissioning timelines. Houston and Dallas utility zones anchor procurement volume for ester-fluid campus distribution units.
Germany
Industrial electrification and renewable integration projects sustain medium-voltage distribution investments across manufacturing belts. REACH compliance and EU Green Deal efficiency mandates reshape material specifications for liquid-immersed designs. The Ruhr industrial corridor and Bavarian manufacturing clusters concentrate procurement for robust enclosure specifications serving heavy-load machinery connections.
China
Grid modernization and urban underground cable infrastructure expansion drive three-phase unit deployment in coastal provinces. GB standards and MIIT efficiency regulations govern dielectric testing protocols for utility-scale installations. Yangtze River Delta cities including Shanghai and Suzhou prioritize compact miniature configurations for space-constrained substation retrofits.
India
Rural electrification and smart grid investments sustain single-phase procurement for residential subdivision applications. CEA technical standards and state-level solar interconnection codes mandate extended temperature rise ratings for renewable projects. Maharashtra and Gujarat industrial zones anchor demand for commercial-grade units serving manufacturing facility expansions.
Japan
Aging distribution infrastructure replacement and disaster-resilient grid investments drive precision-engineered unit procurement. METI efficiency regulations and JIS insulation standards filter supplier pools through rigorous certification requirements. Kanto and Kansai metropolitan areas concentrate demand for underground installations with advanced fire-safety specifications.
Pad-Mounted Transformer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the pad-mounted transformer supply base. The market structure consolidates around integrated manufacturers with captive core-steel processing and assembly-focused competitors dependent on external material sourcing. Three archetypes dominate: vertically integrated electrical equipment conglomerates, regional fabrication specialists, and utility-direct channel operators. Competitive dynamics center on M&A activity targeting ester-fluid technology capabilities and capacity expansion in high-growth United States utility zones.
Among integrated electrical equipment groups, ABB Ltd., Eaton Corporation Plc., and Siemens Energy AG occupy positions exemplifying divergent strategic emphases. ABB Ltd. represents the captive supply chain archetype with in-house core-steel and insulation system control. Eaton Corporation Plc. anchors the North American channel dominance model through utility-direct relationship structures. Siemens Energy AG exemplifies liquid-immersed design specialization for high-reliability urban installation segments.
| Leading Market Players |
|---|
| ABB Ltd. |
| Eaton Corporation Plc. |
| Schneider Electric |
| Siemens Energy AG |
| General Electric |
| Hitachi Energy |
| ERMCO |
| Toshiba Corporation |
| Howard Industries |
| Others |
Supply Flow & Price Mechanics
IEEE C57.12.00 insulation compliance gates both supplier qualification and price differentiation in pad-mounted transformer procurement, compressing margins for uncertified regional fabricators while validating premium positioning for integrated manufacturers with in-house testing capabilities.
Pricing Analysis
The customization-premium spread separates configured-to-order pricing from standard catalog pricing by 15-40% depending on impedance tolerance specifications and ester fluid formulation. Project-based contract pricing dominates utility-scale deployments, with price differentiation resting on NEMA TP-1 efficiency certification tier and embedded dissolved-gas monitoring capability. Cost compression in single-phase residential tiers is intensifying because grain-oriented electrical steel pricing volatility feeds through assembly-focused competitors lacking captive core processing. Data center operators in Northern Virginia and Texas ERCOT territories exhibit lowest price sensitivity, prioritizing fire-safety compliance and direct manufacturer engineering support over unit economics.
Supply Chain Analysis
Extended lead times for grain-oriented electrical steel and copper winding conductors now stretch 16-24 weeks, forcing manufacturers to pre-position inventory ahead of seasonal utility procurement cycles. Supply concentrates in United States, Germany, and China for core steel lamination and insulation system components. Raw material dependencies center on electrical-grade silicon steel, copper magnet wire, and natural ester seed-oil feedstocks. Single-source vulnerability in cold-rolled grain-oriented steel from integrated mills creates procurement risk during capacity allocation periods. Distribution runs through electrical distributor networks for residential and small commercial segments, while direct manufacturer-utility channel partnerships capture large-project specification authority in data center and renewable interconnection markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pad-mounted transformer demand sits in early-cycle expansion as EPA spill-prevention mandates and data center buildouts accelerate replacement of pre-2015 installed base with ester-fluid compliant designs.
For Market Incumbents: Consolidate ester-fluid technology capabilities through targeted acquisition of specialty fluid formulators and containment system engineering talent. Expand captive core-steel processing capacity in United States manufacturing corridors to defend margin structures against assembly-focused competitors exposed to raw material volatility. Deepen direct utility channel control through cooperative procurement agreements that bypass electrical distributors in Texas and Virginia data center zones.
For New Entrants and Emerging Players: Lead with digital monitoring integration as a differentiated value proposition, embedding dissolved-gas analysis sensors and thermal imaging ports to capture predictive maintenance contract premiums. Target renewable interconnection projects in state-level solar and wind farm codes mandating extended temperature rise ratings, where specification authority remains less concentrated among incumbent vendors. Pursue utility-direct technical collaboration rather than distributor-mediated market entry.
For Investors and Strategic Acquirers: EPA SPCC spill-prevention enforcement deadlines reshape the acquisition landscape toward manufacturers with pre-qualified containment basin designs and leak-detection system certifications. Long-term viability centers on backward integration into core-steel processing and ester-fluid formulation capabilities rather than pure assembly scale. Watch state-level interconnection standard adoptions as the signal for inflection in custom-built configuration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Ester Fluid Technology Acquisition | Captures EPA-compliant product positioning ahead of mineral oil displacement in fire-sensitive installations. |
| Direct Utility Channel Partnership | Bypasses electrical distributors to capture margin from specification-to-delivery workflows in data center zones. |
| Digital Monitoring Integration | Creates premium pricing tiers through embedded dissolved-gas sensors and predictive maintenance contracts. |
| Captive Core-Steel Processing Expansion | Insulates margin structures from grain-oriented electrical steel pricing volatility affecting assembly competitors. |
| Renewable Interconnection Certification | Qualifies custom-built designs for state-level solar and wind farm codes mandating extended temperature rise ratings. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, data center facility engineering directors, transformer OEM procurement managers, and EPC contractors; and secondary validation against IEEE standards documentation, EPA SPCC compliance filings, FERC interconnection dockets, and utility cooperative procurement records. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across power rating and installation type segments.
Across the projection horizon, the analytical framework modeled demand trajectories by product type, installation environment, end-user category, and power rating tier. CAGRs derived from regression analysis of historical procurement patterns against regulatory milestone timing and infrastructure investment cycles. Forecast inputs incorporated data center capex disclosures, utility capital expenditure plans, and state renewable interconnection queue data.
Underlying assumptions cover EPA enforcement timeline adherence and grain-oriented electrical steel supply stability, with deviation risk concentrated in tariff exposure for imported core materials and state-level regulatory adoption variance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
Contactors Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
United States Frequency Converter Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Porcelain Insulators Market