
 Global EMC Filtration Market | 2026-2036
Global EMC Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global EMC Filtration Market Analysis
East Asian contract manufacturers is decoupling from legacy European supply chains as regional capacitor and ferrite core capacity expands. TE Connectivity leverages vertical integration into ceramic substrate production to secure feedstock for high-frequency filter modules. Schaffner Holding AG anchors its position through Swiss precision manufacturing standards that command premium positioning in medical and rail applications. Delta Electronics competes aggressively on cost in the standard passive filter tier while extending R&D operations into Taiwan for next-generation PCB-integrated solutions.
EMC filtration encompasses passive, active, hybrid, and custom electromagnetic interference suppression devices engineered from ferrite ceramics, metalized films, and wound copper inductors to attenuate conducted and radiated noise across frequencies from kilohertz to gigahertz. These components protect signal integrity in densely packed electronic assemblies where clock speeds and switching frequencies generate parasitic emissions that corrupt data transmission or trigger regulatory failure. Passive filters still occupy the largest revenue pool given their ubiquity in consumer electronics and automotive power distribution, though hybrid filter architectures are gaining fastest as aerospace and telecommunications OEMs demand adaptive suppression across variable load conditions. PCB solutions concentrate margin in high-layer-count boards where embedded RC and LC networks eliminate discrete component counts while shrinking form factors for 5G infrastructure and satellite payloads.
FCC Part 15 emissions limits in the United States, CE marking requirements under the EU Electromagnetic Compatibility Directive, and China's GB/T 9254 standard collectively tighten product certification thresholds and expand mandatory testing scope for imported electronics. Japan's VCCI self-regulatory framework and South Korea's KC mark add further compliance layers that filter vendors must navigate for market access across major economies. Stakeholders should monitor evolving automotive EMC protocols from ISO 11451 and CISPR 25 as electric vehicle architectures introduce novel interference paths through high-voltage inverters and wireless charging coils.
Market Dynamics
Automotive electrification is compressing filter qualification cycles as OEMs race to meet CISPR 25 automotive EMC protocols before mass production of 800V architectures. This pressure cascades through ferrite core suppliers and PCB fabricators, forcing parallel rather than sequential certification paths.
Growth Catalysts
- China's GB/T 9254 standard:Mandatory electromagnetic compatibility testing for imported electronics expands filter attachment rates in consumer electronics assembly lines across Shenzhen and Dongguan manufacturing clusters.
- Electric vehicle powertrain integration:High-voltage inverters and wireless charging coils create novel conducted emission paths that demand hybrid filter architectures in battery electric vehicle platforms.
- East Asian PCB production concentration:Printed circuit board fabrication gravitating toward Taiwan and South Korea pulls embedded RC and LC network demand for 5G infrastructure and satellite payload applications.
Market Restraints
- Nickel-zinc ferrite raw material volatility:Mining concentration in Southeast Asia exposes filter manufacturers to price swings in magnetic oxide feedstocks that constitute 35-45% of passive component bill-of-materials.
- Swiss and German precision manufacturing lock-in:Medical device and rail signaling certifications require Schaffner-grade manufacturing tolerances that Asian contract manufacturers struggle to replicate without multi-year process transfers.
- Discrete component substitution:Integrated circuit designers at MediaTek and Qualcomm are absorbing EMI suppression into silicon, threatening standard passive filter volumes in mid-tier smartphones.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly create greenfield filter demand as Foxconn and Dixon Technologies expand Noida and Chennai facilities.
- Aerospace adaptive suppression:Variable load conditions in satellite power systems favor hybrid filter architectures that switch between passive and active attenuation modes based on orbital power cycling.
- Direct OEM procurement from filter specialists:Tier 1 automotive suppliers are bypassing distributor layers to negotiate multi-year ferrite core supply agreements with TE Connectivity and TDK for platform-level EMC compliance.
Industry Challenges
- ISO 11451-2 chamber calibration expertise:Automotive EMC test facilities face 18-month lead times for anechoic chamber certification engineers capable of validating whole-vehicle immunity to radiated disturbances.
- Legacy 12V filter inventory stranding:OEMs confront write-downs on passive filter stockpiles designed for internal combustion architectures that fail 800V isolation requirements in electric vehicle inverter compartments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EMC Filtration Market |
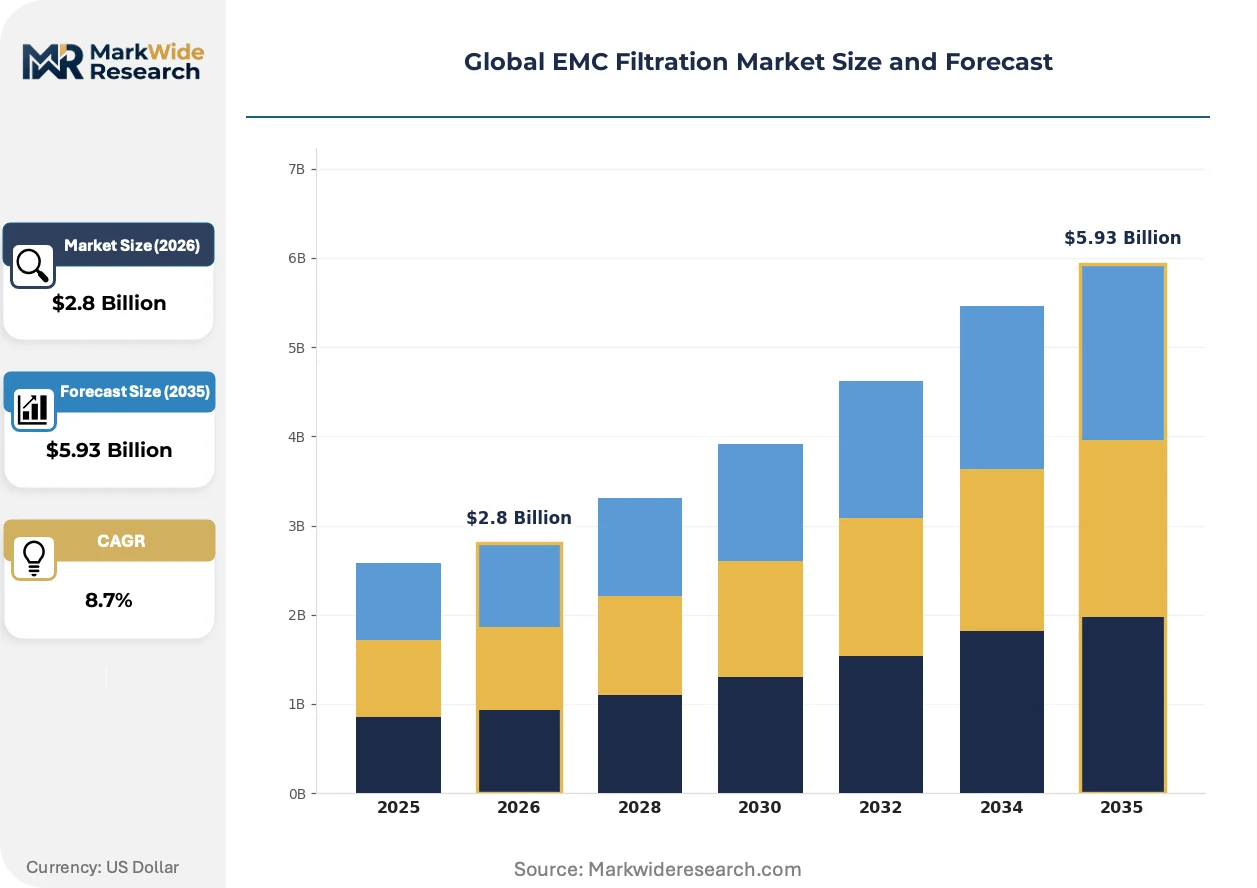
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Filters, Active Filters, Hybrid Filters, Custom Filters Technology: RC Network, LC Network, RLC Network, PCB Solutions End User: Consumer Electronics, Aerospace, Automotive, Telecommunications Application: Signal Integrity, Power Integrity, EMI Shielding, Grounding Solutions |
| Companies Covered | TE Connectivity, TDK Corporation, Delta Electronics, SCHURTER, Littelfuse, Astrodyne TDI, Schaffner Holding AG, ETS-Lindgren, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EMC Filtration Market Emerging Trajectories
Filter architectures are converging toward substrate-integrated solutions that eliminate discrete component placement. This compression demands simultaneous advances in materials science and PCB layer-stack engineering.
PCB-embedded LC networks are unifying discrete inductor and capacitor functions into copper-etched spiral structures within high-layer-count boards. Aerospace OEMs at SpaceX and OneWeb are qualifying these solutions for satellite payloads where component count directly impacts launch mass. The technology is unifying filter and interconnect functions, collapsing separate procurement categories into single-source board fabrication contracts.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing filter manufacturers to abandon SF6-based plasma etching in ceramic substrate production. German and Austrian ferrite processors are retrofitting production lines with nitrogen trifluoride alternatives that maintain via-hole precision for high-frequency modules. Medical device filter suppliers face the steepest compliance costs given Swissmedic requirements for process change documentation in implantable device supply chains.
Automotive Tier 1 buyers are consolidating filter specifications across platform generations to extract volume pricing from ferrite core vendors. Bosch and Continental are pushing single-source agreements that cover both 400V and 800V inverter architectures, compressing supplier margins while locking in capacity. This consolidation is most visible in Germany's Baden-Württemberg automotive cluster, where Schaffner and Würth Elektronik compete for platform-level EMC system design authority rather than component supply.
Global EMC Filtration Market Segmentation
EMC filtration architectures diverge sharply across voltage ratings, frequency domains, and integration depth. Procurement patterns track these technical boundaries, with upgrade cycles in automotive and aerospace forcing parallel qualification of multiple filter generations.
Product Type:
Replacement pressure from 800V automotive platforms and 5G infrastructure rollouts is compressing qualification timelines across all product categories.
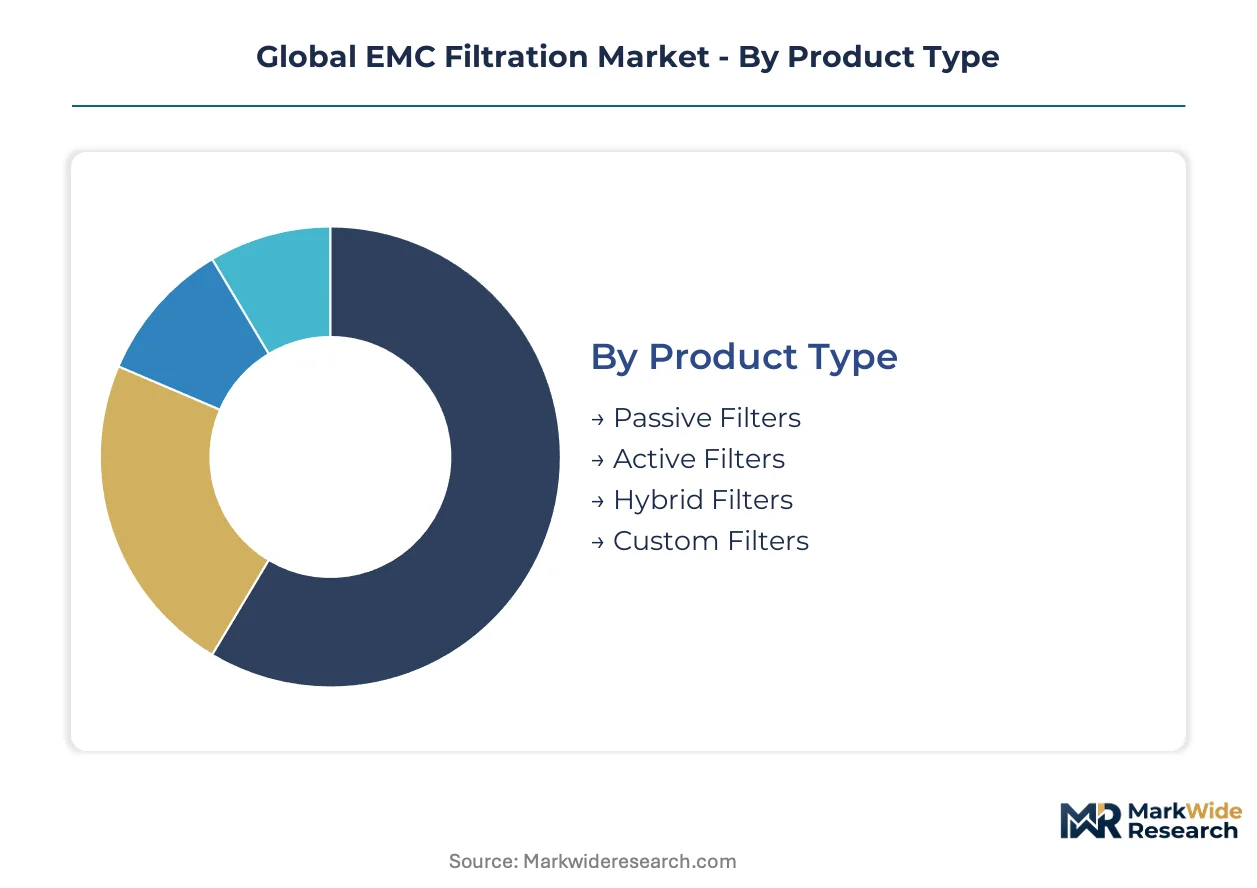
- Passive Filters:Ferrite core and wound copper inductor assemblies dominate consumer electronics and legacy automotive power distribution. China's GB/T 9254 testing mandates in Shenzhen and Dongguan assembly clusters sustain attachment rates in mid-tier smartphone and appliance manufacturing.
- Hybrid Filters:Architectures switching between passive and active attenuation modes address variable load conditions in battery electric vehicle inverters and satellite power systems. Aerospace OEMs at SpaceX and OneWeb prioritize these solutions for orbital applications where launch mass constraints penalize discrete component counts.
- Active Filters:Transistor-based suppression circuits with real-time noise cancellation deploy in high-precision medical imaging and semiconductor test equipment.
- Custom Filters:Application-specific designs for rail signaling and implantable medical devices command Swissmedic-grade process documentation premiums.
Passive filters sit at the top of the volume ranking, with hybrid filters climbing the fastest.
Technology:
Cost tier separation between discrete component and substrate-integrated approaches is widening as PCB layer counts increase.
- PCB Solutions:Embedded RC and LC networks fabricated within high-layer-count boards eliminate separate inductor and capacitor placement. Taiwan and South Korean fabricators capture margin from 5G base station and satellite payload contracts where component reduction directly reduces launch mass.
- LC Network:Copper-etched spiral structures with dielectric layers provide intermediate performance at moderate cost for industrial motor drives.
- RC Network:Resistor-capacitor combinations suppress high-frequency noise in audio equipment and low-power sensors.
- RLC Network:Combined resistor-inductor-capacitor stages address broadband interference in military communications hardware.
PCB solutions command the steepest pricing tier, with LC networks expanding most quickly in industrial applications.
End User:
Customer type fragmentation separates specification-intensive aerospace and medical buyers from price-sensitive consumer electronics procurement.
- Automotive:Electric vehicle powertrain integration demands hybrid architectures for 800V inverter compartments and wireless charging coils. Bosch and Continental negotiate multi-year ferrite core supply agreements covering both 400V and 800V platform generations.
- Aerospace:Satellite payloads and avionics systems require adaptive suppression under variable orbital power cycling. FCC Part 15 and EU Electromagnetic Compatibility Directive compliance layers add certification complexity for cross-border component sourcing.
- Consumer Electronics:High-volume smartphone and laptop assembly in East Asian manufacturing clusters drives standard passive filter procurement.
- Telecommunications:5G infrastructure deployment pulls embedded filter demand toward high-frequency PCB-integrated solutions.
Automotive procurement sits at the top of the volume ranking, with aerospace climbing the fastest on satellite constellation buildouts.
Application:
Margin concentration follows functional criticality, with signal integrity applications commanding premium positioning over commodity grounding.
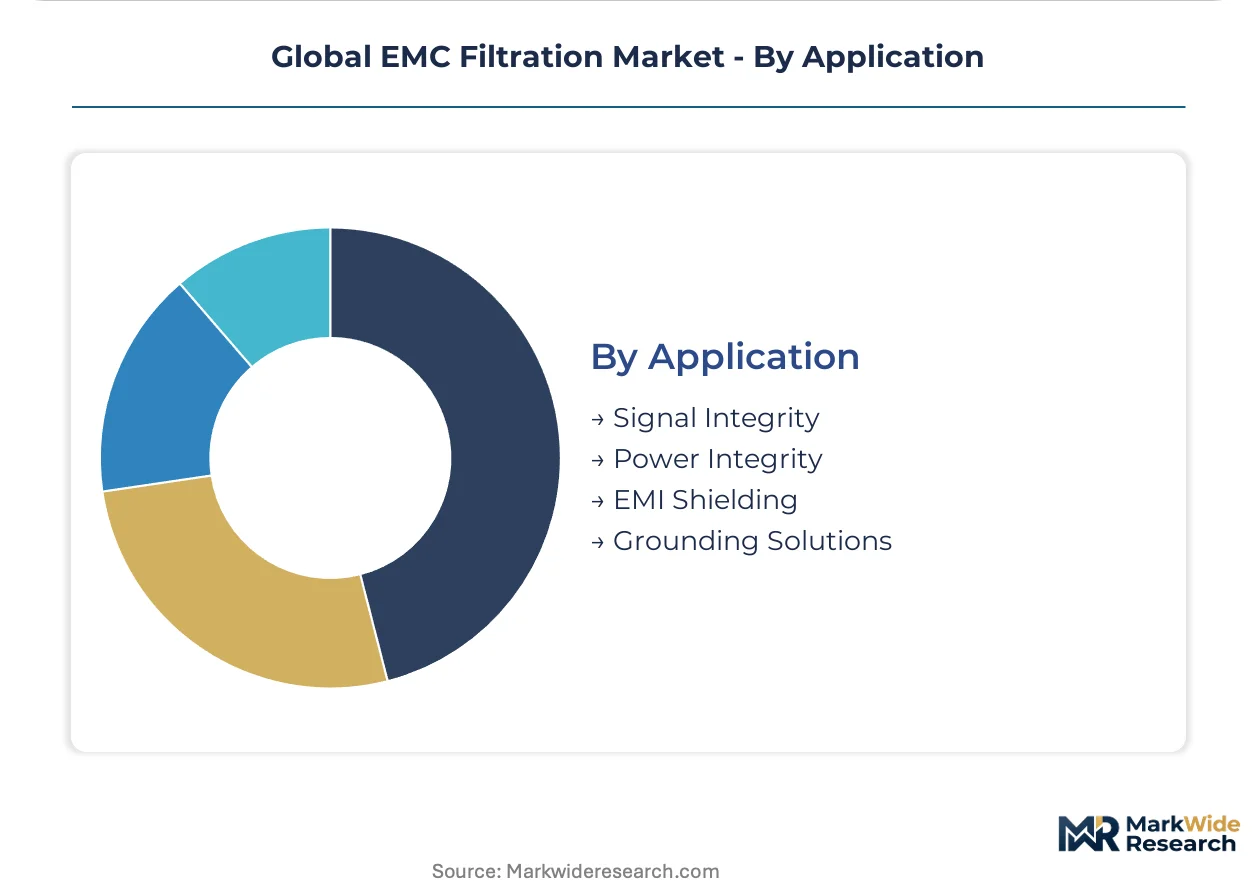
- Signal Integrity:High-speed data transmission protection in densely packed electronic assemblies requires precision-tuned filter stages. Clock speed increases in server processors and networking equipment generate parasitic emissions that corrupt bit error rate performance.
- EMI Shielding:Enclosure-level and board-level radiation containment addresses regulatory compliance for medical device and industrial automation exports.
- Power Integrity:Voltage rail stabilization in multi-phase CPU and GPU power delivery networks.
- Grounding Solutions:Reference plane noise reduction in cost-optimized consumer electronics.
Signal integrity sits at the top of the volume ranking, with EMI shielding climbing the fastest on medical device export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward jurisdictions with streamlined EMC certification pathways is reshaping manufacturing footprints. China's GB/T 9254 testing mandates impose cost-of-compliance burdens that Southeast Asian assemblers exploit. Switzerland and Germany retain premium-tier positioning through precision manufacturing standards that Asian contract manufacturers cannot readily replicate.
Germany
Automotive electrification programs in Baden-Württemberg and Bavaria accelerate filter deployment as OEMs confront stricter CISPR 25 protocols. The KBA enforces whole-vehicle EMC validation for 800V architectures entering European markets. Stuttgart's automotive cluster concentrates platform-level EMC system design authority between Schaffner and Würth Elektronik.
China
Shenzhen and Dongguan manufacturing clusters dominate procurement volumes for consumer electronics assembly. MIIT's GB/T 9254 standard mandates electromagnetic compatibility testing for imported electronics, expanding filter attachment rates. East Asian contract manufacturers decouple from legacy European supply chains as regional capacitor and ferrite core capacity expands.
United States
FCC Part 15 emissions limits tighten product certification thresholds for electronics entering American markets. The NHTSA coordinates with ISO working groups on automotive EMC protocols for electric vehicle architectures. California's technology corridor drives demand for high-frequency filter modules in satellite payload and 5G infrastructure applications.
Switzerland
Swissmedic requirements for process change documentation lock in premium positioning for medical device filter suppliers. The country's precision manufacturing standards command margins that Asian competitors struggle to match without multi-year process transfers. Schaffner Holding AG anchors its position through rail signaling and implantable device certifications.
Japan
METI oversees the VCCI self-regulatory framework that adds compliance layers for filter vendors seeking market access. Kanto and Kansai industrial corridors concentrate PCB fabrication and consumer electronics assembly. Domestic ferrite ceramic production supplies high-frequency modules for telecommunications and automotive applications.
Global EMC Filtration Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue substrate-integrated solutions that collapse discrete component categories. The vendor base stratifies across three archetypes: precision manufacturers commanding medical and rail premiums, scale-driven passive filter suppliers competing on cost, and vertically integrated specialists securing captive ceramic feedstock. Consolidation pressure intensifies as automotive Tier 1 buyers negotiate multi-year supply agreements covering multiple voltage platforms. Geographic expansion and technology licensing represent the dominant competitive moves as firms seek qualification in 800V automotive and 5G infrastructure segments.
Among Swiss and German precision manufacturers, Schaffner Holding AG exemplifies the premium-tier archetype anchored by medical device and rail signaling certifications. TE Connectivity represents the vertically integrated model through upstream control over ceramic substrate production. Delta Electronics occupies the scale-driven position competing aggressively in standard passive filters while extending development operations into Taiwan for PCB-integrated architectures.
| Leading Market Players |
|---|
| TE Connectivity |
| TDK Corporation |
| Delta Electronics |
| SCHURTER |
| Littelfuse |
| Astrodyne TDI |
| Schaffner Holding AG |
| ETS-Lindgren |
| Rohde & Schwarz |
| Others |
Supply Flow & Price Mechanics
Nickel-zinc ferrite raw material volatility cascades through the EMC filtration supply chain, compressing margins in standard passive filter tiers while amplifying pricing power for precision manufacturers with captive ceramic feedstock. Automotive Tier 1 buyers exploit this asymmetry to extract volume discounts across 400V and 800V platform generations.
Pricing Analysis
Distributor margin compression distinguishes procurement patterns across the EMC filtration landscape. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-certified medical device filters from commodity consumer electronics components. Price differentiation hinges on certification grade and volume scale, with Bosch and Continental leveraging platform consolidation to force cost compression in ferrite core supply agreements. Medical device OEMs exhibit lowest price sensitivity given Swissmedic process documentation requirements.
Supply Chain Analysis
Container freight rate fluctuations from Southeast Asian mining hubs to East Asian manufacturing clusters amplify working capital requirements for ferrite core processors. Supply concentrates in China, Japan, and Germany for ferrite ceramic production, with Taiwan and South Korea anchoring PCB-integrated filter fabrication. Raw material dependencies center on nickel-zinc ferrite oxides, wound copper inductors, and metalized film capacitors. Single-source vulnerability in Southeast Asian magnetic oxide mining exposes filter manufacturers to feedstock disruption. Distribution runs through authorized distributors for standard components and direct OEM negotiation for platform-level EMC systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMC filtration market functions as a regulatory compounder where successive emissions mandates from CISPR 25 and GB/T 9254 expand attach rates across automotive and consumer electronics assembly lines.
For Market Incumbents: Hedge against silicon-integrated EMI suppression by MediaTek and Qualcomm through backward integration into ceramic substrate production and certification investment in ISO 11451-2 chamber calibration capabilities. Secure multi-year ferrite core supply agreements with automotive OEMs before 800V platform standardization locks in supplier relationships. For New Entrants and Emerging Players: Capture greenfield demand from India's PLI scheme for electronics manufacturing as Foxconn and Dixon Technologies expand Noida and Chennai facilities. Aerospace adaptive suppression for satellite power systems offers the most penetrable white-space target given launch mass constraints and variable orbital load cycling. Pursue technology licensing partnerships with Taiwan-based PCB fabricators to bypass Swiss and German precision manufacturing lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive Tier 1 buyers negotiate single-source agreements covering multiple voltage platforms and regional capacitor capacity expands. Long-term viability favors vertically integrated specialists with captive ceramic feedstock and medical device certification heritage. Monitor ISO 11451-2 chamber calibration lead times as an inflection indicator for testing bottleneck severity and qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | TE Connectivity's upstream control over feedstock secures high-frequency module supply amid raw material volatility. |
| ISO 11451-2 Chamber Certification Investment | Automotive EMC test facilities with qualified engineers capture premium pricing from OEMs facing compressed qualification timelines. |
| PCB-Embedded Filter Technology Licensing | Taiwan-based fabricators license copper-etched spiral architectures to aerospace OEMs at SpaceX and OneWeb. |
| Platform-Level EMC System Design Authority | Schaffner and Würth Elektronik compete for Baden-Württemberg automotive cluster contracts beyond component supply. |
| Medical Device Process Documentation Investment | Swissmedic-grade certification premiums defend margins against Asian contract manufacturer cost competition. |
Methodological Framework
Direct dialogue with EMC filter procurement managers at automotive Tier 1 suppliers, ferrite core plant engineers in Germany and Japan, PCB fabrication technical directors in Taiwan, and medical device regulatory affairs specialists grounded qualitative findings. Secondary validation drew from FCC Part 15 filings, EU Electromagnetic Compatibility Directive implementation guidance, MIIT GB/T 9254 standard documentation, and SEC 10-K disclosures from listed component manufacturers. Bottom-up and top-down triangulation cross-checked attach rate assumptions against production volume databases.
Segmentation outputs across the analysis window reflect modeled splits by filter architecture, integration technology, end-user industry, and application function. CAGRs derived from regression analysis against automotive electrification program timelines and 5G infrastructure deployment schedules. Industry-specific forecast inputs incorporated CISPR 25 protocol adoption curves and GB/T 9254 testing mandate enforcement intensity across Shenzhen and Dongguan manufacturing clusters.
Raw material price swings, automotive platform standardization delays, and silicon-integrated EMI substitution are the dominant revision risks to projection assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
High Efficiency Low Voltage Aluminum Motors Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
North America Thermal Protector Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Passover Humidifiers Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Contactors Market