
 South America High Voltage Switchgear Market | 2026-2036
South America High Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
South America High Voltage Switchgear Market Insights
State utility procurement consolidation across Brazil and Chile is expanding as national grid operators centralize high voltage switchgear purchasing under unified transmission expansion programs. ABB Ltd leverages its manufacturing footprint in the region to anchor large-scale utility contracts, while Siemens AG competes through localized assembly operations that reduce import dependency. Hitachi Energy Ltd specializes in digital switchgear integration for utility automation, differentiating its portfolio from conventional equipment suppliers.
South America high voltage switchgear encompasses electrical apparatus rated above 36 kV designed to control, protect, and isolate power circuits in transmission and generation networks, typically employing sulfur hexafluoride or vacuum interruption mediums within metal-enclosed assemblies. These systems function as critical nodes in bulk power transfer, ensuring fault containment and operational continuity across interconnected grids. Circuit breakers command the dominant share of product type revenues due to their essential protective function in transmission infrastructure, while gas-insulated switchgear technology captures expanding share in coastal and metropolitan installations where footprint constraints and environmental exposure limit air-insulated alternatives. Renewable energy end users represent the fastest-growing demand segment as wind and solar projects in Argentina's Patagonia and Brazil's northeast require grid connection switchgear with enhanced switching capability.
ANEEL in Brazil and Argentina's ENRE enforce grid reliability standards that mandate switchgear certification for interconnected transmission assets, directly conditioning market access for equipment suppliers. IEC 62271 series standards govern product design and testing protocols across South American markets, with local metrology institutes adapting these frameworks for regional voltage and climate conditions. Stakeholders must monitor regulatory harmonization progress between Mercosur members and assess how evolving decarbonization commitments reshape utility capital allocation toward switchgear with lower lifecycle environmental impact.
Market Dynamics
ANEEL's grid modernization mandates in Brazil are concentrating transmission investment toward gas-insulated switchgear in dense urban corridors, while state utility procurement consolidation across the continent compresses supplier margins and rewards localized manufacturing footprints.
Growth Catalysts
- ANEEL regulatory mandates:Brazil's national electric energy regulator enforces grid reliability standards that require certified high voltage switchgear for all interconnected transmission assets, creating guaranteed demand for compliant equipment suppliers.
- Patagonia wind integration:Argentina's southern region hosts expanding wind generation capacity that requires enhanced switching capability and specialized grid connection infrastructure.
- Gas-insulated technology:Space-constrained metropolitan substations in São Paulo and Rio de Janeiro are driving specification shifts toward compact SF6-insulated assemblies that reduce footprint by over 70% versus air-insulated alternatives.
Market Restraints
- SF6 environmental scrutiny:Sulfur hexafluoride faces mounting regulatory pressure under EU F-Gas Regulation analogs being considered by Mercosur members, threatening the dominant interruption medium's long-term viability.
- Import dependency concentration:Specialized cast resin bushings and epoxy insulators rely heavily on Asian suppliers, exposing Brazilian and Chilean utilities to currency volatility and extended lead times.
- Technical limitation in altitude derating:Standard 145 kV equipment requires significant capacity reduction above 3,000 meters, complicating deployment in Bolivia's Altiplano and Peru's central mining regions.
Strategic Opportunities
- Ecuador transmission expansion:The country's underdeveloped 230 kV backbone presents white space for turnkey substation contractors as the national utility accelerates rural electrification and mining corridor connections.
- Digital switchgear convergence:Integration of IEC 61850-compliant intelligent electronic devices with conventional interruption chambers enables predictive maintenance and asset management revenue streams.
- Peru renewable auction pipeline:The Ministry of Energy and Mines' competitive renewable energy auctions mandate grid connection infrastructure, creating bundled procurement opportunities for switchgear-plus-substation packages.
Industry Challenges
- Specialized commissioning engineer scarcity:Gas-insulated switchgear installation requires certified technicians proficient in SF6 handling and gas quality testing, with training pipelines failing to match deployment timelines in Brazil's northeast.
- IEC 62271 certification timeline compression:Type testing at INMETRO-accredited laboratories extends 14-18 months for new product variants, delaying market entry for refreshed equipment portfolios.
- Legacy air-insulated integration complexity:Hybrid substation designs combining existing AIS bays with new GIS extensions create interface engineering challenges and warranty boundary disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America High Voltage Switchgear Market |
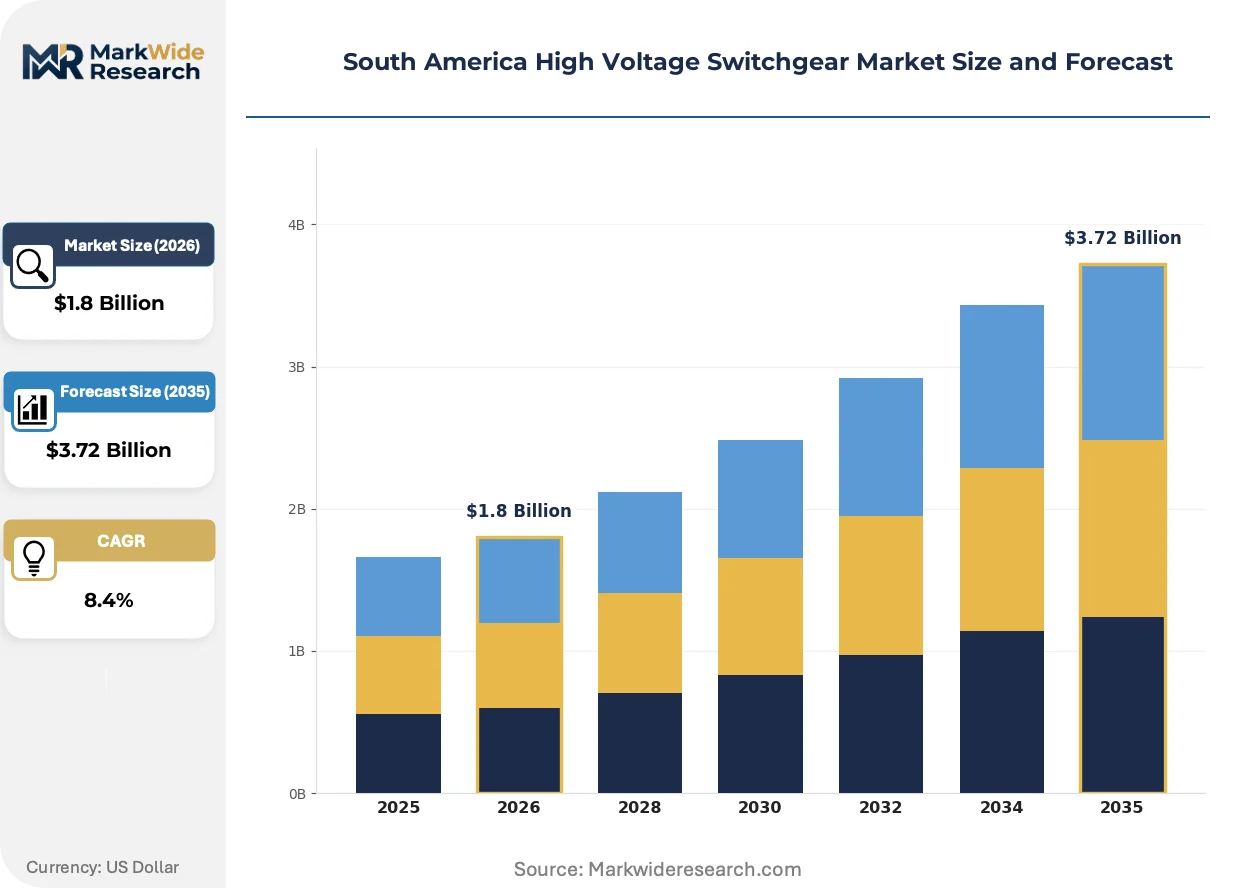
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Disconnectors, Switches, Relay Panels End User: Utilities, Industrial, Commercial, Renewable Energy Technology: Gas-Insulated Switchgear, Air-Insulated Switchgear, Hybrid Switchgear, Solid Insulated Switchgear Application: Power Generation, Transmission, Distribution, Automation |
| Companies Covered | ABB Ltd, Schneider Electric SE, General Electric Company, Siemens AG, Mitsubishi Electric Corporation, Toshiba International Corporation, GE Vernova, Hitachi Energy Ltd, Eaton Corporation plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America High Voltage Switchgear Market Trends and Innovations
Digitalization of switchgear assets is converging with environmental pressure on SF6 to reshape product roadmaps across South American utilities, while procurement centralization favors suppliers capable of integrated hardware-software-service delivery.
Vacuum interruption technology for 145 kV applications is absorbing development investment previously directed toward SF6 alternatives, with Brazilian utilities specifying hybrid modules that combine vacuum bottles with compact GIS enclosures. Eletrobras distribution subsidiaries are piloting these configurations in coastal substations exposed to salt contamination. This technology trajectory is absorbing market share from conventional dead-tank circuit breakers in the 72.5-145 kV range.
Mercosur regulatory harmonization initiatives are converging Brazilian INMETRO certification requirements with Argentine IRAM standards, reducing duplicate testing burdens for equipment suppliers operating across both markets. Chile's SEC has signaled alignment with this framework, creating a pathway toward unified South American type approval. Transmission operators in the Southern Cone are responding by consolidating specifications under IEC 62271-200 for metal-enclosed switchgear.
Utility procurement departments are unbundling after-sales service contracts from initial equipment supply, creating discrete revenue pools for specialized maintenance providers. Brazilian state operators are leading this shift, separating 10-year parts availability guarantees from commissioning and diagnostic services. This pattern is most visible in southeastern Brazil's industrial corridor, where large industrial consumers with captive substations are adopting similar contract structures.
South America High Voltage Switchgear Market Segmentation
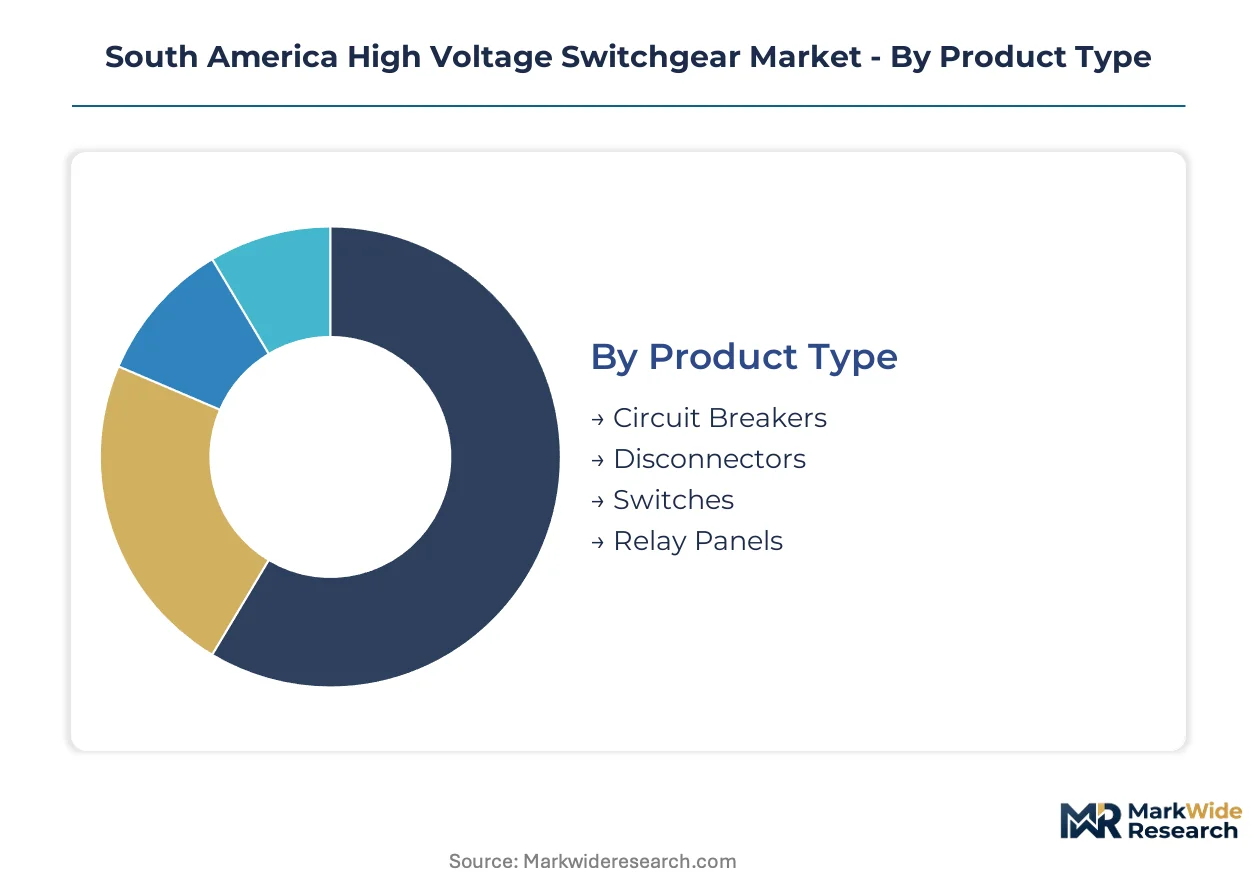
High voltage switchgear procurement across South America fragments along four critical dimensions. Product type determines capital allocation intensity, while technology choice reflects spatial constraints and environmental exposure. End user profiles dictate maintenance regimes and lifecycle cost structures.
Product Type:
Volume equipment dominates procurement budgets, yet premium protective devices command disproportionate engineering attention from transmission planners.
- Circuit Breakers:These protective devices interrupt fault currents through SF6 or vacuum arc quenching mechanisms rated above 36 kV. Brazilian state utilities in the southeastern industrial corridor specify dead-tank configurations for 145 kV substations, driven by ANEEL reliability mandates and coastal salt contamination exposure.
- Disconnectors:Mechanical switching devices isolate circuit sections under no-load conditions, employing rotating blade or pantograph mechanisms. Argentina's Patagonia wind farms require motorized three-column designs for remote operation, responding to ENRE grid connection standards and extreme wind loading.
- Switches:Load-break devices combine switching capability with limited fault protection in compact assemblies.
- Relay Panels:Protection and control enclosures house microprocessor-based intelligent electronic devices for utility automation.
Mature deployment sits with circuit breakers. Newer deployment is concentrated in relay panels.
End User:
Customer concentration patterns split between centralized state procurement and distributed industrial captive generation.
- Utilities:State-owned transmission operators across Brazil, Argentina, and Chile drive bulk procurement through unified expansion programs. Eletrobras subsidiaries consolidate switchgear purchasing for 230 kV backbone extensions, responding to ANEEL grid modernization timelines and renewable integration targets.
- Renewable Energy:Wind and solar developers require specialized grid connection switchgear with enhanced switching cycles. Brazil's northeast solar parks and Argentina's Patagonia wind clusters specify equipment with altitude derating compensation and rapid fault clearance capability.
- Industrial:Mining and metals processors operate captive substations with high reliability requirements.
- Commercial:Large commercial complexes in São Paulo and Santiago deploy compact urban substations.
Established procurement patterns sit with utilities. Expanding most quickly is renewable energy.
Technology:
Insulation medium selection trades footprint efficiency against environmental compliance trajectory.
- Gas-Insulated Switchgear:SF6-insulated assemblies compress equipment volume by over 70% versus air-insulated alternatives through sealed metal enclosures. São Paulo and Rio de Janeiro metropolitan substations specify 145 kV GIS for space-constrained sites, driven by urban land scarcity and ANEEL reliability certification requirements.
- Air-Insulated Switchgear:Open-air busbar and breaker arrangements dominate rural transmission substations with available land.
- Hybrid Switchgear:Configurations combine AIS cost structures with GIS compactness for selective applications.
- Solid Insulated Switchgear:Cast resin insulation eliminates SF6 dependency for environmental compliance positioning.
Conventional deployment sits with air-insulated switchgear. Climbing the fastest is gas-insulated switchgear.
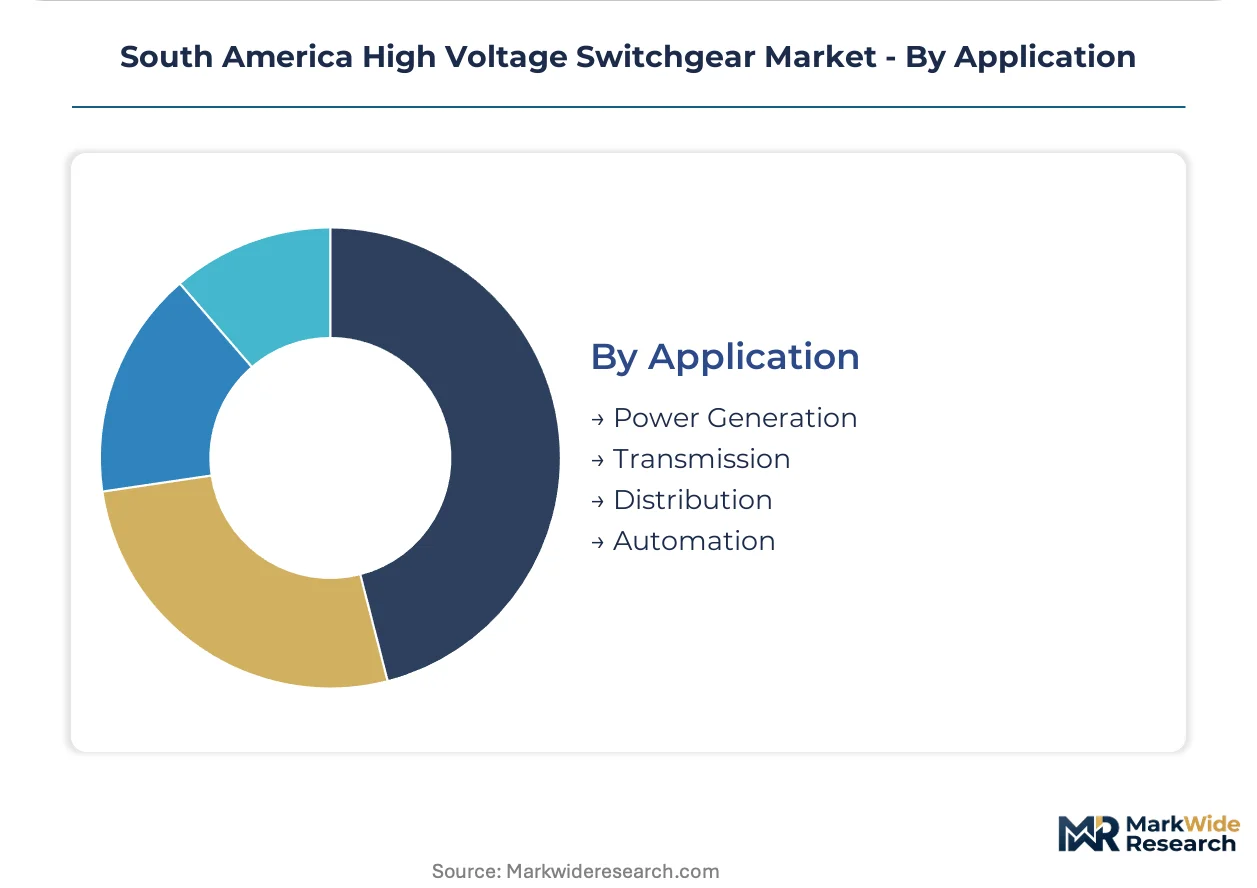
Application:
Functional deployment spans generation connection through grid automation hierarchy.
- Transmission:Bulk power transfer infrastructure employs 230 kV and 145 kV switchgear for interconnection and sectionalizing. Chile's SEC-regulated transmission operators specify metal-enclosed assemblies for the central valley backbone, responding to renewable auction connection deadlines and seismic loading requirements.
- Power Generation:Generation switchgear manages unit connection and synchronization for thermal and renewable plants.
- Distribution:Sub-transmission and primary distribution networks deploy lower-voltage switchgear for load center supply.
- Automation:Digital switchgear integration enables remote monitoring and predictive maintenance protocols.
Legacy investment sits with transmission. Gaining share fastest is automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission infrastructure investment concentrates in Brazil's southeastern industrial corridor, where ANEEL grid modernization mandates and renewable integration timelines are compressing procurement cycles. State utility consolidation across the continent is reshaping supplier access patterns.
Brazil
Eletrobras subsidiaries anchor regional demand through unified 230 kV backbone expansion programs. ANEEL reliability certification requirements mandate certified high voltage switchgear for all interconnected transmission assets, creating guaranteed procurement channels. São Paulo and Rio de Janeiro metropolitan substations specify gas-insulated technology for space-constrained urban sites.
Argentina
Patagonia wind generation clusters require specialized grid connection switchgear with enhanced switching capability and altitude compensation. ENRE grid connection standards enforce technical specifications for remote renewable projects. Buenos Aires province transmission operators are consolidating specifications under unified procurement frameworks.
Chile
Central valley backbone extensions respond to renewable auction connection deadlines and seismic loading requirements. SEC-regulated transmission operators specify metal-enclosed switchgear assemblies for bulk power transfer infrastructure. Mining corridor electrification in the northern regions drives 145 kV substation deployment.
Peru
Ministry of Energy and Mines competitive renewable energy auctions mandate bundled grid connection infrastructure procurement. Central mining regions above 3,000 meters face equipment derating challenges for standard 145 kV switchgear. Lima metropolitan distribution utilities are piloting digital switchgear integration for predictive maintenance protocols.
Colombia
Andean backbone reinforcement programs address hydroelectric integration and cross-border interconnection capacity. National utility transmission expansion targets remote renewable zones in the eastern plains. Bogotá metropolitan substations are evaluating gas-insulated alternatives for footprint-constrained urban sites.
South America High Voltage Switchgear Market Competitive Landscape
European producers anchor one tier through established manufacturing footprints; Asian specialists hold position via component supply integration and technology licensing arrangements. The vendor structure concentrates around integrated electrical equipment conglomerates with regional assembly operations. Three archetypes dominate: full-system integrators with turnkey substation capability, component specialists focused on interruption chambers and insulation systems, and digital technology providers bundling hardware with utility automation platforms. Competitive maneuvering centers on localized manufacturing investments and service contract unbundling.
Within the full-system integrator tier, ABB Ltd and Siemens AG exemplify positioning through regional manufacturing presence and utility relationship depth. Hitachi Energy Ltd occupies a position bridging conventional equipment supply with digital switchgear convergence. These three anchors represent the competitive spectrum from hardware-centric to integrated hardware-software-service delivery models.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| General Electric Company |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Toshiba International Corporation |
| GE Vernova |
| Hitachi Energy Ltd |
| Eaton Corporation plc |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of SF6 gas handling equipment and vacuum interruption chambers anchors pricing power for integrated manufacturers serving ANEEL-certified utility contracts, while outsourced assembly of relay panels and digital control systems compresses margins for component-dependent suppliers competing on standard specifications.
Pricing Analysis
Volume equipment versus premium protective devices splits the pricing architecture, with dead-tank circuit breakers and gas-insulated switchgear assemblies commanding project-based long-term contract structures tied to ANEEL certification tiers and seismic loading specifications. Price differentiation rests on IEC 62271 testing grade and localized manufacturing footprint, with Brazilian utilities least sensitive to upfront capital cost when bundled with 10-year service guarantees. Cost compression in standard air-insulated switchgear intensifies as Asian component suppliers expand direct sales to Chilean and Peruvian transmission operators.
Supply Chain Analysis
Single-source vulnerability sits with specialized cast resin bushings and epoxy insulators drawn from Chinese and South Korean manufacturers, exposing Brazilian utilities to currency volatility and extended procurement cycles. Raw material dependencies center on sulfur hexafluoride gas, copper conductor bar, and vacuum interrupter ceramics. Regulatory restriction risk looms as Mercosur members consider EU F-Gas Regulation analogs targeting SF6 phase-down. Distribution runs through EPC contractors and turnkey substation integrators rather than direct utility sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum interruption technology for 145 kV applications is displacing SF6-dependent switchgear across Brazilian coastal substations, compressing the window for legacy equipment suppliers to transition product roadmaps before regulatory mandates harden.
For Market Incumbents: Deepen backward integration into vacuum interrupter ceramic production and SF6 gas reclamation services to defend margin position against emerging Asian component specialists. Prioritize INMETRO certification investment for hybrid GIS-AIS configurations to lock in Eletrobras backbone expansion contracts before IEC 62271-200 harmonization accelerates competitive entry. For New Entrants and Emerging Players: Digital switchgear convergence with IEC 61850-compliant intelligent electronic devices offers the most penetrable wedge into Brazilian state utility procurement, where predictive maintenance capabilities remain underspecified in current tenders. Target Peru's renewable auction pipeline with bundled switchgear-plus-substation packages, leveraging altitude-derating engineering partnerships with established GIS specialists to bypass 14-18 month type testing timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap component specialists with captive vacuum interruption chamber technology and Mercosur regulatory approval depth. Long-term viability favors suppliers with demonstrated SF6 alternative roadmaps and service contract unbundling capabilities. Watch for ANEEL mandates accelerating beyond current grid modernization timelines as the inflection signal for accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| SF6 Alternative Technology Roadmap | Vacuum interruption development absorbs investment previously directed toward gas-insulated alternatives in ANEEL-regulated corridors. |
| INMETRO Certification Acceleration | Reduced type testing timelines through Mercosur harmonization unlocks faster market entry for refreshed equipment portfolios. |
| Service Contract Unbundling | Discrete revenue pools for predictive maintenance and diagnostic services separate from 10-year parts availability guarantees. |
| Altitude-Derating Engineering Partnership | Specialized capability for 3,000-meter-plus deployments addresses Bolivia and Peru mining corridor requirements. |
| Digital Switchgear Platform Integration | IEC 61850 compliance enables utility automation revenue streams beyond conventional hardware supply margins. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with utility planning officers, EPC contractors, switchgear commissioning engineers, and aftermarket service heads across Brazil, Argentina, and Chile. ANEEL reliability certification databases, INMETRO type approval registries, SEC transmission expansion filings, and import-export documentation provided demand-side validation. Bottom-up equipment procurement tracking triangulated against top-down transmission investment forecasts from national grid operators.
Segment-level granularity modeled product type, technology choice, end user category, and application function across the projection horizon, with voltage class and regional regulatory cluster as additional industry-specific dimensions. CAGRs derived from utility capital expenditure pipeline analysis and renewable auction connection timelines. Forecast inputs incorporated ANEEL grid modernization mandate progression, Mercosur regulatory harmonization trajectory, and SF6 alternative technology adoption curves.
Several conditions sit outside the modeled scope, including sudden currency devaluation episodes, expropriation risk in specific jurisdictions, and breakthrough solid-insulation technologies displacing vacuum interruption before commercial scale. Forecasts reflect documented assumptions about regulatory enforcement consistency and utility procurement centralization pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Modular Contactor Market
Electrical Equipment
Asia-Pacific Circuit Breakers Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
Flexible Heating Element Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Motor Control Centers (MMC) Market
Electrical Equipment
Global Busbar Market