
 Electrical Resistor Market | 2026-2036
Electrical Resistor Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Resistor Market Analysis
Authorized distributor networks is reshaping how electrical resistor manufacturers reach automotive and industrial buyers. Vishay Intertechnology leverages its broad thin-film portfolio to sustain design-win relationships across North American aerospace and defense programs. Yageo Corporation anchors Asia-Pacific supply through massive thick-film capacity and direct OEM contracts with consumer electronics brands. Rohm Co., Ltd. differentiates via SiC-adjacent resistor technologies that support next-generation power electronics.
An electrical resistor is a passive electronic component that limits current flow, divides voltages, and dissipates energy as heat, typically manufactured from carbon composition, metal oxide, or resistive wire wound around ceramic cores and rated by tolerance, temperature coefficient, and power dissipation measured in watts. Fixed resistors dominate volume shipments across consumer electronics and automotive modules where cost minimization governs procurement. Thick-film technology leads in unit economics for high-volume surface-mount applications, while wirewound construction occupies premium niches requiring thermal stability in industrial motor drives and power conversion equipment. Precision resistors with tight tolerance bands capture disproportionate margin pools in instrumentation and medical signal-conditioning chains.
REACH and RoHS frameworks in Europe restrict hazardous substances in resistor substrates and termination plating, compelling reformulation of traditional thick-film paste chemistries. China's GB standards and MIIT efficiency mandates enforce stricter power-dissipation ratings on components entering domestic industrial equipment and new-energy vehicle supply chains. The US EPA and OSHA jointly influence manufacturing site compliance for resistor factories serving military and automotive qualification programs. Buyers must monitor evolving substance restrictions and thermal-performance benchmarks as regulators tighten linkages between component-level specifications and system-level energy efficiency certifications.
Market Dynamics
Automotive electrification is compressing design cycles and tightening thermal-performance specifications across resistor supply chains. Battery management systems and powertrain inverters now demand components that withstand higher operating temperatures while maintaining precision under electrical stress.
Growth Catalysts
- MIIT efficiency mandates:China's Ministry of Industry and Information Technology enforces stricter power-dissipation ratings on components entering new-energy vehicle supply chains, forcing upgrades across domestic manufacturing.
- Thick-film surface-mount technology:High-volume consumer electronics and automotive module production favors thick-film resistors for unit economics and automated assembly compatibility.
- East Asian manufacturing concentration:South Korean and Japanese production clusters anchor regional supply with integrated ceramic substrate and termination plating capabilities.
Market Restraints
- Palladium and ruthenium price volatility:Thick-film paste formulations depend on precious metal conductors, creating input cost instability that compresses margins during commodity spikes.
- Single-source ceramic powder suppliers:High-purity alumina substrate supply concentrates among Japanese specialty chemical producers, exposing buyers to geographic concentration risk.
- Wirewound thermal mass limitations:Ceramic core construction and resistive wire winding impose physical size constraints that exclude the technology from miniaturized portable electronics.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly create greenfield capacity opportunities outside established East Asian supply nodes.
- SiC-adjacent resistor integration:Silicon carbide power electronics operating at higher frequencies and temperatures require matched resistor technologies with expanded thermal envelopes.
- Authorized distributor channel expansion:Direct design-win relationships through technical distributors bypass traditional tiered supply chains for mid-volume industrial and medical buyers.
Industry Challenges
- RoHS substance reformulation timelines:European Chemicals Agency restrictions on hazardous substances in termination plating force multi-year qualification cycles that delay product releases.
- Temperature coefficient calibration expertise:Precision resistor manufacturing requires specialized thin-film deposition technicians and metrology skills in short supply across expanding production bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Resistor Market |
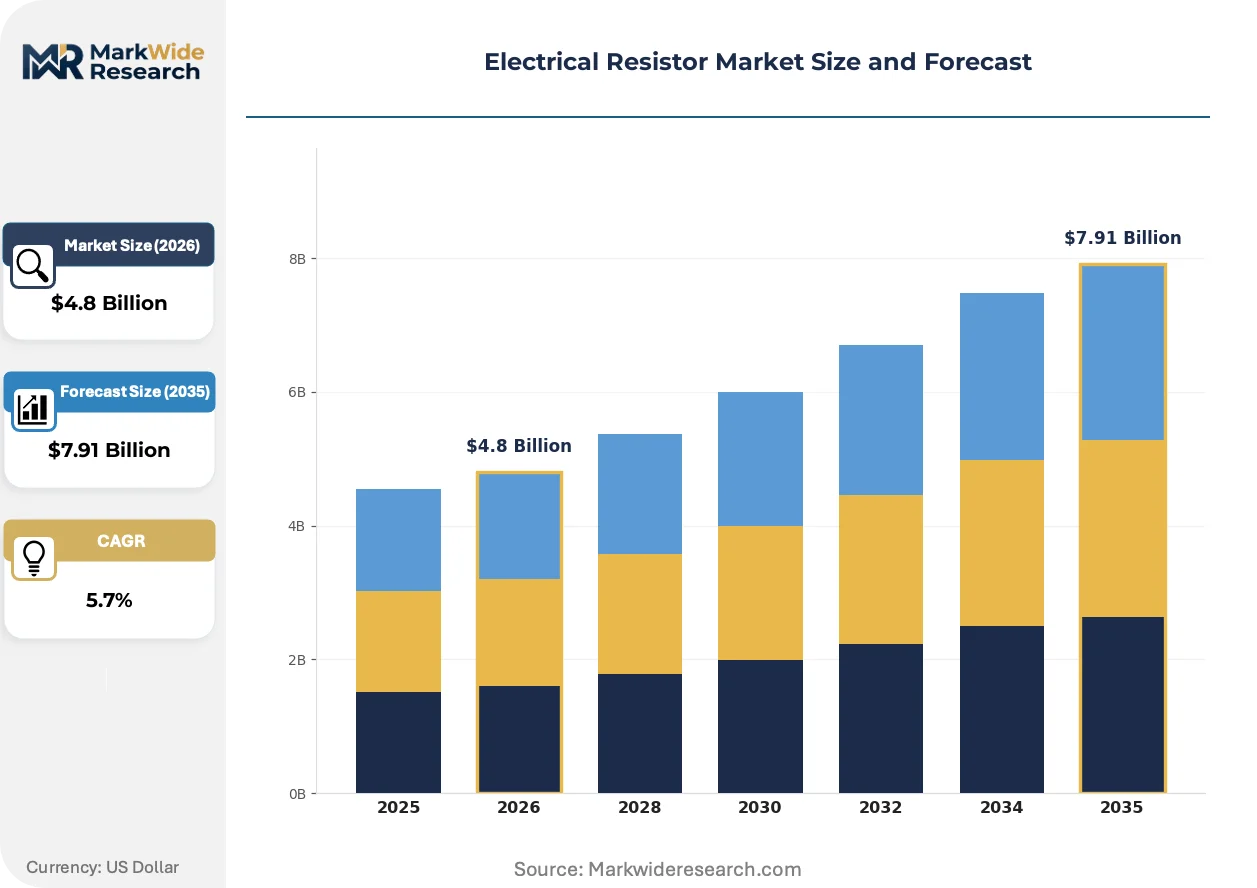
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Resistors, Variable Resistors, Instrumentation Resistors, Precision Resistors Technology: Thin Film, Thick Film, Wirewound, Carbon Composition End User: Consumer Electronics, Automotive Industry, Industrial Equipment, Telecommunications Application: Voltage Dividers, Current Limiting, Signal Conditioning, Filtering |
| Companies Covered | Panasonic Corporation, Rohm Co., Ltd., Yageo Corporation, KOA Corporation, TE Connectivity, Vishay Intertechnology, Samsung Electro-Mechanics, Bourns, Inc., Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Resistor Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are forcing simultaneous performance upgrades and formulation changes. Manufacturers must balance thermal stability gains against compliance-driven paste substitutions.
Metal nitride thin-film deposition is rendering obsolete traditional nickel-chromium alloy resistors in precision instrumentation. Medical device manufacturers and aerospace signal-conditioning chains adopt tantalum nitride and silicon chromium systems for improved long-term stability and moisture resistance. The shift compresses addressable market share for legacy metal foil construction in sub-50 ppm applications.
REACH substance restrictions and RoHS amendments from the European Chemicals Agency prohibit cadmium and lead in termination plating and substrate binders. Resistor manufacturers reformulate thick-film pastes with bismuth-based glass frits and silver-palladium alloys that maintain solderability without restricted elements. European automotive and industrial equipment suppliers now require full material disclosure documentation upstream from component qualification.
Consolidated procurement through technical distributors is fragmenting traditional tiered supply relationships. Mid-size automotive tier-1 suppliers and industrial OEMs now source directly from authorized distributors with in-house application engineering rather than through multi-layer trading companies. The pattern concentrates design-win influence among distributors with regional stocking points in Germany, Texas, and Guangdong province.
Electrical Resistor Market Segmentation
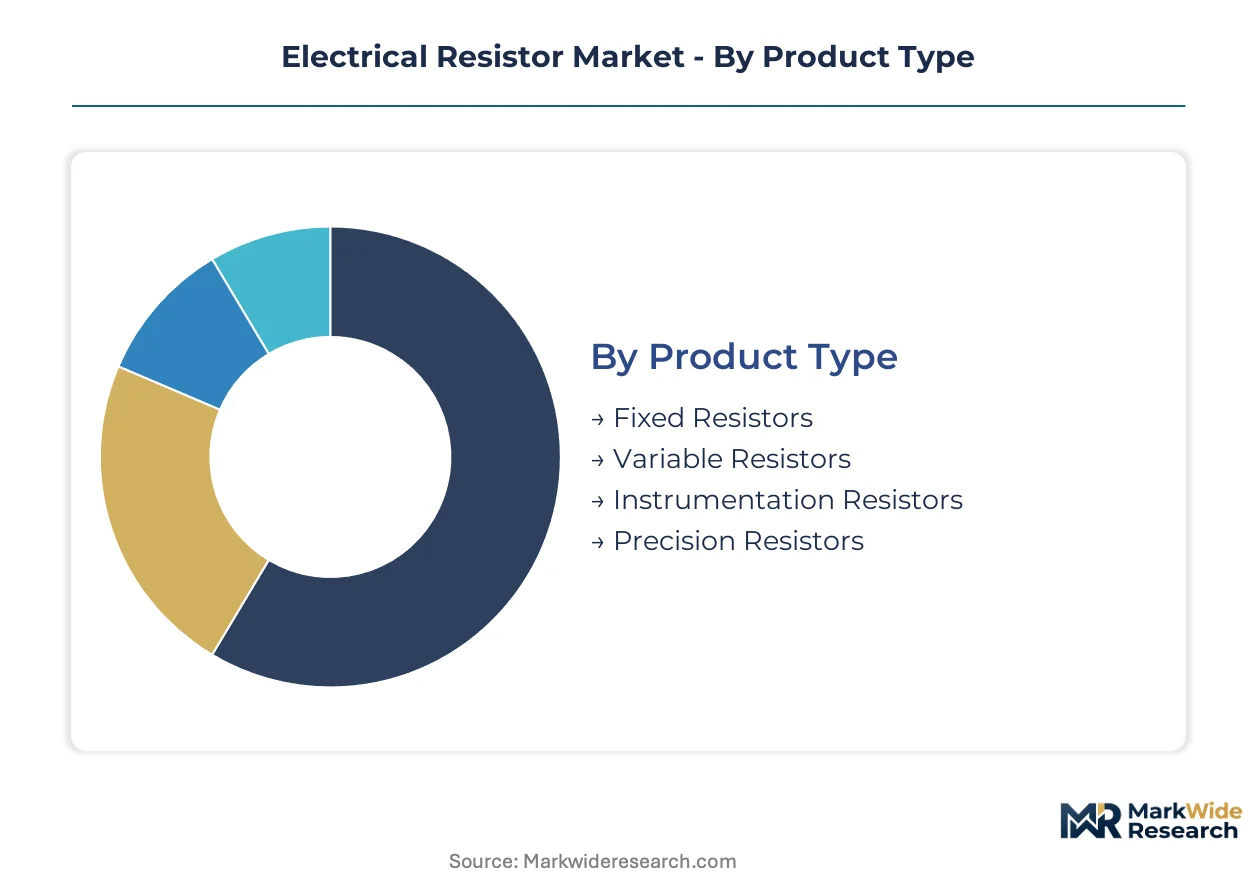
Resistor procurement patterns diverge sharply across product architectures and deployment environments. Component buyers prioritize thermal tolerance, tolerance precision, or cost minimization depending on end-use criticality and regulatory exposure.
Product Type:
Fixed resistors anchor high-volume manufacturing across cost-sensitive electronics assembly.
- Fixed Resistors:Carbon composition, metal oxide, or thick-film elements deliver stable resistance values for surface-mount and through-hole mounting. Consumer electronics manufacturers in Shenzhen and automotive module suppliers in Stuttgart specify these for battery management and power distribution units where unit economics govern procurement.
- Variable Resistors:Potentiometers and trimmers enable adjustable resistance for calibration and tuning functions. Industrial control panel builders and audio equipment manufacturers specify wirewound or cermet constructions for precision adjustment in motor drives and signal processing chains.
- Instrumentation Resistors:Ultra-stable metal foil and thin-film elements serve measurement bridges and sensor excitation circuits. Metrology laboratories and aerospace test equipment vendors demand temperature coefficients below 5 ppm/°C for calibration-grade accuracy.
- Precision Resistors:Tight tolerance bands down to 0.01% support medical imaging and analytical instrumentation. Semiconductor test equipment manufacturers in Tokyo and Boston specify these for reference voltage generation where drift compromises measurement integrity.
The dominant share belongs to Fixed Resistors, while Precision Resistors is closing the gap fastest.
Technology:
Manufacturing process selection determines thermal performance, miniaturization limits, and margin structure.
- Thin Film:Sputtered metal alloys on ceramic substrates achieve tight tolerances and low noise for precision applications. Medical device manufacturers and aerospace avionics suppliers specify tantalum nitride systems for long-term stability in implantable devices and flight control systems.
- Thick Film:Screen-printed resistive pastes on alumina substrates dominate automotive and consumer electronics volume. South Korean and Japanese production clusters integrate ceramic powder processing with termination plating for cost-optimized surface-mount supply.
- Wirewound:Resistive wire wound on ceramic cores handles high power dissipation in industrial motor drives. Power conversion equipment builders specify these for braking resistors and load banks where thermal mass exceeds surface-mount capabilities.
- Carbon Composition:Molded carbon and binder mixtures persist in legacy equipment and surge protection applications. Military depot maintenance and industrial spare parts distributors stock these for compatibility with vintage circuit designs.
Thick Film commands the largest production volume, though Thin Film is expanding most quickly in high-reliability segments.
End User:
Customer verticals impose distinct qualification regimes and thermal specification thresholds.
- Consumer Electronics:Smartphones, laptops, and wearables drive thick-film resistor consumption for miniaturized power management. Chinese contract manufacturers specify 0402 and 0201 case sizes for automated assembly lines serving global brand OEMs.
- Automotive Industry:Battery management systems and powertrain inverters demand AEC-Q200 qualified components with extended temperature ranges. MIIT efficiency mandates in China and EPA automotive emissions frameworks in the US tighten thermal-performance specifications for new-energy vehicle platforms.
- Industrial Equipment:Motor drives, power supplies, and automation controllers specify wirewound and high-power thick-film resistors. German machine builders and Japanese factory automation vendors prioritize RoHS-compliant termination plating for CE-marked equipment exports.
- Telecommunications:Base station power amplifiers and optical transceivers use precision thin-film resistors for impedance matching. 5G infrastructure deployment in India and Southeast Asia is concentrating procurement through technical distributors with regional stocking points.
Automotive Industry holds the dominant procurement volume, while Telecommunications is gaining share fastest on infrastructure buildouts.
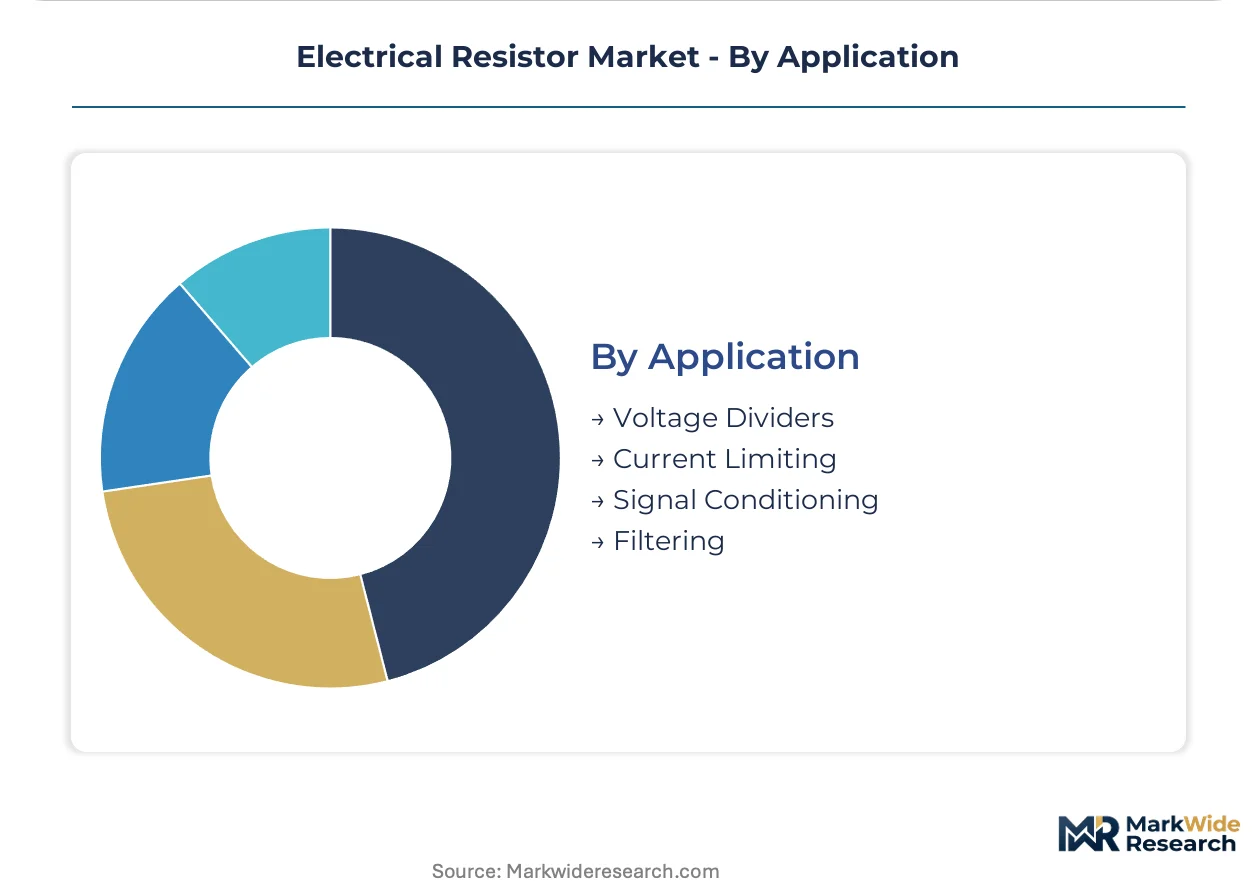
Application:
Circuit function determines resistor specification priority across electrical parameters.
- Voltage Dividers:Matched resistor pairs establish reference potentials and scaling ratios for analog-to-digital conversion. Data acquisition system manufacturers and power supply designers specify precision thin-film networks for ratio stability over temperature.
- Current Limiting:Series resistance restricts fault currents and protects sensitive semiconductors. Battery management system designers specify fusible and pulse-withstanding types for lithium-ion cell balancing circuits.
- Signal Conditioning:Gain-setting and feedback networks preserve signal integrity in sensor interfaces. Medical device manufacturers and industrial IoT vendors select low-noise metal film types for strain gauge and thermocouple amplification.
- Filtering:RC networks with capacitors shape frequency response and suppress electromagnetic interference. Automotive ECU designers and telecommunications equipment builders specify these for noise reduction in high-speed data lines.
Voltage Dividers captures the dominant application share, while Signal Conditioning is climbing the fastest on sensor proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT efficiency mandates and India's PLI scheme for electronics manufacturing are redistributing procurement patterns across major production clusters. Government-backed incentives in battery management and powertrain electronics now determine where resistor manufacturers expand capacity.
China
New-energy vehicle production in Shenzhen and Shanghai drives thick-film resistor demand for battery management systems. MIIT enforces stricter power-dissipation ratings on components entering domestic industrial equipment supply chains. The Yangtze River Delta concentrates Samsung Electro-Mechanics and Yageo Corporation assembly operations serving automotive tier-1 suppliers.
United States
Aerospace and defense programs in Texas and California sustain precision thin-film procurement through design-win relationships. The EPA and OSHA jointly influence manufacturing site compliance for resistor factories serving military qualification programs. Greater Boston hosts semiconductor test equipment manufacturers specifying sub-50 ppm temperature coefficient resistors for reference voltage generation.
Germany
Industrial motor drive builders in Bavaria and Baden-Württemberg specify wirewound resistors for braking applications in factory automation. REACH and RoHS frameworks restrict hazardous substances in termination plating, compelling reformulation of thick-film paste chemistries. The Stuttgart automotive cluster sources AEC-Q200 qualified components for powertrain inverter modules.
Japan
High-purity alumina substrate supply concentrates among Japanese specialty chemical producers serving Murata Manufacturing and KOA Corporation. METI efficiency standards align with domestic automotive electrification roadmaps. The Nagoya industrial corridor integrates ceramic powder processing with precision resistor fabrication for medical device exports.
South Korea
Busan-Ulsan manufacturing anchors regional thick-film capacity with integrated ceramic substrate and termination plating capabilities. Samsung Electro-Mechanics supplies consumer electronics brands through direct OEM contracts. Seoul Capital Area distributors consolidate procurement for 5G base station power amplifiers requiring impedance-matched thin-film networks.
Electrical Resistor Market Vendor Landscape
On the supply side, the industry is consolidating around East Asian production clusters with integrated material capabilities. Japanese and South Korean manufacturers control high-purity ceramic substrate supply while North American and European players dominate precision instrumentation niches. Three archetypes define competitive positioning: scale-driven thick-film specialists, precision thin-film technology leaders, and diversified passive component conglomerates. Capacity expansion in India and strategic partnerships for SiC-adjacent resistor integration represent the dominant competitive moves reshaping supply relationships.
Among diversified passive component conglomerates, Panasonic Corporation and Murata Manufacturing exemplify integrated production models spanning ceramic substrate fabrication through termination plating. Rohm Co., Ltd. occupies a position within the technology-differentiated tier, representing manufacturers pursuing thermal envelope expansion for silicon carbide power electronics applications. These three anchors demonstrate how geographic concentration in East Asian manufacturing clusters intersects with specialization strategies across automotive, industrial, and consumer electronics verticals.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Rohm Co., Ltd. |
| Yageo Corporation |
| KOA Corporation |
| TE Connectivity |
| Vishay Intertechnology |
| Samsung Electro-Mechanics |
| Bourns, Inc. |
| Murata Manufacturing |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries thick-film resistor shipments from Yangtze River Delta production clusters to European automotive tier-1 suppliers, with freight cost volatility amplifying margin pressure at distributors serving mid-volume industrial buyers. This logistics artery concentrates pricing power among Japanese and South Korean manufacturers with captive ceramic substrate capabilities, while forcing buyers in Germany and Texas to absorb delivery premiums or shift to authorized distributor networks with regional stocking points.
Pricing Analysis
Certification level creates the primary spread across procurement tiers, with AEC-Q200 automotive qualification commanding substantial premiums over consumer-grade thick-film equivalents. Pricing stratifies across precision instrumentation, industrial power, and commodity consumer segments, with tolerance bands below 50 ppm capturing disproportionate margins in medical and aerospace signal chains. Cost compression in standard thick-film surface-mount packages intensifies as Chinese contract manufacturers scale 0402 and 0201 case size production for smartphone brands. Automotive battery management system designers show least price sensitivity due to thermal-performance mandates from MIIT and EPA frameworks, while consumer electronics contract manufacturers in Shenzhen drive hardest bargaining on unit economics.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment to China are reshaping resistor supply relationships as regional production clusters seek alternative equipment sources. Supply concentrates in Japan, South Korea, and China, with high-purity alumina substrate fabrication anchoring in Japanese specialty chemical producers serving Murata Manufacturing and KOA Corporation. Raw material dependencies center on palladium-ruthenium thick-film pastes, tantalum nitride sputtering targets, and precision ceramic powders. Single-source vulnerability in Japanese alumina supply exposes buyers to geographic concentration risk during trade disruptions. Distribution runs through authorized technical distributors with application engineering capabilities in Germany, Texas, and Guangdong province, bypassing traditional multi-layer trading companies for mid-volume industrial and medical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical resistor market is approaching a platform-economics inflection as silicon carbide power electronics ecosystems demand matched resistor technologies with expanded thermal envelopes, forcing interoperability standards across automotive and industrial supply chains.
For Market Incumbents: Build captive ceramic substrate capabilities to defend against palladium price volatility and Japanese single-source supply risk. Secure AEC-Q200 qualification pipelines for battery management system components before MIIT efficiency mandates tighten further. Anchor design-win relationships through authorized distributors with in-house application engineering in Stuttgart and Texas, countering emerging thick-film capacity from India's PLI scheme beneficiaries.
For New Entrants and Emerging Players: Pursue greenfield thick-film assembly opportunities in India's PLI-subsidized electronics manufacturing zones, targeting automotive tier-2 suppliers seeking second-source qualification outside East Asian supply nodes. Penetrate the telecommunications infrastructure segment through impedance-matched thin-film networks for 5G base station power amplifiers, leveraging regional distributor partnerships in Southeast Asia rather than direct OEM contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized precision resistor divisions lacking AEC-Q200 certification pipelines. Long-term viability hinges on thermal envelope expansion capabilities for silicon carbide-adjacent applications. Monitor qualification timelines for RoHS-compliant termination plating reformulations as the inflection signal—delayed product releases from substance restriction compliance indicate margin pressure ahead for legacy paste formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Japanese specialty chemical producers capture margin pools from Murata and KOA captive supply arrangements. |
| AEC-Q200 Qualification Pipeline Expansion | Automotive tier-1 suppliers in Stuttgart and Shanghai demand certified components for battery management systems. |
| Authorized Distributor Channel Development | Technical distributors with regional stocking points in Texas and Guangdong consolidate design-win influence. |
| RoHS-Compliant Paste Reformulation | Bismuth-based glass frits and silver-palladium alloys replace restricted cadmium and lead in termination plating. |
| SiC-Adjacent Thermal Envelope Expansion | Rohm Co., Ltd. and precision thin-film specialists target power electronics operating above traditional temperature limits. |
Methodological Framework
Cross-validation between primary interviews with resistor procurement managers at automotive tier-1 suppliers and secondary trade data from customs filings anchors the qualitative findings on East Asian manufacturing concentration. Plant managers at thick-film production facilities, application engineers at authorized distributors, OEM procurement leads in consumer electronics, and regulatory affairs specialists at component manufacturers provided operational perspectives. SEC 10-K disclosures, MIIT efficiency mandate documentation, ECHA REACH substance restriction updates, and ceramic substrate import records supplied external validation. Bottom-up unit shipment estimates from case size and technology tier triangulate against top-down value projections across the analysis window.
Calibration against historical capacity utilization rates at Japanese and South Korean production clusters shapes the forward projection framework. Segmentation dimensions span product architecture, manufacturing technology, end-user vertical, and circuit application function, with thermal performance specifications and certification tiers as cross-cutting variables. CAGRs derive from elasticity-adjusted demand curves for automotive electrification and telecommunications infrastructure buildouts. Palladium price trajectories and MIIT enforcement intensity on power-dissipation ratings serve as industry-specific forecast sensitivity inputs.
Sensitivities concentrate around palladium-ruthenium commodity spikes, REACH substance restriction amendments, and MIIT mandate implementation timelines. Forecasts reflect documented assumptions on automotive electrification penetration and 5G infrastructure deployment pacing. Material shifts in export-control regimes affecting ceramic processing equipment access, or abrupt reformulation requirements from ECHA hazard substance reclassifications, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Sealed DC Contactor Market
Electrical Equipment
Smart Fan Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
Waveguide Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Motor Protection Devices Market