
 GCC Labels and Release Liners Market | 2026-2036
GCC Labels and Release Liners Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Labels and Release Liners Market Foresight
Pharmaceutical firms are bifurcating demand away from generic consumer goods manufacturers across the GCC labels and release liners supply base. Pacman CCL leverages its regional manufacturing footprint to serve high-compliance pharmaceutical serialization requirements. Taghleef Industries LLC anchors the upstream supply of specialized films that converters depend upon for release liner substrates. Sigma Middle East Labels Industries LLC competes through dedicated capacity for pressure sensitive label formats bound for regulated end uses.
Labels and release liners constitute adhesive-backed substrates engineered with silicone-coated release papers or films, typically specified by peel force ranges of 10 to 50 grams per inch, designed to carry printed information while enabling clean separation during automated or manual application. Pressure sensitive labels dominate volume flows across the GCC given their compatibility with variable-information printing and pharmaceutical track-and-trace mandates, while shrink sleeve labels represent the fastest-expanding format as beverage brands pursue 360-degree graphic coverage on contoured containers. Polypropylene and polyester materials command premium positioning due to durability requirements in personal care and electronics applications where moisture resistance and dimensional stability determine specification.
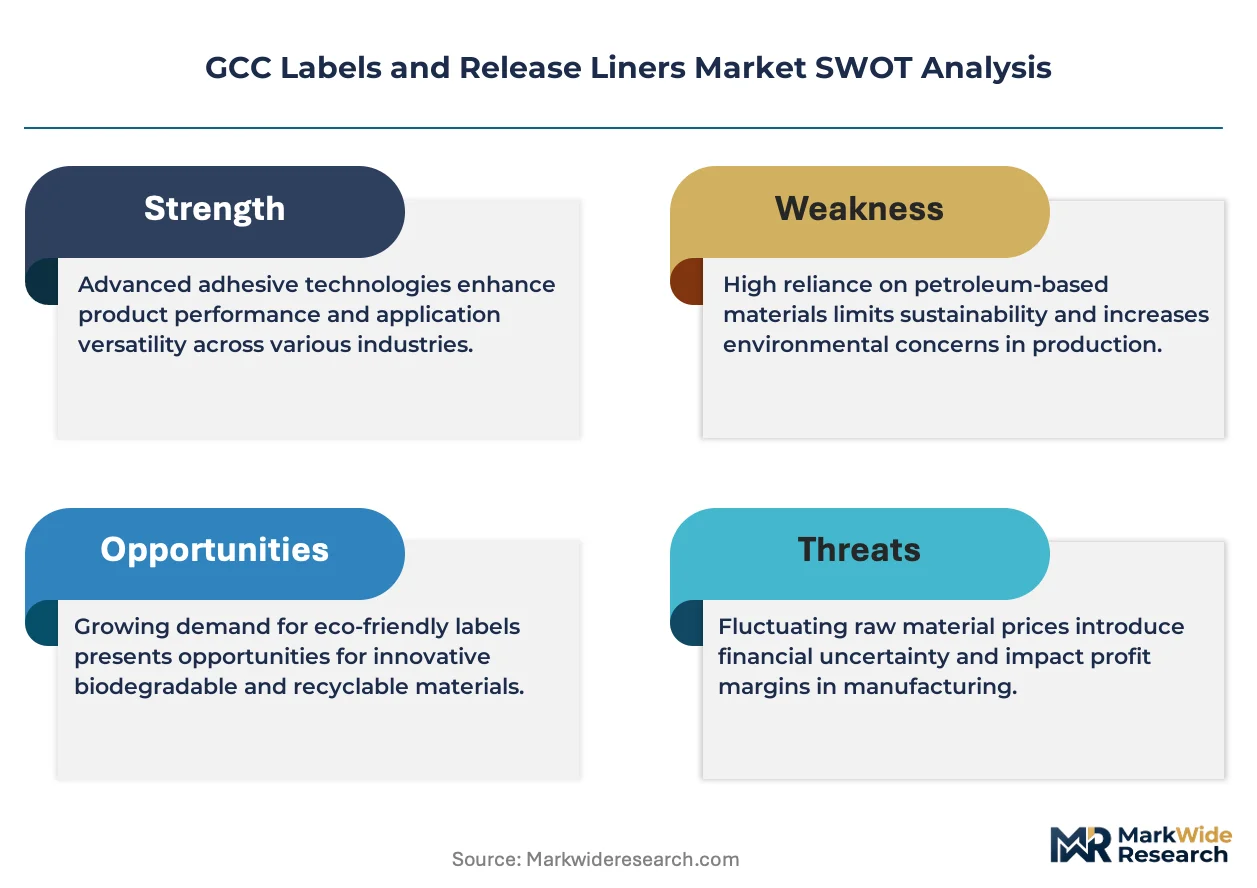
Saudi Food and Drug Authority (SFDA) serialization regulations and UAE Ministry of Health and Prevention (MOHAP) pharmaceutical traceability standards are reshaping label specification requirements across the Gulf, compelling converters to validate adhesive permanence and print durability against regulatory audit protocols. The Saudi Standards, Metrology and Quality Organization (SASO) and Gulf Standardization Organization (GSO) harmonization initiatives for food contact materials further constrain substrate and adhesive selection for packaging applications. Stakeholders must monitor evolving Gulf Cooperation Council technical regulations for label recyclability and single-use packaging restrictions that will determine material substitution timelines and converter capital allocation priorities.
Market Dynamics
Pharmaceutical serialization mandates from Saudi Food and Drug Authority and UAE Ministry of Health and Prevention are forcing converters to reengineer adhesive and substrate specifications for track-and-trace compliance. This regulatory compression is reshaping procurement patterns across the GCC supply base.
Growth Catalysts
- SFDA pharmaceutical traceability mandates:Saudi Arabia's serialization requirements for prescription packaging are accelerating specification upgrades for tamper-evident pressure sensitive labels with integrated variable-data printing.
- Food contact material harmonization:SASO and GSO alignment initiatives are standardizing substrate safety protocols, reducing technical barriers for regional converters serving cross-border food brands.
- Shrink sleeve adoption in beverages:UAE and Saudi beverage manufacturers are migrating from wraparound paper labels to 360-degree polymer sleeves that withstand condensation and refrigeration cycles.
Market Restraints
- Silicone-coated release liner cost volatility:Petrochemical feedstock fluctuations for silicone polymers and glassine papers compress converter margins, particularly for mid-volume pharmaceutical contract manufacturers.
- Upstream film concentration:Specialized biaxially oriented polypropylene supply concentrates among a limited set of European and Asian substrate producers, creating import dependency for GCC converters.
- Adhesive permanence validation timelines:Extended stability testing protocols for pharmaceutical-grade acrylic adhesives delay new product qualification cycles by 12 to 18 months.
Strategic Opportunities
- Qatar and Kuwait pharmaceutical manufacturing:Underdeveloped local label converting capacity in these markets creates first-mover positioning for Saudi and UAE-based suppliers with validated serialization workflows.
- Digital printing convergence with RFID inlays:Hybrid production lines combining inkjet variable printing with embedded NFC tags enable premium authentication solutions for cosmetics and electronics brands.
- E-commerce direct-to-consumer packaging:Last-mile fulfillment requirements for personal care subscription services in Dubai and Riyadh are stimulating demand for dual-layer labels with return-logistics functionality.
Industry Challenges
- Specialized print technician scarcity:GCC converters face recruitment gaps for operators qualified in UV inkjet color management and pharmaceutical-grade die-cutting validation.
- Legacy ERP integration with serialization databases:Small and mid-sized label houses struggle to connect production workflows with national track-and-trace repositories mandated by Saudi and UAE regulators.
- Multi-jurisdiction certification overlap:Converters serving both Saudi SFDA and UAE MOHAP markets must maintain parallel adhesive qualification dossiers despite overlapping technical requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Labels and Release Liners Market |
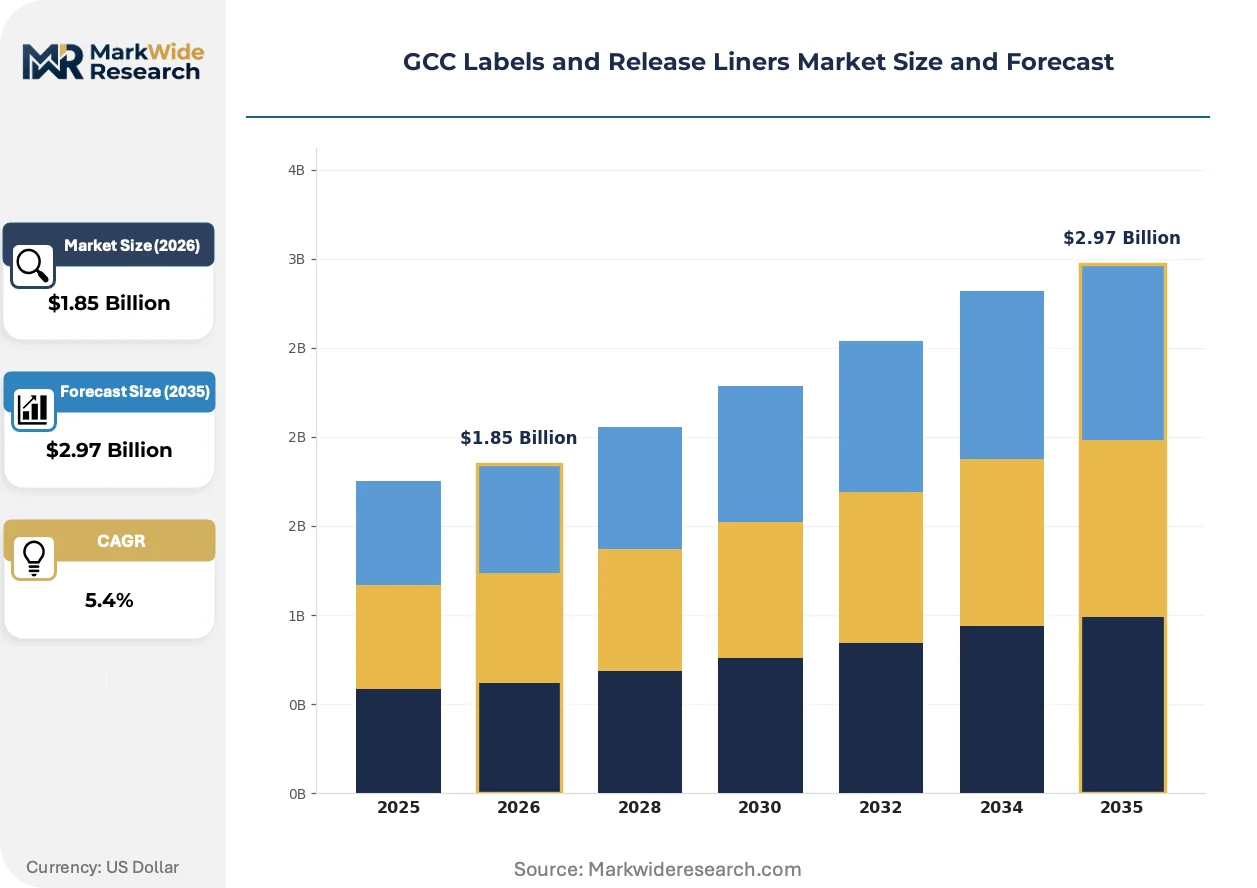
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive Labels, In-Mold Labels, Shrink Sleeve Labels, Tag Labels, Adhesive Transfer Labels Application: Food & Beverage, Personal Care, Pharmaceuticals, Electronics, Homecare End User: Packaging Companies, Consumer Goods Manufacturers, Pharmaceutical Firms, Electronics Suppliers, Personal Products Firms Material Type: Polypropylene, Polyester, Paper, Polyethylene, Vinyl |
| Companies Covered | Pacman CCL, Sticker Products Company (Lawaseq), Taghleef Industries LLC, Sigma Middle East Labels Industries LLC, Brady Middle East FZE, Print Pack LLC, Labels UAE (Mustansir Labels), Label Tech UAE, SoluWise Labels LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Labels and Release Liners Market Shifts & Advancements
Digital production technologies and regulatory authentication requirements are converging to redefine label functionality beyond decorative branding. This shift elevates technical specifications for substrate durability, print resolution, and data-carrying capacity across GCC end-use verticals.
Radio-frequency identification inlay integration with pressure sensitive label constructions is miniaturizing antenna and chip footprints while maintaining read-range performance. Pharmaceutical manufacturers in Jeddah and Dubai are piloting item-level RFID tagging for high-value biologics, compressing the cost differential between optical barcodes and electronic identification to under fifteen percent per unit at volume.
SFDA and MOHAP pharmaceutical serialization regulations are mandating human-readable and machine-scannable codes with minimum ten-year data retention. This policy compression is forcing converters to validate thermal transfer ribbons and laser-marked substrates against accelerated aging protocols, with the greatest compliance burden falling on suppliers serving generic drug manufacturers with thin margin structures.
Brand owners in the UAE personal care sector are consolidating supplier relationships around converters offering integrated design-to-dispatch digital workflows. This procurement consolidation displaces fragmented spot-buying from trading houses, concentrating volume among Riyadh and Dubai facilities with in-house prepress and same-day proofing capabilities. The shift is most visible in premium skincare and fragrance launches targeting Gulf retail chains.
GCC Labels and Release Liners Market Segmentation
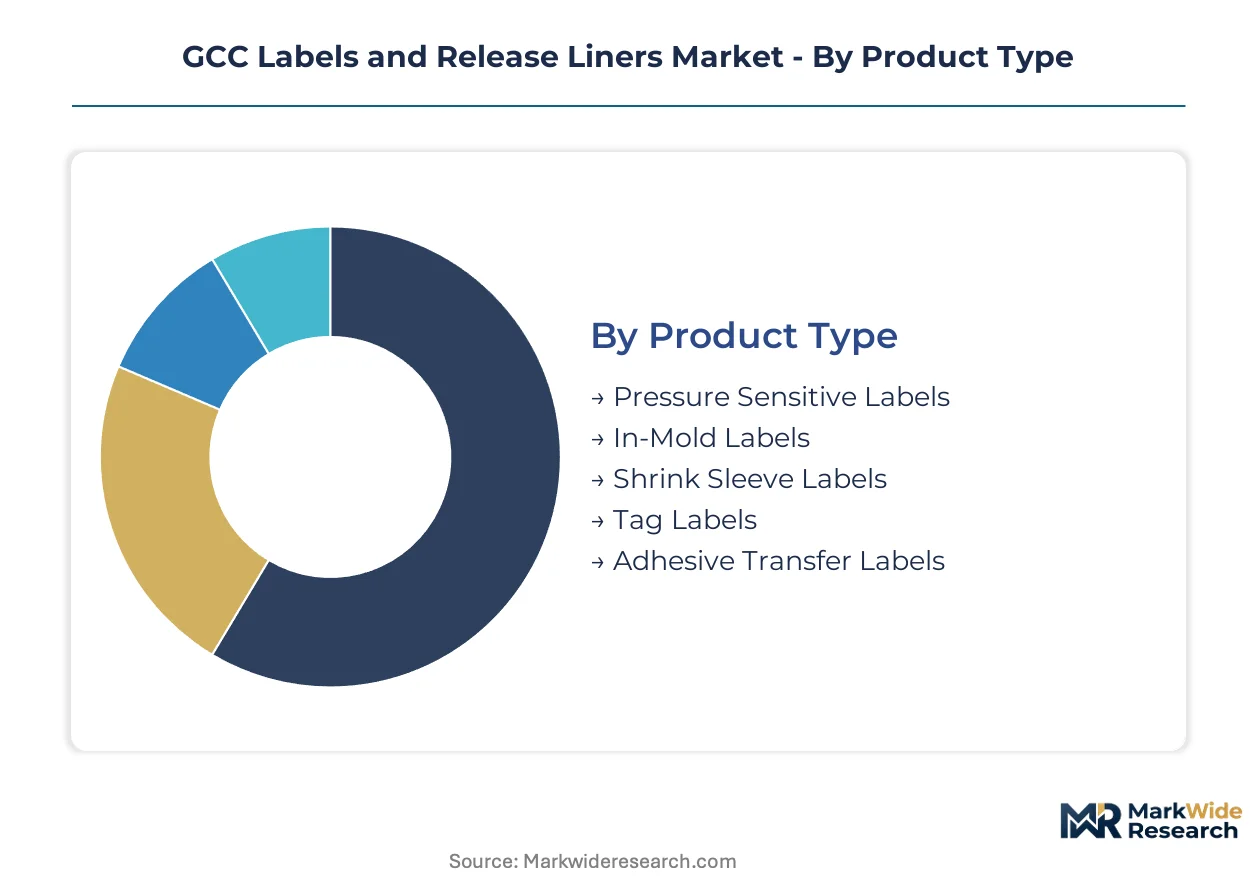
Segmentation across the GCC labels and release liners market reveals how regulatory mandates reshape procurement priorities by end-use vertical. Pharmaceutical serialization requirements and food contact harmonization standards create divergent specification pathways that converters must navigate simultaneously.
Product Type:
SFDA and MOHAP pharmaceutical traceability mandates differentiate pressure sensitive formats from decorative alternatives through validation requirements for variable-data durability and adhesive permanence.
- Pressure Sensitive Labels:Self-adhesive constructions with silicone-coated release liners specified by 10-50 gram per inch peel force ranges. Pharmaceutical serialization mandates across Saudi Arabia and the UAE concentrate procurement volume here, as converters must validate thermal transfer and laser-marked substrates against ten-year data retention protocols.
- Shrink Sleeve Labels:Polymer sleeves providing 360-degree graphic coverage through heat-induced contraction. UAE and Saudi beverage manufacturers are migrating from wraparound paper formats to these polymer constructions that withstand condensation and refrigeration cycles, representing the steepest expansion trajectory among all product types.
- In-Mold Labels:Polypropylene or polyester films fused directly into injection-molded containers during formation. Personal care brands in Dubai specify these for premium cosmetic packaging requiring scratch resistance.
- Tag Labels:Non-adhesive cardstock or synthetic substrates attached by string, wire, or mechanical fasteners. Electronics suppliers in Jeddah utilize these for high-heat equipment where adhesive degradation poses risks.
- Adhesive Transfer Labels:Pressure sensitive constructions without face stock, delivering pure adhesive patterns for bonding applications. Industrial equipment manufacturers in Dammam specify these for permanent assembly labels.
Established volume favors pressure sensitive formats; emerging adoption favors shrink sleeve constructions.
Application:
End-use cost tiering separates regulated pharmaceutical and food contact applications from discretionary personal care and electronics labeling.
- Pharmaceuticals:Prescription packaging and biologics containers requiring tamper-evident seals with integrated serialization. SFDA and MOHAP mandates force converters to maintain parallel adhesive qualification dossiers despite overlapping technical requirements, compressing margins for generic drug manufacturers.
- Food & Beverage:Primary and secondary packaging for perishable and shelf-stable goods. SASO and GSO harmonization initiatives standardize substrate safety protocols, reducing technical barriers for regional converters serving cross-border brands.
- Personal Care:Skincare, fragrance, and hygiene product labeling. Premium brand owners in the UAE consolidate supplier relationships around converters offering integrated design-to-dispatch digital workflows.
- Electronics:Component identification and consumer device branding. Moisture resistance and dimensional stability requirements command premium positioning for polypropylene and polyester materials.
- Homecare:Cleaning product and household goods labeling. Durable substrates withstand chemical exposure and repeated handling in Saudi retail environments.
Regulatory compliance concentrates margin in pharmaceuticals; brand differentiation drives value in personal care.
End User:
Customer type determines volume scale and technical service intensity, with pharmaceutical firms bifurcating demand away from generic consumer goods manufacturers.
- Pharmaceutical Firms:Manufacturers of prescription drugs, biologics, and medical devices requiring validated serialization workflows. Extended stability testing protocols for pharmaceutical-grade acrylic adhesives delay new product qualification cycles.
- Packaging Companies:Contract converters and co-packers serving multiple brand owners. These intermediaries face recruitment gaps for operators qualified in UV inkjet color management and pharmaceutical-grade die-cutting validation.
- Consumer Goods Manufacturers:Mass-market food, beverage, and household product producers. Price sensitivity limits substrate selection to paper and standard polypropylene grades.
- Electronics Suppliers:Component manufacturers and device assemblers. Small and mid-sized label houses struggle to connect production workflows with national track-and-trace repositories.
- Personal Products Firms:Cosmetics, fragrance, and skincare brand owners. Last-mile fulfillment requirements for subscription services stimulate demand for dual-layer labels with return-logistics functionality.
Validation burden favors specialized pharmaceutical suppliers; scale economies favor diversified packaging companies.
Material Type:
Supply concentration among European and Asian substrate producers creates import dependency that shapes material selection for GCC converters.
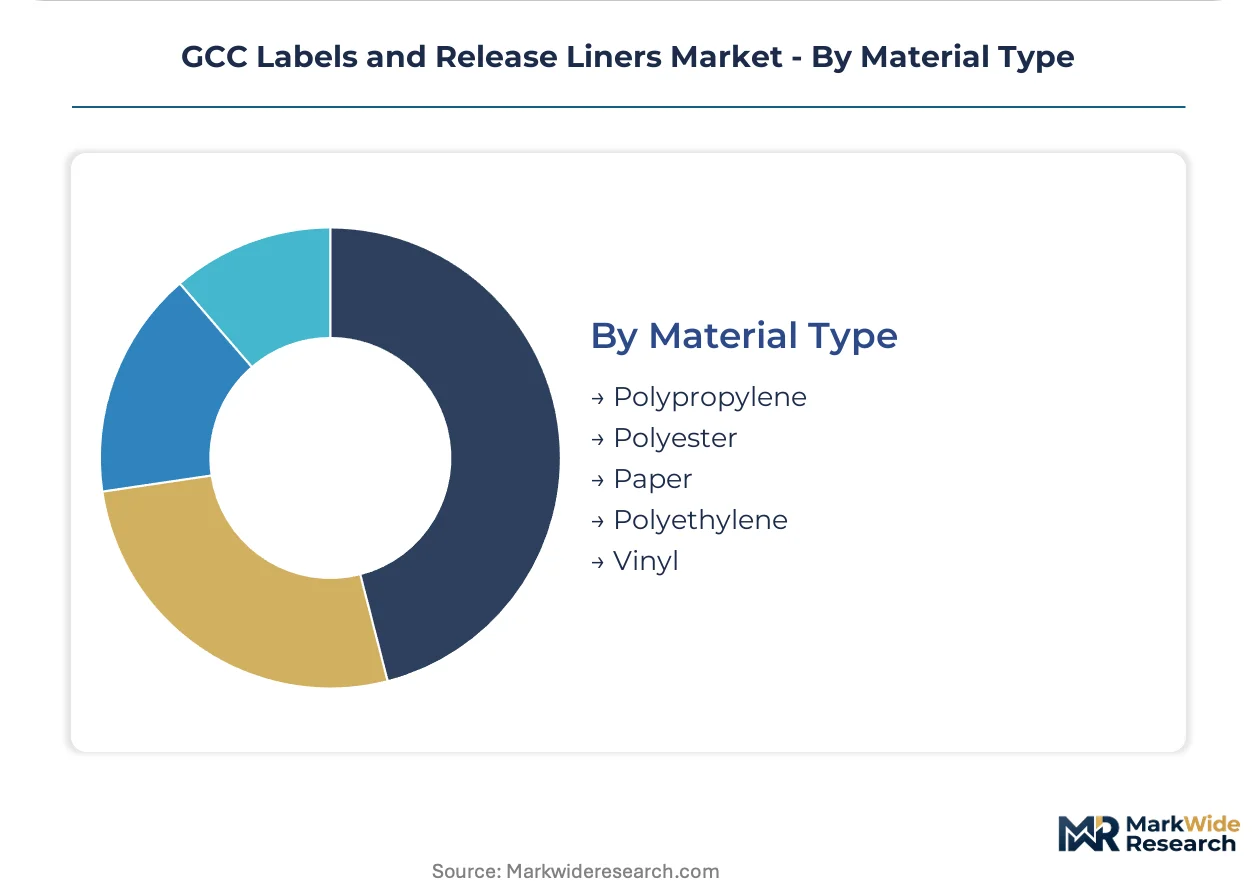
- Polypropylene:Biaxially oriented films offering moisture resistance and dimensional stability. Specialized BOPP supply concentrates among limited European and Asian producers, constraining regional converter margins.
- Polyester:High-performance films for electronics and premium personal care applications. Durability requirements in Dubai and Riyadh electronics manufacturing command premium positioning.
- Paper:Glassine and kraft substrates for cost-sensitive food and beverage applications. Petrochemical feedstock fluctuations for silicone-coated release liners compress margins for mid-volume contract manufacturers.
- Polyethylene:Flexible films for conformable labeling on irregular container shapes. Shrink sleeve beverage applications in the UAE specify these for refrigeration compatibility.
- Vinyl:Durable substrates for outdoor and industrial exposure. Limited regional production capacity necessitates import reliance.
Performance specifications favor polyester and polypropylene; cost constraints sustain paper volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports label stock and converted pressure sensitive materials to pharmaceutical manufacturers across Bahrain, Oman, and Jordan, establishing the kingdom as the dominant supply corridor for GCC serialization compliance.
Saudi Arabia
Pharmaceutical serialization mandates from SFDA drive specification upgrades for tamper-evident pressure sensitive labels with integrated variable-data printing. The Saudi Food and Drug Authority enforces ten-year data retention protocols for thermal transfer and laser-marked substrates. Jeddah and Riyadh industrial zones concentrate converter capacity serving generic drug manufacturers with validated adhesive qualification dossiers.
United Arab Emirates
Beverage manufacturers in Dubai and Abu Dhabi migrate from wraparound paper labels to 360-degree polymer shrink sleeves that withstand condensation and refrigeration cycles. The UAE Ministry of Health and Prevention mandates pharmaceutical traceability standards parallel to Saudi SFDA requirements. Dubai's Jebel Ali industrial corridor anchors premium personal care label production with integrated design-to-dispatch digital workflows.
Qatar
Underdeveloped local label converting capacity creates first-mover positioning for Saudi and UAE-based suppliers with validated serialization workflows. The country's national pharmaceutical regulator aligns import requirements with Gulf Standardization Organization harmonization initiatives. Doha's emerging pharmaceutical manufacturing cluster sources pressure sensitive labels from cross-border converters rather than domestic production.
Kuwait
Food contact material standardization under SASO and GSO alignment reduces technical barriers for regional converters serving cross-border food brands. The country's central standardization body adopts substrate safety protocols matching Saudi and UAE benchmarks. Kuwait City packaging distributors rely on imported converted labels from Eastern Province suppliers rather than indigenous manufacturing capacity.
Oman
Mid-volume pharmaceutical contract manufacturers face margin compression from silicone-coated release liner cost volatility tied to petrochemical feedstock fluctuations. The sultanate's national standards organization maintains technical equivalence with Gulf Cooperation Council regulations for label recyclability. Muscat industrial free zones host trading houses that consolidate spot-buying from fragmented converter networks across the wider GCC.
GCC Labels and Release Liners Market Competitive Landscape
Player mix skews toward regional converters with specialized pharmaceutical serialization capabilities alongside multinational substrate suppliers controlling upstream film supply. Market structure concentrates around mid-scale integrated operations serving regulated end uses rather than commodity trading houses. Two strategic archetypes dominate: vertically integrated converters with in-house prepress and same-day proofing capabilities, and specialized release liner substrate producers supplying downstream converter networks. Competitive moves center on capacity expansion for digital printing convergence and strategic partnerships bridging RFID inlay integration with variable-information workflows.
Within the integrated converter tier, Pacman CCL and Sigma Middle East Labels Industries LLC exemplify operations with validated pharmaceutical serialization workflows and regional manufacturing footprints. Taghleef Industries LLC anchors the upstream supply of specialized films that converters depend upon for release liner substrates, occupying a position between European petrochemical feedstock sources and GCC downstream demand. These three entities represent the dominant competitive positioning vectors: converter integration, substrate specialization, and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Pacman CCL |
| Sticker Products Company (Lawaseq) |
| Taghleef Industries LLC |
| Sigma Middle East Labels Industries LLC |
| Brady Middle East FZE |
| Print Pack LLC |
| Labels UAE (Mustansir Labels) |
| Label Tech UAE |
| SoluWise Labels LLC |
| Others |
Supply & Pricing Matrix
SFDA and MOHAP serialization validation requirements gate both supplier qualification and price differentiation simultaneously, forcing converters to absorb extended adhesive permanence testing costs that stratify procurement tiers across pharmaceutical and non-pharmaceutical buyers.
Pricing Analysis
Digital inkjet variable-printing systems command 40-60% premiums over flexographic legacy equipment, while thermal transfer ribbon specifications for ten-year data retention create additional cost layering. Three-tier pricing structure across pharmaceutical-grade, food-contact-certified, and general industrial levels separates buyers by compliance burden and volume scale. Pricing pressure stems from silicone-coated release liner petrochemical feedstock volatility that compresses mid-volume contract manufacturer margins. Generic drug manufacturers exhibit highest price sensitivity due to thin margin structures, while biologics producers accept premium positioning for tamper-evident authentication features.
Supply Chain Analysis
Strait of Hormuz transit underwrites specialized biaxially oriented polypropylene supply chains feeding GCC converter networks, with upstream film concentration centering on Germany, Italy, and South Korea for pharmaceutical-grade substrates. Raw material dependencies encompass silicone polymers for release coatings, glassine papers for liner backings, and acrylic adhesive formulations for permanent bonding. Single-source vulnerability concentrates in European BOPP supply for moisture-resistant personal care applications. Distribution runs through Jeddah and Dubai industrial corridors that consolidate spot-buying from fragmented converter networks across Bahrain, Oman, and Kuwait.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical serialization mandates are transforming label procurement into a platform-economics inflection where interoperability between converter ERP systems and national track-and-trace repositories determines supplier viability.
For Market Incumbents: Compound defensive positioning by deepening backward integration into silicone-coated release liner production and securing captive supply of pharmaceutical-grade acrylic adhesives. Capacity addition in Qatar and Kuwait pharmaceutical manufacturing clusters counters emerging entrant threats from Saudi and UAE-based suppliers with validated serialization workflows. Certification investment in parallel SFDA and MOHAP adhesive qualification dossiers preserves cross-border market access. For New Entrants and Emerging Players: Last-mile fulfillment infrastructure for personal care subscription services in Dubai and Riyadh represents a service-layer gap where incumbents under-serve dual-layer label demand with return-logistics functionality. Qatar's underdeveloped local converting capacity offers the most penetrable geography for first-mover positioning. Go-to-market execution should anchor on hybrid digital printing with embedded NFC inlay integration for cosmetics authentication. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical serialization-compliant converting capacity, elevating barriers for organic entry and consolidating acquisition premiums around mid-scale integrated operations. Long-term viability favors vertically positioned converters with in-house prepress and same-day proofing capabilities serving regulated end uses. The signal to watch is Gulf Cooperation Council technical regulation evolution for label recyclability mandates that would trigger material substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Release Liner Production | Captive silicone-coated supply insulates margins from petrochemical feedstock volatility affecting Jeddah converters. |
| Digital Printing Convergence with RFID Inlay Integration | Hybrid production lines enable premium authentication solutions for Dubai cosmetics and electronics brands. |
| Cross-Border Capacity Expansion into Qatar | First-mover positioning captures pharmaceutical manufacturing demand from Doha's emerging biologics cluster. |
| Parallel Certification Investment for SFDA and MOHAP | Dual qualification dossiers preserve market access despite overlapping technical requirements. |
| ERP Integration with National Track-and-Trace Repositories | Workflow connectivity with Saudi and UAE serialization databases determines supplier eligibility for regulated contracts. |
Research Methodology
The analysis maps pressure sensitive label formats, shrink sleeve constructions, and release liner substrates, each validated through converter operations directors, pharmaceutical packaging procurement leads, and food brand supply chain managers. Primary interviews with silicone polymer suppliers, BOPP film distributors, and digital printing equipment OEMs combined with secondary validation from SASO technical regulations, GSO harmonization protocols, customs trade data, and SEC filings from multinational substrate producers. Bottom-up facility capacity assessments and top-down end-use demand modeling triangulate volume estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with analytical frameworks segmenting by product type, application vertical, end-user archetype, and material specification across the projection horizon. CAGRs derive from regression analysis of historical pharmaceutical packaging growth, beverage production volumes, and personal care SKU expansion rates. Industry-specific forecast inputs encompass SFDA serialization mandate implementation timelines and shrink sleeve adoption curves in UAE refrigeration-compatible beverage packaging.
Forecasts assume regulatory continuity in Saudi SFDA and UAE MOHAP pharmaceutical traceability regimes; material policy shifts would require re-modeling across generic drug manufacturer procurement patterns. Practitioners should keep alternative scenarios live as Gulf Cooperation Council technical regulations for label recyclability and single-use packaging restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Barcode Label Printer Market
Labels
Hot Melt Glue Labeler Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Non-Adhesive Tags Market
Labels
APAC on-Demand Color Labels Market
Labels
Tags Market
Labels
Global Laminated Labels Market
Labels
Braille Labels Market
Labels
Hang Tags Market
Labels
Kraft Labels Market
Labels
Self-Laminating Tags Market
Labels
Linerless Labels Market
Labels
Ethical Label Market
Labels
Self-Laminating Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Variable Data Printing Labels Market