
 Spain Flexible Plastic Packaging Market | 2026-2036
Spain Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Flexible Plastic Packaging Market Insights
Aftermarket recycling and collection service revenue is fragmenting across Spain's regional waste consortia as EPR obligations deepen. Amcor Plc leverages its multi-site Iberian network to sustain integrated film-to-pouch production for branded food clients. Mondi PLC anchors specialty kraft-plastic hybrid solutions for fresh protein applications, while Constantia Flexibles competes through pharmaceutical blister lidding dominance in Barcelona's dense healthcare manufacturing corridor.
Spain flexible plastic packaging comprises polymer-based materials typically below 250 micrometres in thickness, engineered through blown film extrusion, cast film processes, or lamination of multiple substrate layers to deliver barrier protection, shelf-life extension, and unit-dose convenience across perishable goods distribution. Polyethylene films occupy the largest volume share in Iberian grocery supply chains due to cost efficiency in high-turnover produce and bakery applications, while bioplastics represent the fastest-expanding material category as Spanish retailers enforce compostable packaging mandates for fruit and vegetable overwrap. Pouches capture expanding margin pools in personal care and single-serve food segments where format differentiation commands premium positioning against standard bag configurations.
Spain's extended producer responsibility framework under national packaging waste regulations shapes collection infrastructure investment and recyclate content targets for flexible formats, while BIS-equivalent Spanish standards body AENOR certification requirements and EU REACH chemical compliance govern material approvals for food-contact applications. The country's central bank and competition authority monitor consolidation patterns as EPR cost burdens reshape mid-tier converter economics. Stakeholders must track how Castilla y León and Andalucía regional waste authority tendering for flexible film sorting capacity alters feedstock availability for mechanical recycling investments.
Market Dynamics
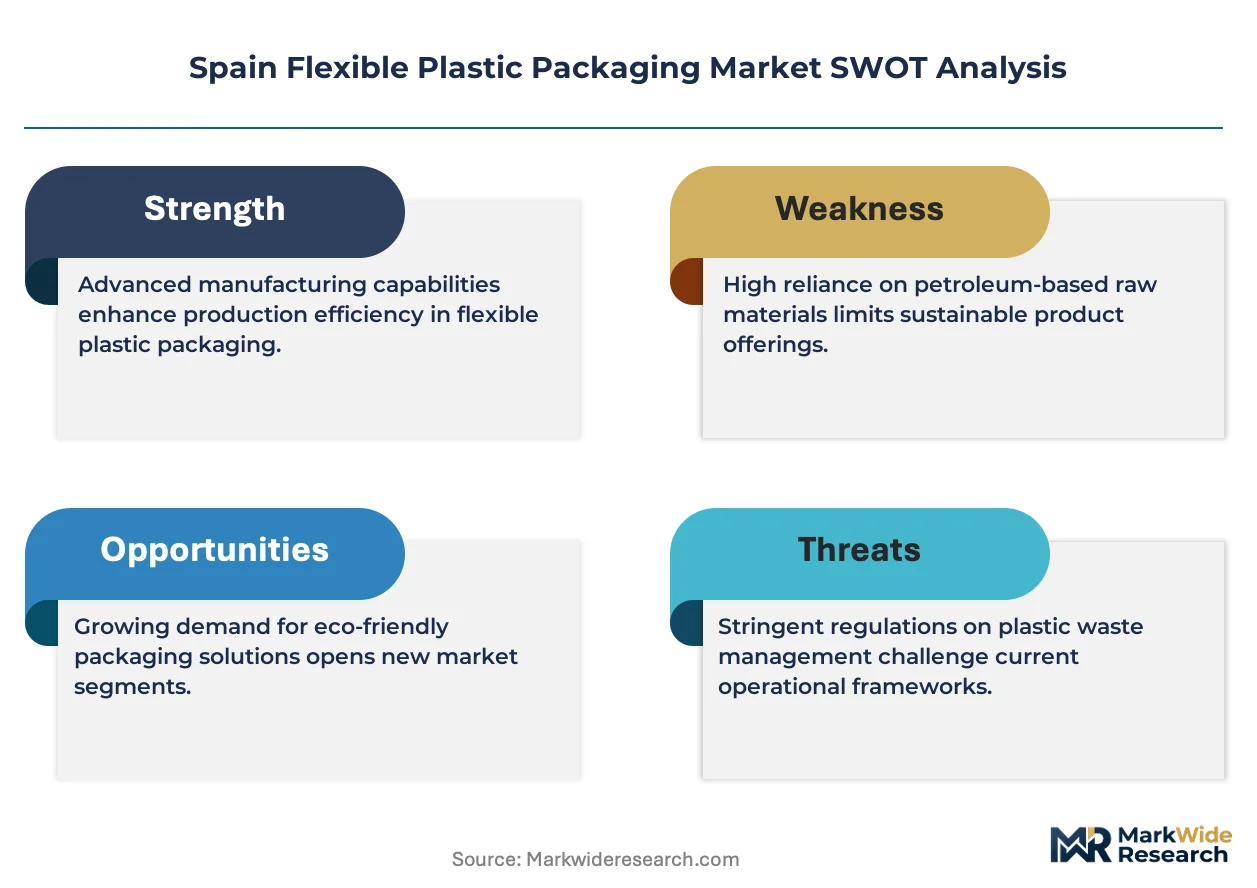
Spain's extended producer responsibility framework is compressing converter margins while redirecting capital toward collection infrastructure and certified compostable film capacity, creating asymmetric pressure across Catalonia's dense retail corridor versus Castilla-La Mancha's research clusters.
Growth Catalysts
- EPR Collection Targets:Spain's national packaging waste regulations mandate escalating recyclate recovery rates, forcing fresh food retail chains in the Basque Country to expand pre-packaged produce lines with standardized collection streams.
- Bioplastics Mandates:Retailer-enforced compostable packaging requirements for fruit and vegetable overwrap are accelerating procurement shifts toward certified films from Castilla-La Mancha polymer research clusters.
- Blown Film Extrusion Efficiency:Advances in multi-layer coextrusion are reducing material thickness below 250 micrometres while preserving barrier performance for perishable protein applications.
Market Restraints
- Polyethylene Feedstock Volatility:Naphtha-derived resin costs fluctuate with Mediterranean refinery output, squeezing margin pools for high-turnover bakery and produce film converters.
- Mechanical Recycling Feedstock Scarcity:Tendering delays by Castilla y León and Andalucía regional waste authorities constrain sorted flexible film availability for reprocessing investments.
- Multi-Layer Lamination Complexity:Barrier films combining polyethylene, polyamide, and ethylene vinyl alcohol create technical barriers to closed-loop mechanical recycling under EU REACH compliance frameworks.
Strategic Opportunities
- Pharmaceutical Blister Lidding:Barcelona's healthcare manufacturing corridor offers underexploited demand for high-barrier lidding films with AENOR certification for unit-dose pharmaceutical packaging.
- Kraft-Plastic Hybrid Formats:Fresh protein applications are adopting fiber-reinforced flexible structures that bridge paper recyclability with plastic barrier performance.
- Single-Serve Pouch Premiumization:Personal care brands are migrating from standard bag configurations to shaped pouches with spout fitments, commanding format differentiation margins.
Industry Challenges
- Compostable Certification Timelines:AENOR and EU harmonized standards for industrial compostability require 12-18 month validation cycles, delaying product launches for converters pivoting from conventional polyethylene.
- Legacy Extrusion Asset Stranding:Existing cast film lines lack the temperature control precision required for polylactic acid and polyhydroxyalkanoate processing, forcing capital-intensive equipment replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Flexible Plastic Packaging Market |
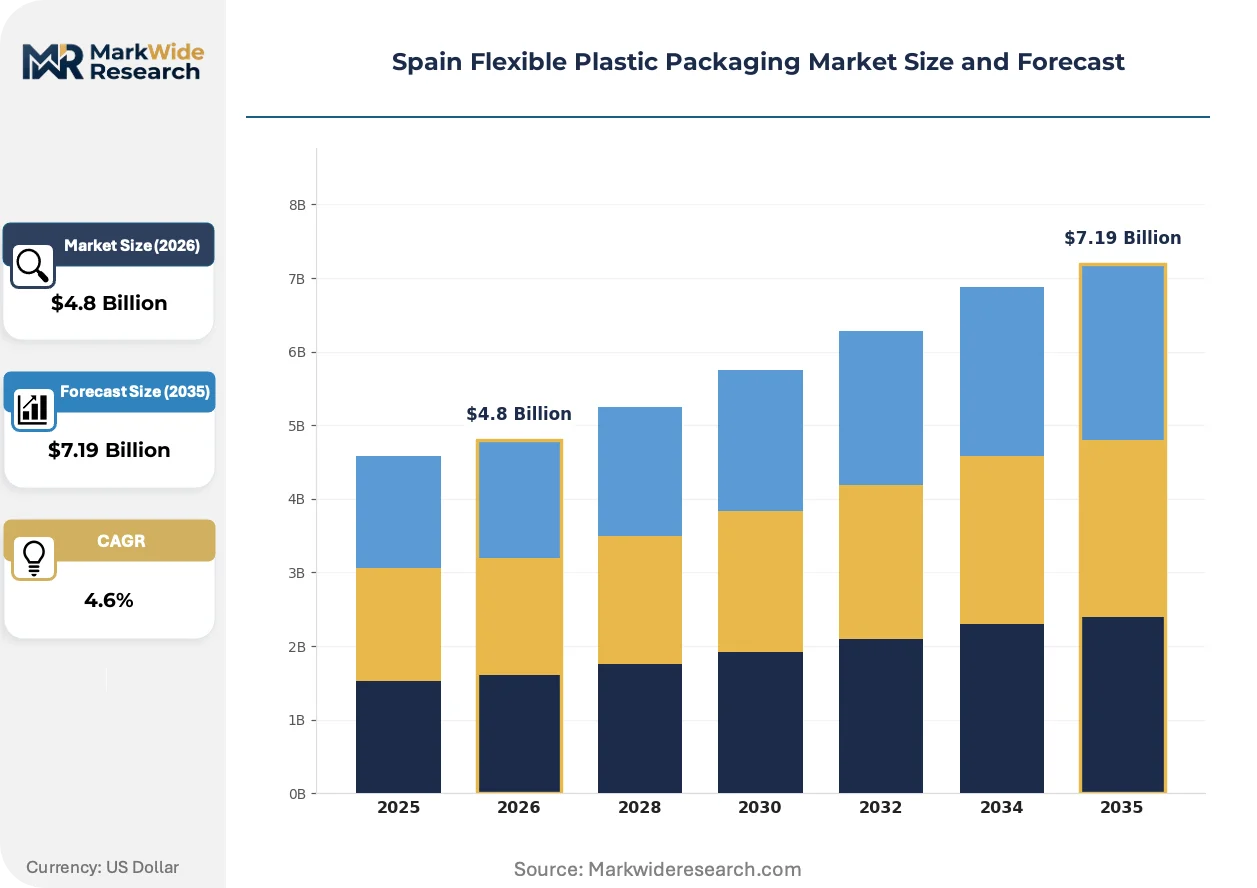
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps End Use Industry: Food & Beverage, Healthcare, Personal Care, Chemicals Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Bioplastics Thickness: Thin, Medium, Thick, Standard |
| Companies Covered | Amcor Plc, Constantia Flexibles, Mondi PLC, IFLEX FLEXIBLE PACKAGING SA, COVINIL SA, Emsur, Belca SA, Berry Global Inc., Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Flexible Plastic Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities while enabling batch-level traceability, reshaping how Spanish converters serve fragmented regional retail chains.
Digital flexographic printing with expanded gamut ink sets is virtualizing the traditional gravure cylinder pre-production step, allowing fresh produce distributors in Catalonia to switch seasonal graphics with 48-hour turnaround rather than six-week cylinder engraving lead times, collapsing inventory risk for promotional packaging cycles.
Spain's transposition of EU Single-Use Plastics Directive enforcement is accelerating substitution mandates for fruit sticker films and lightweight carrier bags, compelling Andalucía-based converters to validate home-compostable alternatives through AENOR certification protocols, with retail compliance deadlines compressing development timelines.
Consolidated buying by Mercadona and Carrefour España procurement desks is displacing fragmented regional distributor networks, forcing mid-tier converters to adopt vendor-managed inventory arrangements with direct-to-store delivery obligations, most visible in Valencia's citrus export packaging supply base where three buyers now represent sixty percent of volume.
Spain Flexible Plastic Packaging Market Segmentation
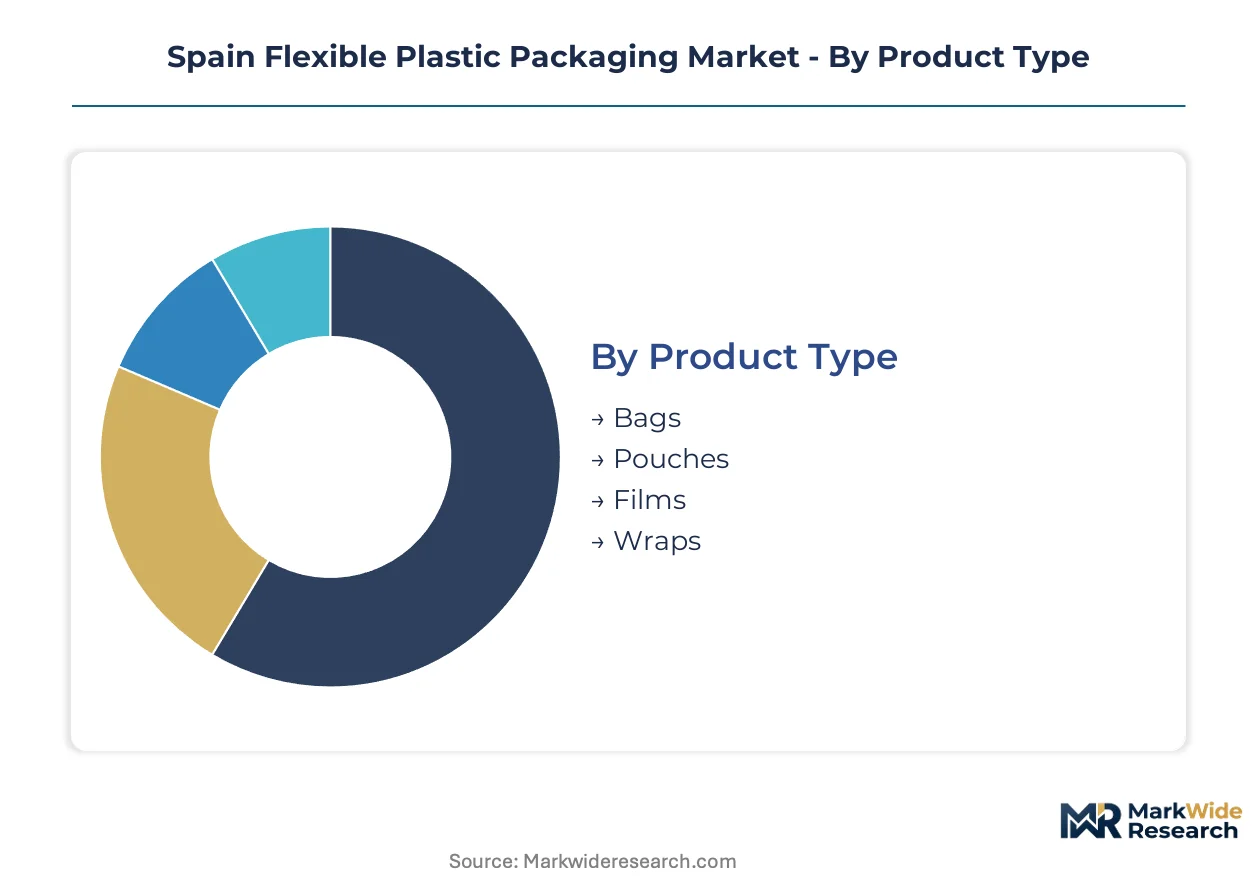
Segmentation in Spain's flexible plastic packaging market exposes divergent margin structures across material technologies and format specifications. Converter capital allocation follows distinct pathways between commodity polyethylene volumes and certified bioplastics capacity, while regional waste authority tendering reshapes feedstock economics for each category.
Product Type:
Application format determines barrier engineering requirements and production asset configuration across Iberian converter networks.
- Films:Blown and cast extrusion processes yield mono-layer and coextruded structures below 250 micrometres, serving high-turnover produce and bakery applications in Catalonia's retail corridor where cost efficiency governs procurement. Mercadona's consolidated buying power squeezes converter margins on standard polyethylene formats while demanding 48-hour graphic changeovers through digital flexographic adoption.
- Pouches:Shaped formats with spout fitments and reseal features command premium positioning in personal care and single-serve food segments, with format differentiation capturing margin pools unavailable to standard bag configurations. Valencia's citrus export base increasingly specifies stand-up pouches for portion-controlled juice concentrates.
- Bags:Side-seal and bottom-gusseted configurations dominate carrier bag and bulk commodity applications, with Andalucía-based converters validating home-compostable alternatives under AENOR protocols to meet EU Single-Use Plastics Directive transposition deadlines.
- Wraps:Stretch and shrink films secure palletized loads across Spain's fragmented fresh food distribution network, with Castilla y León waste authority tendering delays constraining post-consumer recyclate availability for closed-loop reprocessing investments.
Films hold installed capacity. Pouches are rotating up the share rankings.
End Use Industry:
Customer sector concentration shapes certification requirements and technical specifications for barrier performance.
- Food & Beverage:Perishable protein and fresh produce applications drive polyethylene volume demand, with blown film extrusion advances reducing material thickness while preserving oxygen and moisture barriers. Basque Country retail chains are expanding pre-packaged produce lines with standardized collection streams aligned to EPR recovery targets.
- Healthcare:Barcelona's dense pharmaceutical manufacturing corridor generates concentrated demand for high-barrier blister lidding with AENOR certification for unit-dose packaging, where Constantia Flexibles maintains specialized production assets.
- Personal Care:Shaped pouches with premium graphics are displacing standard tube and bottle formats, with digital printing enabling batch-level traceability and seasonal promotional cycles without gravure cylinder lead times.
- Chemicals:Industrial flexible intermediate bulk containers and drum liners require chemical resistance specifications governed by EU REACH compliance frameworks for hazardous material containment.
Food & Beverage anchors volume throughput. Healthcare is climbing the fastest on margin contribution.
Material:
Polymer chemistry determines processing equipment requirements and end-of-life pathway economics under Spain's deepening EPR framework.
- Polyethylene:Naphtha-derived LDPE and LLDPE resins occupy the largest volume share in Iberian grocery supply chains, though Mediterranean refinery output volatility squeezes margin pools for converters serving high-turnover applications without long-term feedstock contracts.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate formulations from Castilla-La Mancha polymer research clusters represent the steepest expansion trajectory, with retailer-enforced compostable mandates for fruit and vegetable overwrap redirecting procurement toward certified films despite 12-18 month AENOR validation cycles.
- Polypropylene:Cast film and oriented structures deliver clarity and heat resistance for microwaveable and retort applications, with existing extrusion lines requiring temperature control upgrades for bioplastics compatibility.
- Polyvinyl Chloride:Pharmaceutical blister and medical device packaging maintains specialized demand despite environmental pressure, with AENOR food-contact approvals constraining formulation flexibility.
Polyethylene dominates installed extrusion capacity. Bioplastics is gaining share fastest on regulatory mandate velocity.
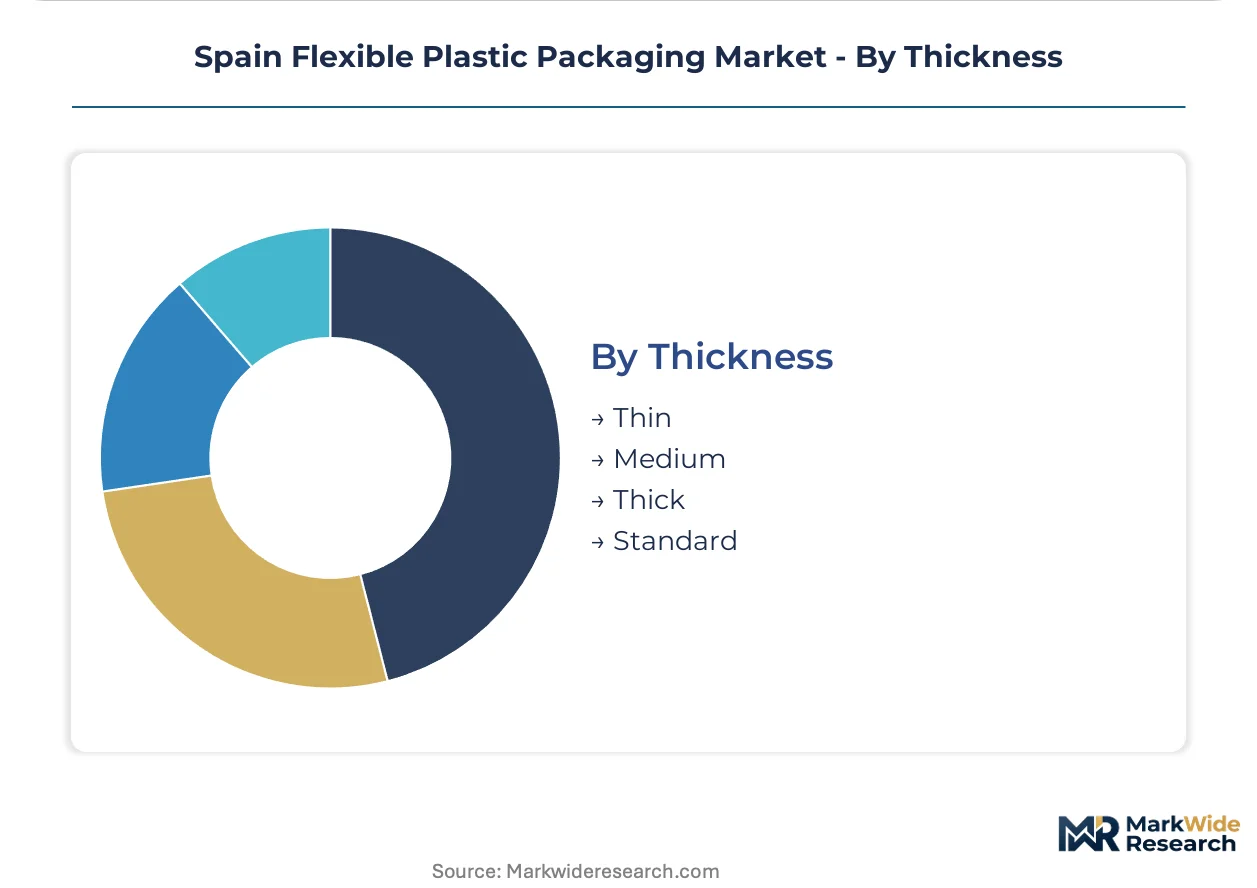
Thickness:
Gauge specification correlates directly with barrier performance requirements and material cost optimization strategies.
- Thin:Sub-50 micrometre structures serve lightweight carrier bag and overwrap applications where EU Single-Use Plastics Directive enforcement is accelerating substitution mandates, compelling validation of home-compostable alternatives.
- Medium:50-150 micrometre films balance cost efficiency with functional performance for standard produce and bakery packaging across Catalonia's retail corridor.
- Thick:Above-150 micrometre specifications protect fresh protein and industrial chemical applications requiring puncture resistance and extended shelf-life extension.
- Standard:Conventional gauge ranges without precise micrometre targeting serve commodity segments where price sensitivity overrides technical optimization.
Medium gauges hold the broadest installed capacity base. Thin specifications are rotating up the share rankings on lightweighting mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters around Madrid and Barcelona, with polymer feedstock access and retail procurement proximity determining regional competitive intensity across Iberian production networks.
Catalonia
Fresh food retail chains in Barcelona and Girona are expanding pre-packaged produce lines with standardized collection streams. The regional waste authority enforces packaging waste recovery targets aligned to Spain's national EPR framework. Terrassa hosts specialized pharmaceutical blister lidding production serving the dense healthcare manufacturing corridor.
Basque Country
Retail chains headquartered in Bilbao and San Sebastián are driving demand for high-barrier protein packaging with extended shelf-life specifications. The Basque government's circular economy programs subsidize mechanical recycling infrastructure investments. Vitoria-Gasteiz anchors blown film extrusion capacity for perishable goods distribution.
Madrid
The capital's consolidated retail procurement desks are displacing fragmented regional distributor networks through vendor-managed inventory arrangements. Spain's central bank monitors packaging sector consolidation patterns as EPR cost burdens reshape mid-tier converter economics. Alcalá de Henares concentrates digital printing capacity for promotional packaging cycles.
Andalusia
Citrus export packaging from Valencia and Seville increasingly specifies stand-up pouches for portion-controlled juice concentrates. Regional waste authority tendering delays constrain sorted flexible film availability for reprocessing investments. Málaga-based converters are validating home-compostable alternatives under AENOR protocols.
Castilla-La Mancha
Polymer research clusters in Albacete and Toledo are redirecting procurement toward certified compostable films for single-serve portions. AENOR certification requirements govern material approvals for food-contact applications. Ciudad Real hosts pilot production lines for polylactic acid formulations.
Spain Flexible Plastic Packaging Market Competitive Landscape
Integrated multi-nationals and specialized regional converters split the market between scale-driven commodity supply and certified niche applications. Three archetypes dominate: global packaging conglomerates with Iberian manufacturing networks, mid-tier converters serving single regional retail chains, and research-cluster spin-offs commercializing bioplastics formulations. M&A activity concentrates among EPR compliance service providers, while capacity expansion targets certified compostable film lines.
Within the integrated multinational tier, Amcor Plc and Mondi PLC exemplify scale-driven positioning across film-to-pouch production. Constantia Flexibles occupies a specialized position anchored to pharmaceutical packaging certification requirements. These three entities represent divergent strategic pathways: commodity volume leadership, hybrid fiber-plastic innovation, and regulatory-intensive healthcare specialization.
| Leading Market Players |
|---|
| Amcor Plc |
| Constantia Flexibles |
| Mondi PLC |
| IFLEX FLEXIBLE PACKAGING SA |
| COVINIL SA |
| Emsur |
| Belca SA |
| Berry Global Inc. |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Castilla-La Mancha's polymer research clusters concentrate certified compostable film capacity, concentrating pricing power among AENOR-validated suppliers while naphtha-derived polyethylene converters absorb Mediterranean refinery volatility. Mercadona's consolidated procurement desk extracts volume discounts from standard film producers, compressing margins for undifferentiated commodity supply.
Pricing Analysis
Spain's national packaging waste regulations dictate the pricing tier structure across flexible formats, with EPR compliance costs stratifying supply into premium-certified compostable films, mid-tier recyclable polyethylene, and economy-grade virgin resin products. Price differentiation rests on AENOR certification status and volume scale, with certified bioplastics commanding substantial premiums over conventional films. Pricing pressure stems from polyethylene feedstock volatility linked to Mediterranean refinery output fluctuations. High-turnover produce and bakery applications exhibit acute price sensitivity, while pharmaceutical blister lidding buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Naphtha-derived resins draw from Mediterranean refinery complexes in Spain, Italy, and Greece, with polymer feedstock flows concentrating around Barcelona and Tarragona petrochemical hubs. Key inputs include low-density polyethylene, linear low-density polyethylene, and emerging polylactic acid formulations from Castilla-La Mancha pilot lines. Single-source vulnerability characterizes bioplastics feedstock availability as AENOR validation cycles constrain qualified supplier pools. Distribution runs through vendor-managed inventory arrangements with direct-to-store delivery obligations imposed by consolidated retail procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compostable film production capability represents the critical scarcity asset, with AENOR validation timelines and temperature-precision extrusion equipment creating defendable competitive moats. Incumbents possessing validated capacity can extract premium positioning while converters lacking certification face margin compression.
For Market Incumbents: Insulate market position by accelerating AENOR certification investments for polylactic acid and polyhydroxyalkanoate formulations before retailer mandates harden, and secure backward integration into Castilla-La Mancha polymer research partnerships to lock in feedstock priority. Threat substitution from kraft-plastic hybrid formats demands defensive capacity in fiber-reinforced flexible structures. For New Entrants and Emerging Players: Pursue pharmaceutical blister lidding specialization within Barcelona's healthcare manufacturing corridor, where AENOR certification requirements and high-barrier technical specifications deter commodity competition. The personal care shaped pouch segment offers penetrable white space through digital printing-enabled format differentiation without gravure cylinder capital requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors research-cluster spin-offs with validated compostable formulations and established retail offtake relationships. Long-term viability hinges on EPR framework deepening and bioplastics mandate expansion rather than polyethylene commodity cyclicality. Monitor Castilla y León and Andalucía regional waste authority tendering outcomes as inflection indicators for mechanical recycling feedstock economics.| Strategic Initiative | Industry Significance |
|---|---|
| AENOR Certification Investment | Validates compostable film claims for Mercadona and Carrefour España procurement compliance. |
| Backward Integration into Bioplastics Feedstock | Secures priority supply from Castilla-La Mancha polymer research clusters amid capacity constraints. |
| Digital Printing Capability Expansion | Enables 48-hour graphic changeovers for Catalonia fresh produce promotional cycles without cylinder lead times. |
| Pharmaceutical Blister Lidding Specialization | Captures high-margin unit-dose demand from Barcelona's dense healthcare manufacturing corridor. |
| Regional Waste Authority Partnership | Positions for sorted flexible film feedstock access as Castilla y León tendering resolves. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association data, and industry publications, combining structured interviews with packaging procurement managers, converter operations directors, polymer research cluster leads, and regional waste authority officials. Secondary validation draws from AENOR certification databases, EU REACH compliance registries, Spain's central bank consolidation monitoring, and national packaging waste recovery statistics. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across material and format segments.
Forecast inputs incorporate blown film extrusion efficiency trajectories, bioplastics mandate enforcement timelines, and EPR cost pass-through elasticity across the projection horizon. Segmentation dimensions span product type, end-use industry, material chemistry, and thickness specification, with regional clustering by autonomous community. CAGRs derive from installed capacity utilization trends and substitution elasticity between conventional polyethylene and certified compostable alternatives. Feedstock volatility indices and retailer procurement consolidation patterns inform scenario-weighted outcomes.
Macroeconomic conditions sit as an overlay; deviation in Mediterranean refinery output, eurozone consumer spending, or EU packaging directive enforcement intensity would shift the trajectory. Forecasts reflect assumptions around AENOR validation cycle durations and regional waste infrastructure investment schedules. Cross-checking against EU packaging waste recovery statistics and Iberian converter capacity utilization surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
United States Flexible Plastic Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Industrial Flexible Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Egypt Flexible Plastic Packaging Market
Flexible Packaging
Saudi Arabia Flexible Packaging Market
Flexible Packaging
Europe, Middle East and Africa (EMEA) Flexible Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
North America Flexible Plastic Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Asia Pacific Single-Use Packaging Market