
 Sterilization Tape Market | 2026-2036
Sterilization Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Tape Market Analytics
Skilled sterile processing technicians is collapsing across North American hospital systems, forcing facilities to standardize on indicator-integrated tapes that reduce human verification errors. 3M leverages its adhesive chemistry portfolio to supply steam and ethylene oxide compatible tapes with built-in color-change chemistry. Medline Industries anchors its position through direct distribution contracts with integrated delivery networks, while Cardinal Health competes by bundling sterilization consumables into procedural kits that lower procurement overhead for under-staffed central sterile departments.
Sterilization tape denotes pressure-sensitive adhesive strips incorporating chemical indicators that undergo visible color transition when exposed to defined sterilization parameters such as steam temperature, ethylene oxide concentration, or gamma radiation dose; substrates include polypropylene, polyester, and paper backings coated with lead-free indicator inks. The product serves to seal wrapped surgical instrument sets and autoclave packs while providing immediate visual confirmation that sterilization conditions were achieved, eliminating unwrapped use of potentially contaminated tools. Polypropylene-backed tapes dominate hospital procurement due to superior tensile strength during high-temperature steam cycles, while silicone adhesive formulations capture growing share in pharmaceutical cleanrooms where residue-free removal protects packaging integrity. Steam indicator technology remains the volume anchor, though radiation-compatible tapes for medical device manufacturers represent the fastest-expanding margin pool as gamma and e-beam sterilization displaces ethylene oxide amid EPA emission scrutiny.
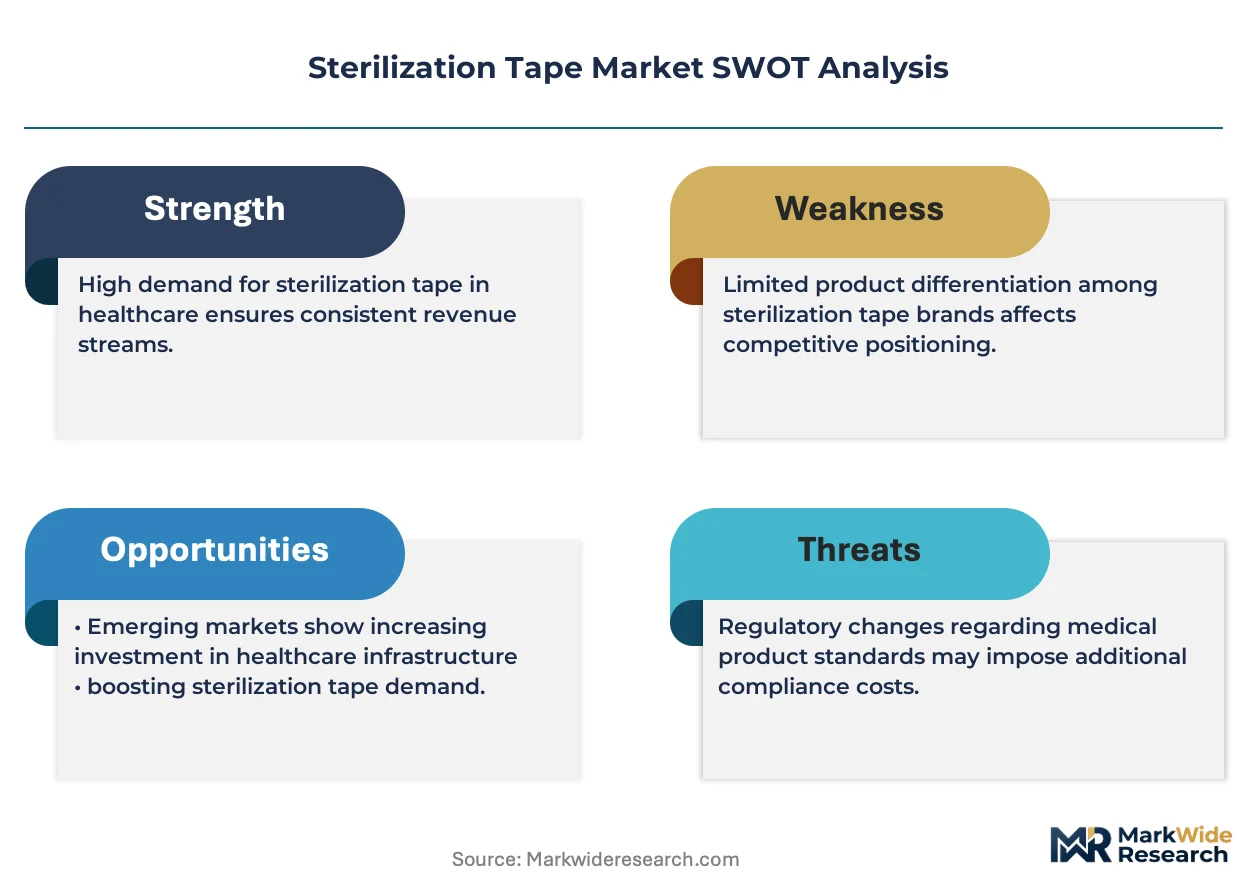
FDA enforcement of 21 CFR 880.2800 for surgical instrument sterilization accessories shapes product validation requirements, while ISO 11140-1 Type 1 indicator standards govern color-change performance thresholds that determine market access for tape suppliers. EPA regulation of ethylene oxide sterilization emissions is forcing tape manufacturers to validate indicator chemistry across alternative modalities, including vaporized hydrogen peroxide and nitrogen dioxide systems. Stakeholders must monitor whether FDA moves to mandate digital sterilization logging, which would either obsolete simple visual-indicator tapes or create hybrid product categories combining chemical and electronic confirmation.
Market Dynamics
Central sterile processing departments are consolidating purchasing authority across integrated delivery networks, compressing vendor counts and forcing tape suppliers to validate multi-modality indicator chemistry as facilities diversify sterilization methods beyond steam.
Growth Catalysts
- ASC Volume Expansion:Ambulatory surgical centers in the United States are expanding procedure throughput, driving bulk tape procurement for wrapped instrument sets.
- ISO 11140-1 Type 1 Mandates:International standardization of chemical indicator performance thresholds is eliminating non-compliant suppliers from hospital formularies.
- Gamma Sterilization Migration:Medical device manufacturers are abandoning ethylene oxide for radiation-based sterilization, creating demand for radiation-compatible indicator tapes.
Market Restraints
- Ethylene Oxide Feedstock Volatility:EPA emission restrictions on EtO sterilization facilities are forcing tape manufacturers to reformulate indicator chemistry, raising R&D overhead.
- Polypropylene Supply Concentration:Substrate sourcing depends on Gulf Coast petrochemical complexes, exposing converters to hurricane-driven production interruptions.
- Indicator Ink Substitution:Lead-free color-change formulations face performance gaps against legacy lead-based chemistry in high-humidity steam cycles.
Strategic Opportunities
- Vaporized Hydrogen Peroxide Compatibility:Low-temperature sterilization adoption in endoscopy suites creates white space for indicator tapes validated to VH2O2 parameters.
- Digital Sterilization Logging Mandates:FDA exploratory guidance on electronic sterilization records could hybridize chemical-indicator tapes with RFID or barcode integration.
- Pharmaceutical Cleanroom Expansion:Silicone-adhesive residue-free tapes are capturing share in aseptic fill-finish operations where packaging integrity demands clean removal.
Industry Challenges
- Sterile Processing Technician Shortage:Collapsing pipeline of certified technicians is forcing facilities to rely on error-prone manual verification rather than indicator-integrated automation.
- Multi-Modality Validation Timelines:Cross-certification of indicator chemistry across steam, gamma, and VH2O2 protocols extends FDA 510(k) clearance cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Tape Market |
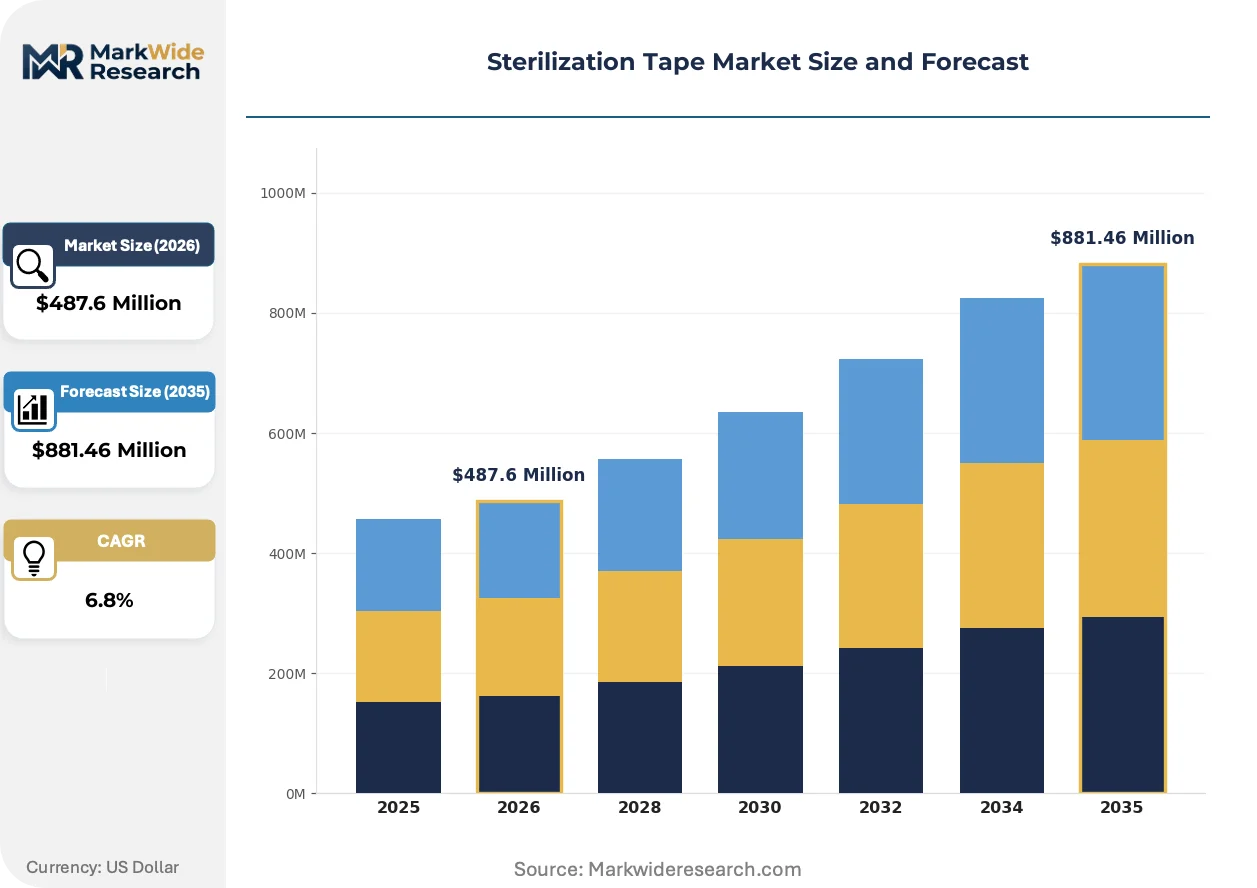
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Paper, Silicone Technology: Steam, Ethylene Oxide, Radiation, Dry Heat End User: Hospitals, Clinics, Laboratories, Pharmaceuticals Application: Instruments, Packaging, Medical Devices, Others |
| Companies Covered | Propper Manufacturing Co., Inc., Medline Industries, 3M, Cardinal Health, GKE GmbH, STERIS plc, Healthmark Industries Company, Inc., Paul Hartmann AG, Advanced Sterilization Products (ASP), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Tape Market Evolving Landscape
Indicator chemistry is converging with digital traceability systems as regulators explore electronic sterilization records, while substrate engineering advances address residue and tensile demands across divergent sterilization modalities.
Gamma and e-beam compatible indicator tapes are displacing ethylene oxide-validated products in medical device manufacturing cleanrooms. Sterilization service providers are accelerating radiation-based contracts as EPA emission scrutiny tightens around EtO facilities. This displacement is compressing demand for multi-modality indicator formulations that span both legacy and emerging sterilization platforms.
EPA enforcement of ethylene oxide emission limits under the Clean Air Act is forcing sterilization facilities to validate alternative modalities. Tape manufacturers must now certify color-change performance across vaporized hydrogen peroxide and nitrogen dioxide parameters. Pharmaceutical and device manufacturers with EtO-dependent supply chains are most affected, accelerating dual-validation programs for indicator-integrated sealing products.
Integrated delivery networks are consolidating sterile processing procurement into centralized contracting offices that bundle tapes with wraps, pouches, and biological indicators. Independent hospitals and smaller ASCs are losing direct vendor negotiation leverage as purchasing authority migrates to IDN supply chain executives. This concentration is most visible in the United States, where Catholic health systems and for-profit chains now control majority tape volume.
Sterilization Tape Market Segmentation
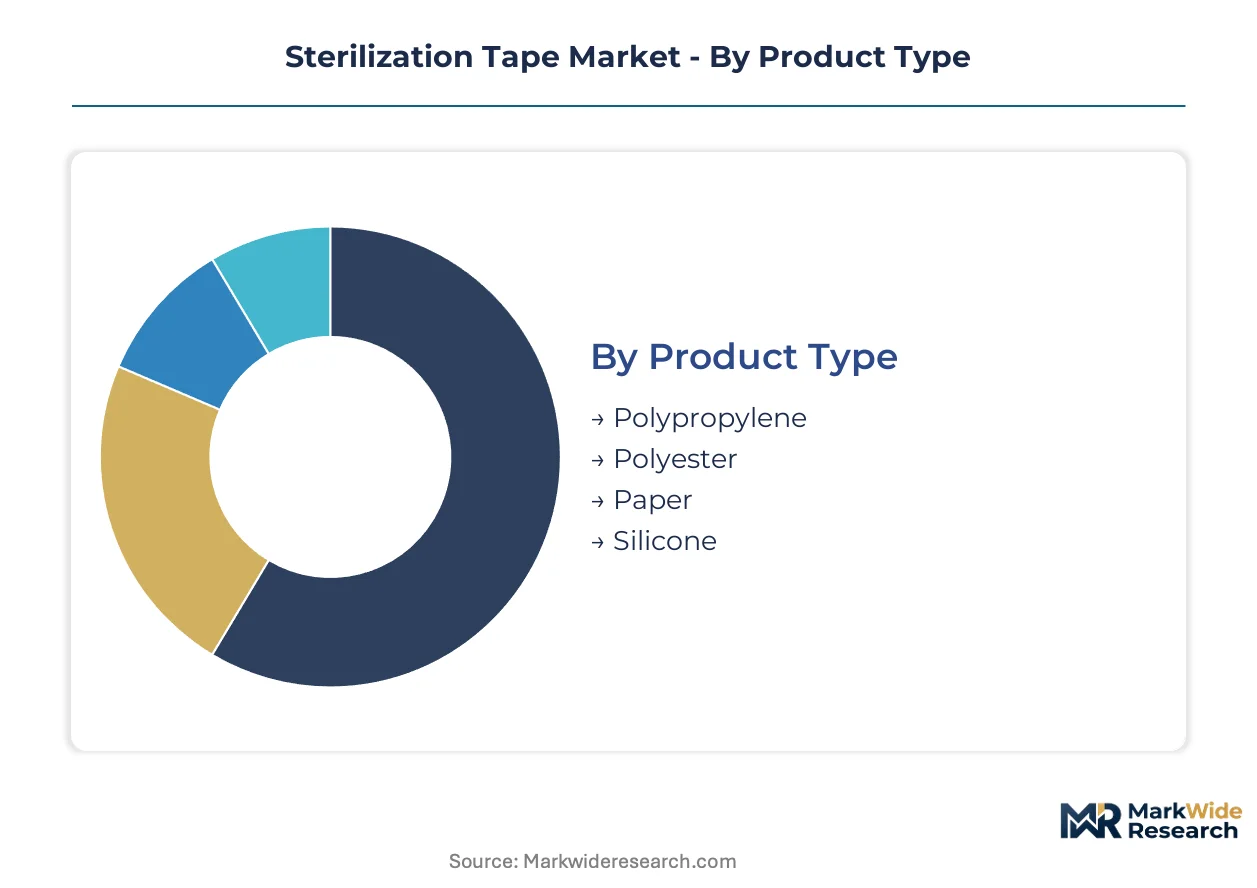
Sterilization tape procurement patterns diverge sharply across substrate chemistry, sterilization modality, and end-use facility type. Understanding these segment boundaries clarifies why suppliers must maintain multi-modality validation portfolios to serve consolidated health system buyers.
Product Type:
Domestic hospital procurement concentrates on polypropylene and paper substrates, while polyester and silicone formulations capture export-led demand from pharmaceutical manufacturers in Germany, Japan, and Switzerland.
- Polypropylene:High-tensile synthetic backing withstands steam autoclave cycles without deformation. United States hospital systems drive volume through centralized sterile processing departments that prioritize durability during instrument set wrapping.
- Paper:Cellulose-based substrate with porous structure suited for steam penetration indicators. Cost-sensitive clinics in India and Southeast Asia favor this grade for single-use instrument packaging where disposal economics matter.
- Polyester:Dimensionally stable film backing resists shrinkage across gamma and e-beam radiation exposure. Medical device manufacturers in Germany and Japan specify this substrate for cleanroom sealing applications.
- Silicone:Residue-free adhesive system enables clean removal from pharmaceutical packaging without surface contamination. Aseptic fill-finish operations in Switzerland and Ireland are expanding procurement of this premium grade.
Polypropylene commands the established base. The steepest expansion runs through silicone.
Technology:
Steam indicator chemistry anchors high-volume hospital procurement, while radiation-compatible formulations serve export-oriented medical device manufacturing clusters.
- Steam:Temperature-sensitive dyes transition at 121°C or 134°C to confirm saturated steam exposure. United States ASCs and hospital sterile processing departments standardize on this technology for wrapped surgical instrument sets.
- Ethylene Oxide:Color-change chemistry responds to EtO concentration and humidity parameters. EPA emission restrictions are compressing domestic demand, though legacy device sterilization facilities in Mexico and Eastern Europe maintain procurement.
- Radiation:Gamma and e-beam compatible indicators undergo visible transition at specified dose thresholds without thermal dependency. Contract sterilization providers in Belgium and the Netherlands are accelerating validation of this modality.
- Dry Heat:High-temperature indicators for 160-180°C depyrogenation cycles. Pharmaceutical glassware sterilization in France and Italy sustains niche demand for this chemistry.
Steam technology retains volume leadership. Radiation indicators are climbing the fastest as EtO displacement accelerates.
End User:
Hospital procurement dominates domestic volume, while pharmaceutical and laboratory segments concentrate in export markets with stringent cleanroom requirements.
- Hospitals:Central sterile processing departments and surgical suites consume indicator-integrated tapes for daily instrument reprocessing. United States integrated delivery networks bundle this procurement with wraps and biological indicators.
- Clinics:Outpatient surgical centers and physician offices purchase lower-volume tape quantities for minor procedure sets. Cost pressure drives preference toward paper-backed steam indicators.
- Laboratories:Research and diagnostic facilities require validated sealing for culture media and biological samples. Academic medical centers in the United Kingdom and Australia specify multi-modality indicator compatibility.
- Pharmaceuticals:Aseptic manufacturing operations demand residue-free silicone adhesive tapes for vial and syringe packaging. Cleanroom expansion in Ireland and Singapore is expanding this segment.
Hospitals anchor procurement volume. Pharmaceutical cleanroom applications are gaining share fastest.
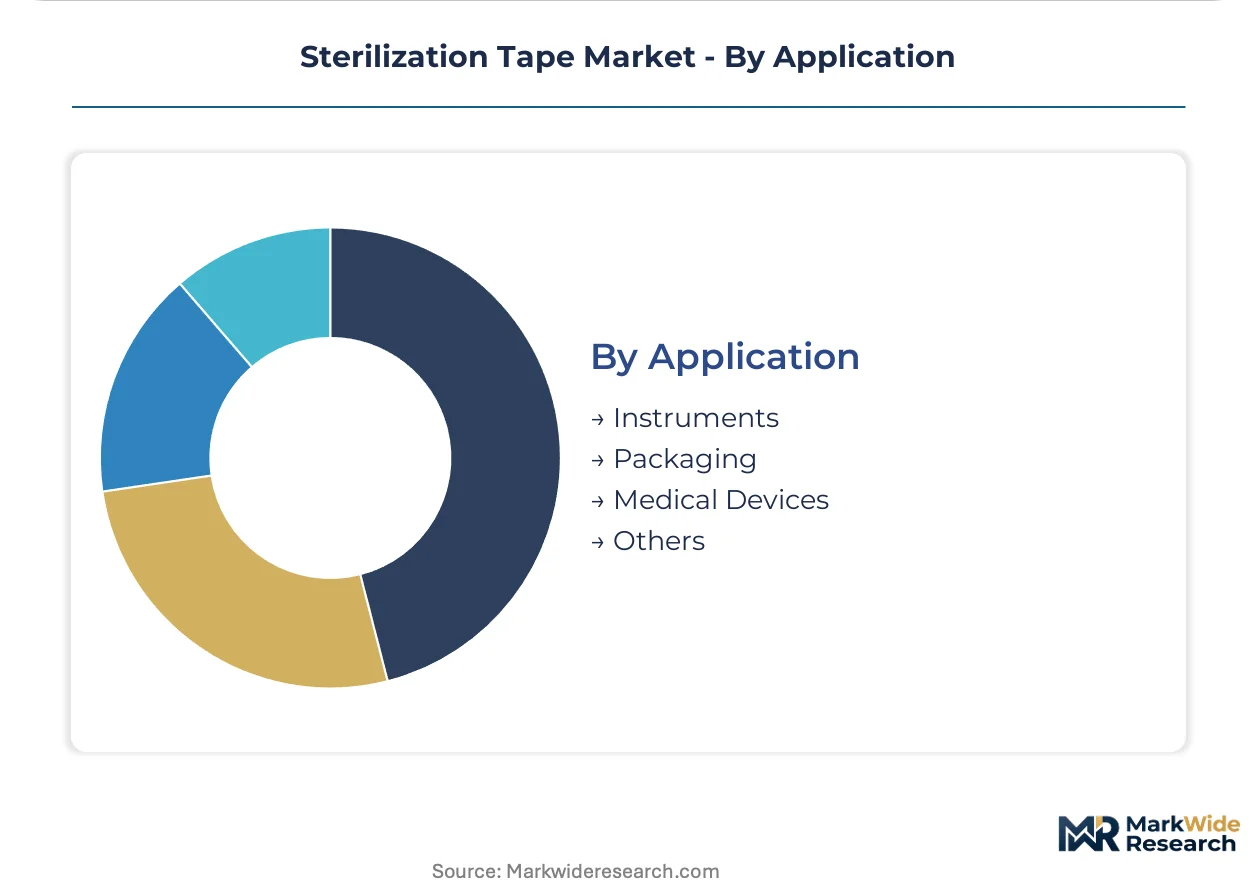
Application:
Instrument sealing concentrates in domestic healthcare facilities, while medical device and packaging applications serve global manufacturing supply chains.
- Instruments:Surgical tool set wrapping and autoclave pack sealing constitute the core use case. United States hospital sterile processing departments validate tape performance against AAMI ST79 guidelines.
- Packaging:Sterile barrier system sealing for pharmaceutical and device primary packaging. Export-oriented manufacturers in Germany and Switzerland drive specification of radiation-compatible indicator tapes.
- Medical Devices:Implantable and single-use device sterilization validation. Contract sterilization providers in Belgium and the Netherlands are transitioning EtO-dependent device lines to radiation protocols.
- Others:Dental instrument reprocessing and veterinary surgical applications. Smaller volume markets with localized regulatory requirements.
Instrument applications command the established base. Medical device sealing is expanding most quickly as gamma sterilization displaces ethylene oxide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterilization tape consumption patterns diverge sharply by geography. United States hospitals prioritize polypropylene-backed steam indicators for high-volume surgical reprocessing, while European pharmaceutical clusters specify silicone-adhesive residue-free grades for cleanroom packaging integrity.
United States
Ambulatory surgical centers and integrated delivery networks drive bulk procurement of steam-compatible indicator tapes. FDA enforcement of 21 CFR 880.2800 shapes validation requirements for surgical instrument sterilization accessories. Centralized sterile processing departments in Texas and Florida health systems are consolidating vendor contracts with multi-modality chemistry suppliers.
Germany
Medical device manufacturers in Baden-Württemberg and Bavaria specify radiation-compatible polyester-backed tapes as gamma sterilization displaces ethylene oxide. ECHA REACH compliance governs lead-free indicator ink formulations entering the European market. The Stuttgart industrial cluster hosts contract sterilization providers accelerating e-beam validation programs for implantable device packaging.
Japan
Pharmaceutical cleanrooms in Osaka and Tokyo demand silicone-adhesive tapes with residue-free removal for aseptic fill-finish operations. METI industrial standards guide chemical indicator performance thresholds for export-oriented device manufacturers. The Kansai region's precision instrument sector is expanding procurement of multi-parameter validation tapes for hybrid sterilization workflows.
Switzerland
Swissmedic regulations enforce stringent documentation requirements for sterilization process indicators used in pharmaceutical primary packaging. Basel's biologics manufacturing corridor specifies premium-grade silicone tapes for vial and syringe sealing applications. The country's device sterilization service providers are diversifying into vaporized hydrogen peroxide modalities requiring revalidated indicator chemistry.
India
Cost-sensitive clinics and mid-tier hospitals in Maharashtra and Karnataka favor paper-backed steam indicators for single-use instrument packaging. CDSCO import regulations govern chemical indicator tape registration for foreign suppliers entering the domestic market. The Pune-Ahmedabad manufacturing belt hosts emerging converters developing lead-free ink formulations for regional export markets.
Sterilization Tape Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on modality-specific validation and substrate engineering. The upper tier controls adhesive chemistry platforms and direct distribution contracts with consolidated health systems. The specialist tier fragments across regional converters, cleanroom-focused material suppliers, and sterilization service providers with captive tape lines. Competitive moves center on multi-modality indicator certification and bundling sterilization consumables into procedural kits that reduce procurement overhead for understaffed central sterile departments.
Within the integrated leader tier, 3M and Cardinal Health exemplify archetypes of chemistry-platform and distribution-bundling dominance respectively. Medline Industries occupies a position between these models, anchoring its presence through direct contracts with integrated delivery networks. GKE GmbH represents the European specialist archetype, sitting within the radiation-validation segment as gamma and e-beam modalities accelerate.
| Leading Market Players |
|---|
| Propper Manufacturing Co., Inc. |
| Medline Industries |
| 3M |
| Cardinal Health |
| GKE GmbH |
| STERIS plc |
| Healthmark Industries Company, Inc. |
| Paul Hartmann AG |
| Advanced Sterilization Products (ASP) |
| Others |
Value Network & Pricing Analysis
Lead-free indicator ink substitution for legacy lead-based chemistry simultaneously relocates formulation expertise toward REACH-compliant European converters and compresses margin structures for Gulf Coast-dependent substrate suppliers. This dual displacement concentrates pricing power with adhesive chemistry specialists while exposing polypropylene-backed tape producers to petrochemical volatility.
Pricing Analysis
Long-term offtake contracts between integrated delivery networks and multi-modality tape suppliers dominate procurement, though spot purchasing persists among independent ambulatory surgical centers. Pricing stratifies across FDA-validated premium tiers, ISO-certified standard grades, and economy paper-backed alternatives, with certification level and volume scale as primary differentiation drivers. Cost compression in economy tiers is intensifying because CDSCO-registered imports from Indian converters are expanding regional supply. Independent clinics exhibit highest price sensitivity, while pharmaceutical cleanroom operators accept substantial premiums for residue-free silicone formulations.
Supply Chain Analysis
Gulf Coast petrochemical complex concentration exposes polypropylene substrate flows to hurricane-driven production interruptions. Raw material sourcing draws from Saudi Arabian propylene feedstock, German specialty chemical indicator plants, and Chinese lead-free ink precursor manufacturers. Single-source vulnerability concentrates in FDA-registered adhesive chemistry suppliers holding 510(k) master files. Distribution runs through GPO-anchored warehouse networks serving consolidated health systems, with direct-to-hospital fulfillment gaining share among IDN central sterile departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization tape procurement is evolving into a service-attach opportunity as sterilization process validation consulting and technician training subscriptions expand faster than consumables volume. This recurring-revenue layer commands superior retention economics versus transactional tape sales.
For Market Incumbents: Fortify multi-modality validation portfolios against gamma sterilization displacement of ethylene oxide protocols by accelerating vaporized hydrogen peroxide indicator certification. Deepen backward integration into lead-free ink precursor manufacturing to offset REACH compliance cost inflation. Channel control through exclusive GPO contracts protects share against regional converter encroachment.
For New Entrants and Emerging Players: Lead with vaporized hydrogen peroxide-compatible indicator tapes targeting endoscopy suite sterilization workflows, the most penetrable white space given FDA exploratory guidance momentum. Pharmaceutical cleanroom silicone-adhesive applications in Singapore and Ireland offer secondary expansion terrain. A technical-specialist direct sales model outperforms distributor reliance for cleanroom qualification support.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sterilization service providers holding captive tape lines and regional indicator chemistry specialists with radiation-validation expertise. Long-term viability hinges on digital sterilization logging regulatory trajectory and EtO displacement velocity. Watch FDA guidance publication on electronic sterilization records as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Vaporized Hydrogen Peroxide Validation | FDA 510(k) clearance for VH2O2 indicators captures endoscopy suite procurement ahead of competitors. |
| Digital Sterilization Logging Partnership | RFID-barcode hybrid tape development with hospital IT systems creates recurring software revenue attachment. |
| Silicone Adhesive Capacity Expansion | Cleanroom-grade residue-free tape production in Ireland serves Basel biologics corridor demand growth. |
| Lead-Free Ink Backward Integration | In-house precursor manufacturing defends margin compression from ECHA REACH compliance cost inflation. |
| IDN Direct Distribution Contract | Exclusive supply agreements with Catholic health systems and for-profit chains lock out regional competitors. |
Research Methodology
Cross-validation between sterile processing technician interviews and sterilization service provider procurement databases anchors the qualitative findings. Primary fieldwork encompassed central sterile department managers, biomedical equipment technicians, GPO contracts administrators, and pharmaceutical cleanroom operations leads. Secondary validation drew from FDA 510(k) device classification databases, ISO 11140-1 technical committee documentation, EPA ethylene oxide emission enforcement records, and hospital procurement system contract disclosures. Bottom-up tape volume modeling triangulated against top-down healthcare expenditure allocation estimates.
Sensitivity analysis across steam-to-radiation modality transition scenarios and technician shortage severity assumptions stress-tested projection robustness. Segmentation modeling spanned substrate chemistry, sterilization technology, end-user facility type, and geographic regulatory cluster dimensions. CAGRs derived from surgical volume recovery trajectories, ASC expansion pipelines, and sterilization modality shift elasticity coefficients. Industry-specific inputs included AAMI ST79 guideline revision timelines and EPA EtO facility closure announcements.
Forecasts assume regulatory continuity in FDA 21 CFR 880.2800 enforcement and ECHA REACH chemical restrictions; material policy shifts would require re-modeling. Sterile processing technician training pipeline recovery, gamma sterilization capacity buildout delays, and digital sterilization logging mandate timing constitute primary revision triggers. Revision becomes warranted when VH2O2 sterilization adoption crosses threshold penetration in United States hospital endoscopy suites.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Shipping Tapes Market
Tapes
ESD Tapes and Labels Market
Tapes
Dicing Tapes Market
Tapes
PVC Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Heat Activated Tear Tape Market
Tapes
Gummed Tapes Market
Tapes
Global Construction Tape Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Acoustic Tape Market
Tapes
Building and Construction Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Heat Release Tape Market
Tapes
Umbilical Tapes Market
Tapes
Hand Wrappers Market
Tapes
Packaging Tapes Market