
 Labels, Tapes and Films Market | 2026-2036
Labels, Tapes and Films Market Size, Share, and Industry Trends Forecast 2026-2036
Labels, Tapes and Films Market Analysis
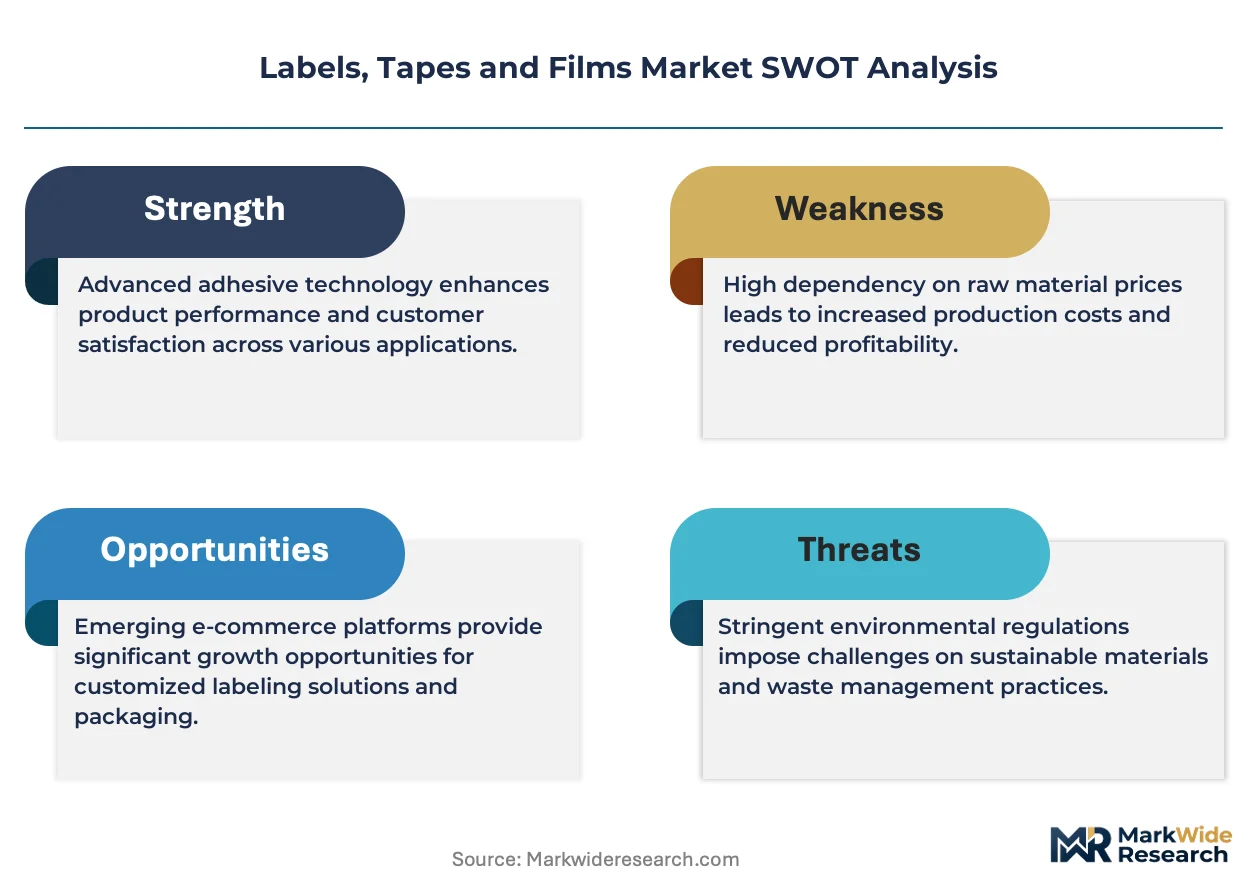
Modular packaging configurations are expanding buyer choice across the labels, tapes and films landscape. 3M leverages its adhesive chemistry portfolio to dominate industrial tape segments with high-temperature and electrical specialization. Avery Dennison anchors global pressure-sensitive label supply through extensive substrate innovation and regional manufacturing scale. CCL Industries competes in premium shrink and stretch film applications through dedicated pharmaceutical and beverage packaging divisions.
Labels, tapes and films constitute engineered adhesive substrates and polymeric coatings designed for surface bonding, containment, identification, or protection, typically manufactured through extrusion, coating, or calendering processes with thickness tolerances measured in microns. Their primary purpose spans logistics tracking, product branding, structural reinforcement, and barrier protection across consumer and industrial supply chains. Pressure-sensitive labels and adhesive tapes lead volume contribution due to universal deployment in e-commerce and automotive assembly, while shrink films and stretch films command margin concentration in food and beverage palletization. Polyethylene and polypropylene substrates are displacing PVC in flexible packaging applications as converters respond to sustainability-driven material specifications.
FDA food-contact regulations, EPA chemical substance reporting under TSCA, and REACH substance restrictions in Europe collectively determine substrate eligibility and migration limits for labels and films in consumer-facing applications. China's GB standards and SAMR packaging directives add compliance layers for imported adhesive products entering Asian manufacturing supply chains. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical disclosure requirements to align product development with multi-jurisdictional market access conditions.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery windows, forcing converters to prioritize pressure-sensitive label formats with instant-adhesion and print-on-demand compatibility over conventional pre-printed alternatives.
Growth Catalysts
- CDSCO serialization mandates:India's pharmaceutical regulator requires track-and-trace labels on all exported medicines, creating dedicated demand for tamper-evident pressure-sensitive constructions with variable data printing.
- Polyethylene substrate displacement:Flexible packaging converters are substituting PE films for PVC in food-contact applications to meet EU REACH substance restrictions and brand sustainability specifications.
- Automotive lightweighting:Electric vehicle battery pack assembly relies on high-temperature acrylic adhesive tapes for thermal management and cell-to-cell bonding, pulling specialty tape volumes.
Market Restraints
- Propylene monomer volatility:Polypropylene substrate costs fluctuate with naphtha-cracker economics and regional refinery maintenance cycles, squeezing converter margins without pass-through mechanisms.
- Adhesive raw material concentration:Acrylic and rubber-based tackifier supply clusters in East Asian petrochemical corridors, exposing buyers to shipping disruptions and tariff exposure.
- Migration testing complexity:FDA food-contact notification requirements for new adhesive chemistries extend qualification timelines to 18-24 months, blocking formulation innovation.
Strategic Opportunities
- Biodegradable film substrates:PLA and PHA-based shrink films command 40-60% price premiums in European premium food packaging where EFSA compliance and home-compostability claims differentiate shelf presence.
- Direct-to-film digital printing:UV-inkjet and toner-based production is eliminating plate costs and MOQ constraints, enabling micro-batch label runs for craft beverage and specialty chemical segments.
- Extended producer responsibility frameworks:EU packaging waste directives and state-level US EPR legislation are mandating recyclability-by-design, rewarding converters with certified closed-loop substrate partnerships.
Industry Challenges
- Adhesive formulator talent scarcity:Experienced polymer chemists capable of balancing peel adhesion, shear resistance, and regulatory compliance across temperature ranges command compensation premiums that mid-tier converters cannot match.
- Multi-jurisdiction certification stacking:Simultaneous FDA, REACH, and GB standard compliance requires redundant testing protocols and documentation systems that strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Labels, Tapes and Films Market |
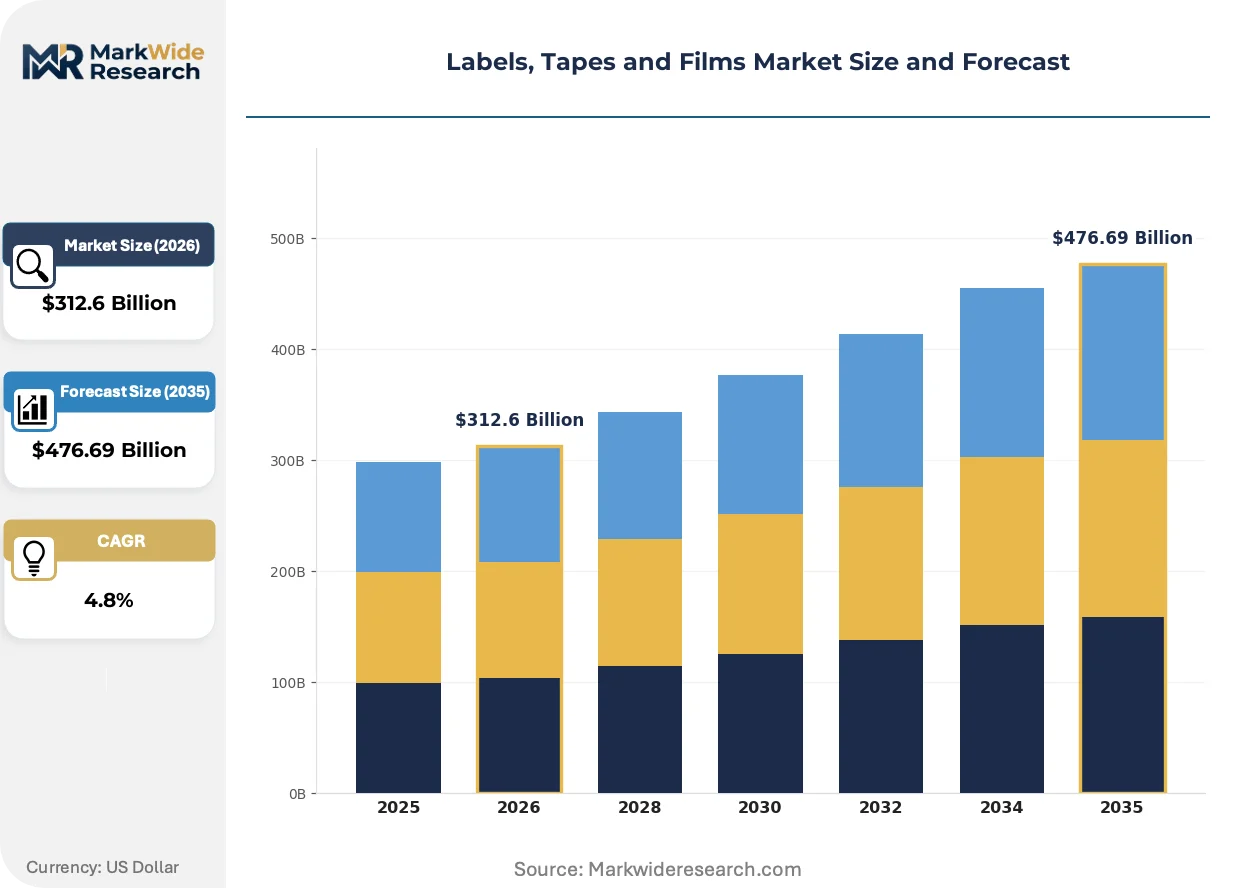
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Adhesive Tapes, Shrink Films, Stretch Films Material: Polyethylene, Paper, PVC, Polypropylene Application: Packaging, Branding, Industrial Use, Consumer Products Distribution Channel: Online Retail, Wholesale, Specialty Stores, Direct Sales |
| Companies Covered | 3M, Avery Dennison, CCL Industries, UPM Raflatac, Nitto Denko Corporation, Lintec Corporation, Tesa SE, Saint-Gobain, Brady Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Labels, Tapes and Films Market Emerging Trajectories
Digital production workflows and bio-based material platforms are converging to redefine converter economics, collapsing minimum order quantities while expanding the addressable market for customized, short-run packaging executions.
Water-based acrylic adhesive formulations are decentralizing label and tape manufacturing by eliminating solvent recovery infrastructure requirements. Regional converters in secondary cities are adopting these chemistries to serve local food processors and logistics hubs without capital-intensive emission controls. This shift is compressing the effective radius of centralized coating operations and enabling distributed production networks.
REACH substance restrictions on phthalate plasticizers and heavy metal pigments are forcing reformulation of legacy PVC shrink films and foil-based decorative laminates. European converters are accelerating migration to polyolefin alternatives and water-based ink systems to maintain market access. The pharmaceutical and premium cosmetics segments are absorbing 15-25% material cost increases to retain CE-marked packaging eligibility.
Brand owners are unbundling label procurement from primary packaging contracts, creating dedicated print-management relationships with specialized converters. Food and beverage multinationals are consolidating label spend under category managers who negotiate master service agreements spanning multiple SKUs and production sites. This concentration is visible across North American CPG supply chains where procurement teams prioritize converters with multi-plant redundancy and digital front-end integration.
Labels, Tapes and Films Market Segmentation
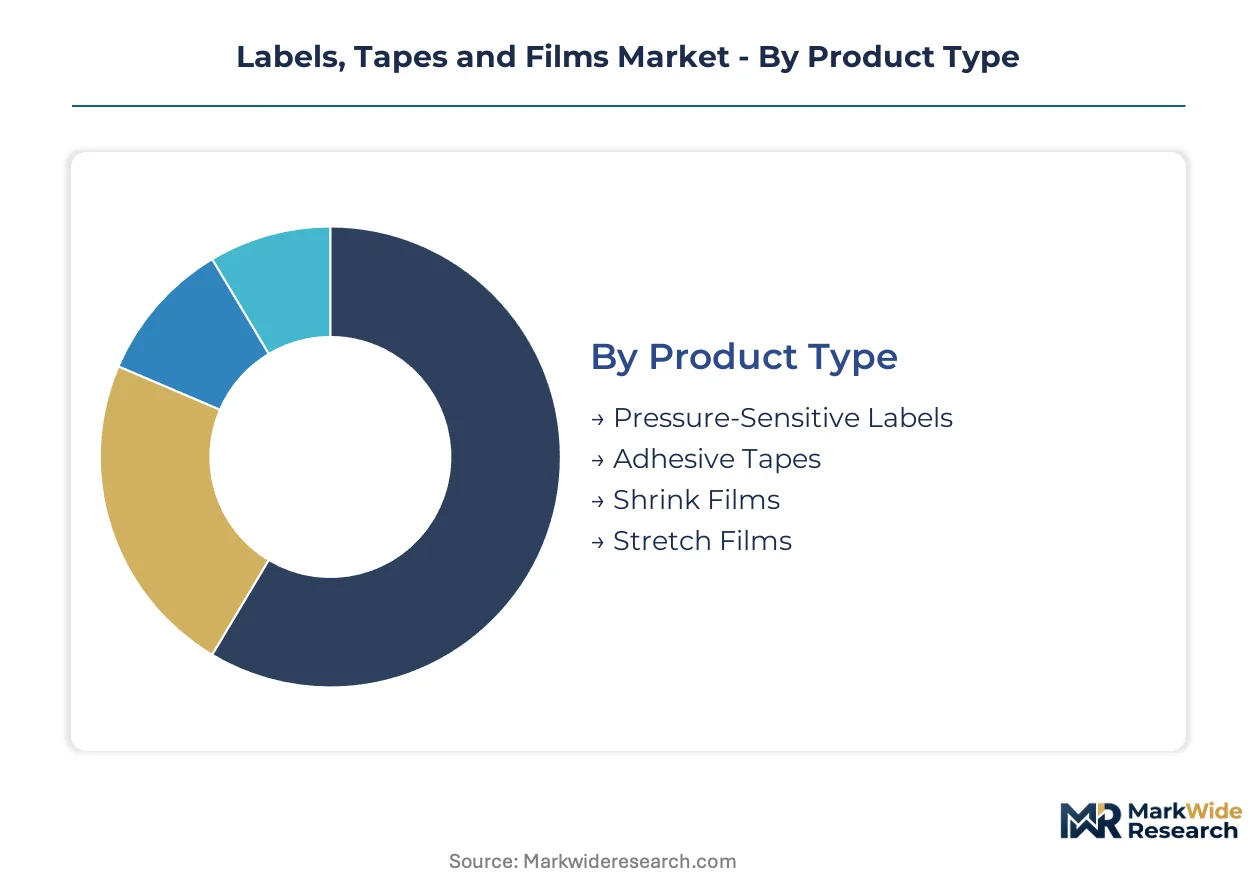
Converters configure production assets around substrate chemistry and adhesion mechanics rather than end-use alone. Segment boundaries in labels, tapes and films reflect capital requirements for coating lines, extrusion equipment, and regulatory certification that lock in competitive positions for years.
Product Type:
Pressure-sensitive label manufacturing demands the heaviest upfront investment in precision coating towers and cleanroom slitting operations, while adhesive tape production scales through simpler hot-melt or solvent-based coating configurations.
- Pressure-Sensitive Labels:Multi-layer constructions combining facestock, adhesive, and release liner require continuous coating lines with micron-level thickness control. Pharmaceutical serialization mandates in India and track-and-trace regulations across European supply chains are concentrating demand for variable-data-capable constructions.
- Adhesive Tapes:Acrylic, rubber, or silicone adhesive films on flexible backings serve automotive assembly and electronics manufacturing. Electric vehicle battery thermal management applications are pulling specialty high-temperature acrylic formulations.
- Shrink Films:Biaxially oriented polyolefin or PVC films that contract under heat application for tight product bundling. Beverage multipacks and premium cosmetics overwraps absorb material cost premiums for EFSA-compliant substrate alternatives.
- Stretch Films:Linear low-density polyethylene cast or blown films for pallet load containment. Logistics consolidation in North American and European distribution centers sustains volume throughput for machine-grade and hand-wrap grades.
Most installed capacity flows through pressure-sensitive labels. Expansion is steepest in adhesive tapes.
Material:
Substrate selection determines converter margin structure through resin index exposure, sustainability certification eligibility, and food-contact compliance burden.
- Polyethylene:Dominant flexible packaging substrate with tunable density grades for clarity, stiffness, and seal performance. REACH-compliant PE formulations are displacing PVC in European food-contact films despite 10-15% material cost premiums.
- Polypropylene:Biaxially oriented films deliver high stiffness-to-weight ratios for label facestocks and overwrap applications. Propylene monomer volatility tied to naphtha-cracker economics squeezes converter margins without pass-through pricing mechanisms.
- Paper:Cellulosic facestocks for beverage labels and direct thermal printing applications. Craft beverage micro-batches and sustainable packaging claims sustain demand despite moisture sensitivity limitations.
- PVC:Legacy shrink film and tape backing material facing phased substitution. Phthalate plasticizer restrictions under REACH and heavy metal pigment bans are accelerating converter migration to polyolefin alternatives.
Polyethylene and polypropylene together anchor substrate throughput. Paper is climbing fastest on sustainability positioning.
Application:
Application segmentation reflects diverging customer technical requirements: packaging demands barrier performance, branding prioritizes print fidelity, industrial use requires environmental durability.
- Packaging:Primary and secondary containment across food, pharmaceutical, and consumer goods supply chains. E-commerce fulfillment compression of delivery windows is forcing adoption of instant-adhesion label formats compatible with print-on-demand workflows.
- Branding:Shelf differentiation through decorative labels, holographic films, and tactile finishes. Unbundling of label procurement from primary packaging contracts is concentrating spend under specialized converters with digital front-end integration.
- Industrial Use:Structural bonding, surface protection, and electrical insulation in manufacturing assembly. Automotive lightweighting and electric vehicle battery pack construction are pulling high-temperature acrylic tape volumes.
- Consumer Products:Household organization, DIY repair, and personal care applications. Retail channel fragmentation between mass merchants and specialty stores shapes SKU proliferation strategies.
Packaging commands the largest share of substrate consumption. Industrial use is expanding most quickly on electrification trends.
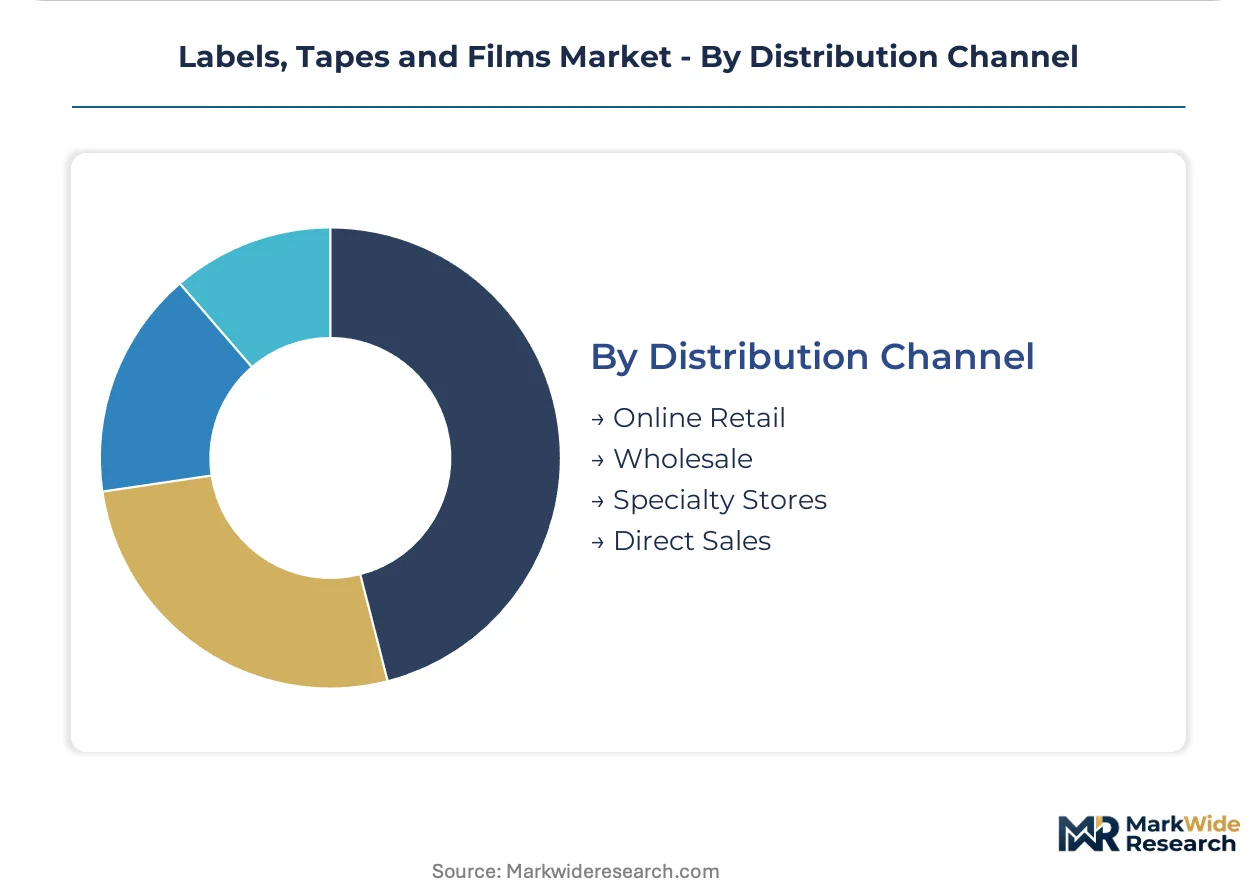
Distribution Channel:
Channel structure determines converter customer acquisition costs, inventory carrying requirements, and technical service intensity.
- Wholesale:Bulk supply to converters, printers, and industrial distributors with volume pricing and technical specification support. Regional distribution hubs in secondary cities are compressing delivery radii for water-based adhesive products.
- Direct Sales:Account-managed relationships with multinational food, beverage, and pharmaceutical brand owners. Master service agreements spanning multiple SKUs and production sites prioritize converters with multi-plant redundancy.
- Online Retail:E-commerce platforms serving small-batch craft producers and maintenance-repair-operations buyers. Digital storefronts enable micro-order quantities that bypass traditional minimum order quantity constraints.
- Specialty Stores:Niche channels for artist supplies, archival materials, and professional-grade adhesive products. Technical consultation and application expertise justify price premiums over mass-market alternatives.
Wholesale channels move the highest substrate tonnage. Online retail is gaining share fastest among small-batch end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The labels, tapes and films industry traces its modern origins to Minnesota Mining and Manufacturing's adhesive tape innovations in the early 20th century United States, with subsequent scaling of pressure-sensitive coating operations across German chemical corridors and Japanese electronics manufacturing zones.
United States
E-commerce fulfillment networks in California and Texas distribution corridors are compressing order-to-delivery windows, forcing adoption of instant-adhesion pressure-sensitive labels. FDA food-contact notification requirements under 21 CFR extend qualification timelines for new adhesive chemistries. The Minneapolis-St. Paul metropolitan area retains legacy coating infrastructure serving industrial tape applications.
Germany
Automotive lightweighting programs in Stuttgart and Munich manufacturing clusters are pulling high-temperature acrylic adhesive tapes for electric vehicle battery assembly. ECHA REACH substance restrictions on phthalate plasticizers are accelerating PVC-to-polyolefin substrate migration. The Rhine-Ruhr industrial corridor hosts concentrated extrusion capacity for biaxially oriented polypropylene films.
China
Domestic e-commerce platforms in Shanghai and Shenzhen logistics hubs are expanding demand for serialized pressure-sensitive labels with variable data printing. NMPA packaging standards and SAMR directives impose compliance layers on polyethylene substrates entering pharmaceutical supply chains. The Yangtze River Delta anchors regional coating operations serving export manufacturing.
India
Pharmaceutical labeling demand concentrates in Maharashtra and Gujarat export zones where CDSCO track-and-trace mandates require tamper-evident pressure-sensitive constructions. FSSAI food-contact regulations add testing protocols for adhesive products entering domestic consumer goods channels. Hyderabad and Bengaluru clusters are emerging as secondary converter locations.
Japan
Electronics manufacturing in the Kanto and Kansai regions sustains specialty tape demand for precision assembly and surface protection applications. METI industrial standards and JIS specifications govern adhesive performance in automotive and consumer electronics supply chains. Nagoya-area chemical producers supply acrylic monomer feedstocks to regional coating operations.
Labels, Tapes and Films Market Vendor Landscape
Premium-margin players sit above commodity-margin players across substrate innovation and regulatory certification dimensions, with consolidated positions in pharmaceutical-grade pressure-sensitive labels and fragmented competition in standard industrial tapes. The vendor base clusters around three strategic archetypes: integrated adhesive chemistry specialists, regional substrate converters with digital front-end capabilities, and diversified materials conglomerates with packaging film divisions. Dominant competitive moves include backward integration into resin production and geographic expansion through master service agreements with multinational brand owners.
Within the integrated chemistry tier, 3M and Avery Dennison occupy positions exemplifying sustained investment in high-performance adhesive platforms and global manufacturing scale. Among Asia-Pacific-based specialists, Nitto Denko Corporation and Lintec Corporation represent concentrated expertise in electronics-grade tapes and precision coating operations. Tesa SE anchors European industrial tape supply through German-engineered acrylic formulations. CCL Industries exemplifies the diversified packaging approach through dedicated pharmaceutical and beverage labeling divisions.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison |
| CCL Industries |
| UPM Raflatac |
| Nitto Denko Corporation |
| Lintec Corporation |
| Tesa SE |
| Saint-Gobain |
| Brady Corporation |
| Others |
Supply Flow & Price Mechanics
Propylene monomer index volatility cascades through polypropylene substrate costs into three-tier pricing stratification across pharmaceutical-grade, industrial-standard, and economy-label tiers. Converters pass through resin-index exposure to multinational brand owners under master service agreements while absorbing margin compression in spot-market transactions with regional food processors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-notified adhesive constructions from REACH-compliant industrial grades and uncertified commodity alternatives. Price differentiation hinges on migration-testing documentation burden and volume-scale commitments in multi-year contracts. Cost compression in standard-grade polyethylene films is intensifying because of naphtha-cracker maintenance cycles and Asian petrochemical corridor shipping disruptions. Regional craft beverage producers exhibit highest price sensitivity, while pharmaceutical exporters absorb 15-25% premiums for serialized tamper-evident constructions.
Supply Chain Analysis
India's PLI scheme for specialty chemicals and China's dual carbon goals are reshaping acrylic monomer sourcing patterns for regional coating operations. Supply concentration rests on South Korean and Japanese petrochemical corridors for high-purity acrylic feedstocks, German extrusion equipment for biaxially oriented polypropylene films, and Chinese Yangtze River Delta converters for serialized label finishing. Single-source vulnerability in East Asian tackifier supply exposes buyers to tariff exposure and maritime chokepoint risk. Distribution runs through wholesale industrial distributors with technical specification support, direct account-managed relationships with multinational brand owners, and emerging e-commerce platforms for micro-batch craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through biodegradable substrate premiums and digital production workflow adoption that collapses minimum order quantity constraints. Cost-down drivers include water-based acrylic formulations eliminating solvent recovery infrastructure.
For Market Incumbents: Deepen backward integration into propylene monomer supply through captive naphtha-cracker partnerships or long-term offtake agreements with Korean and Japanese petrochemical producers. Expand multi-plant redundancy across India and Southeast Asia to defend against CDSCO and NMPA compliance fragmentation threatening single-site certification dependencies. Prioritize digital front-end integration investments to capture unbundled label procurement relationships from multinational food and beverage category managers. For New Entrants and Emerging Players: Craft beverage micro-batch producers represent an underserved buyer archetype demanding sub-thousand-unit label runs with rapid turnaround. Capture this segment through UV-inkjet direct-to-film production eliminating plate costs and partnering with regional water-based adhesive converters in secondary Indian and Southeast Asian cities. Target European premium cosmetics overwrap applications where EFSA-compliant polyolefin alternatives command 40-60% price premiums over legacy PVC constructions. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack capital for multi-jurisdiction certification stacking and digital production infrastructure. Long-term viability favors specialists with captive adhesive chemistry expertise and certified closed-loop substrate partnerships under EU packaging waste directives. Watch for inflection signals in extended producer responsibility framework implementation across US state-level legislation, which will reward recyclability-by-design capabilities with preferential procurement positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock from Korean and Japanese petrochemical corridors insulates margin from propylene volatility and shipping disruption. |
| Biodegradable Film Substrate Certification | PLA and PHA-based shrink films with EFSA compliance and home-compostability claims unlock European premium food packaging price premiums. |
| Digital Production Workflow Adoption | UV-inkjet and toner-based systems eliminate plate costs and enable micro-batch label runs for craft beverage and specialty chemical segments. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, REACH, and GB standard compliance creates barrier to entry protecting pharmaceutical-grade pressure-sensitive label positioning. |
| Regional Converter Network Expansion | Water-based acrylic adhesive adoption in secondary Indian and Southeast Asian cities compresses delivery radii and captures local food processor demand. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged adhesive formulator chemists, pharmaceutical packaging procurement managers, flexible packaging converters, food and beverage category buyers, and regulatory affairs specialists. Secondary sources included FDA 21 CFR food-contact notifications, ECHA REACH substance restriction databases, CDSCO pharmaceutical packaging directives, customs and trade flow data, and SEC 10-K disclosures from listed materials conglomerates. Bottom-up demand modeling triangulated against top-down macroeconomic indicators.
Granularity-level framing applied segment-specific modeling across product type, substrate material, end-use application, and distribution channel dimensions. Pharmaceutical serialization mandates and electric vehicle battery thermal management applications received discrete treatment given their distinct growth trajectories. CAGRs derived from historical volume progression adjusted for regulatory inflection points and substrate substitution dynamics. Forecast inputs incorporated propylene monomer price index correlations, e-commerce fulfillment network expansion rates, and biodegradable substrate adoption curves in European premium packaging.
Underlying measurement precision varies by segment; pharmaceutical-grade pressure-sensitive labels carry tighter precision than commodity industrial tapes given clearer regulatory demand drivers. Forecasts reflect assumptions around CDSCO mandate enforcement timelines, EU EPR framework implementation pace, and water-based adhesive formulation adoption rates. Raw material price volatility, shipping corridor disruptions, and multi-jurisdiction certification stacking complexity constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tear Tape Dispenser Market
Tapes
Double Coated Film Tapes Market
Tapes
Differential Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Masking Tape Market
Tapes
Metal Foil Tapes Market
Tapes
Tape and Label Adhesives Market
Tapes
Dicing Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Breathable Tape Market
Tapes
Wing Walk Tapes Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Unidirectional Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Raffia Tapes Market
Tapes
Moisture Barrier Tapes Market