
 Heat Activated Tear Tape Market | 2026-2036
Heat Activated Tear Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Activated Tear Tape Market Foresight
China is rewriting capacity dynamics for heat activated tear tape as domestic packaging automation accelerates. 3M leverages its adhesive R&D infrastructure to sustain technology leadership in high-temperature activation formulations. Essentra PLC anchors European pharmaceutical compliance demand through specialized tamper-evident tape architectures. tesa SE competes on precision coating scale across German automotive parts packaging segments.
Heat activated tear tape consists of a carrier substrate coated with thermally reactive adhesive that bonds upon controlled heat exposure, typically activating between 80°C and 150°C depending on polymer composition. The technology serves primary industrial functions in tamper-evident sealing, automated carton closure, and clean-release opening mechanisms for consumer goods. Single-sided configurations dominate current volume owing to their compatibility with high-speed flow-wrap equipment, while biodegradable material grades represent the fastest-expanding margin pool as brand owners confront extended producer responsibility frameworks. Polypropylene carriers lead in moisture resistance applications across food and pharmaceutical packaging, whereas paper-based alternatives occupy niche positions in premium cosmetic and sustainable retail segments.
FDA 21 CFR Part 11 traceability requirements and EU MDR tamper-evidence mandates shape product specification thresholds for pharmaceutical applications. REACH substance restrictions and evolving GB standards in China constrain adhesive formulation chemistries, pushing suppliers toward solvent-free coating investments. Stakeholders must monitor regulatory divergence between FDA container closure integrity guidelines and EMA serialization timelines to anticipate specification fragmentation.
Market Dynamics
EU MDR tamper-evidence mandates and FDA container closure integrity guidelines are compressing specification cycles, forcing adhesive suppliers to validate solvent-free coating platforms across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- Pharmaceutical serialization mandates:EMA traceability timelines and FDA 21 CFR Part 11 requirements are expanding tear tape integration into secondary packaging lines across European and North American facilities.
- Food safety compliance:FSSAI packaging integrity standards in India and GB standards in China are accelerating automated carton sealing adoption in moisture-sensitive product categories.
- Biodegradable carrier development:Cellulose-based substrates with comparable heat activation profiles to polypropylene are capturing sustainable packaging specifications in premium cosmetic segments.
Market Restraints
- Solvent-free coating capex intensity:REACH substance restrictions on volatile organic compounds require capital-intensive extrusion equipment that mid-scale converters in Eastern Europe cannot readily finance.
- Petrochemical input volatility:Polypropylene resin prices fluctuate with propylene feedstock markets, compressing margin predictability for tape manufacturers without backward integration into polymer production.
- Hot-melt adhesive substitution:Pressure-sensitive alternatives with room-temperature bonding are displacing heat-activated formulations in low-temperature distribution environments.
Strategic Opportunities
- Extended producer responsibility frameworks:EU Green Deal packaging waste directives create preferential procurement channels for biodegradable tear tape grades in French and German retail supply chains.
- E-commerce authentication integration:Tear tape with embedded NFC or QR traceability layers addresses counterfeiting concerns in direct-to-consumer pharmaceutical and luxury goods channels.
- Automotive battery packaging:Thermal runaway containment requirements for lithium-ion cell transport are opening specifications for high-temperature-resistant activation adhesives in German and South Korean logistics networks.
Industry Challenges
- Cross-jurisdictional validation timelines:Divergent FDA and EMA stability testing protocols for pharmaceutical-grade adhesives extend product qualification cycles by twelve to eighteen months.
- Legacy flow-wrap equipment compatibility:Retrofitting high-speed carton sealing lines for precise temperature control of heat-activated tapes requires mechanical engineering expertise scarce in Southeast Asian contract packaging operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Activated Tear Tape Market |
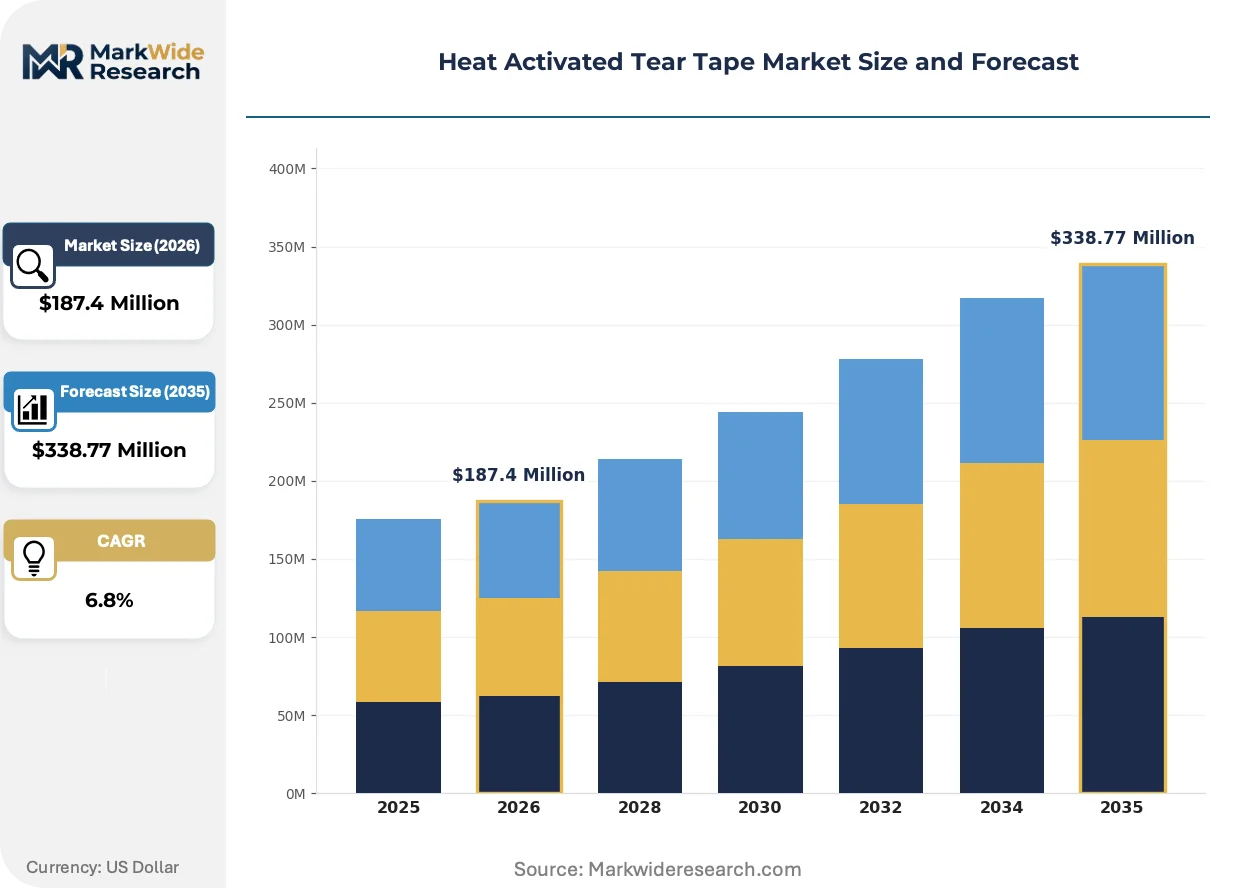
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Custom Adhesive, Reinforced Material: Polypropylene, PVC, Paper, Biodegradable End User: Packaging Industry, Textile Industry, Electronics, Pharmaceuticals Application: Sealing, Bonding, Packaging, Labeling |
| Companies Covered | 3M, Parafix, Maxingvest AG, Essentra PLC, tesa SE, Bagla Group, Tann Group, Avery Dennison Corporation, Nowofol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Activated Tear Tape Market Shifts & Advancements
Adhesive formulation chemistry and activation control systems are converging to enable precision bonding in temperature-sensitive packaging environments previously unsuitable for thermal activation methods.
Water-based acrylic hot-melt adhesives with sub-100°C activation thresholds are migrating from pharmaceutical blister packaging into fresh food tray sealing applications. European dairy processors are piloting these formulations to replace mechanical clips in modified-atmosphere packaging. The technology is migrating from high-value medical segments into mass-market protein packaging, compressing the premium-to-standard pricing gap for precision coating capabilities.
REACH Annex XVII restrictions on organotin catalysts are forcing reformulation of polyurethane-based heat-activated adhesives used in moisture-barrier applications. ECHA substance evaluation timelines are compressing supplier R&D cycles as legacy catalyst stocks deplete. German pharmaceutical packaging converters are accelerating qualification of tin-free alternatives ahead of 2026 authorization sunset dates.
Brand owners in cosmetics and organic food categories are consolidating supplier relationships around certified compostable tear tape grades with third-party home compostability verification. French retail chains are mandating these specifications in private-label sourcing agreements. This specification consolidation is most visible in Paris and Lyon-based contract packaging clusters serving premium European distribution networks.
Heat Activated Tear Tape Market Segmentation
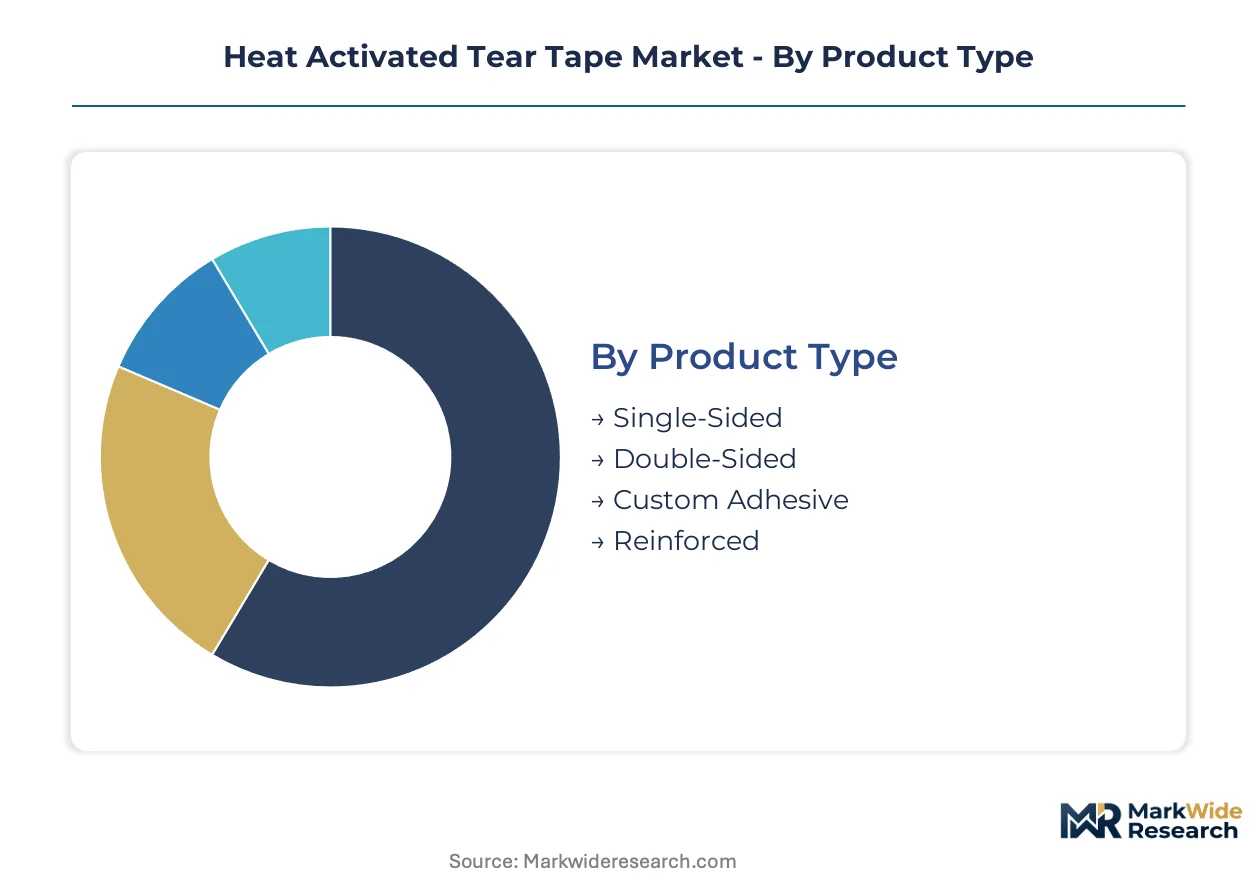
Heat activated tear tape specifications diverge sharply across activation temperature requirements, carrier durability, and regulatory compliance tiers. Manufacturers configure product portfolios around equipment compatibility and end-use certification thresholds rather than universal performance benchmarks.
Product Type:
The use-case spectrum spans high-speed automated sealing to precision manual application, with adhesive architecture determining equipment integration complexity.
- Single-Sided:Thermally reactive adhesive coats one carrier face, enabling direct application onto carton flaps without liner removal. Polypropylene-based single-sided tapes dominate automated flow-wrap operations in China and India due to compatibility with legacy sealing equipment.
- Double-Sided:Dual adhesive layers bond to both substrate and overlay materials simultaneously, serving tamper-evident applications where clean release from one surface is required. Pharmaceutical packaging lines in Germany and France specify double-sided configurations for EU MDR-compliant secondary sealing.
- Custom Adhesive:Formulation adjustments for specific activation temperatures or substrate compatibility address niche industrial requirements. Electronics manufacturers in South Korea commission custom low-residue adhesives for sensitive component packaging.
- Reinforced:Embedded fiber or filament layers enhance tensile strength for heavy-duty carton closure. Automotive parts distributors in Germany specify reinforced grades for lithium-ion battery transport compliance.
Established volume favors Single-Sided; emerging adoption favors Custom Adhesive.
Material:
Carrier selection pivots on moisture resistance requirements against compostability mandates, with cost tiers separating commodity from premium specifications.
- Polypropylene:Thermoplastic polymer carriers deliver superior moisture barrier performance and dimensional stability across temperature cycling. Polypropylene leads food and pharmaceutical packaging specifications where humidity protection is non-negotiable.
- PVC:Chlorinated polymer substrates offer chemical resistance and flame-retardant properties for specialized industrial applications. Electronics packaging in Japan specifies PVC carriers for electrostatic discharge protection.
- Paper:Cellulose-based carriers with heat-resistant coatings serve premium cosmetic and gift packaging segments. French retail chains mandate paper-based alternatives in private-label sustainable sourcing agreements.
- Biodegradable:Certified compostable substrates with comparable activation profiles to synthetic carriers address extended producer responsibility frameworks. Biodegradable grades are climbing the fastest in premium organic food and cosmetic segments.
Polypropylene commands current procurement volumes; Biodegradable specifications are expanding most quickly in regulated European retail channels.
End User:
Customer type determines validation depth, with pharmaceutical and food safety compliance imposing qualification cycles that commodity industrial users avoid.
- Packaging Industry:Contract packagers and carton converters represent the primary demand channel, integrating tear tape into automated sealing lines for consumer goods. Indian FSSAI packaging integrity standards accelerate automated carton sealing adoption in moisture-sensitive categories.
- Textile Industry:Fabric bonding and temporary fixation applications utilize heat-activated tapes in garment manufacturing and technical textiles. Bangladeshi apparel exporters specify low-temperature activation grades to prevent synthetic fiber damage.
- Electronics:Component packaging and anti-static sealing requirements drive specifications for clean-release adhesives with minimal residue. South Korean battery manufacturers are opening specifications for high-temperature-resistant activation adhesives in thermal runaway containment.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU MDR traceability mandates enforce tamper-evidence and serialization integration. EMA serialization timelines compress specification cycles for European pharmaceutical packaging lines.
Packaging Industry absorbs baseline volumes; Pharmaceuticals impose the steepest specification premiums and qualification barriers.
Application:
Functional deployment separates permanent bonding from reversible opening mechanisms, with tamper-evidence requirements elevating performance thresholds.
- Sealing:Permanent closure of cartons, trays, and pouches against environmental contamination and unauthorized access. Food processors in China deploy heat-activated sealing to replace mechanical clips in modified-atmosphere protein packaging.
- Bonding:Structural adhesion between dissimilar materials where mechanical fasteners are impractical. Automotive interior trim manufacturers in Germany specify bonding-grade tapes for vibration-resistant assembly.
- Packaging:Comprehensive integration of tear tape into primary and secondary packaging systems. E-commerce authentication integration with embedded NFC layers addresses counterfeiting in direct-to-consumer pharmaceutical channels.
- Labeling:Tamper-evident label attachment and promotional feature integration on retail packaging. Cosmetic brand owners in France consolidate supplier relationships around certified compostable labeling grades.
Sealing commands installed equipment utilization; Packaging application specifications are gaining share fastest through authentication feature integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin production clusters in China, Germany, and the United States concentrate heat activated tear tape manufacturing capacity near petrochemical feedstock sources. Converter networks in India and South Korea expand secondary processing capacity to serve regional pharmaceutical and electronics packaging demand.
China
Domestic packaging automation accelerates tear tape integration across food and consumer goods sectors. GB standards for packaging integrity tighten adhesive formulation requirements, pushing converters toward solvent-free coating platforms. Yangtze River Delta converters near Shanghai expand high-speed flow-wrap equipment fleets to serve export-oriented electronics manufacturers.
Germany
EU MDR tamper-evidence mandates drive pharmaceutical packaging line upgrades in secondary sealing applications. ECHA REACH Annex XVII restrictions on organotin catalysts force adhesive reformulation ahead of 2026 authorization sunsets. Bavarian automotive parts distributors specify reinforced tear tape grades for lithium-ion battery transport compliance.
United States
FDA 21 CFR Part 11 traceability requirements expand tear tape deployment in pharmaceutical serialization programs. EPA volatile organic compound regulations pressure mid-scale converters to upgrade coating infrastructure. Midwest contract packaging clusters around Chicago retrofit legacy carton sealing lines for temperature-controlled heat activation.
India
FSSAI packaging integrity standards accelerate automated carton sealing adoption in moisture-sensitive food categories. Bureau of Indian Standards certification requirements for food-contact adhesives extend product qualification timelines. Gujarat-based pharmaceutical exporters integrate tear tape into secondary packaging for EU-bound shipments.
South Korea
Battery manufacturers commission high-temperature-resistant activation adhesives for thermal runaway containment in lithium-ion cell transport. MFDS pharmaceutical packaging guidelines align with EMA serialization timelines for export compliance. Busan-Ulsan logistics networks pilot tear tape with embedded NFC traceability layers for e-commerce authentication.
Heat Activated Tear Tape Market Competitive Landscape
Integrated adhesive compounders and specialized tape converters split the market between formulation control and precision coating scale. The vendor base clusters around three strategic archetypes: multinational material science conglomerates with captive polymer supply, regional converters with equipment-integrated service models, and niche specialists in biodegradable substrate development. Competitive moves center on solvent-free coating capacity expansion and pharmaceutical-grade validation investments across multiple regulatory jurisdictions.
Among diversified material science conglomerates, 3M and Avery Dennison Corporation occupy positions anchored by adhesive R&D infrastructure and global distribution networks. Essentra PLC and tesa SE exemplify the European pharmaceutical compliance specialist archetype, with precision coating capabilities aligned to EU MDR and FDA validation requirements. Bagla Group represents regional-scale converter operations serving high-volume automated packaging demand in South Asian markets.
| Leading Market Players |
|---|
| 3M |
| Parafix |
| Maxingvest AG |
| Essentra PLC |
| tesa SE |
| Bagla Group |
| Tann Group |
| Avery Dennison Corporation |
| Nowofol |
| Others |
Supply & Pricing Matrix
Propylene feedstock volatility determines both pricing tier spreads and supply chain shape across heat activated tear tape manufacturing, compressing margins for non-integrated converters while rewarding compounders with captive polymer supply in China and Germany.
Pricing Analysis
EU REACH substance restrictions dictate the pricing tier structure across pharmaceutical-grade and industrial-grade specifications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated adhesives from commodity food-contact grades and generic industrial formulations. Price differentiation hinges on certification investment burden and solvent-free coating capability. Cost compression in standard-tier polypropylene tapes is intensifying because of resin price swings. Contract packagers in India exhibit highest price sensitivity; German pharmaceutical converters accept premium tiers for compliance security.
Supply Chain Analysis
Polypropylene resin production clusters in China, Germany, and the United States anchor upstream feedstock access for carrier substrate manufacturing. Tape production draws from propylene derivatives, adhesive catalysts, and release liner materials. Single-source vulnerability concentrates in organotin catalyst supply chains facing REACH authorization sunsets. Distribution runs through converter networks in India and South Korea serving regional pharmaceutical and electronics packaging demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable substrate innovation and EU Green Deal packaging mandates are accelerating a high-growth disruption that rewards early movers in certified compostable grades.
For Market Incumbents: Insulate pharmaceutical-grade margin pools by accelerating tin-free adhesive qualification ahead of ECHA sunset dates. Secure backward integration into solvent-free coating capacity in Germany and China to defend against propylene cost volatility. Channel control through equipment-integrated service contracts with Yangtze River Delta converters limits substitution risk from pressure-sensitive alternatives.
For New Entrants and Emerging Players: Mid-scale biodegradable substrate development in France and certified home compostability verification represent the most penetrable entry point for premium cosmetic and organic food specifications. South Korean battery packaging applications for thermal runaway containment offer a second white-space target with limited incumbent specialization. Partner with Paris and Lyon contract packaging clusters to secure private-label sourcing mandates from retail chains.
For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors precision coating specialists with multi-jurisdictional validation capabilities. Long-term viability over a five-to-ten-year window rests on solvent-free platform migration and pharmaceutical certification depth. Acquisition targets should demonstrate EMA and FDA stability testing completion. Monitor ECHA substance evaluation timelines as the critical signal for catalyst reformulation urgency and margin compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Coating Capacity Expansion | REACH compliance secures pharmaceutical access in Germany and France. |
| Biodegradable Substrate Certification | EU Green Deal directives create preferential procurement in French retail. |
| Pharmaceutical Validation Investment | FDA 21 CFR Part 11 alignment opens North American serialization demand. |
| High-Temperature Adhesive Development | Thermal runaway specifications penetrate South Korean battery logistics. |
| Equipment-Integrated Service Contracts | Legacy flow-wrap retrofit demand in India locks in converter relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and industry association reports. Tape manufacturing plant managers, pharmaceutical packaging engineers, and food-contact adhesive procurement leads provided operational validation. Secondary sources include ECHA substance evaluation databases, FDA 21 CFR guidance documents, customs import records, and BIS certification registries. Bottom-up volume estimates from converter capacity and top-down demand segmentation from end-use procurement patterns were cross-referenced for triangulation.
Forecast inputs span activation temperature tiers, carrier material grades, end-use industry compliance thresholds, and regional regulatory adoption timelines across the projection horizon. Segmentation modeling incorporates product type, material substrate, end-user vertical, and application function. CAGRs were derived from trend extrapolation of validated base-year estimates against capacity expansion announcements and regulatory mandate implementation schedules. Industry-specific inputs include pharmaceutical serialization timeline acceleration and biodegradable packaging mandate enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in propylene feedstock pricing, EU regulatory enforcement pace, or Chinese packaging automation investment would shift the trajectory. Forecasts reflect documented assumptions regarding catalyst authorization sunsets and solvent-free coating adoption curves. Quarterly review of ECHA evaluation timelines, FDA guidance updates, and GB standards revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
High Bond Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Freezer Tape Market
Tapes
Dicing Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Lacing Tape Market
Tapes
Mastic Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Medical Tapes Market
Tapes
Release Tape Market
Tapes
Pipe Marking Tape Market