
 Aluminum Foil Tape Market | 2026-2036
Aluminum Foil Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Tape Market Outlook
Modular HVAC component packaging is consolidating buyer choice around pre-cut foil tape kits that bundle insulation sealing with vapor barrier solutions. 3M leverages its adhesive chemistry portfolio to anchor premium positioning across specification-driven construction channels. Avery Dennison Corporation sustains volume leadership through global distribution scale and private-label partnerships with regional HVAC distributors. Tesa SE specializes in thin-gauge conductive formulations that serve electronics manufacturing customers with tight thickness tolerances.
Aluminum foil tape consists of a dead-soft aluminum foil backing coated with pressure-sensitive adhesive, typically acrylic or rubber-based, engineered for thermal conductivity, moisture resistance, and conformability to irregular surfaces. The material blocks vapor transmission and reflects radiant heat, serving critical sealing and shielding functions across temperature extremes from cryogenic lines to exhaust systems. Single-sided foil tape dominates volume shipments due to its ubiquity in duct sealing and general-purpose HVAC maintenance, while conductive foil tape captures disproportionate margin pools from aerospace engineering and electronics manufacturing applications where electromagnetic interference shielding specifications are stringent. Acrylic adhesive formulations lead across construction and automotive assembly end user industries because of their broad temperature range and UV stability, though silicone variants are displacing rubber in high-heat automotive underhood sealing as OEM thermal management requirements tighten.
The U.S. EPA enforces refrigerant management standards under Section 608 of the Clean Air Act that mandate leak repair protocols, directly expanding foil tape consumption for system integrity maintenance. The EU F-Gas Regulation and REACH compliance frameworks restrict adhesive solvent content and mandate material traceability, raising formulation costs for suppliers serving European construction and electronics manufacturing customers. China's GB standards for building energy efficiency and its dual carbon goals are tightening HVAC system performance requirements, creating specification upgrades that favor higher-grade reinforced and heat-resistant tape constructions. Stakeholders must monitor how evolving refrigerant chemistries and regional decarbonization timelines reshape the performance specifications that determine tape selection across installation, repair, and retrofit workflows.
Market Dynamics
Refrigerant chemistry transitions under the U.S. EPA's AIM Act are forcing wholesale HVAC equipment replacement cycles, creating specification-grade demand for compliant sealing materials that withstand next-generation low-GWP refrigerant pressures and thermal profiles.
Growth Catalysts
- HVAC Retrofit Mandates:The U.S. EPA's phasedown of hydrofluorocarbon refrigerants under Section 608 of the Clean Air Act mandates leak repair protocols that expand foil tape consumption for system integrity maintenance across commercial building stock.
- Electronics Manufacturing Migration:Vietnam and Indonesia are capturing manufacturing investment shifting from China to lower-cost ASEAN production bases, concentrating demand for thin-gauge conductive foil tapes with tight thickness tolerances.
- Building Energy Efficiency Codes:China's GB standards for building energy efficiency and its dual carbon goals tighten HVAC system performance requirements, creating specification upgrades that favor reinforced and heat-resistant tape constructions.
Market Restraints
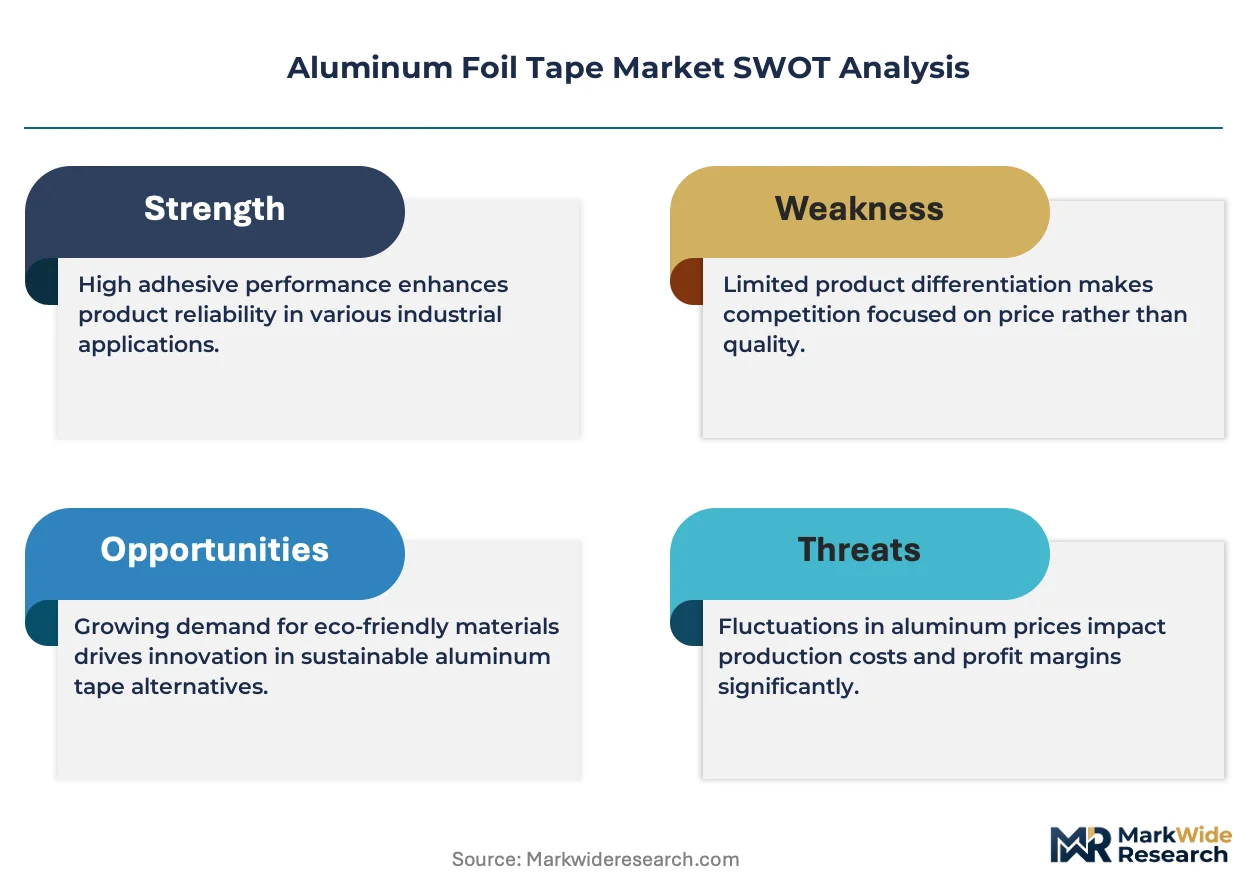
- Aluminum Price Volatility:Raw material input costs fluctuate with London Metal Exchange pricing, compressing margins for converters without long-term supply contracts or backward integration into foil rolling.
- Adhesive Solvent Restrictions:The EU F-Gas Regulation and REACH compliance frameworks restrict solvent content and mandate material traceability, raising formulation costs for suppliers serving European construction and electronics customers.
- Acrylic Substitution Pressure:Silicone adhesive variants are displacing rubber-based formulations in high-heat automotive underhood sealing as OEM thermal management requirements tighten, threatening incumbent product lines.
Strategic Opportunities
- Modular Pre-Cut Kits:HVAC component packaging is consolidating buyer choice around pre-cut foil tape kits that bundle insulation sealing with vapor barrier solutions, creating value-added positioning for converters with kitting capabilities.
- Aerospace EMI Shielding:Conductive foil tape captures disproportionate margin pools from aerospace engineering applications where electromagnetic interference shielding specifications are stringent and certification barriers limit supplier entry.
- India Building Stock Expansion:Urbanization acceleration and commercial construction growth in Indian metropolitan clusters create underpenetrated demand for HVAC installation materials as the country expands its chilled infrastructure.
Industry Challenges
- Cross-Regional Certification Complexity:Suppliers must navigate simultaneous compliance with U.S. EPA refrigerant management standards, EU REACH substance restrictions, and China's GB building codes, fragmenting quality management systems.
- Legacy Duct Inventory Compatibility:Retrofit workflows require tape formulations that seal effectively across aging galvanized steel, aluminum, and flexible duct substrates with varying surface oxidation states and contamination profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Tape Market |
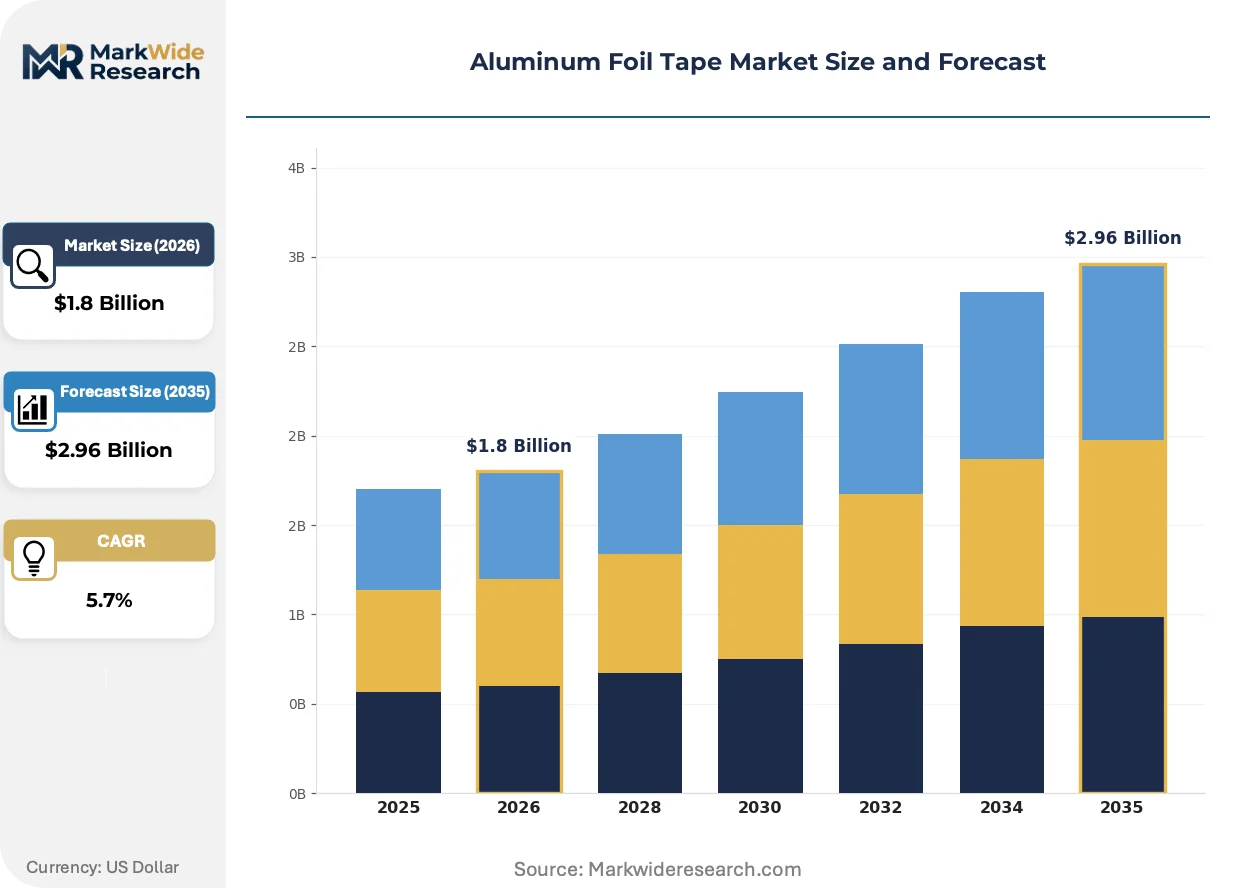
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-sided Foil Tape, Double-sided Foil Tape, Reinforced Foil Tape, Conductive Foil Tape, Heat-Resistant Foil Tape Adhesive Type: Acrylic, Rubber, Silicone, Hot Melt, Water-based Application: HVAC Systems, Electrical Insulation, Packaging Sealing, Automotive Sealing, Soundproofing End User Industry: Construction, Electronics Manufacturing, Automotive Assembly, Aerospace Engineering, Packaging Plants |
| Companies Covered | 3M, Avery Dennison Corporation, Tesa SE, Nitto Denko Corporation, Saint-Gobain Performance Plastics, Intertape Polymer Group, Shurtape Technologies LLC, Scapa Group plc, Advance Tapes International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Tape Market Strategic Shifts
Adhesive chemistry advances and refrigerant regulatory cascades are compressing product lifecycles while elevating performance specifications across temperature extremes from cryogenic lines to exhaust systems.
Multi-layer laminate constructions are unifying thermal conductivity, moisture resistance, and conformability into single-source solutions that reduce field installation steps. Aerospace and automotive OEMs are adopting these integrated materials fastest, specifying them into new platform designs that consolidate previously separate vapor barrier and heat shielding components. The technology is unifying specification channels that historically segmented by function rather than performance grade.
The EU F-Gas Regulation mandates phased reductions in fluorinated greenhouse gas emissions, directly constraining refrigerant choices available to HVAC system designers. Equipment manufacturers must certify compatibility with lower-GWP alternatives that operate at higher pressures, requiring tape seals rated for expanded thermal and mechanical stress ranges. European construction channels are responding by upgrading to reinforced foil constructions with acrylic formulations optimized for broader temperature stability.
Specification-driven procurement now dominates commercial construction channels, with mechanical engineers pre-approving tape grades into project documents before distributor involvement. This pattern compresses distributor influence while elevating adhesive chemistry credentials and certified performance data into primary selection criteria. The shift is most visible in Southeast Asian commercial building projects where multinational contractors enforce global specification standards across local supply chains.
Aluminum Foil Tape Market Segmentation
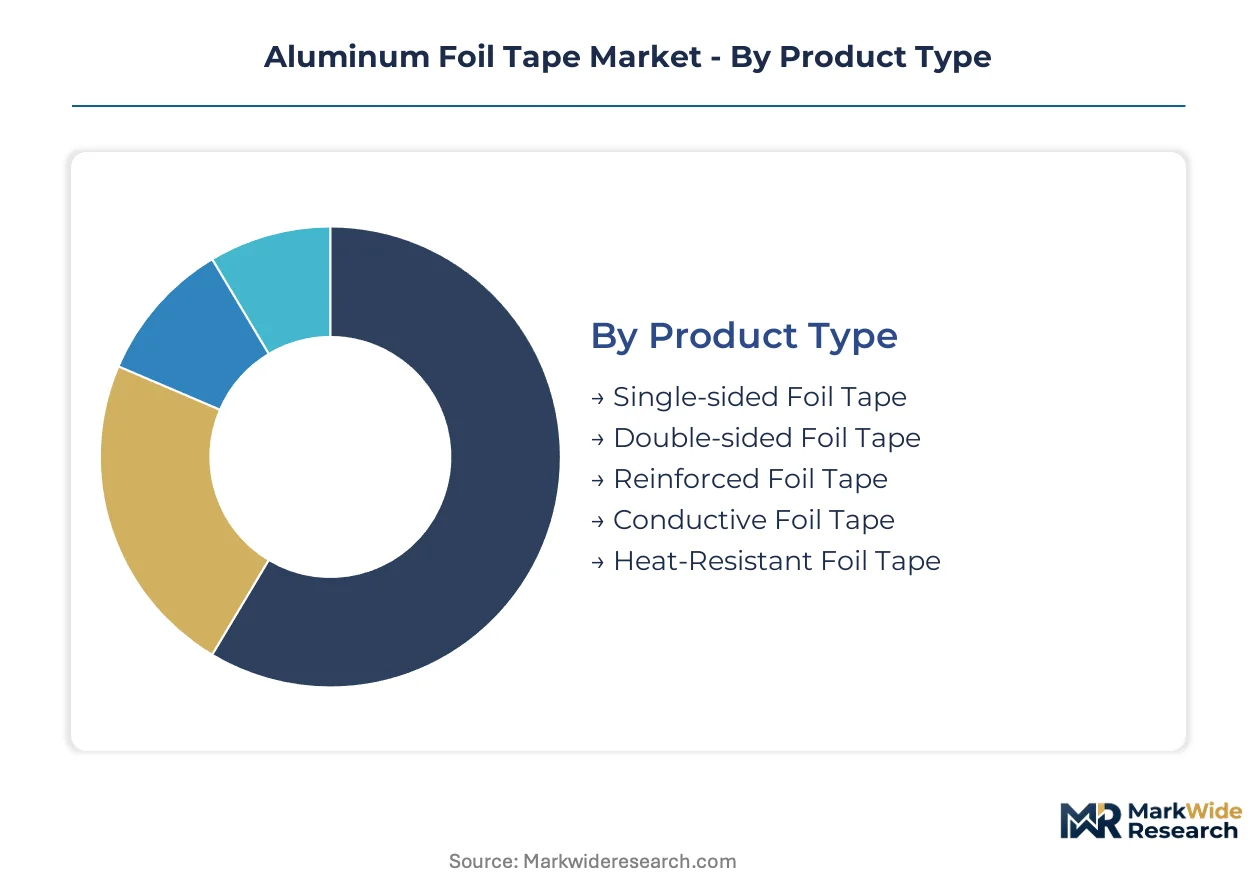
Aluminum foil tape segmentation reflects divergent performance requirements across thermal management, electromagnetic shielding, and moisture sealing applications. Specification engineers prioritize adhesive chemistry compatibility with substrate surface energy and operating temperature ranges when selecting grades for installation workflows.
Product Type:
Buyers differentiate primarily by functional load — thermal stress, mechanical reinforcement, or electrical conductivity — which determines backing construction and adhesive formulation requirements.
- Single-sided Foil Tape:Dead-soft aluminum backing with pressure-sensitive adhesive on one face dominates volume shipments through ubiquity in duct sealing and general-purpose HVAC maintenance. Demand concentrates in Vietnam and Indonesia as manufacturing investment shifts from China to lower-cost ASEAN production bases, with construction contractors specifying this grade for cost-sensitive commercial building stock.
- Conductive Foil Tape:Thin-gauge formulations with controlled electrical resistance serve electronics manufacturing customers with tight thickness tolerances. Aerospace engineering applications in the United States and Germany capture disproportionate margin pools where electromagnetic interference shielding specifications are stringent and certification barriers limit supplier entry.
- Reinforced Foil Tape:Scrim or fiberglass mesh embedded within the aluminum backing provides tear resistance for demanding mechanical applications.
- Double-sided Foil Tape:Pressure-sensitive adhesive on both faces enables bonding between dissimilar substrates in laminating operations.
- Heat-Resistant Foil Tape:Silicone or specialized acrylic formulations maintain adhesion across exhaust system temperature extremes.
Volume sits with Single-sided Foil Tape; growth tilts toward Conductive Foil Tape.
Adhesive Type:
Selection hinges on temperature range, UV exposure, and surface energy compatibility with aged duct substrates or pristine electronic components.
- Acrylic:Broad temperature range and UV stability position this formulation across construction and automotive assembly end user industries. China's GB standards for building energy efficiency tighten HVAC system performance requirements, creating specification upgrades that favor acrylic variants optimized for broader temperature stability.
- Silicone:Displacing rubber-based formulations in high-heat automotive underhood sealing as OEM thermal management requirements tighten. European automotive assembly plants specify silicone grades for underhood applications where exhaust proximity demands sustained adhesion above 150°C.
- Rubber:Aggressive initial tack and cost positioning serve general-purpose packaging sealing and temporary construction applications.
- Hot Melt:Rapid set times and clean processing suit high-volume automated packaging lines.
- Water-based:Reduced volatile organic compound emissions align with EU REACH compliance frameworks restricting adhesive solvent content.
Acrylic formulations anchor current volume; silicone variants are climbing the fastest as thermal specifications tighten.
Application:
End-use context determines whether the priority is vapor barrier integrity, electrical isolation, or acoustic damping.
- HVAC Systems:Vapor barrier sealing and thermal reflection across ductwork, insulation joints, and equipment cabinets. The U.S. EPA's phasedown of hydrofluorocarbon refrigerants under Section 608 of the Clean Air Act mandates leak repair protocols that expand foil tape consumption for system integrity maintenance across commercial building stock.
- Electrical Insulation:Dielectric separation and heat dissipation in transformer winding, capacitor packaging, and motor assemblies. Electronics manufacturing migration to Vietnam concentrates demand for thin-gauge conductive tapes with tight thickness tolerances serving precision component shielding.
- Automotive Sealing:Underhood heat management and exhaust system wrapping.
- Packaging Sealing:Moisture barrier closure for temperature-sensitive pharmaceutical and food shipments.
- Soundproofing:Mass-loaded barrier layers in architectural acoustic treatments.
HVAC Systems command installed volume; Electrical Insulation is gaining share fastest from electronics manufacturing relocation.
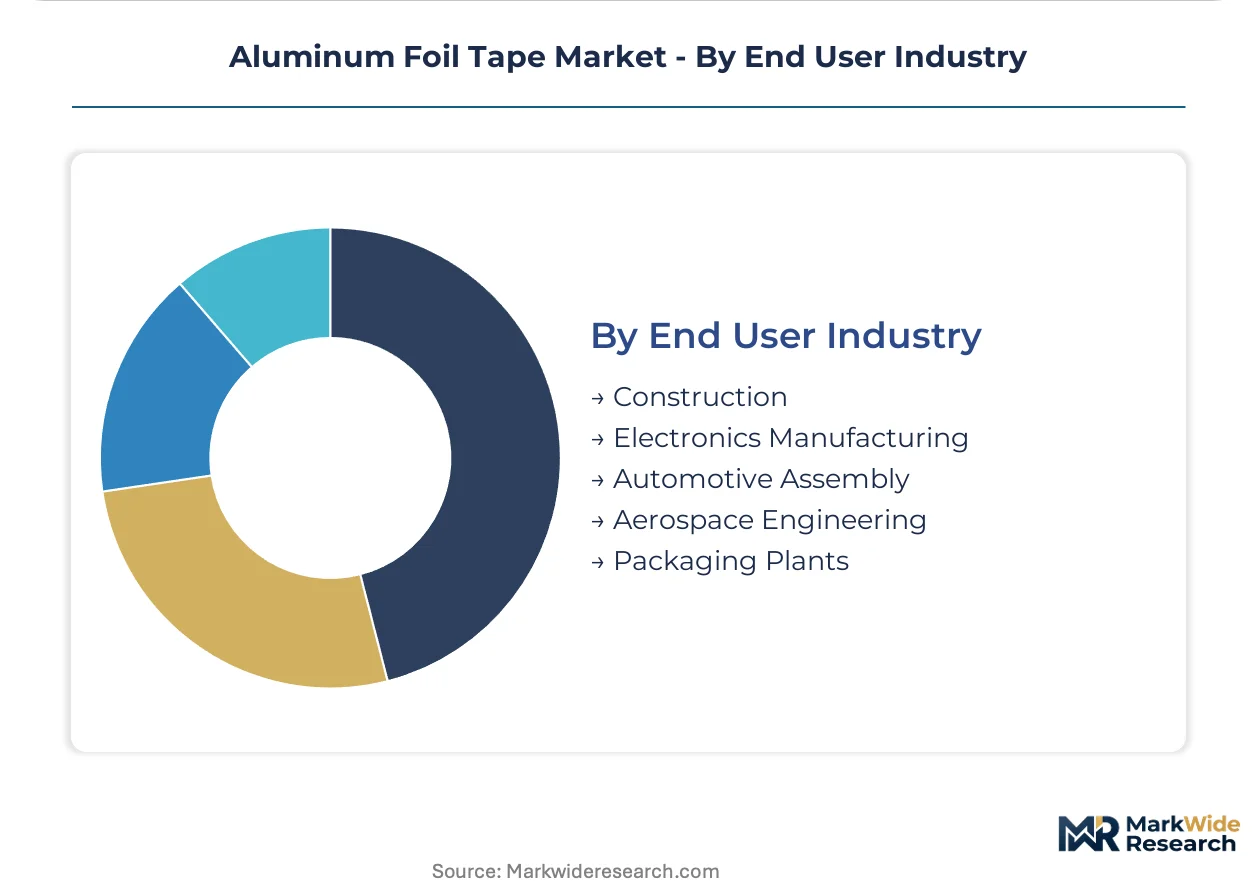
End User Industry:
Procurement patterns diverge between specification-driven engineering channels and price-sensitive maintenance operations.
- Construction:Commercial and residential building stock drives bulk consumption through mechanical contractor purchasing. Modular HVAC component packaging consolidates buyer choice around pre-cut foil tape kits that bundle insulation sealing with vapor barrier solutions.
- Electronics Manufacturing:Cleanroom environments and precision tolerances demand certified traceability and batch consistency. ASEAN production bases in Vietnam and Indonesia capture manufacturing investment shifting from China, concentrating demand for thin-gauge conductive formulations.
- Automotive Assembly:OEM thermal management specifications drive silicone adhesive adoption for underhood applications.
- Aerospace Engineering:EMI shielding and lightweight thermal protection for airframe and avionics installations.
- Packaging Plants:High-speed automated lines prioritize adhesive set speed and roll consistency.
Construction holds volume concentration; Electronics Manufacturing shows the steepest expansion trajectory from supply chain relocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Vietnam and Indonesia are concentrating manufacturing investment migrating from China, creating demand clusters for HVAC installation materials and precision electronics shielding products.
United States
Commercial building stock retrofits and aerospace engineering clusters drive specification-grade consumption. The EPA's AIM Act refrigerant phasedown mandates equipment replacement cycles requiring compliant sealing materials. Houston and Dallas-Fort Worth metropolitan areas concentrate HVAC contractor purchasing for Gulf Coast petrochemical facility maintenance.
China
Building energy efficiency mandates and dual carbon goals tighten HVAC performance requirements across urban construction. GB standards for thermal insulation create specification upgrades favoring reinforced tape constructions. Yangtze River Delta manufacturing bases consume thin-gauge conductive formulations for electronics assembly export production.
Germany
Automotive OEM thermal management specifications and REACH compliance frameworks shape adhesive formulation requirements. The EU F-Gas Regulation constrains refrigerant choices, forcing tape seal upgrades for higher-pressure low-GWP alternatives. Stuttgart and Munich industrial corridors concentrate aerospace EMI shielding demand from avionics suppliers.
Vietnam
Electronics manufacturing relocation from China concentrates demand for tight-tolerance conductive tapes serving precision component shielding. Industrial parks in Bac Ninh and Hai Phong provinces attract semiconductor packaging investment requiring certified traceability. Urbanization acceleration in Ho Chi Minh City expands commercial HVAC installation material consumption.
India
Metropolitan construction growth and chilled infrastructure expansion create underpenetrated demand for duct sealing materials. Commercial building stock in Mumbai and Delhi-NCR drives mechanical contractor purchasing for cost-sensitive installation workflows. Karnataka and Tamil Nadu electronics manufacturing zones develop supplier ecosystems for conductive tape conversion.
Aluminum Foil Tape Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across adhesive chemistry and backing fabrication tiers. Market structure fragments between specification-driven construction channels and price-sensitive maintenance procurement. Three archetypes dominate: multinational adhesive technology leaders with global distribution scale, regional converters with kitting capabilities and private-label partnerships, and specialty formulators serving electromagnetic interference certification barriers. Capacity expansion and backward integration into foil rolling represent the primary competitive moves for margin defense against aluminum price volatility.
Among diversified technology conglomerates, 3M and Avery Dennison Corporation exemplify global scale positioning across specification-driven channels. Tesa SE occupies a specialist tier focused on thin-gauge conductive formulations with tight thickness tolerances. These three anchors represent divergent strategic postures: adhesive chemistry breadth versus distribution scale versus precision manufacturing focus. Regional converters with Vietnamese and Indonesian production bases compete on logistics proximity to electronics manufacturing migration destinations.
| Leading Market Players |
|---|
| 3M |
| Avery Dennison Corporation |
| Tesa SE |
| Nitto Denko Corporation |
| Saint-Gobain Performance Plastics |
| Intertape Polymer Group |
| Shurtape Technologies LLC |
| Scapa Group plc |
| Advance Tapes International Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive foil rolling operations anchor supply position and pricing power for converters serving specification-driven construction channels, while outsourced adhesive formulation exposes mid-tier competitors to margin compression from London Metal Exchange volatility and EU REACH compliance costs.
Pricing Analysis
Short lead-time premiums separate urgent project procurement from contract-scheduled deliveries, with mechanical contractors paying markup differentials for same-day distributor availability on reinforced grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and adhesive chemistry sophistication, with silicone formulations commanding sustained premiums over acrylic alternatives. Pricing pressure stems from aluminum price volatility compressing converter margins on spot foil purchases. Cost-sensitive maintenance contractors in Southeast Asian commercial building stock exhibit highest price sensitivity, while aerospace EMI shielding specifications render OEM procurement least elastic.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given foil tape's consumable nature, though converter scrap recycling into secondary aluminum feedstock is gaining traction under China's dual carbon goals and EU circular economy frameworks. Primary foil supply concentrates in China, Germany, and the United States, with adhesive polymer feedstock drawing from South Korean and Japanese petrochemical complexes. Single-source vulnerability sits with thin-gauge conductive foil rolling capacity, where Tesa SE and limited Asian specialists control precision tolerances required for electronics manufacturing. Distribution runs through regional HVAC distributors and direct OEM specification channels, with multinational contractors consolidating procurement through approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone adhesive formulations are displacing legacy rubber-based chemistries in automotive underhood applications, compressing product lifecycles while elevating thermal performance thresholds across the value chain.
For Market Incumbents: Anchor specification-driven positioning through backward integration into foil rolling and captive acrylic polymer production, defending margin pools against commodity spot-price volatility. Deepen certification investment for EU F-Gas Regulation compliance and REACH substance traceability to maintain distributor shelf access in European construction channels. Prioritize kitting capabilities for modular HVAC pre-cut bundles that consolidate buyer procurement decisions. For New Entrants and Emerging Players: Launch via private-label partnerships with Vietnamese and Indonesian electronics manufacturing zone distributors, capturing conductive tape demand from semiconductor packaging investment migrating from China. Target India's underpenetrated commercial HVAC installation market with cost-optimized single-sided grades for mechanical contractor price sensitivity. Pursue direct technical sales to multinational contractor specification engineers pre-approving materials into project documents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified adhesive technology conglomerates seeking Southeast Asian production footprint, with IPO viability tethered to sustained electronics manufacturing migration momentum. Acquisition target archetype: regional converters with Vietnamese operational presence and certified kitting capabilities for modular HVAC component packaging. Monitor EU F-Gas Regulation phasedown timelines and U.S. EPA AIM Act enforcement intensity as inflection indicators for specification upgrade velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Rolling | Captive aluminum supply insulates margins from London Metal Exchange volatility for specification-grade converters. |
| Silicone Adhesive Capacity Expansion | Thermal stability above 150°C addresses automotive OEM underhood requirements displacing rubber formulations. |
| Modular Pre-Cut Kit Development | Bundled insulation sealing and vapor barrier solutions consolidate mechanical contractor procurement decisions. |
| EU REACH Compliance Certification | Substance traceability mandates maintain distributor shelf access and specification eligibility in European construction. |
| Vietnamese Production Footprint Establishment | Proximity to Bac Ninh and Hai Phong electronics zones captures conductive tape demand from semiconductor packaging investment. |
Study Parameters
Independent corroboration across mechanical contractor interviews, adhesive formulation technical directors, and HVAC distributor procurement managers underwrites the qualitative findings on specification-driven channel dynamics. Secondary validation draws from U.S. EPA refrigerant management guidance documents, EU ECHA REACH substance restriction updates, Chinese GB building energy efficiency standards, and customs trade data on aluminum foil tape shipments. Bottom-up demand modeling across end-use industries triangulates against top-down macroeconomic construction indicators.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon, with segment-level CAGRs derived from regression analysis against HVAC installation activity, electronics manufacturing capital expenditure, and automotive production indices. Segmentation dimensions include product type, adhesive chemistry, application function, and end-user industry procurement pattern. Forecast inputs incorporate refrigerant phasedown regulatory timelines and ASEAN manufacturing relocation velocity.
Aluminum price volatility, refrigerant chemistry transition delays, and electronics manufacturing migration stalling are the dominant revision risks to modeled demand trajectories. Practitioners should monitor London Metal Exchange pricing spreads, U.S. EPA enforcement actions on Section 608 leak repair protocols, and Vietnamese industrial park occupancy rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Nano Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Global Non Woven Tape Market
Tapes
Release Tape Market
Tapes
Differential Tapes Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Twist Tube Market
Tapes
Industrial Tapes Market
Tapes
Flatback Tapes Market
Tapes
Mastic Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Plastic Adhesive Tapes Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Sterilization Tape Market
Tapes
Lacing Tape Market