
 Tape Applicator Machines Market | 2026-2036
Tape Applicator Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tape Applicator Machines Market Outlook
Skilled automation technician availability is rotating toward shortage in mature manufacturing economies, forcing OEMs to redesign machines for lower-touch commissioning. Nordson Corporation leverages its hot melt adhesive systems expertise to anchor premium positioning in automotive assembly lines. Graco Inc. sustains broad geographic coverage through fluid handling technology cross-sell into packaging end users. Robatech AG specializes in compact, energy-efficient applicator architectures that reduce commissioning complexity for mid-sized converters.
A tape applicator machine dispenses adhesive tapes onto substrates with controlled tension, alignment, and cut-off precision, typically operating at speeds between 30 and 300 meters per minute depending on web width and material gauge. These systems integrate unwind stands, dancer arms, servo-driven nip rollers, and programmable logic controllers to achieve repeatable placement accuracy within ±0.5 millimeters for critical electronics and medical applications. Automatic configurations dominate volume shipments due to labor cost arbitrage in high-throughput packaging and automotive plants, while customized systems capture disproportionate margin pools in pharmaceutical cleanroom and semiconductor back-end environments where validated process traceability commands premium pricing. Semi-automatic units retain relevance in short-run labeling and specialty assembly operations where changeover flexibility outweighs throughput optimization.
EPA emissions guidelines and OSHA machine guarding standards shape equipment design and retrofit demand in United States manufacturing facilities, while REACH chemical restrictions and CE machinery directives govern adhesive formulation choices and safety interlock requirements across European installations. FDA validation protocols for pharmaceutical and medical device tape applications create additional compliance layers that filter supplier qualification pools. Stakeholders must monitor how evolving battery safety standards and solid-state cell architectures redirect precision taping requirements across electronics and electric vehicle supply chains.
Market Dynamics
Precision taping requirements for solid-state battery architectures and flexible electronics are compressing placement tolerance specifications from ±0.5 millimeters toward ±0.1 millimeters, forcing machine builders to redesign servo control loops and vision feedback systems.
Growth Catalysts
- EPA industrial emissions standards:Equipment replacement cycles accelerate across United States automotive and packaging plants as older solvent-based adhesive systems face compliance deadlines.
- Battery cell assembly:Electronics manufacturers in China's Pearl River Delta expand precision taping lines for lithium-ion and emerging solid-state cell production.
- REACH chemical restrictions:European adhesive formulation mandates drive demand for compliant hot-melt and UV-curable tape systems with validated process traceability.
Market Restraints
- Specialized servo motors and linear encoders:Component supply concentrates among Japanese and German precision motion suppliers, exposing lead times to 16-24 week volatility.
- Commissioning complexity:Skilled automation technician shortages in Germany and United States extend deployment timelines and inflate field service costs.
- Mechanical tape application:Emerging ultrasonic and laser bonding methods threaten displacement in high-value medical device and semiconductor back-end segments.
Strategic Opportunities
- Mexico's export-oriented packaging corridor:Nearshoring demand from United States consumer goods brands creates greenfield installation opportunities with simplified logistics.
- CE machinery directive compliance:Safety interlock and validated software requirements favor established European OEMs with documented quality management systems.
- Vision-guided robotics convergence:Integration of AI-driven defect detection with tape placement heads opens premium pricing in pharmaceutical cleanroom environments.
Industry Challenges
- ISO 9001 and FDA 21 CFR Part 11 validation:Pharmaceutical and medical device tape applications require 12-18 month qualification timelines that strain smaller machine builders.
- Legacy PLC architecture integration:Brownfield automotive plants demand seamless communication between new tape applicators and 1990s-era production line controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tape Applicator Machines Market |
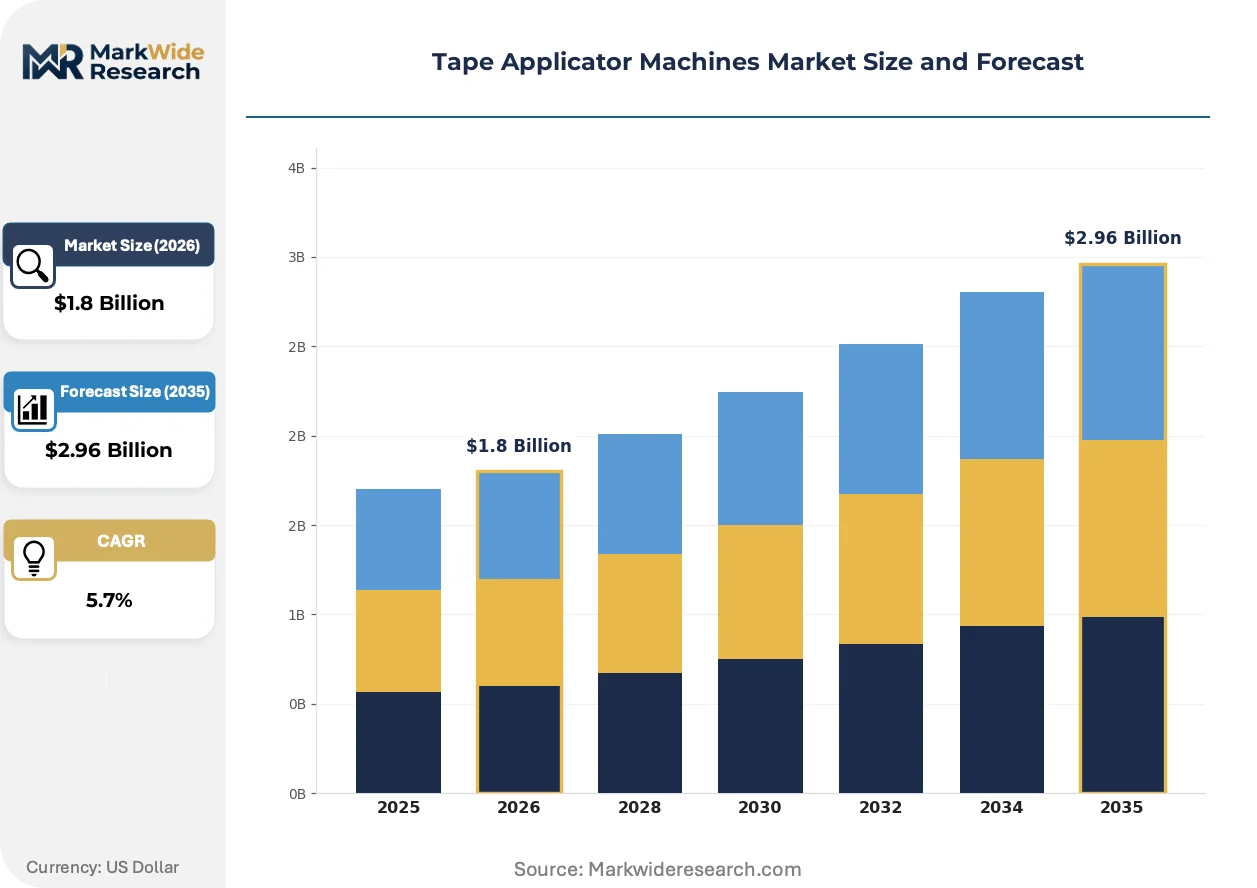
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Customized Application: Packaging, Labeling, Manufacturing, Assembly End User: Food & Beverage, Pharmaceuticals, Electronics, Automotive Technology: Pressure Sensitive, Hot Melt, Water-Based, Solvent-Based |
| Companies Covered | 3M Company, Nordson Corporation, Graco Inc., Robatech AG, Dongguan KEQI Automation Equipment, Shurtape Technologies, Valco Melton, Cyklop, Wayne Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tape Applicator Machines Market Strategic Shifts
Active alignment vision systems and machine learning-driven tension control are compressing setup times and enabling lot-size-one production economics previously unattainable in high-speed taping operations.
Direct-drive linear motor stages are supplanting ball-screw and belt-driven positioning mechanisms in next-generation electronics taping equipment. Semiconductor back-end and battery cell manufacturers in South Korea and Taiwan adopt these architectures to achieve sub-50-micron repeatability. The shift is compressing the addressable market for mid-tier mechanical positioning suppliers while elevating premium capture for integrated motion specialists.
REACH Annex XVII restrictions on persistent organic pollutants and evolving EPA National Emission Standards for Hazardous Air Pollutants reshape adhesive formulation portfolios across European and United States installations. Tape applicator OEMs must validate compatibility with reformulated hot-melt chemistries and water-based pressure-sensitive alternatives. Automotive assembly plants in Germany and Michigan face the steepest compliance curves as they transition multi-line operations.
Outcome-based service contracts with guaranteed uptime thresholds displace traditional break-fix maintenance arrangements in high-volume packaging and automotive accounts. Graco and Nordson anchor this shift through remote monitoring infrastructure and predictive parts replacement. The model concentrates most rapidly in United States and German plants where downtime costs exceed $10,000 per hour.
Tape Applicator Machines Market Segmentation
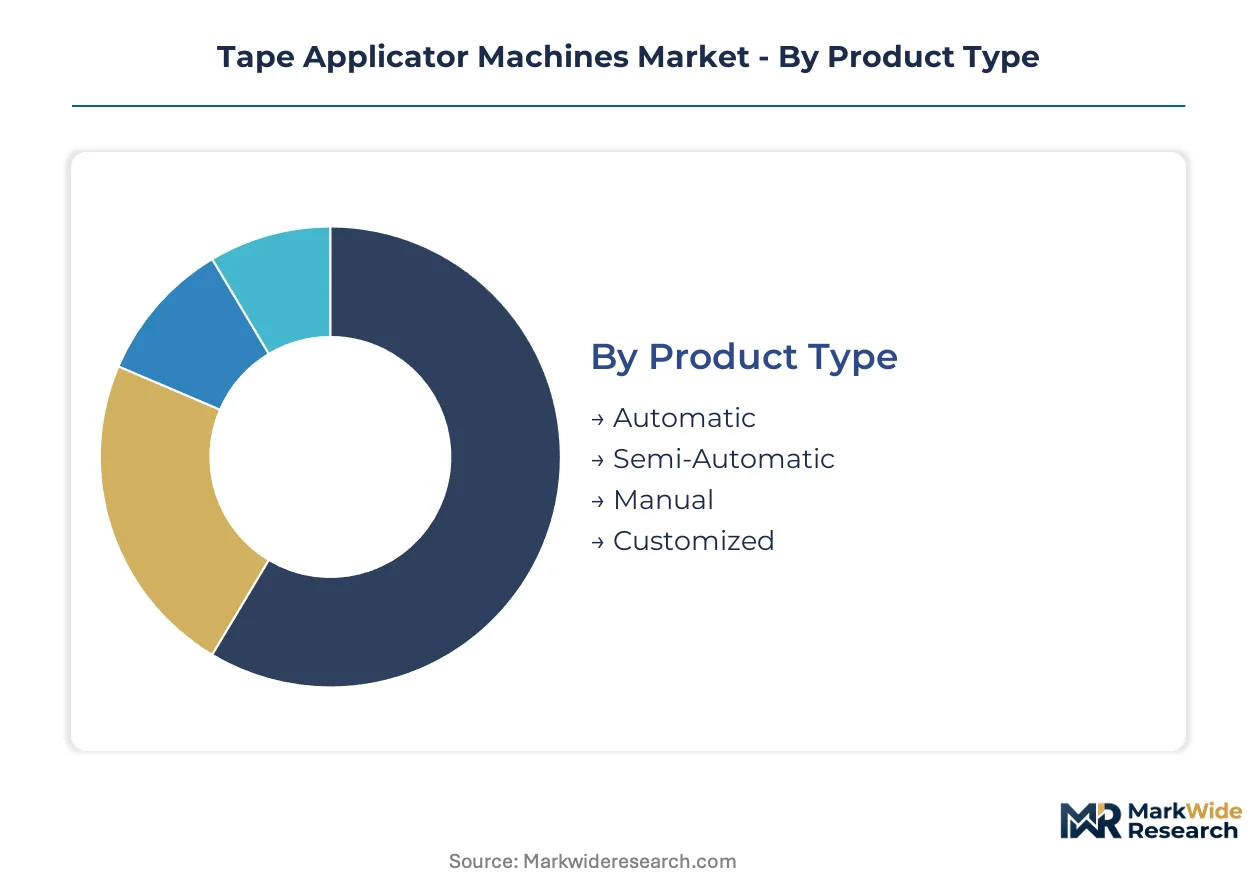
Tape applicator machines serve divergent operational requirements across precision electronics assembly and high-volume packaging corridors. Segmentation reveals how equipment specifications, adhesive chemistries, and automation tiers align with distinct compliance burdens and throughput economics in each vertical.
Product Type:
Automatic configurations dominate channel flows into automotive and electronics plants where labor arbitrage justifies capital intensity, while semi-automatic and manual units reach smaller converters through distributor networks.
- Automatic:Servo-driven systems achieve 30-300 meters per minute with ±0.5 millimeter placement accuracy. Demand concentrates in Germany's automotive component belt and China's Pearl River Delta electronics cluster, driven by EPA emissions deadlines accelerating replacement of legacy solvent-based lines.
- Semi-Automatic:Operator-assisted configurations balance throughput with changeover flexibility for short-run specialty operations. These units retain relevance in Mexico's export-oriented packaging corridor where mid-sized converters prioritize adaptability over pure speed.
- Manual:Hand-fed benchtop systems serve prototyping labs and ultra-low-volume medical device assembly where capital constraints outweigh throughput needs.
- Customized:Validated systems for pharmaceutical cleanrooms and semiconductor back-end environments command premium pricing through documented process traceability and FDA 21 CFR Part 11 compliance.
By volume, Automatic leads. By growth pace, Customized is climbing the fastest as solid-state battery architectures compress tolerance specifications.
Application:
Cost tiers separate high-investment manufacturing and assembly applications from packaging and labeling operations where equipment depreciation cycles stretch longer.
- Packaging:High-speed carton sealing and case erecting operations in United States consumer goods plants drive standard automatic unit shipments. REACH-compliant hot-melt adhesive compatibility is becoming a non-negotiable specification for exporters serving European retail channels.
- Manufacturing:Precision taping for battery cell assembly and flexible circuit protection demands sub-50-micron repeatability. South Korean and Taiwanese semiconductor back-end facilities are adopting direct-drive linear motor stages to meet solid-state cell placement tolerances approaching ±0.1 millimeters.
- Labeling:Pressure-sensitive adhesive application for beverage and pharmaceutical containers requires rapid changeover capabilities. Semi-automatic units retain share here as SKU proliferation outpaces dedicated line economics.
- Assembly:Automotive interior trim and wire harness taping operations in Michigan and Germany face steep compliance curves under evolving EPA National Emission Standards for Hazardous Air Pollutants and REACH Annex XVII restrictions.
Manufacturing commands the steepest price escalation as tolerance specifications tighten. Packaging delivers the largest absolute unit volumes across all geographies.
End User:
Customer type determines validation depth, with pharmaceutical and electronics buyers imposing qualification timelines that filter supplier pools.
- Electronics:Battery cell manufacturers and flexible circuit producers in China's Pearl River Delta and Taiwan drive precision equipment refresh cycles. Solid-state architectures are forcing servo control loop redesigns and vision feedback system upgrades.
- Automotive:Assembly plants in Germany and Michigan transition multi-line operations to compliant hot-melt and water-based pressure-sensitive alternatives. OEMs favor established European suppliers with documented quality management systems for CE machinery directive compliance.
- Pharmaceuticals:Cleanroom tape applications require 12-18 month FDA validation timelines. AI-driven defect detection integration with tape placement heads is opening premium pricing in this segment.
- Food & Beverage:Labeling and secondary packaging operations in Mexico's nearshored export corridor favor simplified logistics and faster commissioning over maximum throughput.
Electronics anchors equipment technology advancement. Pharmaceuticals generates the highest margin capture per installed unit.
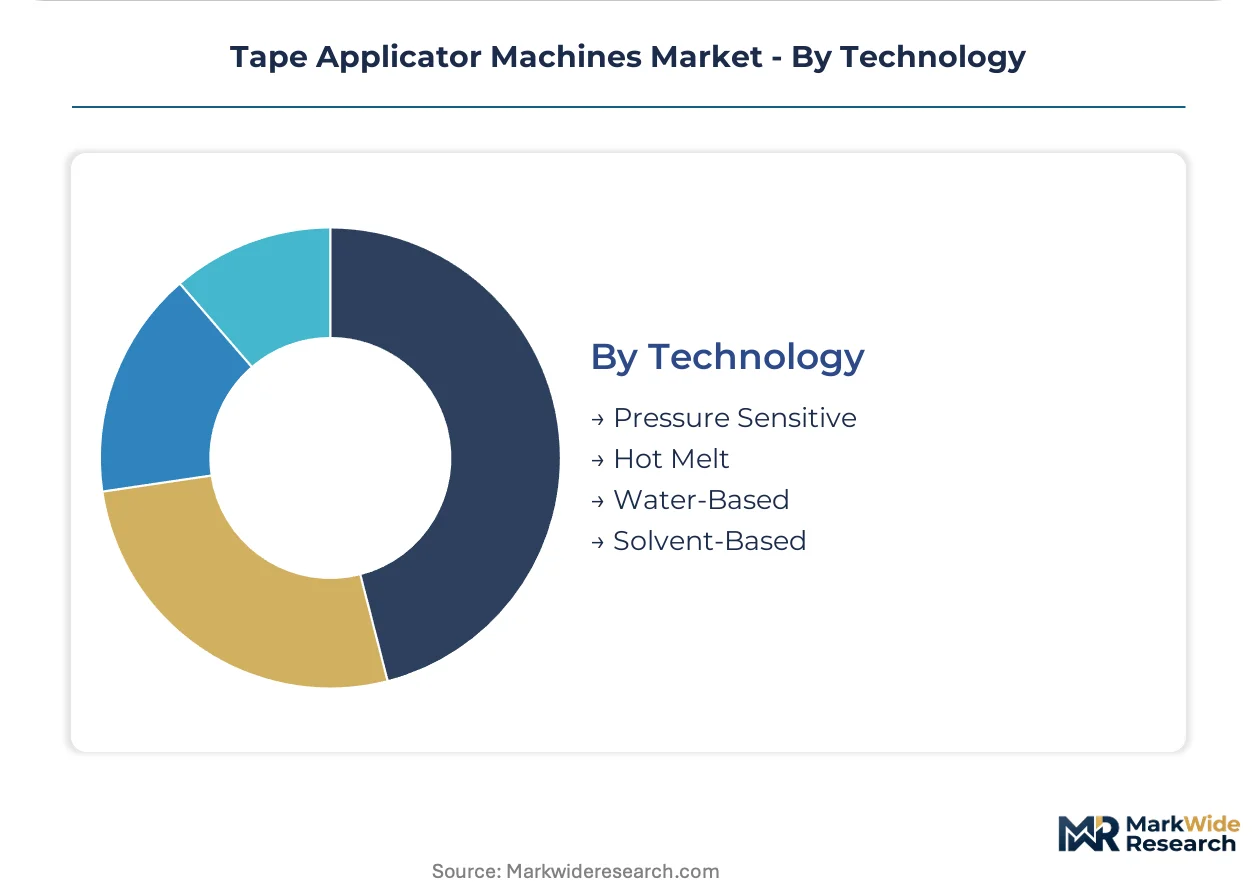
Technology:
Supply concentration in precision motion components from Japanese and German suppliers exposes lead time volatility across all adhesive chemistry configurations.
- Pressure Sensitive:Water-based and solvent-acrylic formulations dominate labeling and general packaging applications. Reformulation under REACH and EPA guidelines is validating compatibility with existing applicator architectures.
- Hot Melt:Thermoplastic adhesive systems anchor automotive assembly lines where Nordson Corporation leverages systems expertise for premium positioning. European REACH compliance and United States emissions standards are accelerating equipment replacement toward these chemistries.
- Water-Based:Lower VOC formulations gain share in food packaging and medical device applications where odor and emission constraints are tightening.
- Solvent-Based:Legacy installations in older automotive and industrial plants face compliance-driven obsolescence, creating retrofit demand for compatible hot-melt transition equipment.
Hot Melt leads by installed value. Water-Based formulations are gaining share fastest as regulatory pressure intensifies across multiple geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment utilization patterns diverge sharply across geographies. Germany's automotive plants prioritize precision tolerance for battery assembly, while China's electronics corridors maximize throughput velocity. Mexico's packaging sector emphasizes rapid commissioning over specification density.
United States
Automotive assembly plants in Michigan and Ohio drive demand for EPA-compliant hot-melt transition equipment. EPA National Emission Standards for Hazardous Air Pollutants force multi-line retrofits away from solvent-based adhesive systems. Detroit-area OEM facilities anchor the largest concentration of replacement installations.
Germany
Battery cell manufacturers and automotive component suppliers require CE machinery directive compliance with documented quality management systems. REACH Annex XVII restrictions on persistent organic pollutants accelerate validation timelines for reformulated adhesive portfolios. Bavaria's automotive component belt concentrates precision equipment refresh cycles.
China
Pearl River Delta electronics manufacturers expand precision taping lines for lithium-ion and solid-state cell production. MIIT industrial standards and dual carbon goals shape equipment efficiency specifications. Shenzhen and Dongguan clusters drive the steepest tolerance compression toward sub-50-micron repeatability.
Mexico
Nearshored export-oriented packaging corridors favor simplified logistics and faster commissioning over maximum throughput. Nuevo León and Jalisco states attract greenfield installations serving United States consumer goods brands. Mid-sized converters prioritize changeover flexibility in semi-automatic configurations.
South Korea
Semiconductor back-end facilities adopt direct-drive linear motor stages for battery cell placement tolerances approaching ±0.1 millimeters. MFDS pharmaceutical validation protocols create premium pricing opportunities in cleanroom tape applications. Gyeonggi-do and Busan-Ulsan regions anchor precision equipment technology advancement.
Tape Applicator Machines Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with fluid handling and adhesive systems expertise determining premium positioning. The structure concentrates around three strategic archetypes: diversified industrial conglomerates with cross-sell capabilities, precision motion specialists with servo control advantages, and regional fabricators serving cost-sensitive packaging corridors. Competitive moves center on outcome-based service contracts with guaranteed uptime thresholds and predictive maintenance infrastructure deployment.
Among diversified industrial conglomerates, 3M Company and Nordson Corporation occupy positions where adhesive chemistry expertise anchors equipment specification influence. Graco Inc. exemplifies the geographic coverage archetype through fluid handling technology cross-sell into packaging end users. Robatech AG sits within the compact architecture specialist tier, representing energy-efficient designs that reduce commissioning complexity for mid-sized converters.
| Leading Market Players |
|---|
| 3M Company |
| Nordson Corporation |
| Graco Inc. |
| Robatech AG |
| Dongguan KEQI Automation Equipment |
| Shurtape Technologies |
| Valco Melton |
| Cyklop |
| Wayne Automation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with Japanese and German precision motion suppliers lock in servo motor and linear encoder access while freezing price visibility for 16-24 week windows, forcing tape applicator OEMs to bake component volatility into equipment quotes for automotive and electronics buyers in Michigan and Bavaria.
Pricing Analysis
Project-based equipment quotations dominate capital sales to automotive assembly plants and battery cell manufacturers, with three-tier pricing structure across premium, standard, and economy levels separating FDA-validated pharmaceutical systems from semi-automatic packaging units and manual benchtop configurations. Price differentiation hinges on CE machinery directive certification tier and after-sales service bundling. Cost compression in mid-tier mechanical positioning segments is intensifying because direct-drive linear motor architectures displace legacy ball-screw systems. Food and beverage packaging converters in Mexico's nearshored corridor exhibit highest price sensitivity, while semiconductor back-end facilities in South Korea show least sensitivity due to uptime cost thresholds exceeding $10,000 per hour.
Supply Chain Analysis
Yokohama Port congestion and Rhine River water level volatility expose just-in-time delivery schedules for precision motion components sourced from Japan and Germany to 16-24 week lead time swings. Component fabrication draws from Taiwanese semiconductor foundries for vision system sensors, German machine shops for linear encoder housings, and Japanese motor windings specialists for servo assemblies. Single-source vulnerability concentrates in direct-drive linear motor stages where two suppliers control sub-50-micron repeatability architectures. Distribution runs through OEM direct sales teams for validated pharmaceutical systems and regional distributor networks for standard packaging equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification fragmentation accelerates as solid-state battery architectures and pharmaceutical cleanroom requirements create non-overlapping technical niches that resist standardization, opening territory for specialized entrants alongside integrated incumbents.
For Market Incumbents: Fortify aftermarket service revenue through predictive maintenance infrastructure and guaranteed uptime outcome-based contracts that offset hardware margin pressure from emerging ultrasonic bonding substitutes. Deepen upstream control over servo motor supply through capacity reservation agreements with Japanese precision motion suppliers, insulating against 16-24 week lead time volatility that disrupts automotive customer delivery schedules. For New Entrants and Emerging Players: Differentiate on AI-driven vision-guided robotics integration for pharmaceutical cleanroom applications where 12-18 month FDA validation timelines filter established supplier pools. Target Mexico's export-oriented packaging corridor with compact, energy-efficient architectures that reduce commissioning complexity for mid-sized converters lacking skilled automation technicians. Pursue distributor partnerships with regional packaging equipment channels rather than direct OEM sales force buildout. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors precision motion specialists with documented CE machinery directive compliance and installed base telemetry infrastructure. Long-term viability across the analysis window rests on positioning for solid-state battery and flexible electronics tolerance compression toward ±0.1 millimeters. Watch for inflection signals in EPA enforcement intensity around National Emission Standards for Hazardous Air Pollutants that would accelerate solvent-based system replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Supply | Captive sourcing from Japanese suppliers insulates against 16-24 week lead time volatility in precision motion components. |
| AI-Driven Vision System Integration | Machine learning defect detection opens premium pricing in pharmaceutical cleanrooms under FDA 21 CFR Part 11 protocols. |
| Outcome-Based Service Contract Rollout | Guaranteed uptime thresholds displace break-fix maintenance in German and United States plants with downtime costs exceeding $10,000 per hour. |
| Geographic Expansion into Mexico Packaging Corridor | Nearshored export demand from United States consumer goods brands favors simplified logistics and faster commissioning. |
| CE Machinery Directive Compliance Investment | Documented quality management systems filter supplier pools for European automotive component belt procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with plant engineers at automotive assembly facilities in Michigan and Bavaria, procurement leads at battery cell manufacturers in China's Pearl River Delta, aftermarket service heads at packaging OEMs, and regulatory affairs specialists navigating FDA 21 CFR Part 11 validation protocols. Secondary validation drew from EPA National Emission Standards for Hazardous Air Pollutants filings, REACH Annex XVII restriction updates, SEC 10-K equipment revenue disclosures, and customs trade data on precision motion component flows. Bottom-up unit shipment estimates triangulated against top-down equipment spending projections across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning automation tier, adhesive chemistry configuration, end-use vertical, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis tied to EPA emissions compliance deadlines and REACH chemical restriction phase-ins. Industry-specific forecast inputs included solid-state battery architecture adoption curves and pharmaceutical cleanroom capital expenditure patterns.
Forecasts assume regulatory continuity in United States EPA enforcement and European REACH implementation; material policy shifts would require re-modeling equipment replacement timing and adhesive chemistry transition trajectories. Practitioners should keep alternative scenarios live as battery safety standard evolution and solid-state cell commercialization timelines mature.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Carry Handle Tape Market
Tapes
Carbon Tapes Market
Tapes
Duct Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Washi Tapes Market
Tapes
Foil Tapes Market
Tapes
Invisible Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Acetate Cloth Tape Market
Tapes
Aluminum Foil Tape Market
Tapes
Masking Tape Market
Tapes
Glue Tape Market