
 Pre-Printed Tape Market | 2026-2036
Pre-Printed Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Printed Tape Market Analytics
Modular packaging configurations are hardening as the dominant procurement logic among enterprise buyers. 3M leverages its adhesive science portfolio to sustain premium positioning across industrial and retail channels. Avery Dennison Corporation anchors North American demand through specialized label-tape hybrid solutions. Tesa SE competes on European automotive and logistics specialization with tightly controlled distribution.
Pre-printed tape denotes adhesive-backed substrates bearing logos, handling instructions, or security patterns prior to application, typically manufactured through flexographic or rotogravure printing on polypropylene, PVC, or reinforced paper backings with hot-melt, acrylic, or rubber-based adhesive layers. Its primary commercial purpose is to merge package sealing with brand communication, traceability, and tamper-evidence in a single operational step. Plastic tape variants dominate volume due to cost scalability, though paper tape is gaining structural share as sustainability mandates intensify across European retail and e-commerce end users. Application-level demand concentrates in packaging, where margin pools sit with custom-printed security and void-pattern products rather than generic branded rolls.
EPA guidelines on volatile organic compound emissions from adhesive manufacturing shape substrate choices for US-based producers, while REACH restricts certain phthalate plasticizers in European tape formulations. FDA indirect food contact rules apply to tapes used in primary food packaging, creating compliance segmentation between industrial and consumer-grade suppliers. ISO 9001 and ISO 14001 certifications function as baseline market-access filters for contract manufacturing relationships. Stakeholders must monitor how extended producer responsibility frameworks for packaging waste alter substrate preferences and regional sourcing patterns.
Market Dynamics
Packaging automation investments across e-commerce fulfillment networks are compressing procurement cycles and forcing tape suppliers to integrate print-to-seal workflows directly into conveyor-line systems, eliminating offline branding steps.
Growth Catalysts
- E-commerce unboxing economics:Branded sealing tapes now function as mobile advertising surfaces, with fulfillment centers in Germany and China prioritizing custom-printed rolls to reduce external packaging costs while reinforcing brand recall at delivery.
- REACH substrate reformulation:European mandates on phthalate-free plasticizers are accelerating migration toward hot-melt acrylic adhesives, creating technical differentiation for compliant suppliers against non-compliant imports.
- Security tape protocols:Void-pattern and tamper-evident formulations are displacing standard branded rolls in pharmaceutical and high-value electronics logistics, driven by chain-of-custody requirements in cross-border trade.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings for biaxially oriented polypropylene directly compress margin pools for volume producers, forcing quarterly contract renegotiations with large-format converters.
- Adhesive supply concentration:Hot-melt formulation expertise concentrates among German and Japanese chemical specialists, creating bottleneck risk for mid-tier tape manufacturers without backward integration into polymer synthesis.
- Paper tape performance ceiling:Fiber-based substrates fail tensile strength thresholds for heavy-load industrial pallets, limiting substitution rates despite sustainability preferences in European retail channels.
Strategic Opportunities
- Indian e-commerce infrastructure:Fulfillment center buildouts by domestic logistics platforms remain under-taped relative to global benchmarks, offering first-mover positioning for security-featured pre-printed products.
- RFID-tape convergence:Integration of passive RFID inlays with printed carrier substrates enables item-level tracking without secondary label application, appealing to automotive component suppliers.
- Extended producer responsibility frameworks:EU packaging waste directives are mandating recyclability disclosures that favor mono-material tape constructions over multi-layer laminates, rewarding substrate innovation.
Industry Challenges
- Flexographic plate turnaround:Short-run customization demands collide with traditional cylinder engraving lead times, requiring capital investment in digital inkjet retrofitting for profitable micro-batch production.
- FDA indirect food contact certification:Tape migration testing timelines stretch 18-24 months for primary food packaging applications, freezing supplier switches until compliance documentation matures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Printed Tape Market |
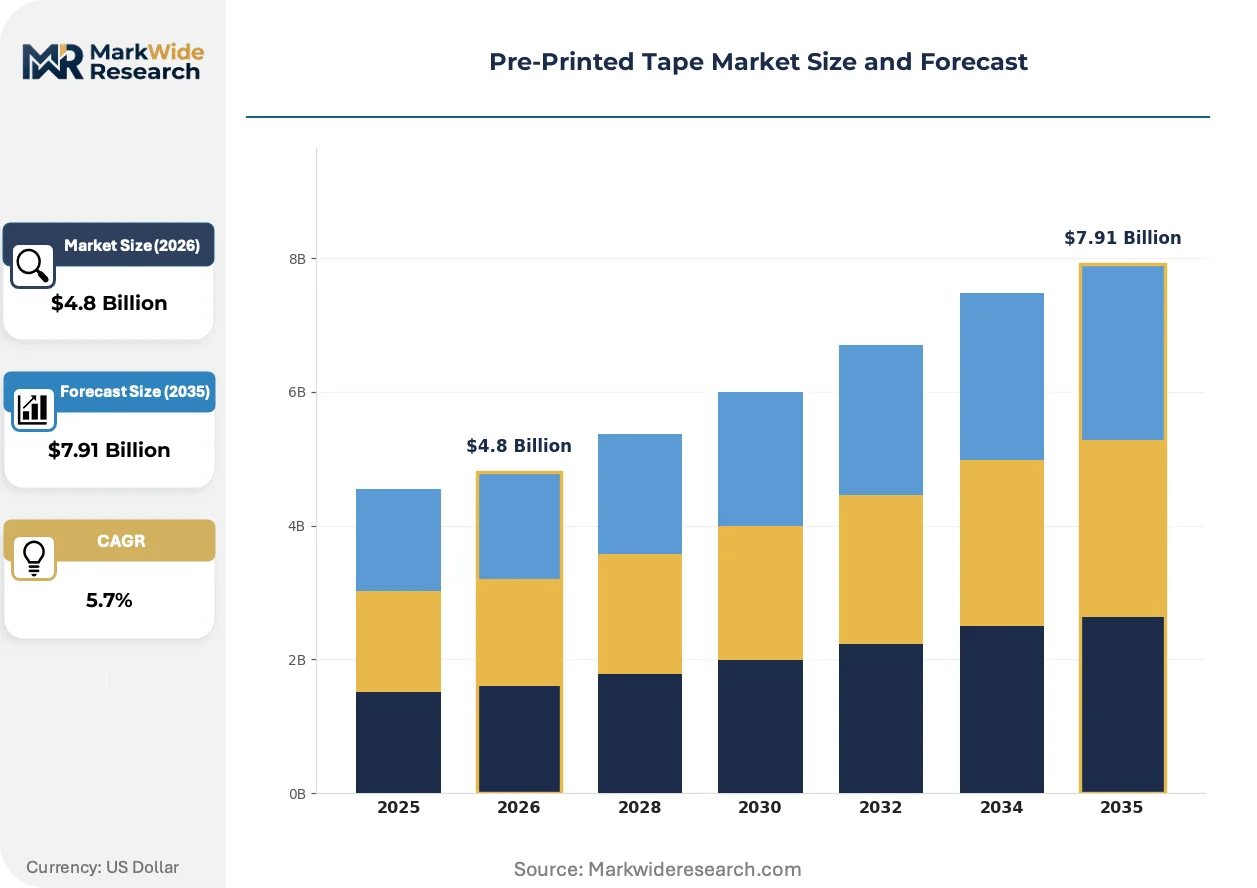
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tape, Plastic Tape, Vinyl Tape, Fabric Tape Application: Packaging, Labeling, Decorative, Industrial Use End User: Retail, E-commerce, Manufacturing, Healthcare Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | 3M, Intertape Polymer Group, Tesa SE, Avery Dennison Corporation, Nitto Denko Corporation, Shurtape Technologies, Scapa Group, Berry Global, Lintec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Printed Tape Market Evolving Landscape
Digital printing infrastructure is collapsing minimum order quantities and enabling SKU proliferation that flexographic systems cannot economically match, reshaping how converters segment their customer base.
Water-based ink formulations for flexographic and rotogravure lines are expanding into high-speed packaging automation previously dominated by solvent systems, with German automotive suppliers now specifying aqueous-printed security tapes for component traceability. The technology eliminates volatile organic compound emissions at the point of application, satisfying EPA guidelines for US-based manufacturing facilities while maintaining print durability through automated dispensing heads. This substrate-ink convergence is compressing the cost gap between standard and custom-printed rolls for mid-volume shippers.
REACH restrictions on phthalate plasticizers in European tape formulations are forcing adhesive reformulation toward bio-based tackifiers and synthetic rubber alternatives, with compliance deadlines accelerating R&D spend among substrate suppliers. The regulation creates segmentation between industrial-grade suppliers with in-house polymer labs and import-dependent distributors lacking formulation control. Food-contact applications face additional EFSA scrutiny on migration limits, privileging suppliers with dual ISO 9001 and ISO 14001 certification stacks.
Unboxing experience investments by direct-to-consumer brands are elevating tape from cost-center to brand asset, with procurement teams now specifying Pantone-matched colors and tactile finishes previously reserved for primary packaging. This specification creep displaces generic printed rolls in premium cosmetics and electronics verticals, concentrating margin with converters offering in-house design services and rapid proofing capabilities. The shift is most visible in US and UK e-commerce clusters where influencer-driven unboxing content drives repeat purchase rates.
Pre-Printed Tape Market Segmentation
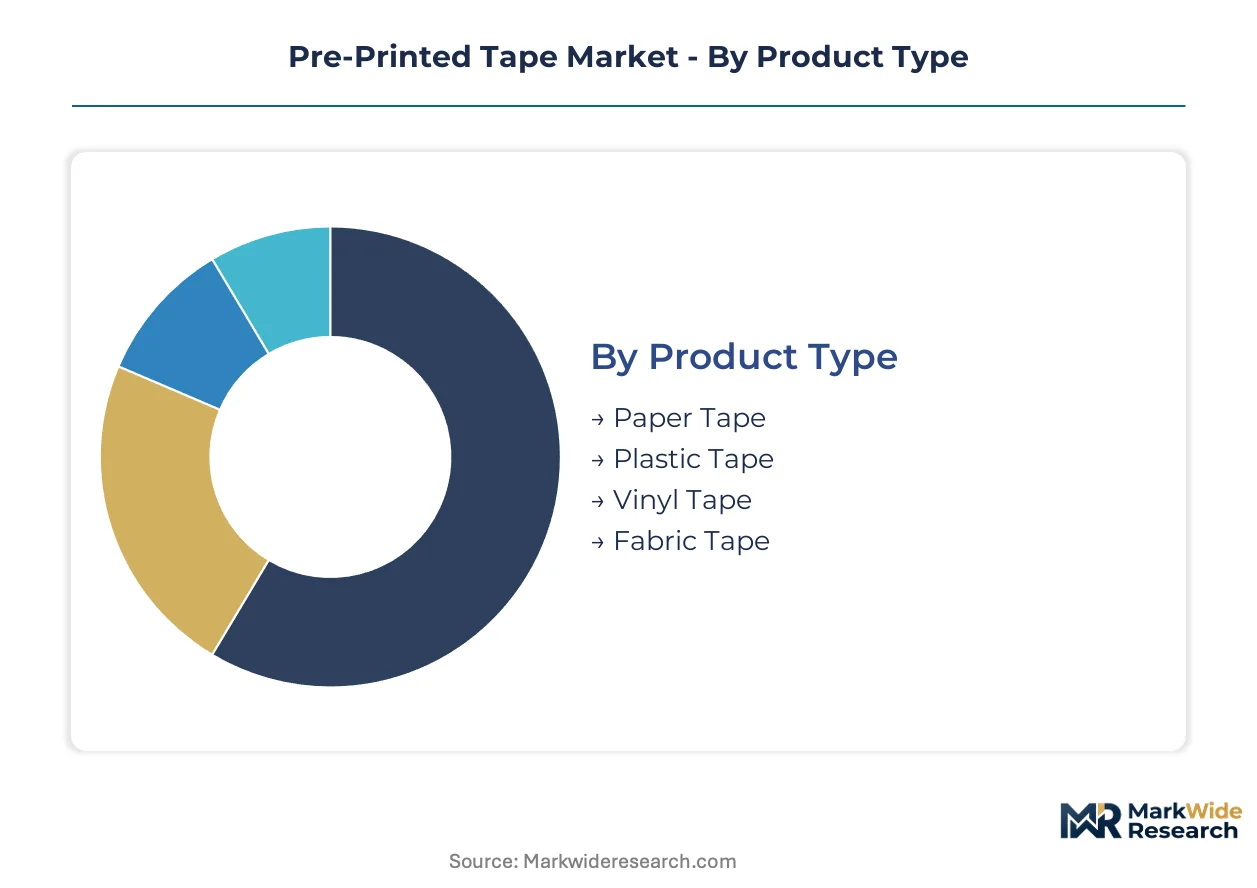
Pre-printed tape procurement splits across substrate chemistry, application intensity, and channel economics. Each dimension carries distinct compliance burdens and margin structures that reshape supplier positioning.
Product Type:
Certification requirements fragment sharply across substrate families. FDA indirect food contact rules apply selectively to paper and plastic tapes in primary packaging, while vinyl formulations face REACH phthalate restrictions in European supply chains.
- Paper Tape:Kraft and reinforced fiber substrates use starch or dextrin adhesives for recyclable mono-material construction. E-commerce fulfillment centers in Germany and France specify aqueous-printed paper tapes to satisfy EU packaging waste directives, though tensile limitations exclude heavy-load pallet applications.
- Plastic Tape:Biaxially oriented polypropylene dominates volume with hot-melt or acrylic adhesive layers. US-based converters optimize for EPA VOC emission guidelines through solvent-free coating lines, serving high-velocity automated packaging operations where print durability and dispensing reliability outweigh substrate premiums.
- Vinyl Tape:PVC backings with rubber-based adhesives deliver conformability on irregular surfaces. REACH compliance deadlines are forcing reformulation toward bio-based plasticizers.
- Fabric Tape:Woven cotton or synthetic reinforcements target industrial bundling and carpet installation. Niche specifications limit standardization.
Plastic tape sits at the top of the volume ranking, with paper tape climbing the fastest.
Application:
Application intensity determines adhesive specification depth and print complexity requirements. High-frequency automated lines demand thermal-stable inks and low-noise unwind properties absent in decorative or intermittent-use segments.
- Packaging:Carton sealing and pallet stabilization consume the majority of pre-printed tape volume. Security-featured void patterns and tamper-evident formulations command premium positioning in pharmaceutical and electronics logistics, where chain-of-custody documentation requirements are tightening across US FDA and EU EMA jurisdictions.
- Labeling:Pre-printed carrier substrates merge identification and sealing functions, reducing secondary label application steps. Automotive component suppliers in Germany and Japan specify Pantone-matched colors and RFID integration for item-level traceability through assembly lines.
- Decorative:Tactile finishes and metallic foils serve premium cosmetics and gift packaging. Short-run digital printing enables micro-batch customization.
- Industrial Use:Masking, bundling, and floor marking applications prioritize adhesive cohesion over print sophistication. Temperature resistance specifications vary by manufacturing vertical.
Packaging captures the dominant revenue share, with labeling expanding most quickly through automation integration.
End User:
End-user procurement sophistication ranges from cost-center commodity buying to brand-asset specification. E-commerce and retail verticals drive custom-printed demand, while healthcare and manufacturing segments impose technical compliance filters.
- Retail:Brick-and-mortar chains specify branded sealing tapes for in-store packaging and promotional displays. Seasonal campaign turnover demands rapid proofing and digital print flexibility.
- E-commerce:Fulfillment centers treat tape as mobile advertising surface, with unboxing experience investments elevating specification to Pantone matching and tactile varnish. Direct-to-consumer brands in the US and UK cluster concentrate procurement with converters offering in-house design services.
- Manufacturing:Component traceability and lot-number printing dominate requirements. Automotive and electronics suppliers in China and Germany specify void-pattern security tapes for cross-border shipment integrity.
- Healthcare:FDA and EMA serialization mandates drive tamper-evident and authentication-featured tape adoption. Migration testing timelines stretch supplier relationships.
E-commerce sits at the top of the volume ranking, with healthcare climbing the fastest on regulatory compulsion.
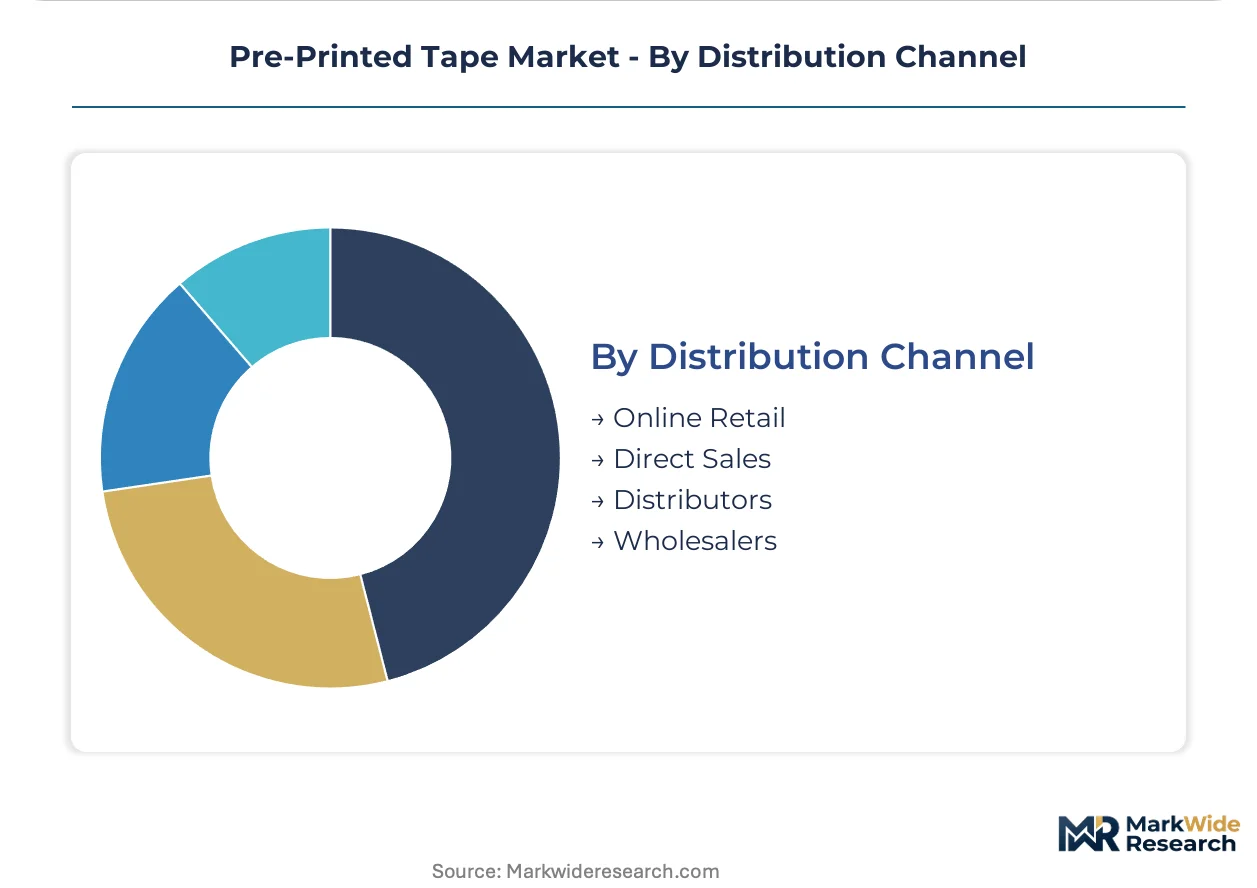
Distribution Channel:
Channel selection reflects order scale, customization depth, and technical support requirements. Large-format converters prefer direct relationships for security-featured products, while standardized rolls flow through wholesale tiers.
- Online Retail:E-procurement platforms serve small and mid-volume shippers with catalog-standard printed tapes. Minimum order quantities compress through digital printing infrastructure.
- Direct Sales:Converter-direct relationships dominate custom security tape and FDA-certified food-contact applications. Technical collaboration on adhesive formulation and print proofing locks in multi-year contracts.
- Distributors:Regional industrial supply houses stock standard branded and handling-instruction tapes for manufacturing maintenance buyers.
- Wholesalers:Volume aggregation serves price-sensitive packaging operations with generic printed rolls and rapid replenishment.
Direct sales sits at the top of the margin ranking, with online retail gaining share fastest among small-format entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pre-printed tape industry traces its industrial scaling to post-war packaging automation in Germany and the United States, where flexographic printing on adhesive substrates first merged brand communication with sealing efficiency.
United States
E-commerce fulfillment centers in California and Texas drive specification upgrades toward Pantone-matched branded tapes that reduce external packaging costs. EPA volatile organic compound guidelines on adhesive manufacturing shape substrate choices for domestic converters. The Chicago-Midwest corridor concentrates automated packaging line integration, where print-to-seal workflows eliminate offline branding steps.
Germany
Automotive component suppliers in Bavaria and Baden-Württemberg specify void-pattern security tapes for cross-border shipment traceability. REACH phthalate restrictions on plasticizers force adhesive reformulation toward hot-melt acrylic systems. The Rhine-Ruhr industrial belt hosts specialized converters serving logistics networks with EFSA-compliant food-contact constructions.
China
Domestic logistics platforms in the Yangtze River Delta and Pearl River Delta expand fulfillment infrastructure with security-featured pre-printed products. GB standards on packaging materials influence substrate selection for export-oriented manufacturers. Shenzhen-Guangzhou clusters lead RFID-tape convergence trials for electronics component tracking.
India
E-commerce fulfillment buildouts by domestic logistics platforms in Maharashtra and Karnataka remain under-taped relative to global benchmarks. BIS certification requirements for adhesive products create compliance segmentation between industrial-grade suppliers and import-dependent distributors. The Delhi-NCR corridor attracts first-mover positioning for branded sealing tape converters.
United Kingdom
Direct-to-consumer brands in London and the Southeast prioritize unboxing experience investments, elevating tape specification to tactile finishes. Extended producer responsibility frameworks under EU packaging waste directives mandate recyclability disclosures favoring mono-material constructions. Manchester-Northwest logistics hubs drive demand for tamper-evident pharmaceutical logistics solutions.
Pre-Printed Tape Market Competitive Landscape
The competitive structure tilts toward diversified adhesive science conglomerates with backward integration into polymer synthesis. Three to four global manufacturers control premium positioning through captive raw material supply and certification stacks, while regional converters compete on short-run digital flexibility. Specialist security-tape formulators and private-label distributors occupy distinct tier positions. Dominant competitive moves include adhesive formulation licensing partnerships and digital inkjet retrofitting of legacy flexographic lines.
Among diversified conglomerates, 3M and Tesa SE exemplify the adhesive science archetype with upstream control over polymer development. Avery Dennison Corporation occupies a position bridging label-tape hybrid solutions with brand-asset specification workflows. These three anchors represent how certification depth and print-to-seal integration capabilities separate premium-tier suppliers from commodity converters.
| Leading Market Players |
|---|
| 3M |
| Intertape Polymer Group |
| Tesa SE |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Shurtape Technologies |
| Scapa Group |
| Berry Global |
| Lintec Corporation |
| Others |
Value Network & Pricing Analysis
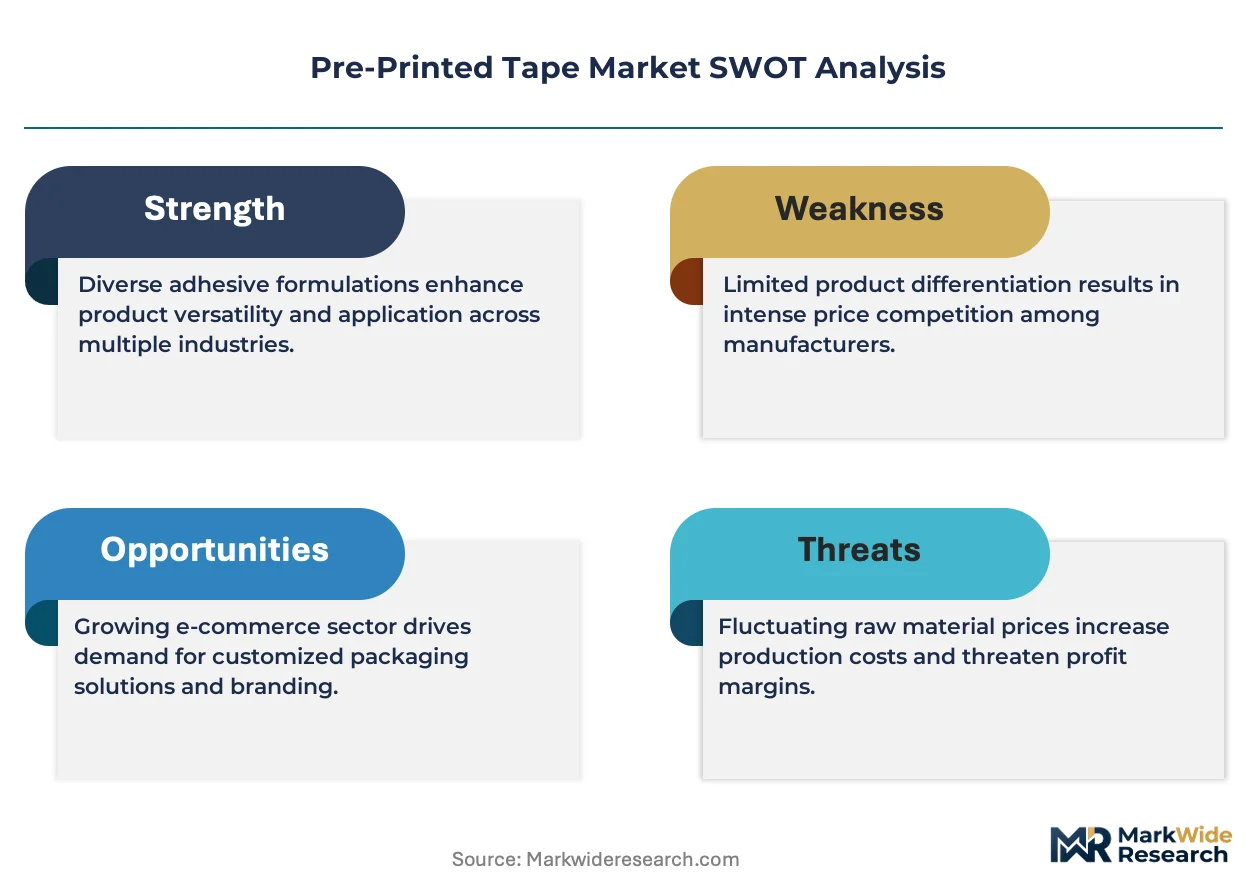
Polypropylene resin volatility cascades through three distinct pricing tiers, with biaxially oriented polypropylene feedstock swings compressing margin pools for volume producers and forcing quarterly contract renegotiations with large-format converters in Germany and the United States. Hot-melt adhesive formulation expertise concentrates among German and Japanese chemical specialists, creating bottleneck risk that amplifies cost pass-through to mid-tier tape manufacturers lacking backward integration into polymer synthesis.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and volume scale. FDA indirect food contact certification and REACH phthalate compliance command tier-one positioning, while generic branded rolls compete on price in high-volume e-commerce fulfillment. Cost compression in the standard tier is intensifying because polypropylene resin volatility forces converters to index contracts to commodity benchmarks. Small and mid-volume shippers exhibit highest price sensitivity, whereas pharmaceutical and automotive buyers prioritize security-featured formulations over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German automotive suppliers and US pharmaceutical distributors mandate multi-supplier qualification for security-tape formulations, preventing single-source dependency even when technical specifications narrow the vendor pool. Manufacturing gravity centers on Germany, China, and the United States, with substrate production drawing from petrochemical feedstocks in the US Gulf Coast and specialty adhesive polymers from Japanese and German chemical specialists. Single-source vulnerability concentrates in hot-melt formulation expertise. Distribution runs through converter-direct relationships for custom security products and regional industrial distributors for standardized rolls.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-printed tape functions as a regulatory compounder where REACH phthalate restrictions and FDA indirect food contact mandates continuously elevate compliance barriers and consolidate demand around certified suppliers.
For Market Incumbents: Acquire digital inkjet retrofitting capabilities to collapse minimum order quantities and capture micro-batch customization demand from direct-to-consumer brands. Secure captive supply of hot-melt acrylic adhesives to defend against formulation bottlenecks from German and Japanese chemical specialists. Lock in multi-year contracts with e-commerce fulfillment centers by integrating print-to-seal workflows directly into conveyor-line systems. For New Entrants and Emerging Players: E-procurement platform penetration offers lowest barrier entry for small-format shippers seeking catalog-standard printed tapes with compressed minimum order quantities. Target Indian e-commerce fulfillment buildouts in Maharashtra and Karnataka, where infrastructure remains under-tapped relative to global benchmarks. Lead with rapid digital proofing capabilities and Pantone-matched color services to differentiate from legacy flexographic converters. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier converters lack ISO 9001 and ISO 14001 certification stacks required for contract manufacturing relationships with enterprise buyers. Long-term viability favors suppliers with backward integration into adhesive formulation and substrate production. Watch RFID-tape convergence trials in Shenzhen-Guangzhou electronics clusters as inflection indicator for next-generation traceability demand.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Inkjet Retrofitting | Collapses minimum order quantities for micro-batch customization serving direct-to-consumer brands. |
| Backward Integration into Adhesive Synthesis | Secures captive supply of REACH-compliant hot-melt acrylic formulations against specialist bottlenecks. |
| RFID-Tape Convergence Development | Enables item-level traceability for automotive component suppliers without secondary label application. |
| Extended Producer Responsibility Compliance | Positions mono-material tape constructions to capture EU packaging waste directive procurement. |
| Print-to-Seal Workflow Integration | Eliminates offline branding steps in automated packaging lines serving high-velocity fulfillment centers. |
Research Methodology
Direct dialogue with tape converter operations managers, adhesive formulation chemists at German and Japanese specialists, e-commerce fulfillment procurement directors, and automotive component supply chain leads grounded qualitative findings. Secondary validation drew from EPA VOC emission guidelines, REACH substance restriction databases, FDA indirect food contact rulings, and customs trade data on polypropylene resin flows. Bottom-up demand modeling across substrate types, applications, and end-user verticals triangulated against top-down macroeconomic indicators.
Bottom-up volume and value outputs reflect a triangulated approach across the analysis window, with segmentation dimensions including substrate chemistry, application intensity, end-user procurement sophistication, and channel economics. CAGRs derived from historical trajectory analysis adjusted for regulatory milestone impacts and automation investment cycles. Forecast inputs incorporated e-commerce fulfillment center buildout rates and REACH compliance deadline acceleration effects on adhesive reformulation demand.
The model assumes a particular technology adoption path; alternative pathways for water-based ink flexographic systems would alter the outlook if solvent-free coating lines achieve cost parity at higher speeds than projected. Deviation in polypropylene resin price volatility or REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Coding Foils and Tapes Market
Tapes
India Reflective Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Smart Card Tapes Market
Tapes
UV Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Seam Tapes Market
Tapes
Release Tape Market
Tapes
Heat Sealing Tape Market
Tapes
Filament Tapes Market
Tapes
Filmic Tapes Market
Tapes
Lacing Tape Market
Tapes
Tapes Market
Tapes
Shipping Tapes Market