
 UV Cured Acrylic Foam Tapes Market | 2026-2036
UV Cured Acrylic Foam Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
UV Cured Acrylic Foam Tapes Market Analytics
UV-cured acrylic formulation chemistry is reconfiguring how manufacturers achieve structural bonding without mechanical fasteners. 3M Company leverages its polymer science infrastructure to sustain leadership in high-performance automotive bonding solutions. Henkel AG & Co. KGaA anchors its position through integrated adhesive systems that serve electronics assembly lines across multiple continents. Avery Dennison Corporation differentiates through precision coating capabilities that control thickness tolerances for critical applications.
UV cured acrylic foam tapes comprise pressure-sensitive adhesive layers cured by ultraviolet radiation, typically ranging from 0.25 mm to 3.0 mm in thickness, formulated from cross-linked acrylic polymers that deliver viscoelastic energy absorption and permanent bonding strength. The primary industrial purpose centers on replacing welds, rivets, and liquid adhesives in applications requiring vibration damping, gap filling, and thermal expansion accommodation across dissimilar substrates. Double-sided tape configurations command the largest volume share due to their ubiquity in automotive panel attachment and electronics lamination, while transfer tape grades capture disproportionate margin pools in semiconductor and display manufacturing where residue-free precision matters. Clear tape variants are gaining fastest in optical bonding applications for consumer electronics, though adhesive strips in pre-cut formats remain the most mature segment with limited growth upside.
FDA regulations govern indirect food-contact adhesive applications in packaging and processing equipment, while EPA emissions standards shape solvent-free curing technology investments across US manufacturing bases. REACH chemical registration requirements in Europe restrict certain monomer inputs, creating compliance barriers for non-integrated compounders. OSHA workplace exposure limits for photoinitiator byproducts influence production line engineering decisions. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as fluorinated surfactants historically used in tape release liners face intensifying regulatory scrutiny that could force reformulation investments.
Market Dynamics
Automotive OEMs are systematically replacing mechanical fasteners with UV-cured acrylic foam tapes to achieve lightweight vehicle assemblies, creating a structural pull that concentrates demand around precision manufacturing corridors.
Growth Catalysts
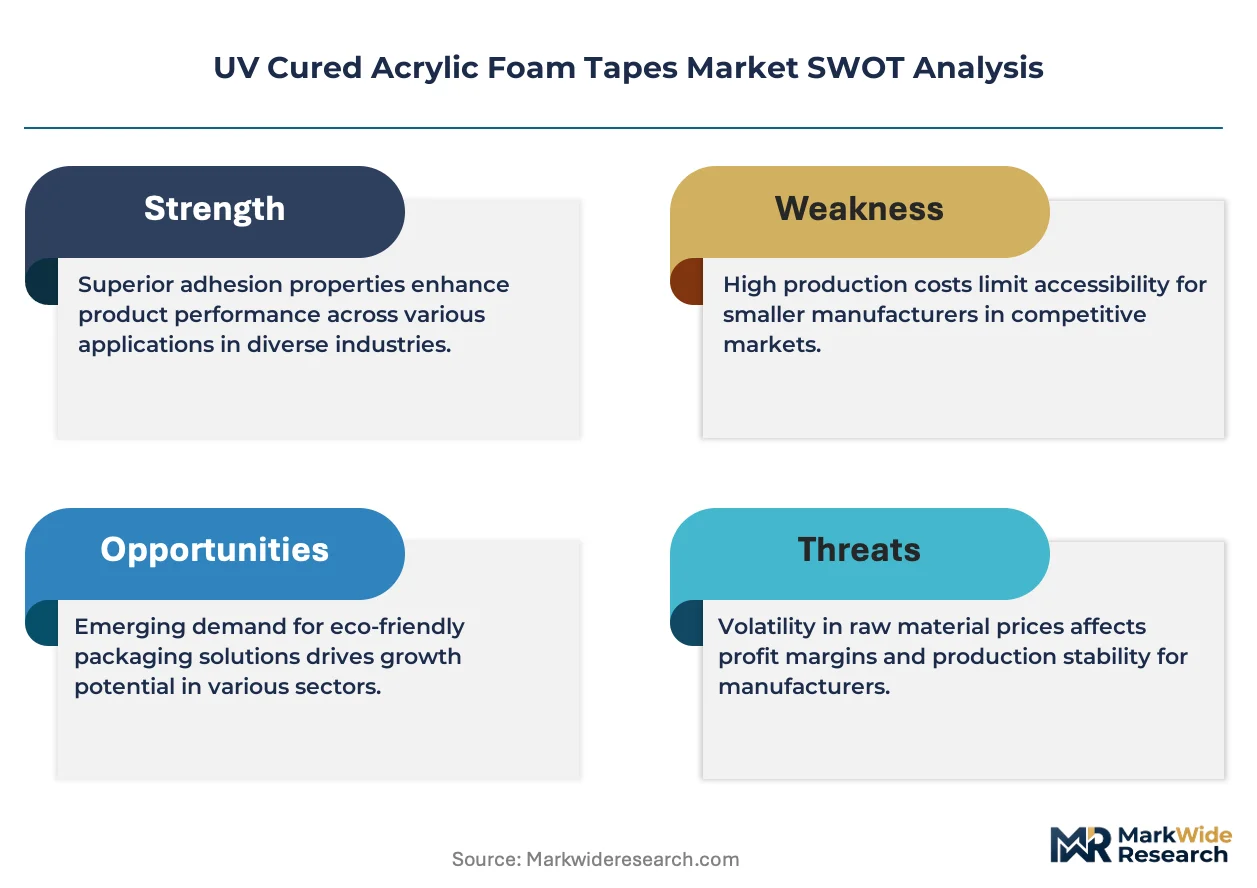
- REACH compliance thresholds:European chemical registration requirements are accelerating solvent-free adhesive adoption as manufacturers reformulate to meet restricted monomer limits.
- Automotive electrification:Battery pack assembly lines require vibration-damping bonding solutions that accommodate thermal expansion across dissimilar substrates without conductivity risks.
- Optical bonding surge:Consumer electronics manufacturers in precision manufacturing clusters are specifying clear tape variants for display lamination applications.
Market Restraints
- Photoinitiator supply concentration:Specialty chemical production for UV-curing agents clusters in limited manufacturing bases, exposing compounders to input volatility.
- PFAS regulatory friction:Fluorinated surfactants historically used in release liners face intensifying scrutiny across multiple jurisdictions, forcing premature reformulation cycles.
- Hot-melt substitution threat:Reactive polyurethane adhesives offer comparable bond strength at lower capital equipment requirements for mid-tier applications.
Strategic Opportunities
- India's electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating demand for residue-free precision bonding in cleanroom environments.
- Solar module encapsulation:Bifacial photovoltaic panel assembly requires edge-sealing tapes that withstand thermal cycling and UV exposure without degradation.
- Medical device miniaturization:Wearable diagnostic equipment assembly lines are adopting transfer tape grades for component positioning in constrained form factors.
Industry Challenges
- Photopolymer formulation expertise:Cross-linked acrylic chemistry requires specialized polymer scientists that compounders struggle to recruit in competitive labor markets.
- Dual certification timelines:FDA indirect food-contact approval combined with automotive OEM qualification protocols extend product launch cycles by 18-24 months.
- Legacy adhesive removal:Manufacturing lines transitioning from solvent-based systems face downtime costs and workforce retraining requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Cured Acrylic Foam Tapes Market |
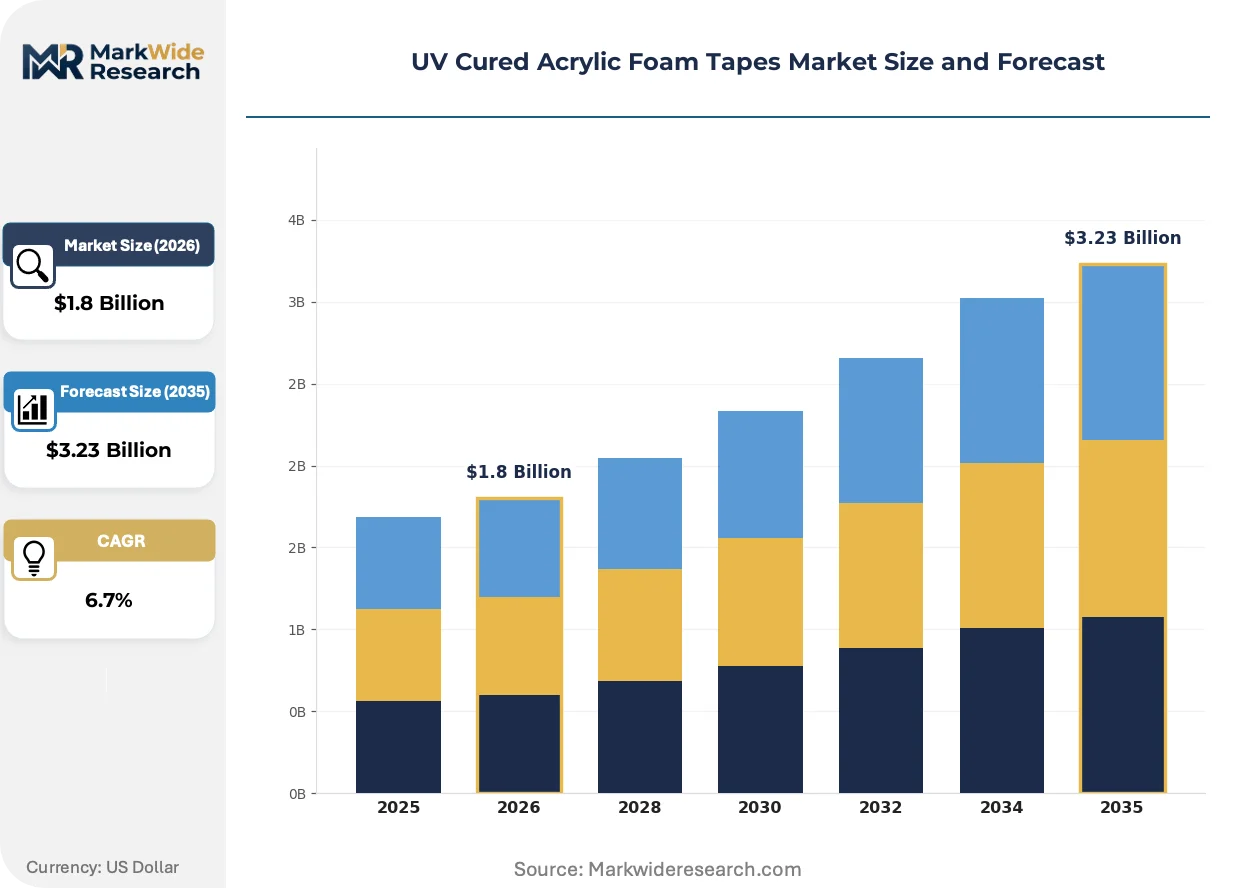
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Tape, Double-Sided Tape, Transfer Tape, Adhesive Strips Application: Automotive Assembly, Electronics Manufacturing, Construction, Packaging End User: Manufacturers, Retailers, Distributors, Contractors Form Factor: Rolls, Sheets, Pre-Cut Shapes, Custom Sizes |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Avery Dennison Corporation, Tesa SE, Nitto Denko Corporation, Scapa Group plc, H.B. Fuller Company, Saint-Gobain, Toyochem Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Cured Acrylic Foam Tapes Market Evolving Landscape
Formulation chemistry and curing equipment are converging to enable thinner, higher-performance bonding layers that displace mechanical attachment across precision assembly applications.
Low-VOC acrylic formulations are migrating from niche medical applications to mainstream automotive interiors as OEMs respond to EPA emissions standards and interior air quality protocols. Tier-1 suppliers in Germany's industrial corridor are qualifying sub-0.5mm tapes for dashboard assembly. This migration from solvent-cured to radiation-cured systems is compressing the competitive set for traditional adhesive compounders.
REACH authorization requirements for specific acrylate monomers are forcing reformulation investments across European manufacturing bases. ECHA's evolving substance evaluation list is redirecting R&D spending toward bio-based photoinitiators and alternative cross-linking chemistries. Specialty tape manufacturers serving automotive and electronics verticals are accelerating qualification programs for monomers with favorable toxicological profiles.
Consolidated procurement functions at major automotive OEMs are unbundling adhesive specification from tiered supply contracts, creating direct relationships with tape manufacturers. This disintermediation of traditional distribution channels is visible most acutely in Germany, where BMW and Volkswagen Group have established approved vendor lists for structural bonding materials that bypass conventional chemical distributors.
UV Cured Acrylic Foam Tapes Market Segmentation
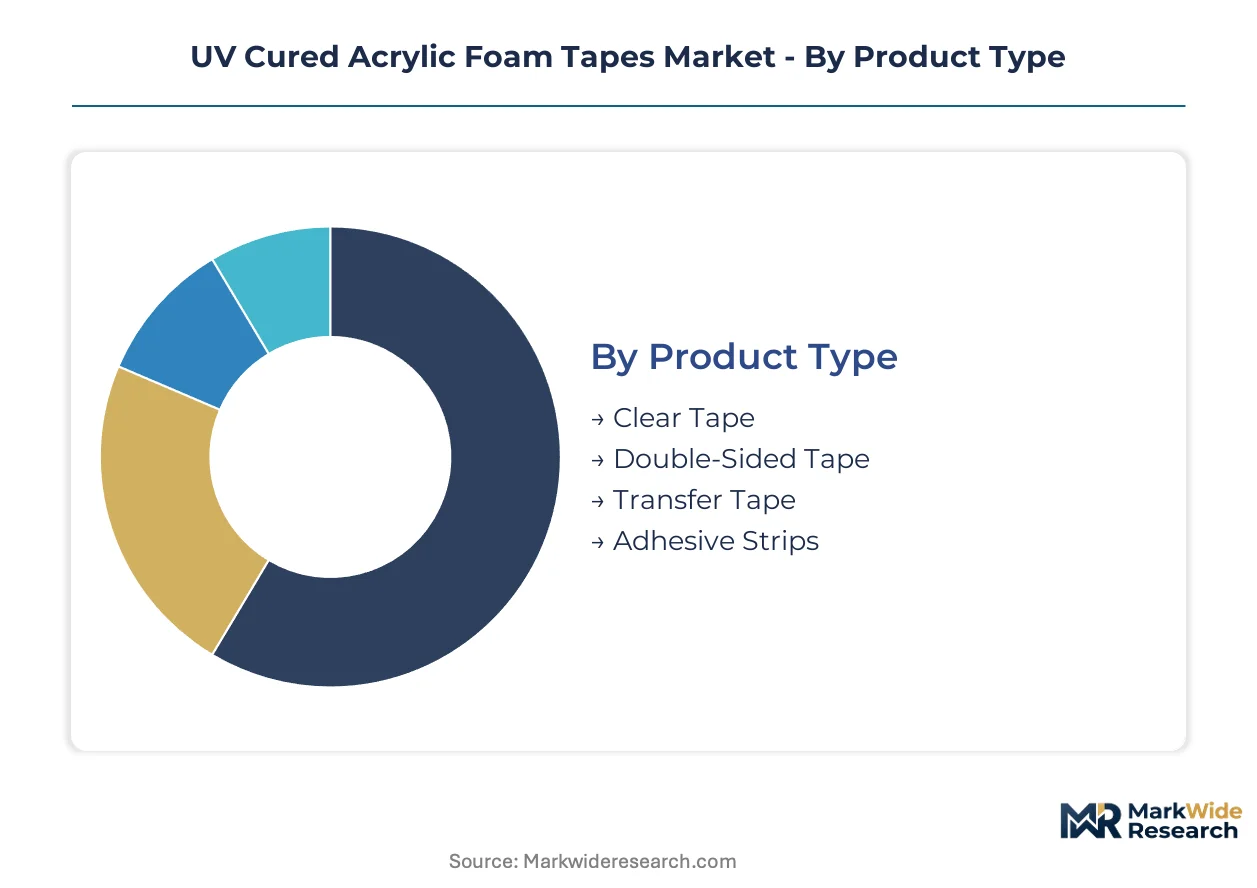
UV cured acrylic foam tapes serve divergent bonding requirements across precision assembly and heavy-duty industrial applications. Segmentation reveals how formulation chemistry and physical configuration align with specific performance thresholds and regulatory constraints.
Product Type:
Use-case spectrum spans optical clarity demands in consumer electronics through structural load-bearing in automotive panels, with each product category optimized for distinct substrate compatibility and curing protocols.
- Double-Sided Tape:Cross-linked acrylic layers on both faces of viscoelastic foam cores deliver permanent bonding with vibration damping across dissimilar metals. Automotive OEMs in Germany's industrial corridor specify these grades for lightweight body-in-white assemblies where weld replacement reduces galvanic corrosion risks.
- Clear Tape:Optically transparent adhesive layers without color shift enable display lamination and touch sensor bonding where visual transmission exceeds 90%. Electronics manufacturers in precision manufacturing clusters are expanding specifications for these variants as bezel-less display designs proliferate.
- Transfer Tape:Adhesive-only constructions without carrier substrates achieve sub-0.1mm bonding lines for semiconductor die attach and micro-component positioning.
- Adhesive Strips:Pre-cut rectangular formats in standardized dimensions serve maintenance and repair operations with minimal tooling requirements.
Established volume favors Double-Sided Tape; emerging adoption favors Clear Tape.
Application:
End-use concentration determines formulation investment priorities, with certification requirements and qualification timelines varying substantially across verticals.
- Automotive Assembly:Structural bonding applications require crash-resistant adhesion that maintains integrity across temperature cycles from -40°C to 150°C. Battery pack manufacturers specify these tapes for module-to-housing attachment where thermal expansion accommodation prevents cell damage.
- Electronics Manufacturing:Cleanroom-compatible formulations with low outgassing properties satisfy semiconductor and display fabrication protocols. REACH-compliant monomer selections are mandatory for equipment exported to European assembly lines.
- Construction:Weather-resistant acrylic formulations bond facade elements and interior fixtures where mechanical fastening would compromise thermal envelopes or aesthetic surfaces.
- Packaging:FDA indirect food-contact approvals govern adhesive selection for processing equipment and secondary packaging machinery in US dairy and beverage facilities.
Revenue concentration sits with Automotive Assembly; steepest expansion trajectory belongs to Electronics Manufacturing.
End User:
Procurement authority and technical specification control differentiate how tape grades enter production workflows.
- Manufacturers:Direct OEM relationships enable collaborative formulation development for qualified material lists, with automotive and electronics producers maintaining approved vendor programs that bypass distribution intermediaries.
- Distributors:Technical stocking distributors serve mid-tier fabricators with cut-to-width services and application engineering support for bonding process transitions.
- Retailers:Big-box and specialty channels move standardized dimensions for maintenance, repair, and small-scale fabrication where performance specifications are less stringent.
- Contractors:Construction and installation trades purchase job-lot quantities with delivery timing aligned to project schedules.
Specification control concentrates with Manufacturers; margin capture concentrates with Distributors.
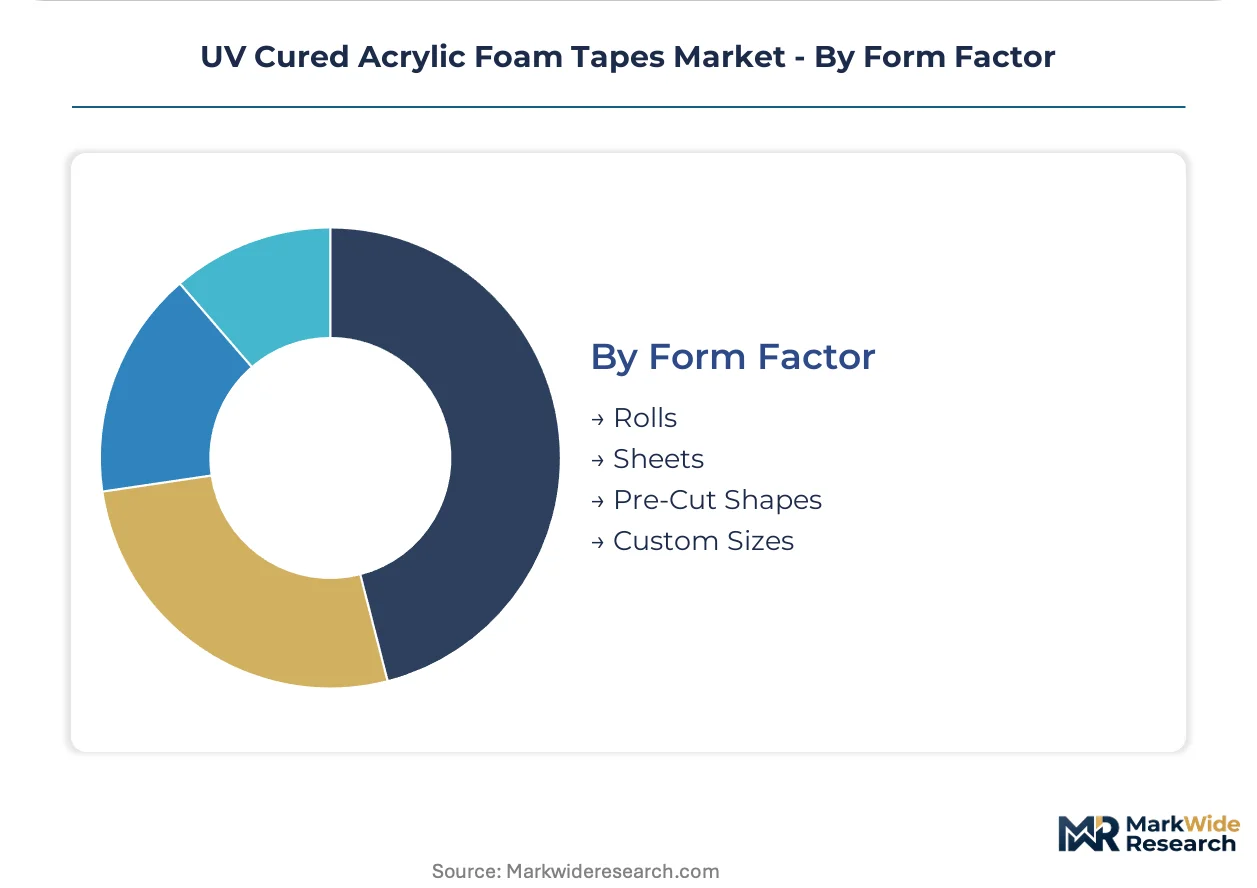
Form Factor:
Physical presentation determines equipment compatibility and labor efficiency in high-volume bonding operations.
- Rolls:Continuous web formats enable automated dispensing systems in automotive and electronics assembly lines where throughput rates exceed manual application limits.
- Pre-Cut Shapes:Die-cut geometries eliminate on-site trimming for component-specific bonding patterns in medical device and wearable equipment manufacturing.
- Sheets:Flat stock formats serve laminating presses and flatbed die-cutting operations for gasket and spacer fabrication.
- Custom Sizes:Made-to-order dimensions address prototyping requirements and specialized industrial equipment where standard formats generate excessive waste.
Production efficiency favors Rolls; customization value favors Pre-Cut Shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and precision electronics manufacturers concentrate procurement authority in industrial corridors where REACH compliance and lightweight assembly specifications intersect. Tape suppliers establish technical service centers adjacent to these buyer clusters to compress qualification timelines.
Germany
Automotive OEMs in Stuttgart and Munich specify sub-0.5mm tapes for dashboard and battery pack assemblies. ECHA substance evaluation lists redirect formulation R&D toward bio-based photoinitiators. Bavaria's industrial corridor hosts qualification programs for monomers with favorable toxicological profiles.
United States
EPA emissions standards accelerate solvent-free curing investments across Michigan and Ohio automotive bases. FDA indirect food-contact approvals govern adhesive selection for dairy processing equipment. Detroit-area battery manufacturers specify vibration-damping bonding for thermal expansion accommodation.
China
MIIT industrial policies support domestic adhesive compounders serving Yangtze River Delta electronics clusters. SAMR quality standards shape display lamination specifications for consumer electronics. Shenzhen precision manufacturers expand clear tape adoption for bezel-less display designs.
Japan
METI carbon neutrality targets pressure automotive suppliers in Nagoya and Tokyo to eliminate mechanical fasteners. JIS standards govern adhesive performance in hybrid vehicle assemblies. Osaka-area electronics fabricators qualify transfer tapes for semiconductor die attach applications.
South Korea
MFDS medical device regulations create demand for low-outgassing formulations in Seoul Capital Area wearable diagnostic equipment. Busan-Ulsan automotive plants specify crash-resistant adhesion for electric vehicle platforms. Government R&D programs support UV-curing equipment localization.
UV Cured Acrylic Foam Tapes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Consolidated procurement functions at major automotive OEMs disintermediate traditional chemical distributors, creating direct specification relationships with tape manufacturers. Three archetypes dominate: integrated polymer science conglomerates with captive raw material positions, precision coating specialists with thickness tolerance control, and regional compounders serving mid-tier fabricators. Competitive moves center on qualification program acceleration and geographic proximity to precision manufacturing clusters.
Within the integrated polymer science tier, 3M Company and Henkel AG & Co. KGaA exemplify players with backward integration into monomer synthesis and photoinitiator supply. Among precision coating specialists, Avery Dennison Corporation occupies a position defined by thickness control capabilities for optical bonding applications. These three anchors represent distinct competitive vectors: broad formulation libraries, systems integration across adhesive portfolios, and precision manufacturing process control.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Tesa SE |
| Nitto Denko Corporation |
| Scapa Group plc |
| H.B. Fuller Company |
| Saint-Gobain |
| Toyochem Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Germany's industrial corridor around Stuttgart and Munich concentrates photoinitiator production capacity and precision coating infrastructure, giving integrated compounders pricing leverage over mid-tier distributors serving automotive OEMs. REACH compliance investments and acrylate monomer qualification timelines compress margin pools for non-integrated players while reinforcing the bargaining position of backward-integrated suppliers with captive raw material positions.
Pricing Analysis
Cost-plus contracts with acrylate monomer indexation dominate procurement relationships between tape manufacturers and automotive OEMs, with quarterly adjustments tracking petrochemical feedstock volatility. Price differentiation hinges on certification tier—FDA indirect food-contact and automotive OEM qualification status—and volume scale, with high-volume electronics contracts commanding standard-grade economics while medical device applications sustain premium positioning. Cost compression in mid-tier industrial grades is intensifying because hot-melt polyurethane adhesives offer comparable bond strength at lower capital equipment thresholds. Tier-1 automotive manufacturers exhibit the lowest price sensitivity due to qualification lock-in effects, whereas maintenance and repair contractors purchasing adhesive strips through retail channels face the highest elasticity.
Supply Chain Analysis
Supplier-financing structures including 90-day extended payment terms and supply-chain finance facilities have become standard in procurement relationships between German tape manufacturers and Yangtze River Delta electronics assemblers. Manufacturing capacity clusters in Germany, China, and Japan, with specialty photoinitiator production concentrated in Bavarian chemical parks and Osaka-area polymer facilities. Raw material dependencies encompass acrylate monomers, viscoelastic foam cores, and fluorinated release liners—though PFAS regulatory restrictions are forcing liner reformulation toward silicone alternatives. Single-source vulnerability in photoinitiator supply exposes compounders to input disruption when ECHA substance evaluations restrict specific chemistries. Distribution runs through direct OEM vendor programs for automotive and electronics verticals, bypassing traditional chemical distributors in consolidated procurement structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV cured acrylic foam tapes represent a service-attach opportunity where application engineering support and qualification program management generate recurring revenue streams expanding faster than base tape volumes. Technical service contracts for bonding process transitions and on-site curing equipment calibration now capture margin pools that hardware margins alone cannot sustain.
For Market Incumbents: Build formulation moats around REACH-compliant monomer libraries and bio-based photoinitiator patents before ECHA substance evaluations restrict legacy chemistries. Secure backward integration into acrylate monomer synthesis to isolate margin pools from petrochemical volatility, while accelerating dual-certification programs for FDA indirect food-contact and automotive OEM qualification to extend product launch cycles as a competitive barrier against emerging compounders. For New Entrants and Emerging Players: Establish a beachhead in India's electronics manufacturing corridor where PLI scheme incentives for semiconductor fabrication are creating demand for residue-free precision bonding in cleanroom environments. Target solar module encapsulation applications for bifacial photovoltaic edge-sealing tapes, where thermal cycling performance requirements favor UV-cured acrylic chemistry over incumbent alternatives, and pursue technical stocking distributor relationships to bypass direct OEM qualification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because procurement disintermediation at major automotive OEMs is compressing the viable competitive set to integrated compounders with captive raw material positions and precision coating capabilities. Acquisition targets should display thickness tolerance control for optical bonding applications and established qualification status with BMW or Volkswagen Group approved vendor lists. Monitor ECHA substance evaluation announcements as the critical signal for reformulation-driven market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive acrylate supply insulates margin pools from REACH-driven raw material volatility. |
| Dual Certification Acceleration | Combined FDA and automotive OEM qualification extends product launch cycles as competitive moats. |
| Application Engineering Service Contracts | On-site curing equipment calibration generates recurring revenue exceeding hardware margins. |
| Geographic Expansion into India Electronics Corridor | PLI scheme incentives for semiconductor fabrication create cleanroom bonding demand. |
| Bio-based Photoinitiator R&D Investment | ECHA substance evaluation redirection favors monomers with favorable toxicological profiles. |
Research Methodology
A standing panel of automotive OEM platform engineers, electronics manufacturing procurement leads, adhesive compounder R&D directors, and technical distribution channel managers provided ongoing calibration across the study period. Primary interviews with these stakeholders were combined with secondary validation from SEC 10-K filings of listed chemical companies, ECHA substance evaluation databases, customs and trade flow data, and automotive production statistics from IHS Markit. Bottom-up triangulation across tape grade volumes and top-down reconciliation against end-use industry consumption patterns ensured analytical consistency.
Scenario-bracketing around regulatory acceleration and substitution threat intensity framed the projection horizon, with segmentation modeling across product type, application vertical, end-user procurement authority, and form factor. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting penetration rates and electronics lamination specification shifts. Industry-specific forecast inputs included battery pack assembly line adoption curves for electric vehicle platforms and solar module encapsulation tape qualification timelines.
Stress conditions across photoinitiator supply disruption, PFAS regulatory acceleration, and hot-melt substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about REACH compliance timelines and OEM qualification protocol stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Tape Unwinder Market
Tapes
Industrial Tapes Market
Tapes
Double Coated Film Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Flocking Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Splicing Tapes Market
Tapes
Breathable Tape Market
Tapes
Plastic Adhesive Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
India Masking Tapes Market
Tapes
Automotive Tapes Market
Tapes
Lacing Tape Market
Tapes
Washi Tapes Market