
 Global Pharmaceutical Processing Seals Market | 2026-2036
Global Pharmaceutical Processing Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Processing Seals Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts as pharmaceutical manufacturers prioritize uptime guarantees over spot replacements. Trelleborg AB leverages its polymer compounding expertise to capture recurring seal kit subscriptions across European biologics plants. Freudenberg Group anchors its position through backward integration into fluorocarbon elastomer production, insulating margin pools from raw material volatility. Parker Hannifin Corporation dominates aftermarket logistics by embedding RFID-enabled seal tracking into customer maintenance systems.
Pharmaceutical processing seals are precision-engineered elastomeric or thermoplastic components designed to maintain sterile barriers, prevent cross-contamination, and contain active pharmaceutical ingredients under pressures ranging from vacuum to 150 bar in aseptic processing equipment. These seals typically incorporate platinum-cured silicone or perfluoroelastomer compounds to withstand repeated steam-in-place and clean-in-place cycles exceeding 150°C. O-rings and diaphragm seals command the largest installed base due to their ubiquity in fluid dispensing and sterile filtration skids, though mechanical seals are capturing expanded margin pools in high-shear bioreactor applications. PTFE and Viton formulations are outpacing EPDM in growth terms as manufacturers migrate toward aggressive solvent chemistries in continuous processing lines.
The FDA's 21 CFR Part 211 guidelines and the EU's MDR framework jointly enforce extractables and leachables testing protocols that disqualify non-validated seal compounds from commercial drug-contact applications. The EPA's National Emission Standards for Hazardous Air Pollutants further tighten fugitive emission thresholds around batch reactors, forcing seal upgrades at legacy installations. Stakeholders must monitor evolving pharmacopeial standards for elastomeric closures, as USP Chapter 381 revisions are expected to redefine acceptable limits for elemental impurities in seal compositions.
Market Dynamics
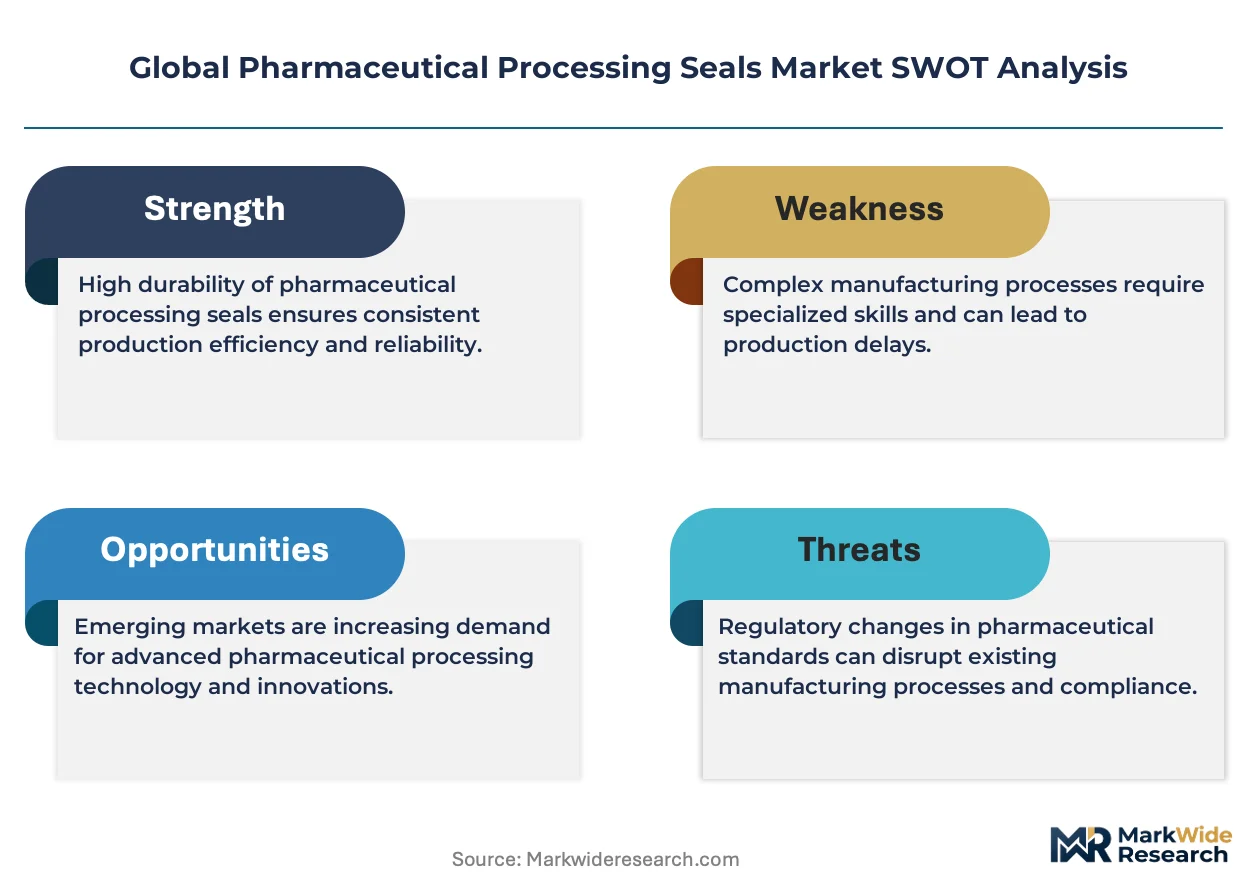
Single-use bioprocessing systems are compressing seal replacement cycles across sterile manufacturing lines, forcing suppliers to pivot from durable hardware toward validated consumable portfolios.
Growth Catalysts
- EMA's Annex 1 revision:The updated sterile manufacturing guidance mandates enhanced containment validation, driving pharmaceutical manufacturers to upgrade seal specifications in aseptic filling lines.
- Continuous manufacturing adoption:Biologics producers are deploying integrated processing trains that demand precision seals capable of withstanding sustained high-shear conditions without degradation.
- India's CDSCO streamlining:Accelerated approval pathways for biosimilars are expanding domestic sterile processing capacity, creating pull for validated sealing components in contract manufacturing facilities.
Market Restraints
- Fluorocarbon elastomer supply concentration:Specialty polymer feedstock production clusters in Japan and Germany, exposing seal manufacturers to input cost volatility and allocation constraints during supply disruptions.
- REACH substance restrictions:ECHA's evolving candidate list for Substances of Very High Concern is forcing reformulation of established seal compounds, extending R&D timelines and recertification costs.
- Metal-to-metal seal substitution:High-pressure homogenizer OEMs are specifying hard-faced mechanical seals for extreme-duty applications, eroding elastomer seal addressable market in specific equipment categories.
Strategic Opportunities
- Brazil's ANVISA capacity expansion:Domestic vaccine production initiatives are greenfielding sterile processing infrastructure, creating first-mover advantage for seal suppliers offering localized technical support.
- Digital twin integration:Convergence of RFID-enabled seal tracking with predictive maintenance platforms enables outcome-based service models that capture recurring revenue streams.
- Cell and gene therapy manufacturing:Closed-system processing requirements for autologous therapies are specifying novel seal geometries that accommodate miniaturized, flexible production modules.
Industry Challenges
- Perfluoroelastomer compounding expertise scarcity:Specialized polymer science talent pools concentrate at incumbent suppliers, constraining new market entrants from achieving validated compound performance.
- USP Chapter 381 compliance timelines:Pending revisions to elastomeric closure testing protocols are freezing procurement decisions as manufacturers await definitive extractables thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Processing Seals Market |
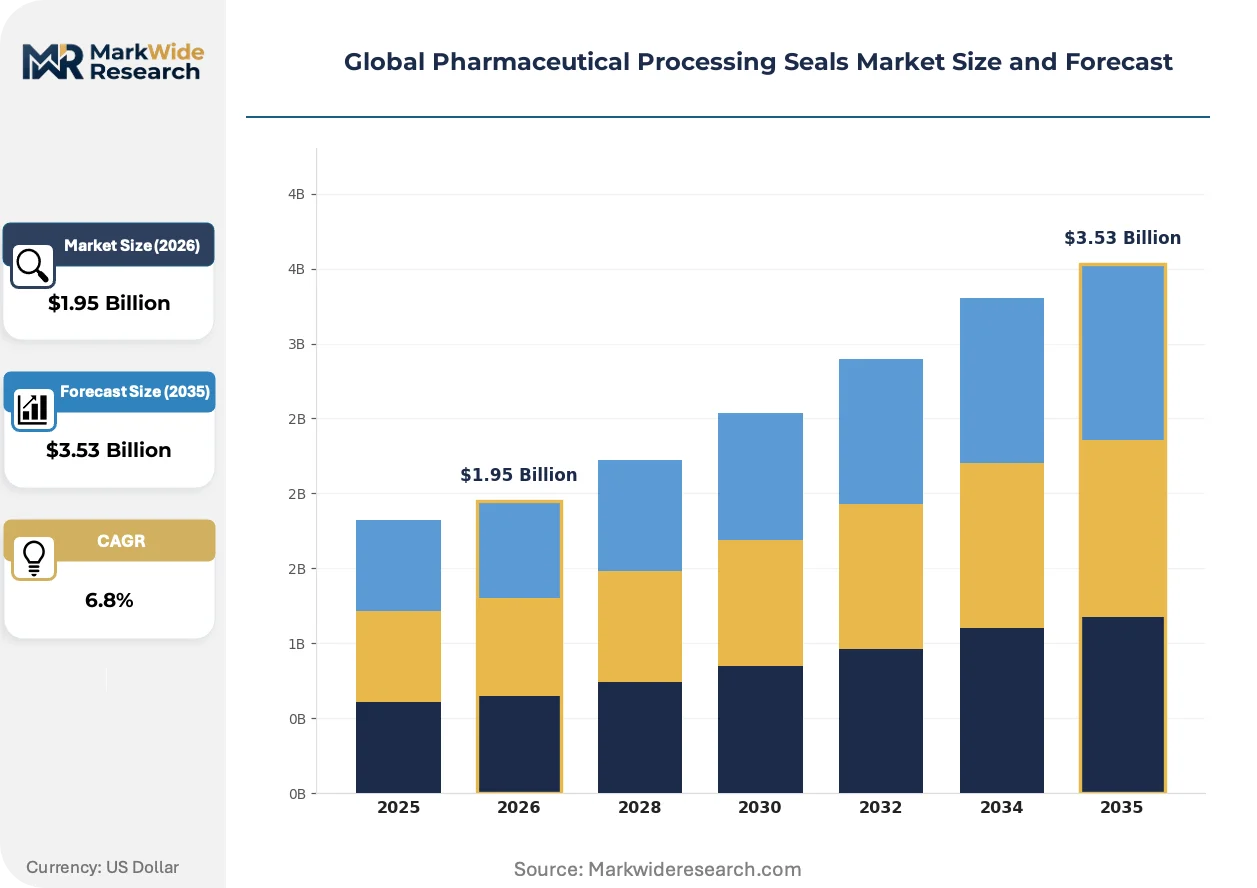
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Lip Seals, Mechanical Seals, Diaphragm Seals Material: PTFE, Silicone, Viton, EPDM, Neoprene, Polyurethane Application: Tablet Coating, Fluid Dispensing, Capsule Filling, Sterile Filtration End User: Pharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Laboratories, Regulatory Bodies |
| Companies Covered | Trelleborg AB, Freudenberg Group, Flowserve Corporation, Parker Hannifin Corporation, Saint-Gobain S.A., Garlock, IDEX Corporation, James Walker, John Crane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Processing Seals Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine seal performance specifications, with digital traceability emerging as a competitive differentiator alongside traditional durability metrics.
Platinum-cured liquid silicone rubber is collapsing the performance gap between thermoset elastomers and thermoplastics in high-purity fluid paths. Biologics contract manufacturers are specifying these materials for single-use bioreactor seals to eliminate batch-to-batch variability. The technology is compressing qualification timelines by enabling rapid prototyping of custom geometries without hard tooling investments.
REACH F-Gas Regulation restrictions on perfluorinated compounds are forcing seal compounders to develop partial-fluorine alternatives for solvent-resistant applications. The industrial consequence is extended validation cycles as pharmaceutical customers demand equivalency data for replacement materials. High-potency API manufacturing facilities in the Netherlands and Belgium are most affected, with several installations deferring seal upgrades pending regulatory clarity.
Consolidated procurement through group purchasing organizations is displacing direct supplier relationships for standardized seal categories. Regional hospital networks and pharmaceutical cooperatives are centralizing specification authority, compressing vendor margins on commodity O-rings and diaphragms. This concentration is most visible in Germany's Rhineland cluster, where contract manufacturing organizations are mandating approved supplier lists with stringent total-cost-of-ownership criteria.
Global Pharmaceutical Processing Seals Market Segmentation
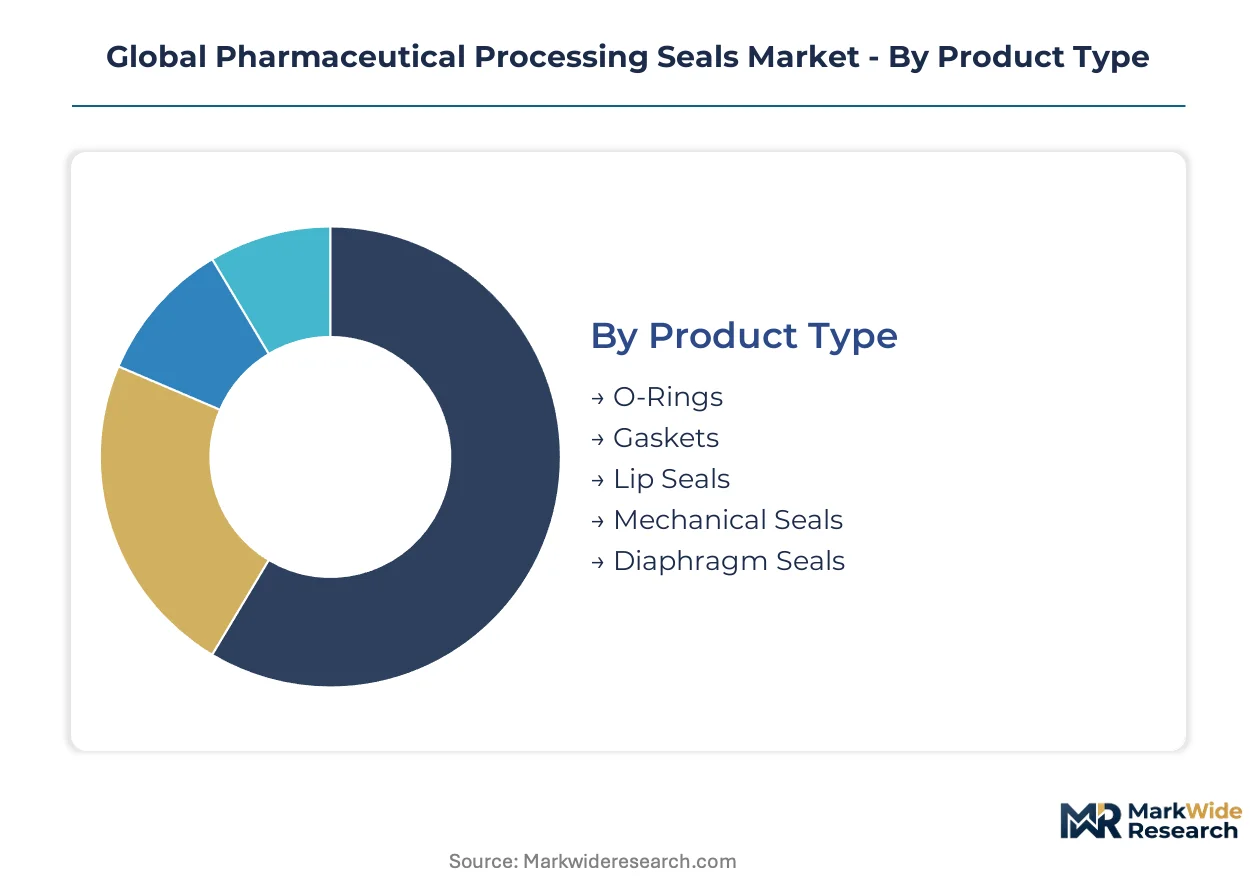
Pharmaceutical processing seals serve heterogeneous equipment configurations across sterile manufacturing environments. Segmentation reveals how material specifications and application pressures fragment supplier addressable markets. Procurement patterns diverge sharply between high-volume consumable categories and engineered mechanical seal systems.
Product Type:
Equipment integration requirements and replacement frequency differentiate seal geometries across sterile processing lines.
- O-Rings:Circular elastomeric profiles compress between mating surfaces to create static or dynamic seals in fluid dispensing manifolds. Demand concentrates in Germany's Rhineland contract manufacturing cluster where single-use bioreactor adoption accelerates replacement cycles.
- Mechanical Seals:Precision-engineered face-seal assemblies withstand sustained high-shear conditions in continuous processing trains. Biologics manufacturers in the Netherlands specify these for high-pressure homogenizer applications where elastomer alternatives degrade.
- Gaskets:Flat sealing elements compressed between flange surfaces in sterile filtration skids.
- Lip Seals:Radial shaft seals containing lubricants and excluding contaminants in rotary equipment.
- Diaphragm Seals:Flexible membranes isolating process fluids from pressure instrumentation in aseptic filling lines.
O-Rings hold installed capacity. Mechanical Seals is rotating up the share rankings.
Material:
Chemical resistance profiles and regulatory validation status stratify compound selection across solvent-intensive process streams.
- PTFE:Fluoropolymer compounds deliver exceptional chemical inertness for aggressive solvent contact applications. Continuous manufacturing lines in Belgium's high-potency API facilities specify PTFE formulations to withstand repeated clean-in-place cycles.
- Silicone:Platinum-cured liquid silicone rubber eliminates batch-to-batch variability in single-use bioreactor seals. Contract manufacturers in Germany compress qualification timelines through rapid prototyping of custom geometries.
- Viton:Fluoroelastomer compounds balance solvent resistance with elastic recovery in dynamic sealing applications.
- EPDM:Ethylene-propylene-diene monomer seals serve aqueous and steam applications with limited solvent exposure.
- Neoprene:Chloroprene-based elastomers for general-purpose sealing in non-critical auxiliary equipment.
- Polyurethane:Thermoplastic elastomers providing abrasion resistance in mechanical seal secondary containment.
Silicone dominates single-use consumable volumes. PTFE is climbing the fastest as solvent chemistry intensifies.
Application:
Process step contamination risk and pressure differentials determine seal performance specifications across drug manufacturing workflows.
- Sterile Filtration:Critical barrier seals maintaining aseptic integrity in final fill-finish operations. India's CDSCO biosimilar approval expansion drives capacity additions at domestic contract manufacturing facilities.
- Fluid Dispensing:Precision volumetric control seals in automated dosing and transfer systems. German pharmaceutical cooperatives mandate approved supplier lists with stringent total-cost-of-ownership criteria.
- Tablet Coating:Seals containing solvent vapors in pan-coating equipment under EPA National Emission Standards.
- Capsule Filling:Containment seals for powder handling in high-potency oral dosage manufacturing.
Sterile Filtration commands premium pricing. Fluid Dispensing is gaining share fastest through automation penetration.
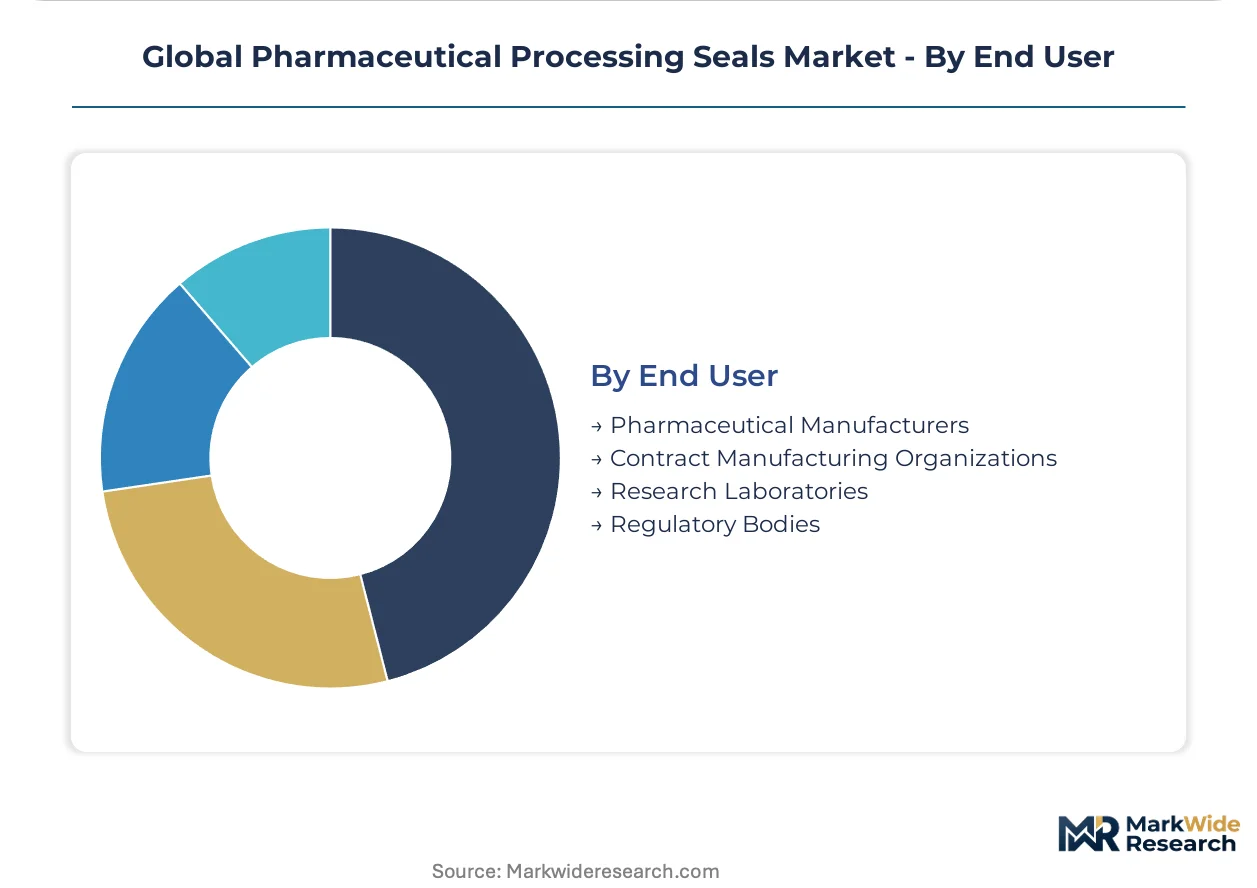
End User:
Procurement sophistication and validation burden separate institutional buyers across the pharmaceutical value chain.
- Contract Manufacturing Organizations:Outsourced sterile processing providers consolidating specification authority through group purchasing organizations. Brazil's ANVISA domestic vaccine initiatives greenfield infrastructure requiring localized technical support.
- Pharmaceutical Manufacturers:Integrated drug developers with captive production capacity and established supplier relationships.
- Research Laboratories:Early-stage development facilities with lower volume requirements and expedited qualification protocols.
- Regulatory Bodies:Standards-setting institutions influencing seal compound acceptance criteria through pharmacopeial revisions.
Contract Manufacturing Organizations concentrate procurement volume. Pharmaceutical Manufacturers retain specification control for proprietary processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing organizations in Germany tolerate premium pricing for validated seals, whereas Indian biosimilar producers prioritize total-cost-of-ownership metrics. This demand-elasticity contrast fragments procurement strategies across major pharmaceutical manufacturing clusters.
United States
FDA enforcement of 21 CFR Part 211 extractables testing drives seal specification upgrades at sterile filling facilities. The EPA's National Emission Standards for Hazardous Air Pollutants mandates fugitive emission controls on batch reactors. Greater Boston's biologics corridor concentrates demand for platinum-cured silicone seals in single-use bioreactor systems.
Germany
EMA Annex 1 sterile manufacturing revisions compel aseptic line containment validation investments. The country's pharmaceutical cooperatives consolidate procurement through group purchasing organizations with stringent supplier qualification criteria. North Rhine-Westphalia's Rhineland contract manufacturing cluster accelerates seal replacement cycles through single-use system adoption.
India
CDSCO's streamlined biosimilar approval pathways expand domestic sterile processing capacity at contract manufacturing facilities. The PLI scheme for pharmaceuticals incentivizes local production infrastructure buildouts. Maharashtra's Mumbai-Pune pharmaceutical belt attracts seal suppliers establishing technical support centers for regional biologics plants.
Netherlands
High-potency API manufacturing facilities demand solvent-resistant PTFE formulations for aggressive chemistry containment. ECHA REACH substance restrictions force reformulation of established seal compounds with extended validation timelines. Belgium's Antwerp pharmaceutical cluster defers seal upgrades pending regulatory clarity on perfluorinated compound alternatives.
Brazil
ANVISA's domestic vaccine production initiatives greenfield sterile processing infrastructure with localized technical support requirements. The national pharmaceutical regulator mandates containment validation for aseptic filling operations. São Paulo's emerging biologics manufacturing zone creates first-mover positioning for seal suppliers offering on-site engineering services.
Global Pharmaceutical Processing Seals Market Competitive Landscape
Capability concentration sits with polymer compounding specialists; scale advantage sits with diversified industrial conglomerates. The market structure stratifies across three tiers: integrated elastomer compounders with backward integration into fluorocarbon production, precision-engineered mechanical seal specialists, and regional fabricators serving standardized consumable categories. Dominant competitive moves include capacity expansion in platinum-cured silicone compounding and strategic partnerships embedding RFID-enabled tracking into customer maintenance platforms.
Among diversified industrial conglomerates, Trelleborg AB and Freudenberg Group exemplify the integrated compounder archetype with captive polymer science capabilities. Parker Hannifin Corporation occupies a position on the precision-engineered systems tier, representing the logistics-embedded service model. These three anchors illustrate how competitive positioning diverges between material science depth and aftermarket infrastructure control.
| Leading Market Players |
|---|
| Trelleborg AB |
| Freudenberg Group |
| Flowserve Corporation |
| Parker Hannifin Corporation |
| Saint-Gobain S.A. |
| Garlock |
| IDEX Corporation |
| James Walker |
| John Crane |
| Others |
Supply & Pricing Matrix
Undercapacity in platinum-cured silicone compounding across European contract manufacturing clusters is elevating supplier pricing power while compressing procurement timelines for validated seal kits. This utilization squeeze feeds directly into buyer behavior: pharmaceutical manufacturers are locking multi-year service contracts to secure capacity allocation, shifting negotiation leverage toward compounders with captive polymer production.
Pricing Analysis
Aftermarket service revenue, particularly predictive maintenance subscriptions, drives lifetime value capture across seal portfolios. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth and RFID-enabled traceability features. Cost compression in commodity O-ring categories is intensifying because group purchasing organizations in Germany's Rhineland cluster consolidate procurement authority. Contract manufacturing organizations exhibit highest price sensitivity due to total-cost-of-ownership mandates, while integrated biologics developers tolerate premium positioning for validated perfluoroelastomer compounds.
Supply Chain Analysis
Fluorocarbon elastomer feedstock production centers on Japan, Germany, and the United States, creating geographic concentration risk for seal compounders. Specialty polymer supply draws from perfluorinated monomer streams and platinum-cured silicone precursors, with both inputs exposed to REACH F-Gas Regulation restrictions. Single-source vulnerability in Japanese fluoropolymer production threatens allocation constraints during supply disruptions. Distribution runs through authorized distributor networks embedding technical support capabilities at biologics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal-to-metal seal substitution in high-pressure homogenizer applications presents a tangible displacement threat that elastomer seal incumbents must neutralize through performance differentiation and service bundling.
For Market Incumbents: Harden compound validation portfolios against REACH substance restrictions by accelerating partial-fluorine alternative development before regulatory deadlines crystallize. Deepen backward integration into fluorocarbon elastomer production to insulate margin pools from Japanese feedstock allocation volatility. Anchor customer relationships through RFID-enabled seal tracking embedded in maintenance platforms, creating switching costs that metal seal alternatives cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA-driven vaccine production infrastructure, where localized technical support capabilities remain undersupplied and first-mover positioning is achievable. Target India's CDSCO-accelerated biosimilar contract manufacturing facilities with rapid-qualification silicone seal offerings that compress validation timelines versus incumbent lead times. Pursue outcome-based service models bundling seal supply with uptime guarantees, mirroring the predictive maintenance contracts displacing spot replacement revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with captive polymer science capabilities and validated regulatory dossiers. Five-to-ten-year viability favors integrated manufacturers with backward integration into fluorocarbon production and established FDA master files. The signal to watch is ECHA's evolving candidate list for Substances of Very High Concern, which will force reformulation cycles and consolidate advantage toward compounders with R&D scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorocarbon Production | Captive polymer supply insulates margins from Japanese feedstock allocation constraints. |
| RFID-Enabled Seal Tracking Deployment | Predictive maintenance platforms embed suppliers into customer uptime operations. |
| Partial-Fluorine Compound Development | REACH F-Gas compliance positions compounders ahead of perfluorinated restrictions. |
| Localized Technical Support Expansion | ANVISA vaccine initiatives in Brazil reward on-site engineering presence. |
| Platinum-Cured Silicone Capacity Addition | Single-use bioreactor adoption accelerates replacement cycle demand. |
Research Methodology
Initial hypotheses were tested against primary input from sterile processing engineers, regulatory affairs specialists at contract manufacturing organizations, procurement directors at pharmaceutical cooperatives, and aftermarket service managers at seal distributors, then refined against secondary validation. FDA 21 CFR Part 211 guidance documents, EMA Annex 1 revision drafts, ECHA REACH candidate list publications, and USP Chapter 381 pharmacopeial standards provided regulatory anchoring. Customs trade data on fluoropolymer imports and SEC filings from diversified industrial conglomerates supplemented demand-side calibration. Bottom-up equipment installation counts and top-down pharmaceutical capital expenditure patterns were triangulated to converge volume estimates.
Demand-supply balance modeling across the projection horizon incorporated capacity utilization signals from platinum-cured silicone compounders and fluorocarbon elastomer producers. Segmentation dimensions included seal geometry, material compound, application pressure regime, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to validated replacement cycle data and biologics manufacturing capacity expansion announcements. Continuous manufacturing adoption rates and single-use system penetration served as industry-specific demand drivers.
Sensitivities concentrate around ECHA substance restriction timelines, FDA extractables testing protocol revisions, and fluorocarbon feedstock allocation disruptions. Forecasts embed assumptions regarding regulatory clarity on perfluorinated compound alternatives and qualification timeline compression for replacement materials. Cross-checking against pharmaceutical capital expenditure surveys and biologics capacity buildout announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Vial Box Market