
 Non-UV Dicing Tapes Market | 2026-2036
Non-UV Dicing Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Non-UV Dicing Tapes Market Analytics
Multi-source procurement among OSATs is consolidating around Japanese and North American adhesive suppliers with captive resin synthesis capabilities. Nitto Denko leverages backward integration into polyimide film casting to control thickness tolerances across 50μm to 150μm specifications. Lintec Corporation anchors its position through solvent-based adhesive formulations optimized for silicon wafer dicing. 3M Company competes via pressure-sensitive adhesive platforms that reduce die-edge chipping during high-speed blade processing.
Non-UV dicing tapes are pressure-sensitive adhesive films engineered for temporary wafer mounting during mechanical or laser dicing, typically comprising a polyolefin or PVC carrier coated with rubber or acrylic adhesives that release thermally without UV exposure. The 130μm and 150μm thickness grades dominate volume for large-diameter wafer handling where mechanical stability during backgrinding is critical. Acrylic adhesive tapes represent the fastest-expanding product category as semiconductor fabs transition from rubber-based systems seeking cleaner thermal release profiles with reduced residue. Medical device end-use applications occupy a narrower but higher-margin niche where biocompatibility certifications command premium positioning.
Japan's METI enforces JIS standards on electronics adhesive outgassing, while the EPA regulates volatile organic compound emissions from solvent-based coating operations in U.S. manufacturing facilities. REACH compliance in Europe restricts certain phthalate plasticizers, compelling reformulation of PVC carrier layers toward non-orthophthalate alternatives. Stakeholders must monitor evolving dual carbon goals from China's MEE and their downstream impact on petrochemical-derived tape substrates.
Market Dynamics
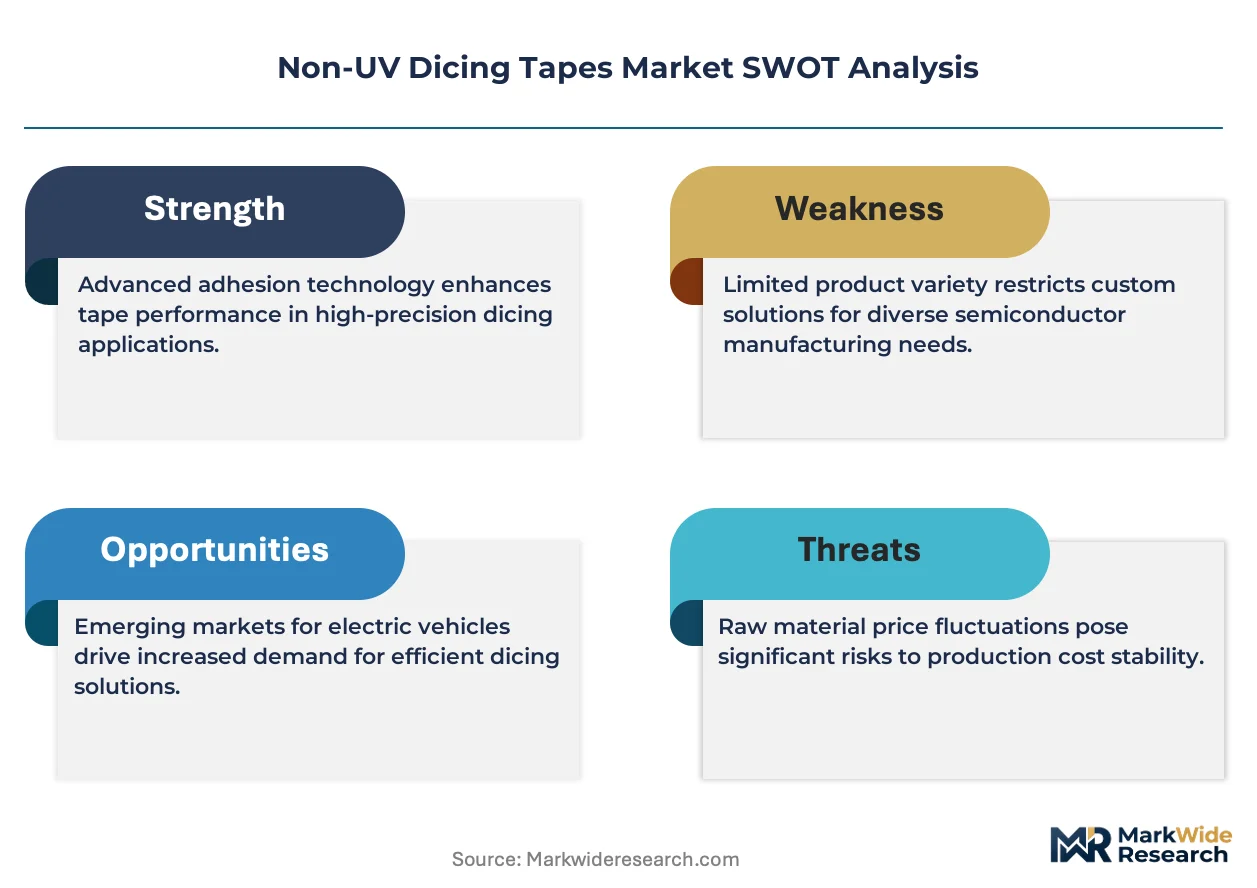
Wafer-level packaging capacity expansion in East Asian foundry clusters is compressing thermal release specifications while China's NMPA and MIIT solvent-free mandates are forcing adhesive reformulation cycles.
Growth Catalysts
- Advanced packaging node migration:Silicon wafer dicing for 3D-IC architectures demands cleaner thermal release profiles without UV exposure, pulling acrylic adhesive systems into mainstream adoption at leading-edge fabs.
- China's dual carbon enforcement:MEE emissions targets are accelerating solvent-free coating line investments, creating captive demand for water-based adhesive formulations in domestic packaging houses.
- Medical device certification pipelines:Biocompatibility-grade tape specifications under ISO 10993 are opening premium positioning for polyolefin carriers in implantable device manufacturing.
Market Restraints
- Petrochemical substrate volatility:Polyimide film and PVC carrier resin prices track naphtha-cracker margins, compressing formulation economics during upstream supply shocks.
- Japanese supplier concentration:Captive resin synthesis capabilities cluster among Osaka and Tokyo-based adhesive specialists, creating single-source vulnerability for OSATs outside East Asia.
- Rubber adhesive residue limitations:Natural rubber-based systems retain higher thermal release contamination versus acrylic alternatives, blocking qualification at sub-10nm die-bonding workflows.
Strategic Opportunities
- South Korean OSAT expansion:Pyeongtaek and Yongin packaging clusters are scaling wafer-level capacity without established local adhesive supply, creating white-space for qualified second-source entrants.
- Laser dicing convergence:Mechanical blade processing is integrating with stealth dicing workflows, requiring tape formulations compatible with both thermal release and picosecond laser thermal stress profiles.
- India's PLI scheme for semiconductors:Modified incentive structures for compound semiconductor packaging are attracting foundry investment, seeding demand for non-UV tape qualification programs.
Industry Challenges
- Cleanroom adhesive coating expertise:Sub-50ppm particulate specifications in Class 10 environments require process engineers with rare cross-training in polymer rheology and semiconductor contamination control.
- Multi-jurisdiction certification lag:Simultaneous REACH phthalate restrictions, METI outgassing standards, and EPA VOC compliance extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-UV Dicing Tapes Market |
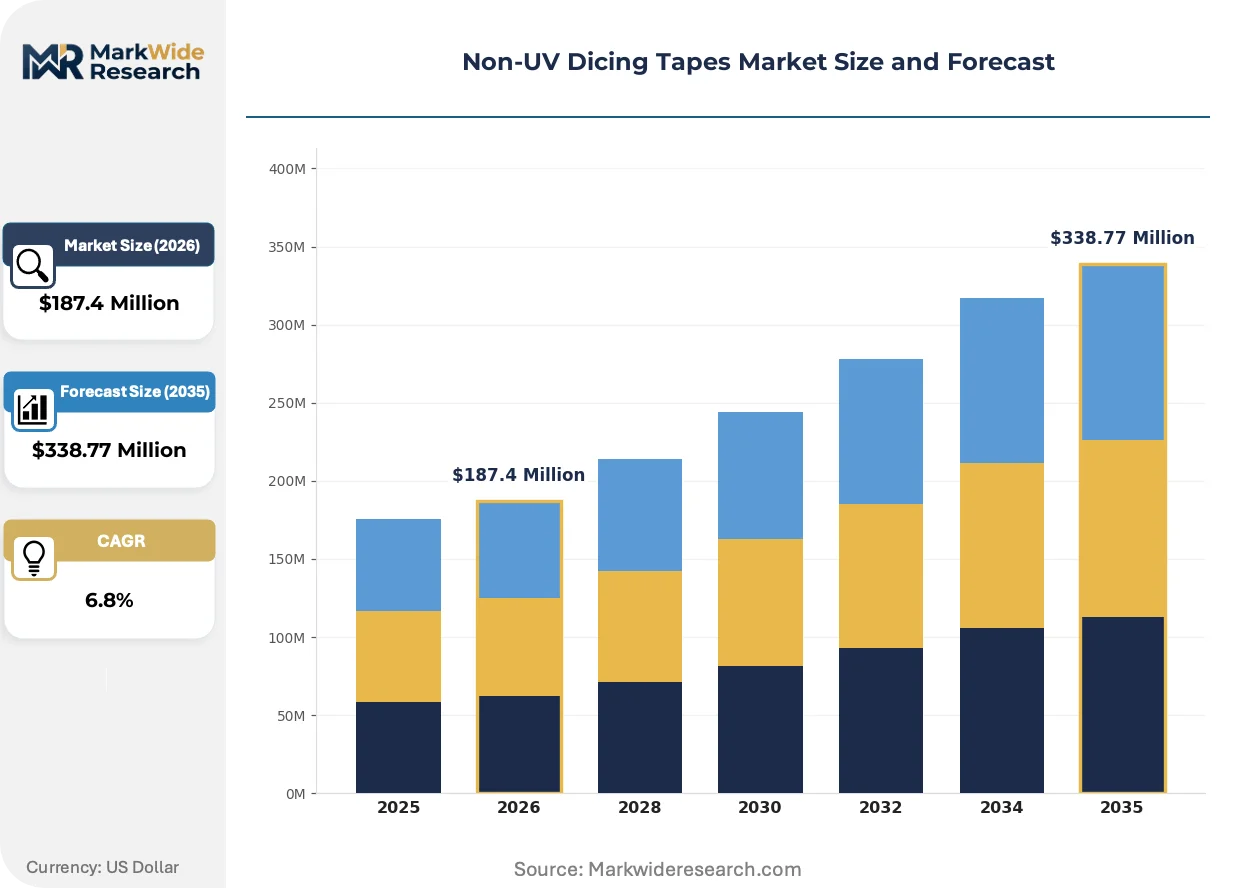
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyimide, Acrylic, Silicone, Rubber Thickness: 50μm, 100μm, 130μm, 150μm End User: Semiconductor, Electronics, Automotive, Medical Devices Adhesive Type: Hot-Melt, Solvent-Based, Water-Based, Pressure-Sensitive |
| Companies Covered | Nitto Denko Corporation, Lintec Corporation, 3M Company, Denka Company Limited, Sumitomo Bakelite Co., Ltd., Furukawa Electric Co., Ltd., AI Technology, Inc., Mitsubishi Plastics, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-UV Dicing Tapes Market Evolving Landscape
Acrylic adhesive platforms are displacing rubber-based systems across thermal release applications while regulatory pressure on solvent emissions accelerates waterborne coating line investments.
Silicone-modified acrylic adhesive technology is decentralizing thermal release performance from Japanese supplier portfolios. Taiwan-based OSATs are qualifying these formulations at 2-3 year replacement cycles versus traditional 5-year rubber system lock-in. The shift is compressing incumbent margin structures while enabling multi-source procurement at 130μm and 150μm thickness grades.
REACH restrictions on orthophthalate plasticizers are forcing PVC carrier layer reformulation across European-bound production. ECHA substance evaluation timelines are extending compliance windows, but German packaging equipment OEMs are already specifying non-orthophthalate alternatives in procurement tenders. The regulatory friction is elevating polyolefin carrier acceptance despite higher base material costs.
Consolidated procurement through semiconductor equipment lessors is displacing direct adhesive purchasing by OSATs. Tokyo-based packaging equipment providers now bundle tape supply into tool maintenance contracts, capturing volume commitments that bypass traditional distributor channels. This channel compression is most visible in South Korean foundry clusters where equipment utilization rates exceed 85 percent.
Non-UV Dicing Tapes Market Segmentation
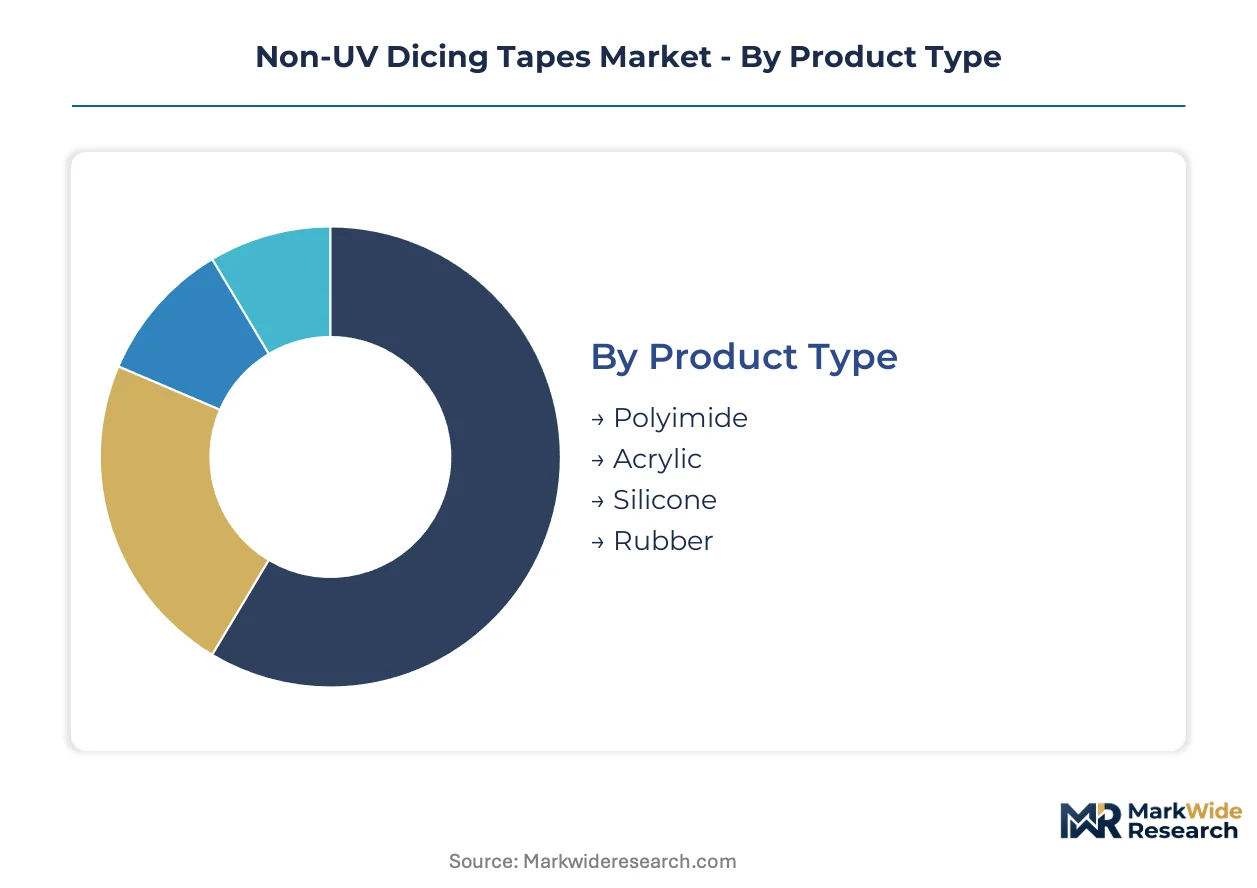
Non-UV dicing tape specifications fragment across adhesive chemistry, carrier materials, and dimensional tolerances. Each segment carries distinct capital requirements for coating line configuration and cleanroom certification. Procurement patterns at OSATs track these technical boundaries closely.
Product Type:
Capital intensity peaks with polyimide film casting infrastructure, while rubber-based systems require less specialized coating equipment.
- Polyimide:High-temperature polyimide substrates withstand thermal release cycles above 150°C without dimensional distortion. Taiwan and South Korea foundry clusters specify polyimide for 300mm wafer backgrinding where mechanical stability during blade dicing is non-negotiable. METI outgassing standards under JIS C 0099 disqualify lower-grade carriers for Japanese OSAT qualification.
- Acrylic:Acrylic adhesive platforms bond to polyolefin or PET carriers with cleaner thermal release profiles than rubber alternatives. Demand concentrates at leading-edge fabs transitioning to sub-10nm die-bonding workflows where residue contamination risks yield loss. China's NMPA solvent-free mandates accelerate waterborne acrylic qualification timelines.
- Silicone:Silicone-modified systems occupy niche applications requiring extreme temperature cycling resistance.
- Rubber:Natural rubber formulations dominate legacy packaging houses with established 5-year qualification cycles and lower switching incentives.
Most installed capacity flows through acrylic platforms. Expansion is steepest in silicone-modified formulations.
Thickness:
Dimensional specifications correlate directly with wafer diameter handling requirements and backgrinding depth parameters.
- 130μm:The 130μm grade balances mechanical rigidity with tape consumption efficiency for 200mm to 300mm wafer transitions. South Korean OSATs in Pyeongtaek specify this thickness for high-volume memory packaging where blade penetration depth is standardized. Thinner alternatives risk edge-lift during high-speed dicing.
- 150μm:Maximum thickness grade provides structural support for ultra-thin wafer handling below 50μm final thickness. Medical device manufacturers in Germany specify 150μm polyolefin carriers for implantable component dicing where biocompatibility certification under ISO 10993-5 requires batch traceability. Premium positioning reflects yield protection value.
- 50μm:Ultra-thin grade serves laser dicing applications with minimal thermal mass requirements.
- 100μm:Mid-range specification fills cost-sensitive packaging segments with moderate mechanical demands.
Volume concentrates at 130μm for mainstream semiconductor packaging. Medical device qualification is expanding fastest at 150μm.
End User:
Customer segmentation separates high-volume semiconductor fabs from premium-margin medical device manufacturers with divergent certification burdens.
- Semiconductor:OSATs and IDMs consume tape volumes scaling with wafer-level packaging capacity expansion. Taiwan's foundry clusters account for dominant procurement volumes with 85 percent-plus equipment utilization rates driving continuous replenishment. Thermal release specifications tighten with each advanced packaging node migration.
- Medical Devices:Implantable device manufacturers command 3-5x pricing premiums for biocompatibility-certified tape lots with full material genealogy. FDA 21 CFR Part 820 quality system requirements extend supplier audit timelines. ISO 10993 cytotoxicity testing adds 12-18 months to qualification cycles.
- Electronics:Discrete component packaging for consumer electronics operates on compressed margin structures with shorter qualification horizons.
- Automotive:Automotive sensor packaging under AEC-Q100 standards requires extended temperature range validation.
Revenue concentration sits with semiconductor end users. Medical device applications deliver the steepest margin expansion trajectory.
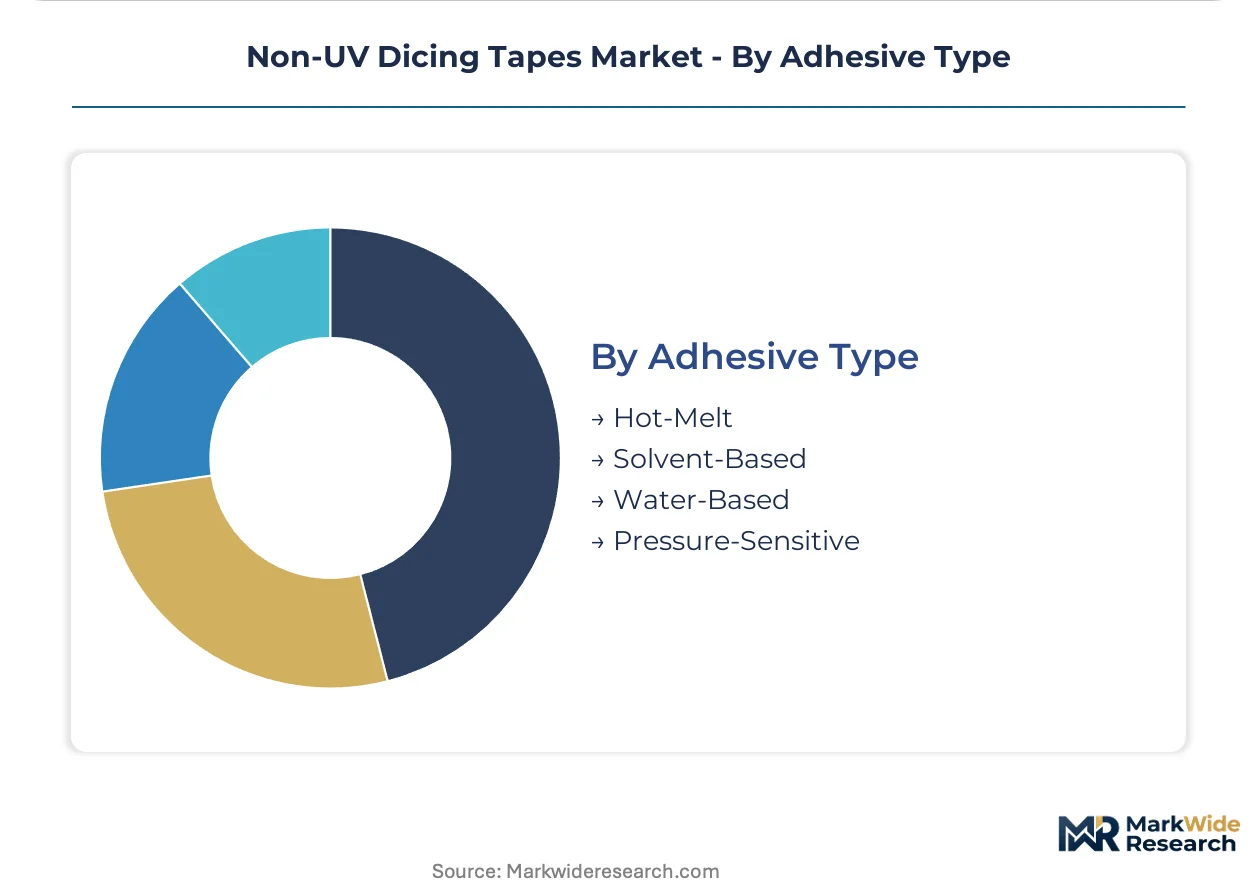
Adhesive Type:
Coating technology selection determines capital deployment for solvent recovery systems versus waterborne line infrastructure.
- Pressure-Sensitive:PSA platforms dominate mechanical dicing applications with immediate tack and clean thermal release. 3M and Nitto Denko anchor supply through proprietary acrylic formulations optimized for silicon wafer surface energy. South Korean packaging houses are diversifying PSA sourcing beyond Japanese incumbents.
- Water-Based:Waterborne adhesive coating eliminates solvent emissions and aligns with China's MEE dual carbon enforcement. Domestic Chinese tape manufacturers are investing captive water-based lines to serve local OSATs under NMPA electronics-grade adhesive standards. Technical gaps persist in thermal release temperature precision versus solvent-based alternatives.
- Hot-Melt:Hot-melt coating requires lower capital investment but limits adhesive formulation flexibility for high-performance specifications.
- Solvent-Based:Solvent coating retains performance leadership for sub-50nm residue specifications despite EPA VOC regulatory pressure.
Production gravity centers on pressure-sensitive platforms. Water-based capacity is climbing the fastest under regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundry clusters in Taiwan and South Korea concentrate the dominant procurement volumes for non-UV dicing tapes, driven by wafer-level packaging capacity scaling and thermal release specification tightening at advanced nodes.
Taiwan
Hsinchu Science Park and Tainan Technology Industrial Park house the world's densest concentration of OSAT capacity. Taiwan's Industrial Development Bureau enforces electronics-grade material standards that align with METI outgassing protocols. Tape qualification cycles at leading foundries compress to 18-month intervals as 3D-IC architectures proliferate.
South Korea
Pyeongtaek and Yongin packaging clusters are scaling wafer-level capacity without established local adhesive supply chains. The Ministry of Trade, Industry and Energy coordinates domestic material sourcing initiatives under the K-Semiconductor Belt program. Samsung and SK Hynix captive packaging operations are diversifying tape procurement beyond Japanese incumbents.
China
Yangtze River Delta and Pearl River Delta packaging houses are retrofitting coating lines under NMPA solvent-free mandates. The MIIT electronics-grade adhesive standards are disqualifying legacy rubber-based formulations from government-supported fab projects. Domestic tape manufacturers in Jiangsu and Guangdong are investing waterborne acrylic capacity to serve local OSATs.
Japan
Osaka and Tokyo-based adhesive specialists retain captive resin synthesis capabilities that supply Taiwan and South Korean foundries. METI enforces JIS C 0099 outgassing standards that disqualify lower-grade carriers from Japanese OSAT qualification. Nagoya-area equipment OEMs are bundling tape supply into tool maintenance contracts.
Germany
Dresden's silicon Saxony cluster and Bavarian automotive sensor packaging operations generate specialized demand for biocompatibility-certified grades. ECHA REACH restrictions on orthophthalate plasticizers are forcing PVC carrier reformulation for European-bound production. German packaging equipment OEMs specify non-orthophthalate alternatives in procurement tenders.
Non-UV Dicing Tapes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue waterborne formulation capabilities under regulatory compulsion. Japanese and North American adhesive specialists with backward integration into resin synthesis control thickness tolerance specifications across 50μm to 150μm grades. Three archetypes dominate: polyimide film casters with captive substrate production, solvent-based formulation specialists serving legacy rubber systems, and pressure-sensitive adhesive platform operators. Competitive moves concentrate on multi-source procurement consolidation by OSATs and channel compression through equipment lessor bundling.
Among Japanese specialists, Nitto Denko Corporation and Lintec Corporation exemplify the integrated archetype with upstream control over carrier substrate production. 3M Company anchors the North American position through pressure-sensitive adhesive platforms. These three entities represent distinct strategic postures: backward integration into polyimide casting, solvent-based formulation optimization, and die-edge chipping reduction through adhesive rheology control.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Lintec Corporation |
| 3M Company |
| Denka Company Limited |
| Sumitomo Bakelite Co., Ltd. |
| Furukawa Electric Co., Ltd. |
| AI Technology, Inc. |
| Mitsubishi Plastics |
| Saint-Gobain |
| Others |
Value Network & Pricing Analysis
OSAT procurement consolidation around multi-source qualification programs is compressing margin structures for adhesive suppliers while elevating performance-tier premiums for residue-critical specifications. China's NMPA solvent-free mandates are forcing coating line retrofits that pass through as cost adjustments in domestic supply contracts.
Pricing Analysis
Input-cost pass-through from naphtha-derived polyimide and PVC carrier resins anchors pricing volatility to petrochemical crack spreads. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade biocompatibility certifications from mainstream semiconductor lots. Cost compression in standard-grade acrylic systems is intensifying because South Korean OSATs are diversifying beyond Japanese incumbents. Memory packaging houses in Pyeongtaek exhibit highest price sensitivity, while German implantable device manufacturers accept 3-5x premiums for ISO 10993-5 traceability.
Supply Chain Analysis
Single-source vulnerability sits with Osaka and Tokyo-based adhesive specialists controlling captive resin synthesis for sub-50μm thickness tolerances. Polyimide film casting, acrylic adhesive monomers, and silicone release coatings draw from Japan, South Korea, and Taiwan production clusters. Tariff exposure on electronics-grade chemicals imported into China under MIIT localization targets threatens cross-border supply continuity. Distribution runs through Tokyo-based packaging equipment lessors bundling tape into tool maintenance contracts, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through solvent-free formulation premiums and medical-device certification tiering. Cost-down pressure from waterborne acrylic qualification is offset by yield-protection value at advanced nodes.
For Market Incumbents: To counter silicone-modified acrylic displacement from Taiwan-based competitors, deepen backward integration into polyimide film casting to control 130μm and 150μm thickness tolerances. Prioritize METI JIS C 0099 outgassing certification investments to maintain Japanese OSAT lock-in against South Korean sourcing diversification. For New Entrants and Emerging Players: Launch via waterborne acrylic coating lines serving Yangtze River Delta packaging houses under NMPA solvent-free mandates. Target India's PLI-backed compound semiconductor packaging clusters where adhesive qualification programs remain open. White-space concentrates in South Korean Pyeongtaek and Yongin clusters lacking established local supply. For Investors and Strategic Acquirers: Asymmetric upside sits with waterborne formulation specialists possessing cleanroom coating expertise and China domestic licensing. Long-term viability hinges on dual qualification for semiconductor and medical device tiers. Watch for ECHA REACH orthophthalate restriction enforcement as inflection indicator elevating polyolefin carrier acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Acrylic Capacity Expansion | Aligns coating operations with China's MEE dual carbon enforcement and NMPA electronics-grade standards. |
| Backward Integration into Polyimide Casting | Captures thickness tolerance control for 300mm wafer backgrinding specifications at Taiwan foundries. |
| ISO 10993-5 Biocompatibility Certification | Unlocks 3-5x pricing premiums from German implantable device manufacturers requiring batch traceability. |
| Equipment Lessor Bundling Partnerships | Secures volume commitments through Tokyo-based packaging OEM maintenance contracts in South Korea. |
| South Korean OSAT Qualification Programs | Captures share in Pyeongtaek and Yongin clusters scaling wafer-level capacity without local adhesive supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive R&D directors, OSAT procurement leads, packaging equipment OEMs, and cleanroom process engineers with secondary validation. Trade data from Japan Chemical Industry Association, Korea Trade-Investment Promotion Agency customs records, Taiwan Semiconductor Industry Association capacity reports, and EPA VOC emission filings anchored supply-side sizing. Bottom-up tape consumption modeling triangulated against top-down wafer-level packaging capacity expansion across the analysis window.
Segment-weighting applied adhesive chemistry, carrier material, thickness grade, and end-use industry dimensions across the modeling period. CAGRs derived from wafer dicing intensity coefficients applied to foundry utilization projections, with thermal release specification tightening and regulatory reformulation cycles as semiconductor-specific inputs. Medical device penetration curves incorporated ISO 10993-5 qualification timeline lags.
Several conditions sit outside the modeled scope, including abrupt petrochemical supply disruptions, unilateral tariff escalations on electronics-grade chemicals, and breakthrough laser dicing technologies eliminating thermal release requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
India Reflective Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Seam Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Heat Activated Tear Tape Market
Tapes
Duct Tapes Market
Tapes
Filament Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Holographic Tear Tape Market
Tapes
Edge Band Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Foam Tape Market