
 Automotive Adhesive Tapes Market | 2026-2036
Automotive Adhesive Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Adhesive Tapes Market Intelligence
Asset-light production models, where specialized converters lease equipment and facilities near major automotive plants, is reconfiguring the supplier ecosystem. This shift allows agile players to compete with established giants like 3M, which leverages its vast R&D infrastructure and global scale. Meanwhile, tesa SE specializes in customized solutions for complex applications like wire harnessing and surface protection. Henkel AG & Co. KGaA anchors its position through a broad portfolio of both adhesives and complementary sealant technologies.
Automotive adhesive tapes are engineered materials, often composed of polymer films or foams coated with a pressure-sensitive adhesive designed for specific peel adhesion and shear strength properties. They serve critical functions in vehicle assembly, including permanent bonding of components, sealing against moisture, masking during painting, and damping noise and vibration. Double-sided tapes, particularly those with high-performance acrylic adhesives, command a significant share for mounting exterior trim and badges. Demand from OEMs for specialty tapes is growing for complex interior assembly applications, displacing mechanical fasteners.
Suppliers must navigate complex chemical regulations, including the European Union's REACH framework, which governs the use of certain adhesive components. In parallel, rules from the US EPA on volatile organic compound (VOC) emissions and China's GB standards for in-cabin air quality influence adhesive formulation. Future material selection will require balancing bonding performance requirements with increasing pressure for designs that facilitate end-of-life vehicle disassembly and recycling.
Market Dynamics
The industry-wide transition to electric vehicles and lightweight materials is the central force shaping the market. This dual pressure elevates the role of adhesive tapes for bonding composites and sealing battery packs, displacing traditional mechanical fasteners.
Growth Catalysts
- Electric Vehicle Production:The expansion of EV manufacturing creates demand for tapes in battery pack sealing and thermal management.
- Automotive Lightweighting:In manufacturing hubs like Germany, tapes are critical for joining dissimilar materials, displacing heavier mechanical fasteners.
- Interior Air Quality Rules:China's GB standards drive OEM specification of low-VOC adhesive tapes for interior assembly applications.
Market Restraints
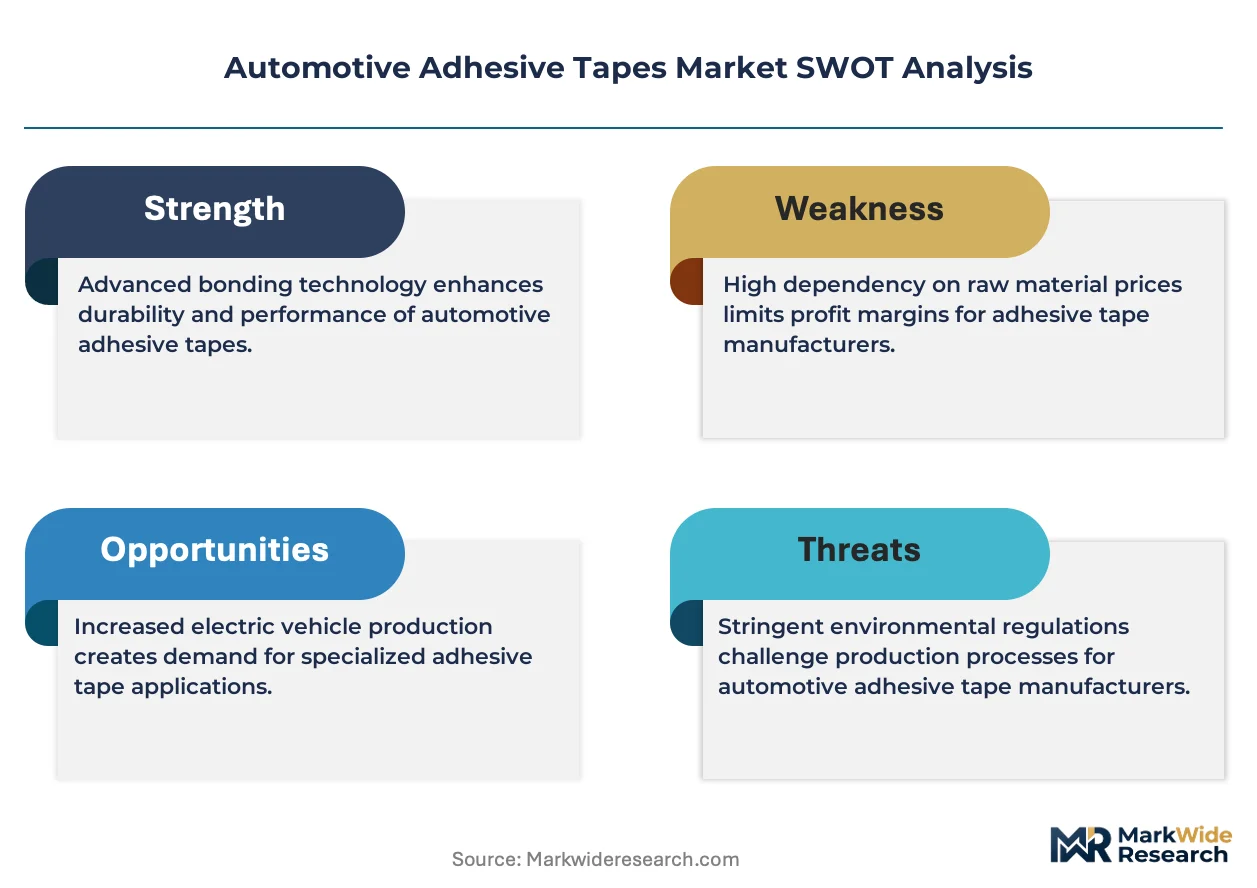
- Raw Material Volatility:Fluctuating prices for petroleum-derived polymer films and acrylic precursors compress margins for tape converters and manufacturers.
- Regulatory Fragmentation:Navigating divergent chemical regulations like the EU's REACH and US EPA rules increases compliance costs and product development timelines.
- Substrate Adhesion Challenges:Achieving reliable bonds to low-surface-energy plastics and advanced composites often requires costly surface preparation or specialized primers.
Strategic Opportunities
- ADAS Sensor Integration:Tapes for mounting and sealing ADAS sensors, cameras, and lidar units represent a high-value, emerging application area.
- Design for Disassembly:Developing tapes that facilitate easier end-of-life vehicle disassembly aligns with circular economy goals and future OEM requirements.
- New EV Manufacturing Clusters:Establishing converting facilities near new EV plants in regions like the southeastern US offers significant growth potential.
Industry Challenges
- Lengthy OEM Qualification:New adhesive tape formulations face extensive and time-consuming testing and validation processes before being specified by automotive OEMs.
- Competition from Liquid Adhesives:In certain structural bonding applications, high-performance liquid adhesives present a strong alternative, challenging tape's market penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Adhesive Tapes Market |
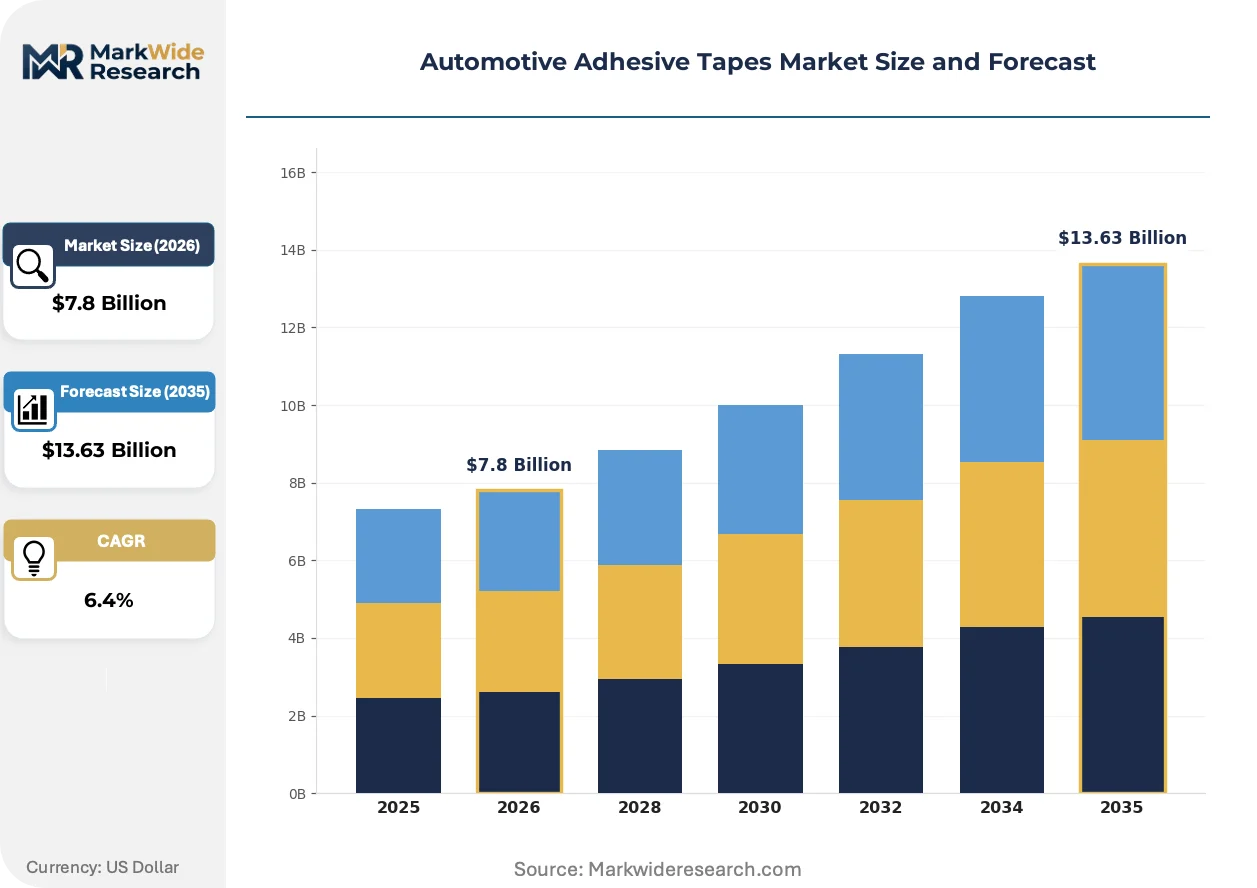
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Masking Tapes, Electrical Tapes, Specialty Tapes Application: Interior Assembly, Exterior Trim, Wiring Harness, Underbody End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Adhesive Type: Acrylic, Rubber-Based, Silicone, Hot Melt |
| Companies Covered | Avery Dennison Corporation, Henkel AG & Co. KGaA, 3M, Lintec Corporation, Sika AG, Nitto Denko Corporation, Lohmann GmbH & Co. KG, Scapa, tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Adhesive Tapes Market Strategic Shifts & Innovations
Material science advancements are converging with digital simulation to redefine adhesive tape capabilities and application processes. This evolution allows for more precise performance engineering and integration into automated vehicle assembly.
Digital simulation software allows engineers to model adhesive joint performance under various stress and environmental conditions. Automotive OEM design teams adopt these tools to optimize material selection early in development. This capability is virtualizing the traditionally lengthy and costly process of physical prototype testing and validation.
The European Union's focus on circular economy principles, within its End-of-Life Vehicles Directive, is creating new material requirements. This policy challenges permanent bonding solutions that complicate vehicle disassembly and material purity. Consequently, tape suppliers are accelerating R&D for "debond-on-demand" adhesives to facilitate component separation.
A shift towards asset-light production models is altering the supplier ecosystem for customized automotive tapes. Specialized converters lease equipment near major OEM plants, offering just-in-time supply without large capital investment. This model is gaining traction in new EV production clusters in Germany and the southeastern United States.
Automotive Adhesive Tapes Market Segmentation
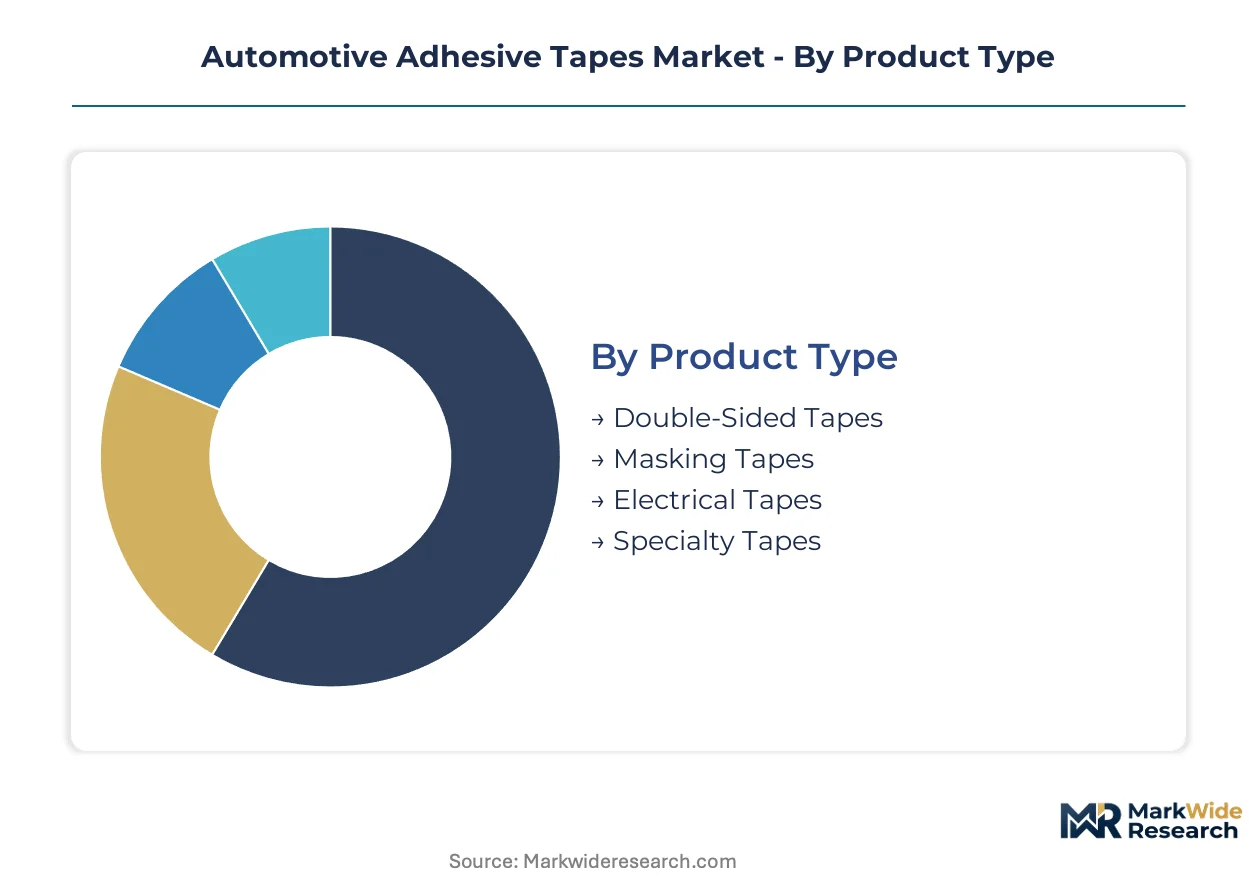
The Automotive Adhesive Tapes Market is intricately segmented, reflecting the diverse material science and application requirements across vehicle manufacturing. Understanding these distinct segments is crucial for suppliers to tailor product development and market strategies effectively.
Product Type:
The product type segmentation highlights the diverse use-case spectrum for adhesive tapes in automotive manufacturing.
- Double-Sided Tapes:These tapes feature adhesive on both sides, often with a carrier film, providing strong bonding for various components. Demand is concentrating in exterior trim and badging applications in Germany.
- Specialty Tapes:Engineered for specific, complex functions, these tapes include solutions for ADAS sensor integration and noise damping. OEM demand is significant for complex interior assembly applications.
- Masking Tapes:Designed for temporary protection and clean removal, these tapes are crucial for paint shop operations.
- Electrical Tapes:These tapes offer insulation and protection for wiring and electronic components within the vehicle.
The dominant share belongs to Double-Sided Tapes, while Specialty Tapes is closing the gap fastest.
Application:
Volume contribution from various application areas dictates tape formulation and performance requirements.
- Interior Assembly:Tapes in this segment bond various cabin components, often displacing mechanical fasteners due to lightweighting initiatives. Demand is high for low-VOC solutions driven by China's GB standards.
- Exterior Trim:This application involves securing decorative elements, moldings, and emblems to the vehicle's exterior surfaces. Acrylic double-sided tapes are widely used for robust adhesion in South Korea.
- Wiring Harness:Tapes bundle, insulate, and protect electrical wiring throughout the vehicle.
- Underbody:Applications here include sealing seams and protecting components from corrosion and abrasion.
Interior Assembly represents a substantial volume segment, with Wiring Harness applications expanding most quickly.
End User:
The customer type classification reveals distinct procurement patterns and technical demands across the automotive value chain.
- OEMs:Original Equipment Manufacturers directly integrate adhesive tapes into vehicle production lines, often requiring custom formulations and extensive qualification. New EV manufacturing clusters in the southeastern US drive significant OEM tape demand.
- Tier-1 Suppliers:These companies provide sub-assemblies and systems to OEMs, incorporating adhesive tapes into their components. Their procurement decisions influence a wide range of tape specifications.
- Aftermarket Providers:These entities supply tapes for repair, replacement, and customization outside of initial vehicle production.
- Vehicle Assemblers:This segment includes facilities that perform final vehicle assembly, utilizing tapes for various finishing and sealing tasks.
OEMs drive significant demand for custom solutions, while Tier-1 Suppliers also command substantial purchasing power.
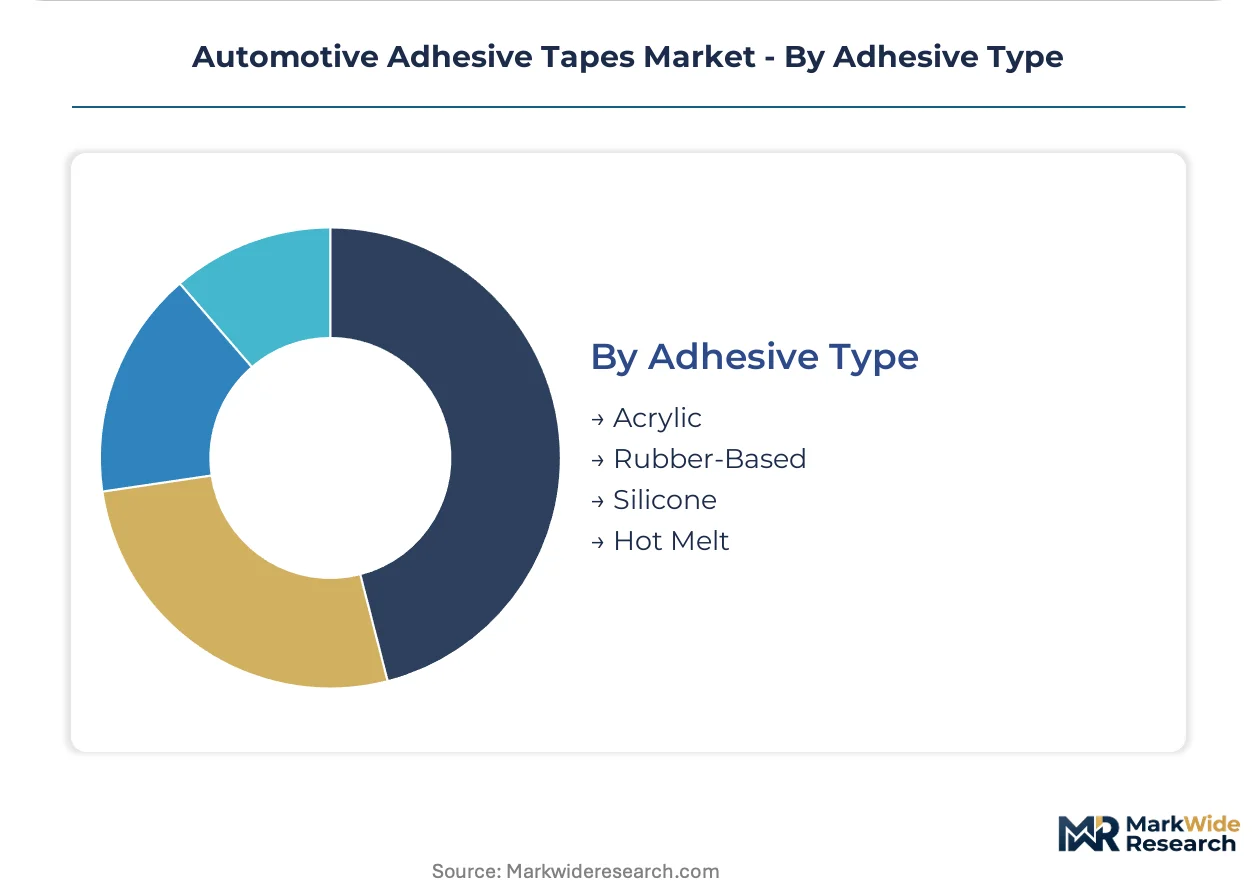
Adhesive Type:
Technical performance characteristics differentiate adhesive types, impacting their suitability for demanding automotive environments.
- Acrylic:Known for high shear strength, temperature resistance, and UV stability, these adhesives are used in demanding structural and exterior bonding applications. They are critical for mounting ADAS sensors.
- Rubber-Based:These adhesives offer good initial tack and flexibility, suitable for general-purpose bonding and sealing. Cost-effectiveness makes them popular in various interior applications.
- Silicone:Providing excellent temperature resistance and flexibility, silicone adhesives are used in high-heat or extreme environment applications.
- Hot Melt:Applied in molten form, these adhesives offer rapid bonding and are favored for high-speed assembly processes.
Acrylic adhesives offer superior long-term durability, whereas Hot Melt formulations provide rapid assembly benefits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive adhesive tapes market exhibits a varied trade balance, with certain regions demonstrating strong export capabilities in specialized formulations while others rely on imports to meet their burgeoning manufacturing demands. This dynamic interplay between local production and international trade shapes supply chain resilience and pricing structures across continents. Automotive manufacturing clusters dictate much of this regional demand.
Germany
Demand for automotive adhesive tapes in Germany stems from its robust automotive manufacturing base and a strong emphasis on lightweighting initiatives. The European Union's REACH framework heavily influences adhesive formulation and material selection for tapes produced and used within the country. The Stuttgart region, a major automotive hub, drives significant specification of advanced tapes for bonding dissimilar materials in premium vehicle production.
South Korea
South Korea's automotive industry drives considerable demand for adhesive tapes, particularly for exterior trim and advanced interior applications. The country's strict environmental regulations, including those on VOC emissions, impact the development of low-emission tape solutions. The Ulsan metropolitan area, a key automotive manufacturing center, sees widespread adoption of acrylic double-sided tapes for robust vehicle assembly.
China
China's expanding electric vehicle production and stringent interior air quality regulations fuel its demand for specialized automotive adhesive tapes. The country's GB standards for in-cabin air quality mandate low-VOC adhesive formulations, influencing product development. Manufacturing hubs like Shanghai and Guangzhou are at the forefront of adopting advanced tapes for EV battery pack sealing and complex interior assemblies.
United States
The United States market for automotive adhesive tapes is characterized by significant investment in new electric vehicle manufacturing clusters, especially in the southeastern US. US EPA regulations on volatile organic compound emissions guide adhesive formulation and application processes for automotive components. The Detroit metropolitan area continues to be a center for automotive innovation, driving demand for tapes in ADAS sensor integration and advanced bonding solutions.
Automotive Adhesive Tapes Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical material science expertise. The market structure for automotive adhesive tapes is tiered, with established chemical giants offering broad portfolios alongside specialized converters focusing on niche applications. Competitive positioning is often achieved through continuous R&D investment in new material formulations and strategic geographic expansion into emerging automotive production clusters.
Among established industry leaders, 3M leverages its vast R&D infrastructure and global scale to offer a wide array of adhesive tape solutions. Henkel AG & Co. KGaA anchors its position through a broad portfolio encompassing both adhesives and complementary sealant technologies, catering to diverse automotive needs. Meanwhile, tesa SE exemplifies specialization, providing customized solutions for complex applications like wire harnessing and surface protection.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| 3M |
| Lintec Corporation |
| Sika AG |
| Nitto Denko Corporation |
| Lohmann GmbH & Co. KG |
| Scapa |
| tesa SE |
| Others |
Cost & Logistics Intelligence
Raw material volatility for petroleum-derived polymers and acrylic precursors directly determines pricing tier spreads and influences the geographic shape of the automotive adhesive tapes supply chain. This commodity price exposure impacts both manufacturers and specialized converters.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for automotive adhesive tapes. Price differentiation stems from the customization level required for complex applications and the stringent certification level for regulatory compliance like EU REACH. Pricing softness reflects intense competition from liquid adhesives and the continuous cost compression demands from major automotive OEMs. Tier-1 suppliers exhibit high price sensitivity, whereas OEMs prioritize performance and long-term reliability for critical applications.
Supply Chain Analysis
Petroleum-derived polymer films and acrylic precursors form the upstream base of automotive adhesive tapes, with supply concentrating in Asia, particularly China and South Korea, while specialized film production centers in Europe. The supply chain relies on consistent availability of polymer films, acrylic monomers, and release liners. Commodity price volatility remains a structural risk. Distribution runs through direct sales channels to OEMs and Tier-1 suppliers, complemented by specialized converters offering regional just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive adhesive tapes market is in an early-cycle expansion phase, driven by the accelerating penetration of electric vehicle manufacturing. Tapes are fundamental to battery pack sealing and lightweighting in new EV platforms.
For Market Incumbents: Entrench existing OEM relationships by co-developing specialized solutions for next-generation EV platforms. Invest in advanced R&D for "debond-on-demand" adhesives to counter the regulatory shift towards end-of-life vehicle disassembly. This counters the threat from alternative bonding solutions and reinforces position against smaller, agile converters. Expand capacity in new EV manufacturing clusters, like the southeastern US, to maintain just-in-time supply.
For New Entrants and Emerging Players: High-performance specialty tapes for ADAS sensor integration and complex interior assemblies represent the most penetrable entry point for new players. Target emerging EV manufacturing clusters in regions like Germany and China, where demand for advanced bonding solutions outstrips current supply. A go-to-market angle focused on rapid OEM qualification and customized low-VOC formulations offers a distinct competitive advantage.
For Investors and Strategic Acquirers: Specialized adhesive tape converters with strong intellectual property in polymer science offer long-term viability over a 5-10 year window. These firms provide critical material science expertise and agile production models. Investors should watch for increased OEM investment in joint development programs with smaller, innovative tape suppliers as an inflection indicator. This signals a shift towards specialized, rather than commoditized, bonding solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeastern US | Supports new electric vehicle manufacturing clusters and secures just-in-time supply for OEMs. |
| Debond-on-Demand Adhesive R&D | Aligns with EU End-of-Life Vehicles Directive and facilitates future vehicle recycling. |
| Digital Simulation Software Integration | Optimizes adhesive joint performance and accelerates OEM design validation processes. |
| Low-VOC Formulation Development | Addresses China's GB standards for in-cabin air quality and expands market access. |
| ADAS Sensor Mounting Solutions | Captures high-value demand from advanced driver-assistance systems integration in new vehicles. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with OEM platform engineers, Tier-1 procurement leads, specialized converter R&D directors, and chemical raw material suppliers. This primary research was validated against secondary sources like automotive production databases, regulatory filings, and industry association reports. A bottom-up sizing approach was triangulated with top-down validation for robust data integrity.
Quantitative models were calibrated to historical market performance and future growth projections across the analysis window. Segmentation dimensions modeled included product type, application, end-user, adhesive type, and regional automotive production output. Compound annual growth rates derived from multi-variable regression. Key forecast inputs included electric vehicle production forecasts and automotive lightweighting material shifts.
Practitioners should monitor raw material price fluctuations and shifts in chemical regulations for early signals of market revision. Forecasts reflect assumptions documented regarding technological advancements and adoption rates. Cross-checking against industry association production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Thermal Release Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Global Printed Tape Market
Tapes
Flocking Tape Market
Tapes
Electrical Shielding Tape Market
Tapes
Invisible Tapes Market
Tapes
Medical Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Tear Tape Dispenser Market
Tapes
High Bond Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Gaffers Tape Market
Tapes
Tape Unwinder Market
Tapes
Sterilization Tape Market