
 Twist Tube Market | 2026-2036
Twist Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Twist Tube Market Analytics
Advanced extrusion and coextrusion technology is fragmenting the traditional monolayer tube supply base into multi-material specialists. Hoffmann Neopac leverages laminated barrier structures to anchor the premium pharmaceutical segment in Switzerland and adjacent markets. Amcor plc sustains global manufacturing scale across multiple substrate platforms, while Essel Propack Limited specializes in decorated laminate tubes for oral care brands operating in Asia.
Twist tubes are cylindrical collapsible containers, typically manufactured through extrusion or impact extrusion processes with wall thicknesses ranging from 0.35mm to 0.60mm, designed to dispense viscous products through a sealed shoulder and threaded closure system. Their primary purpose centers on protecting oxygen-sensitive and moisture-sensitive formulations during repeated consumer use cycles. Plastic tubes still occupy the largest volume share across personal care applications, though composite laminates represent the fastest-growing substrate category as brand owners seek extended shelf-life claims. Aluminum tubes dominate pharmaceutical ointment dispensing where inert metal contact surfaces satisfy pharmacopeial standards.
FDA compliance for pharmaceutical contact materials and EMA's Medical Device Regulation shape substrate selection and migration testing protocols for tube converters serving regulated industries. REACH restrictions on certain plasticizers and EU Packaging and Packaging Waste Directive recycling targets are forcing reformulation of standard polyethylene and polypropylene tube structures. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling infrastructure investments before committing capital to new extrusion capacity.
Market Dynamics
Blow-fill-seal technology is collapsing traditional pharmaceutical filling lines, forcing converters to retool extrusion capacity toward barrier laminates or exit regulated segments entirely. This substrate transition concentrates margin in multi-material specialists while squeezing monolayer polyethylene suppliers.
Growth Catalysts
- EMA Medical Device Regulation:Pharmaceutical contract packagers in Germany and Switzerland are upgrading to aluminum and high-barrier composite tubes to satisfy pharmacopeial contact standards for OTC dermatology products.
- Asia-Pacific oral care expansion:Decorated laminate tubes command premium shelf positioning as regional brand owners compete on extended shelf-life claims in humid climates.
- Europe's F-Gas Regulation:Converters are abandoning fluorinated polymer barriers for aluminum and paperboard composites to avoid phasedown penalties and maintain pharmaceutical customer relationships.
Market Restraints
- Aluminum ingot volatility:Pharmaceutical tube manufacturers face margin compression when London Metal Exchange prices spike, as pharmacopeial-grade aluminum commands fixed contract premiums.
- Barrier film supply concentration:Ethylene vinyl alcohol and polyamide film production clusters in Northeast Asia, exposing European tube converters to freight cost shocks and extended lead times.
- Polyolefin recycling infrastructure gaps:The EU Packaging and Packaging Waste Directive's 2030 recycled content targets outpace mechanical recycling capacity for food-contact and pharmaceutical-grade polyethylene.
Strategic Opportunities
- Saudi Arabia and UAE pharmaceutical localization:SFDA and MOHAP are mandating domestic manufacturing of primary packaging for imported drug registrations, creating captive demand for sterile tube filling capacity.
- Digital printing convergence with barrier laminates:Brands are combining short-run personalization with extended shelf-life substrates to test regional SKU variants without inventory risk.
- India's PLI scheme for medical devices:CDSCO-registered tube converters qualify for production-linked incentives when supplying domestic pharmaceutical formulators.
Industry Challenges
- Multi-material coextrusion technician scarcity:European and North American converters struggle to hire operators capable of calibrating seven-layer barrier structures with tight thickness tolerances.
- Migration testing timeline compression:REACH restrictions on novel plasticizers require 24-month stability studies before pharmaceutical customers accept substrate changes, freezing formulation innovation.
- Legacy filling line incompatibility:Blow-fill-seal tube formats often require pharmaceutical packagers to scrap existing crimping and coding equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twist Tube Market |
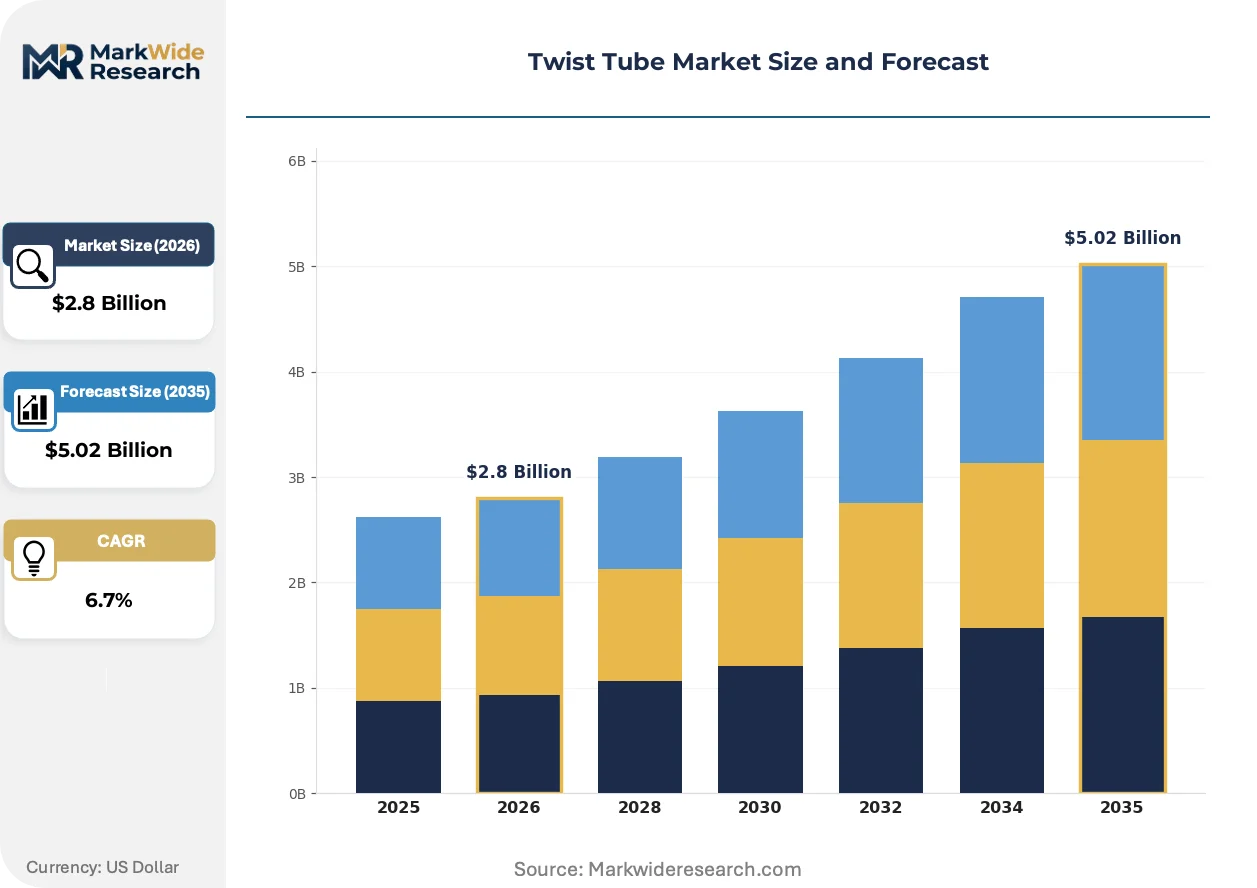
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Composite, Soft Tube Application: Personal Care, Pharmaceuticals, Food & Beverages, Industrial Closure Type: Screw Cap, Flip Top, Nozzle, Pump End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Albea Group, EPL Limited, Amcor plc, Hoffmann Neopac, Essel Propack Limited, Berry Global Inc, Montebello Packaging, CCL Industries, LINHARDT GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twist Tube Market Evolving Landscape
Extrusion technology is fragmenting the supplier base into substrate-specific specialists. Converters must now master barrier chemistry, decoration systems, and regulatory dossier preparation simultaneously.
Multi-layer coextrusion with ethylene vinyl alcohol cores is collapsing the distinction between pharmaceutical and cosmetic tube specifications. German and Swiss OTC dermatology brands are specifying EVOH barriers for products previously packaged in monolayer polyethylene. This convergence forces converters to maintain pharmaceutical-grade cleanrooms for cosmetic contracts, compressing cost structures across both segments.
Europe's F-Gas Regulation is accelerating aluminum tube renaissance in pharmaceutical applications. The phasedown of hydrofluorocarbon blowing agents for plastic foams has disrupted fluoropolymer film availability, pushing converters toward impact-extruded aluminum for oxygen-sensitive ointments. German contract packagers are qualifying new aluminum suppliers to replace laminated barrier tubes in pediatric and geriatric dispensing formats.
Brand owners are consolidating tube specifications across regional portfolios to compress procurement overhead. Oral care multinationals are reducing SKU complexity by specifying identical laminate structures for premium toothpaste in humid Southeast Asian markets and temperate European climates. This standardization concentrates volume with converters capable of global qualification dossiers, marginalizing regional specialists.
Twist Tube Market Segmentation
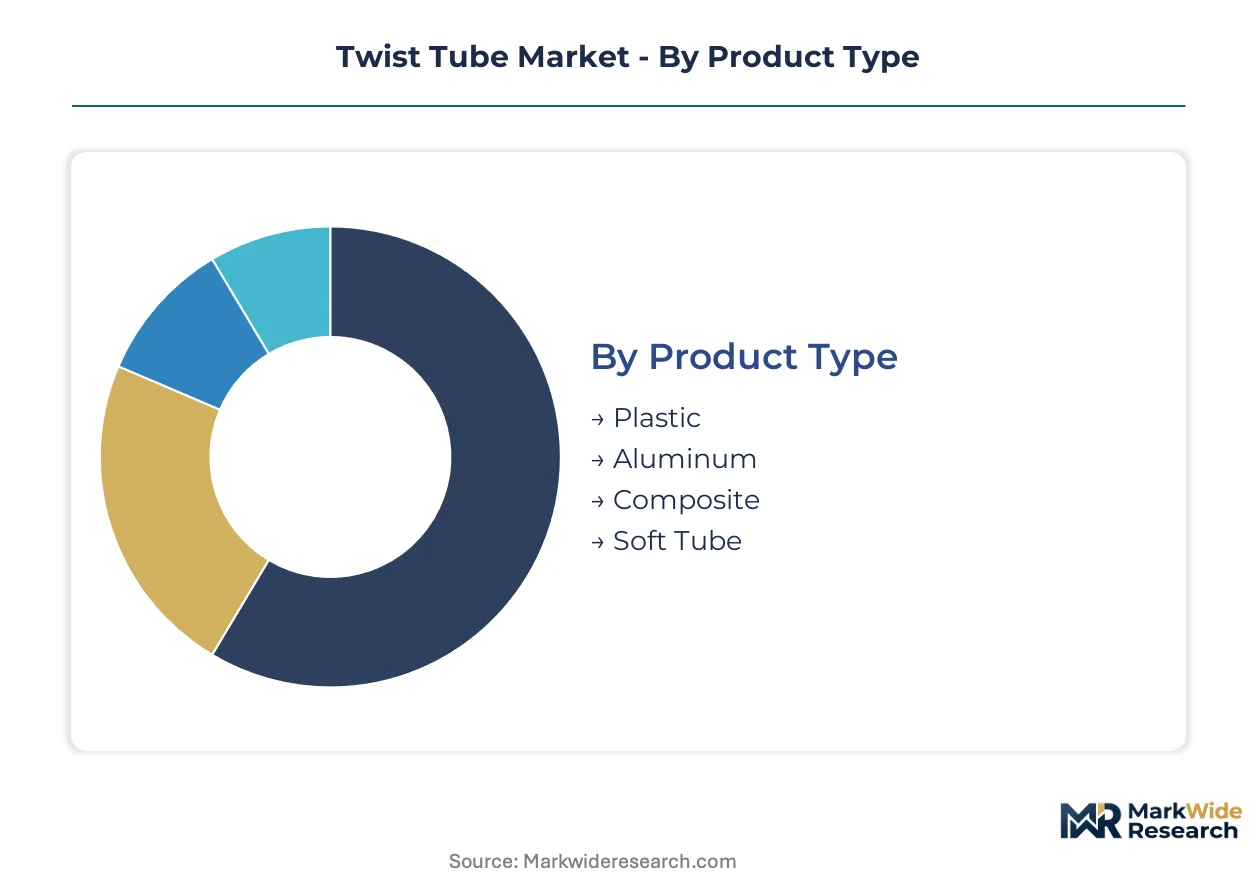
Twist tube specifications fragment sharply across substrate platforms, with pharmaceutical and personal care end-uses demanding incompatible barrier chemistries and filling line formats. Converters must maintain parallel extrusion competencies or surrender margin to substrate specialists.
Product Type:
After-sales technical support intensity escalates dramatically from commodity plastic tubes through multi-layer composites, with pharmaceutical customers demanding 24-month migration study documentation and line qualification support.
- Plastic:Monolayer polyethylene and polypropylene structures dominate high-volume personal care dispensing. German and Swiss OTC dermatology brands are abandoning these formats for barrier alternatives as EMA Medical Device Regulation tightens contact material standards.
- Aluminum:Impact-extruded metal tubes with 0.35mm wall thickness satisfy pharmacopeial inert surface requirements for oxygen-sensitive ointments. Europe's F-Gas Regulation is accelerating aluminum qualification as fluoropolymer barriers face phasedown penalties.
- Composite:Seven-layer laminates with ethylene vinyl alcohol cores collapse pharmaceutical-cosmetic specification boundaries. Demand concentrates in Asia-Pacific oral care where extended shelf-life claims command humid-climate premiums.
- Soft Tube:Low-density polyethylene squeeze formats target economy personal care segments with minimal barrier requirements. India's PLI scheme for medical devices is pulling some soft tube converters toward pharmaceutical-grade cleanroom investments.
By volume, Plastic leads. By growth pace, Composite is ahead.
Application:
Margin structures diverge across end-use categories, with pharmaceutical contracts demanding dedicated cleanroom capacity and 18-month qualification timelines that cosmetic customers refuse to subsidize.
- Personal Care:Shampoo, conditioner, and lotion dispensing drives polyethylene tube volume. Saudi Arabia and UAE retail expansion is localizing decorated laminate production for premium positioning.
- Pharmaceuticals:Ointment, cream, and gel packaging requires pharmacopeial-grade substrates and migration testing dossiers. Blow-fill-seal technology adoption is collapsing traditional filling line economics for contract packagers.
- Food & Beverages:Condiment and sauce dispensing employs high-barrier structures with reduced oxygen transmission rates. REACH plasticizer restrictions are freezing substrate innovation pending 24-month stability studies.
- Industrial:Adhesive, sealant, and lubricant packaging prioritizes chemical resistance over aesthetic decoration. Multi-material coextrusion technician scarcity constrains European and North American converter capacity expansion.
Pharmaceutical contracts yield highest per-unit margins. Personal care generates the steepest volume expansion.
Closure Type:
Customer switching costs escalate from standard screw caps through integrated pump systems, with pharmaceutical packagers validating entire closure-tube combinations rather than mixing formats.
- Screw Cap:Threaded polypropylene closures dominate pharmaceutical ointment dispensing where precise torque control prevents contamination. German contract packagers are qualifying aluminum tube-screw cap combinations to replace laminated barriers.
- Flip Top:Hinged polyolefin lids target single-handed dispensing for personal care and food applications. Asia-Pacific oral care brands specify flip-top laminate tubes for humid-market shelf-life performance.
- Nozzle:Precision-extruded orifices control viscous product flow in adhesive and sealant industrial packaging. Digital printing convergence enables short-run nozzle customization for regional SKU testing.
- Pump:Integrated dispenser systems command premium positioning in high-viscosity personal care. Legacy filling line incompatibility forces pharmaceutical packagers to scrap existing crimping equipment when adopting pump formats.
Screw Cap retains dominant volume share. Pump closures are climbing the fastest.
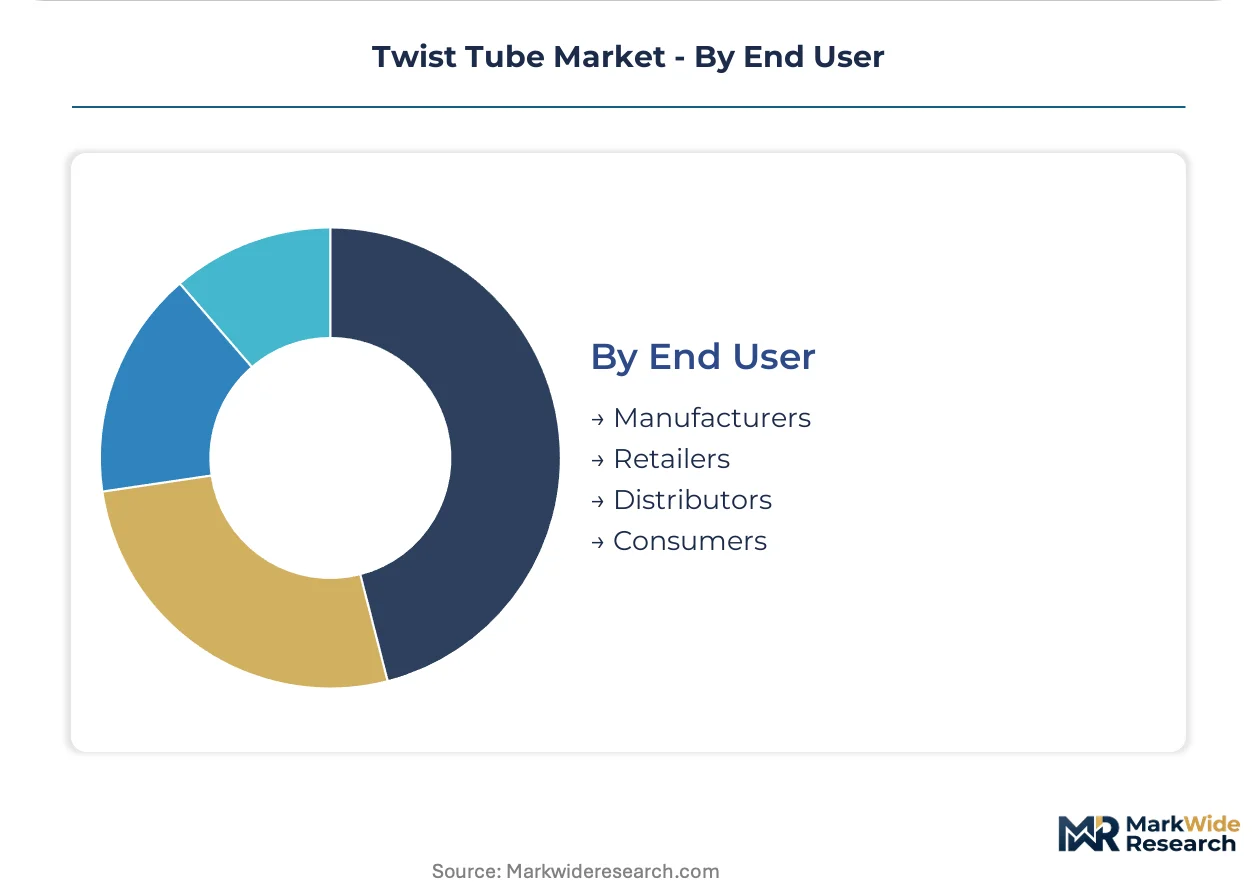
End User:
Procurement sophistication stratifies sharply across the value chain, with manufacturers demanding substrate traceability that retailers and distributors cannot audit.
- Manufacturers:Pharmaceutical and personal care formulators specify substrate platforms and validate filling line compatibility. CDSCO-registered Indian converters qualify for production-linked incentives when supplying domestic drug manufacturers.
- Retailers:Private-label oral care and personal care brands procure decorated tubes through consolidated global specifications. Brand owners are collapsing regional SKU complexity to compress procurement overhead.
- Distributors:Industrial adhesive and sealant channels stock standard polyethylene formats with minimal customization. Barrier film supply concentration in Northeast Asia exposes distributors to freight cost volatility.
- Consumers:Direct-to-subscription personal care brands drive short-run digital printing demand for personalized tube decoration. Extended producer responsibility schemes are shifting recycling infrastructure investment burdens upstream.
Manufacturers command specification authority. Retailers are gaining share fastest through private-label consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packagers in Germany and Switzerland drive premium substrate demand, while oral care multinationals concentrate laminate tube procurement across humid-climate Asian markets.
Germany
EMA Medical Device Regulation compliance is upgrading OTC dermatology packaging to aluminum and high-barrier composites. The country's pharmaceutical regulator enforces pharmacopeial contact standards that disqualify monolayer polyethylene. Contract packaging clusters around Stuttgart and Frankfurt am Main are qualifying new aluminum tube suppliers to replace laminated barriers.
Switzerland
Swissmedic oversight of pharmaceutical contact materials sustains demand for inert metal and laminated barrier tubes. The F-Gas Regulation's phasedown penalties are accelerating converter migration from fluoropolymer films. Basel and Zurich house precision tube converters serving cross-border German pharmaceutical customers.
India
CDSCO-registered tube converters qualify for PLI scheme incentives when supplying domestic drug manufacturers. The national pharmaceutical regulator mandates migration testing dossiers for primary packaging registrations. Maharashtra and Gujarat host decorated laminate specialists pivoting toward pharmaceutical-grade cleanroom investments.
China
NMPA pharmaceutical packaging standards are tightening substrate traceability requirements for imported drug registrations. The national medical products administration enforces stability study protocols that favor established barrier laminate suppliers. Yangtze River Delta converters are scaling ethylene vinyl alcohol coextrusion capacity for oral care export contracts.
Saudi Arabia
SFDA mandates domestic manufacturing of primary packaging for imported drug registrations, creating captive demand for sterile tube filling capacity. The national food and drug authority requires local production certificates for pharmaceutical market entry. Riyadh and Jeddah industrial zones are attracting laminate tube converters establishing regional qualification dossiers.
Twist Tube Market Competitive Landscape
Channel-controlling players compete with product-specialist players across substrate platforms, with pharmaceutical-grade cleanroom capacity separating premium-tier converters from commodity polyethylene suppliers. The market structure concentrates around multi-material specialists capable of seven-layer barrier structures and monolayer scale players serving high-volume personal care. Three archetypes dominate: pharmaceutical-grade barrier specialists, decorated laminate scale operators, and aluminum impact-extrusion traditionalists. Competitive moves center on cleanroom capacity expansion for EMA compliance and strategic partnerships with blow-fill-seal equipment integrators.
Among European-based specialists, Hoffmann Neopac and LINHARDT GmbH & Co. KG exemplify the pharmaceutical-grade barrier archetype, while EPL Limited occupies a position within the decorated laminate tier serving oral care brand owners. These named entities anchor the competitive structure without exhausting the supplier base.
| Leading Market Players |
|---|
| Albea Group |
| EPL Limited |
| Amcor plc |
| Hoffmann Neopac |
| Essel Propack Limited |
| Berry Global Inc |
| Montebello Packaging |
| CCL Industries |
| LINHARDT GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Undercapacity in European multi-layer coextrusion is concentrating pricing power with barrier laminate specialists serving EMA-regulated pharmaceutical packagers. German and Swiss converters exploit this tightness to enforce cost-plus contracts indexed to aluminum ingot and EVOH film benchmarks, while monolayer polyethylene suppliers absorb margin compression from excess Asian capacity.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate pharmaceutical tube procurement, with pharmacopeial-grade metal commanding fixed premiums over commodity grades. Three-tier pricing structure across premium barrier laminates, standard aluminum, and economy polyethylene separates EMA-compliant cleanroom production from cosmetic-grade output. Pricing pressure stems from aluminum ingot volatility squeezing fixed-contract margins when LME spikes occur. Brand owners in personal care exhibit highest price sensitivity, while pharmaceutical formulators prioritize qualification stability over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among German specialists around Stuttgart and Frankfurt am Main, Swiss precision converters in Basel and Zurich, and Indian laminate producers in Maharashtra and Gujarat. Raw material dependencies center on aluminum ingot from smelters, EVOH and polyamide films from Northeast Asia, and pharmaceutical-grade polyethylene resin. Single-source vulnerability in barrier film supply exposes European converters to freight cost shocks and extended lead times. Distribution runs through pharmaceutical contract packagers and oral care brand owners with consolidated global specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The twist tube market operates as a regulatory-moat business where EMA Medical Device Regulation and pharmacopeial certification create entrenched switching costs for pharmaceutical customers. This entrenchment rewards incumbents with multi-year contract visibility while raising barriers for unqualified entrants.
For Market Incumbents: Pre-empt substrate substitution threats by accelerating aluminum tube capacity expansion in Germany and Switzerland before F-Gas Regulation phasedown disrupts fluoropolymer barriers. Secure backward integration into EVOH film supply through strategic partnerships with Northeast Asian producers to insulate margins from freight volatility. Reinforce cleanroom qualification dossiers to capture cosmetic contracts demanding pharmaceutical-grade standards. For New Entrants and Emerging Players: Saudi Arabia and UAE pharmaceutical localization mandates represent the most penetrable entry point, where SFDA domestic manufacturing requirements create captive demand without established incumbent relationships. India's PLI scheme for medical devices offers production-linked incentive qualification for CDSCO-registered converters supplying domestic drug manufacturers. Target sterile tube filling partnerships with regional pharmaceutical formulators seeking import substitution. For Investors and Strategic Acquirers: Capital is best deployed toward multi-material specialists with seven-layer coextrusion capability and existing EMA qualification dossiers, as these assets command scarcity premiums in a technician-constrained environment. Long-term viability hinges on regulatory entrenchment deepening through extended producer responsibility schemes and recycling infrastructure mandates. Monitor aluminum ingot price volatility as an inflection signal for margin compression across fixed-contract pharmaceutical tubes.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Laminate Capacity Expansion | Captures EMA-driven substrate upgrades in German OTC dermatology packaging. |
| Aluminum Impact-Extrusion Qualification | Replaces fluoropolymer barriers facing F-Gas Regulation phasedown penalties. |
| Cleanroom Certification Investment | Enables cosmetic contract capture as pharmaceutical standards converge. |
| Digital Printing Integration | Supports short-run personalization for oral care regional SKU testing. |
| Regional Qualification Dossier Development | Secures SFDA and MOHAP approvals for Saudi and UAE pharmaceutical localization. |
Research Methodology
A standing panel of pharmaceutical contract packaging executives, tube converter operations directors, EMA regulatory affairs specialists, and oral care brand procurement managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from FDA packaging guidance documents, EMA Medical Device Regulation technical standards, CDSCO registration databases, and customs trade records for aluminum ingot and barrier film flows. Bottom-up volume builds across substrate platforms and top-down market sizing triangulated to converge on segment-level estimates.
Scenario-bracketing around aluminum price volatility, EVOH supply disruption, and regulatory timeline acceleration bounded high-low projections across the analysis window. Segmentation modeling incorporated substrate type, application end-use, closure mechanism, and geographic regulatory cluster dimensions. CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends across pharmaceutical and personal care contract structures. Forecast inputs included pharmaceutical pipeline conversion rates for blow-fill-seal technology and oral care shelf-life claim premiums in humid climates.
Stress conditions across London Metal Exchange aluminum spikes, Northeast Asian film export restrictions, and EMA qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between substrate platforms. Quarterly review of CDSCO and SFDA registration volumes, EVOH film freight rate indices, and pharmaceutical contract packager capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Duct Tapes Market
Tapes
Tape Unwinder Market
Tapes
United States End-Of-Line Packaging Tape Market
Tapes
Tape Banding Machine Market
Tapes
Custom Printed Tape Market
Tapes
Tape Stretching Line Market
Tapes
Global Surface Protection Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Strapping Supplies Market
Tapes
Shipping Tapes Market
Tapes
Paper Tapes Market
Tapes
Glue Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Carton Sealing Tape Market
Tapes
Galley Tapes Market
Tapes
Tissue Tapes Market