
 Global Electrical Tapes Market | 2026-2036
Global Electrical Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Tapes Market Foresight
Consolidation among electrical equipment manufacturers is restructuring procurement patterns across the supply base. 3M leverages its polymer science portfolio to sustain premium positioning in high-temperature applications. Nitto Denko anchors its competitive stance through specialized polyimide tape production for electronics fabricators. Tesa SE differentiates via automotive-grade adhesive systems that meet OEM wire harnessing specifications.
Electrical tapes are pressure-sensitive adhesive films engineered from vinyl, rubber, polyester, or polyimide backings with dielectric strength ratings typically exceeding 5 kV per mil, designed to insulate, identify, and protect electrical conductors in industrial and commercial environments. Vinyl tape dominates volume throughput due to its cost-performance balance in general-purpose insulation, while polyimide tape commands margin concentration in aerospace and electronics fabrication where thermal resistance above 180°C is mandatory. Acrylic adhesive formulations are gaining share in outdoor and UV-exposed construction applications where synthetic rubber degrades prematurely.
The EPA oversees volatile organic compound limits on adhesive formulations in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in electrical insulation materials. China's GB standards and the EU's F-Gas Regulation collectively push manufacturers toward solvent-free coating processes and halogen-free backings. Stakeholders must monitor regulatory divergence between major economies to determine whether regional product customization or unified platform strategies offer superior capital efficiency.
Market Dynamics
Wire harnessing demand from electric vehicle manufacturing is compressing specification cycles and forcing adhesive suppliers to validate thermal performance under accelerated timelines. This demand concentration is restructuring procurement relationships across the supply base.
Growth Catalysts
- EV Wire Harnessing:Electric vehicle production in China, Germany, and the United States is consuming specialized electrical tapes rated for 150°C continuous operation. OEMs specify flame-retardant acrylic adhesives that meet UL 510 standards.
- F-Gas Regulation:The EU F-Gas Regulation is phasing down hydrofluorocarbon use in tape manufacturing, creating compliant product premiums for solvent-free coating adopters. REACH alignment is becoming a de facto export requirement.
- Polyimide Thermal Performance:Aerospace and electronics fabricators require dielectric strength above 7 kV per mil at 200°C. Polyimide backings with silicone adhesives are displacing polyester in these high-reliability segments.
Market Restraints
- Petrochemical Input Volatility:Vinyl resin and synthetic rubber prices fluctuate with crude oil markets. Tape margins compress when PVC feedstock costs spike without corresponding price pass-through mechanisms.
- Chinese Supply Concentration:Raw material backings and adhesive intermediates cluster in Zhejiang and Guangdong provinces. Geopolitical friction or logistics disruption threatens just-in-time delivery to European and North American converters.
- Halogen-Free Substitution Pressure:RoHS and REACH restrictions on brominated flame retardants are forcing reformulation. Non-halogen alternatives often require thicker applications, raising material costs per installation.
Strategic Opportunities
- India Industrial Electrification:BIS certification requirements for electrical insulation are tightening as grid expansion accelerates. Early movers establishing testing partnerships gain specification lock-in for infrastructure projects.
- Photovoltaic Installation Surge:Solar farm construction in the southwestern United States and Rajasthan requires UV-stable acrylic tapes for junction box sealing. This application segment remains underpenetrated by established electrical tape suppliers.
- CE Marking Convergence:The EU's Construction Products Regulation is harmonizing fire performance testing. Manufacturers achieving EN 60454-3-1 compliance can access multiple member state markets through single certification.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with pressure-sensitive adhesive expertise are concentrated at legacy tape manufacturers. Mid-tier competitors struggle to recruit specialists capable of developing automotive-grade products.
- Multi-Jurisdiction Certification Timelines:Simultaneous UL, VDE, and CQC approvals require 18-24 month validation cycles. Product launches delay as testing protocols diverge across safety agencies.
- Legacy Equipment Integration:Solvent-free coating lines demand capital investment incompatible with existing rubber-based adhesive production assets. Manufacturers face stranded equipment risk during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Tapes Market |
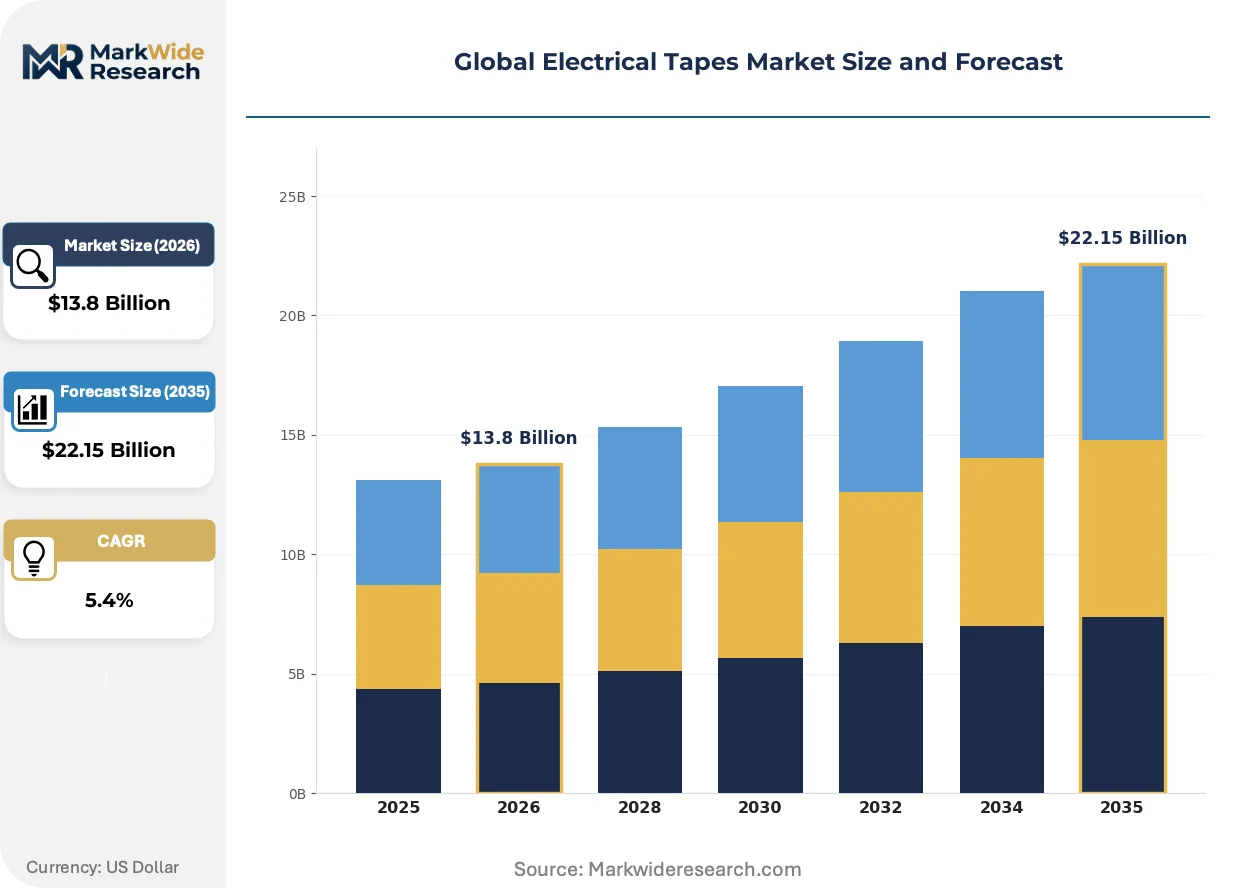
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Tape, Rubber Tape, Polyester Tape, Polyimide Tape, PTFE Tape, Acrylic Tape Adhesive Material: Synthetic Rubber, Silicone, Acrylic, Hot Melt, Pressure Sensitive, Butyl Application: Wire Harnessing, Splicing, Insulation, Masking, Bundling, Identification End User Industry: Electrical Equipment Manufacturers, Construction Contractors, Telecommunications Firms, Aerospace Assemblers, Marine Suppliers, Electronics Fabricators |
| Companies Covered | 3M, Nitto Denko Corporation, tesa SE, Avery Dennison Corporation, HellermannTyton, Intertape Polymer Group, Saint-Gobain, Teraoka Seisakusho Co., Ltd., Plymouth Rubber Europa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Tapes Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are converging to reshape competitive positioning. Manufacturers must now optimize simultaneously for thermal performance, environmental compliance, and total applied cost.
Silicone-acrylic hybrid adhesives are electrifying high-temperature electrical tape performance by combining silicone's thermal stability with acrylic's UV resistance. Automotive OEMs in Germany and Japan are qualifying these formulations for under-hood applications previously reserved for cloth tapes. This convergence is compressing the performance gap between commodity vinyl and specialty polyimide products.
REACH SVHC candidate list expansion is forcing systematic substance tracking across adhesive supply chains. ECHA notifications now cover plasticizers and stabilizers common in PVC backings. European electrical equipment manufacturers are responding by demanding full material disclosure from tape suppliers, with some specifying halogen-free backings as standard procurement terms.
Consolidated procurement by Tier 1 automotive suppliers is concentrating purchase volumes among fewer adhesive tape vendors. Wire harness manufacturers in Mexico and Eastern Europe are negotiating multi-year supply agreements that bundle electrical tapes with connector and terminal purchases. This bundling is most visible in Volkswagen Group and Stellantis supplier parks, where single-source accountability reduces qualification overhead.
Global Electrical Tapes Market Segmentation
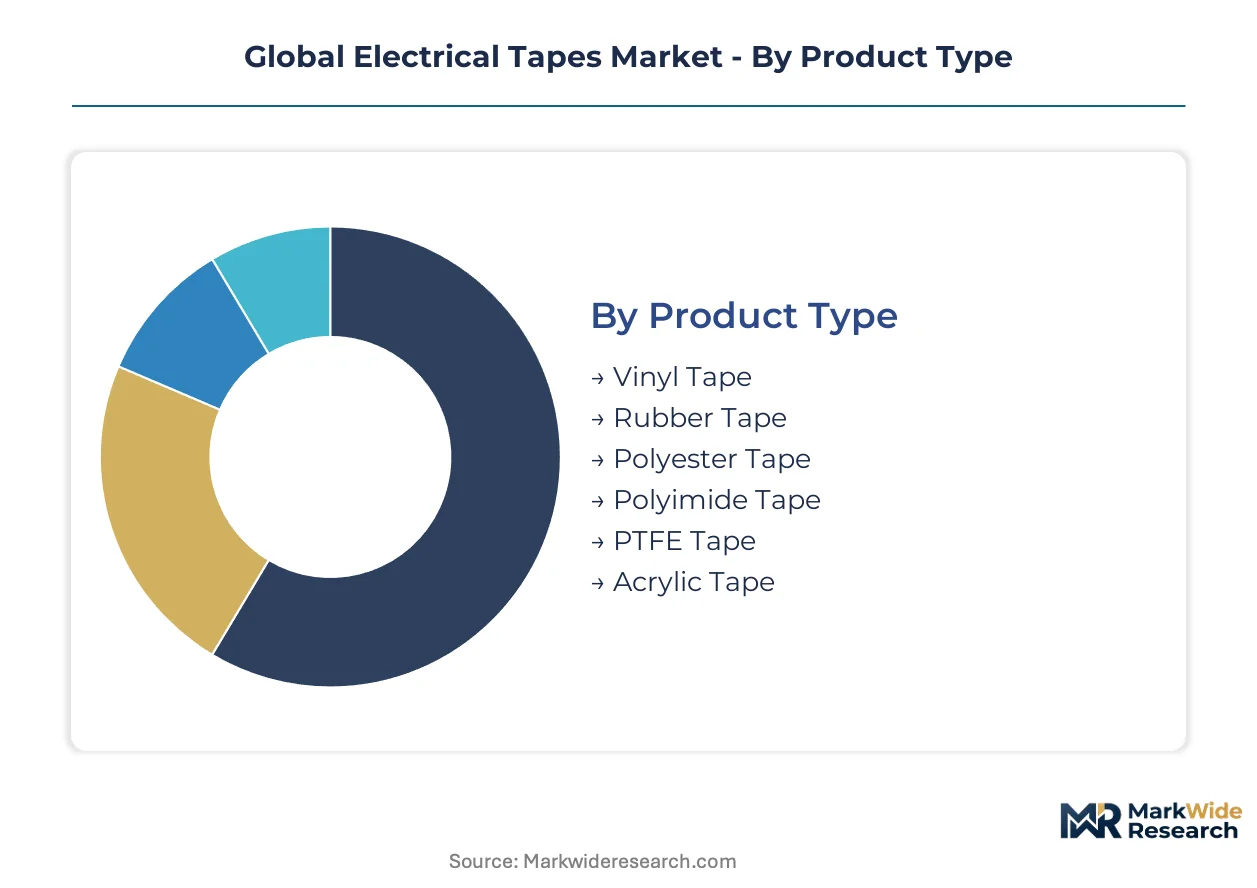
Electrical tapes serve divergent functional requirements across voltage ratings, thermal environments, and regulatory jurisdictions. Segmentation reveals where formulation complexity commands premium positioning versus where commodity specifications dominate procurement decisions.
Product Type:
Integration depth varies sharply — vinyl and rubber tapes anchor standalone field applications, while polyimide and PTFE variants embed into precision manufacturing workflows.
- Vinyl Tape:PVC backing with plasticizer-dependent flexibility dominates general-purpose insulation. Construction contractors in the United States and Germany specify vinyl for low-voltage residential wiring where cost-per-meter drives procurement.
- Polyimide Tape:Amber-colored polyimide film withstands continuous operation above 180°C. Electronics fabricators in Japan and South Korea specify this for flexible circuit board masking during soldering operations.
- Rubber Tape:Self-amalgamating formulations create moisture-resistant seals for outdoor splices.
- Polyester Tape:PET backing offers dimensional stability for coil winding applications.
- PTFE Tape:Fluoropolymer construction provides chemical inertness for harsh industrial environments.
- Acrylic Tape:UV-stable formulations serve photovoltaic junction box sealing in Rajasthan and Arizona installations.
Volume placements concentrate in vinyl tape; the faster expansion belongs to polyimide tape.
Adhesive Material:
Cost tiering separates solvent-borne synthetic rubber formulations from solvent-free acrylic and hot-melt alternatives facing REACH compliance premiums.
- Synthetic Rubber:Solvent-based natural and synthetic rubber adhesives deliver aggressive tack for immediate bond formation. Wire harness manufacturers in Mexico specify rubber adhesives for automotive applications where oily surface conditions prevail.
- Acrylic:UV-resistant acrylic polymers serve outdoor electrical infrastructure without the plasticizer migration issues affecting rubber. Solar farm developers in Gujarat and California specify acrylic tapes for 25-year service life requirements.
- Silicone:Wide temperature range performance suits aerospace thermal protection systems.
- Hot Melt:Thermoplastic formulations enable high-speed coating production for commodity tapes.
- Pressure Sensitive:General classification covering peel-and-stick convenience across multiple backings.
- Butyl:Superior moisture barrier properties serve submarine cable splicing applications.
Customer procurement concentrates in synthetic rubber adhesives; the steepest expansion trajectory belongs to acrylic formulations.
Application:
Application maturity separates decades-old insulation practices from emerging wire harnessing demands reshaping specification cycles.
- Wire Harnessing:Bundled conductor protection demands flame-retardant tapes rated for 150°C continuous operation. Electric vehicle OEMs in Germany, China, and the United States validate thermal performance under accelerated timelines.
- Insulation:Dielectric barrier applications require 5 kV per mil minimum ratings for safety agency compliance. Electrical equipment manufacturers in Italy and France specify insulation tapes meeting EN 60454-3-1 for CE marking access.
- Splicing:Joint sealing and conductor repair in field conditions.
- Masking:Temporary protection during manufacturing processes.
- Bundling:Cable organization and strain relief.
- Identification:Color-coded phase marking for electrical safety compliance.
Volume concentrates in insulation applications; wire harnessing gains share fastest.
End User Industry:
Supply concentration clusters around automotive-adjacent electrical equipment manufacturers, while aerospace and marine segments demand specialized certification portfolios.
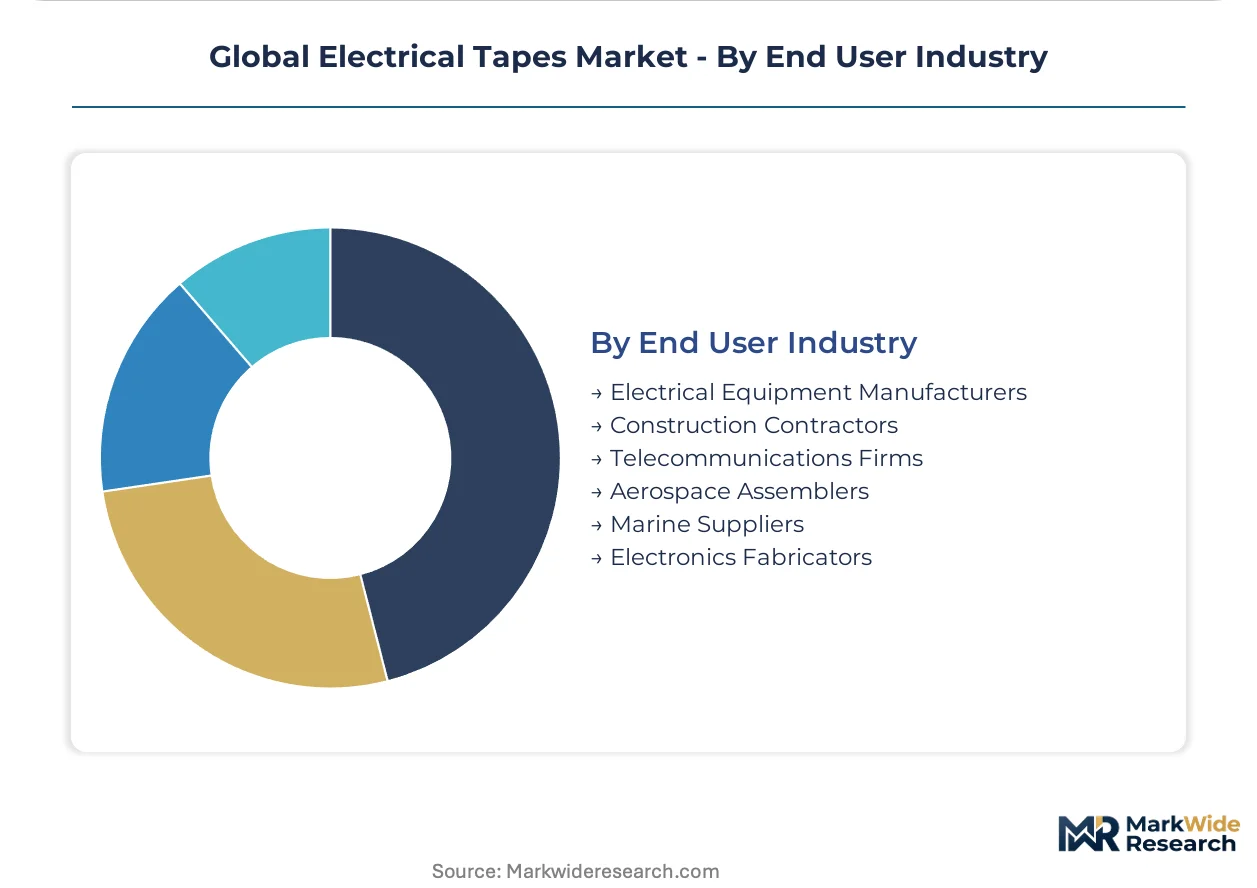
- Electrical Equipment Manufacturers:Transformer, motor, and switchgear producers specify tapes for internal insulation and external protection. Tier 1 suppliers in Germany and Japan negotiate multi-year supply agreements bundling tapes with connector purchases.
- Electronics Fabricators:PCB assemblers and semiconductor packaging operations require ultra-thin polyimide tapes with precise dielectric control. Fabricators in Taiwan and South Korea specify tapes meeting JIS standards for consumer electronics production.
- Construction Contractors:Building wiring installations drive commodity vinyl tape consumption.
- Telecommunications Firms:Fiber optic and copper network infrastructure maintenance.
- Aerospace Assemblers:FAA and EASA certification requirements for aircraft wiring systems.
- Marine Suppliers:Lloyd's Register and DNV classification society compliance for vessel electrical systems.
Procurement volumes concentrate among electrical equipment manufacturers; electronics fabricators expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle manufacturing clusters in China, Germany, and the United States are absorbing specialized electrical tape volumes at rates exceeding traditional industrial demand. Procurement teams at wire harness suppliers in these markets now specify thermal performance ratings that compress traditional validation timelines by half.
China
MIIT's dual carbon goals are accelerating EV production in Shanghai and Shenzhen, where BYD and Tesla Gigafactory operations consume flame-retardant tapes rated for 150°C continuous operation. GB standards compliance has become mandatory for grid infrastructure tenders, pushing domestic converters toward halogen-free backing formulations. Zhejiang and Guangdong provinces host concentrated adhesive intermediate production that supplies both local tape manufacturers and export-oriented converters.
Germany
Volkswagen Group and BMW wire harness specifications are driving demand for automotive-grade acrylic adhesives that meet OEM thermal cycling requirements. The EU F-Gas Regulation is phasing down hydrofluorocarbon use in coating processes, creating compliance premiums for solvent-free production adopters. Bavaria and Baden-Württemberg house Tier 1 supplier parks where bundled procurement agreements concentrate purchase volumes among fewer adhesive vendors.
United States
EPA volatile organic compound limits on adhesive formulations are tightening as domestic EV manufacturing scales in Texas and Michigan. Solar farm construction in Arizona and California requires UV-stable acrylic tapes for junction box sealing, opening underpenetrated application segments. The southeastern manufacturing corridor is attracting wire harness suppliers serving BMW and Mercedes-Benz US assembly operations.
Japan
METI's industrial decarbonization roadmap is pressuring electronics fabricators in Osaka and Nagoya to specify halogen-free insulation materials. JIS standards compliance remains mandatory for consumer electronics exports, maintaining quality thresholds for polyimide tape suppliers. Kyushu-based semiconductor packaging operations require ultra-thin dielectric films with precise thickness control for advanced chip manufacturing.
India
BIS certification requirements for electrical insulation are tightening as grid expansion accelerates in Maharashtra and Gujarat. Domestic EV production at Tata Motors and Mahindra facilities is creating first-time demand for automotive-grade wire harnessing tapes. Tamil Nadu's electronics manufacturing clusters are qualifying imported polyimide films for circuit board assembly operations serving export markets.
Global Electrical Tapes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty thermal performance segments and regional certification arbitrage. The vendor base stratifies across three maturity levels: legacy polymer science conglomerates with multi-jurisdiction approval portfolios, mid-tier converters leveraging geographic proximity to demand clusters, and niche specialists commanding premium positioning in aerospace and semiconductor applications. Strategic moves concentrate on solvent-free coating technology transitions and multi-year supply agreements with Tier 1 automotive suppliers.
Among diversified materials conglomerates, 3M and Nitto Denko Corporation exemplify archetypes built on polymer science depth and specialized film production respectively. Tesa SE occupies a position within automotive-grade adhesive systems, anchoring the European premium tier through OEM qualification relationships. These three entities represent distinct competitive vectors: integrated R&D platforms, focused specialty film expertise, and automotive specification lock-in.
| Leading Market Players |
|---|
| 3M |
| Nitto Denko Corporation |
| tesa SE |
| Avery Dennison Corporation |
| HellermannTyton |
| Intertape Polymer Group |
| Saint-Gobain |
| Teraoka Seisakusho Co., Ltd. |
| Plymouth Rubber Europa |
| Others |
Supply & Pricing Matrix
REACH SVHC candidate list expansion gates qualified supply access and premium-tier pricing power for electrical tape manufacturers serving European automotive OEMs. Solvent-free coating compliance now separates vendors capable of multi-year supply agreements from commodity converters facing margin compression.
Pricing Analysis
Volume concentrates in commodity vinyl tapes where price-per-meter procurement dominates construction contractor purchasing, while margin accrues to polyimide specialists serving aerospace and semiconductor fabricators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL 510 and EN 60454-3-1 compliance command 40-60% premiums over uncertified alternatives. Cost compression in standard-grade vinyl is intensifying because Chinese converters are expanding solvent-free capacity. Construction contractors in India and Southeast Asia exhibit highest price sensitivity; German Tier 1 automotive suppliers demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang and Guangdong provinces, where concentrated adhesive intermediate production feeds both domestic Chinese tape manufacturers and export-oriented converters. PVC resin and synthetic rubber feedstocks draw from petrochemical complexes in China, Germany, and the United States. Tariff exposure threatens just-in-time delivery schedules for European and North American wire harness suppliers. Distribution runs through direct OEM supply agreements for automotive-grade products, while construction and maintenance channels rely on industrial distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into polymer resin production is emerging as the decisive competitive lever, with incumbents securing captive feedstock supply and new entrants facing margin pressure from volatile petrochemical input costs.
For Market Incumbents: Hedge against Chinese supply concentration by qualifying secondary adhesive intermediate sources in India or Southeast Asia. Lock in multi-year offtake agreements with polyimide film suppliers before capacity constraints tighten. Defensive consolidation through acquisition of solvent-free coating specialists preserves specification access for EU automotive OEMs.
For New Entrants and Emerging Players: Regional distributors serving India's solar installation market represent the most accessible channel partnership for acrylic tape specialists. White-space targets include photovoltaic junction box sealing in Rajasthan and Arizona, plus BIS-certified insulation for Maharashtra grid expansion. Qualify products through testing laboratory partnerships rather than competing head-to-head with established automotive supply relationships.
For Investors and Strategic Acquirers: First-mover solvent-free coating adoption among mid-tier Chinese converters is the leading indicator that margin structure will bifurcate between compliant and legacy producers. Acquisition targets should display multi-jurisdiction certification portfolios spanning UL, VDE, and CQC approvals. Watch for Tier 1 automotive supplier consolidation announcements as signals of bundled procurement concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captive PVC and polyimide supply secures margin protection against crude oil volatility. |
| Solvent-Free Coating Transition | REACH and F-Gas Regulation compliance enables premium pricing access to EU automotive OEMs. |
| Multi-Jurisdiction Certification Investment | Simultaneous UL, VDE, and CQC approval reduces 18-24 month validation barriers for new products. |
| Long-Term Supply Agreement with Tier 1 Automotive | Wire harness supplier bundling with Volkswagen Group and Stellantis creates specification lock-in. |
| Photovoltaic Application Development | UV-stable acrylic qualification for Arizona and Rajasthan solar farms opens underpenetrated demand. |
Research Methodology
Document review covered regulatory filings with EPA and ECHA, trade data from customs authorities, and industry association publications, complemented by interviews with procurement directors at Tier 1 automotive suppliers, formulation chemists at adhesive manufacturers, and wire harness engineering leads. Secondary validation drew from SEC 10-K disclosures, GB standards documentation, and BIS certification records. Bottom-up demand modeling triangulated against top-down market sizing.
Segment-level projections across product type, adhesive material, application, and end-use industry fed into consolidated value and volume estimates over the projection horizon. CAGRs were derived from regression analysis of historical production data correlated with EV manufacturing expansion and grid infrastructure investment. Key inputs included wire harness content per vehicle, solar installation growth trajectories, and regulatory compliance timeline assumptions.
Caveats apply where petrochemical price spikes, geopolitical friction affecting Chinese adhesive intermediate exports, or accelerated REACH SVHC list expansion could materially shift the outlook. Forecasts reflect documented assumptions about EV production scaling and regulatory harmonization pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Labels, Tapes and Films Market
Tapes
Pucker Free Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Packaging Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Filmic Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Foam Tape Market
Tapes
Seam Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Removal Strips Market
Tapes
Industrial Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Hot Melt Adhesive Tapes Market