
 Ultra High Bond (UHB) Tape Market | 2026-2036
Ultra High Bond (UHB) Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Bond (UHB) Tape Market Analytics
Automotive OEMs are collapsing their reliance on mechanical fasteners in favor of adhesive bonding systems, and this buyer archetype now commands the largest procurement volumes in UHB tape. 3M Company leverages its multi-layer acrylic formulations to dominate North American automotive programs. Nitto Denko Corporation anchors Asian electronics supply chains with ultra-thin bonding films for display assemblies. Saint-Gobain competes through specialized foam tapes engineered for acoustic dampening in European luxury vehicle platforms.
Ultra High Bond tape is a pressure-sensitive adhesive system engineered with viscoelastic acrylic or modified rubber compositions that achieve structural bonding strengths exceeding 1,000 psi on substrates including metals, composites, and coated glass, manufactured through solvent-free UV-curing or hot-melt calendering processes. Its primary industrial purpose is to replace welds, rivets, and screws in applications where load distribution, vibration dampening, and thermal expansion accommodation are critical. Double-sided acrylic tapes occupy the largest revenue pool due to their universal substrate compatibility, while foam tapes represent the fastest-expanding category as electric vehicle battery pack assembly demands compressible gasket-bonding solutions. Adhesive transfer tapes concentrate margin pools in electronics miniaturization, where micron-level thickness control commands premium pricing.
EPA regulations on volatile organic compound emissions from adhesive manufacturing are forcing reformulation toward solvent-free UV-curable chemistries in US production facilities. REACH restrictions on hazardous substances in Europe, alongside ECHA substance evaluations on acrylate monomers, are reshaping raw material qualification protocols for tape importers. China's GB standards on building material fire performance and SAMR product quality certifications create layered compliance requirements for construction-grade bonding products. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent chemical safety thresholds threaten to fragment product portfolios and inflate certification costs without harmonized international standards.
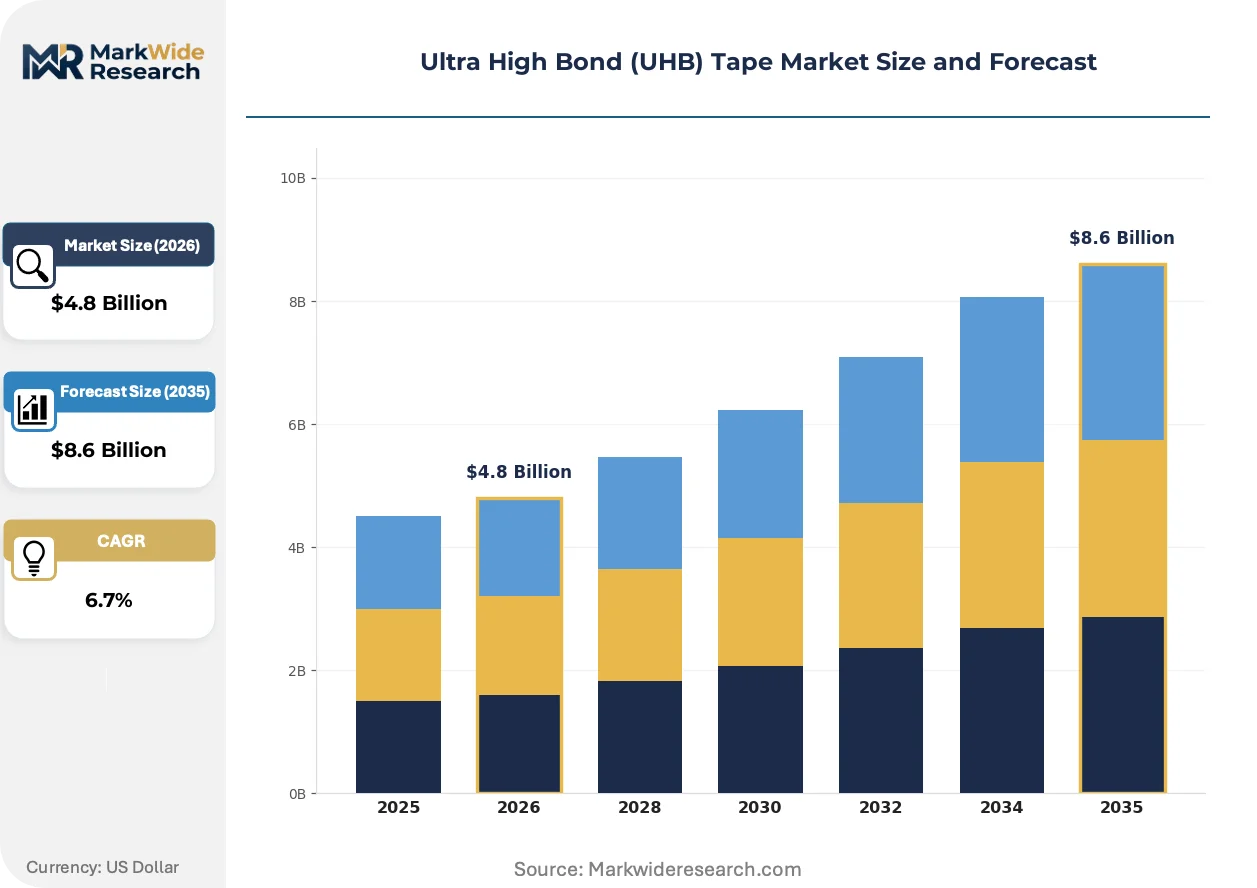
Market Dynamics
Automotive OEMs are systematically replacing mechanical fasteners with adhesive bonding systems, compressing procurement cycles and forcing tape suppliers to certify products for crash-test-validated structural applications.
Growth Catalysts
- Electric vehicle battery pack assembly:Compressible foam tapes seal thermal interface materials in pouch cell configurations, with automakers specifying die-cut gasket-bonding solutions for module-to-pack integration.
- REACH substance restrictions:ECHA evaluations on acrylate monomers are accelerating reformulation investments, creating first-mover advantages for suppliers with pre-qualified solvent-free chemistries.
- Acoustic dampening specifications:European luxury vehicle platforms now mandate multi-layer foam tapes for NVH reduction, expanding addressable content per vehicle.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and synthetic rubber prices fluctuate with crude oil indices, compressing margin visibility for tape converters.
- Asian electronics supply concentration:Display assembly bonding films rely on concentrated substrate and equipment ecosystems in specific manufacturing zones, amplifying disruption risk.
- Structural adhesive substitution:Two-part epoxy and polyurethane systems compete for load-bearing applications where tape cannot achieve required shear strength.
Strategic Opportunities
- Mexico auto assembly expansion:OEMs establishing electrified vehicle production in the northern industrial corridor require localized bonding material supply chains.
- Building-integrated photovoltaics:Structural tape mounting systems for facade solar panels open construction-grade applications beyond traditional industrial markets.
- UV-curable chemistry convergence:Solvent-free manufacturing aligns with EPA VOC regulations while enabling faster line speeds than thermal curing.
Industry Challenges
- Automotive qualification timelines:OEM crash-test validation cycles for structural bonding applications extend 18-36 months, delaying revenue recognition.
- Cross-jurisdictional certification burden:Divergent chemical safety thresholds between EPA, REACH, and China's SAMR standards fragment product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Bond (UHB) Tape Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Foam, Adhesive Transfer, Specialty Application: Automotive Assembly, Electronics, Construction, Packaging Material: Polyethylene, Acrylic, Polyester, PVC End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Lintec Corporation, H.B. Fuller Company, 3M Company, Lohmann GmbH & Co. KG, Saint-Gobain, Avery Dennison Corporation, Nitto Denko Corporation, ORAFOL Europe GmbH, Tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Bond (UHB) Tape Market Evolving Landscape
Reformulation toward solvent-free chemistries is compressing legacy manufacturing processes while enabling new substrate bonding capabilities. Three interconnected developments are restructuring competitive positioning.
Multi-layer acrylic foam tapes with viscoelastic cores are decomposing traditional weld-and-rivet assembly sequences in automotive body-in-white applications. Tier 1 suppliers are specifying these systems for aluminum-to-steel bonding in mixed-material vehicle architectures. The technology is decomposing capital equipment requirements for joining operations while demanding micron-level thickness control from converters.
EPA regulations on volatile organic compound emissions from adhesive manufacturing are forcing production facility retrofits toward UV-curable lines. US-based tape producers face compliance deadlines that compress investment horizons. Automotive-grade product categories bear the highest compliance burden, with reformulation costs concentrated in structural bonding portfolios.
Automotive OEMs are consolidating supplier relationships around full-bonding-system providers rather than component vendors. Tier 1 integrators now specify tape alongside surface preparation protocols and application equipment. This concentration is most visible in Germany's automotive supplier corridor, where OEMs require single-source accountability for structural joint performance.
Ultra High Bond (UHB) Tape Market Segmentation
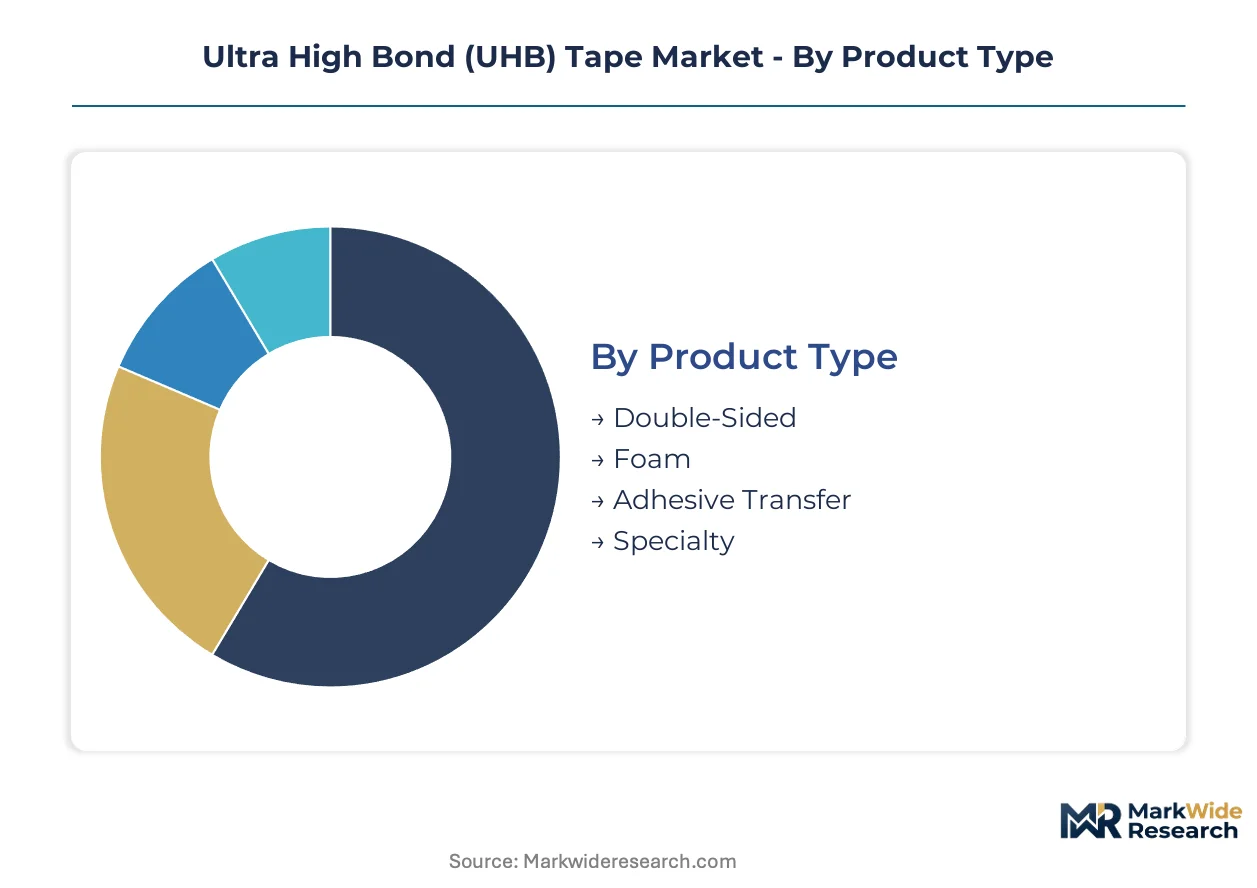
Ultra High Bond tape suppliers configure product portfolios around four intersecting dimensions. Material chemistry determines regulatory compliance pathways, while application specificity dictates qualification timelines and margin structures.
Product Type:
Double-sided acrylic tapes capture the deepest margin pools due to universal substrate compatibility and automotive structural certification requirements.
- Double-Sided:Multi-layer acrylic constructions achieve structural bonding strengths exceeding 1,000 psi on aluminum, steel, and coated glass. Automotive OEMs in Germany specify these systems for mixed-material body-in-white assemblies where thermal expansion accommodation is critical.
- Foam:Compressible viscoelastic cores with polyethylene or acrylic bases seal thermal interface materials in electric vehicle battery packs. China's electronics manufacturing zones drive volume for ultra-thin foam configurations in display gasket applications.
- Adhesive Transfer:Unsupported film adhesives enable micron-level thickness control for electronics miniaturization. Premium pricing concentrates in semiconductor packaging and flexible circuit bonding.
- Specialty:Custom formulations include fire-rated constructions for building facades and optically clear variants for visible bonding joints.
The dominant share belongs to Double-Sided, while Foam is closing the gap fastest.
Application:
Volume concentration tracks automotive electrification investments, with assembly line specifications commanding the longest contract durations.
- Automotive Assembly:Structural bonding replaces welds and rivets in aluminum-intensive vehicle architectures. Mexico's northern industrial corridor is accelerating localized procurement as OEMs establish electrified production platforms.
- Electronics:Display assembly bonding films require ultra-thin caliper control and cleanroom-grade manufacturing. Supply chains concentrate in specific East Asian substrate and equipment ecosystems.
- Construction:Building-integrated photovoltaics and facade panel mounting systems demand weather-resistant structural tapes with fire performance certification.
- Packaging:Heavy-duty carton sealing and reusable container bonding utilize cost-optimized acrylic formulations with lower shear strength requirements.
Automotive Assembly holds the largest revenue base, though Electronics demonstrates the steepest expansion trajectory in absolute volume terms.
Material:
Raw material selection determines VOC compliance pathways and thermal performance ceilings across geographic regulatory regimes.
- Polyethylene:Closed-cell foam carriers provide compressibility for gasket-sealing applications. Electric vehicle battery module integration in Germany and China specifies PE foam tapes for thermal interface management.
- Acrylic:UV-curable solvent-free formulations dominate automotive structural bonding. EPA compliance deadlines are compressing US production facility conversion timelines toward acrylic chemistries.
- Polyester:High-tensile film carriers enable thin, dimensionally stable bonding for electronics flex circuits and membrane switches.
- PVC:Cost-competitive formulations serve construction and packaging applications with moderate performance requirements and shorter qualification cycles.
Acrylic formulations command premium positioning, while Polyethylene volumes expand most quickly on electric vehicle platform ramps.
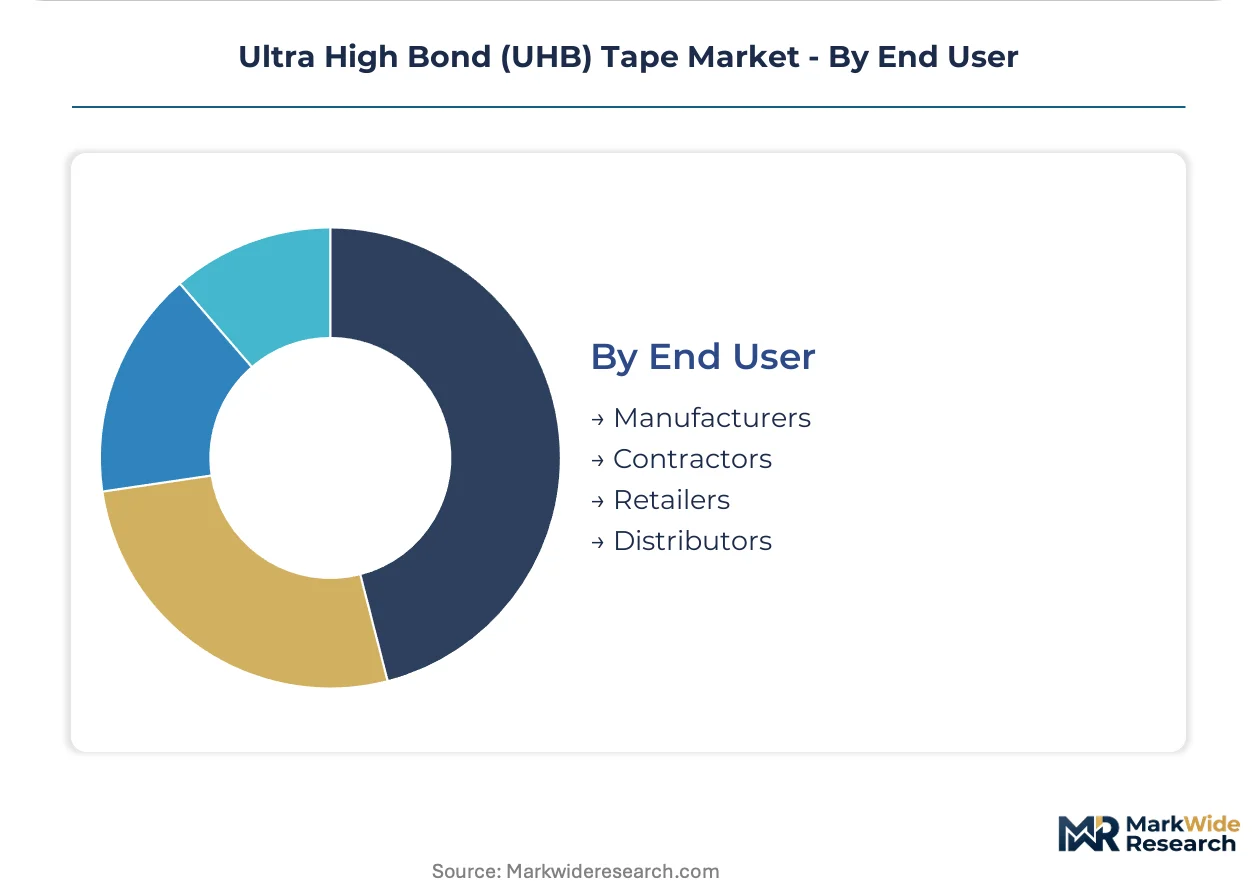
End User:
Procurement authority concentrates with direct manufacturers who control specification writing and application equipment selection.
- Manufacturers:Automotive OEMs and Tier 1 integrators specify full bonding systems including surface preparation protocols. Germany's automotive supplier corridor demands single-source accountability for structural joint performance.
- Contractors:Building facade and solar installation specialists procure construction-grade tapes through distribution with project-specific fire rating requirements.
- Retailers:Consumer and light industrial channels stock general-purpose double-sided tapes for DIY and small-scale assembly applications.
- Distributors:Industrial supply houses consolidate fragmented demand from mid-sized converters and specialty fabricators.
Manufacturers retain specification control, though Distributors are capturing incremental margin through value-added converting services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and electronics contract manufacturers concentrate procurement authority in four countries where regulatory frameworks and industrial clustering create distinct competitive environments. Each geography presents unique qualification requirements and supply chain configurations.
Germany
Luxury vehicle platforms in Bavaria and Baden-Württemberg specify multi-layer foam tapes for NVH reduction. REACH substance restrictions through ECHA accelerate reformulation toward solvent-free acrylic chemistries. Stuttgart's automotive supplier corridor demands single-source accountability for structural joint performance across mixed-material body-in-white assemblies.
United States
EPA VOC regulations compress production facility conversion timelines toward UV-curable manufacturing. Electric vehicle battery pack assembly in Michigan and Ohio drives demand for compressible gasket-bonding solutions. Detroit's Tier 1 integrators consolidate supplier relationships around full-bonding-system providers.
China
Electronics manufacturing zones in Shenzhen and Suzhou consume ultra-thin bonding films for display assemblies. SAMR product quality certifications and GB standards on building material fire performance create layered compliance requirements. Shanghai's semiconductor packaging facilities command premium pricing for micron-level thickness control.
Japan
Display assembly bonding films rely on concentrated substrate ecosystems in Nagoya and Osaka. METI industrial standards shape qualification protocols for automotive-grade applications. Kyushu's electronics component suppliers anchor regional supply chains for flexible circuit bonding.
Mexico
OEMs establishing electrified vehicle production in Nuevo León require localized bonding material supply chains. Northern industrial corridor expansion accelerates procurement from US-based tape converters. Querétaro's aerospace suppliers adopt structural tapes for interior panel assemblies.
Ultra High Bond (UHB) Tape Market Competitive Landscape
Player mix skews toward diversified adhesive conglomerates with multi-industry certification capabilities. Market structure concentrates around three to five global suppliers holding automotive OEM validation credentials. Strategic archetypes separate into full-system integrators, specialty foam converters, and electronics-focused thin-film specialists. Competitive moves center on geographic expansion into Mexico's auto corridor and backward integration into acrylic monomer supply.
Among diversified adhesive conglomerates, 3M Company, Nitto Denko Corporation, and Saint-Gobain occupy positions representing distinct geographic and application specializations. 3M exemplifies the North American automotive structural bonding archetype through its multi-layer acrylic formulations. Nitto Denko sits within the Asian electronics supply chain specialist tier. Saint-Gobain represents the European acoustic dampening and foam tape engineering segment.
| Leading Market Players |
|---|
| Lintec Corporation |
| H.B. Fuller Company |
| 3M Company |
| Lohmann GmbH & Co. KG |
| Saint-Gobain |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| ORAFOL Europe GmbH |
| Tesa SE |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with automotive OEMs lock in acrylic monomer supply access and compress price visibility windows for UHB tape converters serving Germany's supplier corridor. These contracts tie pricing to crude oil indexation, amplifying margin compression when petrochemical feedstock costs spike.
Pricing Analysis
Cost-plus contracts with acrylic monomer indexation dominate procurement between tape converters and automotive Tier 1 suppliers. Three-tier pricing structure across automotive-grade certified, industrial-standard, and economy construction tiers separates qualification-intensive structural bonding from commodity packaging applications. Cost compression in industrial-grade segments is intensifying because Asian electronics manufacturers are consolidating purchase volumes around ultra-thin foam configurations. Automotive OEMs demonstrate lowest price sensitivity due to crash-test validation requirements, while construction contractors exhibit highest sensitivity as they procure through distribution on project-based spot purchasing.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive assembly line supply, while strategic stockpiling of acrylic monomers persists among converters hedging against petrochemical price volatility. Manufacturing concentrates in Germany, China, and Japan, with Mexico's northern corridor emerging as a regional fulfillment hub. Raw material dependencies center on acrylic monomers, synthetic rubber feedstocks, and UV-curable resin systems. Single-source vulnerability runs through concentrated Asian electronics substrate ecosystems. Distribution runs through Tier 1 integrators who bundle tapes with surface preparation protocols and application equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to electric vehicle platform ramp schedules, where battery pack assembly investments are compressing procurement cycles and expanding addressable content per vehicle.
For Market Incumbents: Fortify structural certification portfolios by accelerating solvent-free acrylic reformulation ahead of EPA VOC compliance deadlines. Deepen backward integration into acrylic monomer supply to offset petrochemical feedstock volatility. Capture channel control through full-bonding-system bundling that locks in surface preparation protocol specification.
For New Entrants and Emerging Players: Application engineering services for mid-sized automotive suppliers represent a service-layer gap where incumbents under-serve with standardized product catalogs. Mexico's electrified vehicle production corridor offers the most penetrable geographic entry point. Pursue joint development agreements with Tier 2 battery module integrators seeking localized gasket-bonding solutions.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty foam converters with pre-qualified electric vehicle battery pack applications and established relationships with German automotive OEMs. Long-term viability over the five-to-ten year window hinges on regulatory alignment with REACH substance restrictions and EPA VOC mandates. Watch for inflection when automotive OEMs consolidate supplier panels around single-source structural bonding accountability.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Chemistry Reformulation | EPA VOC compliance deadlines force UV-curable line conversions at US production facilities. |
| Backward Integration into Acrylic Monomers | Captive supply of feedstocks insulates margins from crude oil index volatility. |
| Mexico Manufacturing Footprint Expansion | Localized supply chains serve OEM electrified vehicle platforms in Nuevo León. |
| Full-Bonding-System Bundling | Tier 1 integrators in Stuttgart demand single-source accountability for joint performance. |
| Electric Vehicle Battery Pack Certification | Die-cut gasket-bonding solutions for pouch cell configurations expand content per vehicle. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive OEM procurement directors, Tier 1 supplier platform engineers, tape converter plant managers, and electronics manufacturing services procurement leads. Secondary validation drew from EPA regulatory filings, ECHA substance evaluation databases, SAMR certification registries, customs trade data on acrylic monomer flows, and automotive production databases. Bottom-up volume modeling triangulated against top-down market sizing across material chemistry, application, and end-user dimensions.
Across the analysis window, projections integrate segment-level CAGRs derived from electric vehicle platform ramp schedules, battery pack content per vehicle trajectories, and regulatory compliance cost pass-through assumptions. Segmentation dimensions modeled include product type, application specificity, material chemistry, and end-user procurement authority. Forecast inputs incorporate OEM crash-test validation cycle timelines and REACH substance restriction implementation phases.
Underlying assumptions cover electric vehicle adoption curves and petrochemical feedstock price bands, with deviation risk concentrated in regulatory timeline delays and automotive qualification cycle extensions. Revision becomes warranted when EPA VOC enforcement intensity or ECHA acrylate monomer restriction scope crosses thresholds that accelerate reformulation investment requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Shipping Tapes Market
Tapes
Tear Tape Dispenser Market
Tapes
Correction Tapes Market
Tapes
Adhesive Transfer Tape Market
Tapes
Pre-Printed Tape Market
Tapes
Tissue Tapes Market
Tapes
Tape Banding Machine Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Coding Foils and Tapes Market
Tapes
Painting Masking Tapes Market
Tapes
Global Electrical Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Heat Sealing Tape Market
Tapes
India Masking Tapes Market
Tapes
Application Tapes Market
Tapes
Foam Tape Market