
 US Wound Care Management Devices Market | 2026-2036
US Wound Care Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Wound Care Management Devices Market Insights
Domestic wound dressing production capacity is rebalancing toward advanced material platforms after years of commodity reliance. Smith & Nephew leverages hydrofiber technology leadership to sustain premium positioning in surgical wound care. Medtronic anchors its presence through negative pressure wound therapy systems that dominate hospital procurement channels. ConvaTec Group PLC differentiates via ostomy and wound convergence, occupying a defensible niche in complex chronic wound management.
Wound care management devices encompass dressings, negative pressure systems, and adjunctive technologies engineered to maintain moist wound environments, manage exudate, and accelerate re-epithelialization through controlled microclimate regulation and active debridement. These products serve primarily to reduce infection rates, shorten healing timelines, and lower total cost of care across acute and post-acute settings. Advanced wound care and negative pressure wound therapy command the deepest margin pools, while antimicrobial technology segments register the fastest clinical uptake due to rising multidrug-resistant organism concerns in long-term care facilities. Surgical wound care remains the largest volume category, though home healthcare channel expansion is redistributing growth toward outpatient-compatible dressing formats.
FDA 510(k) clearance pathways and CMS national coverage determinations jointly shape product development priorities and reimbursement access for wound care innovators in the United States. State-level Medicaid expansion variations and Joint Commission infection control standards further stratify market entry requirements across hospital and long-term care networks. Stakeholders must monitor evolving FDA guidance on antimicrobial claims and CMS bundled payment models to align R&D portfolios with the reimbursement architectures that will govern commercial viability.
Market Dynamics
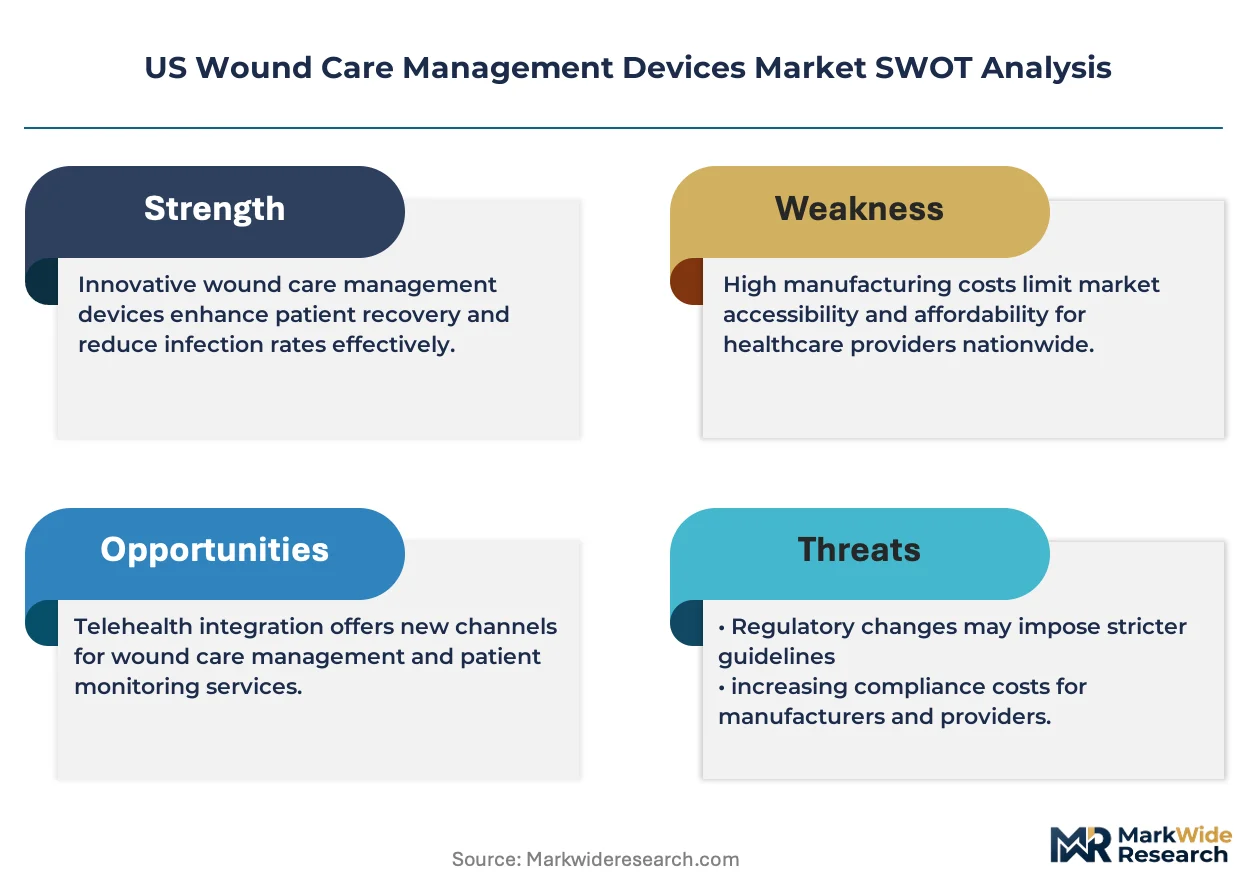
Medicare's bundled payment models for post-acute care are forcing hospital systems to prioritize wound devices that demonstrably reduce readmission penalties, creating procurement criteria centered on total cost-of-care validation rather than unit price alone.
Growth Catalysts
- CMS Innovation Center models:The accountable care organization (ACO) REACH program rewards providers for reduced episode spending, driving investment in negative pressure systems with proven length-of-stay compression.
- Silver tsunami demographics:Southeast and Midwest census projections show 65+ populations expanding fastest, concentrating demand for antimicrobial dressings in long-term care networks across Florida, Georgia, and Ohio.
- Hydrofiber platform maturation:Advanced gelling fiber technology now enables sustained antimicrobial release without secondary dressing changes, accelerating surgical adoption in ambulatory surgery centers.
Market Restraints
- Advanced material input concentration:Medical-grade alginate and silver ion sources concentrate among Asian chemical processors, exposing US converters to freight cost volatility and customs processing delays.
- FDA 510(k) pathway friction:Antimicrobial claim substantiation requirements have tightened substantially, extending clearance timelines for novel silver and iodine formulations by 8-14 months versus standard dressing predicates.
- Negative pressure commoditization:Disposable canister and drape assemblies face price erosion from private-label entrants, compressing margin pools for established system manufacturers.
Strategic Opportunities
- Home health channel expansion:CMS home health value-based purchasing models create reimbursement headroom for portable negative pressure systems with remote monitoring capabilities.
- Chronic wound-ostomy convergence:Complex patient populations with fistulae and peristomal skin breakdown represent underserved segments where integrated dressing systems command premium positioning.
- IRA domestic manufacturing incentives:Production tax credits for medical device reshoring reduce capital recovery periods for automated dressing conversion lines in Ohio and North Carolina.
Industry Challenges
- Wound care specialist workforce gaps:Certified wound ostomy continence nurses (CWOCNs) remain scarce in rural Texas and Appalachian service areas, limiting protocol adherence for advanced device deployment.
- Interoperability with EHR systems:Device-generated wound measurement data lacks standardized HL7 FHIR integration, forcing manual documentation that undermines quality reporting efficiency.
- Legacy supply chain reconfiguration:Just-in-time alginate sourcing from legacy European converters conflicts with domestic inventory requirements under new FDA device shortage reporting mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wound Care Management Devices Market |
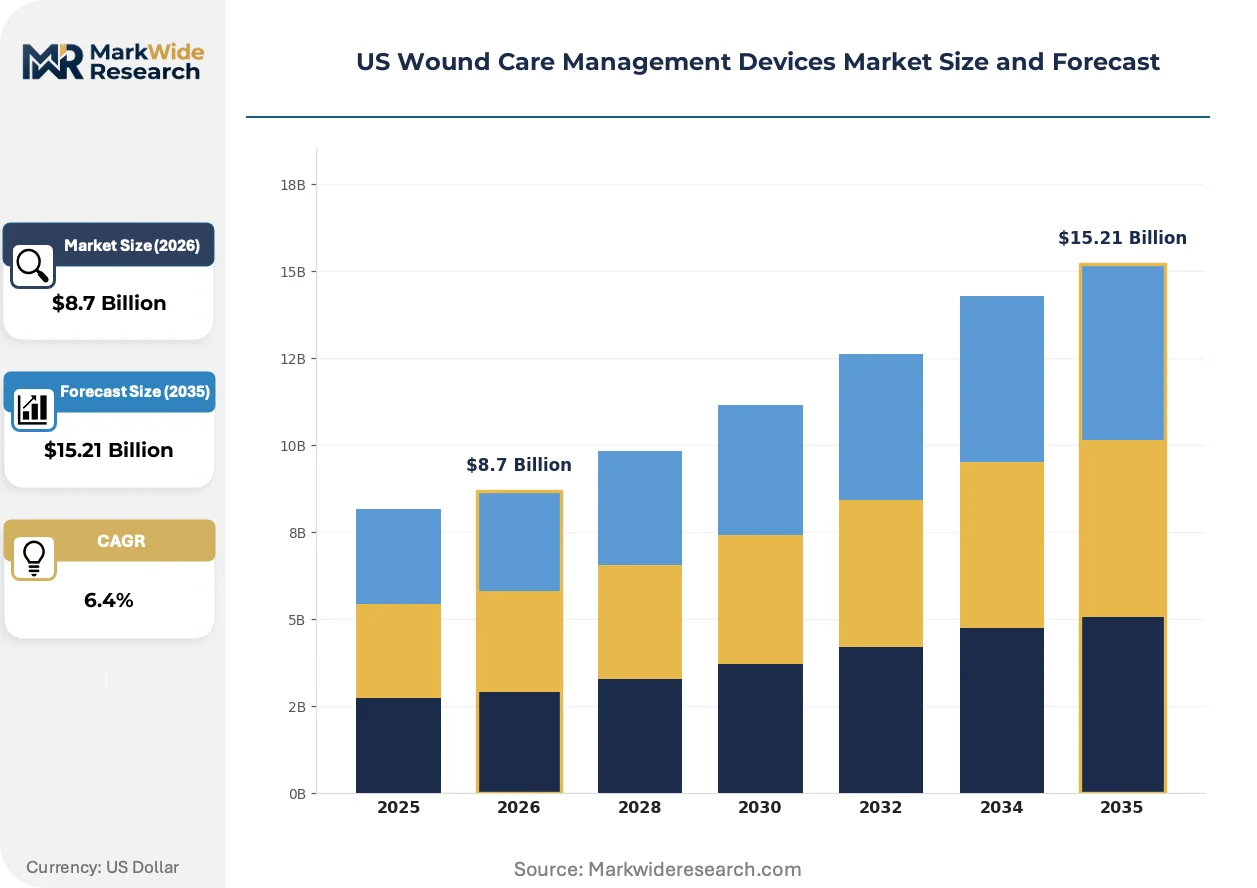
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Negative Pressure Wound Therapy, Advanced Wound Care, Surgical Wound Care End User: Hospitals, Home Healthcare, Outpatient Clinics, Long-term Care Facilities Technology: Hydrocolloid, Foam, Alginate, Antimicrobial Application: Diabetic Ulcers, Pressure Ulcers, Surgical Wounds, Burns |
| Companies Covered | ConvaTec Group PLC, Smith & Nephew, Medtronic, Solventum, Coloplast, 3M, Cardinal Health, Johnson & Johnson, Ethicon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wound Care Management Devices Market Trends and Innovations
Material science convergence with digital health infrastructure is redefining wound care from passive coverage to active therapeutic intervention, creating new value capture points at the device-data interface.
Smart dressing platforms incorporating printed biosensors and wireless transmission are consolidating clinical workflow around continuous moisture and pH monitoring. Hospital systems in California and Massachusetts are piloting these systems in surgical units, with early data showing 30% reduction in unscheduled dressing changes. The technology is consolidating vendor relationships by bundling disposable sensors with analytics subscriptions, displacing standalone dressing procurement.
FDA's 2023 guidance on antimicrobial wound care claims has tightened evidentiary standards for silver and iodine efficacy assertions. Device manufacturers must now submit quantitative microbiological data rather than qualitative antimicrobial labeling, raising R&D costs for novel formulations. Long-term care facilities in Florida and Arizona are responding by standardizing on predicate 510(k) cleared products with established clinical literature, slowing uptake of unproven antimicrobial platforms.
Hospital procurement departments are consolidating vendor contracts through integrated delivery network (IDN) centralization, reducing the number of approved wound care suppliers from 12-15 to 3-5 per system. Group purchasing organizations are capturing this consolidation by negotiating exclusive distribution agreements for advanced dressing portfolios. The shift is most visible in Texas and Illinois health systems, where IDN-level standardization now governs 60% of negative pressure device selection.
US Wound Care Management Devices Market Segmentation
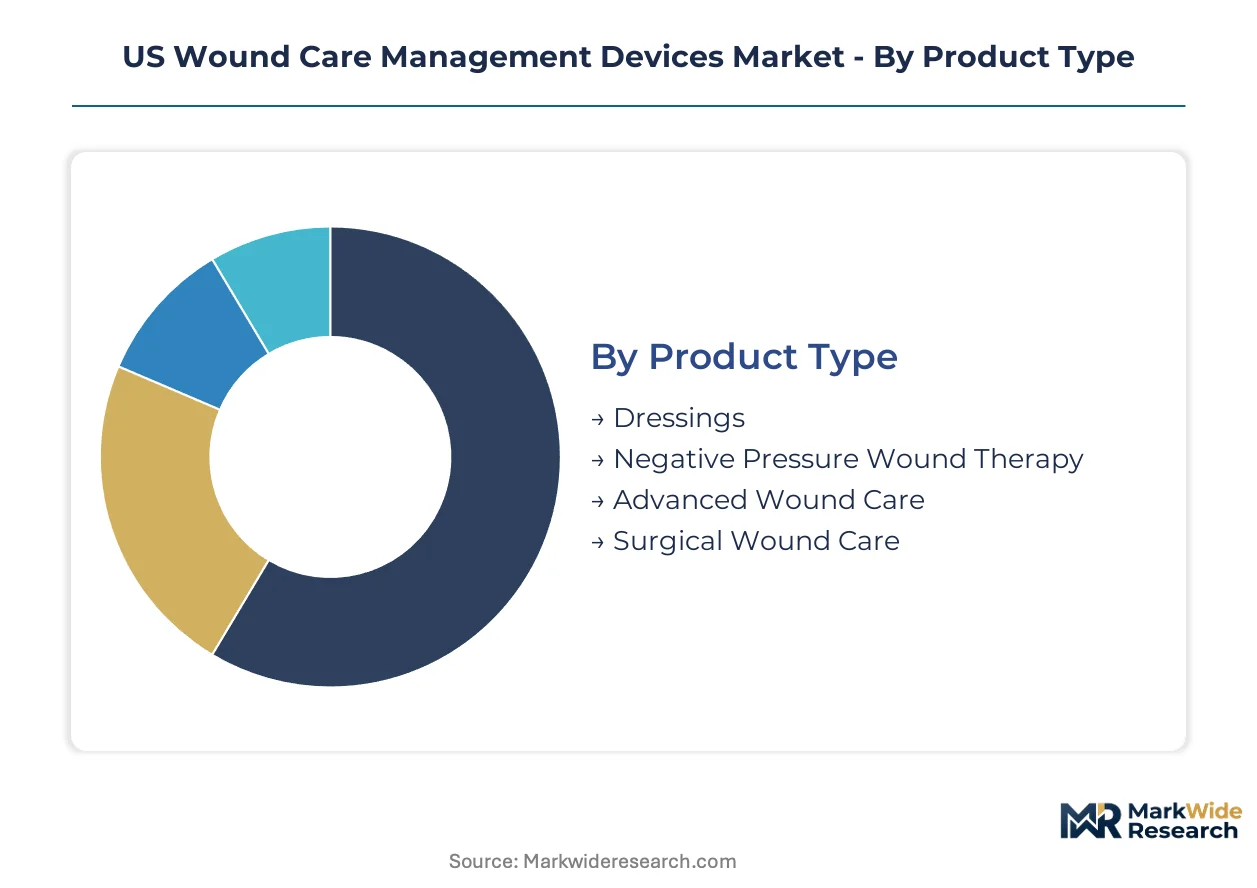
Segmentation in the US wound care management devices market reveals how procurement criteria diverge across care settings and wound etiologies. Hospital systems prioritize length-of-stay compression while home health channels demand portability and simplified protocol adherence.
Product Type:
Dressings and negative pressure systems function as standalone interventions, while advanced wound care platforms increasingly embed sensors and connectivity modules for remote monitoring integration.
- Dressings:Conventional gauze, hydrocolloid, and foam variants serve as primary or secondary coverage layers. Demand concentrates in Southeast long-term care networks where pressure ulcer prevalence drives high-volume antimicrobial dressing consumption.
- Negative Pressure Wound Therapy:Vacuum-assisted closure systems apply sub-atmospheric pressure to accelerate granulation tissue formation. Hospital procurement in Texas and Illinois IDNs favors portable units with disposable canister assemblies that reduce readmission penalties under CMS bundled payments.
- Advanced Wound Care:Bioactive matrices and skin substitutes engineered for chronic wound environments. Ohio and North Carolina manufacturing incentives are reshoring production capacity for alginate and hydrofiber platforms.
- Surgical Wound Care:Incision management systems and post-operative dressings designed for ambulatory surgery center workflows. California and Massachusetts health systems pilot smart dressing integration in surgical units.
Dressings lead volumes today; advanced wound care is gaining share fastest.
End User:
Cost tier stratification separates capital-intensive hospital deployments from consumable-heavy home health models with lower per-episode infrastructure requirements.
- Hospitals:Acute care facilities with 24-hour wound care specialist coverage and negative pressure system infrastructure. Florida and Arizona hospital systems standardize on predicate 510(k) cleared antimicrobial products under tightened FDA guidance.
- Home Healthcare:Post-acute providers delivering wound management in residential settings. CMS home health value-based purchasing models create reimbursement headroom for portable negative pressure systems with remote monitoring capabilities in Midwest service areas.
- Outpatient Clinics:Ambulatory settings managing debridement and dressing changes without overnight admission. Georgia and Ohio clinics show expanding adoption of hydrofiber platforms for surgical wound follow-up.
- Long-term Care Facilities:Skilled nursing and assisted living environments with high chronic wound burden. Silver tsunami demographics in Florida concentrate demand for antimicrobial dressings amid rising multidrug-resistant organism concerns.
Hospitals anchor revenue concentration; home healthcare channels are expanding most quickly.
Technology:
Application maturity separates established hydrocolloid and foam platforms from antimicrobial segments facing tightened FDA evidentiary requirements.
- Hydrocolloid:Gel-forming dressings that maintain moist wound environments through autolytic debridement. Surgical units in ambulatory surgery centers favor these for low-exudate incision management.
- Foam:Highly absorbent polyurethane structures managing moderate to heavy exudate. Long-term care networks in the Southeast deploy these as secondary dressings over antimicrobial primary layers.
- Alginate:Seaweed-derived fibers forming gel matrices upon contact with wound fluid. Medical-grade alginate sourcing concentrates among Asian chemical processors, exposing US converters to freight cost volatility.
- Antimicrobial:Silver, iodine, or polyhexamethylene biguanide impregnated dressings targeting bioburden reduction. FDA clearance timelines for novel formulations have extended substantially versus standard dressing predicates.
Hydrocolloid and foam dominate unit volumes; antimicrobial technology faces regulatory headwinds despite clinical uptake.
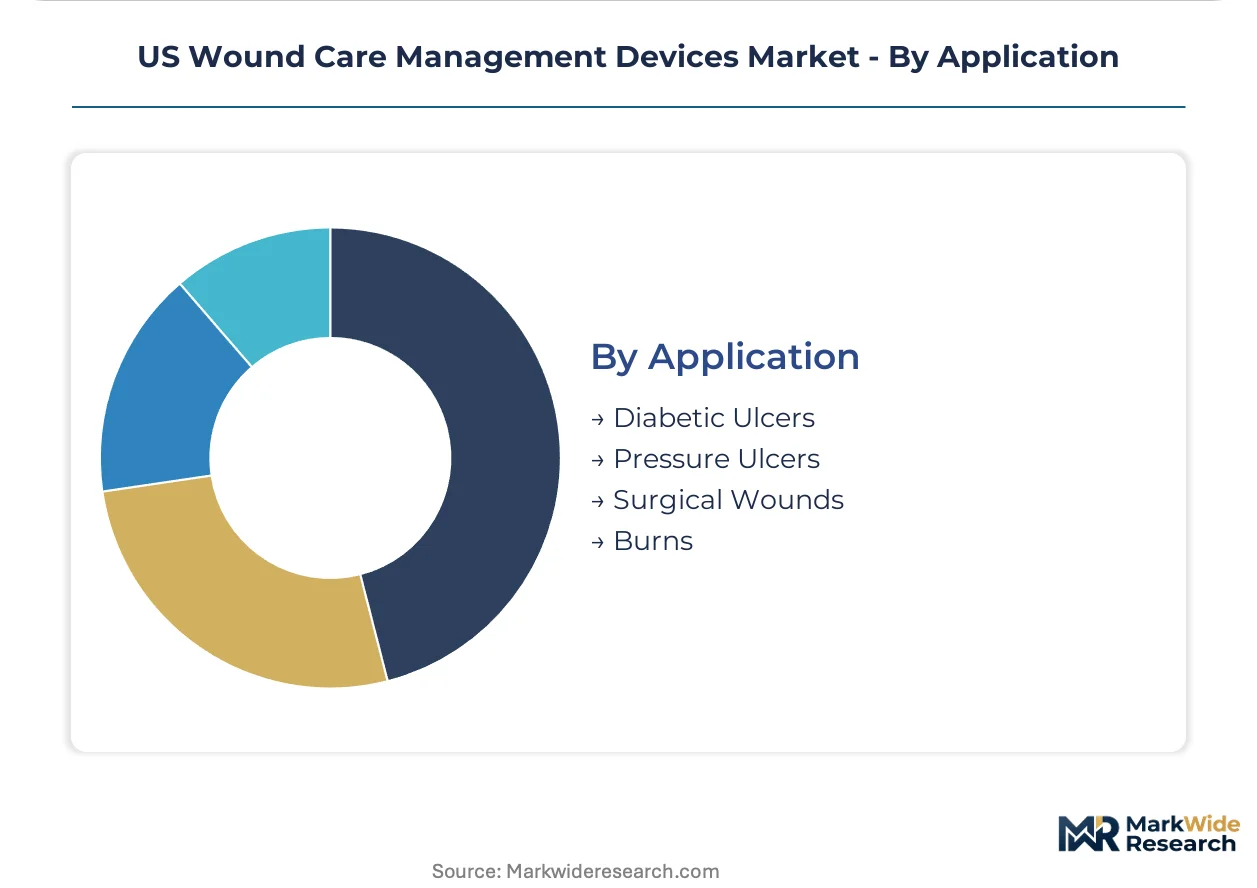
Application:
Geographic demand concentration aligns with population health burdens — diabetes prevalence in the Southeast and aging demographics in the Midwest shape wound etiology patterns.
- Diabetic Ulcers:Lower extremity wounds arising from neuropathy and vascular compromise. Texas and Appalachian service areas show persistent specialist workforce gaps limiting protocol adherence for advanced device deployment.
- Pressure Ulcers:Localized tissue damage from sustained pressure, primarily over bony prominences. Florida long-term care facilities drive sustained utilization of negative pressure therapy and antimicrobial dressings.
- Surgical Wounds:Incisions and tissue trauma from operative procedures. IDN centralization in Texas and Illinois health systems now governs 60% of negative pressure device selection for post-operative care.
- Burns:Thermal, chemical, or electrical injury requiring specialized fluid management and infection control. Advanced wound care platforms with bioactive matrices serve complex partial-thickness cases.
Surgical wounds generate the largest procedure volume; diabetic ulcers present the steepest expansion trajectory amid population health trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives under the IRA are reshaping production geography as US converters reshore alginate and hydrofiber capacity to reduce exposure to Asian chemical processor concentration and customs processing volatility.
Southeast
Florida and Georgia long-term care networks drive antimicrobial dressing demand amid silver tsunami demographics and multidrug-resistant organism prevalence. State Medicaid expansion variations in Georgia create reimbursement stratification that favors predicate 510(k) cleared products. Tampa and Miami medical device clusters concentrate distribution infrastructure for pressure ulcer management systems.
Midwest
Ohio and Illinois hospital systems anchor negative pressure wound therapy procurement through IDN centralization governing 60% of device selection. CMS bundled payment models for post-acute care force prioritization of readmission-reducing systems. Cleveland and Chicago manufacturing corridors host automated dressing conversion lines benefiting from IRA production tax credits.
Southwest
Texas health systems exhibit the most aggressive IDN-level vendor consolidation, reducing approved wound care suppliers from 12-15 to 3-5 per system. Rural service areas face certified wound ostomy continence nurse scarcity limiting advanced device protocol adherence. Dallas-Fort Worth distribution hubs coordinate procurement for diabetic ulcer populations across the state.
West Coast
California and Massachusetts health systems pilot smart dressing platforms with printed biosensors in surgical units, achieving 30% reduction in unscheduled dressing changes. FDA 510(k) pathway friction for antimicrobial claims tightens evidentiary standards, extending clearance timelines. San Francisco and Boston medical technology corridors concentrate digital health infrastructure for remote monitoring integration.
US Wound Care Management Devices Market Competitive Landscape
US-based producers anchor the premium-tier negative pressure and advanced dressing segments; European specialists hold defensible positions in ostomy-wound convergence and hydrofiber platforms. Hospital procurement consolidation through IDN centralization and GPO exclusive distribution agreements is compressing vendor counts per system from double digits to single digits. Three archetypes dominate: diversified medical technology conglomerates with system-level bundling power, mid-cap wound care pure-plays with material science differentiation, and private-label assemblers eroding disposable component margins. Competitive moves center on M&A for vertical integration into medical-grade alginate sourcing and strategic partnerships for EHR interoperability.
Within the diversified technology tier, Medtronic and 3M exemplify scale-driven platform bundling that captures IDN procurement consolidation. Smith & Nephew represents the European specialist archetype with hydrofiber technology positioning in surgical wound care. ConvaTec Group PLC occupies a defensible niche at the chronic wound-ostomy convergence point where integrated dressing systems command premium positioning.
| Leading Market Players |
|---|
| ConvaTec Group PLC |
| Smith & Nephew |
| Medtronic |
| Solventum |
| Coloplast |
| 3M |
| Cardinal Health |
| Johnson & Johnson |
| Ethicon |
| Others |
Pricing and Supply Chain Analysis
Hydrofiber platform maturation toward automated conversion lines simultaneously compresses per-unit production economics and concentrates manufacturing capacity among IRA-incentivized domestic producers. This technology transition rewards scaled operators with captive alginate sourcing while fragmenting pricing power across hospital procurement tiers.
Pricing Analysis
Distributor margin layering shapes three-tier pricing structure across premium, standard, and economy levels. Premium hydrofiber and negative pressure systems command placement through GPO exclusive agreements and FDA 510(k) predicate advantages, while standard foam and hydrocolloid variants face compression from private-label entrants. Pricing pressure stems from IDN vendor consolidation reducing approved suppliers from double digits to single digits. Home health channels exhibit highest price sensitivity due to CMS reimbursement caps, whereas surgical units in IDN-anchored systems prioritize total cost-of-care validation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Asian chemical processors controlling medical-grade alginate and silver ion feedstocks. US converters draw from Japan, South Korea, and coastal Chinese processors for gelling fiber precursors, with European converters supplying legacy hydrocolloid resins. Tariff exposure on imported active ingredients threatens margin stability for antimicrobial dressing assemblers. Distribution runs through regional medical device clusters in Tampa, Dallas-Fort Worth, and Cleveland, with GPOs capturing consolidated procurement flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Medicare bundled payment models and FDA antimicrobial claim tightening concentrate procurement around predicate-cleared premium platforms.
For Market Incumbents: Deepen backward integration into medical-grade alginate sourcing to offset Asian processor concentration and customs volatility. Expand automated conversion capacity in Ohio and North Carolina to capture IRA production tax credits. Fortify GPO exclusive distribution agreements before IDN centralization completes vendor rationalization. For New Entrants and Emerging Players: Direct-to-home-health digital channels offer the most penetrable route around established hospital procurement gatekeepers. Target portable negative pressure systems with remote monitoring capabilities for Midwest service areas where CMS value-based purchasing creates reimbursement headroom. Lead with simplified protocol adherence to address rural specialist workforce gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap wound care pure-plays with material science differentiation but limited EHR interoperability. Long-term viability hinges on device-data platform convergence over the coming decade. Monitor FDA 510(k) clearance timelines for novel antimicrobial formulations as the inflection signal for R&D portfolio risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | IDN centralization in Texas and Illinois now governs sixty percent of negative pressure device selection. |
| Reimbursement Strategy | CMS bundled payment alignment reduces readmission penalties and secures procurement preference. |
| Software Companion Development | HL7 FHIR integration for wound measurement data addresses quality reporting efficiency gaps. |
| FDA Submission | Predicate 510(k) pathway selection accelerates clearance amid tightened antimicrobial claim requirements. |
| Backward Integration | Captive alginate sourcing insulates margin from Asian chemical processor freight volatility. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, GPO contract database analysis, and CMS reimbursement filing review — were reconciled against secondary validation. Primary fieldwork engaged wound care specialists, biomedical engineers, IDN supply chain directors, and long-term care facility administrators across Southeast and Midwest service areas. Secondary sources encompassed FDA 510(k) clearance databases, CMS national coverage determinations, hospital procurement records, and IRA manufacturing incentive filings. Bottom-up unit demand modeling and top-down expenditure reconciliation anchored value estimates.
Cross-reference between historical utilization patterns and expert panel input shaped the analytical framework. Segmentation dimensions spanned product type, end-user channel, wound etiology, and technology platform across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating demographic projections, reimbursement trajectory assumptions, and regulatory pathway timelines. Forecast inputs included certified wound specialist workforce density and IDN consolidation velocity.
Regulatory guidance shifts, Medicare payment model revisions, and antimicrobial resistance surveillance data are the dominant revision risks for trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Collagen Dressings Market
Wound Care
Bioactive Wound Care Market
Wound Care
Europe Wound Care Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Pressure Bandages Market
Wound Care
Bioactive Wound Management Market
Wound Care
Animal Wound Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
US Burn Care Centers Market
Wound Care
Wound Drainage Devices Market
Wound Care
France Wound Care Market