

Surgical Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Wound Care Market Insights
Chinese absorbent material producers is repositioning capacity toward medical-grade foam substrates to serve branded device makers in Europe and North America. Mölnlycke Health Care leverages its Gothenburg manufacturing base to sustain just-in-time supply for Nordic hospital networks. Smith + Nephew anchors its competitive stance through specialized negative pressure wound therapy systems for post-operative sites. Baxter differentiates via integrated delivery platforms that bundle dressings with irrigation solutions.
Surgical wound care encompasses sterile barrier systems, hemostatic agents, and moisture-retentive dressings engineered to maintain optimal wound healing environments, typically measured by MVTR (moisture vapor transmission rate) thresholds between 2,000 and 5,000 g/m²/24h. These products serve primarily to reduce surgical site infection rates and accelerate epithelialization across acute incision closures. Advanced dressings command the dominant margin pool due to sustained premium pricing for antimicrobial and enzymatic formulations, while traditional gauze occupies a shrinking but still substantial volume position in cost-sensitive procurement channels. Negative pressure therapy within the delivery mode dimension is expanding fastest as post-discharge protocols extend hospital-at-home reimbursement frameworks.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) establish divergent conformity pathways that force manufacturers to maintain dual quality management systems for transatlantic distribution. The EPA regulates antimicrobial agents incorporated into wound dressings, creating additional toxicology submission burdens that filter out smaller formulation suppliers. Stakeholders must monitor evolving hospital value-based procurement criteria that increasingly bundle infection rate outcomes with device selection decisions.
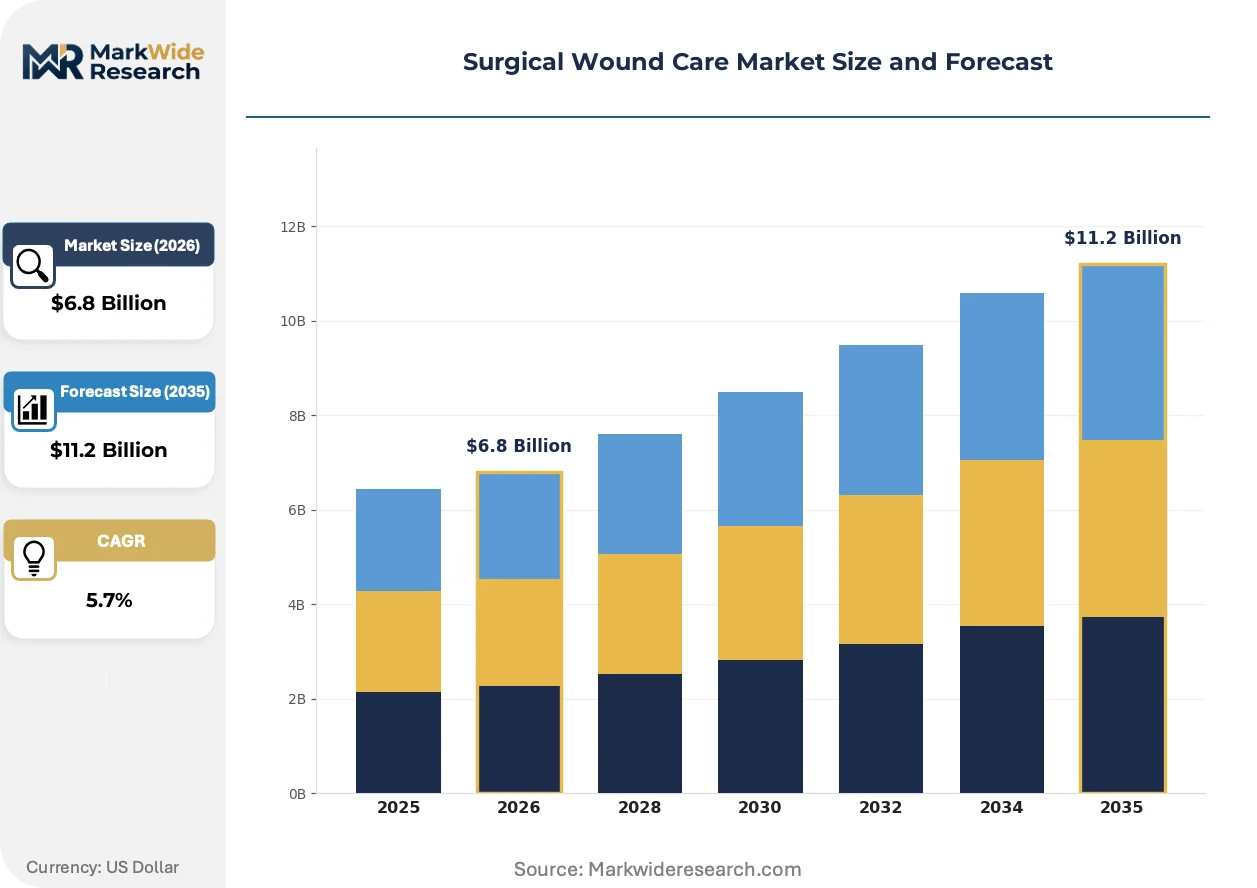
Market Dynamics
Hospital consolidation across Germany is compressing vendor counts and centralizing purchasing authority, forcing suppliers to reconfigure account management structures around group procurement organizations rather than individual facility relationships.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation's phased enforcement is filtering out marginal suppliers and opening shelf space for certified incumbents with established quality management systems.
- Silver-Substitute Antimicrobials:EPA scrutiny of silver ion environmental accumulation is accelerating iodine-based and polyhexamethylene biguanide formulations through toxicology review pipelines.
- Ambulatory Surgery Expansion:Freestanding surgical centers in the United States are building dedicated supply chains for advanced closure systems that match hospital-grade performance at lower per-procedure footprints.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane foam substrates depend on propylene oxide and toluene diisocyanate pricing, with European producers exposed to naphtha-cracker margin squeezes.
- Single-Source Medical-Grade Adhesives:Acrylic pressure-sensitive adhesive supply concentrates among German and Japanese specialty chemical houses, creating qualification bottlenecks for dressing laminators.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face 14-18 month queues at accredited laboratories, freezing product iteration cycles.
Strategic Opportunities
- Hospital-at-Home Reimbursement:CMS expanded post-acute coverage for negative pressure wound therapy in residential settings, opening device rental and disposable subscription models.
- Enzymatic Debridement Convergence:Collagenase formulations are integrating with hydrogel delivery matrices, creating combination products that straddle drug-device regulatory boundaries.
- Direct-to-Provider E-Procurement:Specialized distributors in the United Kingdom are building cloud-based inventory management platforms that bypass traditional medical-surgical distributor markups.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with hydrogel crosslinking and controlled-release expertise command premium compensation, constraining R&D team expansion.
- Dual QMS Maintenance:Manufacturers serving transatlantic markets must operate parallel FDA 21 CFR Part 820 and EU MDR quality systems, doubling audit and documentation overhead.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Wound Care Market Trends and Innovations
Digital connectivity and enzymatic biochemistry are displacing passive materials as the primary vectors of product differentiation, while regulatory complexity is becoming a competitive moat rather than a compliance burden.
Smart dressing systems incorporating printed sensors for moisture detection and temperature monitoring are decentralizing wound assessment from centralized nursing stations to automated remote monitoring platforms. Post-acute care facilities in Denmark and the Netherlands are piloting these systems for surgical site surveillance. The technology is decentralizing clinical decision-making authority and compressing readmission-triggered intervention timelines.
The FDA's updated 510(k) pathway for antimicrobial dressings is streamlining predicate device referencing for silver and iodine formulations, reducing average submission preparation from 18 to 12 months. This regulatory recalibration favors incumbent manufacturers with extensive cleared-device libraries. Wound care divisions with established 510(k) portfolios are accelerating refresh cycles to exploit the compressed review timeline.
Group purchasing organizations in the United States are unbundling infection rate guarantees from device supply contracts, creating standalone performance-based agreements that tie dressing selection to surgical site infection outcomes. This restructuring shifts risk from hospitals to suppliers and demands real-world evidence generation capabilities. The model is most visible in cardiovascular and orthopedic service lines where procedure volumes justify outcome tracking infrastructure investment.
Surgical Wound Care Market Segmentation
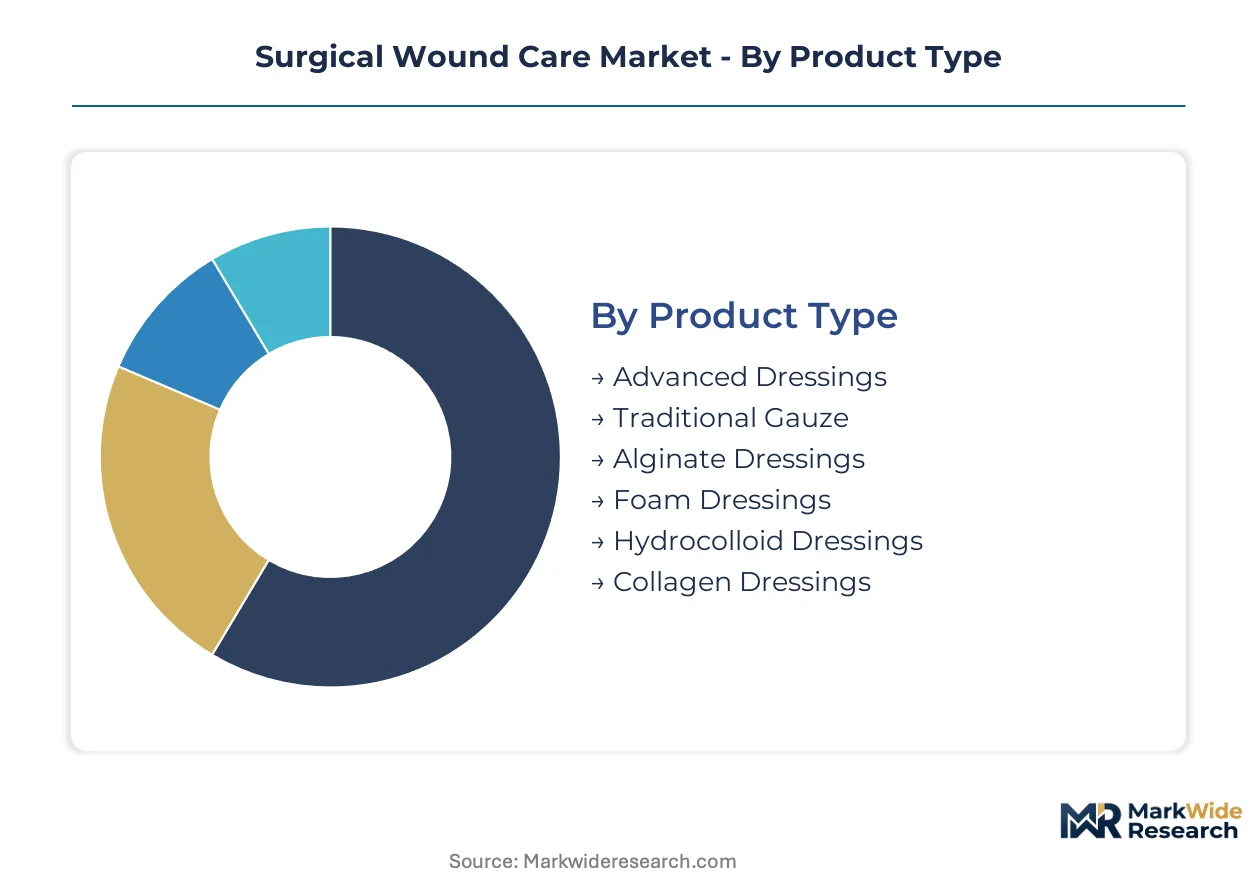
Surgical wound care segmentation reveals divergent margin structures across product maturity tiers. Manufacturers configure portfolio depth around procedure-specific reimbursement codes and infection risk stratification protocols.
Product Type:
Advanced formulations embed antimicrobial or enzymatic functionality requiring companion quality systems; traditional materials operate as standalone commodities with minimal regulatory overhead.
- Advanced Dressings:Silver-ion, iodine, or PHMB-impregnated substrates engineered for MVTR thresholds between 2,000-5,000 g/m²/24h. Hospital procurement in Germany concentrates demand through consolidated group purchasing organizations seeking infection rate guarantees.
- Traditional Gauze:Cotton or synthetic woven materials without active pharmaceutical ingredients. Cost-sensitive channels in India and Brazil sustain volume despite compression in premium markets.
- Alginate Dressings:Calcium-sodium seaweed-derived fibers forming gel matrices upon exudate contact.
- Foam Dressings:Polyurethane substrates with controlled hydrophilicity; Chinese producers are repositioning capacity toward medical-grade specifications.
- Hydrocolloid Dressings:Carboxymethylcellulose and gelatin composites for low-exudate environments.
- Collagen Dressings:Bovine or porcine extracellular matrix scaffolds promoting granulation tissue formation.
Volume placements concentrate in Traditional Gauze; the faster expansion belongs to Advanced Dressings.
Application:
Procedure complexity dictates dressing specification depth, with high-complication specialties commanding multi-layer systems and remote monitoring integration.
- Orthopedic Procedures:Joint arthroplasty and fracture fixation sites require negative pressure therapy compatibility and shear-resistant adhesion. CMS reimbursement expansion for hospital-at-home protocols is accelerating post-discharge device rental models in the United States.
- Cardiothoracic Surgeries:Sternotomy and thoracotomy closures demand sterile barrier integrity under continuous cardiac monitoring conditions.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair closures across diverse anatomical locations.
- Neurosurgery:Cranial and spinal procedures requiring minimal adhesive trauma to delicate tissue planes.
- Obstetrics & Gynecology:Cesarean section and hysterectomy sites with cosmetic outcome sensitivity.
- Plastic Surgery:Aesthetic and reconstructive procedures where scar minimization drives premium material selection.
General Surgery generates the highest absolute unit demand; Orthopedic Procedures are climbing the fastest on ambulatory surgery expansion.
End User:
Facility accreditation status determines formulary access tiers, with academic medical centers maintaining broader advanced product authorization than community sites.
- Ambulatory Surgical Centers:Freestanding facilities building dedicated supply chains for advanced closure systems matching hospital-grade performance at compressed per-procedure footprints. United States site-of-service payment differentials favor this channel.
- Specialty Clinics:Dermatology and wound care centers with focused procedure mixes and limited inventory breadth.
- Academic Hospitals:Teaching institutions with research mandates and complex case referral patterns.
- Long-Term Care Facilities:Skilled nursing environments managing post-acute surgical site surveillance with limited on-site clinical resources.
Academic Hospitals anchor premium product adoption; Ambulatory Surgical Centers are gaining share fastest on procedure migration.
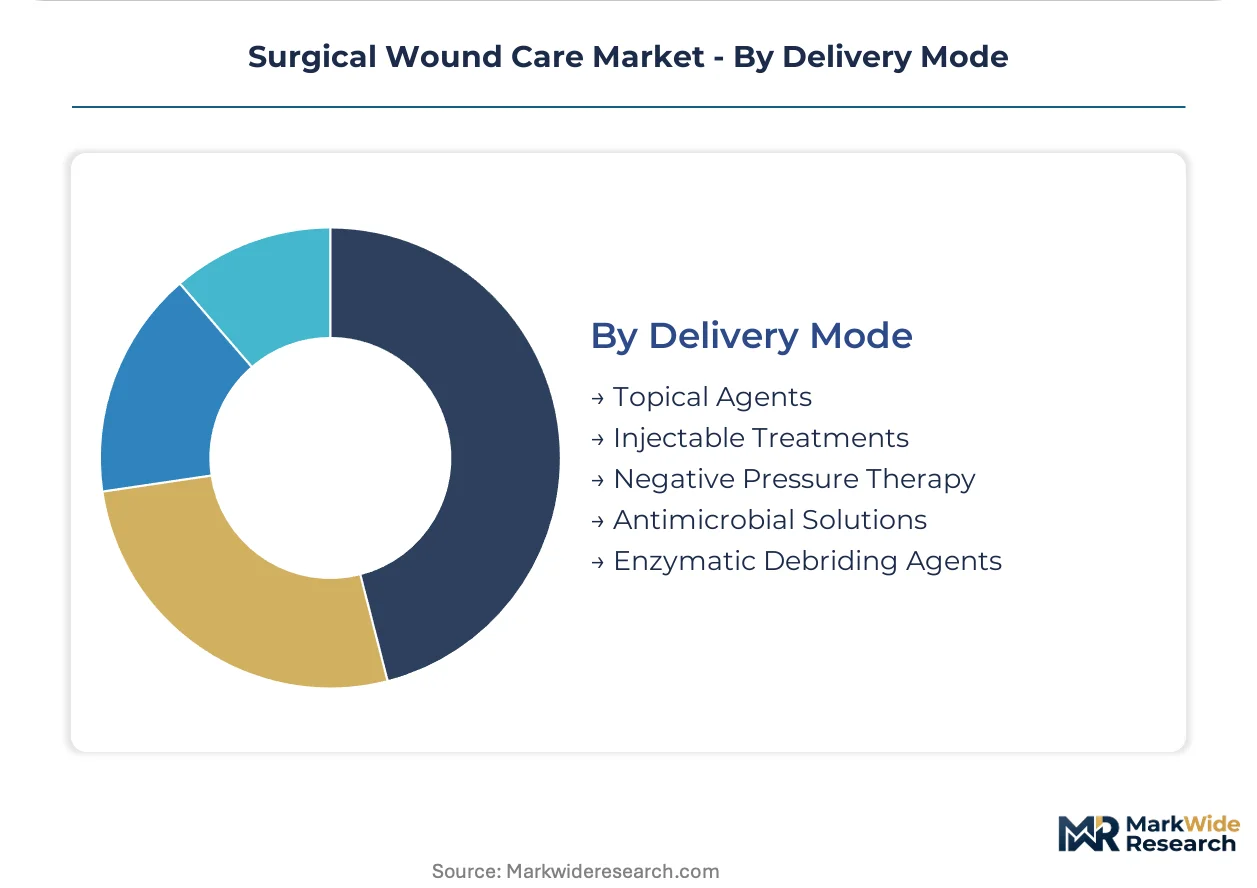
Delivery Mode:
Mechanism of action separates passive moisture management from active biological intervention, with regulatory pathway complexity scaling accordingly.
- Negative Pressure Therapy:Vacuum-assisted closure systems with portable pumps and disposable canisters. Denmark and Netherlands post-acute pilots are validating remote monitoring integration for surgical site surveillance.
- Antimicrobial Solutions:Topical or impregnated agents subject to EPA toxicology review for silver substitutes and iodine formulations.
- Topical Agents:Passive or semi-occlusive dressings applied directly to incision sites without mechanical assistance.
- Injectable Treatments:Subcutaneous hemostats and sealants delivered at wound closure.
- Enzymatic Debriding Agents:Collagenase-hydrogel combinations straddling drug-device regulatory boundaries.
Topical Agents dominate current utilization; Negative Pressure Therapy shows the steepest expansion trajectory on reimbursement framework extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane foam substrate production in northern China supplies lamination houses serving branded device makers across Germany and the United States. This feedstock geography shapes finished dressing cost structures and qualification timelines for transatlantic distribution.
United States
Freestanding ambulatory surgical centers in Texas and Florida are building dedicated supply chains for advanced closure systems that match hospital-grade performance. The FDA's streamlined 510(k) pathway for antimicrobial dressings is compressing predicate device referencing timelines. Post-acute pilots in Massachusetts and North Carolina are validating remote monitoring integration for surgical site surveillance.
Germany
Hospital consolidation across Bavaria and North Rhine-Westphalia is compressing vendor counts and centralizing purchasing authority through group procurement organizations. The EU Medical Device Regulation's phased enforcement is filtering out marginal suppliers and opening shelf space for certified incumbents. Mölnlycke Health Care leverages its Gothenburg manufacturing base to sustain just-in-time supply for Nordic hospital networks serving German clients.
China
Absorbent material producers in Zhejiang and Jiangsu provinces are repositioning capacity toward medical-grade foam substrates. The National Medical Products Administration is tightening biocompatibility documentation requirements for export-oriented manufacturers. Shanghai-based lamination specialists are qualifying European and North American device makers as anchor customers.
Denmark
Post-acute care facilities in Copenhagen and Aarhus are piloting smart dressing systems with printed sensors for moisture detection and temperature monitoring. The Danish Medicines Agency is aligning with EU MDR implementation timelines for notified body oversight. Odense-based distribution platforms are building cloud-based inventory management systems that bypass traditional medical-surgical distributor markups.
Netherlands
Academic medical centers in Amsterdam and Rotterdam are extending negative pressure wound therapy protocols into residential settings under expanded reimbursement frameworks. The Dutch Healthcare Authority is monitoring site-of-service payment differentials favoring hospital-at-home models. Eindhoven-region sensor technology clusters are supplying printed electronics for next-generation dressing connectivity.
Surgical Wound Care Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and just-in-time supply reliability. The market structure consolidates around diversified medical device conglomerates with established quality management systems, while specialized wound care divisions operate as portfolio anchors within larger health technology platforms. Three archetypes dominate: integrated delivery platform builders, negative pressure therapy specialists, and advanced dressing formulation houses. Competitive intensity centers on M&A-driven portfolio diversification and geographic expansion through distributor acquisition.
Among diversified health technology conglomerates, 3M and Johnson & Johnson Services occupy positions representing integrated material science and consumer health platform strategies. Baxter exemplifies the delivery system bundling archetype through integrated platforms combining dressings with irrigation solutions. Smith + Nephew anchors the negative pressure therapy specialization vector for post-operative site management. These three entities represent distinct competitive positioning frameworks rather than direct product overlap.
| Leading Market Players |
|---|
| 3M |
| Mölnlycke Health Care |
| Smith + Nephew |
| Johnson & Johnson Services |
| Baxter |
| Medtronic |
| Cardinal Health |
| ConvaTec Group |
| Coloplast |
| Others |
Pricing and Supply Chain Analysis
Formulation chemists with hydrogel crosslinking expertise command premium compensation in Germany and Japan, and this workforce concentration widens pricing spreads between antimicrobial dressing tiers and commodity gauze alternatives. Labor-cost differentials between European specialty chemical houses and Chinese substrate producers feed directly into three-tier pricing stratification across premium certified, standard medical-grade, and economy unbranded channels.
Pricing Analysis
Warranty and infection-rate guarantee bundling separates premium antimicrobial dressings from unbundled commodity alternatives in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU MDR and FDA 510(k) pathways alongside volume scale commitments from consolidated German hospital networks. Cost compression in the economy tier is intensifying because Chinese foam substrate producers are repositioning capacity toward medical-grade specifications. Ambulatory surgical centers in the United States exhibit the highest price sensitivity, while academic medical centers in Germany show the least due to outcome-based contracting mandates.
Supply Chain Analysis
Dual-sourcing requirements from German group purchasing organizations and U.S. hospital systems mandate multi-supplier qualification for medical-grade polyurethane foam and acrylic pressure-sensitive adhesives. Supply concentrates in China for foam substrates, Germany for specialty adhesives, and Sweden for just-in-time finished dressing logistics. Raw material dependencies rest on propylene oxide, toluene diisocyanate, and naphtha-cracker outputs vulnerable to European energy cost volatility. Single-source vulnerability in Japanese and German adhesive houses creates qualification bottlenecks. Distribution runs through group procurement organizations in Germany and specialized medical-surgical distributors in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR compliance deadlines filter out marginal suppliers lacking established quality management systems. The regulatory burden is forcing weaker formulation houses and regional distributors toward exit or acquisition.
For Market Incumbents: Deepen backward integration into medical-grade foam substrate production to offset Chinese supply volatility and petrochemical feedstock exposure. Expand in-house ISO 10993 biocompatibility testing capabilities to circumvent 14-18 month laboratory queues freezing product iterations. Mölnlycke Health Care's Gothenburg just-in-time model offers a template for Nordic network replication.
For New Entrants and Emerging Players: Enter via enzymatic debridement convergence products straddling drug-device regulatory boundaries, where incumbent quality system requirements are less entrenched. Target ambulatory surgical centers in Texas and Florida building dedicated supply chains for advanced closure systems. Pursue direct-to-provider e-procurement partnerships with cloud-based inventory platforms bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized negative pressure therapy device makers given CMS hospital-at-home reimbursement expansion enabling rental and subscription revenue models. Long-term viability over the next decade hinges on real-world evidence generation capabilities tying device selection to surgical site infection outcomes. Watch for FDA antimicrobial dressing 510(k) clearance acceleration as an inflection signal favoring incumbents with extensive predicate device libraries.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Opens shelf space in German hospital networks filtering out non-compliant suppliers. |
| Hospital-at-Home Reimbursement Strategy | Captures CMS expanded coverage for negative pressure therapy in residential settings. |
| Smart Dressing Sensor Integration | Leverages Eindhoven-region printed electronics for remote surgical site surveillance. |
| Silver-Substitute Formulation Pipeline | Addresses EPA scrutiny of silver ion accumulation through iodine and PHMB alternatives. |
| Direct-to-Provider E-Procurement Platform | Bypasses traditional medical-surgical distributor markups via Odense-based cloud systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this surgical wound care market assessment. Primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and antimicrobial formulation chemists were cross-validated against FDA 510(k) databases, EU MDR notified body registers, and hospital procurement platform disclosures. Bottom-up unit demand modeling and top-down value aggregation were triangulated to constrain forecast variance.
Data-stream reconciliation across manufacturer shipment reports, distributor inventory turns, and end-user consumption patterns shaped the analytical framework. Segmentation dimensions modeled include product formulation tier, procedure type, facility accreditation status, and delivery mode complexity throughout the forecast period. CAGRs were derived from procedure volume trajectories, reimbursement code expansion rates, and technology substitution elasticities. Antimicrobial dressing MVTR specification evolution and negative pressure therapy portable pump adoption curves served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA antimicrobial agent regulatory shifts or naphtha-cracker margin collapses. Deviation in EU MDR enforcement timelines or FDA 510(k) pathway recalibration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.