
 Global Wound Irrigation System Market | 2026-2036
Global Wound Irrigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wound Irrigation System Market Foresight
Ambulatory surgery centers are unwinding the historical hospital-centric procurement model for wound irrigation equipment. Becton, Dickinson and Company leverages its distribution breadth to anchor hospital contracts across North American metropolitan clusters. Irrimax Corporation specializes in pulsatile delivery systems that compete on precision metrics against broader portfolio players.
Wound irrigation systems mechanically cleanse wound beds through pressurized fluid delivery, with pulsatile devices generating 1-15 psi pressure ranges to dislodge debris while preserving viable tissue. Saline irrigation dominates current procurement volumes due to formulary standardization, though battery-operated devices represent the fastest-growing deployment category as point-of-care mobility requirements intensify. Chronic wound care applications command premium positioning within reimbursement frameworks, while surgical wound management generates the highest absolute procedure volumes.
The FDA governs device classification and 510(k) clearance pathways for electromechanical irrigation systems in the United States, while the EU MDR imposes strengthened clinical evidence requirements for reusable equipment marketed across European member states. Japan's PMDA maintains distinct biological safety testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving battery safety standards and single-use material restrictions as these frameworks increasingly determine market access velocity and product redesign obligations.
Market Dynamics
Hospital procurement departments are consolidating purchasing authority into centralized supply chain offices, compressing vendor negotiation cycles and favoring multi-year equipment lease structures over capital acquisition models for wound irrigation platforms.
Growth Catalysts
- Same-day discharge protocols:United States, Germany, and Japan are scaling ambulatory surgical protocols that require portable irrigation systems at point-of-care sites outside traditional operating theaters.
- Battery-operated device category expansion:Point-of-care mobility requirements in emergency departments and field medical units are accelerating procurement of cordless pulsatile delivery systems.
- EU MDR clinical evidence pathways:Strengthened reusable equipment requirements are creating replacement demand for validated single-use alternatives across European member states.
Market Restraints
- Lithium-ion battery supply concentration:Raw material processing and cell manufacturing cluster in China, exposing device makers to export control volatility and forced supply redesigns.
- Saline solution input cost inflation:Pharmaceutical-grade sodium chloride and sterile water sourcing costs are compressing margins for disposable cartridge suppliers.
- Biological safety testing timelines:Japan's PMDA extended validation protocols for foreign manufacturers delay market entry by 12-18 months versus domestic registrants.
Strategic Opportunities
- India's surgical infrastructure buildout:Government hospital modernization programs and medical device PLI incentives create first-mover positioning for automated irrigation suppliers.
- Chronic wound home care transition:Reimbursement frameworks in Germany are expanding coverage for patient-operated low-pressure devices outside clinical settings.
- Antimicrobial solution convergence:Integration of povidone-iodine and hypochlorous acid delivery with mechanical irrigation opens premium positioning against saline-only systems.
Industry Challenges
- Cross-functional training deficits:Operating room staff must simultaneously manage electromechanical troubleshooting and sterile technique, stretching competency requirements.
- 510(k) premarket validation compression:FDA's tightened battery-operated device pathway demands expanded electrical safety and biocompatibility documentation, extending submission preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wound Irrigation System Market |
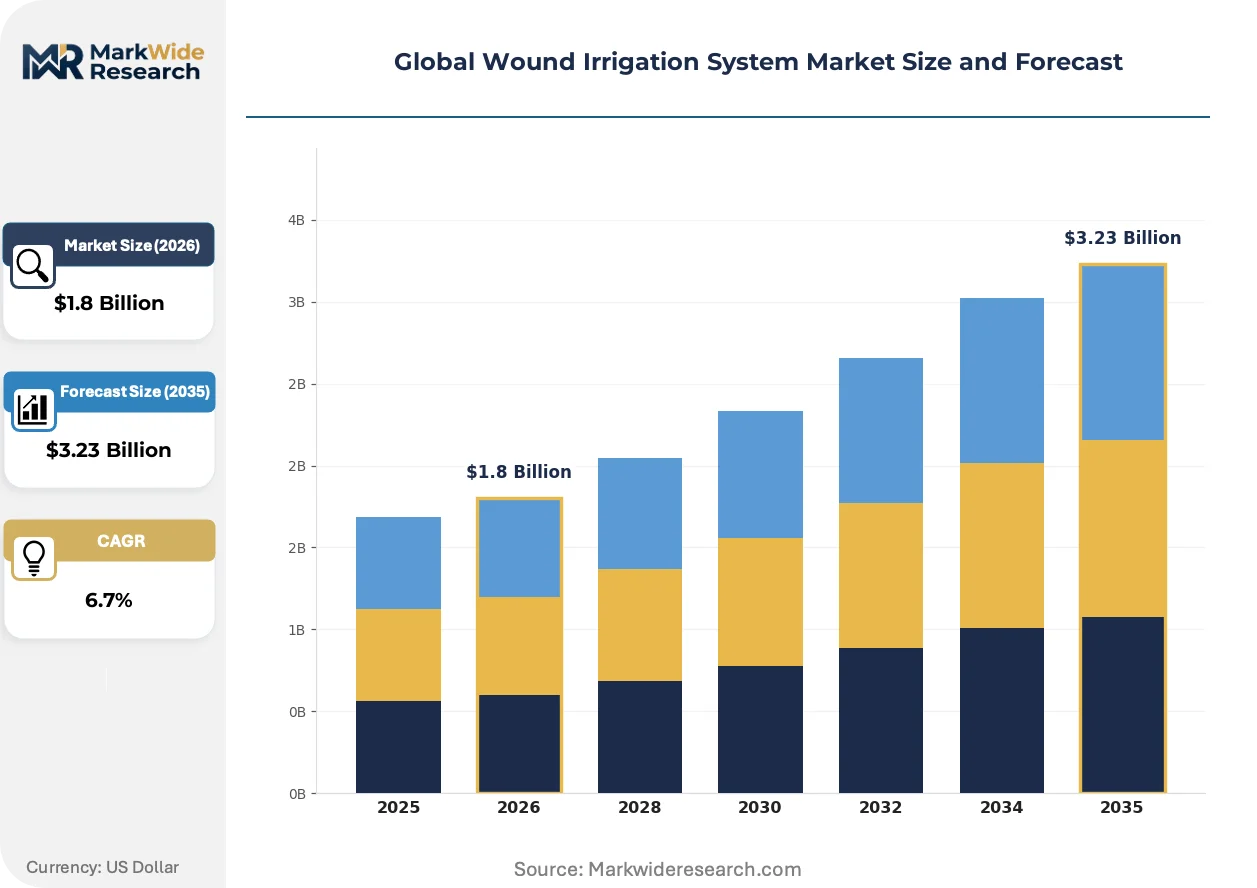
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saline Irrigation, Pulsatile Irrigation, Spray Irrigation, Continuous Flow Irrigation, Pressure Irrigation Application: Chronic Wound Care, Surgical Wound Management, Burn Treatment, Orthopedic Wound Cleansing, Trauma Wound Care End User Industry: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Home Healthcare, Long-term Care Facilities Deployment Type: Manual Systems, Battery Operated Devices, Corded Electric Systems, Single-use Devices, Reusable Equipment |
| Companies Covered | Smith & Nephew plc, CooperSurgical, Inc., Becton, Dickinson and Company, B. Braun Melsungen AG, Irrimax Corporation, Stryker Corporation, Medline Industries, LP, Mölnlycke Health Care AB, Zimmer Biomet Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wound Irrigation System Market Shifts & Advancements
Electromechanical delivery platforms are displacing gravity-fed and manual syringe methods across acute care settings, with software-enabled pressure modulation emerging as the primary vector for product differentiation and clinical outcome documentation.
Pulsatile pressure modulation technology is fragmenting the traditional wound cleansing category by enabling tissue-selective debris removal. Ambulatory surgery centers in the United States are adopting these systems at twice the rate of hospital outpatient departments. The technology is fragmenting vendor competitive sets by decoupling precision metrics from portfolio breadth, allowing specialized players to capture high-margin niches.
EU MDR strengthened clinical evidence requirements for reusable surgical equipment are forcing redesign cycles across European markets. Manufacturers must now generate post-market surveillance data and biological safety documentation previously exempt under MDD rules. Reusable pulsatile handpieces face the steepest compliance burden, accelerating single-use cartridge development.
Centralized procurement offices are consolidating vendor relationships and demanding outcome guarantees from irrigation equipment suppliers. Metropolitan hospital clusters in the United States are replacing unit-by-unit purchasing with system-wide service contracts that bundle devices, consumables, and maintenance. Germany's university hospital networks are pioneering this model, with purchasing cooperatives capturing volume discounts previously unavailable to individual facilities.
Global Wound Irrigation System Market Segmentation
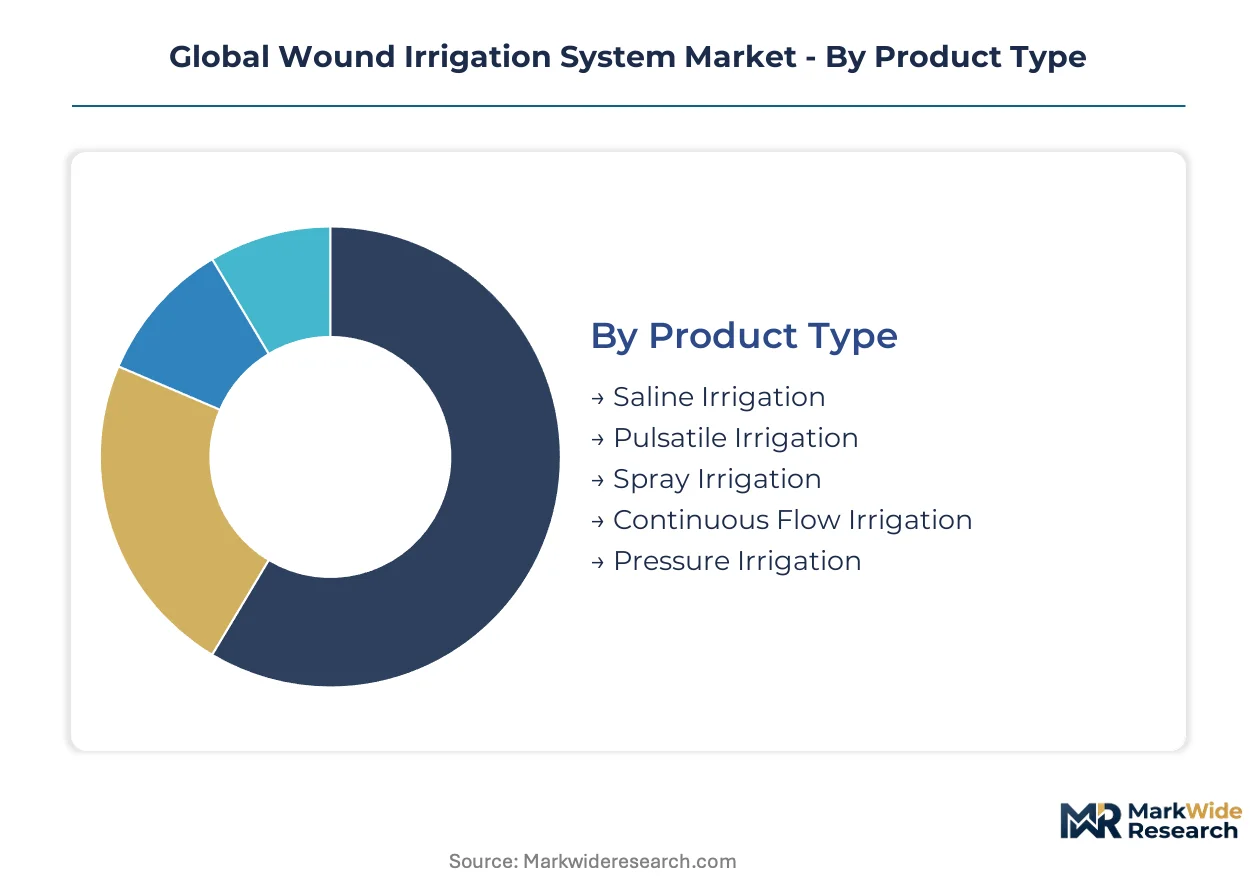
Segmentation in wound irrigation systems determines procurement pathways, reimbursement tiers, and regulatory clearance requirements. Product architecture and deployment modality shape whether systems flow through hospital supply chains, ambulatory surgery center group purchasing organizations, or direct-to-consumer channels.
Product Type:
Channel distribution varies sharply across product architectures, with saline-based systems dominating formulary contracts while pulsatile technologies penetrate through specialty surgical distributors.
- Saline Irrigation:Pharmaceutical-grade sodium chloride solutions constitute the procurement volume baseline across hospital formularies. Demand concentrates in United States metropolitan hospital clusters where formulary standardization and bulk purchasing agreements compress vendor margins.
- Pulsatile Irrigation:Pressure-modulated delivery systems generate 1-15 psi ranges for tissue-selective debris removal. Germany's university hospital networks are scaling these systems fastest, driven by same-day discharge protocols requiring precision wound bed preparation outside traditional operating theaters.
- Spray Irrigation:Low-pressure misting configurations serve burn treatment centers and delicate tissue applications.
- Continuous Flow Irrigation:Steady-stream delivery systems support orthopedic lavage procedures and deep wound cavity cleansing.
- Pressure Irrigation:High-pressure syringe and mechanical systems remain prevalent in emergency department settings for trauma debridement.
Saline Irrigation dominates installed base. Pulsatile Irrigation is where expansion concentrates.
Application:
Reimbursement intensity varies across clinical use cases, with chronic wound care commanding premium positioning while surgical wound management generates absolute procedure volume leadership.
- Surgical Wound Management:Perioperative irrigation protocols in operating theaters and ambulatory surgery centers drive the highest absolute device utilization. United States same-day discharge expansion is accelerating portable system deployment across freestanding surgical facilities.
- Chronic Wound Care:Diabetic foot ulcers, pressure injuries, and venous leg ulcers require extended treatment cycles with specialized low-pressure delivery. Germany's reimbursement frameworks are expanding coverage for patient-operated devices outside clinical settings, opening home care transition pathways.
- Burn Treatment:Specialized misting and cooling irrigation protocols serve thermal and chemical injury management.
- Orthopedic Wound Cleansing:Deep lavage requirements in joint and bone procedures favor high-volume continuous flow systems.
- Trauma Wound Care:Emergency department and field medical applications prioritize rapid deployment battery-operated platforms.
Surgical Wound Management captures procedure volume leadership. Chronic Wound Care is climbing the fastest on reimbursement expansion.
End User Industry:
Procurement authority consolidation is rewiring customer segmentation, with centralized supply chain offices replacing unit-level purchasing across metropolitan health systems.
- Hospitals:Inpatient surgical departments and wound care centers maintain the largest capital equipment budgets. Japan's extended PMDA validation timelines for foreign manufacturers create 12-18 month entry delays versus domestic registrants, favoring established supplier relationships.
- Ambulatory Surgery Centers:Freestanding surgical facilities in the United States are adopting pulsatile systems at twice the rate of hospital outpatient departments. Centralized procurement offices in metropolitan clusters are consolidating multi-year service contracts that bundle devices, consumables, and maintenance.
- Specialty Clinics:Wound care and burn centers operate on narrower device portfolios with higher utilization intensity.
- Home Healthcare:Patient-operated low-pressure systems are gaining reimbursement traction in German outpatient frameworks.
- Long-term Care Facilities:Pressure injury prevention protocols drive basic irrigation system deployment.
Hospitals retain capital equipment authority. Ambulatory Surgery Centers are gaining share fastest on procurement model innovation.
Deployment Type:
Power source and reusability architecture determine regulatory pathway complexity, with battery-operated devices facing tightened FDA 510(k) validation and single-use alternatives benefiting from EU MDR reusable equipment restrictions.
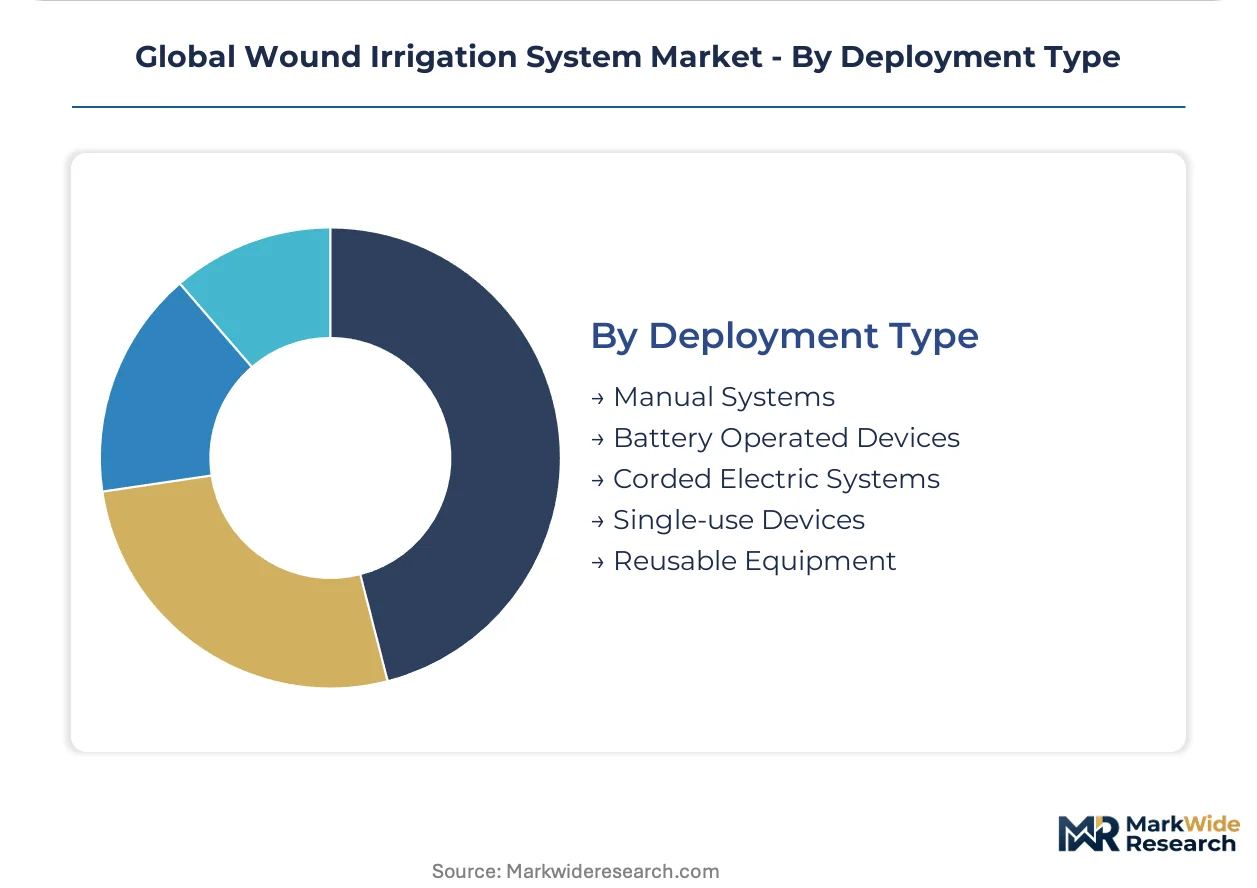
- Battery Operated Devices:Cordless pulsatile delivery systems address point-of-care mobility requirements in emergency departments and field medical units. FDA's updated 510(k) pathway demands expanded electrical safety and biocompatibility documentation, extending submission preparation cycles for new entrants.
- Single-use Devices:Disposable cartridges and handpieces circumvent EU MDR post-market surveillance burdens for reusable equipment. Strengthened clinical evidence requirements under European regulations are accelerating replacement demand for validated single-use alternatives.
- Manual Systems:Syringe and gravity-fed methods persist in cost-constrained settings and basic wound cleansing protocols.
- Corded Electric Systems:Tethered platforms retain operating theater preference for high-volume surgical irrigation.
- Reusable Equipment:Multi-cycle handpieces face steepest EU MDR compliance burdens, driving redesign toward disposable architectures.
Manual Systems dominate legacy installed base. Battery Operated Devices are gaining share fastest on mobility requirements and same-day discharge expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics hub underwrites Europe's wound irrigation supply chain reliability. Distribution networks radiate from this node to surgical centers across the continent.
United States
Same-day discharge protocols at ambulatory surgery centers are accelerating portable system procurement. The FDA's tightened 510(k) pathway for battery-operated devices extends validation timelines for new market entrants. Metropolitan hospital clusters in Chicago and Dallas-Fort Worth are consolidating multi-year service contracts that bundle devices with consumables.
Germany
University hospital networks are pioneering centralized procurement cooperatives that capture volume discounts. The EU MDR imposes strengthened clinical evidence requirements for reusable equipment, accelerating single-use cartridge adoption. The Rhine-Ruhr metropolitan region hosts the densest concentration of wound care technology distributors in Europe.
Japan
PMDA's extended biological safety testing protocols create 12-18 month registration delays for foreign manufacturers. Domestic registrants leverage these timelines to defend established supplier relationships. The Kanto region surrounding Tokyo concentrates surgical device procurement authority within integrated hospital networks.
India
Government hospital modernization programs and medical device PLI incentives are attracting automated irrigation suppliers. CDSCO regulatory harmonization efforts are streamlining import pathways for electromechanical platforms. Maharashtra's medical device manufacturing clusters in Pune and Mumbai are scaling contract fabrication capacity for international OEMs.
United Kingdom
NHS supply chain consolidation is compressing vendor negotiation cycles toward framework agreements. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines, creating parallel compliance obligations. The Greater Manchester health system is piloting outcome-based procurement models for surgical equipment.
Global Wound Irrigation System Market Competitive Landscape
Listed leaders compete with private specialists across distribution breadth and precision technology vectors. The vendor base separates into three tiers: diversified medical technology conglomerates, focused surgical device specialists, and regional contract manufacturers. Strategic archetypes include portfolio breadth players, precision delivery specialists, and private-label suppliers. Consolidation through multi-year hospital service contracts and geographic expansion into India's surgical infrastructure represent dominant competitive moves.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Stryker Corporation exemplify scale-driven positioning through distribution infrastructure. Irrimax Corporation occupies the precision specialist archetype, competing on pressure modulation metrics rather than portfolio breadth. Smith & Nephew plc anchors the wound care focused segment with historical strength in advanced surgical applications.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| CooperSurgical, Inc. |
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Irrimax Corporation |
| Stryker Corporation |
| Medline Industries, LP |
| Mölnlycke Health Care AB |
| Zimmer Biomet Holdings, Inc. |
| Others |
Supply & Pricing Matrix
Contract manufacturing scale in China's lithium-ion cell production clusters anchors cost floors for battery-operated wound irrigation platforms, concentrating supplier power among three dominant cell producers while compressing margins for device assemblers downstream. This scale concentration simultaneously enables volume-discount tiering for metropolitan hospital procurement offices and exposes OEMs to forced redesign cycles when export controls disrupt cathode precursor flows.
Pricing Analysis
Volume-discount tiering separates premium pulsatile systems with software-enabled pressure modulation from standard battery-operated devices and economy manual syringe alternatives. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance status and after-sales service bundling. Cost compression in the standard tier is intensifying because saline solution input inflation runs through disposable cartridge suppliers. Ambulatory surgery centers exhibit highest price sensitivity; chronic wound care clinics with reimbursement coverage show lowest.
Supply Chain Analysis
The Strait of Malacca transit corridor underwrites lithium carbonate flows from Australian hard-rock mines and Chilean brine operations to Chinese cell manufacturing hubs. Raw material processing draws from China, South Korea, and Japan for battery components; sterile saline production centers on United States and European pharmaceutical-grade facilities. Single-source vulnerability concentrates in Chinese cathode active material suppliers. Distribution runs through hospital group purchasing organizations and specialty surgical distributors to end-user facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wound irrigation market functions as a service-attach opportunity where multi-year equipment lease contracts with bundled consumable replenishment expand faster than standalone hardware transactions. Preventive maintenance subscriptions and software upgrade pathways now capture recurring revenue streams exceeding initial device margins.
For Market Incumbents: Consolidate procurement relationships through centralized supply chain office penetration in United States metropolitan hospital clusters. Lock in multi-year service contracts that bundle devices, saline cartridges, and preventive maintenance before emerging battery-technology entrants secure FDA 510(k) clearances. Vertical integration into lithium-ion cell sourcing mitigates raw material volatility exposure.
For New Entrants and Emerging Players: FDA's expanded access pathway for breakthrough device designation offers accelerated premarket review for antimicrobial solution integration platforms. Target India's government hospital modernization programs where CDSCO regulatory harmonization streamlines electromechanical platform import pathways. Pursue white-label manufacturing partnerships with Maharashtra-based contract fabricators to bypass capital-intensive production buildout.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision delivery specialists with software-enabled pressure modulation platforms and consumable cartridge attach rates. Five-to-ten year viability favors acquisition targets with validated single-use architectures positioned for EU MDR reusable equipment replacement demand. Monitor Japan's PMDA biological safety testing timeline compression as inflection signal for foreign manufacturer market entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance for battery-operated devices captures ambulatory surgery center procurement windows ahead of competitors. |
| Hospital System Partnership | Multi-year service contracts with metropolitan clusters bundle hardware, consumables, and maintenance into recurring revenue streams. |
| CE Marking Pathway Investment | MDR-compliant single-use cartridge validation unlocks European university hospital network procurement cooperatives. |
| Software Companion Development | Pressure modulation documentation platforms differentiate precision delivery systems in outcome-based reimbursement frameworks. |
| Reimbursement Strategy Alignment | German outpatient coverage expansion for patient-operated devices opens chronic wound home care transition revenue pools. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries. Clinical stakeholders including wound care specialists, biomedical engineers, and hospital purchasing committee chairs provided operational validation. GPO contracts managers and ambulatory surgery center administrators supplied procurement pathway intelligence. Bottom-up device shipment analysis triangulates against top-down reimbursement expenditure modeling.
Segmentation dimensions modeled span product architecture, application setting, end-user facility type, and deployment modality across the projection horizon. CAGRs derive from procedure volume elasticity against same-day discharge protocol expansion rates and battery-operated device substitution curves. Forecast inputs incorporate saline solution cost trajectories and lithium-ion cell supply concentration risk adjustments.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity or accelerated FDA review timeline compression would require recalibration. Practitioners should keep alternative scenarios live as Japan's PMDA foreign manufacturer validation protocols and India's PLI scheme incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Wound Measurement Devices Market
Wound Care
Italy Wound Care Market
Wound Care
Alginate Dressing Market
Wound Care
US Burn Care Centers Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Europe Wound Care Market
Wound Care
Europe Compression Bandages Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Asia Pacific Advanced Wound Care Market