
 Foot Ulcer Sensors Market | 2026-2036
Foot Ulcer Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Foot Ulcer Sensors Market Intelligence
The EU Medical Device Regulation (MDR) is repositioning compliance requirements for pressure-sensing insoles and smart bandages sold in European markets. Orpyx Medical Technologies leverages its proprietary SurroSense Rx platform to sustain clinical validation partnerships across wound care centers. Tekscan anchors its competitive stance through advanced tactile sensing arrays that dominate plantar pressure mapping applications.
Foot ulcer sensors comprise electromechanical and biochemical transducers engineered to detect localized pressure, temperature elevation, and tissue perfusion changes at wound sites, typically operating within 0.1°C thermal resolution and sub-millimeter pressure granularity to enable early intervention before tissue breakdown progresses. These devices serve primarily to reduce amputation incidence among diabetic populations by triggering clinical alerts prior to visible ulcer formation. Wearable sensors currently occupy the largest addressable segment due to patient compliance advantages and continuous data capture capabilities, while biochemical sensors represent the fastest-expanding technology category as enzymatic and pH-responsive materials mature for infection biomarker detection. Smart bandages concentrate margin pools through disposable consumable models that lock in recurring revenue streams.
The FDA's breakthrough devices program and the EU MDR's Class IIa classification requirements for active therapeutic monitoring devices are tightening clinical evidence standards for market authorization, directly shaping R&D investment priorities among developers. Health Canada's alignment with ISO 14155 clinical investigation protocols further standardizes trial design expectations for North American commercialization pathways. Stakeholders must weigh regulatory jurisdiction sequencing against reimbursement velocity when prioritizing geographic deployment of novel sensor modalities.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing commercialization timelines for diabetic foot ulcer sensor developers while simultaneously elevating clinical evidence requirements for premarket authorization. This regulatory acceleration is redistributing competitive advantage toward developers with established wound care center validation partnerships and robust ISO 14155-compliant trial infrastructure.
Growth Catalysts
- Medicare Remote Patient Monitoring Reimbursement:Expanded coverage for connected wound assessment tools in the United States is pulling hospital procurement departments toward continuous monitoring platforms. Hospital wound care departments now specify wireless data transmission as a mandatory procurement criterion.
- Enzymatic Biosensor Maturation:pH-responsive and infection-biomarker-detecting materials are unlocking biochemical sensor categories for early ulcer detection. Research institutions are prioritizing grant funding toward electrochemical transducer miniaturization.
- Amputation Prevention Mandates:Diabetic population health management programs are hardwiring sensor-based early intervention into standard-of-care protocols. Payers are attaching quality metrics to ulcer prevention outcomes.
Market Restraints
- EU MDR Class IIa Compliance Burden:Active therapeutic monitoring device classification is extending clinical investigation timelines and inflating regulatory submission costs for European market entry.
- Specialized MEMS Fabrication Concentration:Sub-millimeter pressure sensor foundry capacity clusters in East Asian contract manufacturers, creating supply vulnerability for Western developers.
- Silver-Zinc Battery Chemistry Constraints:Disposable smart bandage power sources face energy density limitations that restrict continuous monitoring duration below clinically optimal windows.
Strategic Opportunities
- Home-Based Care Transition:Post-acute settings and skilled nursing facilities are creating demand for patient-operated ulcer monitoring systems with simplified alert interfaces.
- FDA Breakthrough Device Parallel Review:Expedited access pathway is enabling simultaneous design validation and reimbursement coding negotiations for qualifying sensor platforms.
- AI-Enabled Predictive Analytics Integration:Machine learning classification of temperature and pressure pattern anomalies is converging with hardware sensor deployment to enable pre-ulcer clinical alerts.
Industry Challenges
- Biocompatibility Certification Complexity:ISO 10993 testing for prolonged skin contact materials is extending product development cycles by 12-18 months for novel adhesive formulations.
- Interoperability with EHR Systems:HL7 FHIR integration requirements are forcing sensor developers to allocate engineering resources toward health information exchange compatibility rather than core sensing innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot Ulcer Sensors Market |
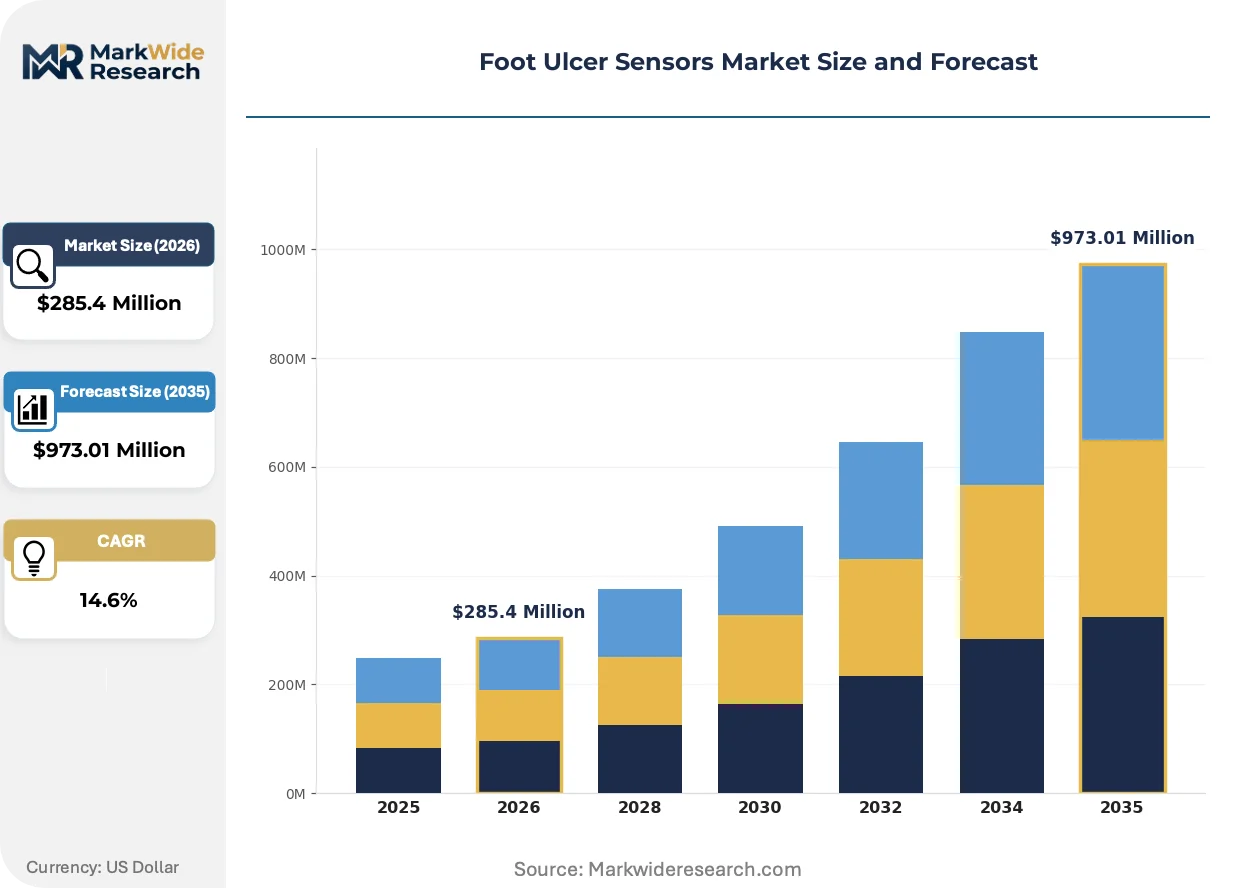
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $973.01 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Smart Bandages, Monitoring Devices, Imaging Systems Technology: Pressure Sensors, Thermal Sensors, Biochemical Sensors, Wireless Communication End User: Hospitals, Home Care, Clinics, Rehabilitation Centers Distribution Channel: Direct Sales, Online Retail, Distributors, Medical Supply Stores |
| Companies Covered | Digitsole, Orpyx Medical Technologies, Sensoria Health, Tekscan, XSENSOR, Moticon ReGo, Linepro Controls, PI Bioelectronics, Voxelcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot Ulcer Sensors Market Strategic Shifts & Innovations
Biochemical sensing modalities are displacing purely mechanical approaches in next-generation ulcer detection platforms. Material science advances in enzymatic transducers and conductive hydrogels are enabling continuous biomarker monitoring that electromechanical sensors cannot replicate.
Printed flexible electronics is expanding into conformable wound dressing substrates that maintain electrical continuity across irregular tissue surfaces. Academic medical centers in Germany and the Netherlands are piloting these platforms in multidisciplinary diabetic foot clinics. The technology is compressing the form factor gap between hospital-grade plantar pressure mapping systems and ambulatory patient wearables.
EU MDR's Class IIa classification for active therapeutic monitoring devices is tightening clinical evidence standards for smart bandage authorization. Manufacturers are redirecting R&D budgets toward prospective randomized trials rather than predicate device equivalency pathways. Small-to-mid-sized developers are responding through strategic partnerships with academic wound care centers to share trial infrastructure costs.
Hospital procurement departments are consolidating vendor relationships around full-stack monitoring platforms rather than point-solution sensors. Integrated data analytics and automated clinical workflow integration are displacing standalone hardware purchases in United States health system tender specifications. This concentration is most visible in Medicare Advantage network hospitals seeking remote patient monitoring bundled payment compliance.
Foot Ulcer Sensors Market Segmentation
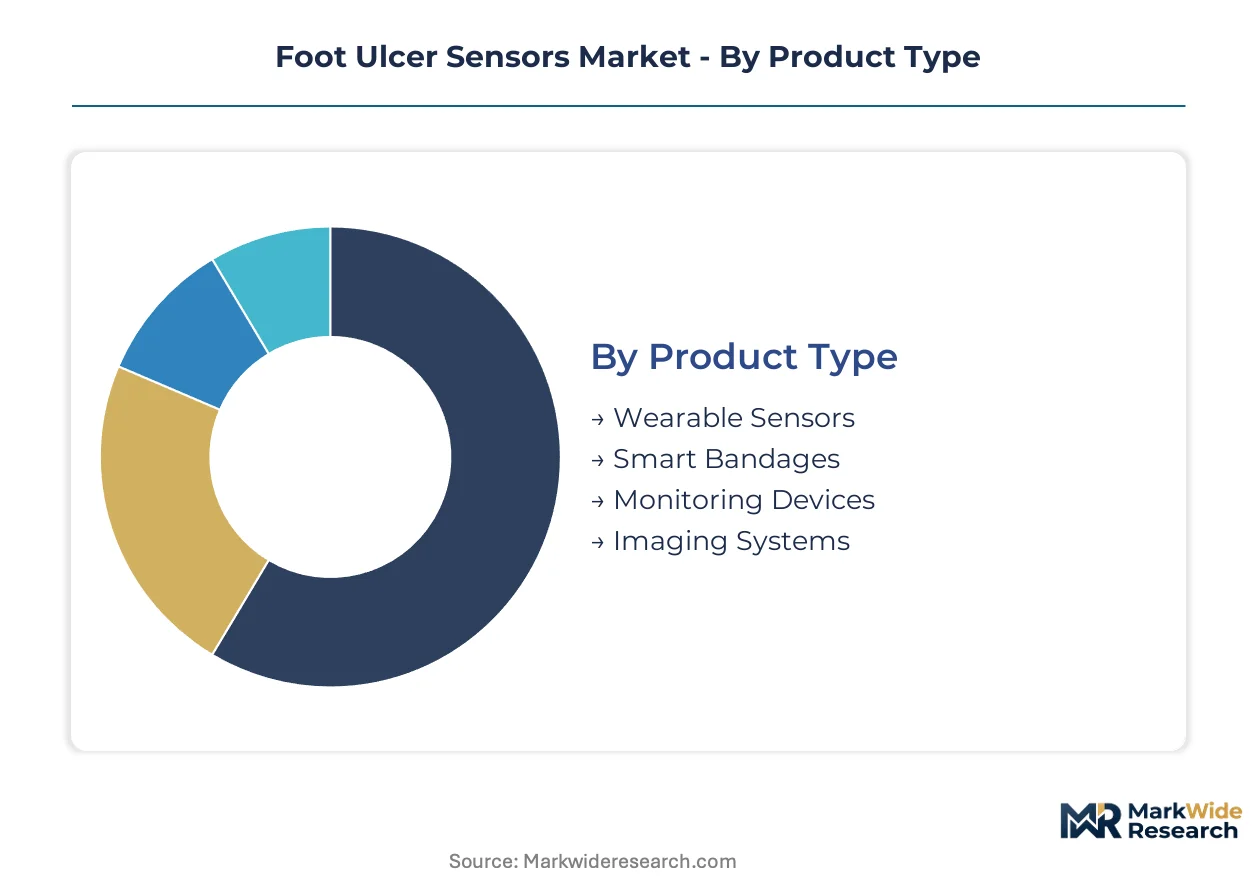
Foot ulcer sensor deployment varies sharply by integration depth. Standalone wearable units dominate ambulatory monitoring, while embedded biochemical transducers increasingly penetrate continuous wound assessment platforms.
Product Type:
Wearable sensors and smart bandages anchor opposite ends of the integration spectrum—discrete body-worn units versus conformable dressing-integrated systems.
- Wearable Sensors:Electromechanical transducers packaged as insoles, socks, or ankle straps detect plantar pressure and thermal gradients. Hospital wound care departments in the United States specify wireless data transmission as mandatory procurement criteria under expanded Medicare remote patient monitoring reimbursement.
- Smart Bandages:Disposable conformable substrates embed pH-responsive enzymatic biosensors and conductive hydrogels for biomarker detection. The FDA's breakthrough device designation pathway is compressing commercialization timelines for developers with robust ISO 14155-compliant trial infrastructure.
- Monitoring Devices:Bedside or chair-mounted systems aggregate multi-parameter data for clinical decision support.
- Imaging Systems:Optical and thermal imaging hardware captures wound surface morphology and perfusion patterns.
Wearable sensors lead volumes today; smart bandages are gaining share fastest.
Technology:
Cost stratification separates high-precision MEMS fabrication from emerging printed electronics approaches.
- Pressure Sensors:Sub-millimeter tactile sensing arrays fabricated through specialized MEMS processes enable plantar pressure mapping with granularity below clinical ulcer formation thresholds. Foundry capacity concentration in East Asian contract manufacturers creates supply vulnerability for Western developers.
- Thermal Sensors:Thermistor and infrared thermopile arrays operating within 0.1°C resolution detect localized inflammation preceding visible tissue breakdown. EU MDR Class IIa classification requirements are extending clinical investigation timelines for European market entry.
- Biochemical Sensors:Enzymatic and electrochemical transducers continuously monitor infection biomarkers.
- Wireless Communication:Bluetooth Low Energy and proprietary protocols transmit alerts to clinical workflow systems.
Pressure sensors lead volumes today; biochemical sensors are expanding most quickly.
End User:
Patient acuity and reimbursement velocity concentrate demand across institutional versus home-based settings.
- Hospitals:Acute care and wound care departments procure full-stack monitoring platforms with automated EHR integration through HL7 FHIR protocols. Health Canada's alignment with ISO 14155 clinical investigation protocols standardizes trial design expectations for North American commercialization.
- Home Care:Post-acute and skilled nursing facility demand is pulling toward patient-operated systems with simplified alert interfaces.
- Clinics:Outpatient diabetic foot clinics require portable diagnostic-grade sensing.
- Rehabilitation Centers:Long-term care facilities prioritize durability and staff training simplicity.
Hospitals lead volumes today; home care is climbing the fastest.
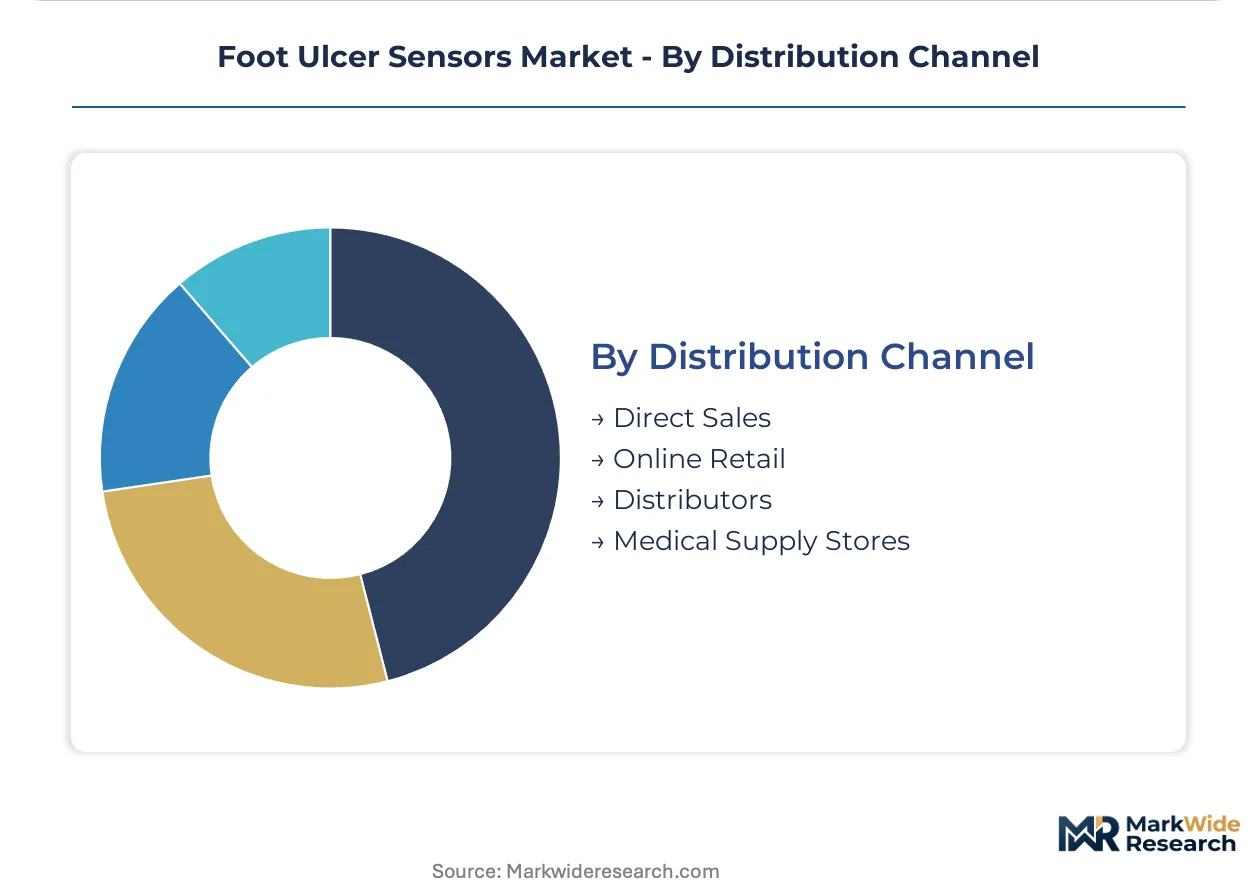
Distribution Channel:
Customer scale and procurement sophistication determine channel selection across health system tenders versus individual purchases.
- Direct Sales:Enterprise contracts with integrated data analytics and clinical workflow integration displace standalone hardware in United States health system specifications. Medicare Advantage network hospitals consolidate vendor relationships around remote patient monitoring bundled payment compliance.
- Online Retail:E-commerce platforms serve individual diabetic patients and small clinic practices with lower procurement thresholds.
- Distributors:Regional medical device distributors provide local inventory and technical support.
- Medical Supply Stores:Retail channels reach home care patients with limited digital procurement access.
Direct sales lead volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered continuous glucose monitoring and remote patient monitoring reimbursement frameworks that diabetic foot ulcer sensor developers now exploit. Early Medicare coverage decisions in wound care established the commercial template that European and Asian regulators later adapted.
United States
Medicare Advantage networks and hospital procurement departments specify wireless data transmission as mandatory criteria for connected wound assessment tools. The FDA's breakthrough device designation pathway compresses commercialization timelines while elevating clinical evidence standards. Boston and Minneapolis medical device clusters host validation partnerships between sensor developers and academic wound care centers.
Germany
Academic medical centers in Munich and Heidelberg pilot printed flexible electronics for conformable wound dressing substrates. The EU MDR Class IIa classification for active therapeutic monitoring devices tightens clinical evidence requirements for smart bandage authorization. Stuttgart's industrial electronics corridor supplies MEMS fabrication expertise to pressure-sensing insole manufacturers.
Netherlands
Eindhoven's high-tech systems ecosystem concentrates printed electronics and flexible sensor research institutions. Dutch diabetic foot clinics in Amsterdam and Rotterdam lead European adoption of ambulatory monitoring platforms. Health technology assessment bodies evaluate cost-effectiveness of continuous ulcer prevention against standard visual inspection protocols.
United Kingdom
NHS England's diabetic foot pathway quality metrics create procurement pull for sensor-based early intervention systems. London and Manchester wound care centers integrate pressure-mapping technologies into multidisciplinary clinic workflows. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device authorization with ISO 14155 clinical investigation standards.
Japan
Tokyo and Osaka medical device distributors prioritize miniaturized electromechanical transducers for aging diabetic populations. The PMDA's convergence with international harmonization standards accelerates market authorization for foreign sensor developers. Japanese electronics conglomerates supply thermistor and infrared thermopile components to Western wearable sensor manufacturers.
Foot Ulcer Sensors Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory validation depth and clinical partnership density. The vendor base stratifies between full-stack monitoring platform providers and discrete component specialists. Three archetypes dominate: MEMS fabrication-anchored pressure sensor developers, biochemical transducer specialists leveraging enzymatic materials science, and integrated data analytics platform operators. Competitive moves concentrate on strategic partnerships with academic wound care centers and ISO 14155-compliant trial infrastructure sharing.
Within the MEMS pressure sensing tier, Tekscan and XSENSOR occupy positions defined by tactile sensing array specialization. Orpyx Medical Technologies exemplifies the integrated platform archetype through sustained clinical validation partnerships. Digitsole and Sensoria Health represent wearable form factor innovators competing on patient compliance advantages.
| Leading Market Players |
|---|
| Digitsole |
| Orpyx Medical Technologies |
| Sensoria Health |
| Tekscan |
| XSENSOR |
| Moticon ReGo |
| Linepro Controls |
| PI Bioelectronics |
| Voxelcare |
| Others |
Cost & Logistics Intelligence
Silver spot price volatility cascades through disposable smart bandage manufacturing, compressing margins on zinc-silver battery chemistry while amplifying cost spreads between premium enzymatic biosensors and economy-grade electromechanical alternatives.
Pricing Analysis
Subscription-plus-consumable pricing stratifies across premium, standard, and economy tiers, with FDA breakthrough device certification and ISO 14155 trial infrastructure anchoring premium positioning. Price differentiation hinges on wireless data transmission capability and HL7 FHIR EHR integration depth. Cost compression in the standard tier intensifies as Medicare Advantage networks consolidate procurement around bundled remote patient monitoring contracts. Home care settings exhibit highest price sensitivity; hospital wound care departments prioritize clinical workflow integration over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for MEMS pressure sensor foundries mandate qualification of East Asian and European contract manufacturers simultaneously, though sub-millimeter tactile array capacity clusters in Taiwan, South Korea, and Japan. Raw material dependencies span silver-zinc battery chemistry, conductive hydrogel substrates, and enzymatic transducer reagents. Single-source vulnerability concentrates in specialized MEMS fabrication for sub-millimeter pressure granularity. Distribution runs through enterprise direct sales for hospital systems and regional medical device distributors for post-acute facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as hospital procurement departments mandate wireless data transmission and automated EHR integration, elevating late-cycle winners with validated clinical partnerships over commodity sensor vendors.
For Market Incumbents: Lock in exclusive validation partnerships with academic wound care centers in Boston and Minneapolis to preempt emerging biochemical sensor specialists from securing ISO 14155-compliant trial infrastructure. Deepen backward integration into MEMS fabrication through captive supply agreements with Taiwanese foundries, insulating against tariff exposure and capacity constraints that threaten standard-tier pricing power. For New Entrants and Emerging Players: Skilled nursing facilities represent the most penetrable buyer archetype, underserved by incumbent platforms optimized for acute care workflows. Target post-acute settings with simplified alert interfaces and patient-operated form factors. Pursue white-space positioning in enzymatic biosensor categories where pH-responsive materials science is displacing electromechanical approaches. For Investors and Strategic Acquirers: Asymmetric upside sits with biochemical transducer specialists possessing proprietary enzymatic materials IP and Health Canada-aligned trial infrastructure. Long-term viability favors developers with dual FDA-EU MDR regulatory pathways rather than single-jurisdiction plays. Watch for inflection in Medicare remote patient monitoring reimbursement velocity for infection-biomarker detection categories.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures procurement preference in Medicare Advantage networks specifying wireless data transmission mandates. |
| FDA Breakthrough Device Submission | Compresses commercialization timelines while elevating clinical evidence requirements for premarket authorization. |
| CE Marking Pathway under EU MDR | Enables European market entry for active therapeutic monitoring devices with Class IIa classification compliance. |
| Software Companion Development | Delivers AI-enabled predictive analytics integration for pre-ulcer clinical alerts via HL7 FHIR protocols. |
| Reimbursement Strategy | Aligns product positioning with Medicare remote patient monitoring coverage expansion for connected wound assessment. |
Research Approach
Coverage spans the United States, Germany, the Netherlands, the United Kingdom, and Japan, with primary inputs from each market combined with secondary validation. The research triangulates perspectives from wound care clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers against FDA filings, EU MDR authorization databases, CMS Medicare reimbursement data, and hospital procurement tenders. Bottom-up sensor shipment modeling and top-down healthcare expenditure allocation cross-validate market sizing across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by product type, technology, end user, and distribution channel, with additional dimensioning across reimbursement pathway and regulatory jurisdiction clusters. CAGRs derive from logistic growth curve fitting calibrated to Medicare remote patient monitoring adoption curves and diabetic population health management program penetration rates. Forecast inputs incorporate enzymatic biosensor maturation timelines and MEMS foundry capacity expansion trajectories.
Underlying measurement precision varies by segment; wearable sensors and smart bandages carry tighter precision than imaging systems due to denser primary data availability. Forecasts reflect assumptions on FDA breakthrough device pathway utilization rates and EU MDR Class IIa compliance timelines. Deviation in Medicare reimbursement coding decisions for infection-biomarker detection would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Transradial Closure Devices Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
North America C-Arms Market
Medical Devices
Water Flosser Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Global Bowel Management System Market
Medical Devices
Japan Hemostats Market
Medical Devices
Asia-Pacific Viscosupplementation Market