
 Compound Potassium Hydrogen Phosphate Injection Market | 2026-2036
Compound Potassium Hydrogen Phosphate Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Potassium Hydrogen Phosphate Injection Market Insights
Automated aseptic filling and closed-system transfer technology is reshaping how compound potassium hydrogen phosphate injection products are manufactured and delivered to end users. Shanxi PUDE Pharmaceutical leverages vertical integration across raw material synthesis to finished sterile dosage forms. Merck KGaA anchors quality positioning through its European pharmacopoeia-grade excipient supply chain. Tianjin Kingyork Pharmaceuticals competes on manufacturing scale within China's northern pharmaceutical cluster.
Compound potassium hydrogen phosphate injection is a sterile parenteral solution containing dibasic potassium phosphate and monobasic potassium phosphate, typically buffered to a physiological pH range of 7.4 to 7.6 for intravenous electrolyte replenishment. The formulation serves as a critical phosphate source in patients with hypophosphatemia, particularly in post-operative, diabetic ketoacidosis, and refeeding syndrome protocols where oral supplementation is contraindicated. Vials dominate current hospital procurement due to established cold-chain compatibility and lower per-unit cost structures, though pre-filled syringes are gaining traction in emergency medicine and home healthcare settings where dosing precision and reduced preparation time command premium positioning. Therapy area segmentation shows hypophosphatemia management as the mature revenue base, while metabolic conditions including renal failure-associated phosphate dysregulation represent the fastest-growing application cluster.
China's NMPA enforces updated GB standards for sterile injectable phosphate products, while the US FDA maintains current Good Manufacturing Practice oversight through its Center for Drug Evaluation and Research. India's CDSCO has tightened import licensing requirements for parenteral electrolyte formulations, reshaping market access pathways for multinational suppliers. Stakeholders must monitor evolving pharmacopoeial harmonization between USP, EP, and ChP monographs for phosphate injection specifications, as divergence in assay limits and bacterial endotoxin thresholds could fragment regulatory compliance costs across manufacturing footprints.
Market Dynamics
Hospital consolidation and centralized pharmacy procurement are compressing supplier margins while elevating sterility assurance requirements, forcing manufacturers to automate aseptic filling lines and absorb validation costs that smaller compounders cannot shoulder.
Growth Catalysts
- Post-surgical hypophosphatemia protocols:Elective surgery volume recovery in tertiary hospitals is expanding parenteral phosphate utilization in pre-operative optimization pathways. CDSCO's streamlined approval for critical care electrolytes is accelerating product registration timelines for qualified applicants.
- Closed-system transfer devices:USP Chapter 800 compliance mandates for hazardous drug handling are driving adoption of needle-free closed vial transfer systems in oncology-adjacent pharmacy operations. This hardware pull-through elevates bundled contract values for compliant injection formats.
- Refeeding syndrome management:ICU nutrition support protocols are integrating phosphate replacement earlier in parenteral nutrition initiation, particularly in diabetic ketoacidosis and severe malnutrition cases where oral supplementation remains contraindicated.
Market Restraints
- Phosphoric acid feedstock volatility:Technical-grade phosphate rock supply concentrates in Moroccan and Chinese state-controlled mining operations, exposing formulation costs to export quota fluctuations and energy-linked price spikes.
- Single-source API dependency:GMP-grade dibasic potassium phosphate API production clusters in three Chinese provinces, creating geographic concentration risk that hospital procurement officers must mitigate through dual-source qualification requirements.
- Endotoxin testing capacity:Limulus amebocyte lysate reagent supply constraints are extending batch release timelines for sterile injectable manufacturers, compressing inventory turns and working capital efficiency.
Strategic Opportunities
- Home infusion expansion:Medicare reimbursement adjustments for home-based electrolyte replacement are opening patient discharge pathways previously restricted to inpatient administration, requiring pre-filled syringe formats with extended stability data.
- Pharmacopoeial harmonization:Convergence between USP, EP and ChP monographs for phosphate injection assay limits would reduce multi-region registration costs and enable centralized manufacturing for multinational suppliers.
- Emergency medicine pre-positioning:Mass casualty and disaster response stockpiling programs are creating demand for ambient-stable, unit-dose presentations suitable for forward deployment without cold chain infrastructure.
Industry Challenges
- Aseptic processing workforce:Qualified personnel shortages in isolator operation and environmental monitoring are extending facility startup timelines and elevating labor costs for sterile injectable manufacturers.
- Legacy system integration:Automated filling line upgrades must interface with existing serialization infrastructure and warehouse management systems, creating validation complexity and downtime risk during technology transitions.
- Stability protocol harmonization:Divergent ICH zone requirements between registration jurisdictions force redundant long-term studies, accelerating R&D expenditure without commensurate market access benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Potassium Hydrogen Phosphate Injection Market |
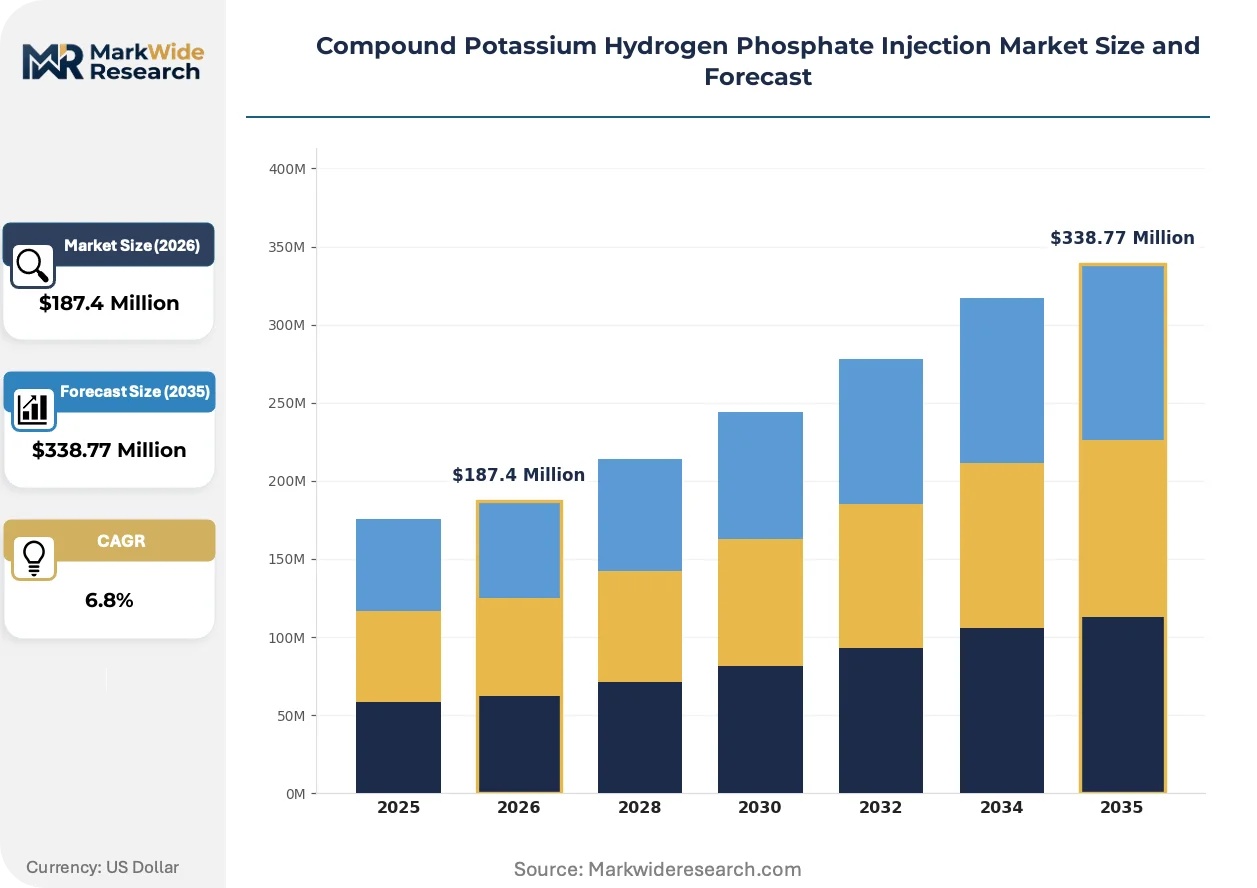
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Vials, Ampoules, Multi-Dose Containers Therapy Area: Hypophosphatemia, Bone Disorders, Metabolic Conditions, Neurological Disorders End User: Hospitals, Clinics, Home Healthcare, Pharmacies Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral |
| Companies Covered | Shanxi PUDE Pharmaceutical, Tianjin Kingyork Pharmaceuticals, Jilin Huakang Pharmaceutical, Hainan Herui Pharmaceutical, Anhui Healstar Pharmaceutical, Chengdu Leer Pharmaceutical, Suzhou Tianma Pharma Group, Haifa Group, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Potassium Hydrogen Phosphate Injection Market Trends and Innovations
Digital batch records and real-time release testing are compressing quality control cycles while regulatory agencies demand deeper process analytical technology integration for sterile injectable manufacturing.
Isolator-based robotic filling is virtualizing human intervention in aseptic processing. Hospital pharmacy buyers are specifying closed isolator technology for high-volume electrolyte contracts to minimize contamination risk documentation. This automation is virtualizing the traditional cleanroom operator role and compressing facility footprint requirements for new manufacturing sites.
China's NMPA has intensified sterility and pyrogen testing mandates for injectable phosphate formulations under updated GB standards. Manufacturers must now submit enhanced container closure integrity data and accelerated stability protocols. Domestic suppliers in Shanxi and Tianjin are responding by consolidating testing capabilities within vertically integrated quality centers.
Hospital group purchasing organizations are unbundling electrolyte contracts from broad parenteral nutrition bundles, enabling direct negotiation for phosphate-specific volume commitments. This disintermediation of traditional distribution is most visible in China's provincial centralized procurement platforms and US IDN consolidated service centers, where unit-price transparency is displacing rebate-driven contracting structures.
Compound Potassium Hydrogen Phosphate Injection Market Segmentation
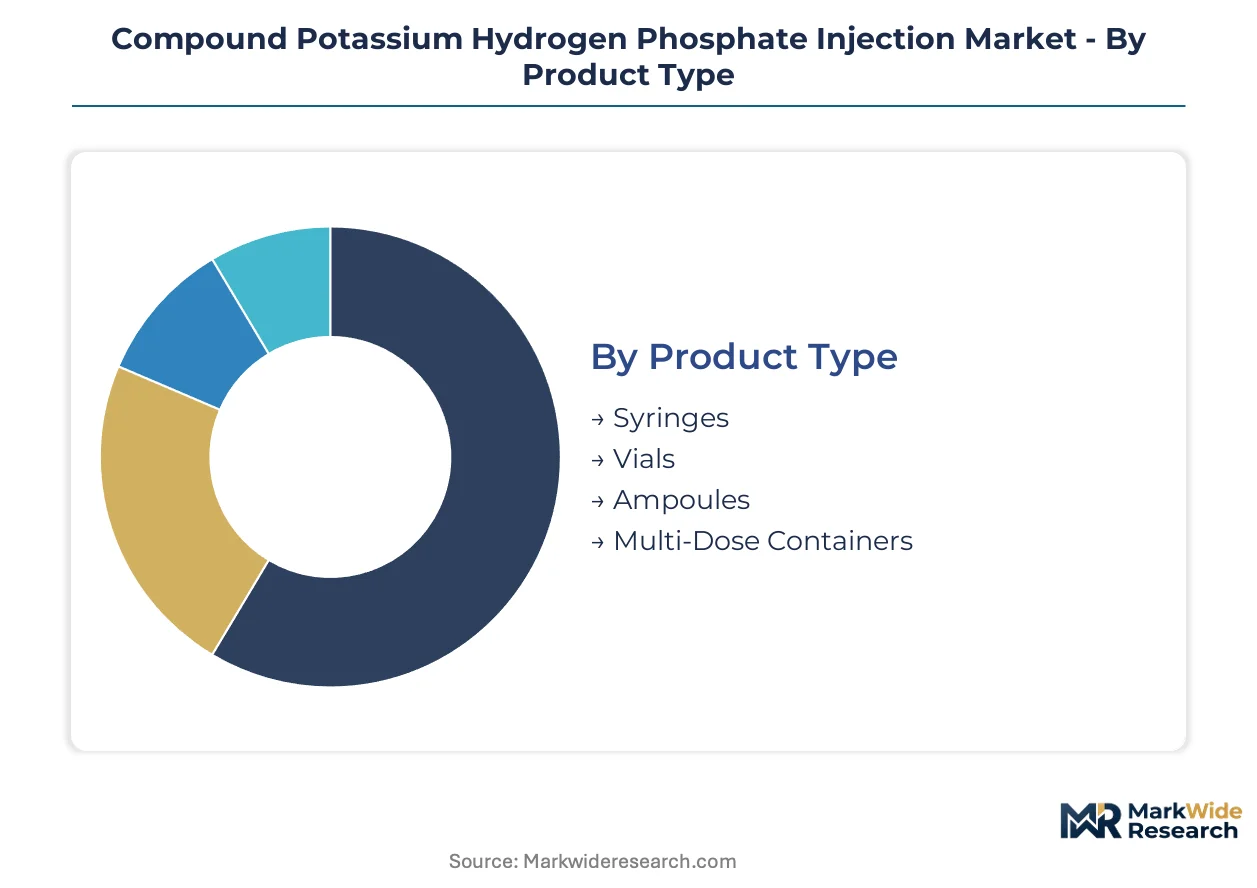
Segmentation in the compound potassium hydrogen phosphate injection market reflects divergent clinical workflows and procurement economics. Hospital pharmacy buyers prioritize sterility assurance and cold-chain compatibility, while home healthcare channels demand stability and ease of administration.
Product Type:
Cost tier differentiation across container formats shapes procurement volume allocation and margin capture for sterile injectable manufacturers.
- Vials:Glass or polymer containers typically ranging from 10mL to 50mL capacity, sealed with rubber stoppers and aluminum crimp seals for multi-dose withdrawal. Hospital centralized pharmacy operations in China and the United States concentrate procurement here due to established cold-chain infrastructure and lower per-unit acquisition costs, though preparation time and contamination risk elevate total cost of ownership.
- Syringes:Pre-filled, single-use presentations with integrated needles or luer-lock connectors, terminally sterilized and packaged for immediate administration. Emergency medicine departments and home healthcare settings in India are rotating toward this format as closed-system transfer device compatibility reduces compounding labor and dosing error liability.
- Ampoules:Single-dose glass containers with scored necks for snap-open access, offering minimal headspace and reduced oxidation exposure. Tertiary hospital networks in China's northern pharmaceutical cluster specify ampoules for high-acuity electrolyte replacement where precise unit dosing overrides preparation convenience.
- Multi-Dose Containers:Larger-volume vials or bags with antimicrobial preservatives enabling multiple withdrawals over 24-48 hours. Dialysis centers and extended-care facilities leverage these for recurrent phosphate replacement in chronic hypophosphatemia management.
Vials hold installed capacity across tertiary hospital networks. Syringes are rotating up the share rankings in emergency and ambulatory channels.
Therapy Area:
Application severity and reimbursement intensity determine which clinical indications drive volume and which expand most quickly.
- Hypophosphatemia:Acute phosphate depletion states requiring rapid intravenous correction, including post-operative recovery, diabetic ketoacidosis, and alcohol withdrawal protocols. Surgical and intensive care units in the United States anchor demand here as electrolyte management protocols tighten monitoring thresholds and replacement triggers.
- Metabolic Conditions:Renal failure-associated phosphate dysregulation, refeeding syndrome, and parenteral nutrition-induced electrolyte shifts. ICU nutrition support protocols in China are climbing the fastest as early phosphate replacement integration expands addressable patient populations beyond traditional hypophosphatemia boundaries.
- Bone Disorders:Osteomalacia, rickets, and chronic kidney disease-mineral and bone disorder (CKD-MBD) requiring sustained phosphate repletion. Nephrology and endocrinology clinics in India manage these cases predominantly through oral supplementation, constraining injectable penetration.
- Neurological Disorders:Seizure management in severe hypophosphatemia and phosphate-dependent encephalopathy. Neurological ICUs represent niche utilization given the rarity of primary neurological indications for parenteral phosphate.
Hypophosphatemia management holds installed capacity in surgical protocols. Metabolic conditions are climbing the fastest as ICU nutrition pathways evolve.
End User:
Customer type concentration reflects care setting economics and regulatory oversight intensity for sterile injectable administration.
- Hospitals:Tertiary care centers, community hospitals, and surgical facilities with centralized pharmacy compounding capabilities. China's provincial centralized procurement platforms and US integrated delivery networks concentrate volume here, leveraging group purchasing organization leverage to compress supplier margins while elevating sterility documentation requirements.
- Home Healthcare:Infusion therapy providers and visiting nurse services managing post-discharge electrolyte replacement. Medicare reimbursement adjustments in the United States are gaining share fastest as patient discharge pathways expand beyond inpatient administration, though pre-filled syringe stability data requirements constrain supplier qualification.
- Clinics:Ambulatory surgical centers, dialysis facilities, and specialty infusion centers. India's CDSCO streamlined approval pathways for critical care electrolytes are expanding clinic access, though infrastructure investment lags hospital channels.
- Pharmacies:Hospital outpatient, retail, and specialty pharmacy dispensaries. Compounding pharmacies face USP Chapter 800 compliance burdens for hazardous drug handling that limit participation in sterile phosphate distribution.
Hospitals hold installed capacity across procurement platforms. Home healthcare is climbing the fastest as reimbursement and discharge protocols shift.
Delivery Mode:
Route of administration determines formulation pH, osmolality specifications, and clinical supervision requirements.
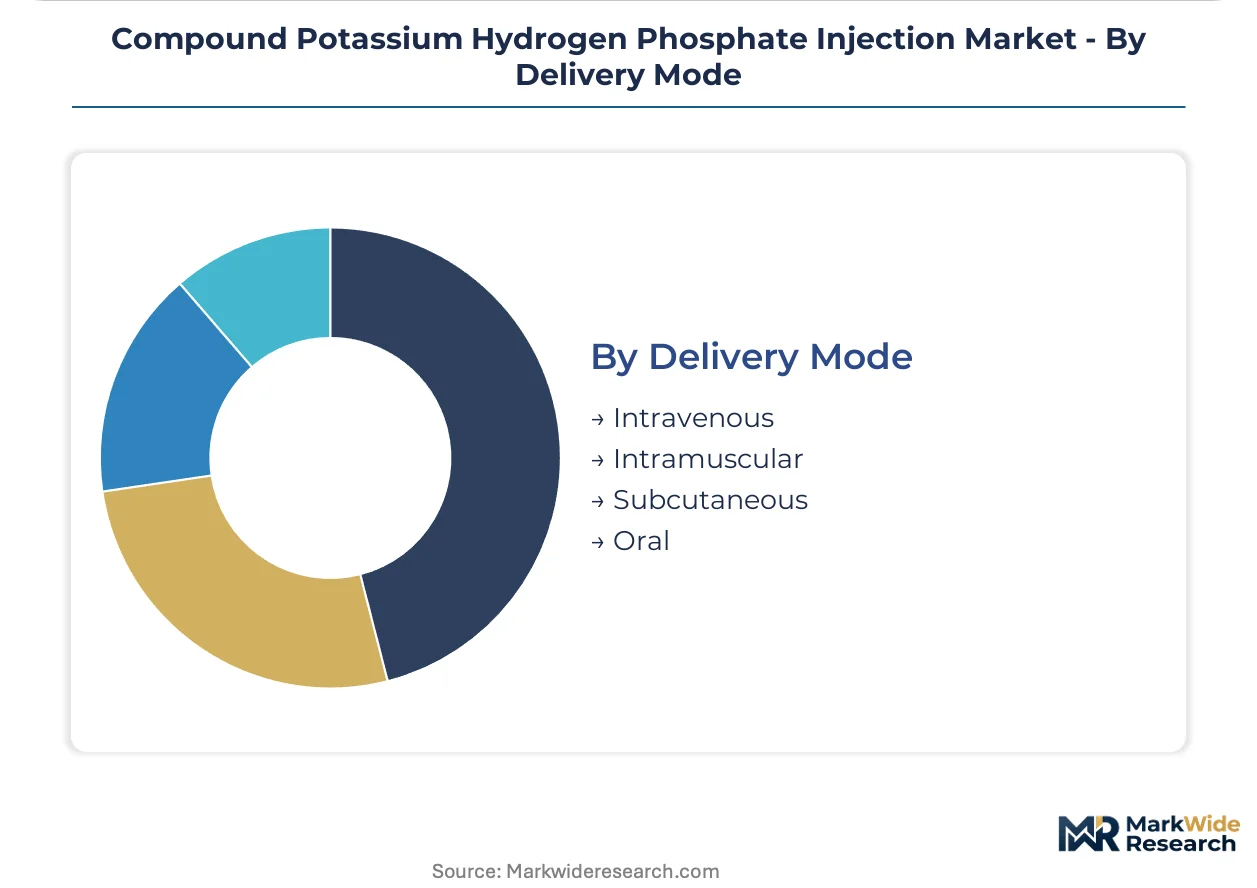
- Intravenous:Direct infusion into peripheral or central venous lines, requiring buffered pH 7.4-7.6 and isotonic osmolality to minimize phlebitis. Hospital infusion centers in China, India, and the United States concentrate utilization here as the standard of care for acute hypophosphatemia correction.
- Intramuscular:Depot injection into skeletal muscle for sustained phosphate release, typically reserved for patients without venous access. Emergency field medicine and mass casualty stockpiling programs are climbing the fastest as ambient-stable unit-dose presentations suit forward deployment without cold chain infrastructure.
- Subcutaneous:Infusion into subcutaneous tissue via butterfly needles or infusion sets, enabling home administration with reduced supervision. Home healthcare protocols in the United States are expanding utilization as patient training programs mature.
- Oral:Not a parenteral formulation but included as comparator for mild hypophosphatemia where gastrointestinal absorption remains viable. Oral supplementation constrains injectable market expansion in chronic management settings.
Intravenous delivery holds installed capacity across acute care protocols. Intramuscular administration is climbing the fastest as emergency preparedness programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital pharmacy buyers in China, India, and the United States concentrate procurement volume for parenteral phosphate replacement therapies. Tertiary care networks in these markets drive sterility documentation requirements and cold-chain infrastructure investment.
China
Provincial centralized procurement platforms in Shanxi and Tianjin absorb the majority of domestic manufacturing output. NMPA enforces updated GB standards for sterile injectable phosphate products, mandating enhanced container closure integrity submissions. The northern pharmaceutical cluster around Tianjin anchors capacity expansion for multi-dose vial formats serving tertiary hospital networks.
United States
Integrated delivery networks and group purchasing organizations compress supplier margins while elevating USP Chapter 800 compliance requirements for closed-system transfer devices. FDA oversight through the Center for Drug Evaluation and Research maintains current Good Manufacturing Practice standards for sterile injectable registration. The Northeast Corridor and California hospital systems drive pre-filled syringe adoption in emergency medicine settings.
India
CDSCO streamlined approval pathways for critical care electrolytes accelerate product registration for qualified applicants entering surgical and intensive care channels. Import licensing requirements for parenteral electrolyte formulations have tightened, reshaping market access for multinational suppliers. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate domestic API production and finished dosage form capacity.
Germany
EMA pharmacopoeia-grade excipient standards anchor quality positioning for European hospital procurement of parenteral phosphate therapies. The Bavaria and Baden-Württemberg regions host sterile injectable manufacturing infrastructure serving centralized pharmacy operations across the continent. German hospital networks specify isolator-based aseptic processing for high-volume electrolyte contracts.
Japan
PMDA oversight of sterile injectable manufacturing maintains stringent bacterial endotoxin thresholds for hospital pharmacy procurement. The Kanto region around Tokyo concentrates demand from tertiary care centers managing post-surgical hypophosphatemia protocols. Japanese hospital buyers prioritize pre-filled syringe formats with extended stability data for emergency medicine stockpiling.
Compound Potassium Hydrogen Phosphate Injection Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement platforms. Hospital group purchasing organizations and provincial centralized procurement systems fragment supplier relationships while compressing unit-price transparency. Three archetypes dominate: vertically integrated domestic manufacturers with raw material synthesis capabilities, European pharmacopoeia-grade excipient suppliers, and scale-driven regional formulators. Competitive moves center on automated aseptic filling line upgrades and dual-source API qualification to mitigate geographic concentration risk.
Among China-based pharmaceutical manufacturers, Shanxi PUDE Pharmaceutical, Tianjin Kingyork Pharmaceuticals, and Jilin Huakang Pharmaceutical occupy positions within the domestic supply base. Shanxi PUDE exemplifies the vertically integrated archetype spanning raw material synthesis to finished sterile dosage forms. Tianjin Kingyork sits within the northern pharmaceutical cluster competing on manufacturing scale. Jilin Huakang represents regional formulators serving provincial procurement platforms. Merck KGaA anchors the European pharmacopoeia-grade excipient tier for quality-positioned hospital contracts.
| Leading Market Players |
|---|
| Shanxi PUDE Pharmaceutical |
| Tianjin Kingyork Pharmaceuticals |
| Jilin Huakang Pharmaceutical |
| Hainan Herui Pharmaceutical |
| Anhui Healstar Pharmaceutical |
| Chengdu Leer Pharmaceutical |
| Suzhou Tianma Pharma Group |
| Haifa Group |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's freight volatility transmits directly into landed cost spreads for GMP-grade phosphate salts, amplifying price differentiation between European pharmacopoeia-certified suppliers and standard-grade Asian manufacturers while hospital procurement officers arbitrage quality tiers against total cost of ownership.
Pricing Analysis
Cost-plus contracts indexed to Moroccan phosphate rock export quotas dominate long-term hospital supply agreements, with European pharmacopoeia-grade excipient suppliers commanding premium positioning against standard-grade Chinese manufacturers. Price differentiation rests on FDA versus NMPA certification tiers and closed-system transfer device compatibility. Cost compression in standard-grade vials is intensifying because provincial centralized procurement platforms in China unbundle electrolyte contracts from parenteral nutrition bundles. Home healthcare channels show least price sensitivity due to Medicare reimbursement adjustments for pre-filled syringe formats.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for multinational pharmaceutical manufacturers. GMP-grade dibasic potassium phosphate API production clusters in Shanxi, Tianjin, and Jilin provinces, drawing from technical-grade phosphate rock concentrated in Moroccan and Chinese state-controlled mining operations. Single-source vulnerability in Limulus amebocyte lysate reagent supply extends batch release timelines. Distribution runs through hospital group purchasing organizations in the United States and provincial centralized procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement platforms creates white-space opportunities as hospital pharmacy buyers disintermediate traditional distribution and demand product-specific volume commitments rather than bundled contracts.
For Market Incumbents: Build regulatory moats through dual-source API qualification across Shanxi and Tianjin manufacturing clusters to mitigate geographic concentration risk. Automate aseptic filling lines with isolator-based robotic systems to absorb validation costs that smaller compounders cannot shoulder. Secure closed-system transfer device compatibility certifications ahead of USP Chapter 800 enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in home healthcare infusion therapy by developing pre-filled syringe formats with extended stability data for Medicare reimbursement pathways. Target ambulatory surgical centers in India's Maharashtra and Gujarat corridors where CDSCO streamlined approvals reduce registration barriers. Lead with closed isolator technology documentation to differentiate from legacy cleanroom operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated domestic manufacturers with captive API synthesis capabilities over pure-play formulators exposed to phosphate rock feedstock volatility. Five-to-ten year viability hinges on pharmacopoeial harmonization convergence between USP, EP, and ChP monographs. Monitor NMPA sterility mandate enforcement intensity as inflection indicator for quality-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Aseptic Filling Line Upgrade | Isolator-based robotic systems reduce contamination risk documentation for hospital GPO contracts. |
| Dual-Source API Qualification | Geographic diversification across Shanxi and Tianjin mitigates single-source concentration risk. |
| Closed-System Transfer Device Certification | USP Chapter 800 compliance elevates bundled contract values in oncology-adjacent pharmacy operations. |
| Pre-Filled Syringe Stability Extension | Medicare reimbursement adjustments for home-based electrolyte replacement open patient discharge pathways. |
| Pharmacopoeial Harmonization Lobbying | Convergence between USP, EP, and ChP monographs reduces multi-region registration costs for multinational suppliers. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, sterile manufacturing plant managers, GPO contract negotiators, and regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 483 inspection observations, NMPA drug master file submissions, CDSCO import licensing records, and hospital procurement database extracts. Bottom-up volume modeling triangulated against top-down electrolyte utilization rates in surgical and intensive care protocols.
Scenario-bracketing around phosphate rock export quota volatility and endotoxin testing capacity constraints bounded the forecast range across the analysis window. Segmentation dimensions modeled include container format, therapy area severity, end-user channel, and delivery mode. CAGRs derived from hospital admission trend extrapolation, surgical volume recovery patterns, and ICU nutrition protocol adoption curves. Industry-specific inputs incorporated parenteral phosphate replacement trigger thresholds and closed-system transfer device penetration assumptions.
Sensitivities concentrate around Moroccan phosphate rock export policy shifts, NMPA sterility mandate enforcement intensity, and Medicare reimbursement adjustment timing for home infusion. Forecasts reflect documented assumptions regarding surgical volume trajectories and pharmacopoeial harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Europe Meglitinide Market