
 Wound Care Biologics Market | 2026-2036
Wound Care Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Care Biologics Market Analysis
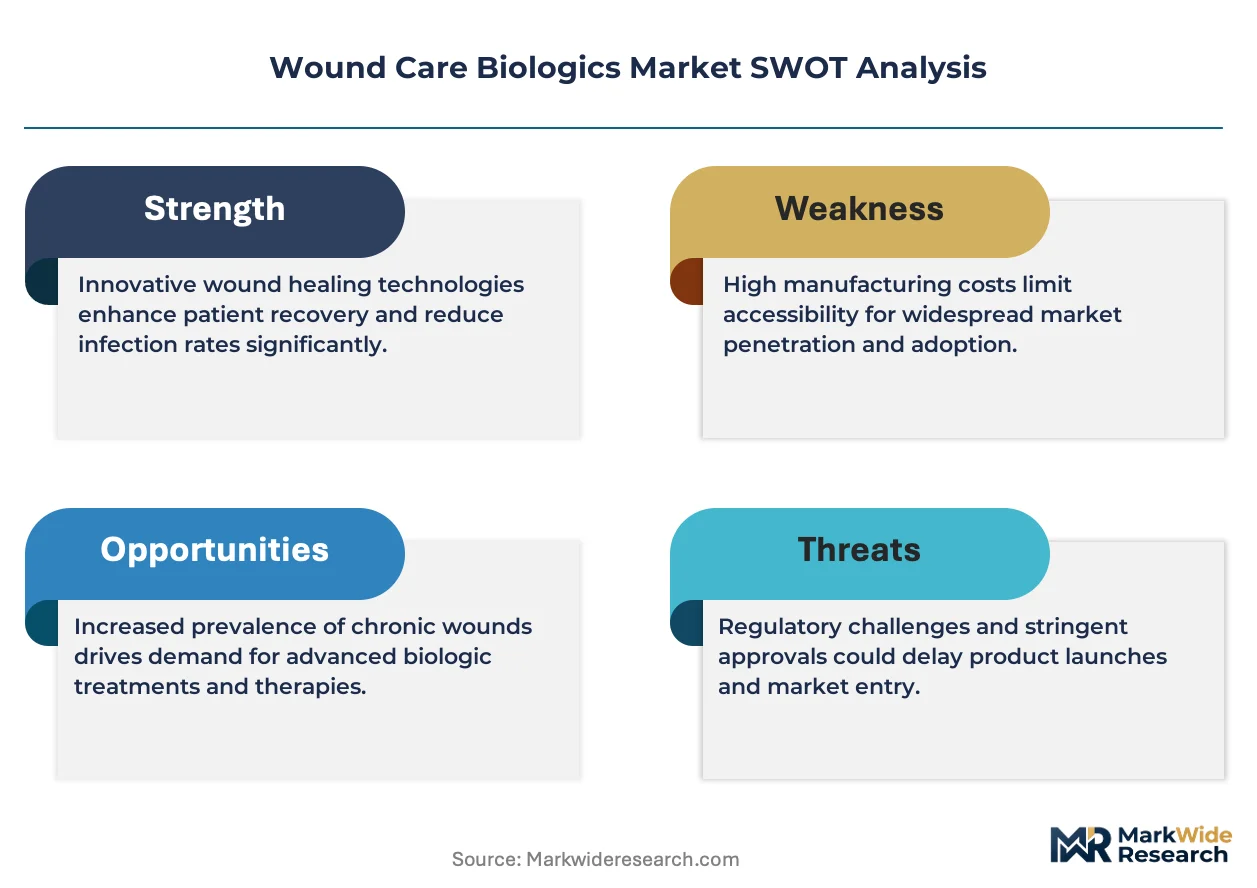
ISO 13485 certification is rotating the competitive set toward manufacturers with validated quality management systems for active biologic devices. Integra LifeSciences leverages its regenerative tissue portfolio to sustain leadership in dermal regeneration matrices. Smith & Nephew anchors its position through broad hospital contracting and advanced wound management infrastructure across North America and Europe. Mölnlycke Health Care differentiates via direct channel control and specialized burn care distribution networks.
Wound care biologics comprise engineered living tissues, extracellular matrix derivatives, and signaling proteins applied to dermal lesions to accelerate closure and reduce scar formation. These products typically require cryopreserved or lyophilized storage between minus eighty degrees Celsius and controlled room temperature to maintain cellular viability and structural integrity. Skin substitutes command the largest revenue pool given their use in limb-salvage protocols, while growth factors represent the fastest-expanding category as point-of-care activation methods improve. Chronic wounds generate disproportionate margin capture due to extended treatment cycles and recurring product consumption.
FDA premarket approval pathways and EMA's Advanced Therapy Medicinal Products framework govern clinical evidence requirements for biologic wound products entering their respective jurisdictions. The EU Medical Device Regulation and FDA's 21 CFR Part 1271 human cells, tissues, and cellular and tissue-based products rules impose manufacturing and traceability standards that elevate compliance costs for smaller developers. Stakeholders must monitor evolving reimbursement determinations from CMS and national health technology assessment bodies, as coverage decisions for bioengineered skin substitutes will determine which product formats achieve scalable clinical adoption.
Market Dynamics
CMS reimbursement tightening around amputation prevention is accelerating hospital procurement of bioengineered skin substitutes for diabetic foot ulcers, compressing clinical decision timelines and elevating product performance standards.
Growth Catalysts
- 21 CFR Part 1271 framework:FDA's human cells and tissue-based product rules create compliance clarity that accelerates IND-to-commercial pathways for dermal matrix developers.
- Integrated wound care center networks:United States-based specialty clinics concentrate patient volume and standardize biologic protocols, amplifying product pull-through velocity.
- Lyophilized storage advances:Ambient-stable growth factor formulations eliminate cold-chain dependency, expanding point-of-care deployment in outpatient settings.
Market Restraints
- Donor tissue supply volatility:Allograft raw material availability fluctuates with cadaveric donation rates and tissue bank processing capacity constraints.
- EMA Advanced Therapy Medicinal Products complexity:European developers face extended clinical evidence requirements that stretch regulatory timelines and capital consumption.
- Synthetic matrix substitution:Collagen-based scaffolds from non-biological sources capture price-sensitive cases in burn care and partial-thickness wounds.
Strategic Opportunities
- Rural United States access gaps:Telemedicine-integrated wound care delivery models enable remote specialist consultation paired with shipped cryopreserved biologics.
- Veterans Affairs procurement centralization:Federal integrated service networks offer sole-source contracting pathways for limb-salvage biologics meeting DFU protocol specifications.
- 3D bioprinting convergence:Patient-specific dermal constructs combining autologous cells with extracellular matrix deposition systems address chronic wound heterogeneity.
Industry Challenges
- ISO 13485 certification timelines:Active biologic device QMS validation requires 18-24 month implementation cycles that delay market entry for emerging manufacturers.
- Cell viability monitoring:Real-time quality assurance for cryopreserved products demands specialized logistics partnerships and temperature excursion protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Care Biologics Market |
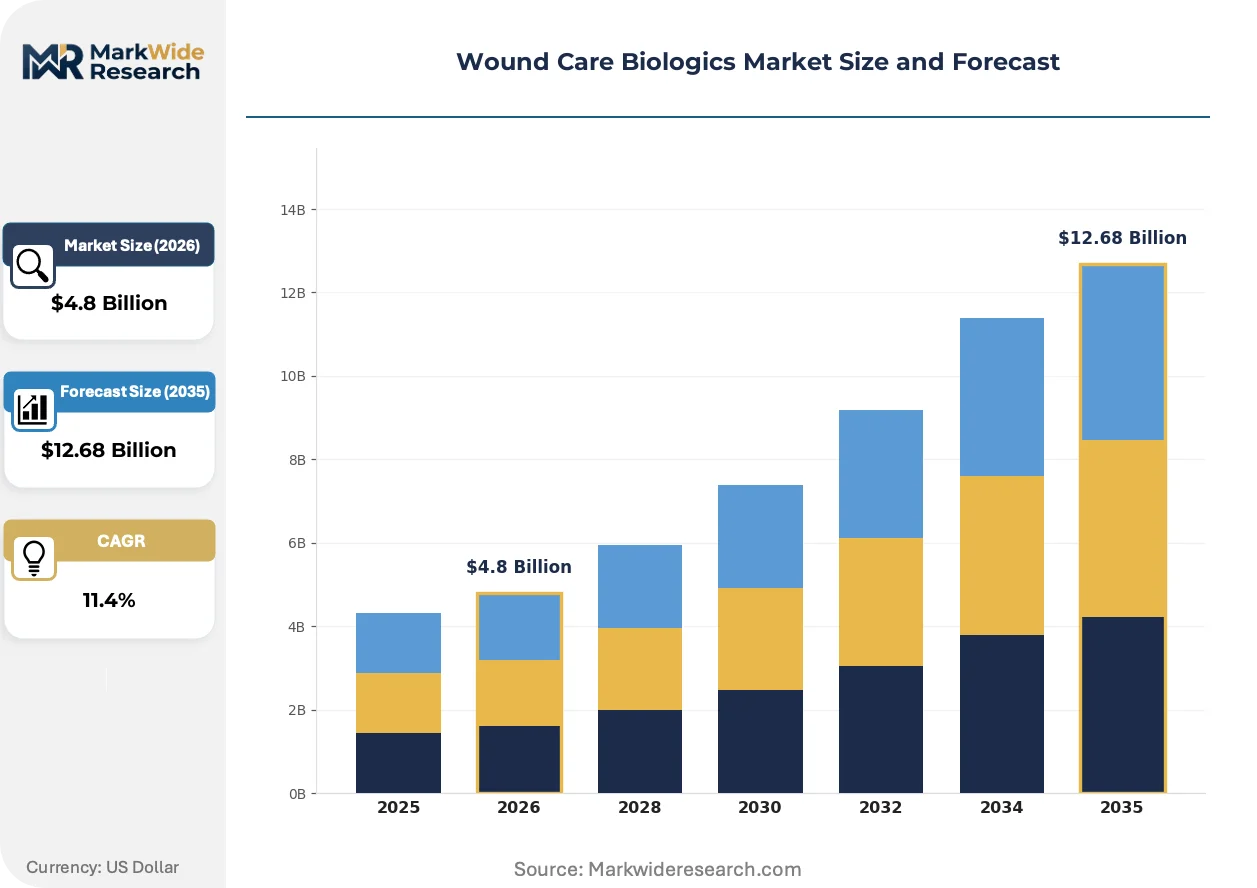
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Hyaluronic Acid, Skin Substitutes, Growth Factors Application: Chronic Wounds, Surgical Wounds, Burn Care, Traumatic Injuries End User: Hospitals, Home Healthcare, Ambulatory Surgical Centers, Specialty Clinics Delivery Mode: Topical, Injectable, Implanted, Transdermal |
| Companies Covered | ConvaTec Group, Kerecis, Integra LifeSciences, Stryker, Bioventus, MiMedx, Mölnlycke Health Care, Organogenesis, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Care Biologics Market Emerging Trajectories
Manufacturing automation and regulatory science advances are compressing development cycles while elevating product complexity thresholds for commercial viability in advanced wound management.
Point-of-care activated growth factor delivery systems are supplanting pre-mixed biologic formulations in outpatient wound centers. Ambulatory care facilities adopt these on-demand preparation platforms to reduce waste from expired multi-dose vials. The shift is compressing inventory carrying costs and enabling procedure-specific dosing that matches chronic wound heterogeneity.
EU Medical Device Regulation recasts bioengineered skin substitutes as Class III devices with enhanced clinical evidence requirements. Manufacturers must generate post-market surveillance data and maintain technical documentation accessible to notified bodies. The framework elevates compliance investment for matrix products entering German, French, and Italian hospital procurement channels.
Accountable care organizations consolidate wound care purchasing through specialty distributor arrangements that bundle biologics with negative pressure therapy and debridement services. These consolidated procurement models displace fragmented product-by-product ordering across individual hospital departments. The concentration is most visible in Medicare Advantage networks across the United States where total cost of care contracts incentivize limb-salvage outcomes over amputation.
Wound Care Biologics Market Segmentation
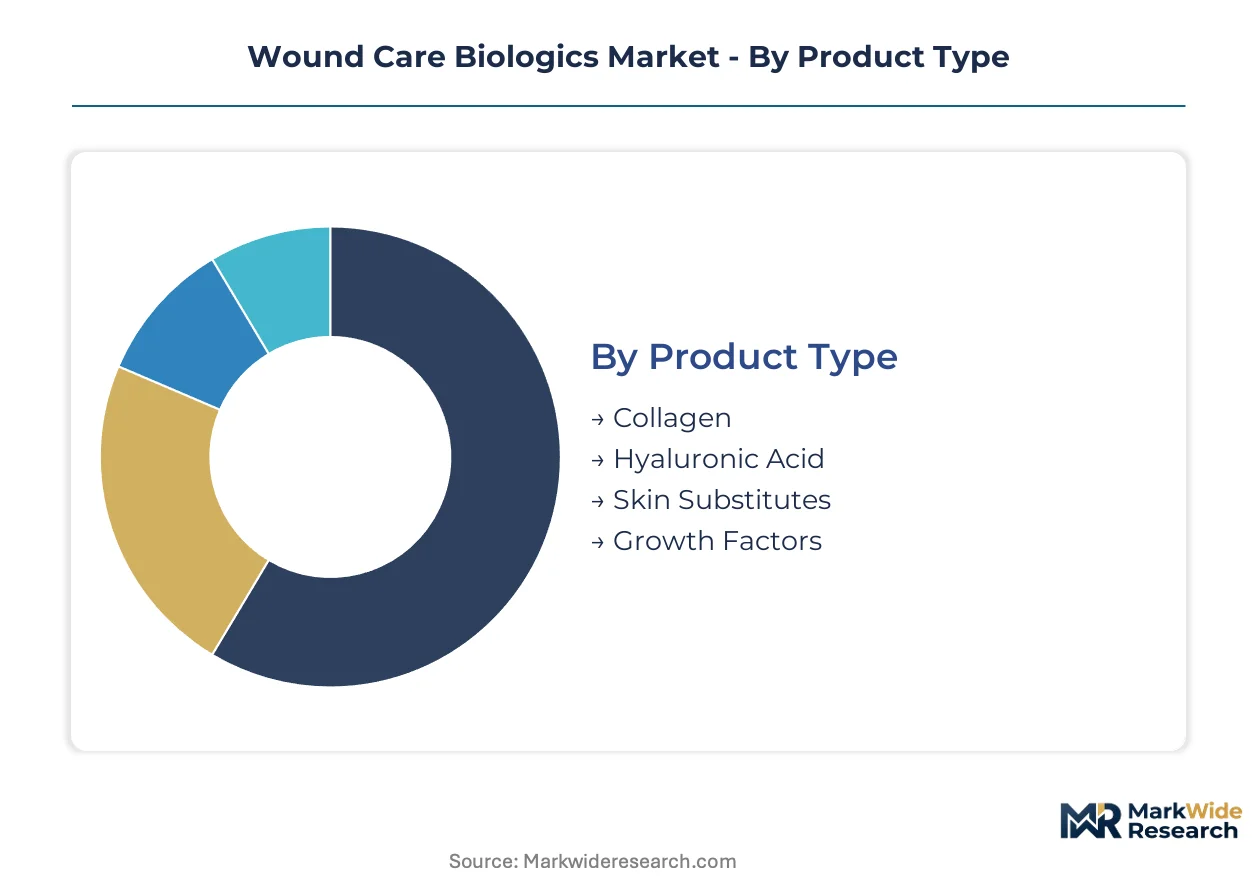
Wound care biologics segmentation reveals distinct regulatory pathways, storage requirements, and reimbursement codes that shape manufacturer portfolio decisions. Product format determines whether FDA 21 CFR Part 1271 or EMA Advanced Therapy Medicinal Products frameworks apply, directly influencing commercialization timelines and capital requirements.
Product Type:
FDA and EMA classification schemes diverge most sharply across this dimension, with matrix-based products facing device-like controls while cellular therapies trigger drug-biologic hybrid pathways.
- Skin Substitutes:Engineered living tissues and acellular dermal matrices derived from human or xenogeneic sources. Hospital limb-salvage protocols for diabetic foot ulcers in the United States concentrate procurement volume here, driven by CMS reimbursement tightening around amputation prevention.
- Growth Factors:Recombinant signaling proteins such as PDGF and EGF formulations that accelerate granulation tissue formation. Outpatient wound centers in Medicare Advantage networks are expanding point-of-care activation systems for these products, eliminating cold-chain dependency through lyophilized storage advances.
- Collagen:Structural scaffold materials from bovine, porcine, or marine sources that support cellular infiltration and revascularization.
- Hyaluronic Acid:Glycosaminoglycan-based hydrogels that modulate inflammatory response and maintain moist wound environments.
Skin substitutes handle the majority of throughput; growth factors are expanding most quickly on share as ambulatory activation platforms mature.
Application:
Clinical evidence requirements and treatment cycle duration create divergent margin profiles across wound etiologies, with chronic conditions generating recurring consumption patterns.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries requiring extended management protocols. United States integrated wound care center networks standardize biologic interventions here, capturing disproportionate margin through multi-month treatment cycles and repeat product application.
- Burn Care:Full-thickness and partial-thickness thermal injuries demanding immediate dermal coverage. Specialized burn center distribution networks in Germany, France, and Italy concentrate procurement under EU Medical Device Regulation Class III device frameworks.
- Surgical Wounds:Post-operative incisions and reconstructive procedures utilizing biologics for scar reduction.
- Traumatic Injuries:Acute lacerations and degloving injuries treated in emergency and trauma settings.
Chronic wounds dominate revenue capture; burn care is climbing the fastest as European regulatory harmonization accelerates product registration.
End User:
Procurement concentration and reimbursement access determine which delivery settings support premium biologic pricing versus commodity substitution.
- Hospitals:Inpatient and outpatient departments with centralized purchasing authority and specialty wound care infrastructure. Veterans Affairs integrated service networks in the United States offer sole-source contracting pathways for limb-salvage biologics meeting diabetic foot ulcer protocol specifications.
- Specialty Clinics:Dedicated wound care centers with standardized protocols and high patient volume. These United States-based facilities amplify product pull-through velocity through concentrated biologic adoption and physician specialization.
- Ambulatory Surgical Centers:Same-day surgical facilities with limited storage capacity favoring ambient-stable formulations.
- Home Healthcare:Skilled nursing and visiting nurse services managing wound care in residential settings.
Hospitals retain the largest procurement volume; specialty clinics are gaining share fastest as integrated networks consolidate patient flows.
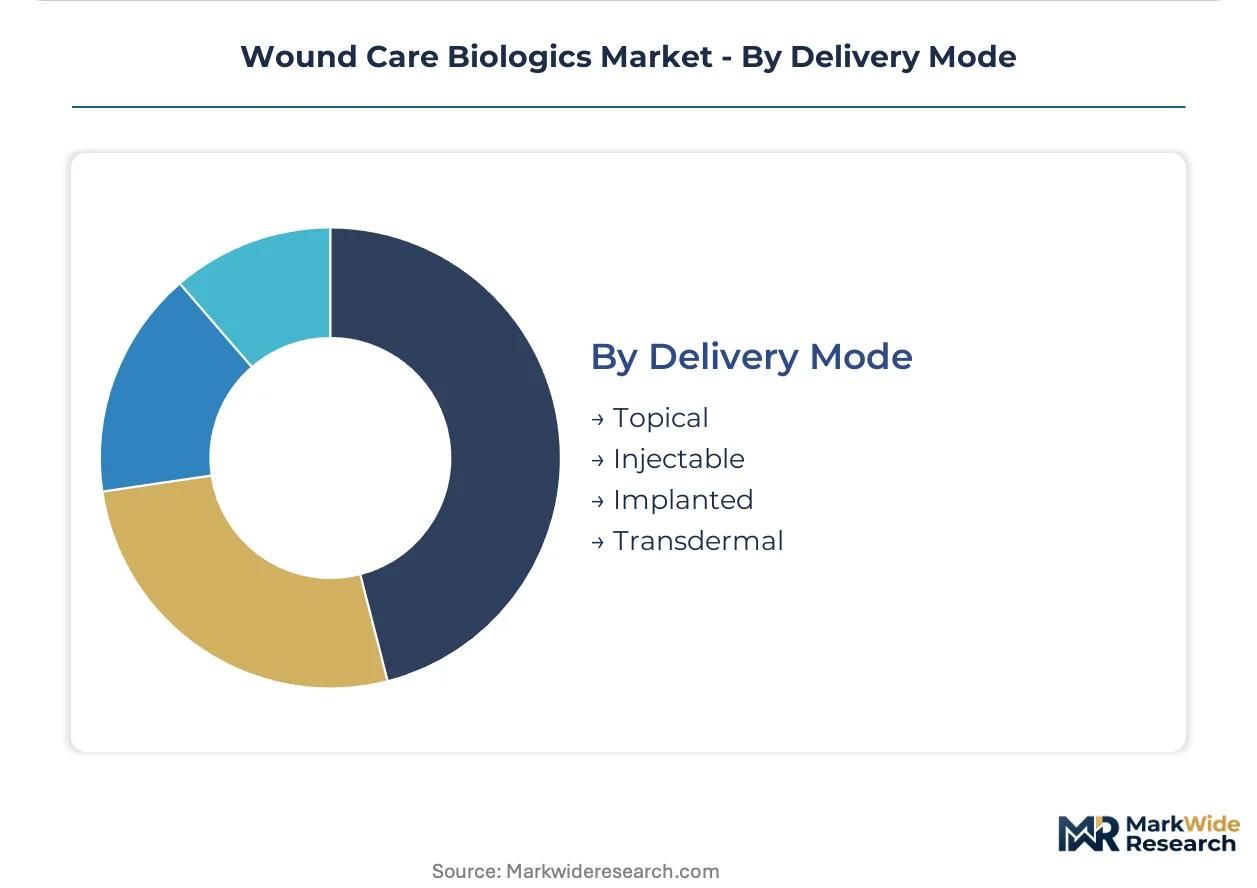
Delivery Mode:
Storage stability and administration complexity segment addressable markets by care setting capability and cold-chain infrastructure investment.
- Topical:Direct application of gels, sheets, and powders to wound beds. Ambulatory care facilities across United States Medicare Advantage networks adopt these formats to reduce waste from expired multi-dose inventory.
- Implanted:Surgical placement of dermal matrices and cellular constructs. Cryopreserved products requiring minus eighty degrees Celsius storage concentrate in hospital operating rooms with specialized logistics partnerships.
- Injectable:Subcutaneous or intralesional delivery of concentrated biologic suspensions.
- Transdermal:Sustained-release patches and microneedle systems for growth factor delivery.
Topical formats command the widest deployment; implanted products follow the steepest expansion trajectory as 3D bioprinting convergence enables patient-specific constructs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The interstate highway network and specialized cold-chain logistics corridors connecting the Midwest to the Eastern Seaboard sustain the United States' central position in wound care biologics distribution. These transport arteries enable cryopreserved skin substitutes to reach integrated wound care centers within critical viability windows.
United States
CMS reimbursement tightening around diabetic foot ulcer protocols drives hospital procurement acceleration. FDA's 21 CFR Part 1271 framework governs human cells and tissue-based product manufacturing standards. The Texas Medical Center in Houston anchors limb-salvage clinical trials and specialist training programs.
Germany
EU Medical Device Regulation Class III device classification elevates clinical evidence requirements for dermal matrix manufacturers. EMA's Advanced Therapy Medicinal Products framework applies to cellular therapies entering German hospital procurement channels. The Rhine-Main cluster around Frankfurt concentrates notified body technical documentation review capacity.
United Kingdom
NHS England's specialized commissioning frameworks concentrate biologic procurement through designated wound care centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining national access pathways. The Cambridge-Oxford-London triangle hosts regenerative medicine research translation facilities.
Japan
PMDA's regenerative medicine product designation accelerates conditional approval timelines for cellular skin substitutes. METI's healthcare technology export initiatives support domestic manufacturers entering Southeast Asian markets. The Kansai region around Osaka maintains specialized burn center distribution networks.
France
ANSM's national health technology assessment determines hospital reimbursement rates for bioengineered wound products. HAS evaluation criteria emphasize amputation prevention outcomes in diabetic foot ulcer protocols. The Paris-Saclay cluster coordinates clinical investigation sites for dermal matrix post-market surveillance.
Wound Care Biologics Market Vendor Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and integrated service network access. The competitive set rotates toward manufacturers with validated ISO 13485 quality management systems as hospital procurement tightens performance standards. Three archetypes dominate: diversified medical technology conglomerates with broad hospital contracting infrastructure, pure-play regenerative medicine specialists with concentrated biologic portfolios, and tissue bank operators controlling allograft raw material supply. M&A activity concentrates on acquiring cryopreserved logistics capabilities and point-of-care activation technology platforms.
Among diversified medical technology conglomerates, Stryker and Smith & Nephew exemplify scale-driven positioning through broad hospital infrastructure and advanced wound management distribution networks. Within the regenerative medicine specialist tier, Integra LifeSciences and Organogenesis occupy positions defined by dermal matrix portfolios and limb-salvage protocol penetration. These five entities represent the competitive anchors across listed and private ownership structures.
| Leading Market Players |
|---|
| ConvaTec Group |
| Kerecis |
| Integra LifeSciences |
| Stryker |
| Bioventus |
| MiMedx |
| Mölnlycke Health Care |
| Organogenesis |
| Smith & Nephew |
| Others |
Supply Flow & Price Mechanics
Lyophilized growth factor formulations displacing cryopreserved skin substitutes in outpatient settings are simultaneously redistributing manufacturing toward ambient-stable production hubs and compressing price premiums previously commanded by cold-chain infrastructure. This substitution dynamic concentrates value capture among manufacturers with validated stabilization chemistry while eroding margins for legacy cryopreservation-dependent product lines.
Pricing Analysis
Certification level creates the primary spread across product tiers, with ISO 13485-validated active biologic devices commanding premium positioning against tissue bank-sourced allografts lacking equivalent quality system documentation. Contract-based long-term offtake agreements dominate hospital procurement, particularly within Veterans Affairs integrated service networks and Medicare Advantage accountable care organizations. Pricing pressure stems from synthetic collagen matrix substitution in price-sensitive burn care applications, compressing margins for xenogeneic dermal scaffolds. Ambulatory surgical centers exhibit highest price sensitivity due to limited storage infrastructure, while academic medical centers with limb-salvage protocols demonstrate lowest sensitivity given outcome-based reimbursement incentives.
Supply Chain Analysis
Cadaveric tissue bank processing capacity in the United States anchors supply availability for allograft-derived matrices, with secondary concentration in German and French tissue establishments serving EU Medical Device Regulation compliance requirements. Raw material dependencies center on human donor tissue availability, porcine and bovine collagen sources, and recombinant protein production cell lines. Single-source vulnerability characterizes specialized cryopreservation logistics partnerships maintaining minus eighty degrees Celsius cold chains. Distribution runs through specialty wound care distributors bundling biologics with negative pressure therapy and debridement services, displacing fragmented direct hospital contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wound care biologics sit at a regulatory inflection where FDA's 21 CFR Part 1271 framework and EU MDR Class III device reclassification are simultaneously elevating compliance thresholds and consolidating viable competitor sets. This technological-regulatory convergence favors manufacturers with capitalized quality infrastructure over emerging developers facing eighteen-to-twenty-four month ISO 13485 implementation cycles.
For Market Incumbents: Fortify cryopreserved logistics networks through exclusive partnerships with specialized cold-chain operators, defending against lyophilized formulation entrants targeting outpatient displacement. Deepen backward integration into tissue bank operations to secure allograft raw material supply against donor availability volatility. Prioritize CE marking pathway investment for EU MDR compliance ahead of notified body capacity constraints. For New Entrants and Emerging Players: Anchor in Veterans Affairs sole-source contracting pathways for diabetic foot ulcer limb-salvage protocols, where federal integrated service networks concentrate procurement volume and reduce customer acquisition friction. Target rural United States access gaps through telemedicine-integrated delivery models pairing remote specialist consultation with shipped ambient-stable growth factors. Pursue 3D bioprinting convergence partnerships to differentiate via patient-specific construct capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors quality-system-validated mid-cap specialists with established hospital contracting infrastructure over pre-revenue cellular therapy developers facing extended EMA Advanced Therapy Medicinal Products timelines. Acquisition focus should center on point-of-care activation technology platforms and cryopreserved logistics capabilities as defensive moats. Monitor CMS reimbursement determination schedules for bioengineered skin substitutes as the critical inflection signal for scalable clinical adoption.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Eighteen-to-twenty-four month quality system validation accelerates FDA premarket approval pathways for active biologic devices. |
| Hospital System Partnership | Accountable care organization bundling agreements with Medicare Advantage networks secure recurring limb-salvage protocol volume. |
| Reimbursement Strategy | CMS National Coverage Determination alignment for diabetic foot ulcer amputation prevention protocols determines scalable adoption. |
| Manufacturing Scale-Up | Lyophilized growth factor production capacity expansion eliminates cold-chain dependency for outpatient wound center deployment. |
| Regulatory Approval Pathway | EMA Advanced Therapy Medicinal Products framework navigation determines European market entry timelines for cellular therapies. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital wound care center medical directors, biomedical engineers managing tissue processing facilities, GPO contracts managers, and CMS reimbursement policy specialists, then refined through secondary validation across FDA 510(k) and PMA filings, EMA Advanced Therapy Medicinal Products submissions, CMS National Coverage Determination databases, and hospital procurement contract repositories. Bottom-up demand modeling from individual wound care center biologic utilization rates triangulated against top-down market sizing from manufacturer revenue disclosures and distributor shipment data.
Variance decomposition across product type, application etiology, end-user setting, and delivery mode segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends and chronic wound epidemiology projections. Industry-specific forecast inputs incorporated CMS reimbursement policy trajectory assumptions and EU MDR implementation timeline impacts on notified body review capacity.
Decision-makers should treat outputs as directional under stable regulatory framework assumptions; material deviation in FDA enforcement discretion or EMA clinical evidence requirements would warrant model refresh. Practitioners should keep alternative scenarios live as cadaveric donation rates and synthetic matrix substitution trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Biopatches Market
Wound Care
Topical Wound Agents Market
Wound Care
Wound Closure Devices Market
Wound Care
Europe Wound Care Market
Wound Care
Europe Compression Bandages Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Chronic Wound Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Bioactive Wound Care Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Wound Skin Care Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Autologous Wound Patches Market
Wound Care
Global Digital Wound Measurement Devices Market