
 Global Contact Lens Solution Market | 2026-2036
Global Contact Lens Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contact Lens Solution Market Foresight
Multi-source procurement of active pharmaceutical ingredients is recalibrating how solution manufacturers secure benzalkonium chloride and polyhexamethylene biguanide supplies. Johnson & Johnson Vision Care, Inc. leverages captive polymer chemistry expertise to control preservative quality from raw material through finished formulation. Alcon anchors its supply chain through backward integration into buffer component production. Bausch + Lomb competes by sustaining dual-source agreements for hydrogen peroxide catalyst suppliers.
Contact lens solution comprises sterile aqueous formulations containing antimicrobial agents, surfactants, chelating agents, and buffering salts designed to clean, disinfect, rinse, and store hydrogel or silicone hydrogel lenses while maintaining physiological compatibility with ocular surface tissue. Multipurpose solution dominates volume due to convenience-driven consumer preference for single-bottle regimens, though hydrogen peroxide systems command premium positioning among preservative-sensitive users. Soft contact lenses absorb the majority of solution consumption because their higher water content and porous matrix structure demand more frequent chemical disinfection cycles than rigid gas permeable alternatives.
FDA ophthalmic guidance, EMA MDR classification for Class IIa medical device fluids, and ISO 11980 biocompatibility standards collectively govern preservative efficacy thresholds and cytotoxicity limits that determine market access eligibility. REACH restrictions on quaternary ammonium compounds within the European Union are forcing reformulation investments that favor peroxide-based and polyquaternium alternatives. Stakeholders must monitor evolving preservative-free packaging innovations and regional divergence in disinfectant registration pathways to anticipate where compliance costs will reshape competitive economics.
Market Dynamics
Multipurpose solution formulations face reformulation pressure as REACH restrictions on quaternary ammonium compounds force European manufacturers toward peroxide-based and polyquaternium alternatives, compressing legacy preservative economics while opening premium positioning for preservative-free systems.
Growth Catalysts
- Daily Disposable Lens Proliferation:Silicone hydrogel daily disposables require specialized storage solutions with enhanced osmolarity matching, expanding the addressable base beyond traditional monthly replacement users.
- FDA Standalone Disinfectant Guidance:Updated efficacy testing protocols are elevating quality thresholds that filter marginal competitors and reward manufacturers with captive polymer chemistry capabilities.
- Preservative-Sensitive Demographics:Rising incidence of contact lens-related dry eye among aging populations in Germany and Japan is accelerating hydrogen peroxide system adoption.
Market Restraints
- Benzalkonium Chloride Supply Concentration:Active pharmaceutical ingredient procurement depends heavily on Chinese and Indian chemical manufacturers, exposing formulators to geopolitical friction and shipping volatility.
- EMA MDR Class IIa Registration Burden:Medical device fluid reclassification in Europe extends compliance timelines and elevates clinical documentation costs for new market entrants.
- Saline Solution Substitution:Rigid gas permeable lens wearers increasingly migrate to plain saline rinsing protocols, eroding chemical disinfection demand in this segment.
Strategic Opportunities
- India's Underpenetrated Tier-2 Cities:Contact lens adoption among young professionals in Pune, Hyderabad, and Ahmedabad outpaces organized retail solution availability.
- Subscription Direct-to-Consumer Channels:Lens wearers in the United States are consolidating purchasing through automated replenishment platforms that bundle solution with lens orders.
- ISO 11980 Biocompatibility Premium Tier:Certification-driven procurement in hospital-affiliated optical chains rewards manufacturers exceeding baseline cytotoxicity thresholds.
Industry Challenges
- Ocular Surface Toxicology Expertise Scarcity:Formulation teams require specialized knowledge of corneal epithelial cell assay interpretation that outstrips current graduate program output.
- Legacy Manufacturing Line Retrofit Costs:Hydrogen peroxide system production demands aseptic filling infrastructure incompatible with existing multipurpose solution equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contact Lens Solution Market |
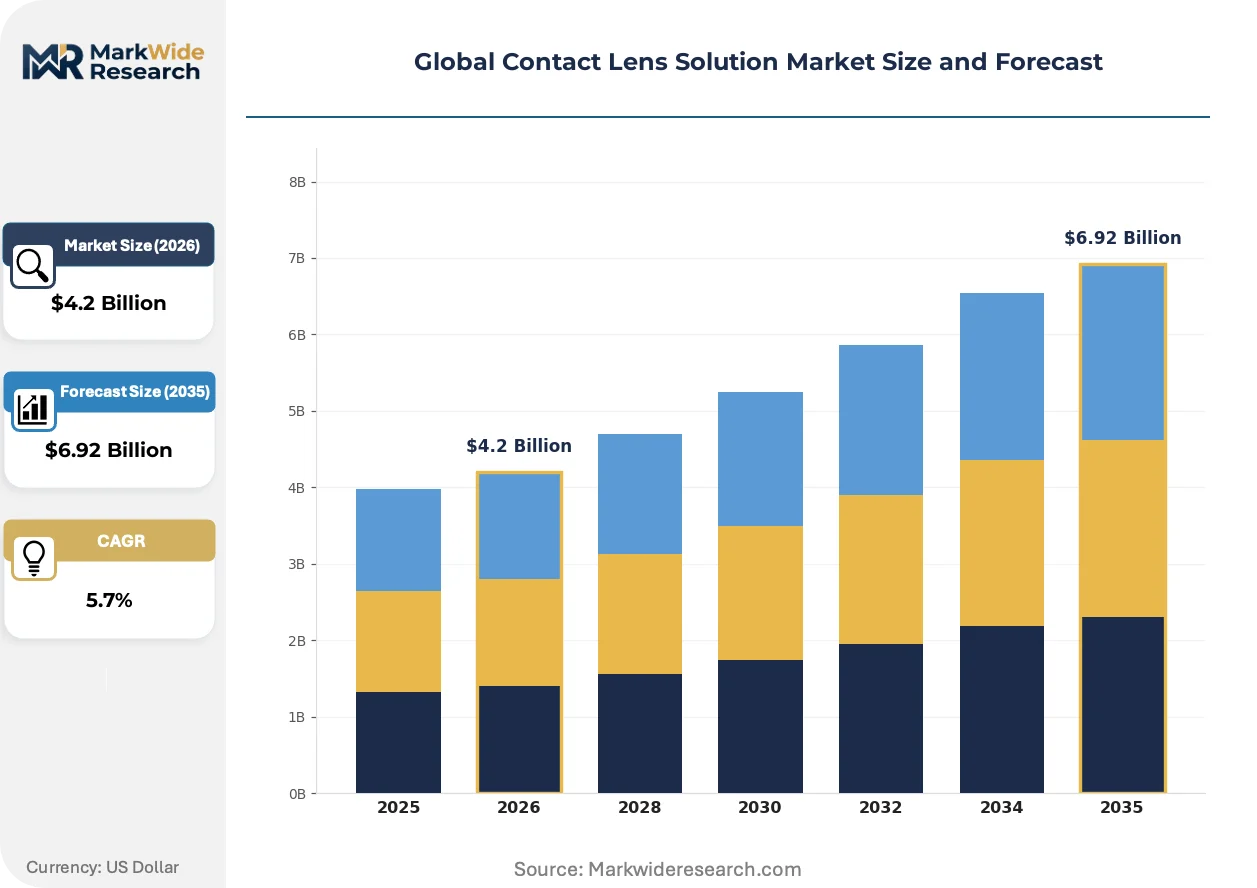
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.92 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multipurpose Solution, Disinfecting Solution, Enzymatic Cleaner, Saline Solution, Hydrogen Peroxide Solution Application: Soft Contact Lenses, Rigid Gas Permeable Lenses, Extended Wear Lenses, Cosmetic Lenses End User: Optometrists, Eye Care Clinics, Retail Pharmacies, Online Retailers Distribution Channel: Specialty Stores, Supermarkets & Hypermarkets, E-commerce Platforms, Optical Stores |
| Companies Covered | Johnson & Johnson Vision Care, Inc., Alcon, Bausch + Lomb, The Cooper Companies, Inc., Allergan (AbbVie), Menicon Co., Ltd., Ciba Vision, CooperVision, Inc., FreshKon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contact Lens Solution Market Shifts & Advancements
Reformulation chemistry, regulatory pathway fragmentation, and channel consolidation are simultaneously compressing commodity margins and expanding premium tier boundaries across solution categories.
Polyquaternium-1 is absorbing market share from traditional biguanide preservatives as silicone hydrogel lens manufacturers specify compatibility with their proprietary surface coatings. Daily disposable wearers in Germany and Japan are adopting these reformulated multipurpose solutions at rates that outpace North American conversion. The technology is absorbing volume that previously flowed to hydrogen peroxide systems among moderate-sensitivity users.
REACH restrictions on quaternary ammonium compounds are forcing European Union manufacturers to eliminate benzalkonium chloride from formulations ahead of sunset dates. Industrial consequence includes accelerated R&D spend on peroxide catalyst stabilization and polyquaternium synthesis pathways. Multipurpose solution producers serving France, Germany, and the Netherlands are responding with dual-product portfolios that segregate EU-compliant and legacy formulations.
Automated replenishment platforms are consolidating solution purchasing decisions away from retail pharmacy counters toward lens manufacturer direct channels. United States-based wearers of Johnson & Johnson and Alcon lens brands are bundling solution subscriptions with their lens shipments, compressing independent solution brand shelf space. This channel shift is most visible in suburban markets where optical retail density has declined post-pandemic.
Global Contact Lens Solution Market Segmentation
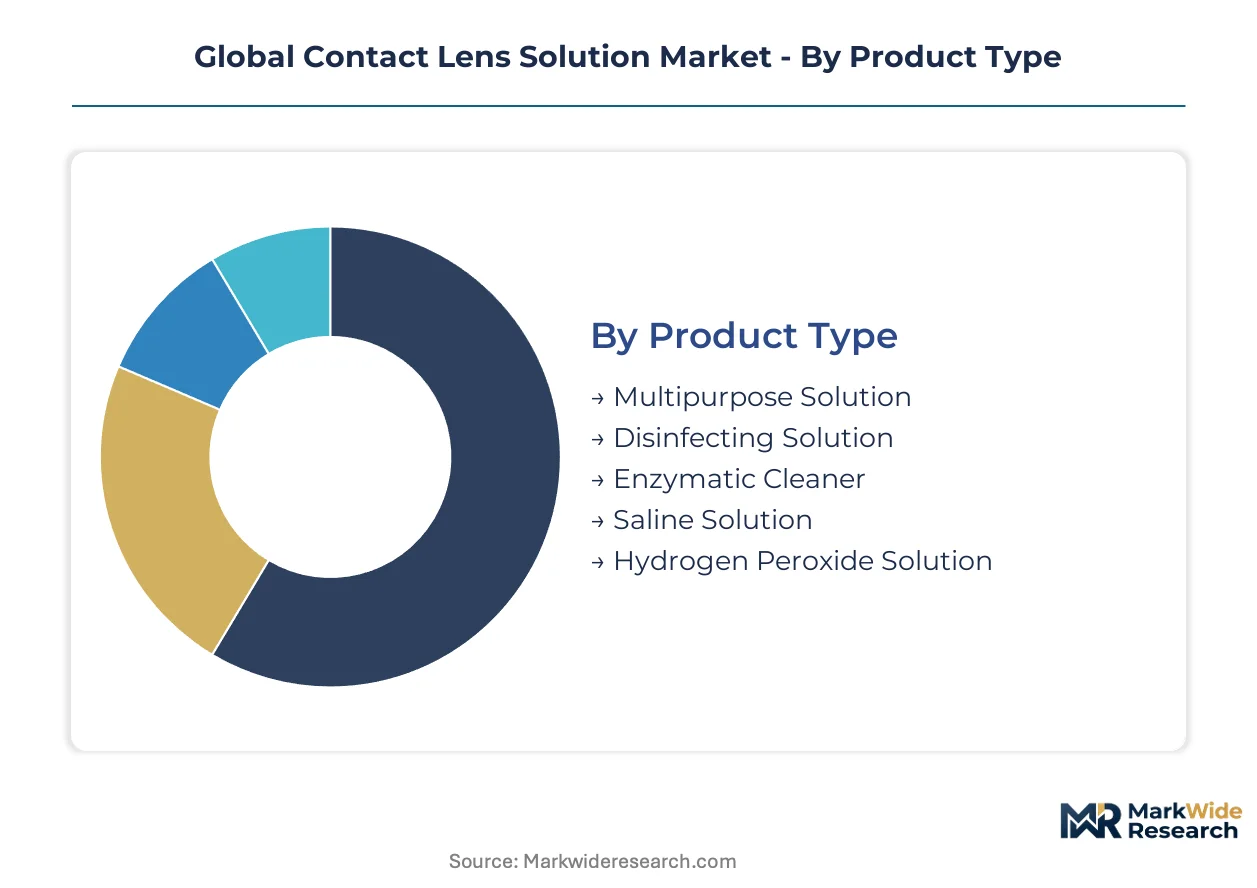
Solution formulation chemistry and lens material compatibility create divergent margin profiles across product categories. Channel concentration and regulatory pathway complexity further stratify competitive positioning within each segment dimension.
Product Type:
Convenience-driven consumer preference for simplified regimens dominates purchasing decisions across formulation categories.
- Multipurpose Solution:Single-bottle formulations integrate cleaning, disinfection, rinsing, and storage functions through polyhexamethylene biguanide or polyquaternium-1 antimicrobial systems. Daily disposable lens wearers in Germany and Japan favor these solutions for their streamlined compliance with silicone hydrogel surface coatings. Volume sits with multipurpose formulations; growth tilts toward preservative-free and peroxide-based alternatives.
- Hydrogen Peroxide Solution:Three-step catalytic neutralization systems deliver preservative-free disinfection through stabilized hydrogen peroxide breakdown to water and oxygen. Aging populations with contact lens-related dry eye in the United States and Germany are migrating toward these premium-positioned systems despite complex handling requirements.
- Disinfecting Solution:Standalone chemical disinfection formulations without integrated surfactant cleaning, requiring separate mechanical cleaning steps.
- Enzymatic Cleaner:Weekly protein deposit removal systems using subtilisin enzymes to clear accumulated tear film deposits from hydrogel matrices.
- Saline Solution:Isotonic sodium chloride rinsing formulations without antimicrobial agents, serving rigid gas permeable lens protocols and multipurpose solution rinsing.
Margin compression concentrates in legacy multipurpose formulations; premium positioning accrues to peroxide and enzymatic systems.
Application:
Lens material water content and replacement frequency determine disinfection intensity requirements and solution consumption rates.
- Soft Contact Lenses:Hydrogel and silicone hydrogel materials with porous matrix structures demand frequent chemical disinfection cycles due to protein and lipid deposition from tear film contact. Daily disposable adoption in the United States and China absorbs the majority of solution volume through enhanced osmolarity-matched storage formulations. Application concentration follows soft lens deployment; expansion steepest in extended wear silicone hydrogel segments.
- Extended Wear Lenses:Continuous-wear silicone hydrogel designs approved for overnight use require specialized solutions with enhanced antimicrobial efficacy and hypotonic buffering to support corneal oxygenation during sleep periods.
- Rigid Gas Permeable Lenses:Low-water-content fluorosilicone acrylate materials resist microbial adherence and enable saline-only rinsing protocols that erode chemical disinfection demand.
- Cosmetic Lenses:Decorative and colored hydrogel lenses with pigment-impregnated surfaces require compatible solutions that preserve tint integrity while maintaining disinfection standards.
Consumption intensity peaks with extended wear protocols; substitution risk concentrates in rigid gas permeable maintenance.
End User:
Professional credentialing requirements and procurement authorization levels segment demand across clinical and retail channels.
- Optometrists:Primary eye care providers with prescribing authority bundle solution recommendations with lens fittings, capturing recurring refill revenue through practice-affiliated dispensaries.
- Eye Care Clinics:Hospital-affiliated optical departments in Germany and Japan specify ISO 11980 biocompatibility certification thresholds that filter non-compliant suppliers from procurement tenders.
- Retail Pharmacies:Chain pharmacy counters face shelf space compression as automated replenishment platforms consolidate solution purchasing through direct-to-consumer channels.
- Online Retailers:E-commerce platforms aggregate independent solution brands outside manufacturer-direct subscription systems, competing on price transparency and bulk packaging.
Procurement authority clusters with optometrists; volume migration accelerates toward online and subscription channels.
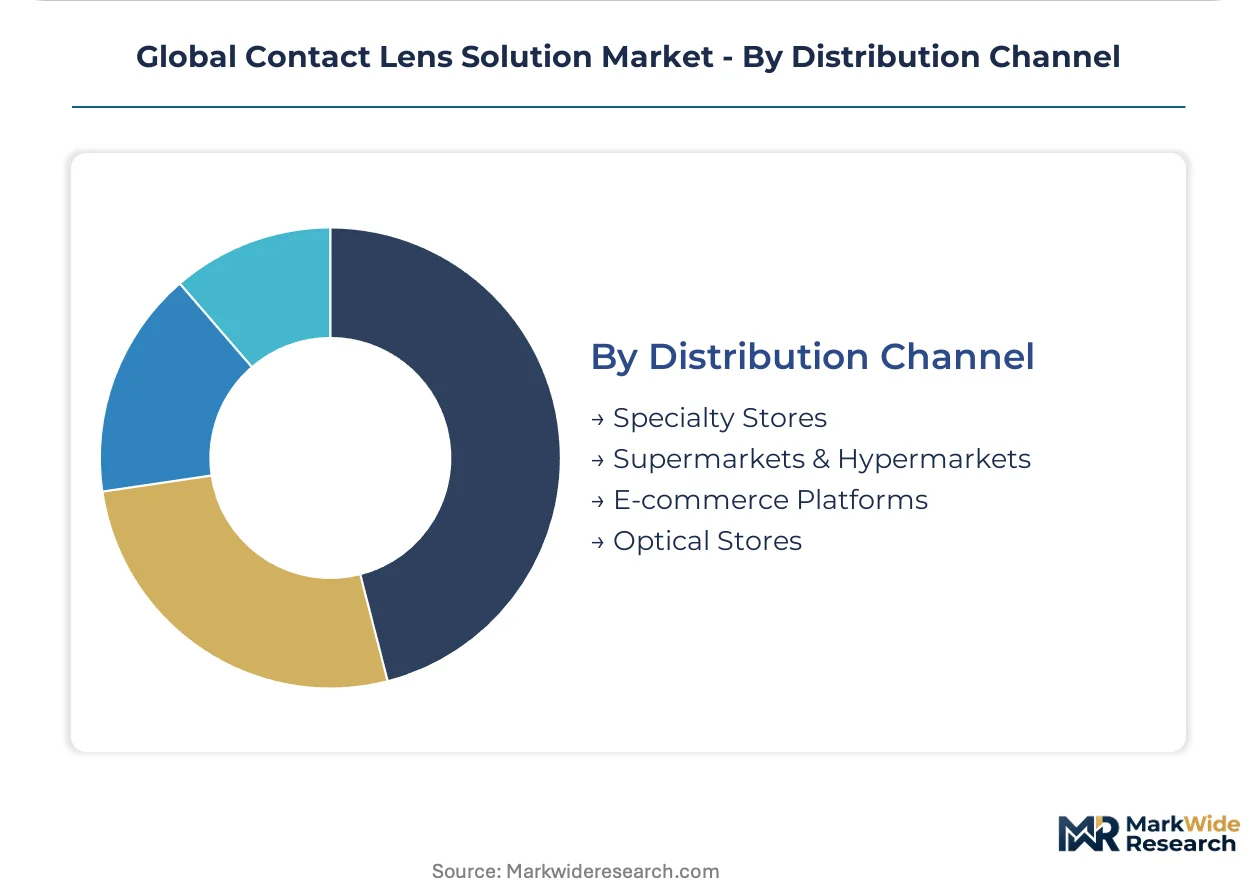
Distribution Channel:
Physical retail density and digital infrastructure maturity determine channel viability across geographic markets.
- E-commerce Platforms:Automated replenishment systems bundle solution with lens orders, compressing independent brand visibility through algorithmic recommendation engines and subscription lock-in.
- Optical Stores:Independent and chain optometry practices maintain solution inventory for immediate patient dispensing, supported by professional recommendation authority.
- Specialty Stores:Dedicated vision care retailers concentrate in suburban United States markets where optical retail density has declined post-pandemic.
- Supermarkets & Hypermarkets:Mass merchandisers stock commodity multipurpose solutions for convenience purchasing, competing primarily on price positioning.
Channel concentration favors optical stores for professional guidance; digital platforms capture replenishment automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India supply the bulk of benzalkonium chloride and polyhexamethylene biguanide active pharmaceutical ingredients that feed formulation plants across Germany, the United States, and Japan. This chemical trade flow concentrates procurement risk in Asian manufacturing clusters while shaping where solution producers locate backward integration investments.
United States
Daily disposable silicone hydrogel adoption among aging professionals drives solution volume in suburban markets where optical retail density has declined post-pandemic. FDA standalone disinfectant guidance elevates quality thresholds that filter marginal competitors from interstate commerce. Johnson & Johnson Vision Care anchors formulation expertise in New Jersey polymer chemistry facilities.
Germany
Preservative-sensitive demographics in aging metropolitan centers accelerate hydrogen peroxide system migration away from traditional multipurpose formulations. EMA MDR Class IIa medical device fluid reclassification extends compliance timelines for new market entrants. REACH restrictions on quaternary ammonium compounds force manufacturers in North Rhine-Westphalia toward polyquaternium alternatives ahead of sunset dates.
China
Contact lens adoption among young professionals in tier-2 cities outpaces organized retail solution availability, creating distribution gaps for automated replenishment platforms. NMPA ophthalmic guidance governs preservative efficacy thresholds for domestic formulation approval. Chemical manufacturers in Jiangsu and Zhejiang provinces dominate benzalkonium chloride export supply.
Japan
Rising contact lens-related dry eye incidence among elderly populations shifts demand toward peroxide-based and preservative-free systems despite complex handling requirements. PMDA biocompatibility standards enforce ISO 11980-aligned cytotoxicity limits for market access. Menicon Co., Ltd. maintains formulation capabilities in Nagoya optical manufacturing clusters.
India
Young professionals in Pune, Hyderabad, and Ahmedabad adopt contact lenses faster than organized retail solution networks can supply. CDSCO medical device registration pathways for Class B fluids determine import eligibility for multinational brands. Local chemical manufacturers in Gujarat and Maharashtra supply active pharmaceutical ingredients to both domestic formulators and export markets.
Global Contact Lens Solution Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution channel control. The vendor base stratifies into three tiers: integrated lens-solution conglomerates with captive polymer expertise, standalone solution specialists competing on price, and regional private-label distributors serving pharmacy chains. Strategic moves concentrate on backward integration into buffer component production and dual-source procurement agreements for hydrogen peroxide catalyst supplies.
Within the integrated conglomerate tier, Johnson & Johnson Vision Care, Inc. and Alcon exemplify archetypes that leverage captive polymer chemistry to control preservative quality from raw material through finished formulation. These entities occupy positions where lens manufacturing and solution formulation capabilities reinforce each other. Bausch + Lomb sits within the standalone solution specialist category, competing through sustained dual-source agreements that mitigate supply concentration risk in active pharmaceutical ingredient procurement.
| Leading Market Players |
|---|
| Johnson & Johnson Vision Care, Inc. |
| Alcon |
| Bausch + Lomb |
| The Cooper Companies, Inc. |
| Allergan (AbbVie) |
| Menicon Co., Ltd. |
| Ciba Vision |
| CooperVision, Inc. |
| FreshKon |
| Others |
Supply & Pricing Matrix
REACH sunset clauses on quaternary ammonium compounds gate qualified supply for European manufacturers while simultaneously creating premium-tier pricing access for peroxide-based and polyquaternium alternatives. Formulators lacking backward integration into compliant chemistry face margin compression as certification costs and reformulation investments concentrate pricing power among integrated conglomerates.
Pricing Analysis
Subscription bundling with lens orders increasingly includes solution replenishment, while standalone solution purchases remain unbundled and exposed to retail price competition. Three-tier pricing structure across premium, standard, and economy levels separates hydrogen peroxide systems from multipurpose formulations and private-label saline alternatives. Price differentiation hinges on ISO 11980 biocompatibility certification tier and captive polymer chemistry capabilities. Pricing pressure stems from automated replenishment platforms compressing independent brand shelf space. Daily disposable lens wearers show lowest price sensitivity; rigid gas permeable maintenance users exhibit highest substitution elasticity toward plain saline protocols.
Supply Chain Analysis
Specialized formulation chemists and aseptic filling technicians concentrate in New Jersey, North Rhine-Westphalia, and Nagoya manufacturing clusters, constraining capacity expansion for hydrogen peroxide system production. Active pharmaceutical ingredient supply draws from Jiangsu and Zhejiang provinces in China alongside Gujarat and Maharashtra states in India. Raw material dependencies center on benzalkonium chloride, polyhexamethylene biguanide, and stabilized hydrogen peroxide catalysts. Single-source vulnerability in Chinese chemical manufacturing exposes formulators to shipping volatility and geopolitical friction. Distribution runs through automated replenishment platforms, optical store dispensaries, and mass merchandiser channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contact lens solution manufacturing is consolidating around integrated lens-solution conglomerates as FDA standalone disinfectant guidance and EMA MDR reclassification force marginal competitors from interstate and European commerce.
For Market Incumbents: To counter REACH-driven reformulation cost inflation, Johnson & Johnson Vision Care and Alcon should deepen backward integration into polyquaternium synthesis pathways and buffer component production. Captive polymer chemistry capabilities must expand to preserve quality control from raw material through finished formulation. Dual-source procurement agreements for hydrogen peroxide catalyst supplies will mitigate concentration risk in Asian chemical manufacturing. For New Entrants and Emerging Players: CDSCO medical device registration pathways in India open a window for regional formulation specialists to capture underpenetrated tier-2 city demand in Pune, Hyderabad, and Ahmedabad. White-space concentration sits with preservative-free multipurpose solutions for silicone hydrogel daily disposables. Direct-to-consumer subscription bundling with domestic lens brands offers the most penetrable go-to-market angle outside established optical retail networks. For Investors and Strategic Acquirers: FDA ophthalmic guidance updates are the leading indicator that quality threshold elevation will accelerate sector consolidation. Five-to-ten year viability favors integrated conglomerates with captive supply chains over standalone solution specialists exposed to API procurement volatility. Acquisition targets should display backward integration into buffer production or proprietary polyquaternium chemistry. The signal to monitor is EMA MDR Class IIa registration timeline extensions filtering new entrants from European procurement tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Buffer Component Production | Alcon's captive supply of buffering salts reduces formulation cost exposure to commodity chemical volatility. |
| Dual-Source Procurement Agreement for Hydrogen Peroxide Catalysts | Bausch + Lomb's supplier diversification mitigates single-source concentration risk in Chinese chemical manufacturing. |
| Preservative-Free Multipurpose Solution Launch | Polyquaternium-1 formulations capture migrating demand from benzalkonium chloride-sensitive demographics in Germany and Japan. |
| Automated Replenishment Platform Partnership | Subscription bundling with lens orders compresses independent brand visibility through algorithmic recommendation lock-in. |
| ISO 11980 Biocompatibility Certification Investment | Hospital-affiliated optical chains in Japan and Germany specify exceeding baseline cytotoxicity thresholds for procurement eligibility. |
Research Methodology
Multi-period observation of FDA guidance revisions, EMA MDR implementation timelines, and REACH sunset clause progressions anchored the trend analysis, supplemented by interviews with formulation chemists at integrated lens-solution conglomerates, procurement managers at hospital-affiliated optical chains, regulatory affairs specialists navigating CDSCO and PMDA pathways, and distribution channel heads at automated replenishment platforms. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, NMPA ophthalmic guidance documents, customs trade data on benzalkonium chloride imports, and SEC 10-K disclosures from publicly traded vision care entities. Bottom-up demand modeling across lens wearer demographics and top-down supply assessment through chemical manufacturing capacity triangulated market sizing.
Input-output matrices mapped formulation chemistry requirements against raw material availability, regulatory compliance costs, and channel economics across the projection horizon. Segmentation dimensions modeled included solution formulation type, lens material compatibility, end-user credentialing requirements, and distribution channel concentration. CAGRs were derived from fitted growth curves incorporating daily disposable lens adoption rates, preservative sensitivity demographic shifts, and automated replenishment platform penetration. Industry-specific forecast inputs encompassed silicone hydrogel surface coating compatibility specifications and hydrogen peroxide catalyst stabilization R&D trajectories.
Caveats apply where FDA guidance enforcement intensity, EMA MDR audit backlog resolution, or REACH alternative substance approval timelines could materially shift the outlook. Forecasts reflect assumptions regarding continued silicone hydrogel material dominance and sustained optical retail density decline in suburban United States markets. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Global IV Bags Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
UAE Hospital Supplies Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Blood Collection Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
United States Face Mask Market