
 Liquid Bandages Market | 2026-2036
Liquid Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Bandages Market Foresight
Pharmacy retail networks is reshaping how liquid bandages reach consumers, with shelf placement algorithms and pharmacist recommendations now governing category visibility more than traditional advertising. 3M leverages its decades-long institutional relationships with hospital purchasing coalitions to sustain volume leadership in surgical-grade formulations. Johnson & Johnson competes through brand recognition and extensive retail shelf presence across North American pharmacy chains.
Liquid bandages constitute polymer-based topical wound sealants, typically formulated with n-butyl cyanoacrylate or 2-octyl cyanoacrylate monomers that polymerize upon contact with tissue moisture to form a flexible antimicrobial barrier with tensile strength exceeding 20 MPa within 30 seconds. Spray formats dominate professional clinical settings where rapid, uniform coverage of irregular wound geometries proves essential, while gel formulations capture expanding home care usage due to controlled application precision and reduced risk of overspray contact with mucous membranes. Film-based variants occupy a narrower but higher-margin niche in cosmetic and pediatric segments where invisible, flexible protection commands premium positioning.
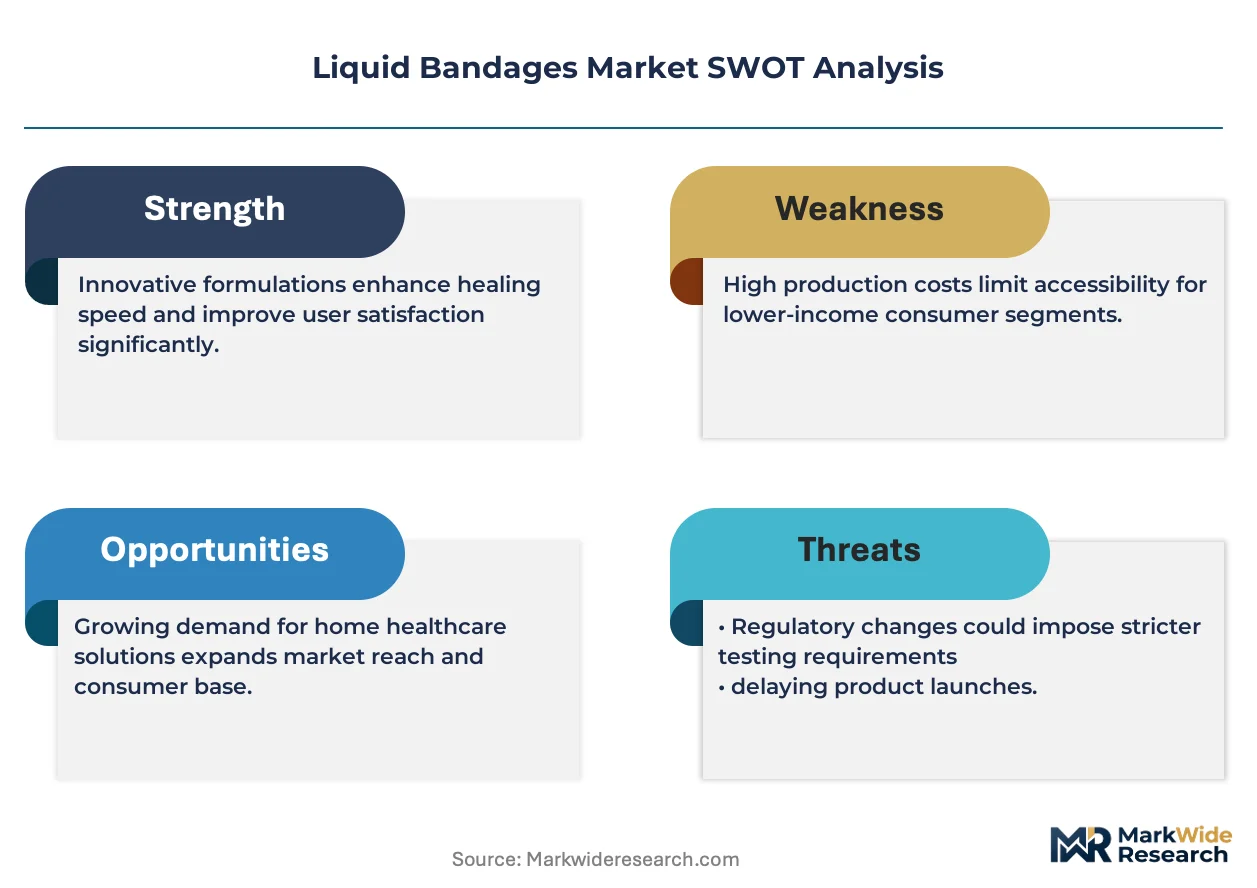
FDA 510(k) clearance pathways and ISO 10993 biocompatibility standards govern market entry for cyanoacrylate-based medical devices, with the FDA's evolving guidance on dermal sensitization testing now extending premarket validation timelines for new formulations. The EU Medical Device Regulation's reclassification of certain liquid bandage products from Class I to Class IIa has intensified conformity assessment burdens for European market access. Stakeholders must monitor how tightening biocompatibility thresholds in major jurisdictions will reshape R&D allocation between incremental formulation improvements and breakthrough polymer platforms.
Market Dynamics
The FDA's tightening scrutiny of cyanoacrylate dermal sensitization is compressing premarket timelines and forcing reformulation investments that favor established polymer chemistry platforms over experimental alternatives.
Growth Catalysts
- Sports medicine protocols:Athletic injury management now prioritizes rapid wound closure to minimize training disruption, driving institutional procurement of spray-format sealants in professional team facilities.
- ISO 10993 biocompatibility standards:Harmonized international testing frameworks reduce redundant certification costs for multi-jurisdiction product launches, accelerating geographic expansion for compliant manufacturers.
- Direct-to-consumer pharmacy channels:Shelf placement algorithms and pharmacist recommendation systems are displacing traditional advertising as the primary visibility mechanism for home care formulations.
Market Restraints
- Monomer supply concentration:n-butyl cyanoacrylate feedstock production clusters in East Asian chemical manufacturing zones, exposing formulators to shipping cost volatility and tariff friction.
- FDA 510(k) pathway extension:Evolving dermal sensitization guidance has lengthened premarket validation timelines, delaying revenue recognition for pipeline products by 12-18 months.
- Traditional adhesive bandage substitution:Low-cost fabric strip alternatives retain dominant shelf space in emerging market retail pharmacies, constraining premium liquid bandage penetration.
Strategic Opportunities
- Pediatric cosmetic applications:Invisible film-forming variants command premium positioning in parental purchasing decisions for minor childhood injuries, creating margin expansion potential.
- EU MDR Class IIa reclassification:Heightened conformity assessment burdens create competitive moats for notified body-approved manufacturers against unqualified market entrants.
- Telemedicine wound care integration:Remote consultation platforms are validating self-applied liquid bandage protocols, opening subscription-based replenishment channels for chronic wound patients.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation expertise in medical-grade cyanoacrylates concentrates among a narrow cohort of specialty chemists, inflating R&D compensation costs and extending hiring cycles.
- Legacy manufacturing equipment retrofitting:Aseptic spray production lines require seven-figure capital redeployment to meet updated FDA Current Good Manufacturing Practice expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Bandages Market |
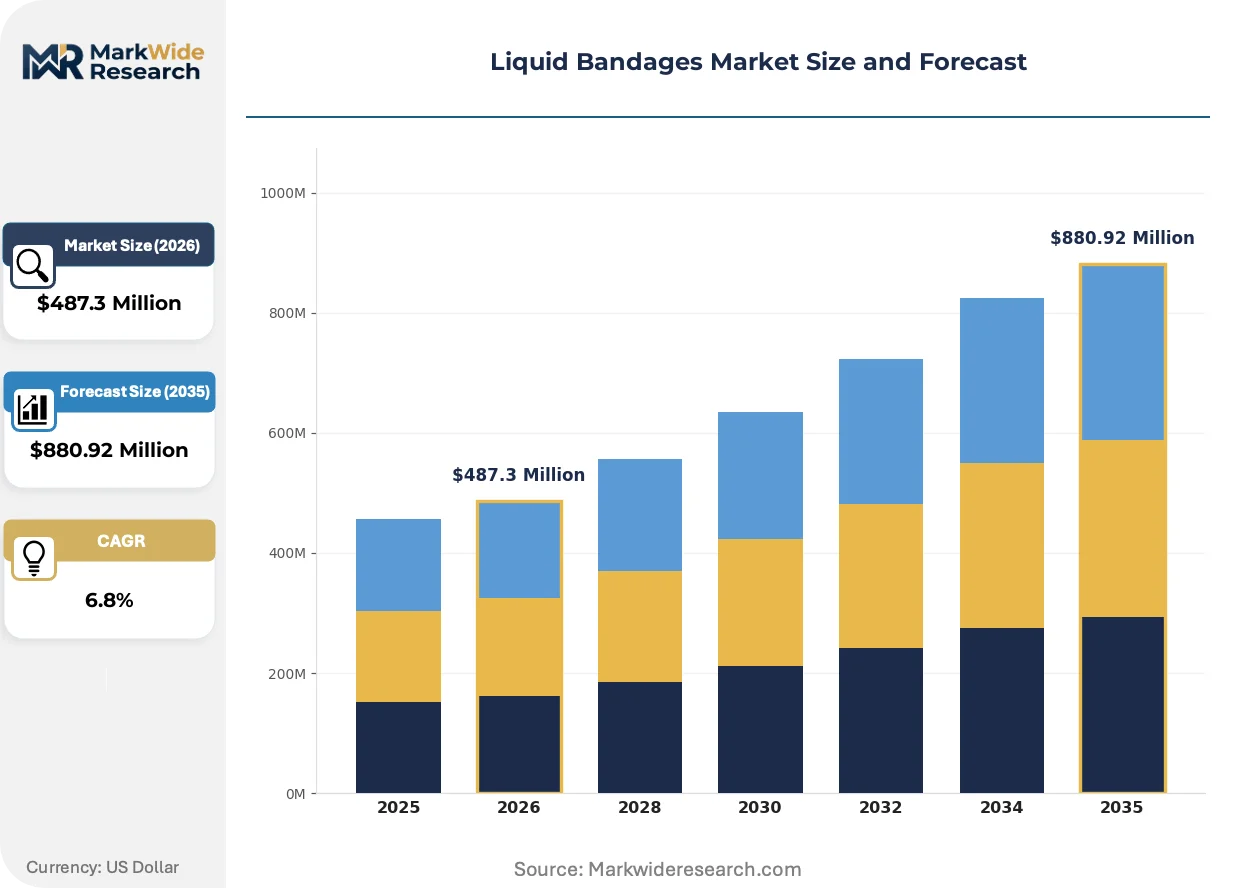
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Gels, Creams, Films Application: Wound Care, Surgical Sites, Burns, Abrasions End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online, Retail Stores, Wholesale, Medical Supply |
| Companies Covered | ConvaTec, Chemence, 3M, Mölnlycke Health Care, Advantice Health, Medline Industries, Kobayashi.Co., Johnson & Johnson, Smith & Nephew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Bandages Market Shifts & Advancements
Formulation science and regulatory harmonization are converging to reshape competitive positioning, with polymer platform choices now determining long-term market access trajectories more than incremental packaging improvements.
Antimicrobial-loaded cyanoacrylate matrices are virtualizing traditional two-step wound care protocols by integrating infection prevention directly into the sealant polymerization reaction. Hospital outpatient departments are adopting these silver-ion or iodine-complex formulations for post-surgical incision management, collapsing the separate antiseptic application step and reducing nursing labor allocation per wound closure event.
REACH substance restriction proposals for residual formaldehyde in medical adhesives are forcing European formulators to validate alternative stabilizer chemistries before the 2026 sunset review deadline. Manufacturers with existing MDR technical documentation are accelerating dossier updates to incorporate new toxicological data, while smaller competitors face notified body queue congestion that threatens market continuity.
Pharmacist-driven recommendation algorithms now govern category visibility in consolidated retail pharmacy chains, displacing manufacturer trade promotion spending as the primary demand generation mechanism. Independent community pharmacies retain residual influence in rural catchment areas, but formulary standardization across CVS, Walgreens, and Rite Aid networks concentrates purchasing leverage among three national buyers.
Liquid Bandages Market Segmentation
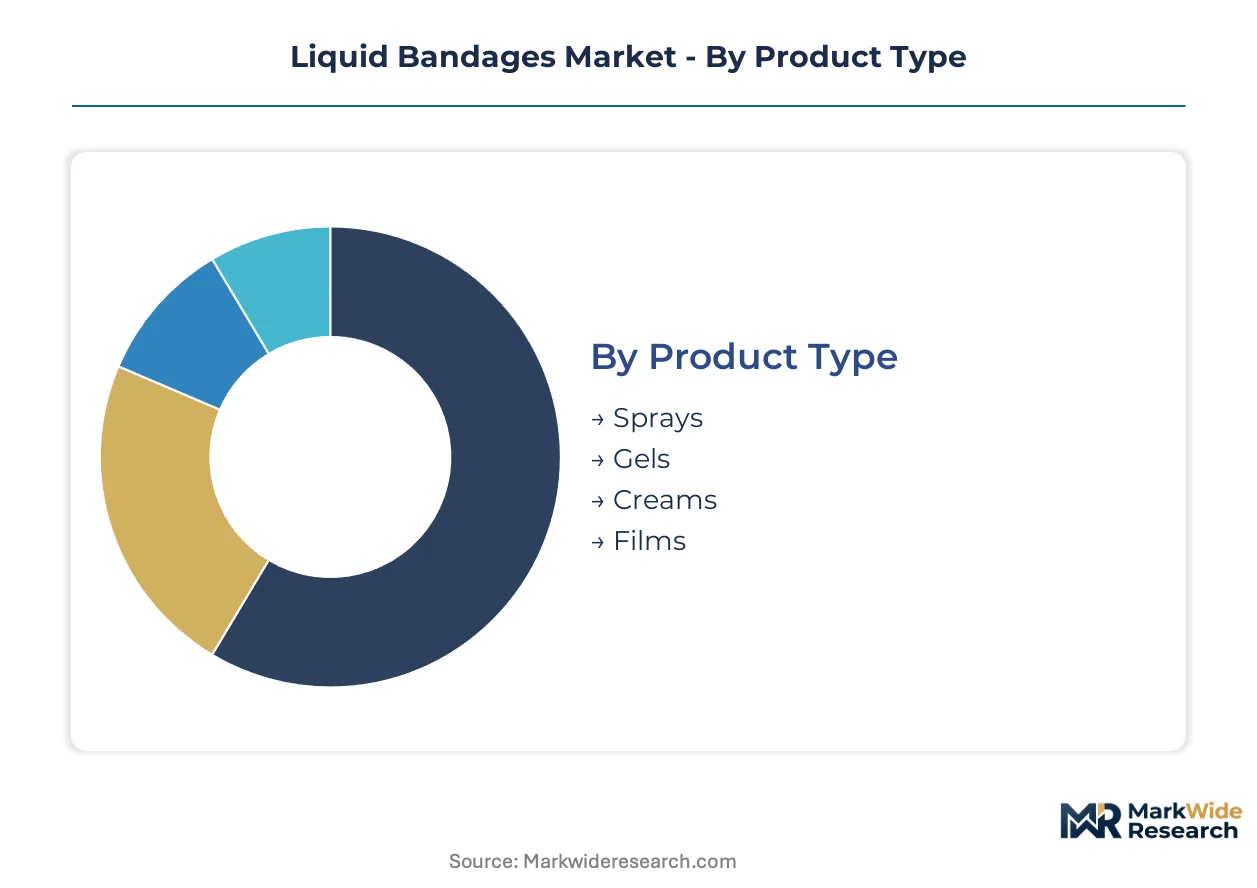
Liquid bandage manufacturers configure service and replenishment protocols differently across product formats, with spray systems requiring technical training support while gel formats emphasize consumer education. Segmentation reveals how formulation chemistry and application setting jointly determine margin architecture and regulatory burden distribution.
Product Type:
After-sales service intensity varies sharply across formats, with professional-grade spray equipment demanding calibration support and clinical training programs that gel and film formats rarely require.
- Sprays:Aerosolized or pump-dispensed cyanoacrylate formulations polymerize rapidly across irregular wound geometries. Demand concentrates in hospital outpatient departments and professional sports medicine facilities where uniform coverage speed reduces nursing labor allocation per procedure.
- Gels:Viscous monomer preparations enable controlled application with reduced overspray risk to mucous membranes. Home care settings in the United States drive category expansion as pharmacist recommendation algorithms elevate visibility in CVS, Walgreens, and Rite Aid networks.
- Creams:Lower-viscosity emulsified formulations suit superficial abrasions and pediatric applications where gentle spreading action matters.
- Films:Ultra-thin polymer layers cure to near-invisible barriers; cosmetic and pediatric segments command premium positioning for appearance-conscious consumers.
Sprays hold the largest share; momentum sits with gels as pharmacy channel algorithms reshape home care procurement.
Application:
Cost tier differentiation separates acute institutional procedures from routine consumer self-treatment, with surgical and burn applications bearing full regulatory validation costs that abrasion management avoids.
- Wound Care:General-purpose sealant applications span acute traumatic injuries to chronic ulcer management. Hospital wound care centers in the United States specify antimicrobial-loaded matrices that integrate silver-ion complexes directly into polymerization reactions.
- Surgical Sites:Post-operative incision sealing demands ISO 10993 biocompatibility documentation and FDA 510(k) clearance with extended dermal sensitization testing protocols. Professional team facilities and ambulatory surgery centers drive procurement volume.
- Burns:Partial-thickness thermal injury coverage requires breathable, flexible films that accommodate edema progression without delamination.
- Abrasions:Superficial skin injuries represent the highest-volume, lowest-margin segment where traditional adhesive bandage substitution constrains premium liquid bandage penetration in emerging market retail pharmacies.
Wound care commands the broadest installed base; surgical sites are climbing the fastest as outpatient procedure volumes expand.
End User:
Customer type determines purchasing authority structure, with hospital procurement committees negotiating multi-year supply agreements that home care consumers cannot replicate.
- Hospitals:Integrated delivery networks and purchasing coalitions govern formulary decisions for surgical-grade formulations. 3M sustains volume leadership through decades-long institutional relationships with these procurement bodies.
- Clinics:Sports medicine clinics represent an expanding segment as athletic injury protocols prioritize rapid wound closure to minimize training disruption.
- Home Care:Self-administered applications dominate this segment, with telemedicine wound care platforms now validating liquid bandage protocols for chronic wound patients.
- Pharmacies:Consolidated retail chains concentrate purchasing leverage among three national buyers, with shelf placement algorithms displacing manufacturer trade promotion spending.
Hospitals retain the largest procurement volume; home care is gaining share fastest through direct-to-consumer channel expansion.
Distribution Channel:
Supply concentration differs by channel, with medical supply distributors maintaining regional warehouse networks that online pure-plays have not replicated for temperature-sensitive formulations.
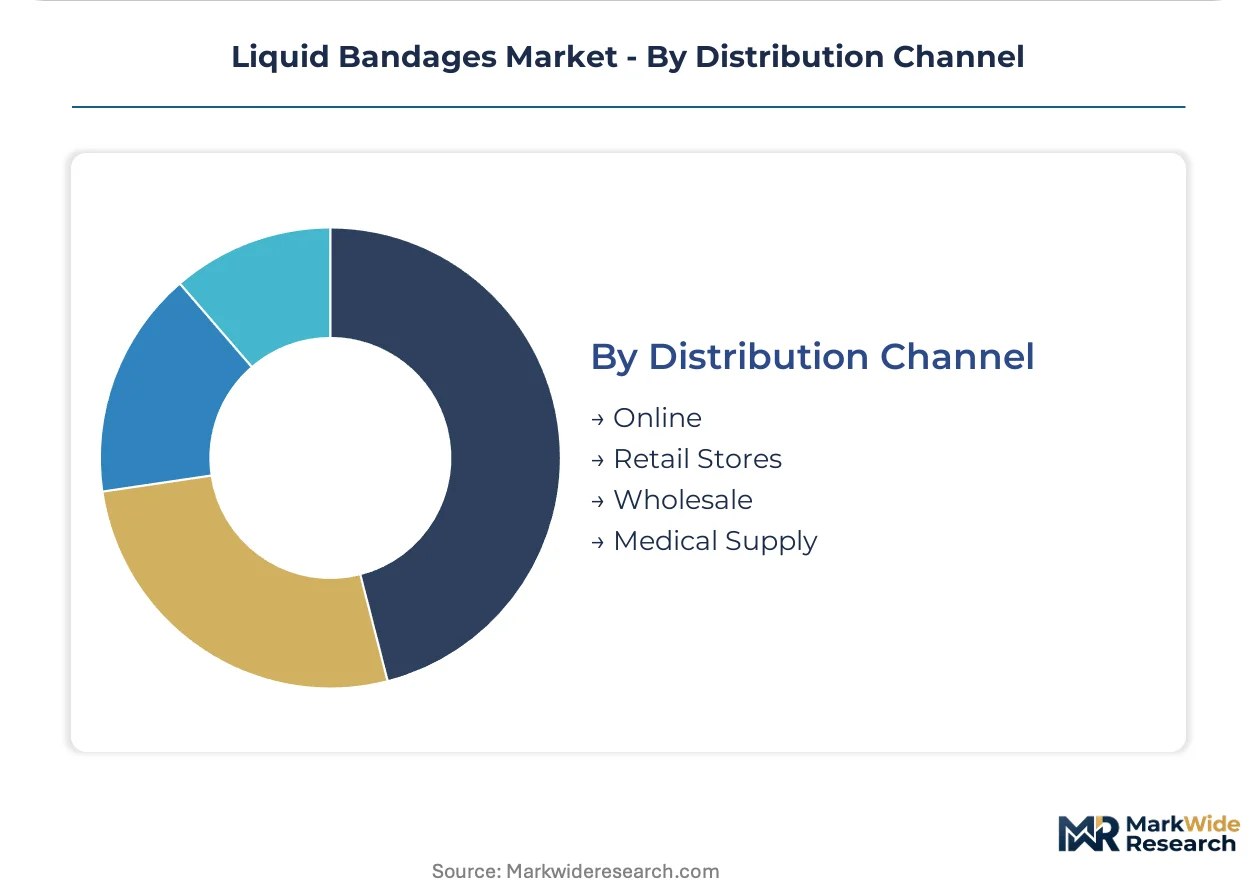
- Online:E-commerce platforms capture replenishment purchases from chronic wound patients and subscription-based telemedicine integrations.
- Retail Stores:Physical pharmacy networks remain dominant for acute need fulfillment, with independent community pharmacies retaining residual influence in rural United States catchment areas.
- Wholesale:Institutional procurement flows through medical supply distributors serving hospital purchasing coalitions.
- Medical Supply:Specialized distributors handle surgical-grade formulations requiring cold chain integrity and lot traceability documentation.
Retail stores maintain the largest share; online channels show the steepest expansion trajectory as telemedicine protocols normalize remote wound management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA scrutiny of cyanoacrylate dermal sensitization anchors the United States as the regulatory benchmark geography, with procurement patterns in this market cascading into formulation standards adopted elsewhere.
United States
Direct-to-consumer pharmacy channels and specialized wound care centers concentrate demand for liquid bandages, with CVS, Walgreens, and Rite Aid algorithms governing category visibility. FDA 510(k) clearance pathways with extended dermal sensitization testing now lengthen premarket timelines by 12-18 months. Greater Boston hosts contract research organizations conducting biocompatibility validation for surgical-grade formulations.
Germany
Hospital purchasing coalitions and ambulatory surgery centers drive institutional procurement of ISO 10993-compliant sealants. REACH substance restriction proposals for residual formaldehyde force alternative stabilizer chemistry validation before 2026 sunset deadlines. Baden-Württemberg polymer chemistry clusters supply medical-grade cyanoacrylate feedstock to European formulators.
China
NMPA medical device registration reforms accelerate market entry for biocompatible wound sealants in tier-one hospital systems. GB standards for medical adhesives tighten testing protocols for cyanoacrylate-based products. Yangtze River Delta chemical manufacturing zones concentrate n-butyl cyanoacrylate monomer production, exposing supply chains to shipping cost volatility.
Japan
PMDA quality management system inspections prioritize dermal sensitization documentation for imported liquid bandage devices. METI industrial standards harmonization facilitates cross-recognition of ISO 10993 testing data. Kanto region medical device distributors maintain cold chain networks for temperature-sensitive spray formulations.
United Kingdom
Telemedicine wound care platforms validate self-applied liquid bandage protocols for chronic wound patients in National Health Service pilot programs. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR Class IIa reclassification thresholds. London-based procurement consortia negotiate multi-year supply agreements for surgical-grade formulations.
Liquid Bandages Market Competitive Landscape
Institutional suppliers and consumer health specialists split the market between surgical-grade procurement channels and retail pharmacy networks. Three strategic archetypes dominate: diversified medical device conglomerates with hospital purchasing coalition relationships, consumer health pure-plays with pharmacy shelf presence, and specialty adhesive chemists with polymer platform expertise. Competitive moves concentrate on M&A to secure notified body approvals and geographic expansion through distributor partnerships.
Within the diversified conglomerate tier, 3M and Johnson & Johnson exemplify archetypes leveraging institutional relationships and retail shelf dominance respectively. Chemence and Kobayashi.Co. occupy positions as specialty adhesive formulators with concentrated polymer chemistry capabilities. Mölnlycke Health Care and Smith & Nephew sit within the advanced wound care portfolio segment, representing European and UK-based medical device structuring.
| Leading Market Players |
|---|
| ConvaTec |
| Chemence |
| 3M |
| Mölnlycke Health Care |
| Advantice Health |
| Medline Industries |
| Kobayashi.Co. |
| Johnson & Johnson |
| Smith & Nephew |
| Others |
Supply & Pricing Matrix
Tariff exposure between East Asian monomer production zones and North American formulators compresses margin buffers across all pricing tiers while simultaneously forcing inventory positioning strategies that elongate working capital cycles. This structural cost pressure widens the spread between surgical-grade formulations and commodity alternatives as manufacturers pass through compliance and logistics burdens unevenly.
Pricing Analysis
The customization-premium spread separates FDA 510(k)-cleared surgical formulations from standard retail pharmacy offerings, with certification tier and after-sales service bundling as the primary price differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies around ISO 10993 biocompatibility documentation and clinical training inclusion. Cost compression in the economy tier intensifies because traditional adhesive bandage substitution constrains liquid bandage penetration in emerging market retail pharmacies. Home care consumers exhibit the highest price sensitivity, while hospital purchasing coalitions prioritize total procedure cost over unit price.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk management for n-butyl cyanoacrylate feedstock procurement. Manufacturing gravity centers on Yangtze River Delta chemical zones in China, with secondary concentration in Baden-Württemberg polymer clusters in Germany and Kanto region distributors in Japan. Raw material dependencies rest on medical-grade cyanoacrylate monomers, silver-ion antimicrobial additives, and aerosol propellant systems. Distribution runs through medical supply distributors maintaining cold chain integrity for temperature-sensitive spray formulations, supplemented by consolidated retail pharmacy networks for gel and film variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent liquid bandage manufacturers face sustained substitution pressure from low-cost fabric adhesive strips in emerging market pharmacies, requiring defensive repositioning around clinical efficacy documentation and channel control.
For Market Incumbents: Entrench hospital purchasing coalition relationships through multi-year supply agreements bundling clinical training and calibration support for spray equipment. Deepen backward integration into East Asian monomer supply through long-term offtake contracts or captive production partnerships to neutralize tariff volatility. FDA 510(k) pathway extensions for dermal sensitization testing represent the critical regulatory threat requiring preemptive dossier investment. For New Entrants and Emerging Players: Pediatric cosmetic applications in North American retail pharmacies represent the most penetrable entry point, where invisible film-forming variants command parental premium willingness and pharmacist recommendation algorithms elevate new brand visibility. Telemedicine wound care platform partnerships offer a direct-to-patient go-to-market angle bypassing consolidated retail buyer concentration. Sports medicine clinics in tier-one United States metropolitan areas present secondary white-space opportunity with lower regulatory burden than surgical-grade formulations. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors notified body-approved manufacturers with existing MDR technical documentation and ISO 10993 validation libraries. Long-term viability hinges on polymer chemistry platform ownership rather than formulation branding, positioning specialty adhesive chemists with concentrated R&D capabilities as attractive acquisition targets. Watch for EU REACH formaldehyde restriction enforcement timelines as the inflection signal indicating which European formulators have successfully navigated alternative stabilizer chemistry transitions.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Update | REACH formaldehyde restrictions force notified body queue positioning before 2026 sunset deadlines. |
| Hospital Purchasing Coalition Partnership | Integrated delivery network formulary inclusion secures multi-year surgical-grade volume commitments. |
| Telemedicine Platform Integration | Remote wound care validation opens subscription replenishment channels for chronic patient segments. |
| Antimicrobial Polymer Platform Extension | Silver-ion matrix formulations collapse separate antiseptic application steps in outpatient protocols. |
| East Asian Monomer Supply Agreement | Long-term offtake contracts neutralize tariff exposure and shipping cost volatility from Yangtze River Delta production. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, sports medicine clinicians, retail pharmacy category buyers, and polymer chemistry R&D directors and refined through secondary validation against FDA 510(k) clearance databases, ISO 10993 biocompatibility test registries, hospital GPO contract filings, and customs trade data for cyanoacrylate monomer flows. Bottom-up demand modeling across product formats, application settings, and end-user segments was triangulated with top-down market sizing from manufacturer revenue disclosures and distributor shipment records.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning spray-gel-cream-film formats, wound care-surgical site-burn-abrasion applications, and hospital-clinic-home care-pharmacy end users. CAGRs were derived from fitted growth curves incorporating FDA premarket timeline extensions, EU MDR reclassification implementation pacing, and telemedicine protocol adoption trajectories. Industry-specific inputs included pharmacist recommendation algorithm weighting factors and sports medicine clinic procurement cycle timing.
Practitioners should monitor FDA dermal sensitization guidance evolution, EU REACH substance restriction enforcement, and NMPA registration reform implementation for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Hemostats for Wound Closure Market
Wound Care
Global Active Wound Care Market
Wound Care
Wound Retractor Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Europe Wound Care Market
Wound Care
Chronic Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Global Compression Bandages Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Wound Management Market
Wound Care
North America Advanced Wound Care Market
Wound Care
US Wound Irrigation System Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market