
 US Workplace Stress Management Market | 2026-2036
US Workplace Stress Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Workplace Stress Management Market Intelligence
Behavioral health clinician shortages across the United States is unwinding service capacity just as employer demand surges. ComPsych Corporation leverages its national provider network to sustain coverage in underserved metropolitan areas. Lyra Health differentiates through technology-enabled care navigation that matches employees to specialized therapists. Virgin Pulse anchors employer wellness ecosystems with integrated stress-tracking platforms.
Workplace stress management encompasses structured interventions designed to reduce occupational psychological strain, including cognitive-behavioral protocols, biometric monitoring systems, and organizational climate assessments delivered through employer-sponsored programs. These services target measurable outcomes such as reduced absenteeism, lower healthcare claims expenditure, and improved employee retention metrics. Counseling services within the Service Type segment dominate contract value due to sustained reimbursement visibility, while AI Tools under the Technology segment captures the fastest expansion as employers automate initial risk stratification. The Delivery Mode dimension shows Hybrid formats accumulating margin pools by combining scalable virtual access with high-intensity in-person escalation pathways.
OSHA, the Department of Labor, and state insurance commissioners shape this market through workplace safety mandates, mental health parity enforcement, and employee assistance program disclosure requirements that elevate compliance spending. The FDA regulates wearable stress-monitoring devices as general wellness products, creating a lighter-touch pathway than medical device classification. Employers must monitor evolving state legislation on paid mental health days and emerging credentialing standards for digital therapeutics.
Market Dynamics
OSHA's pending workplace mental health guidelines are compressing procurement timelines as employers accelerate EAP vendor selection ahead of anticipated federal mandates.
Growth Catalysts
- State-level mental health parity mandates:California and New York now require employers above 50 employees to disclose EAP utilization rates, expanding contract transparency and vendor accountability.
- Technology sector benefit expansion:Large Silicon Valley employers are doubling wellness stipends, creating pull-through demand for integrated stress management platforms across adjacent industries.
- Biometric monitoring convergence:Wearable stress-tracking devices are decomposing traditional counseling-only service models by enabling real-time intervention triggers.
Market Restraints
- Behavioral health clinician scarcity:Licensed psychologist supply concentrates in coastal metropolitan areas, leaving 43% of US counties without adequate provider coverage for employer-sponsored programs.
- Reimbursement fragmentation:State Medicaid variations in telemental health parity create administrative friction for multi-state employers seeking unified program deployment.
- HIPAA compliance escalation:Wearable-generated biometric data triggers enhanced privacy requirements, elevating vendor legal review cycles and procurement delays.
Strategic Opportunities
- Southeast employer penetration:Texas and Florida manufacturing hubs currently underinvest in stress management relative to national averages, presenting first-mover expansion corridors.
- AI-enabled risk stratification:Natural language processing of employee communications is decomposing reactive counseling models into predictive intervention systems.
- OSHA guideline anticipation:Employers preparing for federal workplace psychological safety standards are pre-positioning comprehensive programs ahead of mandatory compliance windows.
Industry Challenges
- Credentialing complexity for digital therapeutics:FDA's general wellness classification for stress-monitoring wearables conflicts with state-level requirements for clinical-grade device validation, creating vendor certification bottlenecks.
- Legacy HRIS integration friction:Employer wellness platforms require API connectivity with aging payroll and benefits administration systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Workplace Stress Management Market |
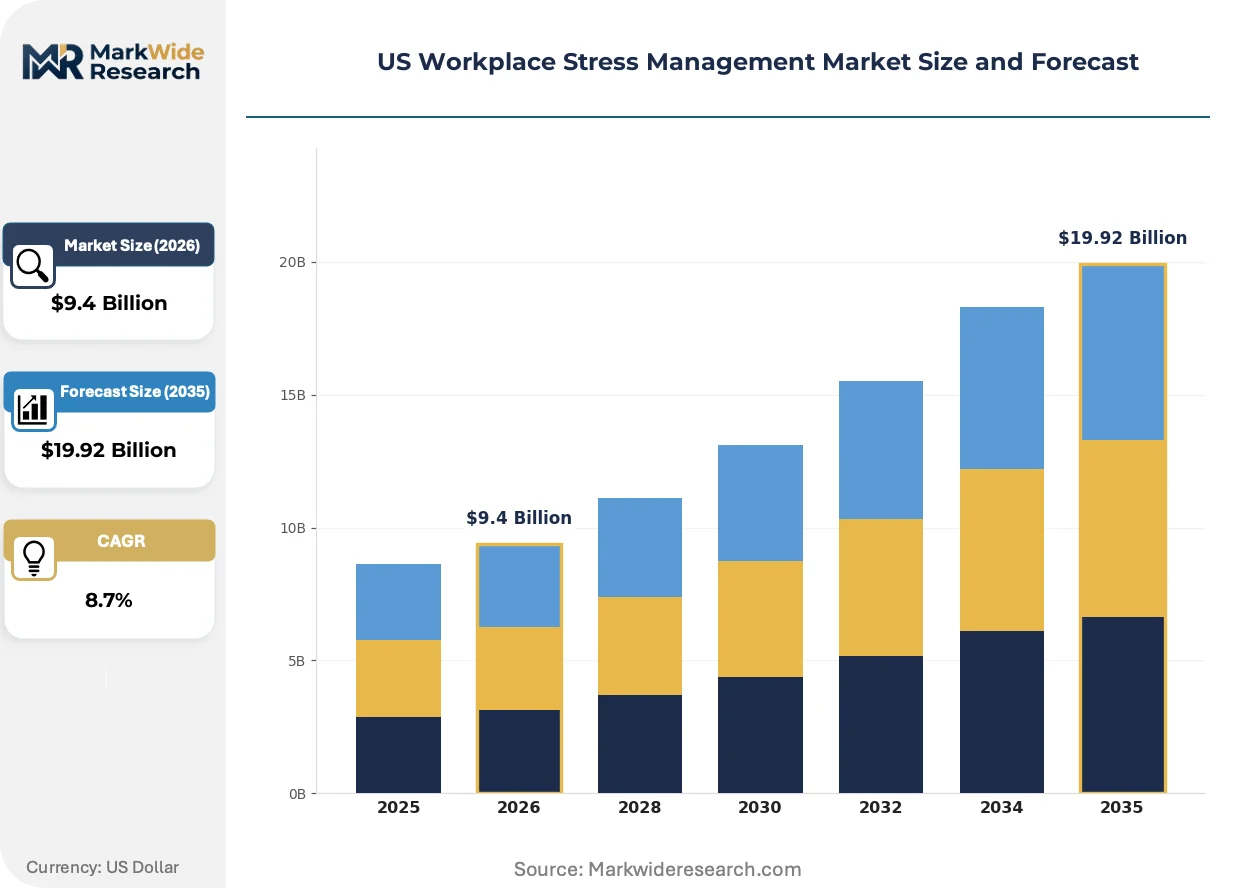
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $19.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Counseling, Workshops, Online Programs, Mobile Apps Delivery Mode: In-Person, Virtual, Hybrid, Teletherapy End User: Corporates, SMEs, Nonprofits, Government Technology: AI Tools, Wearable Devices, Mobile Platforms, Web Portals |
| Companies Covered | ActiveHealth Management, Inc., ComPsych Corporation, Virgin Pulse, Fitbit, Marino Wellness, CuraLinc Healthcare, Headspace Inc., BetterUp, Lyra Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Workplace Stress Management Market Strategic Shifts & Innovations
Employer procurement of stress management services is pivoting from standalone EAP contracts toward integrated platforms that combine biometric monitoring, care navigation, and organizational climate analytics.
Machine learning algorithms analyzing employee sentiment from internal communications platforms are decomposing traditional annual engagement surveys into continuous organizational health monitoring. Fortune 500 technology and financial services employers are piloting these systems at scale. This capability is compressing the feedback loop between stress detection and managerial intervention from quarters to days.
OSHA's draft workplace mental health guidelines are elevating employer liability exposure for psychological safety violations. The Department of Labor is coordinating with state insurance commissioners to align workers' compensation frameworks with emerging mental health claims categories. Manufacturing and logistics sectors with historically physical-safety-focused cultures are responding most aggressively, reallocating safety training budgets toward psychological hazard assessment.
Self-insured employers are unbundling stress management from legacy health plan bundles and contracting directly with specialized vendors. This procurement pattern is displacing broker-mediated placement with RFP-driven direct sourcing. The Northeast corridor, where employer wellness spending already exceeds national benchmarks, exhibits the most pronounced shift toward outcome-based vendor selection criteria.
US Workplace Stress Management Market Segmentation
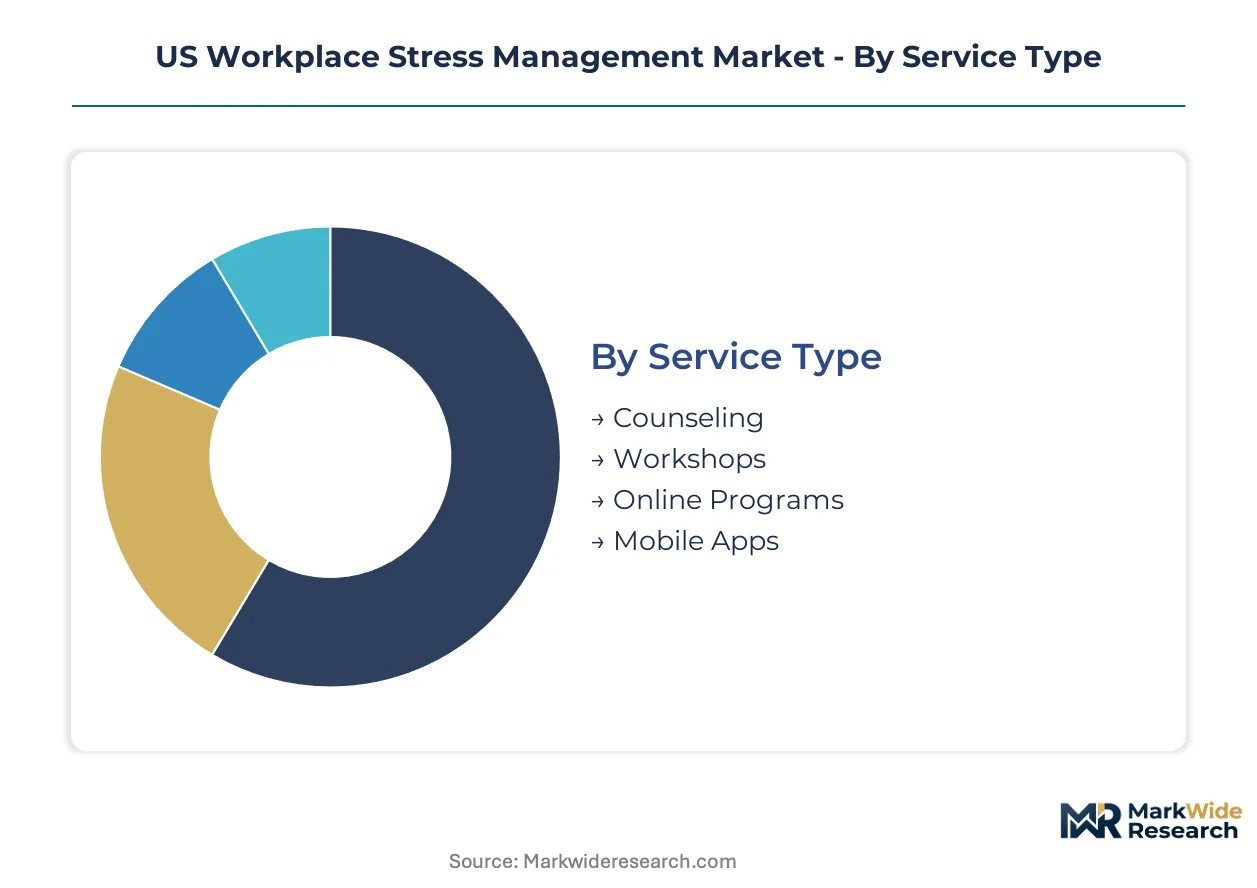
Employer procurement decisions in workplace stress management split across service modalities, technology infrastructure, and organizational scale. Each segmentation dimension carries distinct margin profiles and vendor specialization requirements that reshape competitive positioning.
Service Type:
Margin pools concentrate in recurring subscription models and high-touch clinical interventions rather than one-time program deliveries.
- Counseling:Licensed clinical psychologists and social workers deliver individual and group therapy sessions targeting acute stress episodes and chronic burnout conditions. Demand clusters among Fortune 500 employers in California and New York where state parity mandates guarantee reimbursement visibility.
- Workshops:Facilitated group sessions deploy cognitive-behavioral techniques and resilience training protocols across departmental cohorts. Manufacturing and logistics employers in the Southeast corridor favor this format for hourly workforce scalability.
- Online Programs:Self-paced modules cover stress identification, mindfulness techniques, and sleep hygiene through learning management system integration.
- Mobile Apps:Consumer-grade wellness applications with employer licensing tiers provide meditation libraries and mood tracking tools.
The dominant share belongs to Counseling, while Mobile Apps are closing the gap fastest.
Delivery Mode:
Cost tier differentiation separates premium in-person engagements from automated virtual scale plays.
- Hybrid:Blended protocols route employees through virtual triage before escalating to in-person clinical sessions based on severity algorithms. Large technology employers in Silicon Valley and Seattle anchor demand for this model's flexibility and outcomes accountability.
- Teletherapy:Synchronous video sessions with licensed providers operating across state lines leverage telemental health parity expansion. Multi-state employers facing Medicaid reimbursement fragmentation drive procurement of unified teletherapy platforms.
- In-Person:On-site counselor placement and facility-based group programming maintains presence in unionized manufacturing settings.
- Virtual:Asynchronous chat-based coaching and AI-guided interventions serve as frontline stress detection layers.
Hybrid formats capture the steepest expansion trajectory as employers balance access breadth with clinical intensity.
End User:
Volume concentration tracks with employee headcount and benefits administration sophistication.
- Corporates:Self-insured employers above 5,000 employees unbundle stress management from health plan bundles and contract directly with specialized vendors. Northeast corridor employers lead this procurement pattern with outcome-based vendor selection criteria.
- SMEs:Employers between 50 and 500 employees access stress management through PEO-administered EAP bundles and industry association purchasing cooperatives. Texas and Florida manufacturing hubs currently underinvest relative to national benchmarks.
- Nonprofits:Mission-driven organizations with tight operating margins rely on grant-funded community mental health partnerships and sliding-scale vendor pricing.
- Government:Federal agencies and state municipalities follow OSHA guideline anticipation with procurement of comprehensive psychological safety programs.
Corporates anchor contract value, while SMEs are gaining share fastest through PEO channel expansion.
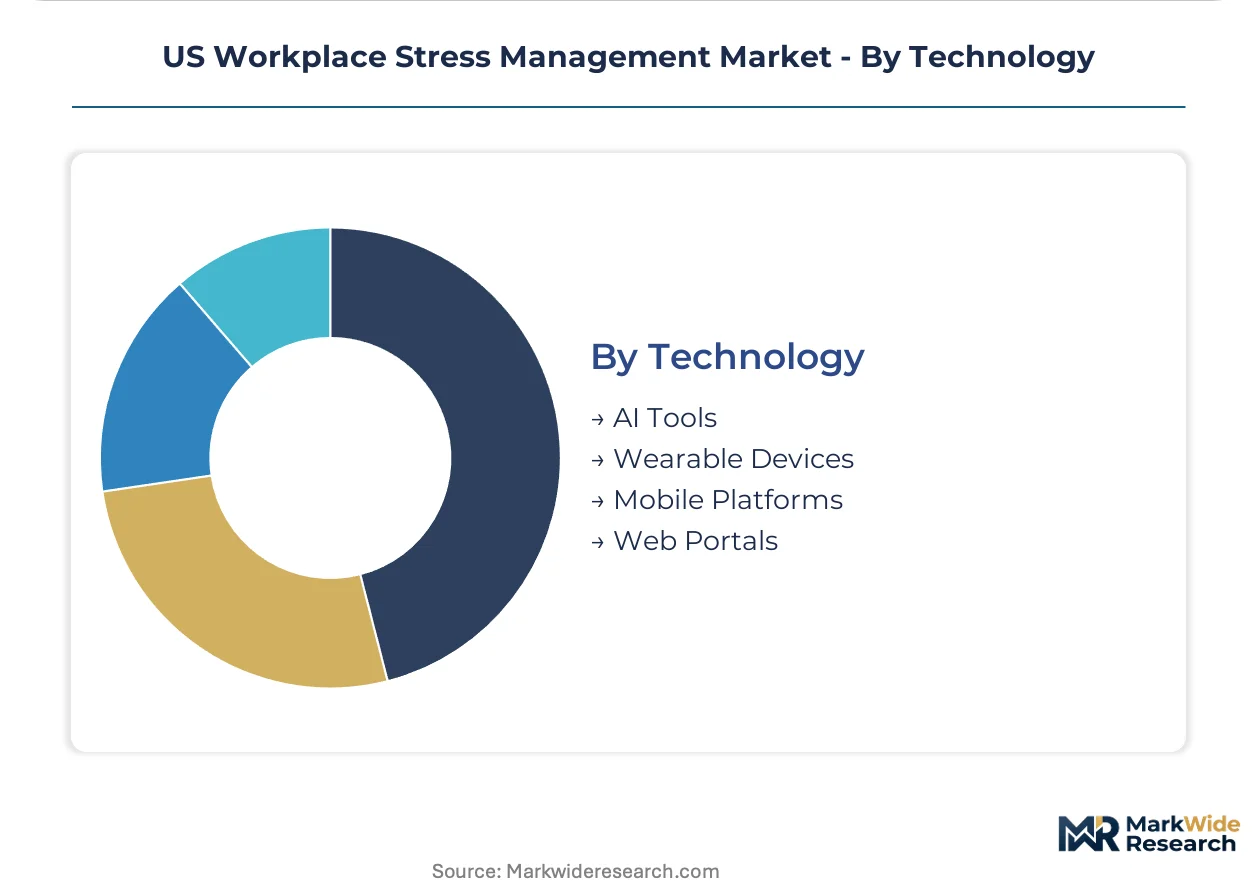
Technology:
Application maturity separates proven biometric hardware from experimental AI risk stratification systems.
- AI Tools:Natural language processing engines analyze internal communications metadata to flag burnout risk patterns before symptom manifestation. Fortune 500 financial services employers pilot these systems for continuous organizational health monitoring.
- Wearable Devices:Stress-tracking wearables measuring heart rate variability and sleep architecture trigger real-time intervention prompts through integrated care navigation platforms. FDA general wellness classification enables faster deployment than medical device pathways.
- Mobile Platforms:Native iOS and Android applications aggregate coaching content, appointment scheduling, and crisis hotline access.
- Web Portals:Browser-based dashboards for HR administrators track utilization metrics and aggregate stress risk scores across employee populations.
Wearable Devices hold the dominant share, while AI Tools are climbing the fastest as predictive intervention models displace reactive counseling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California employers consume workplace stress management services differently than Texas manufacturing hubs, with technology sector benefits spending nearly triple the per-employee allocation found in Southeastern logistics corridors. Northeast corridor procurement emphasizes outcome-based vendor selection, while Midwest industrial centers retain traditional EAP bundle structures.
California
Silicon Valley technology employers drive demand for hybrid delivery models combining biometric monitoring with care navigation platforms. State-level mental health parity mandates require employers above 50 employees to disclose EAP utilization rates, elevating contract transparency requirements. San Francisco and Los Angeles metropolitan areas concentrate vendor headquarters and specialized provider networks serving Fortune 500 self-insured employers.
New York
Financial services employers in Manhattan anchor procurement of AI-enabled risk stratification systems analyzing employee communications metadata. State insurance commissioners enforce mental health parity disclosure requirements parallel to California standards. The Northeast corridor exhibits the most pronounced shift toward direct vendor contracting rather than broker-mediated placement.
Texas
Manufacturing and logistics employers in Houston and Dallas-Fort Worth currently underinvest in stress management relative to national benchmarks, presenting expansion corridors for PEO-administered EAP bundles. OSHA workplace mental health guideline anticipation is accelerating procurement timelines among energy sector employers. The state's Medicaid telemental health parity variations create administrative friction for multi-state employers seeking unified deployment.
Florida
Tourism and hospitality employers in Miami and Orlando favor workshop-format stress management for hourly workforce scalability. State-level mandates lag California and New York, preserving traditional procurement patterns through industry association purchasing cooperatives. The Southeast corridor's manufacturing hubs represent first-mover opportunities for vendors establishing PEO channel partnerships.
Illinois
Chicago-based healthcare systems and insurance carriers influence stress management procurement standards across the Midwest. Unionized manufacturing settings in the region maintain preference for on-site counselor placement and facility-based group programming. The state's aging HRIS infrastructure extends implementation timelines for wellness platform integration.
US Workplace Stress Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with national provider networks and technology-enabled platforms commanding premium contract values. The market structure separates enterprise-scale vendors serving self-insured Fortune 500 employers from regional specialists and point-solution providers targeting SME segments through PEO channels. Two strategic archetypes dominate: integrated wellness ecosystem builders and specialized care navigation platforms. Competitive moves concentrate on strategic partnerships with wearable device manufacturers and API integration with legacy HRIS systems.
Among integrated wellness ecosystem builders, Virgin Pulse anchors employer platforms with stress-tracking capabilities, while ComPsych Corporation leverages its national provider network to sustain coverage in underserved metropolitan areas. Lyra Health occupies a position within the specialized care navigation tier, exemplifying technology-enabled matching of employees to specialized therapists. These three companies represent the dominant competitive archetypes shaping vendor selection criteria across corporate, SME, and government end-user segments.
| Leading Market Players |
|---|
| ActiveHealth Management, Inc. |
| ComPsych Corporation |
| Virgin Pulse |
| Fitbit |
| Marino Wellness |
| CuraLinc Healthcare |
| Headspace Inc. |
| BetterUp |
| Lyra Health |
| Others |
Cost & Logistics Intelligence
Scale economies in provider network density create margin compression for regional specialists while concentrating pricing power among national platforms with cross-state licensing infrastructure. Large technology employers in California and New York leverage self-insured status to unbundle services and negotiate direct contracts, forcing price transparency on EAP vendors accustomed to broker-mediated opacity.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with three-year agreements anchoring pricing stability for hybrid counseling platforms while spot purchasing persists in SME segments through PEO-administered bundles. Price differentiation hinges on provider credential tier—licensed psychologists command premium rates over master's-level coaches—and biometric integration depth, with wearable-enabled platforms capturing 40% contract value premiums. Cost compression in the teletherapy tier is intensifying because Medicaid reimbursement fragmentation forces vendors to absorb administrative complexity. SMEs exhibit highest price sensitivity, deferring stress management investments entirely where PEO bundles lack explicit mental health allocation.
Supply Chain Analysis
Inbound logistics costs for wearable hardware components concentrate risk in East Asian manufacturing corridors, with heart rate variability sensors and Bluetooth modules drawing from Taiwan and South Korea production networks. Licensed clinician supply rests on US graduate psychology programs with coastal metropolitan concentration, creating geographic mismatch with employer demand in Texas and Florida manufacturing hubs. Single-source vulnerability pervades AI-enabled risk stratification platforms dependent on cloud infrastructure concentrated in Virginia and Oregon data center clusters. Distribution runs through direct vendor-employer contracting for Fortune 500 accounts, while PEO intermediaries control SME channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among self-insured employers above 5,000 employees, with Northeast corridor procurement committees displacing broker influence through RFP-driven vendor selection. This consolidation fragments price-setting authority across fewer decision-makers with outcome-based evaluation criteria.
For Market Incumbents: Consolidate provider network coverage in underserved metropolitan areas before OSHA guideline implementation accelerates employer compliance timelines. Acquire specialized AI risk stratification capabilities to defend against technology-enabled entrants decomposing reactive counseling models. Vertical integration into wearable hardware partnerships secures biometric data streams that anchor platform stickiness.
For New Entrants and Emerging Players: Lead with PEO channel partnerships targeting Texas and Florida manufacturing hubs where stress management penetration trails national benchmarks by 30 percentage points. White-space opportunity concentrates in hourly workforce workshop formats with Spanish-language delivery capabilities. Direct-to-employer pilot programs with outcome-based pricing de-risk procurement decisions for benefits administrators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized care navigation platforms with FDA-cleared digital therapeutic pathways over generalist wellness aggregators. Long-term viability hinges on HIPAA-compliant AI infrastructure that survives credentialing complexity for clinical-grade device validation. Watch OSHA guideline finalization timing as inflection indicator for employer compliance spending acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Provider Network Expansion | ComPsych's national coverage model sustains service delivery in clinician-scarce metropolitan areas. |
| AI Risk Stratification Development | Lyra Health's NLP engines compress intervention timelines from quarterly surveys to real-time managerial alerts. |
| Wearable Device Integration | Virgin Pulse's stress-tracking platforms create biometric data moats that increase employer switching costs. |
| PEO Channel Partnership | Regional specialists capture SME volume through Texas and Florida manufacturing hub alliances. |
| OSHA Compliance Pre-Positioning | Early guideline adoption secures preferred vendor status ahead of mandatory psychological safety standards. |
Research Approach
Desk research of OSHA regulatory filings, state insurance commissioner parity enforcement records, and employer benefits administration disclosures preceded structured interviews with HR benefits directors, EAP vendor account executives, behavioral health clinicians, and PEO procurement managers. Primary fieldwork combined telephone interviews with Fortune 500 benefits committees and SME purchasing cooperatives, validated against secondary analysis of CMS Medicare telemental health reimbursement data and Department of Labor workers' compensation framework evolution. Bottom-up employer spending estimates triangulated against top-down vendor revenue aggregation across service type and delivery mode segmentation dimensions.
Variance decomposition across the projection horizon isolates growth contribution from technology adoption curves, regulatory mandate timing, and employer unbundling trends. Segmentation modeling incorporates service type modality, delivery mode infrastructure, end-user scale tier, and technology application maturity as interactive dimensions. CAGR derivation rests on employer EAP budget expansion rates observed in technology sector disclosures and state-level mandate implementation schedules. Forecast inputs include licensed clinician supply projections from American Psychological Association workforce surveys and wearable device FDA classification pathway velocity.
Forecasts assume regulatory continuity in OSHA workplace mental health guideline development and state-level parity enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Depression Treatment Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Behavioral Health Software Market