
 Agoraphobia Market | 2026-2036
Agoraphobia Market Size, Share, and Industry Trends Forecast 2026-2036
Agoraphobia Market Analysis
Specialized exposure therapy protocols with virtual reality augmentation is reorganizing competitive dynamics among pharmaceutical and therapeutic developers. Pfizer sustains dominant positions in selective serotonin reuptake inhibitor supply through extensive psychiatric distribution networks. Eli Lilly differentiates via dual-action antidepressant pipelines targeting comorbid panic and depressive symptoms. H. Lundbeck A/S specializes in European psychiatric markets with region-specific regulatory dossiers and prescriber education programs.
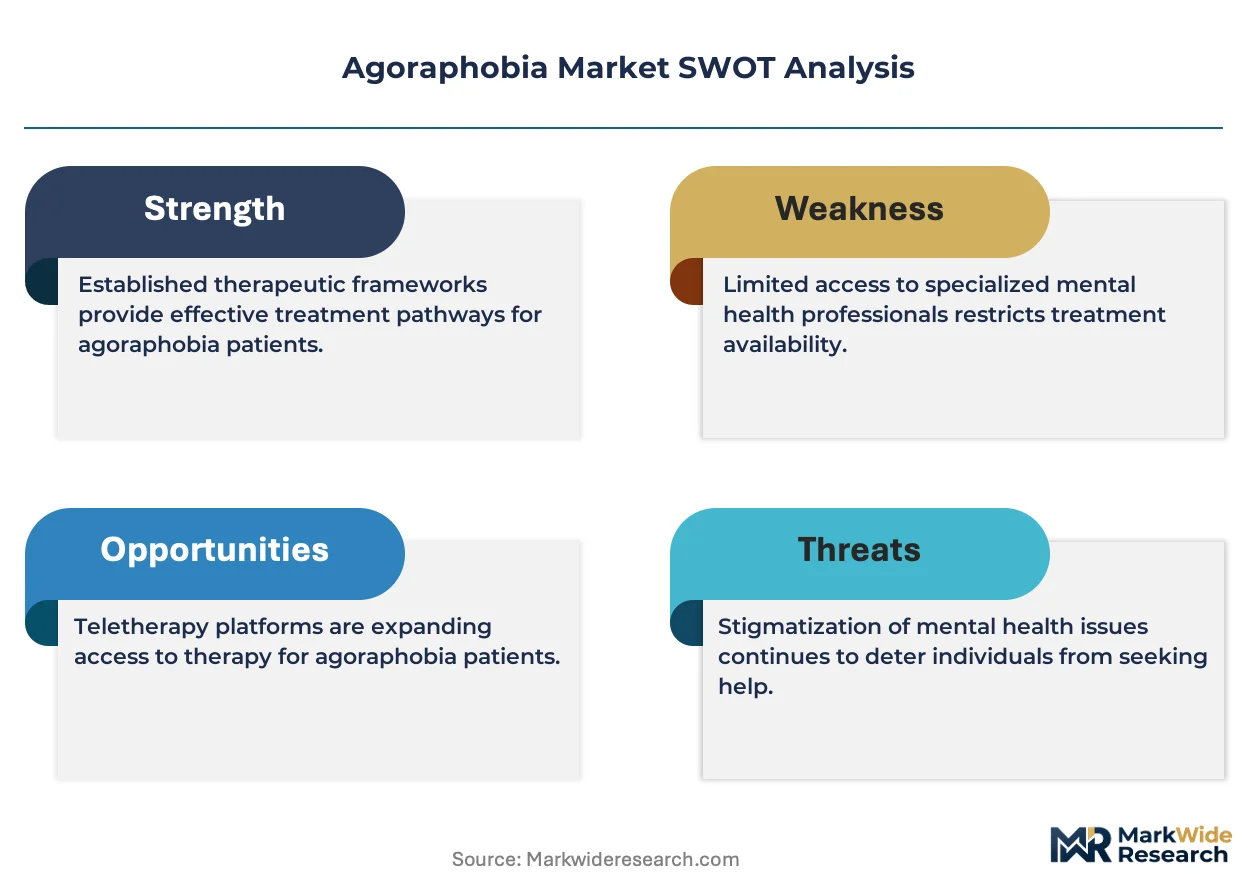
Agoraphobia constitutes a complex anxiety disorder characterized by marked fear or avoidance of situations where escape might prove difficult or help unavailable, with diagnostic criteria specifying symptom persistence exceeding six months and clinically significant functional impairment. Cognitive behavioral therapy and exposure therapy segments command the largest current revenue pools due to established reimbursement codes and proven efficacy profiles, while teletherapy represents the fastest-expanding treatment setting as asynchronous digital platforms reduce geographic and mobility barriers for patients. Medication management retains mature growth trajectories with generic SSRI commoditization, though novel rapid-onset anxiolytics are creating new margin pools in severe and chronic severity tiers.
The FDA's psychiatric drug review divisions and the European Medicines Agency's centralised procedure shape trial design requirements and commercialization timelines for novel agoraphobia therapeutics, while the UK's National Institute for Health and Care Excellence issues mandatory treatment guidelines that determine National Health Service formulary access. Stakeholders must monitor evolving digital therapeutics classification frameworks and reimbursement parity legislation across multiple jurisdictions to anticipate channel shifts between in-person and virtual care delivery models.
Market Dynamics
Virtual reality exposure therapy protocols are compressing traditional in-person cognitive behavioral therapy volumes while expanding addressable patient pools beyond geographic clinic density limits. This technological inflection is redistributing value capture between device manufacturers, software platforms, and licensed clinical networks.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's psychiatric drug review divisions have streamlined IND-to-NDA timelines for novel anxiolytics targeting treatment-resistant agoraphobia, compressing development cycles for sponsors with breakthrough therapy designations.
- Employer-Sponsored Mental Health Benefits:Large self-insured employers in the United States have expanded behavioral health carve-outs to include specialized anxiety disorder programs, creating direct-to-patient access channels outside traditional Medicaid gatekeeping.
- Teletherapy Platform Scale:Asynchronous digital therapeutic platforms have reduced mobility barriers for patients with severe avoidance symptoms, enabling treatment initiation rates previously inaccessible to brick-and-mortar psychiatric clinics.
Market Restraints
- Generic SSRI Commoditization:Patent expirations for fluoxetine, sertraline, and escitalopram have collapsed pricing power in first-line pharmacotherapy, constraining R&D reinvestment capacity for established psychiatric portfolios.
- Reimbursement Code Fragmentation:The Centers for Medicare and Medicaid Services maintains distinct billing codes for in-person versus virtual exposure therapy sessions, creating administrative friction that slows provider adoption of augmented reality protocols.
- Clinical Workforce Concentration:Licensed exposure therapists with virtual reality certification cluster in metropolitan academic medical centers, leaving rural and exurban patient populations dependent on generalist practitioners with limited anxiety specialization.
Strategic Opportunities
- Digital Therapeutics Reimbursement Parity:Pending legislation in multiple US states would mandate equivalent coverage for FDA-cleared prescription digital therapeutics, creating formulary access for software-based exposure protocols previously restricted to out-of-pocket payment.
- Pediatric and Adolescent Expansion:Current diagnostic criteria and therapeutic protocols concentrate on adult populations, leaving adolescent agoraphobia—a high-incidence, underdiagnosed segment—without developmentally adapted intervention frameworks.
- Biomarker-Guided Patient Stratification:Integration of heart rate variability monitoring and galvanic skin response sensors with exposure therapy platforms enables real-time arousal calibration, differentiating premium service tiers from standardized cognitive behavioral protocols.
Industry Challenges
- Virtual Reality Hardware Integration Complexity:Clinical workflows require seamless interoperability between head-mounted displays, physiological monitoring devices, and electronic health record systems, demanding specialized health informatics expertise scarce in community mental health settings.
- Cross-Jurisdictional Licensing for Teletherapy:Therapists delivering exposure therapy across state lines face conflicting professional licensure requirements that complicate staffing models for national virtual care platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agoraphobia Market |
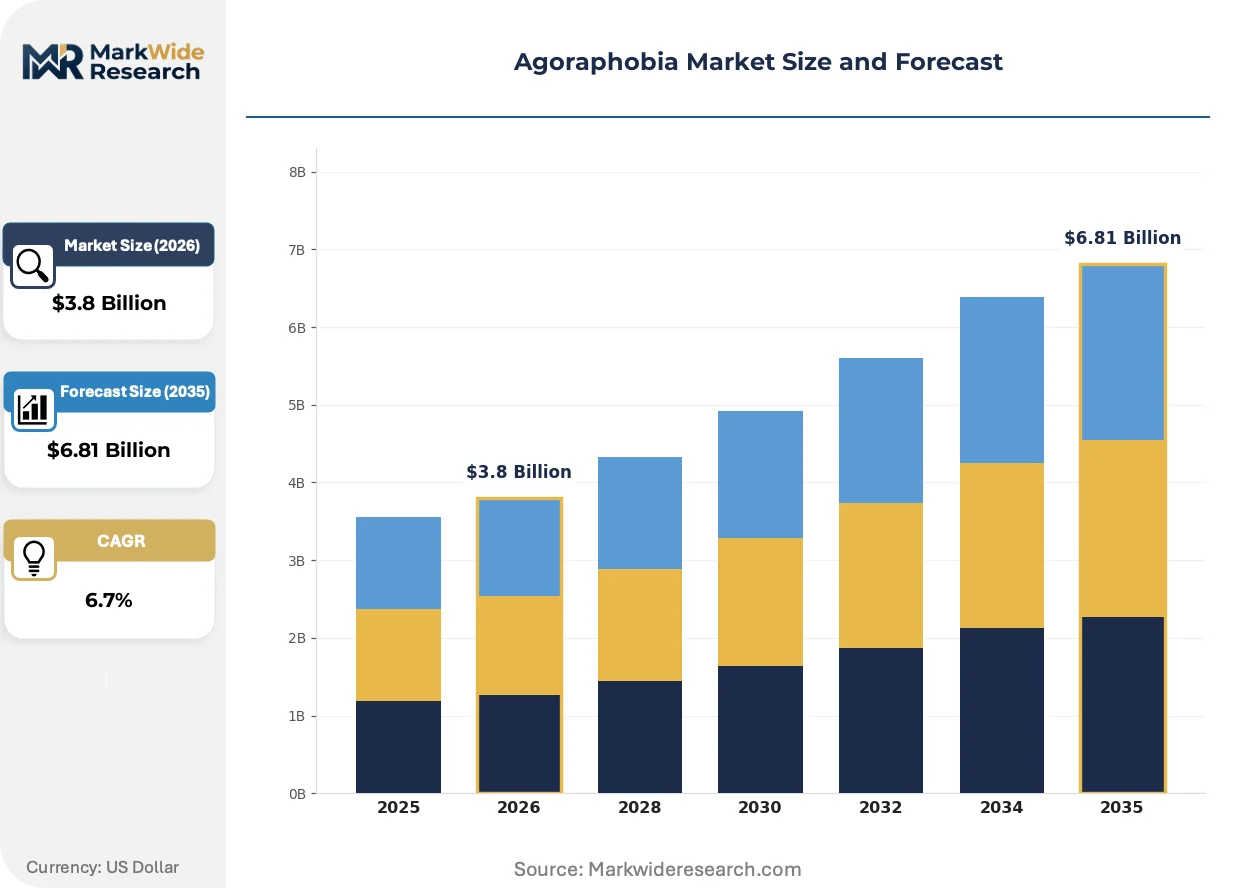
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cognitive Behavioral Therapy, Exposure Therapy, Medication Management, Support Groups Severity Level: Mild, Moderate, Severe, Chronic Age Group: Children, Adolescents, Adults, Seniors Treatment Setting: Outpatient, Inpatient, Teletherapy, Community Clinics |
| Companies Covered | Pfizer, Johnson & Johnson, Eli Lilly, F. Hoffmann-La Roche Ltd, Sanofi, Bristol-Myers Squibb, GlaxoSmithKline, H. Lundbeck A/S, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agoraphobia Market Emerging Trajectories
Immersive technology deployment and regulatory classification frameworks are actively restructuring how agoraphobia interventions are developed, reimbursed, and delivered across clinical settings.
Virtual reality exposure therapy is bifurcating the traditional cognitive behavioral therapy market into hardware-enabled premium protocols and conventional in-person sessions. Academic medical centers and specialized anxiety clinics have adopted FDA-cleared VR systems at accelerated procurement cycles, compressing margins for standalone talk therapy providers while creating new device-software recurring revenue streams. The technology is bifurcating patient segmentation into severity tiers, with immersive platforms capturing moderate-to-severe cases and conventional methods retaining mild symptom presentations.
The European Medicines Agency's centralised procedure for orphan drug incentives has redirected psychiatric development portfolios toward rare disease adjacencies, including severe treatment-resistant anxiety phenotypes. This regulatory tailwind compresses commercialization timelines for novel mechanisms while mandating pediatric investigation plans that extend development costs. Small-cap biotech sponsors with European headquarters have reorganized trial design strategies to exploit these incentives, shifting comparator standards and endpoint selection toward EMA-preferred methodologies.
Patients with agoraphobia have demonstrated elevated preference for asynchronous digital engagement models that eliminate real-time scheduling constraints and transportation requirements. This behavioral pivot has disrupted traditional outpatient psychiatric clinic volume patterns, with platform-based care capturing initial consultations and medication management that previously required in-person evaluation. The shift is most visible in United States metropolitan markets with dense telehealth infrastructure and employer-sponsored benefit designs that de-emphasize network restrictions.
Agoraphobia Market Segmentation
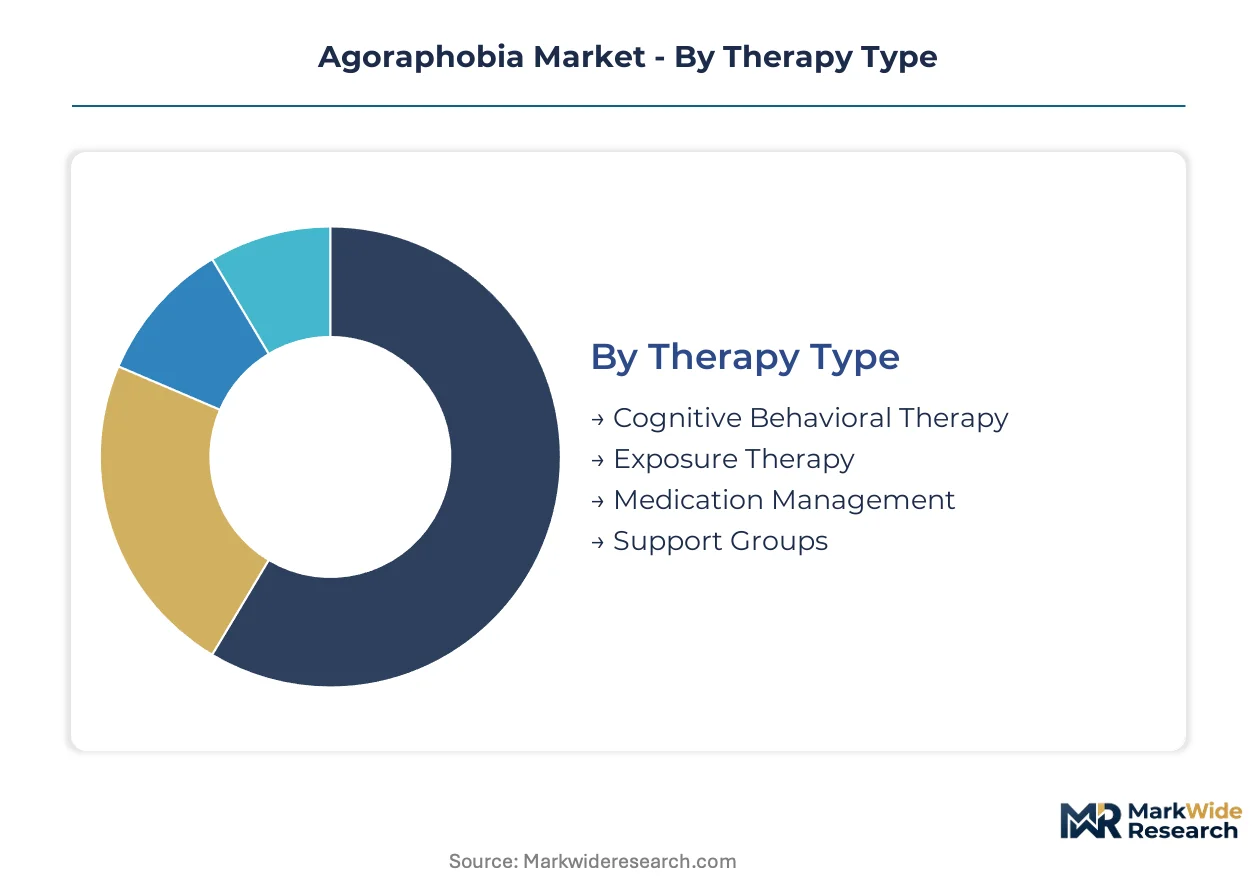
Therapy modality selection in agoraphobia treatment follows severity gradients and patient mobility constraints, with reimbursement codes and technology access reshaping how interventions distribute across clinical settings. Segmentation clarity enables stakeholders to align development pipelines with addressable patient pools and regulatory pathways.
Therapy Type:
Virtual reality platforms and digital therapeutics are intensifying substitution pressure on conventional pharmacotherapy and in-person modalities, compressing market share for legacy approaches while expanding premium service tiers.
- Cognitive Behavioral Therapy:Structured psychotherapy protocols targeting maladaptive thought patterns and avoidance behaviors through systematic cognitive restructuring. Demand concentrates in United States metropolitan markets with dense licensed psychologist networks and employer-sponsored behavioral health carve-outs, though workforce scarcity limits rural penetration.
- Exposure Therapy:Graduated confrontation with feared situations or stimuli, increasingly delivered via FDA-cleared virtual reality systems that enable controlled environment simulation. United States academic medical centers and specialized anxiety clinics in Germany and the United Kingdom have accelerated procurement of immersive hardware, capturing moderate-to-severe cases previously dependent on in vivo protocols.
- Medication Management:Pharmacological intervention dominated by generic selective serotonin reuptake inhibitors with collapsed pricing power. Prescription volumes remain substantial in Medicaid-dependent populations and regions with limited psychotherapy access.
- Support Groups:Peer-facilitated or clinician-guided group interventions, predominantly community-based with minimal reimbursement infrastructure. Digital platforms have expanded reach for homebound patients.
Cognitive Behavioral Therapy anchors the volume base while Exposure Therapy gains share at the steepest rate.
Severity Level:
Clinical trial design and regulatory endpoints stratify sharply across severity tiers, with FDA breakthrough therapy designations concentrating on treatment-resistant phenotypes that command premium pricing and accelerated review timelines.
- Mild:Subclinical functional impairment with situational avoidance limited to specific contexts. Self-directed digital interventions and primary care brief counseling capture this tier with minimal specialist involvement.
- Moderate:Significant interference with occupational or social functioning requiring structured intervention. United States integrated care networks and United Kingdom National Health Service stepped-care protocols route these patients to outpatient cognitive behavioral therapy with measurable outcome requirements.
- Severe:Substantial restriction of daily activities and frequent panic attacks. Academic medical centers in Boston, London, and Munich have developed specialized intensive outpatient programs combining pharmacotherapy and immersive exposure protocols.
- Chronic:Persistent symptoms exceeding five years with multiple treatment failures. European Medicines Agency orphan drug incentives have redirected biotech development toward this underserved tier with novel rapid-onset anxiolytic mechanisms.
Moderate severity anchors the volume base while Severe cases command the highest per-patient revenue and fastest regulatory pathway access.
Age Group:
Developmental adaptation requirements and pediatric investigation plan mandates from EMA and FDA reshape trial economics and commercialization timelines across age strata.
- Children:Pre-pubertal presentations requiring family-system intervention models and school-based accommodation protocols. Diagnostic complexity and parental involvement constraints limit specialized service availability.
- Adolescents:High-incidence segment with emerging social and academic functional demands. United Kingdom National Institute for Health and Care Excellence guidelines have mandated adapted cognitive behavioral protocols, though workforce training lags.
- Adults:Primary revenue pool with established reimbursement codes and workforce capacity. United States commercial insurance and employer-sponsored benefits drive treatment initiation in this demographic.
- Seniors:Underdiagnosed presentations frequently comorbid with cardiovascular conditions and polypharmacy. Medicare billing codes for anxiety disorder treatment have expanded, though geriatric psychiatry workforce scarcity constrains access.
Adults anchor the volume base while Adolescents represent the most significant unmet need with developmentally adapted protocol gaps.
Treatment Setting:
Channel economics diverge sharply between capital-intensive inpatient units and scalable asynchronous platforms, with reimbursement parity legislation determining relative growth trajectories across United States state jurisdictions.
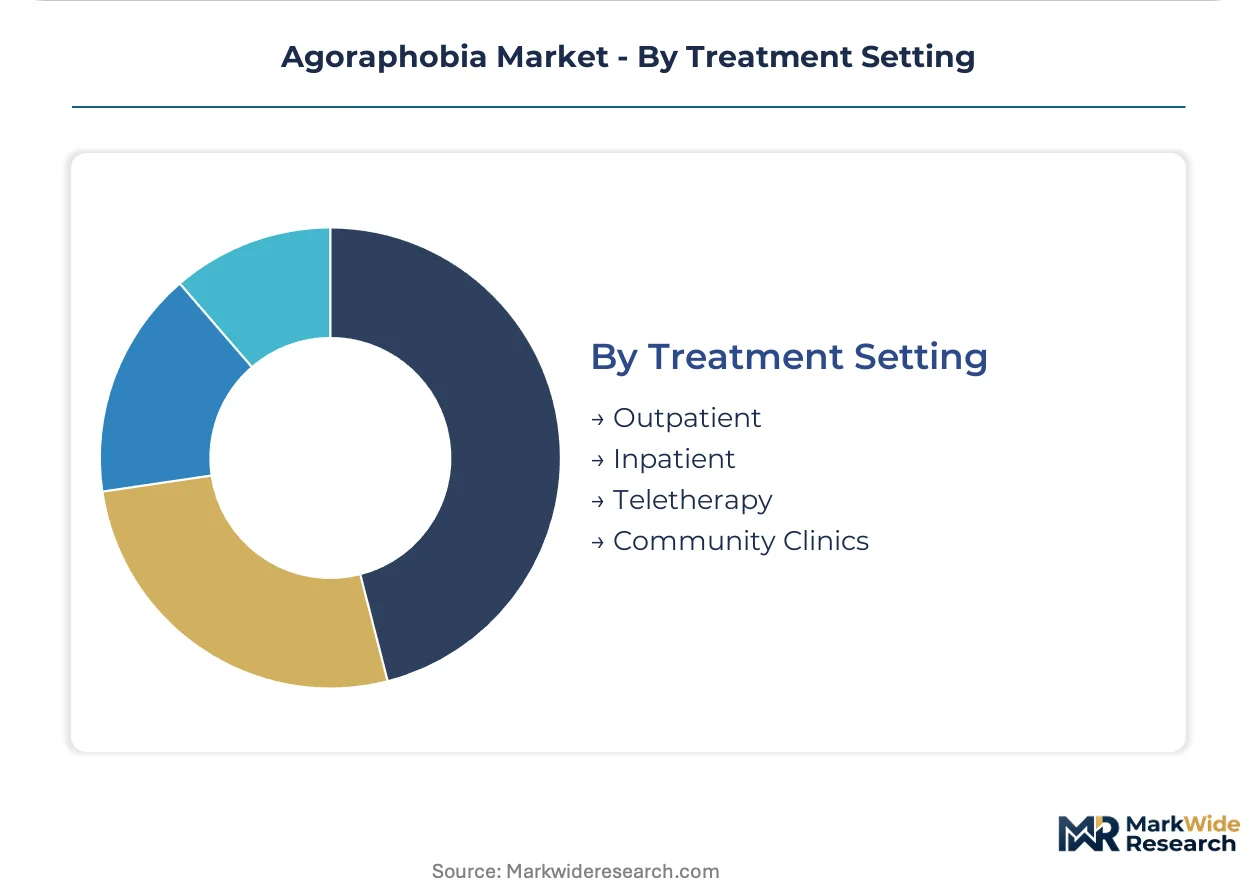
- Outpatient:Traditional brick-and-mortar psychiatric and psychology clinics with established CPT billing infrastructure. Volume concentration in urban United States markets and Western European capitals with dense specialist networks.
- Inpatient:Residential and partial hospitalization programs for crisis stabilization and severe functional impairment. High per-episode costs limit utilization to commercial insurance populations and public sector commitment criteria.
- Teletherapy:Synchronous video and asynchronous digital platforms eliminating transportation barriers. United States venture-backed platforms have scaled rapidly, though cross-state licensure constraints complicate staffing models.
- Community Clinics:Federally qualified health centers and nonprofit providers serving Medicaid and uninsured populations. Funding dependence on state behavioral health allocations creates geographic variability.
Outpatient settings anchor the volume base while Teletherapy climbs the fastest as asynchronous platforms reduce geographic and mobility barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based pharmaceutical developers export anxiety disorder therapeutics to Germany, the United Kingdom, and Japan, establishing transatlantic and transpacific trade corridors for novel anxiolytic compounds and digital therapeutic platforms.
United States
Integrated care networks in Boston and New York City drive demand for exposure therapy protocols with virtual reality augmentation. FDA breakthrough therapy designations compress IND-to-NDA timelines for sponsors targeting treatment-resistant agoraphobia. Academic medical centers in California and Massachusetts have accelerated procurement of FDA-cleared immersive hardware systems.
Germany
Specialized anxiety clinics in Munich and Hamburg expand outpatient cognitive behavioral therapy programs with employer-sponsored mental health benefits. The EMA centralised procedure shapes trial design requirements for novel psychiatric therapeutics entering European markets. Bavaria hosts the highest concentration of virtual reality-certified exposure therapists outside metropolitan United States markets.
United Kingdom
National Health Service stepped-care protocols route moderate agoraphobia cases to measurable outcome-based interventions. NICE issues mandatory treatment guidelines that determine formulary access for cognitive behavioral and exposure therapy modalities. London's academic medical centers collaborate with Oxford and Cambridge on biomarker-guided patient stratification research.
Japan
PMDA psychiatric drug review divisions maintain distinct requirements for anxiety disorder endpoints that diverge from FDA methodologies. METI funding programs support domestic development of digital therapeutics for mental health applications. Tokyo and Osaka concentrate specialized outpatient clinics with limited rural penetration due to clinical workforce scarcity.
Switzerland
Swissmedic regulatory frameworks attract biotech sponsors seeking European commercialization pathways with streamlined pediatric investigation plans. Geneva and Basel host clinical research organizations specializing in anxiety disorder trial design. The country's private insurance market enables premium pricing for novel rapid-onset anxiolytic mechanisms.
Agoraphobia Market Vendor Landscape
Listed leaders compete with private specialists across therapeutic modality and geographic coverage dimensions. The vendor base concentrates around three tiers: multinational pharmaceutical conglomerates with psychiatric distribution networks, mid-cap biotech developers with orphan drug incentives, and emerging digital therapeutic platforms with software-as-medical-device clearance. Competitive dynamics revolve around M&A activity for virtual reality exposure therapy assets and strategic partnerships between device manufacturers and licensed clinical networks.
Within the multinational pharmaceutical tier, Pfizer and Eli Lilly occupy positions shaped by extensive psychiatric distribution infrastructure and dual-action antidepressant pipelines respectively. H. Lundbeck A/S exemplifies the European specialist archetype with region-specific regulatory dossiers. These three entities represent contrasting approaches to agoraphobia market participation: volume-driven SSRI supply, differentiated mechanism development, and geographically focused prescriber education programs.
| Leading Market Players |
|---|
| Pfizer |
| Johnson & Johnson |
| Eli Lilly |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Bristol-Myers Squibb |
| GlaxoSmithKline |
| H. Lundbeck A/S |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
Virtual reality hardware substitution for conventional in-person therapy equipment simultaneously redistributes supply geography toward East Asian electronics manufacturing clusters and compresses pricing power for legacy cognitive behavioral therapy providers dependent on labor-intensive delivery models.
Pricing Analysis
Current-generation FDA-cleared VR exposure systems command premium positioning against prior-generation in vivo protocols and next-generation AI-augmented adaptive platforms still in clinical validation. Three-tier pricing structure across premium immersive systems, standard teletherapy subscriptions, and economy generic SSRI management dominates reimbursement landscapes. Price differentiation rests on certification tier (FDA breakthrough designation vs. 510(k) clearance) and geographic delivery cost (metropolitan academic centers vs. rural community clinics). Cost compression in standard-tier teletherapy is intensifying because venture-backed platforms compete for employer-sponsored benefit contracts. Medicaid-dependent populations exhibit highest price sensitivity; commercial insurance populations with behavioral health carve-outs demonstrate lowest sensitivity to out-of-pocket exposure.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Shanghai and Shenzhen to Long Beach and Rotterdam have extended lead times for head-mounted display procurement at United States academic medical centers. Geographic supply concentrates in China for VR hardware assembly, Taiwan for semiconductor components, and Germany for specialized clinical software integration. Raw material dependencies span lithium-ion batteries, OLED microdisplays, and medical-grade sensors. Single-source vulnerability in advanced display manufacturing from South Korean suppliers creates procurement risk. Distribution runs through psychiatric device distributors with FDA establishment registration, bypassing general medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agoraphobia treatment market exhibits cyclical recovery characteristics driven by post-pandemic normalization of in-person care utilization and employer benefit reinvestment in behavioral health infrastructure.
For Market Incumbents: Shield formulary position against digital therapeutic substitution by securing FDA breakthrough therapy designations for novel rapid-onset anxiolytics before software-based exposure protocols achieve reimbursement parity. Deepen backward integration into virtual reality hardware partnerships to control channel access for immersive therapy certification programs. Defensive consolidation through acquisition of teletherapy platforms with established cross-state licensure infrastructure addresses workforce concentration risks. For New Entrants and Emerging Players: Lead with adolescent-focused developmentally adapted protocols, the most penetrable segment given current guideline gaps and NICE-mandated training lags in United Kingdom markets. Geographic white-space exists in Japan's rural prefectures outside Tokyo-Osaka corridors where PMDA regulatory requirements have slowed domestic platform development. Go-to-market angle should emphasize asynchronous engagement models that eliminate real-time scheduling constraints for homebound severe presentations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed teletherapy platforms holding Series C-D positions and seeking liquidity pathways through strategic pharmaceutical partnerships. Long-term viability over the five-to-ten year horizon hinges on successful navigation of digital therapeutics reimbursement parity legislation across multiple United States state jurisdictions. Acquisition target archetype: mid-cap biotech sponsors with EMA orphan drug incentives for treatment-resistant chronic agoraphobia phenotypes. Signal to watch: FDA digital therapeutics guidance updates classifying prescription software as complementary to pharmacotherapy versus substitutive.| Strategic Initiative | Industry Significance |
|---|---|
| VR Hardware Certification Program | FDA 510(k) clearance for exposure therapy systems enables formulary placement at academic medical centers. |
| Cross-State Licensure Infrastructure | Platform staffing models bypass conflicting professional requirements complicating national virtual care delivery. |
| Adolescent Protocol Development | NICE guideline compliance captures high-incidence underdiagnosed segment with adapted cognitive behavioral frameworks. |
| Biomarker Integration Partnership | Heart rate variability sensor deployment differentiates premium service tiers from standardized exposure protocols. |
| EMA Orphan Drug Designation | Accelerated review timelines redirect biotech portfolios toward severe treatment-resistant anxiety phenotypes. |
Methodological Framework
The analysis maps therapy modality segments, severity tier distributions, and treatment setting channels, each validated through exposure therapy specialists, digital health platform executives, formulary directors at United States commercial payers, and regulatory affairs leads at EMA-centralized procedure sponsors. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) and breakthrough therapy designation filings, ClinicalTrials.gov anxiety disorder protocol registries, NICE guideline documentation, and CMS CPT code utilization databases. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation ensure cross-method consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models therapy type substitution dynamics, severity-stratified pricing tiers, age-group developmental adaptation requirements, and regional regulatory cluster adoption patterns. CAGRs derive from segment-level growth rate synthesis calibrated to reimbursement code expansion trajectories and employer benefit carve-out penetration curves. Forecast inputs include teletherapy platform scaling coefficients and VR hardware procurement cycle data from academic medical center supply chain disclosures.
The analysis sits within stated boundaries; outcomes outside FDA digital therapeutics classification finalization, EMA pediatric investigation plan enforcement, or United States state reimbursement parity legislative passage would require recalibration. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory timeline probabilities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Depression Treatment Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Global Mental Health Apps Market