
 Mental Health Software Market | 2026-2036
Mental Health Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mental Health Software Market Outlook
North American health IT infrastructure is consolidating around behavioral health platforms that integrate clinical workflow with reimbursement systems. Epic Systems Corporation sustains dominance through deep EHR interoperability across hospital networks. Netsmart Technologies specializes in post-acute and human services segments where regulatory reporting complexity creates defensive moats. Qualifacts Systems competes on configurable workflow engines that accommodate state-by-state Medicaid documentation rules.
Mental health software comprises digital platforms that schedule, document, bill, and deliver therapeutic interventions across care settings, with core architectures requiring HL7 FHIR compatibility and AES-256 encryption for protected health information. EHR Systems anchors current revenue as legacy migration cycles extend replacement timelines for on-premise installations. Cloud-Based Solutions represent the fastest-expanding technology tier, with AI-Driven Platforms capturing concentrated R&D investment for predictive risk stratification. Corporate Wellness Programs emerge as an underpenetrated end-user channel where employer liability concerns expand budget authority outside traditional clinical procurement.
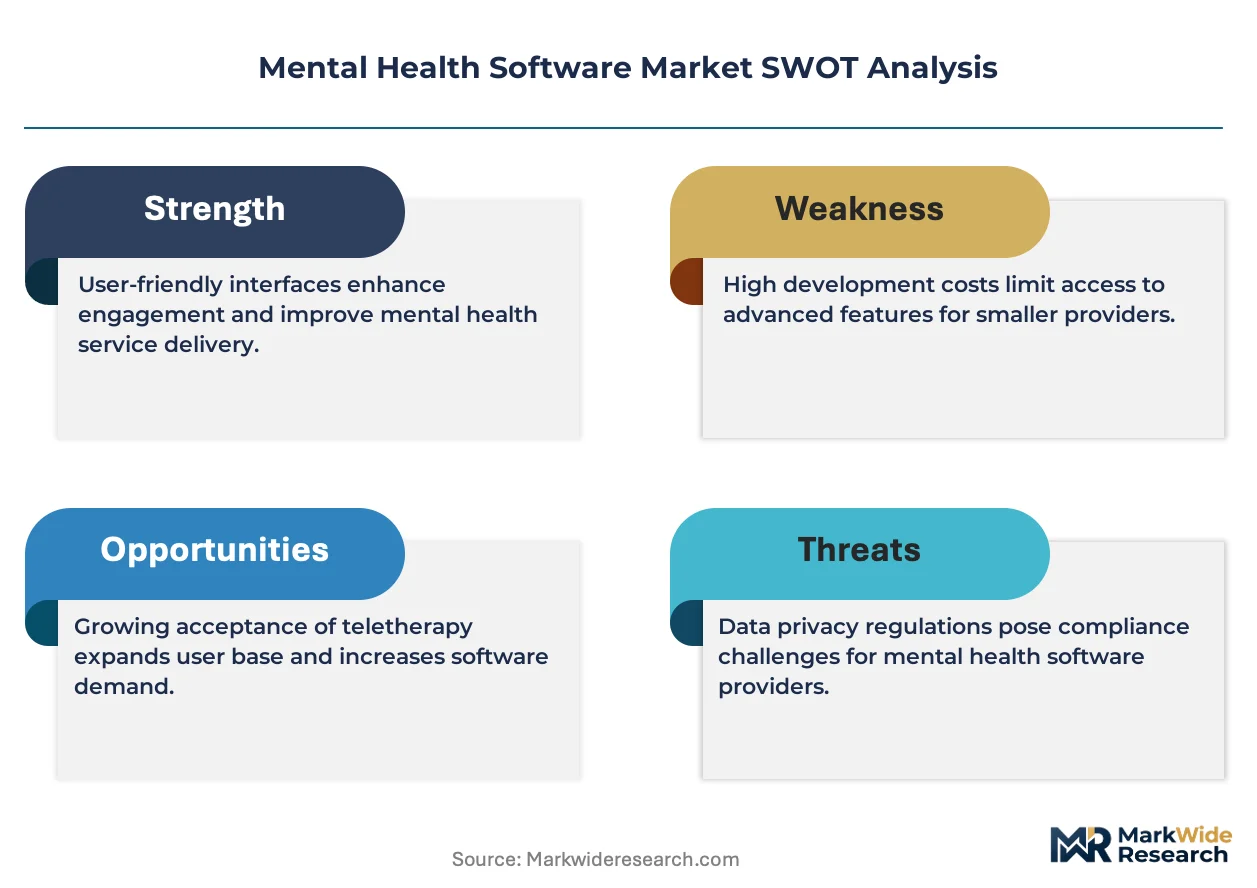
FDA oversight of clinical decision support algorithms intersects with HIPAA security rule enforcement from the Office for Civil Rights, tightening validation requirements for AI-assisted diagnostic outputs. State telehealth licensing compacts and DEA e-prescribing waivers for controlled substances create fragmented compliance matrices that favor vendors with dedicated regulatory operations. Stakeholders must evaluate whether platform architectures can absorb impending interoperability mandates without wholesale infrastructure replacement.
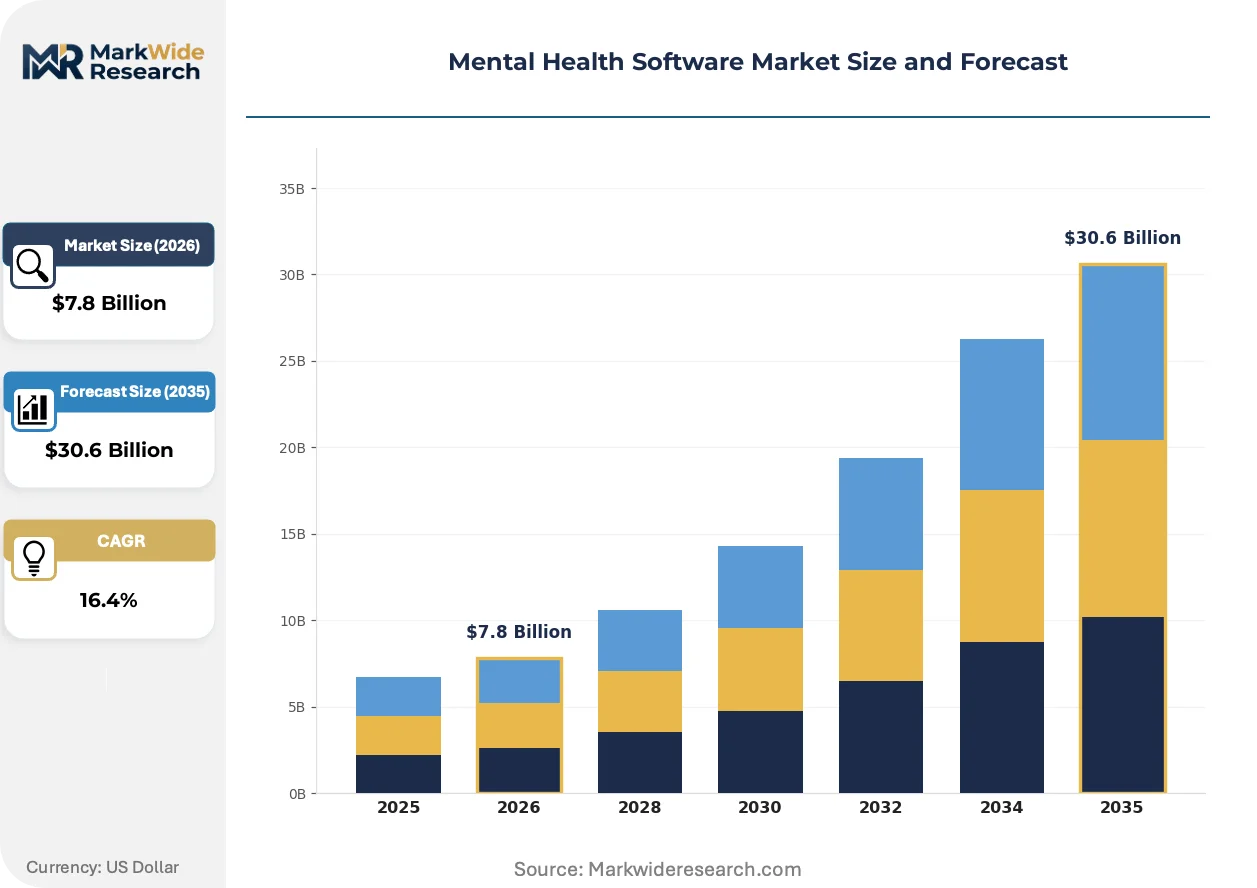
Market Dynamics
Behavioral health clinics are consolidating onto unified platforms that merge clinical documentation with revenue cycle management, compressing vendor selection cycles as HIPAA compliance deadlines tighten and state Medicaid agencies mandate interoperable reporting formats.
Growth Catalysts
- Telehealth Parity Legislation:State-level mandates requiring equivalent reimbursement for virtual mental health sessions are accelerating platform procurement across Medicaid provider networks in the United States.
- AI Risk Stratification:Machine learning algorithms that predict patient deterioration are embedding into EHR workflows, creating pull-through demand for integrated behavioral health modules.
- Workplace Mental Health Mandates:Large employers in Germany and the United Kingdom are expanding EAP software budgets under duty-of-care litigation pressure and EU psychosocial risk directives.
Market Restraints
- Input Cost Volatility:Cloud infrastructure pricing from hyperscale providers is squeezing gross margins for mid-tier SaaS vendors serving community health centers.
- Supply Concentration Risk:Interoperability middleware depends on a narrow base of HL7 FHIR certification bodies, creating single-point-of-failure exposure for cross-platform data exchange.
- Regulatory Friction:FDA 510(k) pathways for clinical decision support algorithms remain ambiguous, delaying commercialization timelines for diagnostic AI modules.
Strategic Opportunities
- Underpenetrated Geography:India's district mental health programs lack digitized case management, creating first-mover advantage for cloud-native platforms adapting to CDSCO data localization requirements.
- Technology Convergence:Wearable biometric sensors paired with passive mood monitoring APIs are opening reimbursement codes for continuous care models outside traditional session-based billing.
- Regulatory Tailwind:DEA e-prescribing waivers for controlled substances in the United States are enabling full-stack platforms to capture medication management workflows previously siloed in separate systems.
Industry Challenges
- Specialized Talent Scarcity:Behavioral health informaticists who understand both clinical workflows and Medicaid billing rules command premium compensation, constraining implementation velocity for mid-market vendors.
- Legacy System Entrenchment:On-premise EHR installations with customized state reporting modules require expensive API middleware to connect with modern cloud architectures, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mental Health Software Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $30.6 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online Therapy, Mobile Apps, Telehealth Solutions, EHR Systems End User: Clinics, Hospitals, Individual Practitioners, Corporate Wellness Programs Technology: AI-Driven Platforms, Cloud-Based Solutions, Virtual Reality, Video Conferencing Application: Patient Monitoring, Cognitive Behavioral Therapy, Mood Tracking, Crisis Management |
| Companies Covered | Oracle (Cerner Corporation), Epic Systems Corporation, Netsmart Technologies, Qualifacts Systems, Valant Medical Solutions, Welligent, SimplePractice, Credible Behavioral Health, Allscripts Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mental Health Software Market Strategic Shifts
Platform architectures are pivoting from documentation-centric designs toward predictive intervention systems, with regulatory validation and reimbursement coding racing to catch technical capability.
Natural language processing engines that transcribe and code therapy sessions in real time are rewriting clinical productivity benchmarks. Community mental health centers in Texas and Florida are piloting ambient documentation tools that reduce administrative burden by automating Medicaid-compliant note generation. This compression of documentation time is enabling higher patient throughput without proportional staffing expansion.
The EU AI Act's risk classification framework for medical decision support is forcing vendors to segregate algorithmic outputs by clinical criticality. Systems that flag suicide risk now face conformity assessment requirements that delay deployment by 12-18 months compared to administrative automation features. German psychiatric hospitals are prioritizing vendors with notified body relationships to accelerate CE marking timelines.
Subscription fatigue among mid-sized behavioral health practices is driving unbundling of all-in-one platforms. Purchasers in California and New York are assembling best-of-breed stacks—scheduling from one vendor, telehealth from another, billing from a third—rather than accepting functional trade-offs in integrated suites. This fragmentation is pressuring incumbents to expose robust APIs or risk disintermediation by specialized point solutions.
Mental Health Software Market Segmentation
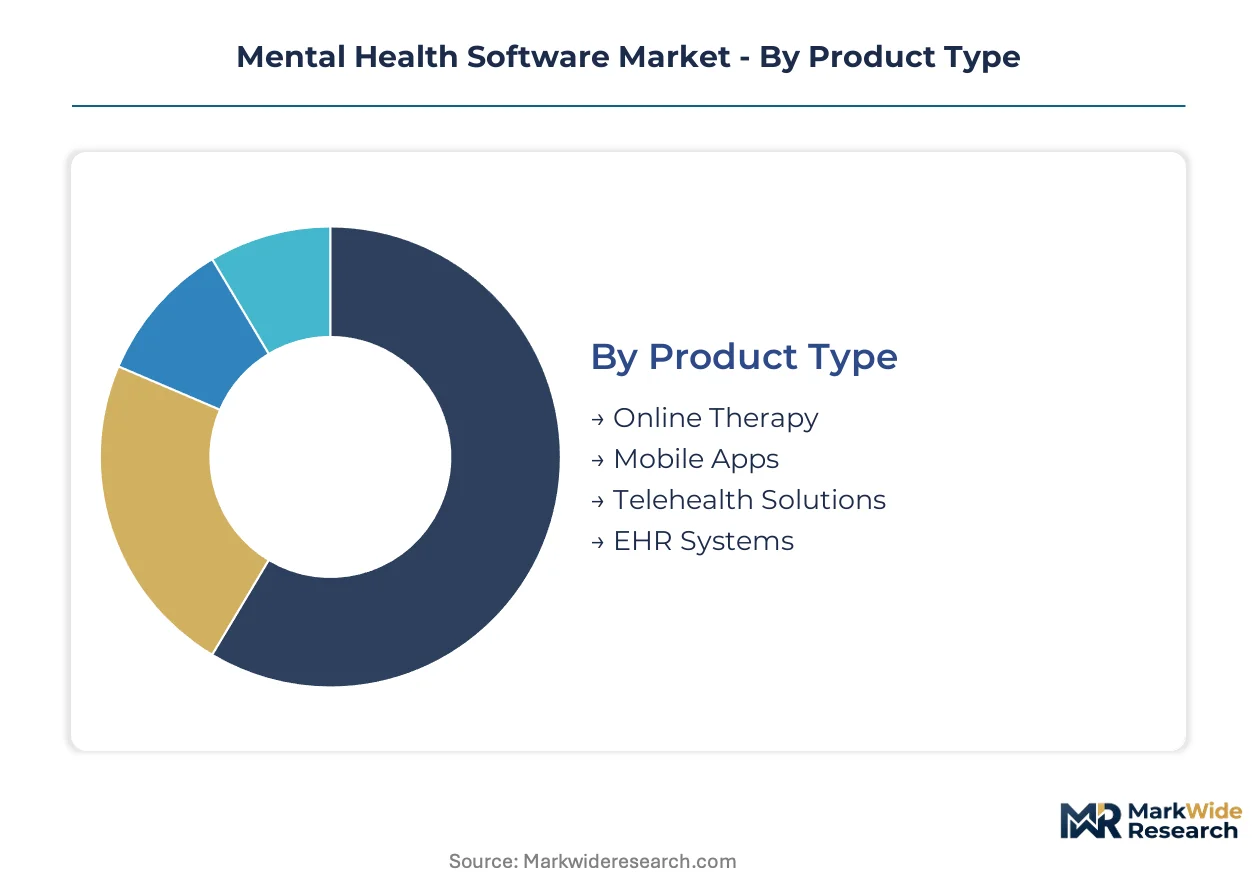
Segmentation reveals how procurement authority fragments across clinical settings and technology maturity tiers. Buyers prioritize different combinations of compliance depth, integration burden, and workflow specificity depending on their operational scale and reimbursement complexity.
Product Type:
Supply concentrates in platforms that bundle documentation with revenue cycle management, compressing standalone point solutions into marginal positions.
- EHR Systems:Core clinical data repositories with HL7 FHIR interoperability and state Medicaid reporting modules. Demand clusters in United States behavioral health clinics consolidating from paper-based workflows ahead of HIPAA enforcement deadlines.
- Telehealth Solutions:Virtual care delivery infrastructure with DEA e-prescribing integration for controlled substances. United States provider networks are prioritizing these platforms as state parity mandates extend reimbursement equivalence to video-based sessions.
- Mobile Apps:Consumer-facing symptom tracking and guided intervention tools with passive sensor integration.
- Online Therapy:Text and asynchronous messaging platforms connecting patients with licensed clinicians through subscription models.
Today's leader: EHR Systems. Tomorrow's challenger: Telehealth Solutions.
End User:
Customer type determines pricing tolerance and implementation complexity, with institutional buyers demanding customization that strains SaaS delivery models.
- Clinics:Outpatient behavioral health practices with 5-50 clinicians requiring integrated scheduling, documentation, and billing. United States community mental health centers are driving procurement as Medicaid managed care contracts mandate interoperable reporting to state agencies.
- Corporate Wellness Programs:Employer-sponsored mental health benefits administered through third-party EAP vendors. German and United Kingdom multinationals are expanding budgets under EU psychosocial risk directives and duty-of-care litigation exposure.
- Hospitals:Acute care systems embedding behavioral health modules within enterprise EHR deployments.
- Individual Practitioners:Solo therapists and psychologists purchasing lightweight subscription tools with minimal IT overhead.
Institutional buyers dominate current revenue. Employer channels are climbing the fastest as procurement authority shifts outside clinical departments.
Technology:
Margin structure diverges sharply between commodity infrastructure and algorithmic differentiation, with AI layers commanding implementation premiums.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with AES-256 encryption and automated HIPAA compliance updates. United States provider networks are prioritizing these deployments to eliminate on-premise maintenance overhead and accelerate state reporting adaptability.
- AI-Driven Platforms:Machine learning systems for suicide risk prediction and treatment response forecasting embedded in clinical workflows. FDA 510(k) pathway ambiguity and EU AI Act conformity assessments are delaying commercialization for diagnostic-critical algorithms.
- Video Conferencing:HIPAA-compliant telehealth infrastructure with session recording and billing code automation.
- Virtual Reality:Immersive exposure therapy environments for PTSD and anxiety disorders with limited reimbursement coding.
Cloud infrastructure anchors current deployments. AI layers are gaining share fastest as regulatory validation frameworks mature.
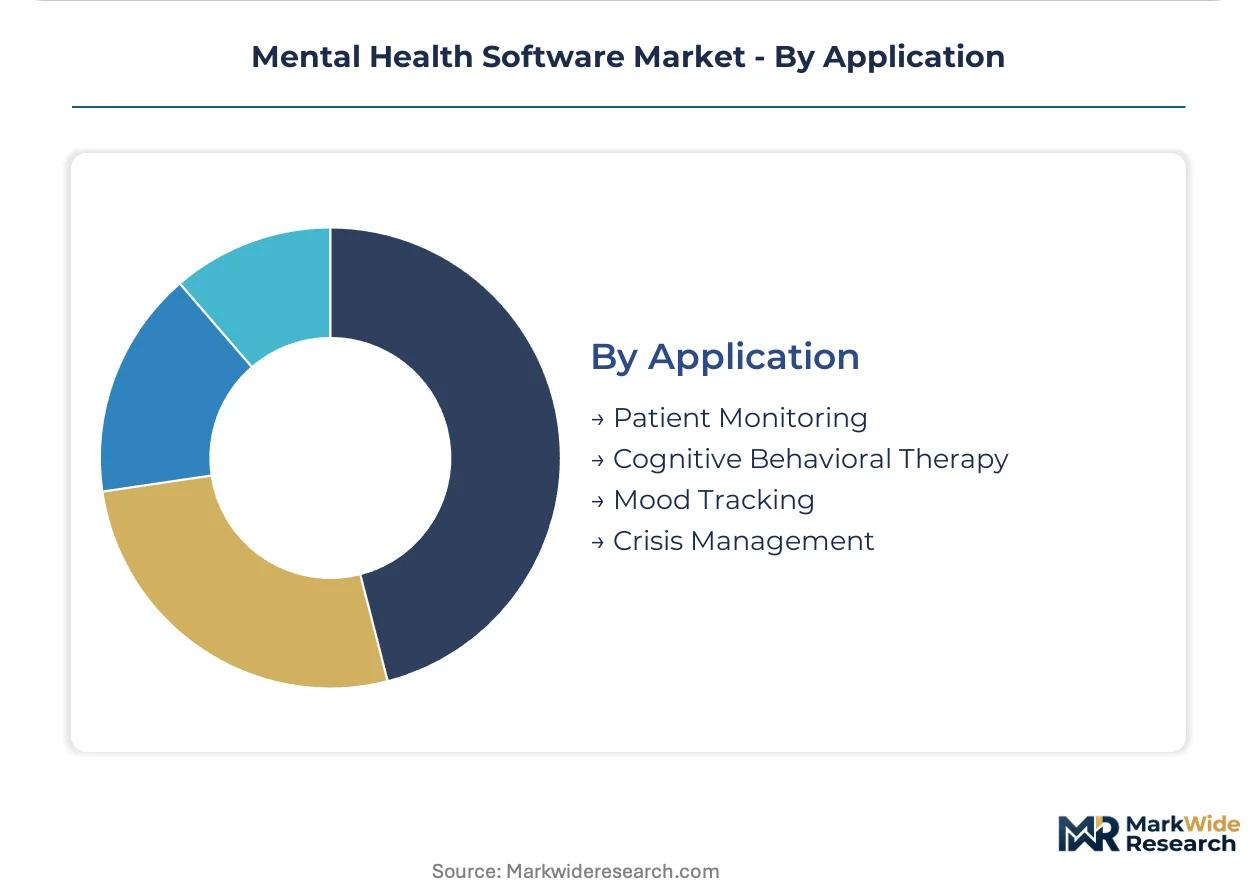
Application:
Use case specificity determines reimbursement eligibility and clinical liability exposure, with crisis-tier applications facing the steepest validation requirements.
- Patient Monitoring:Continuous remote tracking of medication adherence, sleep patterns, and biometric indicators through wearable integration. United States value-based care contracts are creating reimbursement codes for monitoring outside traditional session boundaries.
- Crisis Management:Real-time suicide risk detection and escalation protocols with emergency services integration. EU AI Act high-risk system classification and FDA enforcement discretion are extending validation timelines for algorithmic crisis flags.
- Cognitive Behavioral Therapy:Structured digital intervention protocols with automated homework assignments and progress tracking.
- Mood Tracking:Patient-reported outcome measures with longitudinal visualization for clinical review.
Monitoring applications lead current adoption. Crisis management tools face the steepest regulatory climb but offer the highest defensive value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting vendor certification investments toward jurisdictions with clearer AI governance frameworks, as FDA 510(k) ambiguity and EU AI Act conformity assessments create divergent compliance cost structures across major markets.
United States
Behavioral health clinics in Texas and Florida are consolidating onto unified platforms as state Medicaid agencies mandate interoperable reporting formats. HIPAA enforcement deadlines from the Office for Civil Rights are compressing vendor selection cycles for community mental health centers. The Dallas-Fort Worth metroplex is emerging as a deployment hub where cloud-native vendors pilot ambient documentation tools for automated Medicaid-compliant note generation.
Germany
Psychiatric hospitals in Bavaria and North Rhine-Westphalia are prioritizing vendors with notified body relationships to accelerate CE marking timelines under the EU AI Act's risk classification framework. The country's psychosocial risk directives are expanding employer liability exposure and driving EAP software procurement by multinationals. Berlin's startup cluster is concentrating development resources on algorithmic outputs segregated by clinical criticality to satisfy conformity assessment requirements.
United Kingdom
Duty-of-care litigation pressure is elevating mental health software budgets within corporate wellness programs at London-headquartered financial services firms. The NHS is mandating HL7 FHIR interoperability for behavioral health modules integrated into enterprise EHR deployments. Manchester's health tech corridor is hosting pilot programs for wearable biometric sensors paired with passive mood monitoring APIs.
India
District mental health programs in Maharashtra and Karnataka lack digitized case management, creating first-mover advantage for cloud-native platforms adapting to CDSCO data localization requirements. The country's national pharmaceutical regulator is tightening validation protocols for clinical decision support algorithms. Hyderabad's IT cluster is attracting vendor development centers focused on state-by-state Medicaid documentation rule configurability.
Canada
Provincial health authorities in Ontario and British Columbia are expanding telehealth parity mandates to behavioral health sessions, accelerating platform procurement across community provider networks. Health Canada is aligning medical device oversight with FDA enforcement discretion patterns for diagnostic AI modules. Toronto's hospital network is consolidating behavioral health modules within enterprise EHR deployments to eliminate on-premise maintenance overhead.
Mental Health Software Market Competitive Environment
United States producers anchor the premium tier through deep EHR interoperability across hospital networks; European specialists hold defensive positions in regulatory reporting complexity. The vendor base organizes around three strategic archetypes: enterprise platform consolidators, post-acute workflow specialists, and configurable Medicaid rule engines. Dominant competitive moves include M&A activity to absorb ambient documentation capabilities and strategic partnerships with hyperscale cloud providers to secure infrastructure pricing advantages.
Within the enterprise tier, Oracle (Cerner Corporation) and Epic Systems Corporation exemplify scale-driven positioning through EHR interoperability dominance across acute care systems. Netsmart Technologies occupies a specialist position in post-acute and human services segments where regulatory reporting complexity creates defensive moats. These three entities represent the concentration of procurement authority within institutional buyer channels, with each anchoring distinct workflow specificity tiers that strain pure SaaS delivery models.
| Leading Market Players |
|---|
| Oracle (Cerner Corporation) |
| Epic Systems Corporation |
| Netsmart Technologies |
| Qualifacts Systems |
| Valant Medical Solutions |
| Welligent |
| SimplePractice |
| Credible Behavioral Health |
| Allscripts Healthcare |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure pricing from hyperscale providers feeds through SaaS vendor margins into subscription tiers for behavioral health clinics, with AWS and Azure compute costs compressing gross margins for mid-tier platforms serving community mental health centers before reaching end-user pricing.
Pricing Analysis
Direct-to-provider subscription models dominate, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on HIPAA certification grade and state Medicaid reporting module depth. Pricing pressure stems from hyperscale cloud cost compression forcing mid-tier vendors toward feature unbundling. Individual practitioners exhibit highest price sensitivity, while hospital systems demonstrate lowest sensitivity due to bundled enterprise procurement.
Supply Chain Analysis
Freight costs for on-premise server hardware shipments to legacy clinic installations remain marginal as cloud-native architectures displace physical infrastructure. Software development labor concentrates in the United States, India, and Germany. Raw material dependencies center on semiconductor chips for data center expansion, API middleware licensing, and cybersecurity certification services. Single-source vulnerability sits with HL7 FHIR certification bodies controlling interoperability compliance. Distribution runs through direct SaaS provisioning and value-added reseller networks serving state Medicaid agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into procurement acceleration, with HIPAA enforcement deadlines from the Office for Civil Rights compressing vendor selection cycles for community mental health centers.
For Market Incumbents: To counter unbundling pressure from best-of-breed point solutions, Epic Systems and Oracle Cerner should deepen API exposure for workflow interoperability and acquire ambient documentation specialists to automate Medicaid-compliant note generation. Channel control through GPO contracts with hospital purchasing committees remains essential for defending enterprise tier positioning. For New Entrants and Emerging Players: Launch via white-label partnerships with employer-sponsored EAP vendors to bypass clinical procurement gatekeepers. India's district mental health programs offer the most penetrable geography, with cloud-native platforms adapting to CDSCO data localization requirements capturing first-mover advantage. Target corporate wellness procurement authority shifting outside traditional clinical departments under EU psychosocial risk directives. For Investors and Strategic Acquirers: Roll-up economics work for configurable Medicaid rule engines because state-by-state documentation complexity creates defensive moats that resist pure SaaS commoditization. Acquisition targets should demonstrate notified body relationships for EU AI Act conformity acceleration. Watch FDA 510(k) pathway clarification for clinical decision support algorithms as the inflection signal for diagnostic AI module commercialization viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic Systems sustains dominance through deep EHR interoperability across hospital networks. |
| Acquisition of Specialist Firm | Ambient documentation capabilities compress administrative burden for Medicaid-compliant note generation. |
| Strategic Partnership | Hyperscale cloud provider alliances secure infrastructure pricing advantages for mid-tier SaaS vendors. |
| Geographic Expansion | India's district mental health programs lack digitized case management for cloud-native platforms. |
| Product Launch | AI-driven risk stratification modules embed into clinical workflows for predictive intervention systems. |
Study Parameters
Bottom-up behavioral health clinic modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core, combining primary interviews with CTOs, IT procurement officers at provider networks, platform engineers, and integration specialists with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and state Medicaid agency reporting requirements.
Historical trendline analysis of EHR replacement cycles and telehealth adoption curves informs the projection framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical specificity, integration complexity, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for HIPAA enforcement timeline acceleration and state parity mandate rollout patterns.
Several conditions sit outside the modeled scope, including DEA e-prescribing waiver permanence decisions and EU AI Act conformity assessment timeline variability. Forecasts reflect assumptions about regulatory validation pathways and reimbursement code expansion that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
US Behavioral Health Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Schizophrenia Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market