
 Global Mental Health Apps Market | 2026-2036
Global Mental Health Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mental Health Apps Market Foresight
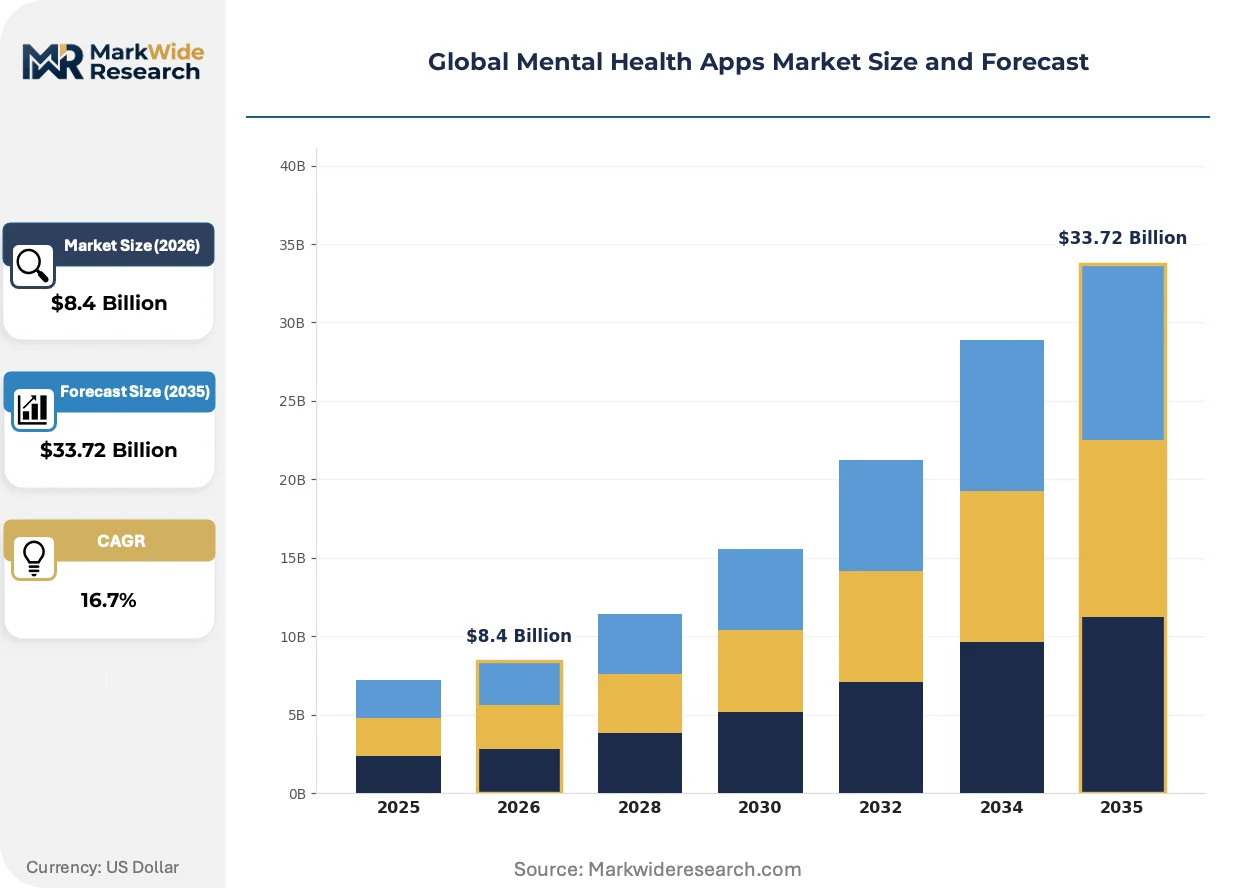
Subscription-based access models is broadening what mental health platforms sell beyond one-time downloads. Calm leverages recurring revenue through tiered membership structures spanning sleep, meditation, and workplace content. Headspace Inc. anchors its position with employer contracts that embed mental health benefits into corporate benefit packages. Talkspace competes through licensed therapist networks accessible via messaging and live session formats.
Mental health apps are software applications delivering psychological support, mood monitoring, and therapeutic interventions through smartphone interfaces, typically incorporating cognitive behavioral therapy protocols, biometric feedback loops, and artificial intelligence-driven personalization engines. Their primary commercial purpose centers on scalable, lower-cost alternatives to traditional in-person counseling for anxiety, depression, and stress-related conditions. Self-help tools command the largest user base due to minimal friction and zero gatekeeper requirements, while AI-powered guidance represents the fastest-expanding margin pool as natural language processing capabilities advance. Teletherapy services occupy a mature, regulated tier where professional licensure creates higher barriers but sustains premium pricing.
The FDA exercises oversight through its software-as-a-medical-device pathway, determining which apps require premarket clearance based on intended diagnostic or therapeutic claims. The EU AI Act imposes risk-classification requirements on mental health algorithms deployed across European member states, affecting product architecture and liability exposure. HIPAA compliance obligations govern data handling for US-based platforms serving clinical populations, influencing cloud infrastructure choices and vendor partnerships. Stakeholders must monitor how divergent regulatory timelines across jurisdictions reshape product development roadmaps and market entry sequencing.
Market Dynamics
Corporate wellness programs are embedding digital mental health tools as standard benefits, while the FDA's evolving software-as-a-medical-device framework reclassifies therapeutic apps into regulated medical products. This dual pressure from employer demand and regulatory recalibration is compressing development timelines and reshaping competitive moats.
Growth Catalysts
- HIPAA-compliant cloud infrastructure:Healthcare enterprises now mandate encrypted data architectures for employee wellness platforms, accelerating vendor certification investments.
- Employer-sponsored coverage expansion:Large US corporations are adding mental health apps to benefits packages, creating institutional procurement channels.
- Natural language processing advancement:Conversational AI capabilities are enabling real-time therapeutic guidance without licensed clinician intervention.
Market Restraints
- FDA premarket clearance costs:Clinical validation requirements for diagnostic claims impose multi-million dollar regulatory burdens on development-stage platforms.
- Data localization mandates:EU GDPR and emerging national privacy laws fragment cloud architecture requirements across jurisdictions.
- Licensed therapist supply constraints:Teletherapy networks face recruitment bottlenecks in states with restricted interstate practice laws.
Strategic Opportunities
- India's underpenetrated employer market:Corporate wellness adoption remains below 15% among large Indian enterprises, creating first-mover positioning potential.
- Brazil's ANVISA digital health pathway:Recent regulatory clarity for software medical devices enables structured market entry for therapeutic platforms.
- Biometric-therapy convergence:Wearable heart-rate variability data integration with cognitive behavioral protocols opens personalized intervention models.
Industry Challenges
- Cross-border credential recognition:Therapist licensure portability restrictions complicate platform scaling across US state lines.
- Clinical evidence generation timelines:Randomized controlled trials required for FDA clearance extend product development cycles beyond typical software release cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mental Health Apps Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
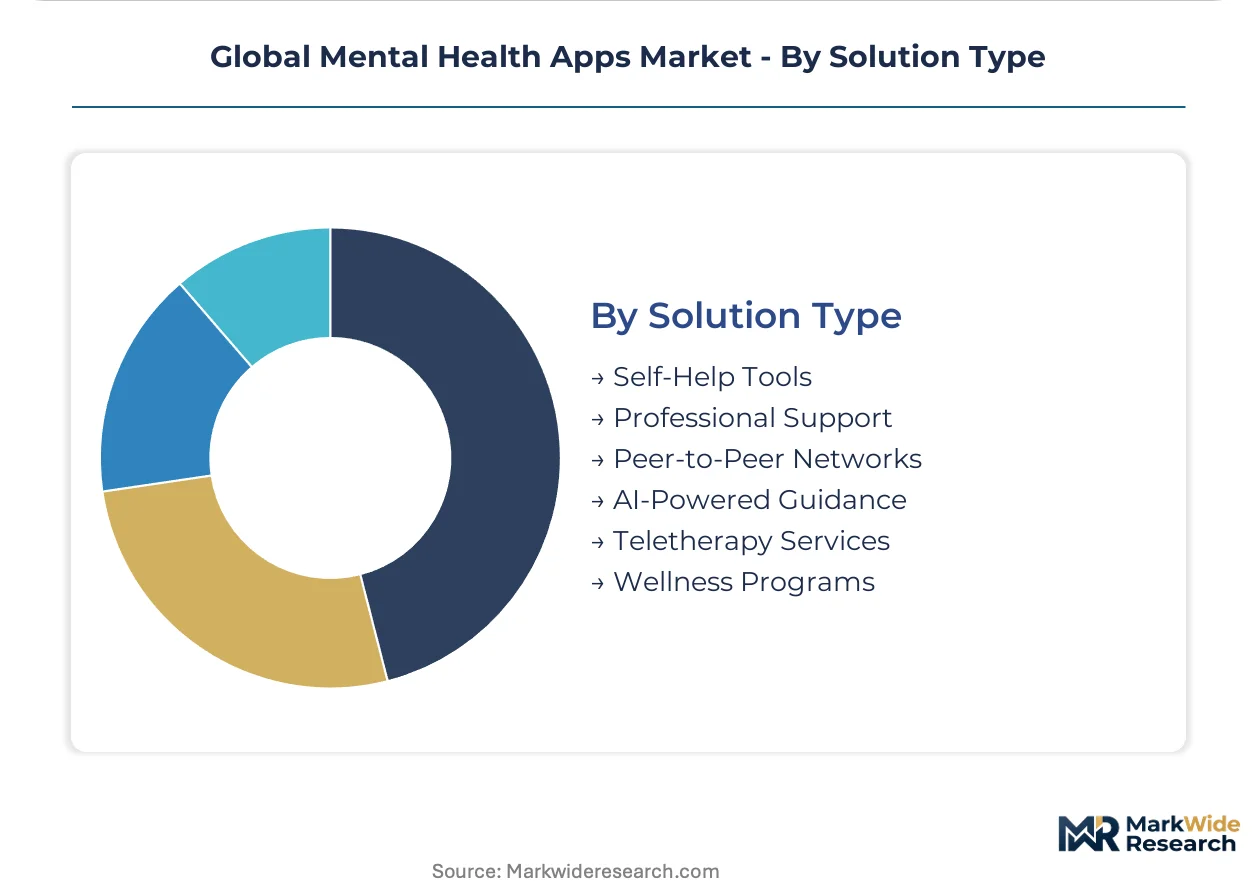
| Segmentation | Application: Stress Management, Sleep Improvement, Mood Tracking, Anxiety Relief, Cognitive Behavioral Therapy, Mindfulness Training Deployment: Mobile Apps, Web-Based Platforms, Wearable Integration, Chatbot Assistance, Virtual Reality, Desktop Applications End User: Individual Consumers, Educational Institutions, Corporate Employees, Counselors, Support Groups, Veterans Solution Type: Self-Help Tools, Professional Support, Peer-to-Peer Networks, AI-Powered Guidance, Teletherapy Services, Wellness Programs |
| Companies Covered | Calm, Headspace Inc., Talkspace, BetterHelp, Happify, Inc., Sanvello Health, Youper, Inc., MoodMission, Woebot Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mental Health Apps Market Shifts & Advancements
Artificial intelligence architectures are fragmenting monolithic mental health platforms into composable service layers. This decomposition enables faster regulatory targeting and vertical-specific customization without full-stack redevelopment.
Machine learning personalization engines are modularizing how therapeutic content gets delivered to end users. Large employers are adopting these APIs for white-label integration into existing benefits portals. The shift is compressing standalone app margins while expanding B2B infrastructure licensing revenue pools.
The EU AI Act's risk-classification framework is imposing algorithmic audit requirements on mental health applications deployed across European member states. High-risk system designations now mandate conformity assessments before market entry. Platforms serving clinical populations are restructuring product architectures to isolate diagnostic functions from wellness features.
Subscription fatigue among direct-to-consumer users is accelerating employer-sponsored channel migration. Individual download growth is stagnating while benefits-administrator procurement is expanding. The United States exhibits the sharpest channel rotation, with workplace benefits now accounting for the majority of new paid memberships.
Global Mental Health Apps Market Segmentation
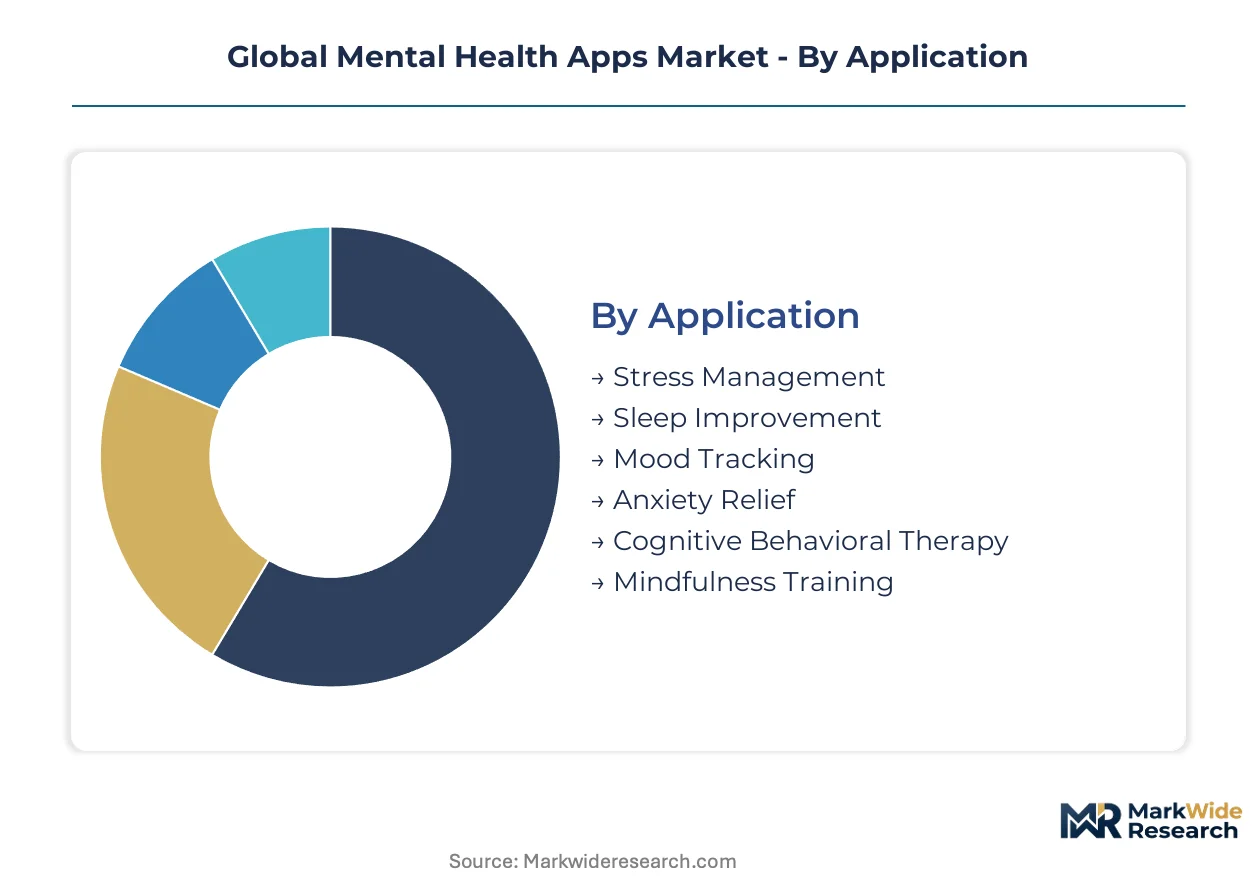
Mental health apps fragment across four distinct classification axes that reshape competitive positioning and margin architecture. Each dimension carries divergent regulatory exposure, customer acquisition costs, and technology requirements that determine viable business models.
Application:
Functional specialization determines therapeutic intensity and FDA pathway requirements.
- Cognitive Behavioral Therapy:Structured protocols deliver evidence-based interventions through digital modules. Demand concentrates in employer-sponsored programs where clinical validation supports insurance reimbursement claims.
- Anxiety Relief:Real-time symptom management tools incorporate breathing exercises and grounding techniques. Corporate wellness contracts in the United States drive procurement volume as HR departments prioritize measurable stress reduction outcomes.
- Stress Management:Workplace-focused content bundles target productivity metrics alongside wellbeing scores.
- Sleep Improvement:Audio-based interventions leverage circadian science with minimal regulatory burden.
- Mood Tracking:Passive data collection interfaces feed longitudinal mental health datasets.
- Mindfulness Training:Meditation content libraries compete on instructor brand recognition and production quality.
CBT leads on scale; anxiety relief leads on momentum.
Deployment:
Interface modality dictates hardware dependencies and user engagement patterns.
- Mobile Apps:Native iOS and Android applications dominate direct-to-consumer distribution with push notification retention mechanics. The United States and India generate the highest download velocity through app store optimization and influencer partnerships.
- Wearable Integration:Apple Watch and Fitbit ecosystem connections enable biometric-triggered interventions using heart rate variability and sleep stage data. Premium pricing sustains where hardware lock-in creates switching costs.
- Web-Based Platforms:Browser-accessible tools bypass app store commissions for B2B sales cycles.
- Chatbot Assistance:Conversational interfaces deploy natural language processing for scalable triage.
- Virtual Reality:Immersive exposure therapy environments require specialized headset penetration.
- Desktop Applications:Full-screen experiences target clinical workflows and documentation integration.
Mobile apps capture the largest installed base; wearable integration climbs the fastest.
End User:
Customer archetype shapes pricing power, contract structure, and churn profiles.
- Corporate Employees:Benefits-administrator procurement channels aggregate thousands of seats under single contracts. United States enterprises with self-insured health plans drive the steepest expansion trajectory as mental health parity regulations tighten.
- Individual Consumers:Direct subscriptions face mounting cancellation pressure from subscription fatigue and macroeconomic sensitivity.
- Educational Institutions:University counseling center partnerships create semester-aligned revenue cycles.
- Counselors:Licensed practitioner tools focus on caseload management and outcome documentation.
- Support Groups:Peer-facilitated communities monetize through moderated discussion access.
- Veterans:Government contract eligibility opens specialized PTSD and reintegration content requirements.
Corporate employees anchor revenue stability; veterans represent the most concentrated procurement opportunity.
Solution Type:
Service intensity tier determines regulatory classification and margin structure.
- AI-Powered Guidance:Algorithmic personalization engines analyze user input patterns to adapt content sequencing. The EU AI Act's high-risk system designation imposes conformity assessment costs that favor well-capitalized platforms with dedicated compliance infrastructure.
- Teletherapy Services:Licensed clinician networks command premium pricing through state-regulated practice credentials. Interstate licensure compacts in the United States partially ease therapist supply constraints.
- Self-Help Tools:Ungated content libraries minimize friction and maximize top-of-funnel conversion.
- Professional Support:Asynchronous coaching bridges self-help and clinical intervention tiers.
- Peer-to-Peer Networks:Community moderation costs scale with user-generated content volume.
- Wellness Programs:Employer-customized bundles combine multiple modalities under single contracts.
Teletherapy services lead on revenue per user; AI-powered guidance expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates employer-sponsored procurement channels, while Germany's statutory health insurance framework creates divergent reimbursement pathways for therapeutic software. India and Brazil represent acceleration markets where regulatory clarity is reshaping competitive entry sequencing.
United States
Large enterprises with self-insured health plans drive corporate wellness adoption, embedding mental health apps into benefits packages. FDA's software-as-a-medical-device pathway determines which platforms require premarket clearance based on diagnostic claims. Silicon Valley and Boston clusters host venture-backed platforms developing AI-powered therapeutic guidance engines.
Germany
Statutory health insurance reimbursement for digital health applications creates institutional procurement channels distinct from direct-to-consumer markets. BfArM's DiGA fast-track approval process enables prescribed mental health apps to receive temporary reimbursement listing. Berlin and Munich clusters concentrate health-tech startups navigating EU AI Act conformity requirements for high-risk algorithmic systems.
United Kingdom
NHS Digital's assessment framework for mental health apps shapes procurement criteria for integrated care systems. MHRA's software medical device guidance aligns with evolving FDA precedents on therapeutic claims classification. London's health-tech corridor attracts platforms seeking English-language market entry before EU regulatory compliance.
India
Corporate wellness penetration remains below 15% among large enterprises, creating first-mover positioning potential for platform providers. CDSCO's emerging digital health oversight framework remains less prescriptive than FDA or EU pathways. Bangalore and Mumbai clusters concentrate employer-focused startups adapting global CBT protocols for regional workforce stressors.
Brazil
ANVISA's recent regulatory clarity for software medical devices enables structured market entry for therapeutic platforms previously operating in gray zones. Employer-sponsored mental health benefits expansion lags US and European adoption curves. São Paulo's health-tech ecosystem hosts platforms targeting Portuguese-speaking markets across Latin America.
Global Mental Health Apps Market Competitive Landscape
Top-tier vendors anchor employer-contract channels, while mid-tier platforms compete through direct-to-consumer subscription models and specialized therapeutic modalities. The vendor base stratifies across three archetypes: meditation-content aggregators, teletherapy network operators, and AI-guided intervention developers. Strategic moves concentrate on B2B channel migration and regulatory pre-clearance positioning for diagnostic claim expansion.
Within the employer-contract tier, Calm and Headspace Inc. exemplify platform-scale archetypes, while Talkspace occupies a position bridging teletherapy services and digital self-help tools. Calm represents the content-aggregation model with tiered membership structures spanning sleep and workplace modules. Headspace Inc. anchors corporate benefit package integration. Talkspace sits within the licensed-clinician network category, competing through messaging and live session accessibility.
| Leading Market Players |
|---|
| Calm |
| Headspace Inc. |
| Talkspace |
| BetterHelp |
| Happify, Inc. |
| Sanvello Health |
| Youper, Inc. |
| MoodMission |
| Woebot Health |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs for HIPAA-compliant hosting cascade through subscription tiers, with enterprise procurement in the United States absorbing premium pricing while direct-to-consumer users face compressed margins in competitive app store environments.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for employer-sponsored deployments, forcing incumbents to defend margin position through tiered certification investments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared therapeutic modules from wellness content and basic meditation libraries. Price differentiation hinges on clinical validation depth and employer contract scale, with individual subscribers exhibiting highest price sensitivity due to subscription fatigue. Pricing pressure stems from AI-powered guidance commoditization as natural language processing capabilities diffuse across platforms.
Supply Chain Analysis
Freight costs for wearable hardware integration remain minimal given software-dominant delivery models, though biometric sensor procurement draws from Taiwan, South Korea, and China manufacturing clusters. Cloud compute dependencies rest on Amazon Web Services, Microsoft Azure, and Google Cloud data center networks with regional localization mandates. Single-source vulnerability concentrates in licensed therapist networks facing interstate practice restrictions. Distribution runs through benefits administrator portals for corporate contracts and app store marketplaces for direct-to-consumer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA's software-as-a-medical-device pathway and Brazil's ANVISA digital health framework creates cost-efficient market entry sequencing for platforms seeking therapeutic claim expansion.
For Market Incumbents: Lock in employer contract renewals through embedded EAP integration and white-label API architectures before AI-powered guidance erodes teletherapy pricing power. Defend margin position by deepening vertical integration into biometric sensor partnerships and securing interstate licensure compacts for therapist network scalability. Prioritize FDA premarket clearance investments for diagnostic claim differentiation against wellness-only competitors. For New Entrants and Emerging Players: Mid-market Indian enterprises with sub-15% wellness penetration offer lowest competitive density for first-mover positioning. Target Brazil's Portuguese-speaking Latin American corridor through ANVISA-structured regulatory entry before EU AI Act compliance costs favor well-capitalized incumbents. Deploy chatbot-assisted triage as lightweight entry wedge with minimal clinical validation burden. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA clearance requirements and EU AI Act conformity assessments strand development-stage platforms lacking dedicated compliance infrastructure. Long-term viability centers on B2B channel dominance with recurring revenue visibility exceeding direct-to-consumer volatility. Watch for employer benefits administrator procurement consolidation as inflection signal for platform valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-clearance Investment | FDA software-as-a-medical-device pathway unlocks insurance reimbursement and employer contract eligibility. |
| Employer Channel Migration | Benefits administrator procurement aggregates seat volume with lower churn than direct-to-consumer subscriptions. |
| Biometric-therapy Convergence | Apple Watch and Fitbit ecosystem integration enables personalized intervention triggered by heart rate variability data. |
| Geographic Expansion to Underpenetrated Markets | India's corporate wellness adoption below 15% offers first-mover positioning with localized CBT protocols. |
| AI Architecture Modularization | Composable service layers enable faster regulatory targeting and vertical-specific customization without full-stack redevelopment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with digital health platform executives, benefits administrators at Fortune 500 enterprises, FDA regulatory consultants, and EU AI Act compliance specialists with secondary validation against FDA 510(k) filings, DiGA directory listings, SEC S-1 disclosures, and app store download analytics. Bottom-up triangulation across subscription revenue estimates and top-down cross-checks against employer benefits spending data anchored market sizing.
Comparable-period anchoring to historical employer adoption curves and direct-to-consumer subscription fatigue patterns structured the projection horizon across deployment model, end user archetype, solution type, and regional regulatory cluster segmentation. CAGRs were derived from logistic diffusion modeling of corporate wellness penetration rates and AI capability advancement trajectories. Forecast inputs incorporated FDA clearance timeline distributions and EU AI Act risk-classification implementation schedules.
Inputs from platform executives and regulatory consultants were available through the study window; gaps in private company revenue disclosures and pre-revenue startup traction metrics introduce uncertainty bands around employer channel growth assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Depression Treatment Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
US Psychiatry Clinic Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Agoraphobia Treatment Market