
 Global Mental Health Care Software and Services Market | 2026-2036
Global Mental Health Care Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mental Health Care Software and Services Market Foresight
The capital-intensity divergence between cloud-native platforms and legacy on-premise systems is unwinding competitive dynamics across the sector. Epic Systems Corporation anchors its position through deep integration with hospital enterprise systems. Cerner Corporation leverages its installed base in acute care settings to extend behavioral health modules. Netsmart Technologies specializes in Medicaid-funded community providers, a segment larger rivals often overlook.
Mental health care software and services encompass digital platforms, clinical applications, and professional services designed to assess, monitor, treat, and coordinate care for psychiatric and behavioral conditions, typically operating through cloud-based architectures with HIPAA-compliant encryption, FHIR interoperability standards, and real-time analytics dashboards. Teletherapy platforms and electronic health records capture the largest revenue pools currently, while patient monitoring solutions represent the fastest-expanding segment as remote physiological tracking integrates with crisis intervention protocols. Clinical decision support tools occupy a mature niche where algorithmic diagnostic assistance now faces heightened scrutiny over bias and transparency.
The FDA regulates digital therapeutics as software-as-medical-device under evolving guidance that demands randomized trial evidence for reimbursement eligibility, while the EU AI Act classifies certain mental health algorithms as high-risk systems requiring conformity assessments before CE marking. HIPAA in the United States and GDPR in Europe impose divergent data residency and consent architectures that vendors must navigate simultaneously. Stakeholders should monitor how reimbursement parity laws in specific states reshape procurement criteria for behavioral clinics.
Market Dynamics
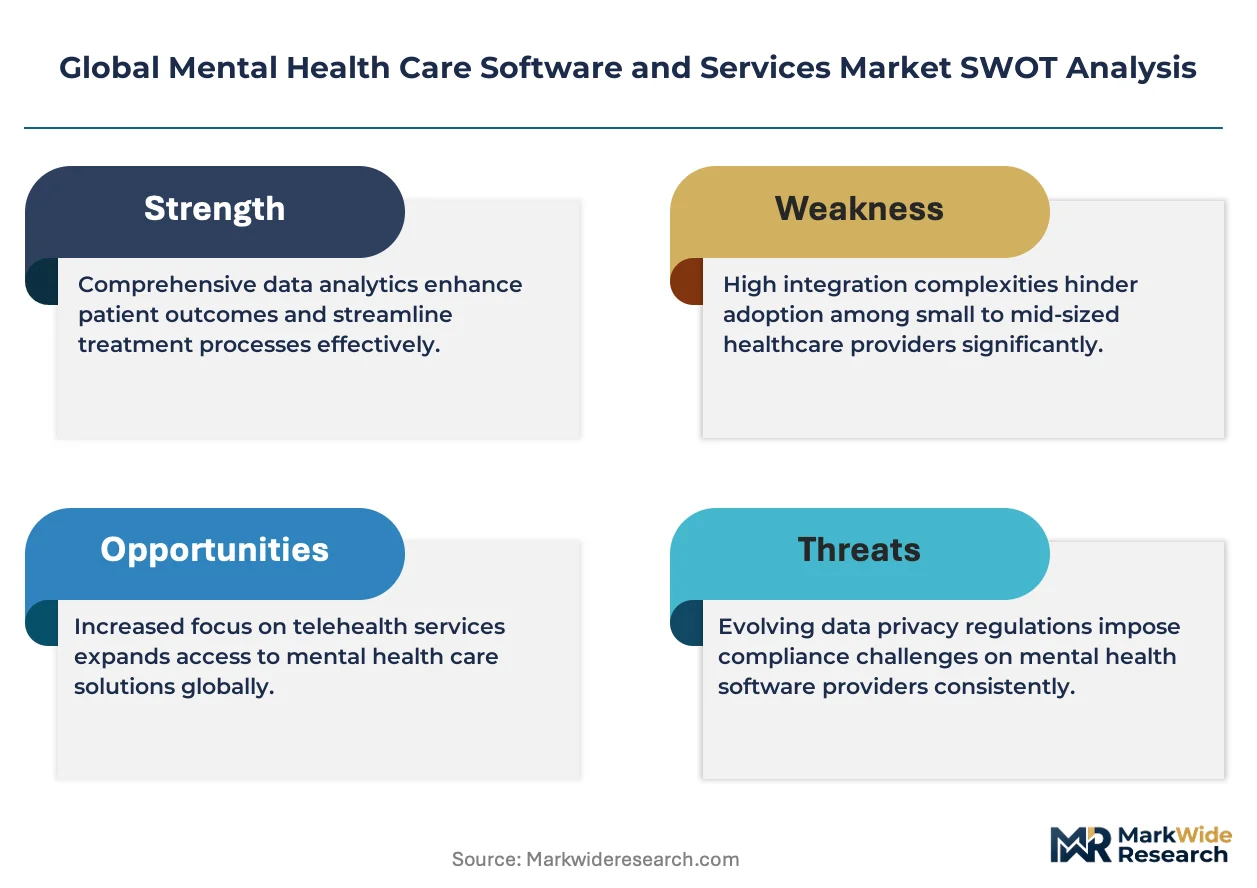
Interoperability mandates from the FDA's digital therapeutics pathway and Europe's MDR framework are forcing vendors to rebuild architecture stacks for simultaneous multi-jurisdiction compliance, compressing product development cycles and elevating capital requirements for market entry.
Growth Catalysts
- Reimbursement parity statutes:State-level mandates in the United States now require commercial insurers to cover teletherapy sessions at rates equivalent to in-person care, expanding addressable spend for behavioral clinics.
- FHIR interoperability standards:The HL7 Fast Healthcare Interoperability Resources specification enables seamless data exchange between electronic health records and specialized mental health platforms, reducing integration friction for health systems.
- Remote physiological monitoring:Wearable biosensors that track sleep architecture, heart rate variability, and galvanic skin response now feed real-time alerts into crisis intervention protocols, extending clinical reach beyond traditional encounters.
Market Restraints
- Clinical validation costs:The FDA's randomized controlled trial requirement for digital therapeutics reimbursement eligibility demands multi-million-dollar evidence generation that excludes lean software startups from the prescription-grade segment.
- Data residency fragmentation:Divergent HIPAA and GDPR consent architectures force vendors to maintain separate infrastructure stacks for United States and European patient data, duplicating fixed costs across geographies.
- Algorithmic bias scrutiny:Heightened regulatory attention to diagnostic algorithm transparency creates liability exposure for clinical decision support tools trained on non-representative patient populations.
Strategic Opportunities
- Medicaid-funded community providers:The United States safety-net segment remains underserved by enterprise vendors, creating white space for specialized platforms that address value-based contracting and social determinants documentation.
- Japan's aging demographic:METI's Silver ICT initiatives prioritize mental health monitoring for isolated elderly populations, opening procurement channels for culturally adapted cognitive behavioral therapy applications.
- AI-actuarial convergence:Integration of natural language processing with risk stratification algorithms enables payers to identify high-acuity members before crisis episodes, creating new revenue streams for predictive analytics vendors.
Industry Challenges
- Behavioral informatics talent scarcity:The intersection of clinical psychology, data science, and regulatory affairs commands premium compensation that strains mid-cap vendor hiring pipelines.
- Legacy EHR integration complexity:Proprietary data models from entrenched hospital information systems resist standardized API connections, extending implementation timelines and eroding margin on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mental Health Care Software and Services Market |
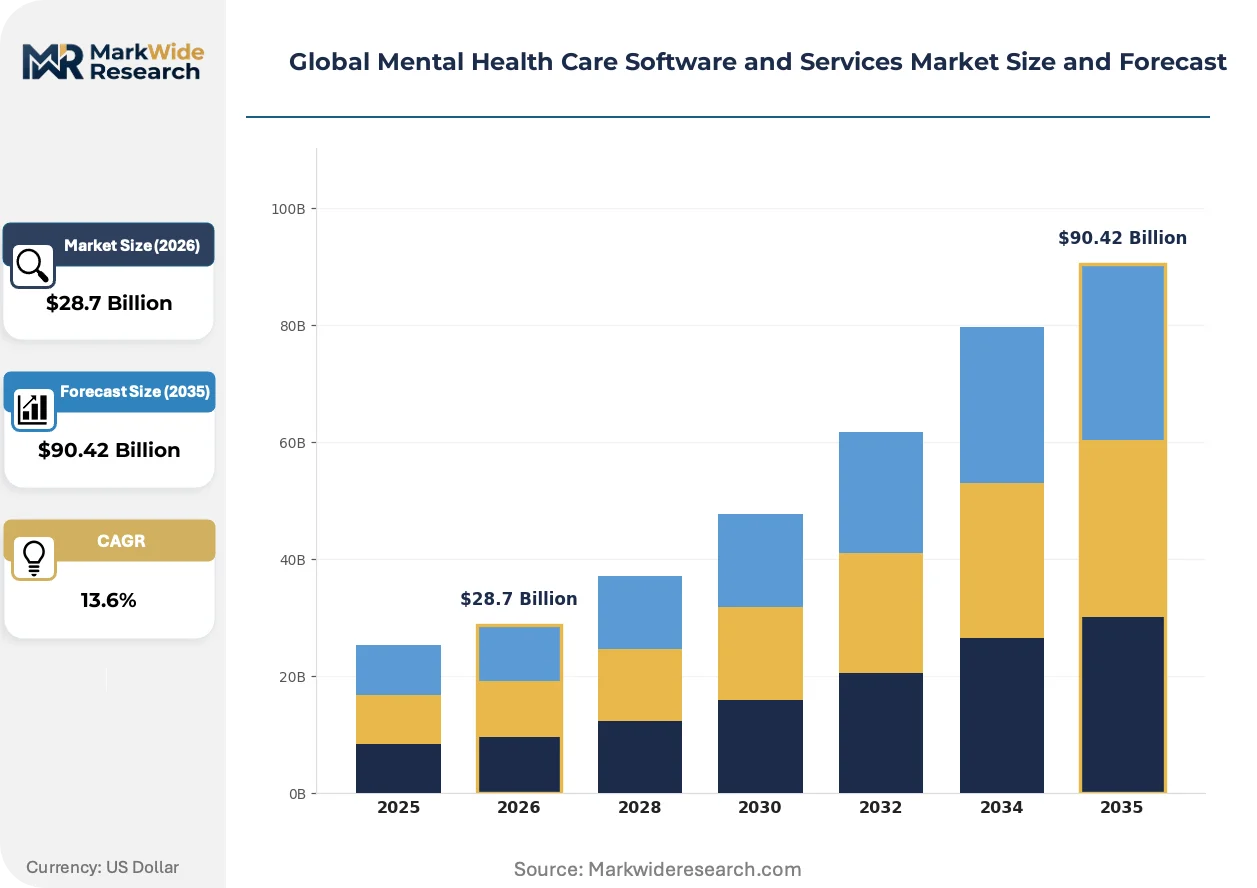
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $90.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Clinical Decision Support, Teletherapy Platform, Patient Monitoring, Electronic Health Records, Appointment Scheduling Service Type: Consultation, Therapy Sessions, Training & Education, Support & Crisis Management, Follow-up Care Application: Depression Management, Anxiety Treatment, PTSD Intervention, Substance Abuse Recovery, Stress Reduction End User: Behavioral Clinics, Psychiatric Clinics, Rehabilitation Centers, Counseling Centers, Academic Research Institutes |
| Companies Covered | Cerner Corporation, Core Solutions, Inc., AdvancedMD, Inc., Advanced Data Systems, Netsmart Technologies, Qualifacts Systems, Inc., Epic Systems Corporation, Credible Behavioral Health, Welligent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mental Health Care Software and Services Market Shifts & Advancements
Modular platform architectures are displacing monolithic systems as behavioral clinics demand configurable workflows that adapt to diverse funding streams and care delivery models without complete stack replacement.
Natural language processing is decomposing traditional clinical documentation by extracting structured diagnostic indicators from unstructured therapy session transcripts. Community mental health centers in the United States are piloting these tools to reduce administrative burden on licensed clinicians. The technology is compressing the time between patient encounter and billing submission while creating training data repositories for algorithmic diagnostic assistance.
The EU AI Act's high-risk system classification for certain mental health algorithms is forcing vendors to implement conformity assessment procedures before CE marking. European behavioral health platforms must now document algorithmic decision logic and maintain human oversight protocols for automated treatment recommendations. Germany's digital health applications directory (DiGA) has become the primary compliance pathway for software-as-medical-device seeking statutory health insurance reimbursement.
Subscription-based licensing is displacing perpetual software purchases as behavioral clinics prioritize operational expenditure flexibility over capital commitment. United States community providers facing Medicaid reimbursement volatility favor usage-based pricing that scales with patient census fluctuations. This shift pressures vendors to rebuild revenue recognition models and customer success functions around retention metrics rather than upfront license recognition.
Global Mental Health Care Software and Services Market Segmentation
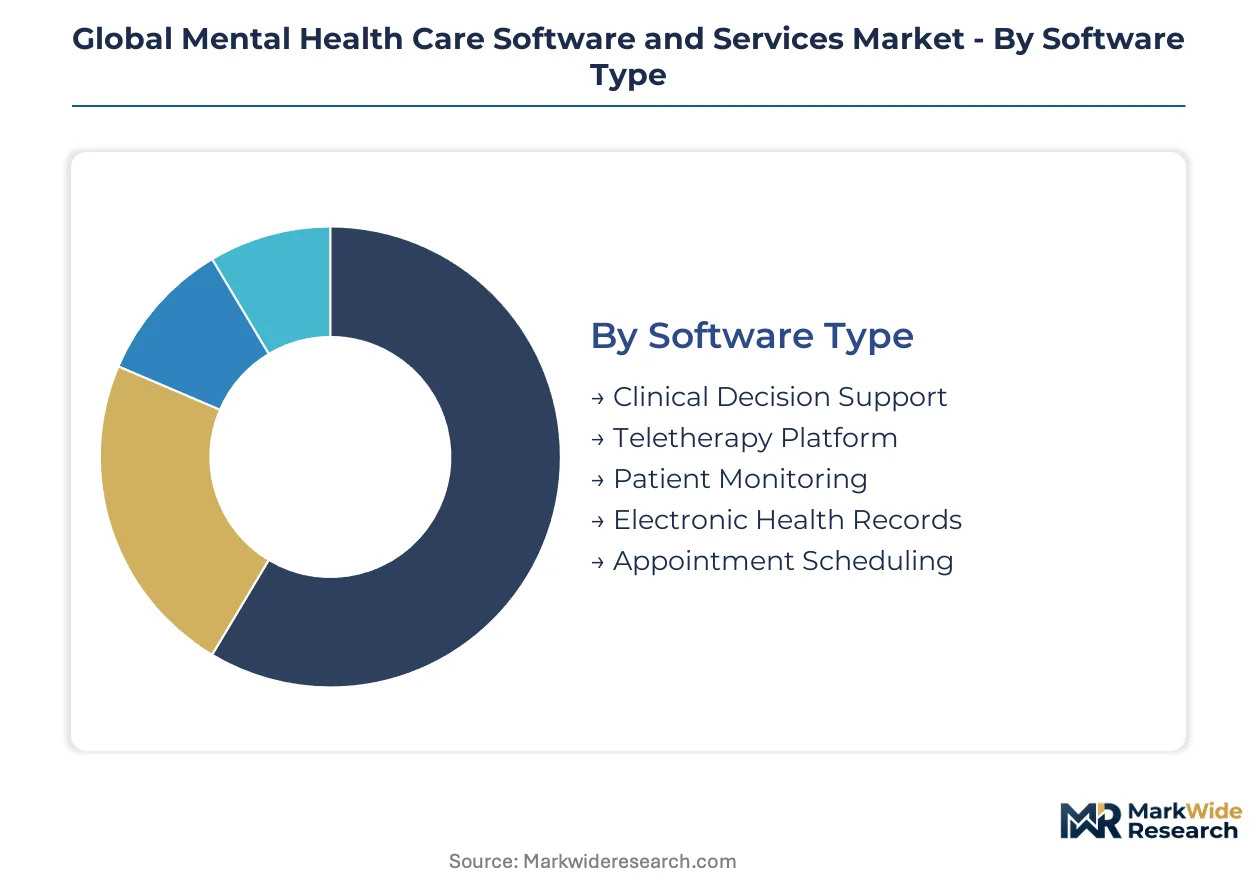
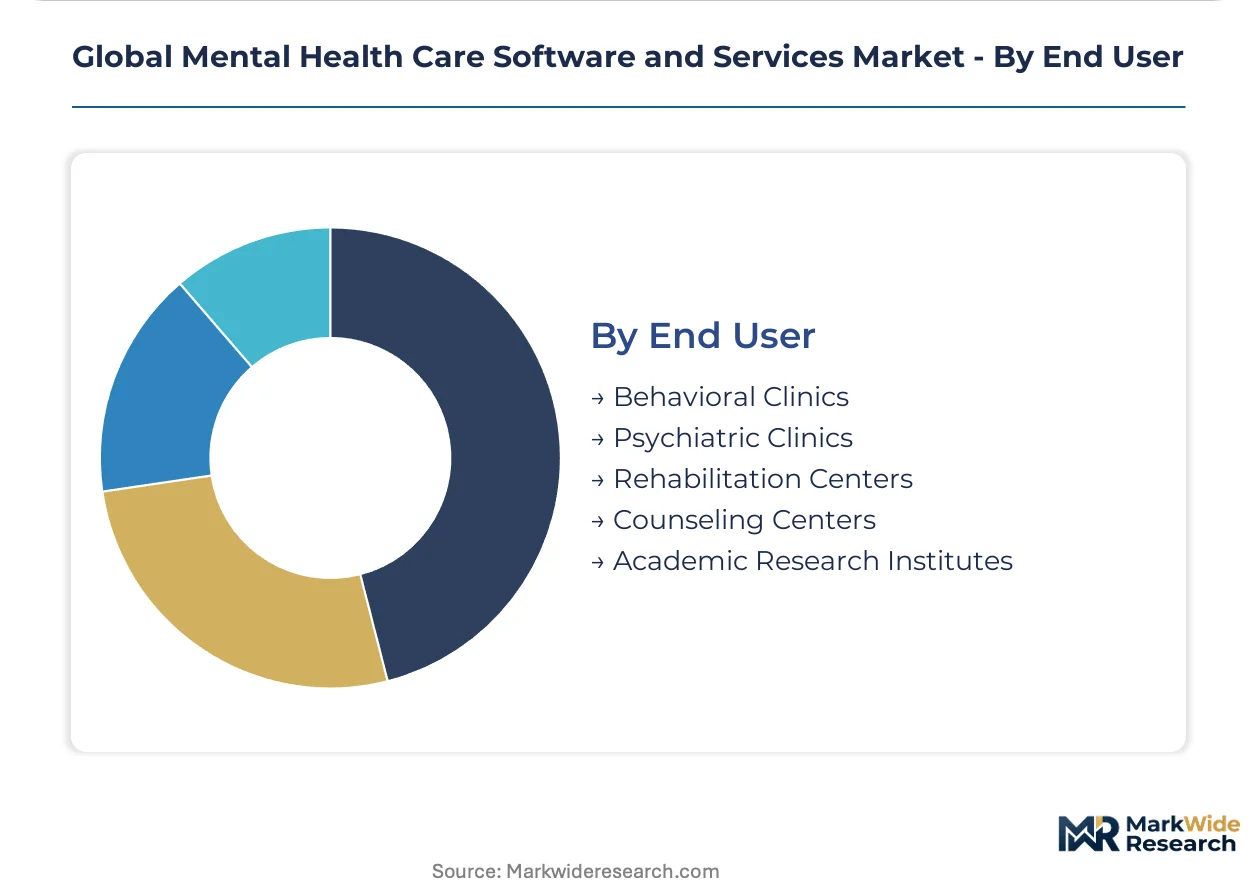
Segmentation in mental health care software reveals distinct procurement patterns across clinical settings. Behavioral clinics prioritize modular platforms that accommodate Medicaid billing complexity, while academic research institutes demand FHIR-compliant data architectures for multi-site trials.
Software Type:
Channel-mix variation is pronounced: enterprise health systems procure through integrated EHR contracts, while independent clinics favor direct SaaS subscriptions for specialized modules.
- Electronic Health Records:Core clinical data repositories with CPOE, medication management, and billing integration. Demand concentrates in United States health systems consolidating behavioral modules into enterprise Epic or Cerner deployments, constrained by legacy data migration costs.
- Teletherapy Platform:HIPAA-compliant video infrastructure with session documentation and payment processing. Germany's DiGA reimbursement pathway and United States state parity statutes are accelerating procurement by community providers seeking geographic expansion.
- Patient Monitoring:Wearable-integrated dashboards for physiological tracking and crisis alerts.
- Clinical Decision Support:Algorithmic diagnostic assistance with bias-audited recommendation engines.
- Appointment Scheduling:Automated intake and calendar coordination with insurance verification.
By volume, Electronic Health Records leads. By growth pace, Patient Monitoring is ahead.
Service Type:
Cost tier differentiation separates premium white-glove implementation from standardized self-service packages.
- Consultation:Pre-implementation workflow assessment and regulatory readiness planning. Japan's METI Silver ICT procurement channels favor vendors offering culturally adapted consultation for elderly care settings.
- Training & Education:Clinician certification programs for platform utilization and documentation compliance. United States Medicaid-funded community providers represent concentrated demand as workforce turnover necessitates continuous retraining investments.
- Therapy Sessions:Platform-mediated synchronous and asynchronous clinical encounters.
- Support & Crisis Management:24/7 escalation protocols and emergency response coordination.
- Follow-up Care:Longitudinal outcome tracking and relapse prevention workflows.
By revenue contribution, Consultation dominates. By margin expansion, Training & Education outperforms.
Application:
Application segmentation tracks reimbursement code availability and clinical evidence requirements.
- Depression Management:PHQ-9 integrated screening with cognitive behavioral therapy protocol libraries. United States commercial payers and Germany's statutory health insurance both reimburse digital applications with randomized trial evidence, concentrating vendor investment.
- PTSD Intervention:Trauma-focused CBT modules with exposure hierarchy management. United States Veterans Affairs health system and Japan's disaster mental health programs anchor procurement volume for specialized platforms.
- Anxiety Treatment:GAD-7 tracking with relaxation technique libraries and panic response tools.
- Substance Abuse Recovery:Medication-assisted treatment coordination with peer support integration.
- Stress Reduction:Workplace wellness and preventive intervention applications.
By addressable patient population, Depression Management leads. By regulatory approval velocity, Stress Reduction is climbing fastest.
End User:
Customer type determines pricing architecture and contract structure.
- Behavioral Clinics:Outpatient psychiatric and psychological practices with mixed payer panels. United States safety-net providers in Medicaid expansion states represent underserved demand, driving specialized vendor focus on value-based contracting documentation.
- Psychiatric Clinics:Medication-focused practices with higher acuity patient populations. Germany's hospital outpatient departments and Japan's psychiatric medical homes concentrate procurement for integrated medication-therapy platforms.
- Rehabilitation Centers:Residential and intensive outpatient substance use programs.
- Counseling Centers:University and employee assistance program settings.
- Academic Research Institutes:Clinical trial data collection and algorithmic validation sites.
By procurement frequency, Behavioral Clinics lead. By contract value, Academic Research Institutes command premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Community health centers in the United States exhibit the highest price elasticity, deferring platform upgrades until Medicaid reimbursement rates stabilize, whereas German statutory health insurance funds absorb premium pricing for DiGA-certified applications with minimal procurement friction.
United States
Behavioral clinics in Medicaid expansion states drive procurement volume for modular EHR systems with value-based contracting documentation. HIPAA compliance mandates and state-level reimbursement parity statutes shape vendor selection criteria. The Boston-Cambridge corridor concentrates digital therapeutics startups developing FDA-cleared prescription applications for depression management.
Germany
Hospital outpatient departments and psychiatric medical homes anchor demand for integrated medication-therapy platforms with statutory health insurance billing integration. The EU AI Act and MDR framework enforce conformity assessments for algorithmic diagnostic tools. Berlin's digital health cluster hosts vendors pursuing DiGA directory inclusion for cognitive behavioral therapy applications.
Japan
Isolated elderly populations and disaster mental health programs generate procurement for culturally adapted monitoring solutions. METI's Silver ICT initiatives prioritize mental health applications with Japanese-language natural language processing. Tokyo and Osaka metropolitan areas concentrate platform vendors adapting Western therapeutic protocols for local clinical workflows.
United Kingdom
NHS Digital's interoperability requirements accelerate FHIR-compliant platform adoption across integrated care systems. GDPR data residency rules and MHRA software-as-medical-device guidance constrain vendor architecture choices. London's health tech corridor attracts vendors targeting NHS England's Talking Therapies procurement frameworks for anxiety and depression services.
India
Corporate employee assistance programs and telemedicine startups drive demand for scalable cloud-native platforms with vernacular language support. CDSCO's evolving software-as-medical-device regulations and data localization requirements under the Digital Personal Data Protection Act shape market entry strategies. Bangalore and Hyderabad clusters host engineering operations for global mental health SaaS providers.
Global Mental Health Care Software and Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enterprise EHR vendors commanding premium pricing through hospital system integration while specialized behavioral health platforms compete on implementation speed and Medicaid billing expertise. The market structure tilts toward consolidation at the enterprise tier and fragmentation among point solutions. Three archetypes dominate: integrated health system vendors, behavioral health specialists, and teletherapy-native platforms. Competitive dynamics center on strategic partnerships with payers and geographic expansion into underserved safety-net segments.
Among enterprise-anchored vendors, Epic Systems Corporation and Cerner Corporation exemplify the integrated health system archetype through deep EHR penetration, while Netsmart Technologies occupies a specialist position serving Medicaid-funded community providers often bypassed by larger rivals. These three companies represent distinct competitive vectors—enterprise consolidation, acute care extension, and safety-net specialization—that collectively span the pricing and functionality spectrum.
| Leading Market Players |
|---|
| Cerner Corporation |
| Core Solutions, Inc. |
| AdvancedMD, Inc. |
| Advanced Data Systems |
| Netsmart Technologies |
| Qualifacts Systems, Inc. |
| Epic Systems Corporation |
| Credible Behavioral Health |
| Welligent, Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day implementation timelines for cloud-native behavioral health platforms compress procurement cycles and concentrate pricing power with vendors holding pre-certified FHIR interoperability stacks, while legacy system migration costs lock incumbents into maintenance-heavy contracts that subsidize SaaS expansion.
Pricing Analysis
Training and certification revenue streams now drive lifetime value for mental health software vendors as behavioral clinics prioritize workforce continuity over perpetual licensing. Three-tier pricing structure across enterprise, mid-market, and safety-net levels separates integrated EHR deployments from modular point solutions and Medicaid-optimized configurations. Pricing pressure stems from state reimbursement parity volatility that forces community providers to defer platform upgrades. United States safety-net clinics exhibit highest price sensitivity; German statutory health insurance funds show least sensitivity due to DiGA reimbursement certainty.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes have elevated inbound logistics costs for wearable biosensor hardware integrated into patient monitoring solutions. Cloud infrastructure provisioning concentrates in United States, Ireland, and Singapore data center clusters. Software development draws from specialized behavioral informatics talent pools in Boston-Cambridge, Berlin, and Bangalore. Single-source vulnerability sits with AWS and Azure hyperscaler dominance for HIPAA-compliant hosting. Distribution runs through direct SaaS sales teams for enterprise accounts and channel partners for community provider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated United States health systems that negotiate enterprise EHR contracts bundling behavioral modules, fragmenting procurement influence among independent community providers.
For Market Incumbents: Consolidate through acquisition of specialized Medicaid billing platforms to neutralize Netsmart Technologies' safety-net dominance and Cerner's acute care extension. Deepen FHIR interoperability certification investment to maintain pricing power against cloud-native challengers. Prioritize backward integration into wearable biosensor data pipelines to capture patient monitoring growth. For New Entrants and Emerging Players: Post-implementation support gaps in legacy EHR migrations present immediate white-space opportunity. Target United States Medicaid expansion states where reimbursement parity statutes expand addressable spend but incumbent vendors underserve value-based contracting documentation requirements. Deploy usage-based pricing models that align with community provider census volatility. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA digital therapeutics pathways and EU AI Act conformity assessments erect multi-million-dollar evidence barriers that concentrate prescription-grade segments among capitalized platforms. Target acquisition archetype: specialized behavioral health vendors with DiGA directory inclusion or FDA breakthrough device designation. Monitor state-level reimbursement parity statute adoption velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Interoperability Certification | Epic Systems and Cerner leverage HL7 standards to lock out modular competitors from enterprise procurement. |
| DiGA Directory Inclusion | German statutory health insurance reimbursement eligibility requires BfArM conformity assessment for cognitive behavioral therapy applications. |
| Backward Integration into Wearables | Patient monitoring vendors source biosensor hardware directly to reduce dependency on consumer electronics supply chains. |
| Medicaid Billing Specialization | Netsmart Technologies captures safety-net procurement through value-based contracting documentation modules rivals lack. |
| EU AI Act Conformity Assessment | Algorithmic diagnostic tools require documented decision logic and human oversight protocols before CE marking. |
Research Methodology
Two parallel data streams informed the analysis: structured conversations with behavioral health CIOs, Medicaid program directors, FDA regulatory consultants, and GPO contracts managers; and secondary validation against CMS Medicare reimbursement databases, FDA 510(k) clearance records, DiGA directory listings, and hospital procurement RFP archives. Bottom-up sizing triangulated vendor-reported implementation volumes with top-down spending estimates from national health IT budget disclosures.
Across the modeling period, forecasts segmented by deployment architecture, organization scale, clinical application, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating reimbursement parity statute adoption rates, FHIR interoperability mandate phase-in schedules, and digital therapeutics evidence generation timelines. Hyperscaler capex disclosures and wearable biosensor shipment data informed infrastructure and hardware segment projections.
Forecasts assume regulatory continuity in FDA digital therapeutics guidance, EU AI Act implementation, and HIPAA enforcement posture; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Behavioral Health Care Software and Services Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Depression Treatment Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Schizophrenia Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Postpartum Depression Management Market