
 North America Maternal Mental Health Market | 2026-2036
North America Maternal Mental Health Market Size, Share, and Industry Trends Forecast 2026-2036
North America Maternal Mental Health Market Analytics
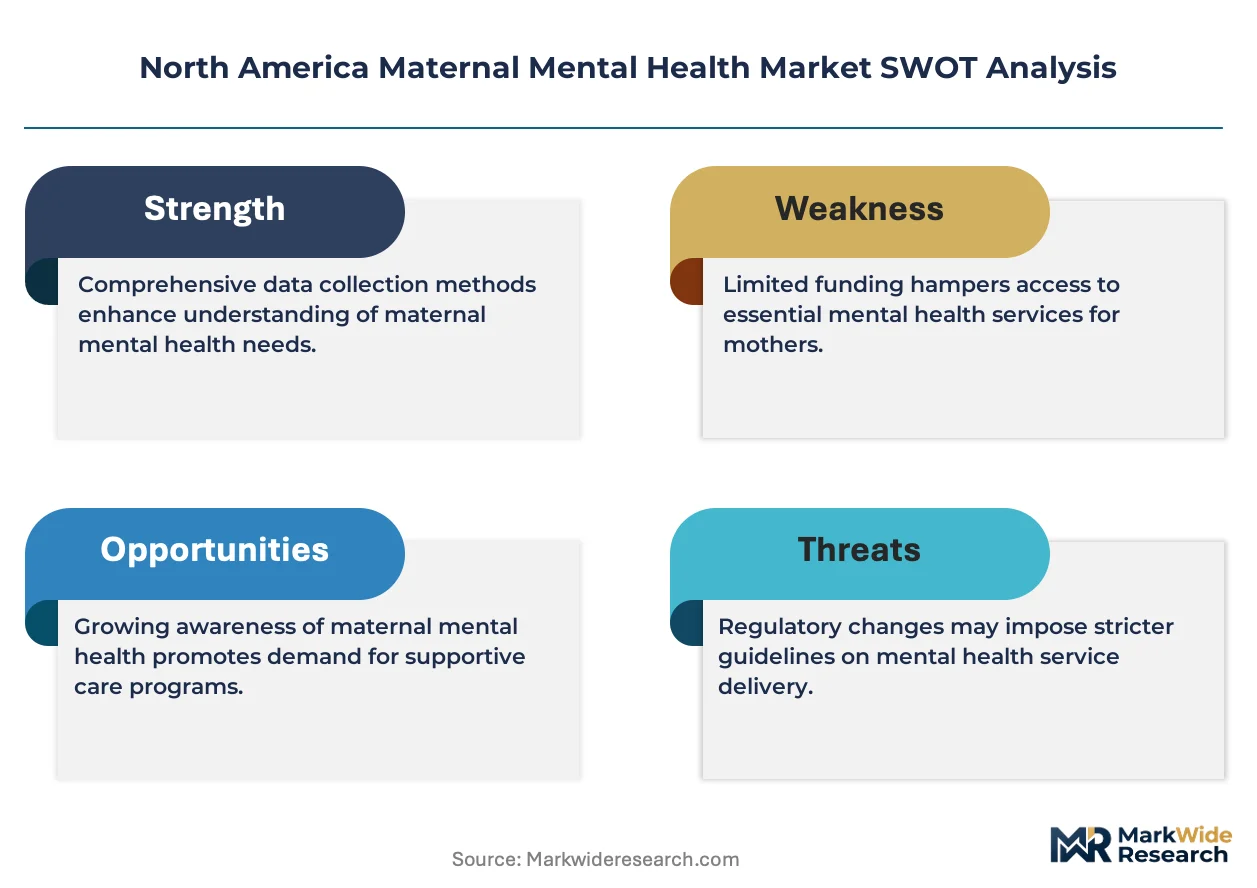
Modular care bundling is restructuring how employers and health plans purchase maternal mental health services, shifting from standalone teletherapy contracts to integrated perinatal benefit packages. Maven Clinic leverages its virtual care infrastructure to anchor employer-sponsored contracts across multiple states. Sage Therapeutics competes through its specialized pharmacotherapy focus for severe postpartum depression. SonderMind differentiates via its therapist matching technology that routes patients to in-network providers with perinatal training.
North America maternal mental health encompasses clinical and nonclinical interventions targeting psychiatric and psychological conditions occurring during pregnancy and the first postpartum year, including diagnostic screening protocols, psychotherapeutic modalities, psychopharmacologic treatments, and peer support systems designed to reduce maternal morbidity and infant developmental risk. Teletherapy delivery models are capturing the fastest expansion as asynchronous and synchronous virtual platforms reduce geographic access barriers and provider shortage constraints. Counseling services occupy the largest service type segment due to broader licensure availability and lower regulatory burden relative to medication management. Postpartum depression represents the most clinically recognized therapy area with established screening infrastructure through Edinburgh Postnatal Depression Scale deployment in obstetric and pediatric settings.
Medicaid state plan amendments, FDA psychopharmacologic labeling requirements for perinatal populations, and HIPAA privacy frameworks collectively shape reimbursement pathways and treatment accessibility across the United States and Canada. State Medicaid agencies determine coverage duration and provider qualification standards that directly gate market participation. Stakeholders must monitor evolving state-level postpartum extension policies and digital health platform licensure reciprocity agreements to anticipate reimbursement and competitive dynamics.
Market Dynamics
Medicaid state plan amendments are restructuring reimbursement eligibility for postpartum mental health services, eliminating the 60-day coverage cliff that previously interrupted treatment continuity for low-income mothers.
Growth Catalysts
- American Rescue Plan State Option:The 2021 federal provision permits states to extend Medicaid coverage for twelve months postpartum, expanding addressable patient populations in states adopting the amendment.
- Telehealth Infrastructure Maturation:Synchronous and asynchronous virtual platforms are penetrating rural counties where psychiatrist-to-patient ratios fall below national thresholds.
- Employer Benefit Expansion:Large self-insured employers are adding perinatal mental health modules to employee assistance programs, creating direct-to-consumer payment channels outside traditional insurance.
Market Restraints
- Provider Shortage Concentration:Perinatal psychiatrists and psychiatric-mental health nurse practitioners cluster in metropolitan corridors, leaving exurban and rural markets dependent on generalist providers without specialized training.
- Reimbursement Rate Compression:Medicaid fee schedules in multiple states reimburse below commercial insurance parity, constraining provider participation in publicly funded programs.
- Pharmacotherapy Liability Exposure:FDA labeling requirements for perinatal populations create prescribing hesitation among obstetricians managing depression in pregnant patients.
Strategic Opportunities
- Canada Provincial Expansion:Ontario and British Columbia perinatal mental health strategies remain underdeveloped relative to US market sophistication, presenting first-mover positioning for integrated care models.
- Digital Therapeutics Integration:FDA-cleared prescription digital therapeutics for depression are converging with obstetric electronic health record systems, enabling automated screening-to-treatment pathways.
- Peer Support Workforce Development:State Medicaid agencies are credentialing community health workers with lived experience, creating reimbursement pathways for nonclinical interventions.
Industry Challenges
- Cross-State Licensure Fragmentation:Teletherapy platforms face operational complexity from non-reciprocal professional licensing requirements between US states, limiting provider pool elasticity.
- Electronic Health Record Interoperability:Edinburgh Postnatal Depression Scale screening data rarely flows automatically from obstetric to pediatric to mental health records, creating care coordination gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Maternal Mental Health Market |
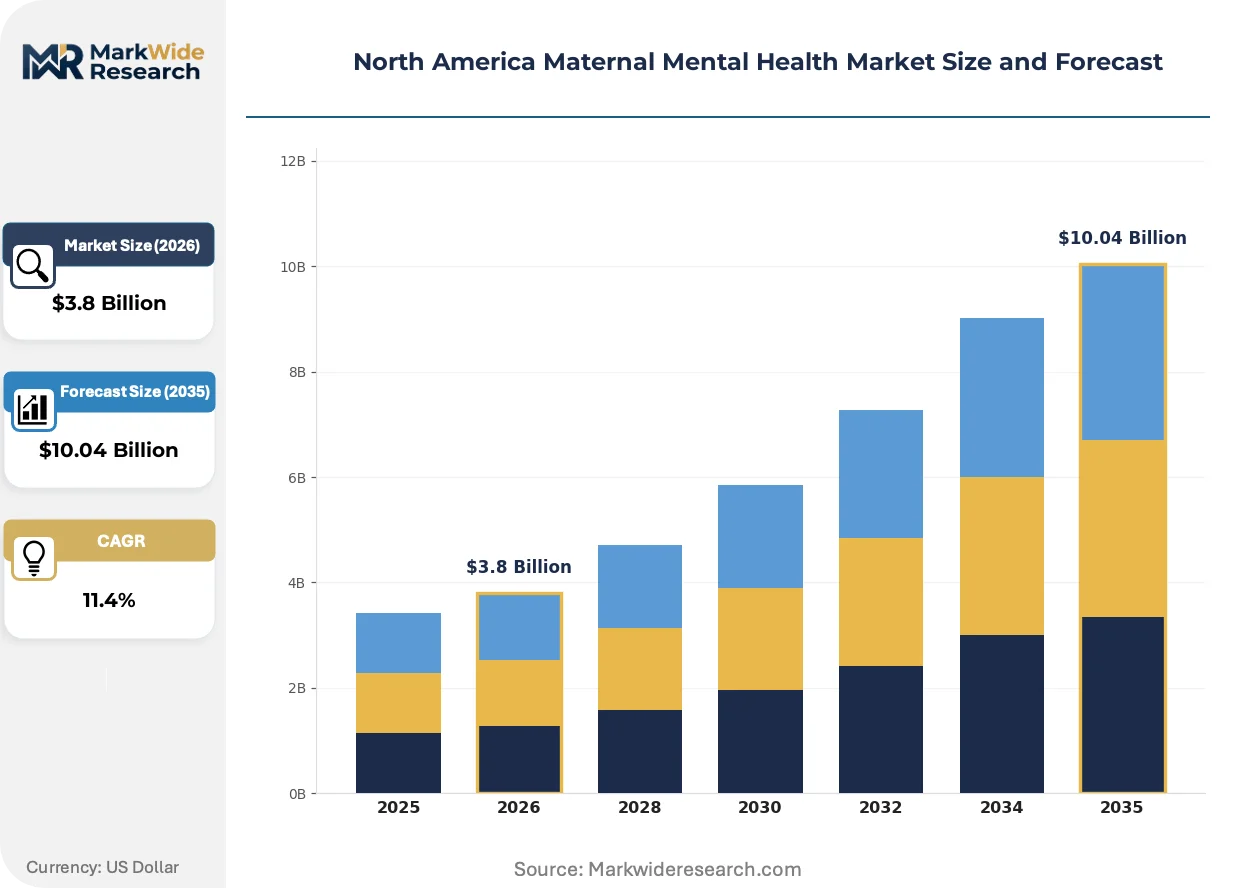
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Counseling, Medication, Support Groups, Teletherapy Therapy Area: Postpartum Depression, Anxiety Disorders, Stress Management, Psychosis Patient Type: Expecting Mothers, New Mothers, Healthcare Providers, Family Members Delivery Model: In-Person, Online, Hybrid, Community-Based |
| Companies Covered | Sage Therapeutics, Maven Clinic, Happify Health, SonderMind, Wildflower Health, Brightside Health, Postpartum Support International, March of Dimes, Canopie, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Maternal Mental Health Market Evolving Landscape
Asynchronous teletherapy platforms are compressing the interval between symptom onset and clinical intake, restructuring how health systems triage perinatal mood disorders outside traditional appointment windows.
Remote patient monitoring with biometric wearables is overtaking self-reported symptom tracking in high-risk pregnancy clinics. Maternal-fetal medicine departments at academic medical centers are piloting continuous heart rate variability and sleep architecture monitoring to detect depression onset before clinical presentation. This sensor-based approach is enabling preemptive outreach that reduces emergency department utilization for psychiatric decompensation.
The 2021 American Rescue Plan's state option to extend Medicaid postpartum coverage is reshaping payer-provider contracting. State Medicaid agencies in California, Illinois, and New Jersey have amended their state plans, triggering health plan requests for proposals that prioritize perinatal care coordination capabilities. Managed care organizations are responding with dedicated maternal mental health care manager staffing.
Large self-insured employers are unbundling perinatal mental health from general employee assistance programs, contracting directly with specialized virtual care platforms. This bypasses traditional health plan intermediaries and compresses implementation timelines from 18-month benefit cycles to 90-day pilot agreements. The shift is most visible in technology and financial services sectors with above-average female workforce concentrations.
North America Maternal Mental Health Market Segmentation
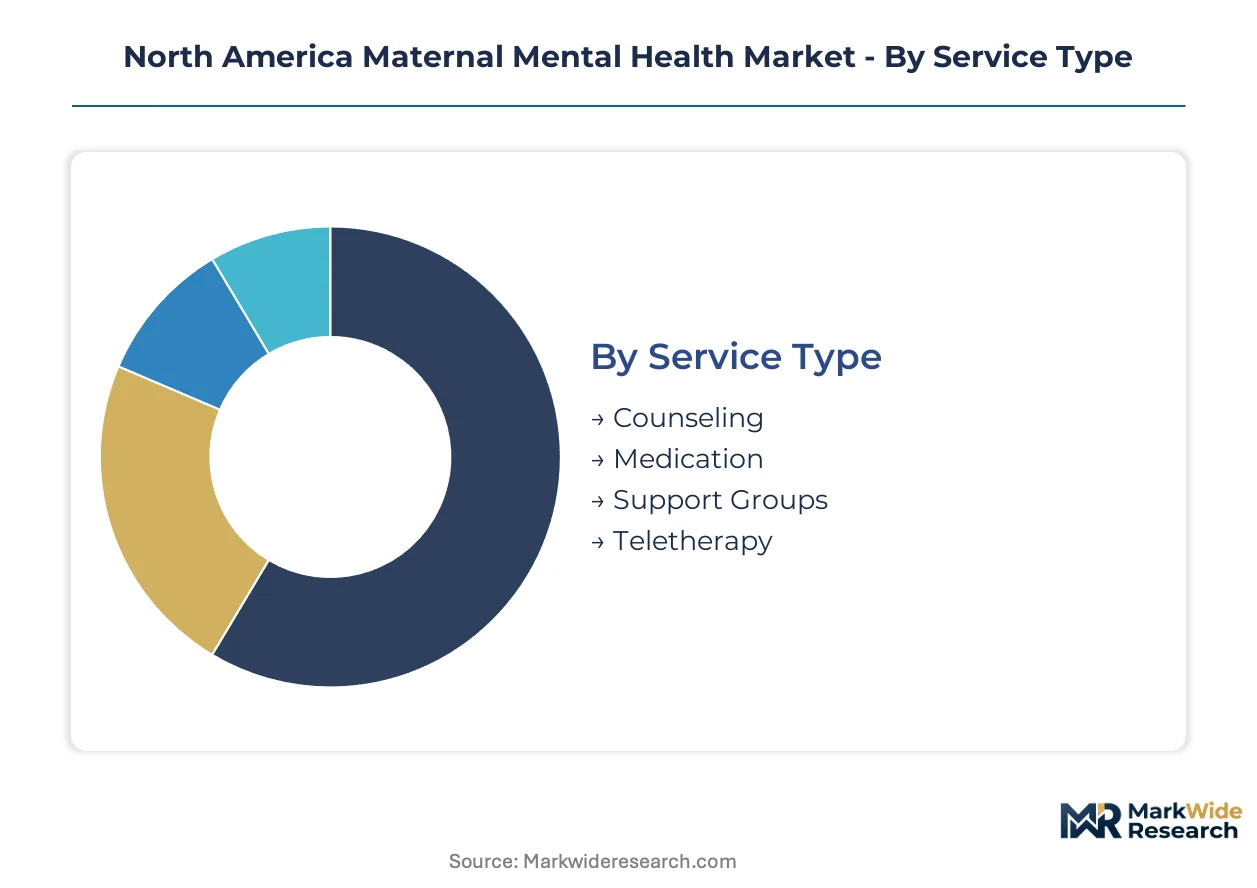
Maternal mental health services fragment across four distinct dimensions that determine reimbursement pathways, provider qualifications, and patient access patterns. Service type and delivery model classifications particularly shape how Medicaid agencies and commercial payers structure prior authorization requirements.
Service Type:
Buyers differentiate primarily by clinical licensure requirements and regulatory burden intensity.
- Counseling:Licensed clinical social workers and professional counselors deliver psychotherapeutic interventions including cognitive behavioral therapy and interpersonal therapy adapted for perinatal populations. California's perinatal mental health collaborative networks concentrate demand here due to broader licensure reciprocity and lower malpractice exposure relative to medication management. Medicaid fee schedules in multiple states reimburse counseling at parity with medical services.
- Teletherapy:Synchronous video and asynchronous messaging platforms connect patients with specialized perinatal providers across state lines. Rural counties in Texas and Montana where psychiatrist-to-patient ratios fall below national thresholds drive fastest adoption. HIPAA-compliant infrastructure investments by virtual care platforms reduce geographic access barriers.
- Medication:Psychopharmacologic management requires prescriber credentials—psychiatrists, psychiatric-mental health nurse practitioners, or obstetricians with specialized training. FDA labeling requirements for perinatal populations create prescribing hesitation that constrains volume.
- Support Groups:Peer-facilitated interventions led by community health workers with lived experience. State Medicaid agencies in Illinois and New Jersey have established reimbursement pathways for these nonclinical services.
Counseling leads volumes today; teletherapy is gaining share fastest.
Therapy Area:
Clinical recognition and screening infrastructure maturity determine addressable patient pools.
- Postpartum Depression:Edinburgh Postnatal Depression Scale deployment in obstetric and pediatric settings creates established referral pathways. Academic medical centers in California and New York anchor specialized treatment programs with dedicated perinatal psychiatrist staffing.
- Anxiety Disorders:Generalized anxiety and perinatal-specific obsessions receive less systematic screening than depression. Employer-sponsored contracts in technology and financial services sectors increasingly cover these conditions.
- Stress Management:Subclinical psychological distress interventions target prevention and early intervention. Community health centers in Illinois integrate these services into prenatal care bundles.
- Psychosis:Severe postpartum psychiatric emergencies requiring hospitalization. Limited to specialized perinatal psychiatry units at academic medical centers in major metropolitan corridors.
Postpartum depression dominates clinical volume; anxiety disorders are expanding most quickly as screening protocols broaden.
Patient Type:
Risk stratification and care coordination responsibility shift across these categories.
- Expecting Mothers:Prenatal mental health screening and preventive interventions during pregnancy. California's Medicaid state plan amendments extend coverage through twelve months postpartum.
- New Mothers:Postpartum depression treatment and continuity of care during the first year after delivery. Hospital networks are widening intake pipelines for this population.
- Healthcare Providers:Training and consultation services for obstetricians, pediatricians, and primary care providers. Perinatal psychiatry access programs in New Jersey concentrate here.
- Family Members:Psychoeducation and support for partners and extended family. Emerging reimbursement category with limited Medicaid coverage.
New mothers represent the largest addressable population; expecting mothers are climbing the fastest as prenatal screening expands.
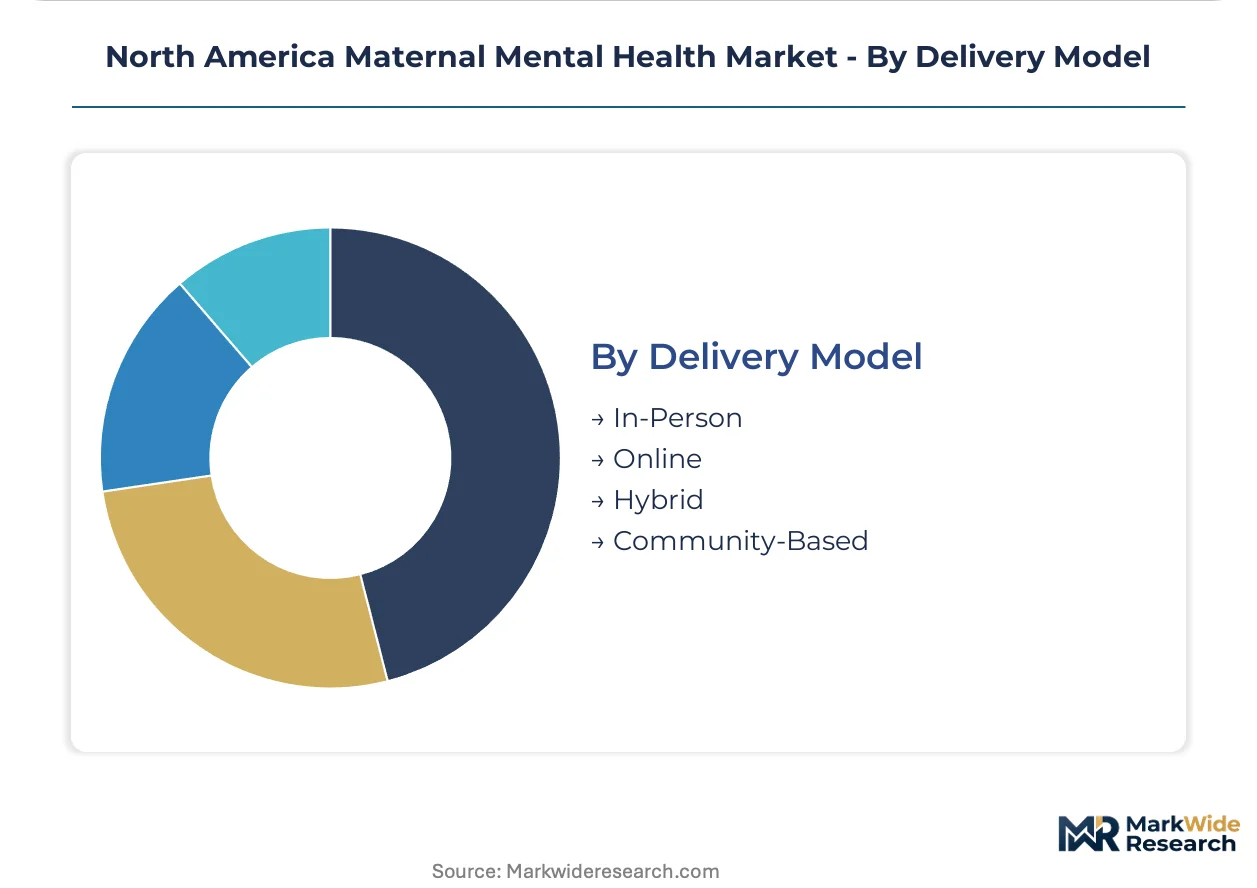
Delivery Model:
Capital intensity and provider geographic distribution drive model selection.
- In-Person:Traditional clinic-based and hospital-embedded services requiring physical infrastructure. Metropolitan corridors with perinatal psychiatrist concentration.
- Online:Fully virtual platforms with no physical care component. Rural and exurban markets where provider shortages are most acute.
- Hybrid:Blended models combining initial in-person assessment with ongoing virtual follow-up. Preferred by large self-insured employers seeking care continuity.
- Community-Based:Services delivered in nonclinical settings—homes, community centers, faith organizations. Peer support workforce development in New Jersey and Illinois.
In-person services retain volume leadership; hybrid models are gaining share fastest as employers seek flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maternal mental health infrastructure in North America traces its modern scaling to California's 2006 perinatal depression screening mandates, which established the first statewide protocols for Edinburgh Postnatal Depression Scale deployment in obstetric settings. This California model subsequently diffused through Medicaid waiver demonstrations and employer benefit expansions across the United States and Canada.
United States
California, Illinois, and New Jersey anchor service volume through Medicaid state plan amendments extending postpartum coverage to twelve months. The 2021 American Rescue Plan's state option eliminated prior 60-day eligibility cliffs, triggering managed care organization contracting for dedicated maternal mental health care managers. Texas and Montana rural counties exhibit fastest teletherapy adoption where psychiatrist-to-patient ratios fall below national thresholds.
Canada
Ontario and British Columbia perinatal mental health strategies remain underdeveloped relative to US market sophistication, presenting positioning opportunities for integrated care models. Health Canada guidelines for perinatal psychopharmacology lag FDA labeling frameworks, creating prescribing hesitation among obstetricians. Toronto and Vancouver academic medical centers pilot community health worker credentialing programs for peer support reimbursement.
Mexico
Mexico City Metro concentrates private-sector demand through employer-sponsored contracts with multinational corporations in financial services and technology sectors. The Secretaría de Salud's national perinatal mental health guidelines, issued in 2020, lack enforcement mechanisms or dedicated reimbursement pathways. Guadalajara and Monterrey hospital networks experiment with hybrid delivery models combining in-person assessment and virtual follow-up.
North America Maternal Mental Health Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service specialization and care coordination capabilities. The vendor base stratifies between virtual care platforms with employer direct-contracting infrastructure, specialized pharmacotherapy developers with FDA perinatal labeling, and therapist-matching networks with perinatal training credentialing. Three archetypes dominate: integrated perinatal benefit packagers, severe postpartum depression pharmacotherapy specialists, and peer support workforce developers. Geographic expansion through state Medicaid reciprocity agreements and vertical integration into obstetric electronic health record systems constitute the dominant competitive vectors.
Within the pharmacotherapy-specialist tier, Sage Therapeutics occupies a position exemplifying FDA-regulated perinatal drug development. Among virtual care platforms, Maven Clinic represents the employer-direct contracting archetype with multi-state infrastructure deployment. In the therapist-matching segment, SonderMind exemplifies technology-enabled routing to in-network providers with perinatal training credentials.
| Leading Market Players |
|---|
| Sage Therapeutics |
| Maven Clinic |
| Happify Health |
| SonderMind |
| Wildflower Health |
| Brightside Health |
| Postpartum Support International |
| March of Dimes |
| Canopie |
| Others |
Value Network & Pricing Analysis
Telehealth platform maturation is compressing per-session delivery costs while concentrating provider network ownership among multi-state virtual care infrastructure operators, simultaneously reshaping cost economics and supply concentration in maternal mental health service delivery.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specialized perinatal psychiatrist consultations from licensed clinical social worker counseling sessions and community health worker peer support interventions. Price differentiation hinges on prescriber credential requirements and care coordination intensity. Cost compression in the standard tier is intensifying because Medicaid fee schedule parity pressures constrain provider participation margins. Self-insured employers in technology and financial services sectors demonstrate lowest price sensitivity, while state Medicaid agencies exhibit highest price sensitivity due to budget cycle constraints.
Supply Chain Analysis
Freight cost considerations are minimal in this services-dominant market, though logistics for FDA-cleared prescription digital therapeutics and biometric wearable distribution introduce physical supply chain elements. Provider labor supply concentrates in California, New York, and Illinois where perinatal psychiatry training programs anchor specialist pipelines. Raw material dependencies include cloud computing infrastructure, HIPAA-compliant telehealth software licenses, and Edinburgh Postnatal Depression Scale screening tool intellectual property. Single-source vulnerability sits with interstate licensure reciprocity agreements that gate provider pool elasticity. Distribution runs through employer benefits administrators, state Medicaid managed care organizations, and hospital network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as demand shifts toward premium specifications requiring specialized perinatal training credentials and integrated care coordination capabilities that command sustained reimbursement premiums.
For Market Incumbents: Acquire specialized perinatal psychiatry practices in metropolitan corridors to secure prescriber capacity before Medicaid state plan amendments trigger demand surges. Consolidate teletherapy platforms with established HIPAA infrastructure to defend against new entrants lacking multi-state licensure reciprocity agreements. Prioritize backward integration into obstetric electronic health record systems to capture automated screening-to-treatment pathway revenue. For New Entrants and Emerging Players: Enter via Ontario and British Columbia where perinatal mental health strategies remain underdeveloped relative to US market sophistication. Target credentialing programs for community health workers with lived experience, as Illinois and New Jersey Medicaid agencies establish reimbursement pathways for peer support workforce development. Pursue direct-to-employer contracting in technology sector self-insured plans to bypass traditional health plan intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among therapist-matching networks with perinatal training credentialing technology but limited care coordination infrastructure. Long-term viability over the five-to-ten year window favors platforms with vertical integration into both provider credentialing and payer contracting capabilities. Monitor FDA psychopharmacologic labeling decisions for perinatal populations as the critical inflection signal for pharmacotherapy-specialist acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Medicaid State Plan Amendment Navigation | California's twelve-month postpartum extension triggers health plan RFPs prioritizing perinatal care coordination capabilities. |
| Perinatal Psychiatry Workforce Development | Academic medical center partnerships in New York and California secure prescriber capacity for severe postpartum depression treatment. |
| Digital Therapeutics FDA Clearance | Prescription digital therapeutics integration with obstetric EHR systems enables automated depression screening-to-treatment pathways. |
| Employer Direct Contracting Infrastructure | Technology sector self-insured employers unbundle perinatal mental health from general EAPs, compressing implementation timelines. |
| Interstate Licensure Reciprocity Expansion | Multi-state virtual care platforms reduce operational complexity from non-reciprocal professional licensing requirements. |
Research Methodology
Direct dialogue with maternal mental health platform executives, state Medicaid policy directors, perinatal psychiatry department chairs, employer benefits administrators, and FDA regulatory affairs specialists grounded qualitative findings. Secondary validation drew from CMS Medicare and Medicaid data, FDA psychopharmacologic labeling archives, state health department postpartum coverage extension filings, and hospital procurement databases. Bottom-up service volume estimates triangulated against top-down payer expenditure models.
Segment-level projections across service type, therapy area, patient type, and delivery model dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from Medicaid enrollment expansion trajectories, employer benefit adoption curves, and telehealth penetration rates in rural counties with psychiatrist shortages. Forecast inputs incorporated FDA perinatal labeling decision timelines and state Medicaid state plan amendment adoption schedules.
Inputs from state Medicaid agencies and hospital network procurement committees were available through the study window; gaps in commercial payer claims data introduce uncertainty bands around employer-sponsored segment estimates. Forecasts reflect assumptions regarding twelve-month postpartum coverage extension adoption rates and telehealth platform licensure reciprocity expansion. A model refresh is warranted upon material change in FDA psychopharmacologic labeling requirements for perinatal populations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Mental Health Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
Agoraphobia Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market