
 Global Behavioral Health Market | 2026-2036
Global Behavioral Health Market Size, Share, and Industry Trends Forecast 2026-2036
Global Behavioral Health Market Analysis
Modular care packaging is shifting how employers and payers purchase behavioral health services, unbundling traditional inpatient bundles into discrete outpatient, digital, and crisis-intervention components. Universal Health Services dominates inpatient psychiatric capacity across multiple US states. Acadia Healthcare specializes in facility-based addiction and residential treatment. Elevance Health leverages its insurance platform to integrate behavioral and medical claims data.
Behavioral health encompasses the clinical diagnosis, treatment, and management of mental health conditions and substance use disorders through pharmacological, psychotherapeutic, and psychosocial interventions, typically delivered via multidisciplinary teams operating under diagnostic frameworks such as DSM-5 or ICD-11. Teletherapy platforms now handle intake, triage, and ongoing cognitive behavioral therapy sessions with lower overhead than brick-and-mortar equivalents. EHR systems segment captures margin pools where interoperability mandates force consolidation among vendors serving psychiatrists and counselors. Virtual Reality technology leads in exposure therapy for PTSD and phobia treatment, though deployment remains concentrated in academic medical centers and specialized clinics.
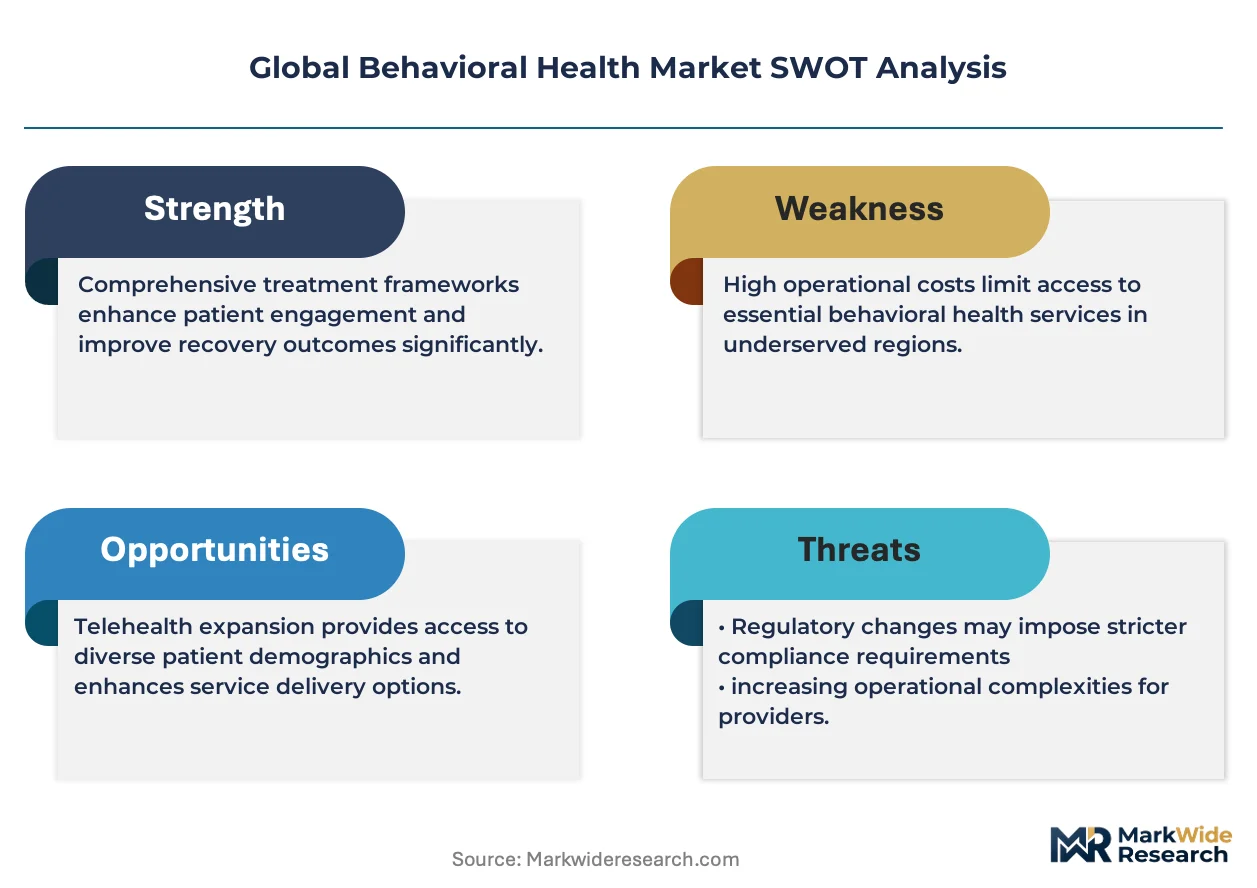
FDA digital therapeutics oversight and HIPAA privacy requirements shape product development timelines and reimbursement pathways for technology-enabled behavioral interventions. The EU AI Act imposes risk-classification obligations on algorithmic mental health diagnostics deployed in European clinical settings. Stakeholders must monitor evolving FDA enforcement discretion for prescription digital therapeutics as clinical evidence standards tighten.
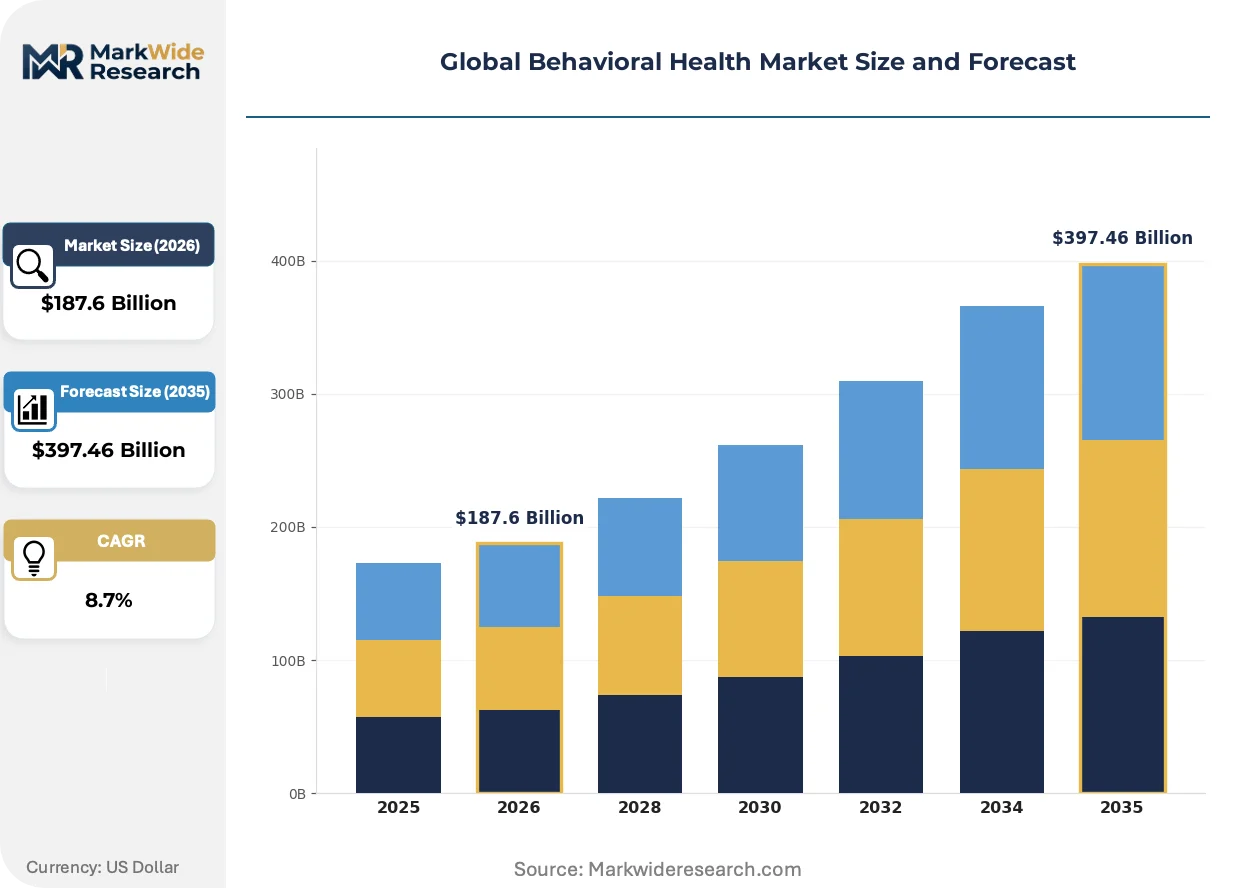
Market Dynamics
Modular care packaging is fragmenting traditional behavioral health purchasing, forcing providers to unbundle inpatient bundles into discrete outpatient, digital, and crisis-intervention components that employers and payers now procure separately.
Growth Catalysts
- FDA Digital Therapeutics Pathway:Software-based interventions for substance use disorders and insomnia now qualify for expedited review, accelerating commercialization timelines for prescription digital therapeutics developers.
- Employer Mental Health Parity Mandates:Large employers in the United States face regulatory pressure to expand coverage for anxiety and depression treatment, driving service utilization through integrated care models.
- Teletherapy Platform Scalability:Virtual intake, triage, and cognitive behavioral therapy delivery achieves lower overhead than brick-and-mortar equivalents, enabling geographic expansion without facility capital.
Market Restraints
- HIPAA Compliance Burden:Privacy requirements impose development timeline delays and reimbursement pathway friction for technology-enabled behavioral interventions seeking scale.
- Clinician Supply Concentration:Psychiatrist and licensed psychologist shortages cluster in urban United States corridors, leaving rural and exurban markets underserved regardless of platform reach.
- Reimbursement Rate Compression:Medicare and Medicaid fee schedules for psychotherapy sessions lag private payer rates, constraining margin expansion for providers dependent on public coverage.
Strategic Opportunities
- VR Exposure Therapy Deployment:Academic medical centers in Germany and the United States demonstrate efficacy for PTSD and phobia treatment, creating white space for specialized clinic network expansion.
- EU AI Act Algorithmic Diagnostics:Risk-classification obligations for mental health diagnostics create compliance service opportunities for vendors serving European clinical settings.
- EHR Interoperability Mandates:Consolidation among vendors serving psychiatrists and counselors generates margin pools for platforms integrating behavioral and medical claims data.
Industry Challenges
- Evidence Generation Timeline:Randomized controlled trial requirements for prescription digital therapeutics extend development cycles beyond typical software release cadences.
- Workforce Credentialing Complexity:Interstate licensure reciprocity gaps complicate teletherapy staffing models, particularly for practitioners serving multiple United States jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Behavioral Health Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psychiatrists, Psychologists, Counselors, Social Workers Technology: Teletherapy, Mobile Apps, EHR Systems, Virtual Reality End User: Clinics, Hospitals, Residential Treatment Centers, Schools Application: Anxiety Disorders, Mood Disorders, Substance Abuse, PTSD |
| Companies Covered | Universal Health Services, Acadia Healthcare, Magellan Health, Elevance Health, Centene Corporation, Cigna, CareTech Holdings, Pyramid Healthcare, Sevita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Behavioral Health Market Emerging Trajectories
Artificial intelligence and immersive technologies are restructuring how behavioral health interventions are developed, regulated, and consumed, compressing traditional care delivery timelines while raising new compliance obligations.
Machine learning algorithms are integrating into diagnostic workflows for depression screening and suicide risk stratification. Payers and large health systems in the United States pilot these tools for triage automation. The technology is integrating clinical decision support with population health management platforms, compressing the gap between identification and intervention.
The EU AI Act imposes risk-classification obligations on algorithmic mental health diagnostics deployed in European clinical settings. Manufacturers must demonstrate conformity with transparency and human oversight requirements before market entry. Mental health apps with diagnostic functions face reclassification as high-risk medical devices, forcing architectural redesigns.
Employer purchasers now unbundle behavioral health benefits from traditional medical plan structures, contracting directly with specialized vendors for employee assistance programs and digital therapeutics. Large United States employers lead this disintermediation, bypassing incumbent carriers. Procurement teams evaluate vendors on clinical outcome metrics rather than network size alone.
Global Behavioral Health Market Segmentation
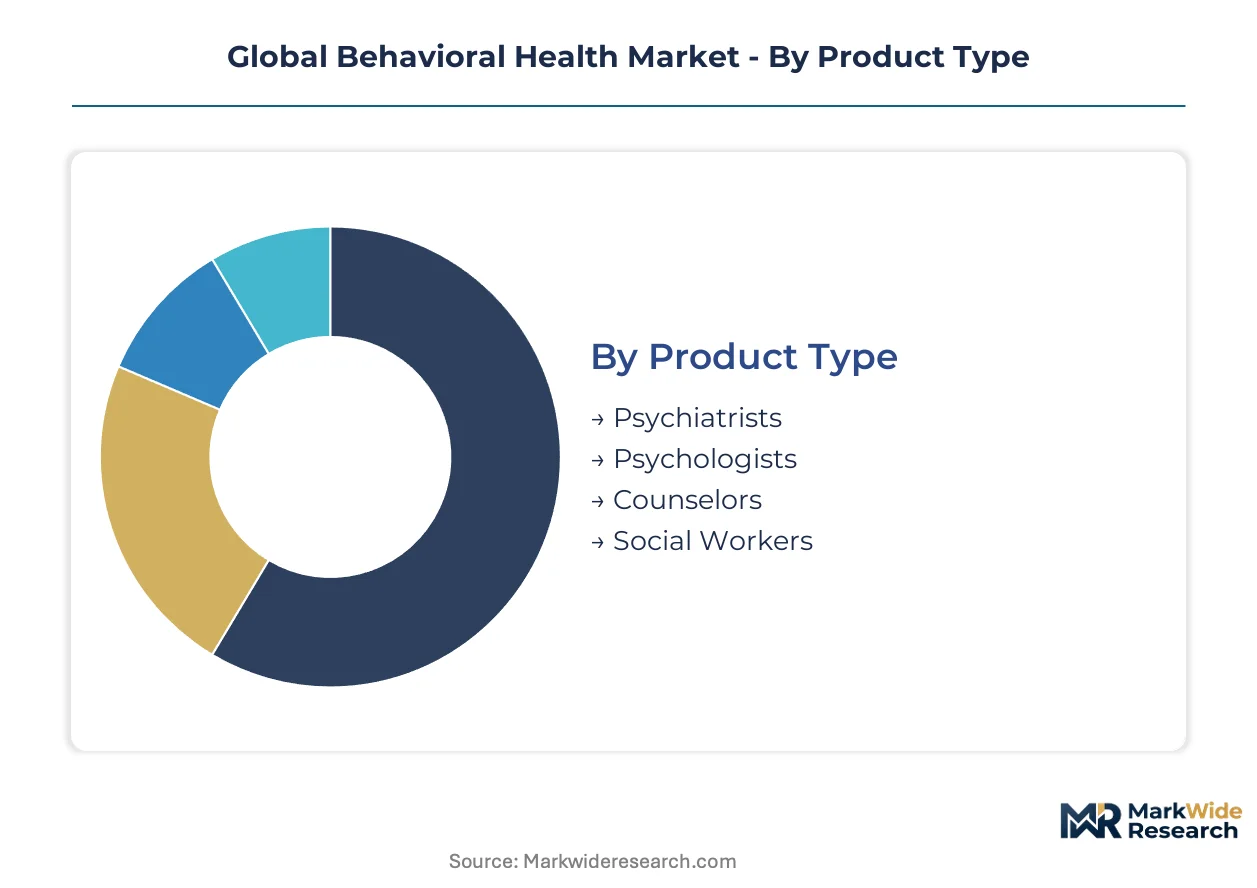
Behavioral health delivery fragments across professional credentials, technology modalities, care settings, and diagnostic categories. Each segment carries distinct regulatory burdens, reimbursement codes, and workforce supply constraints that shape vendor strategy and payer procurement decisions.
Product Type:
FDA oversight concentrates on pharmacological interventions prescribed by psychiatrists, while state licensing boards govern psychologist and counselor practice scopes. Medicare reimbursement rates vary substantially across these credential tiers, creating cost stratification in employer-sponsored benefit designs.
- Psychiatrists:Medical doctors specializing in psychopharmacology and complex diagnostic differentiation. Demand concentrates in urban United States corridors where academic medical centers anchor referral networks, constrained by residency training bottlenecks and interstate licensure reciprocity gaps.
- Psychologists:Doctoral-level practitioners delivering psychological testing and evidence-based psychotherapy. United States Veterans Health Administration facilities represent the largest institutional employer, driving demand for PTSD assessment protocols and cognitive rehabilitation programs.
- Counselors:Master's-prepared clinicians handling routine anxiety and depression interventions. Community mental health centers in Texas and Florida deploy licensed professional counselors as frontline intake providers.
- Social Workers:LCSW-credentialed professionals integrating psychosocial support with care coordination. Hospital systems in Massachusetts embed psychiatric social workers within readmission-reduction programs.
Leading the category by volume: Counselors. Growing fastest: Psychiatrists.
Technology:
Development timelines stretch longest for FDA-regulated prescription digital therapeutics, while EHR interoperability mandates force vendor consolidation. Cost tiers separate enterprise hospital deployments from direct-to-consumer subscription models.
- Teletherapy:Synchronous video platforms enabling intake, triage, and ongoing cognitive behavioral therapy. United Kingdom NHS Talking Therapies program contracts national teletherapy vendors, while United States employers bypass carriers for direct vendor relationships.
- Mobile Apps:Smartphone-delivered mood tracking, meditation, and psychoeducation tools. Germany's DiGA fast-track approval pathway reimburses prescription mental health apps through statutory health insurance.
- EHR Systems:Electronic health records segmenting behavioral and medical claims data. United States ONC certification requirements drive psychiatrists toward consolidated vendor platforms.
- Virtual Reality:Immersive exposure therapy for phobia and PTSD treatment. Academic medical centers in the Netherlands and United States demonstrate efficacy, though hardware costs limit community clinic deployment.
Teletherapy commands the largest installed base. Virtual Reality claims the steepest expansion trajectory.
End User:
Facility capital intensity and staffing ratios create margin dispersion across inpatient, outpatient, and community-based settings. Reimbursement parity legislation most directly impacts hospital-based integrated care models.
- Clinics:Outpatient settings delivering psychotherapy and medication management. Federally qualified health centers in California integrate behavioral clinicians into primary care workflows.
- Hospitals:Inpatient psychiatric units and emergency department psychiatric services. Universal Health Services operates the largest for-profit psychiatric hospital network across multiple United States states.
- Residential Treatment Centers:24-hour structured programs for substance use and eating disorders. Acadia Healthcare specializes in facility-based addiction treatment in the southeastern United States.
- Schools:K-12 and university-based counseling and crisis intervention. Texas and New York mandate school counselor ratios, driving public district hiring.
Hospitals lead by revenue concentration. Schools represent the fastest-climbing demand segment.
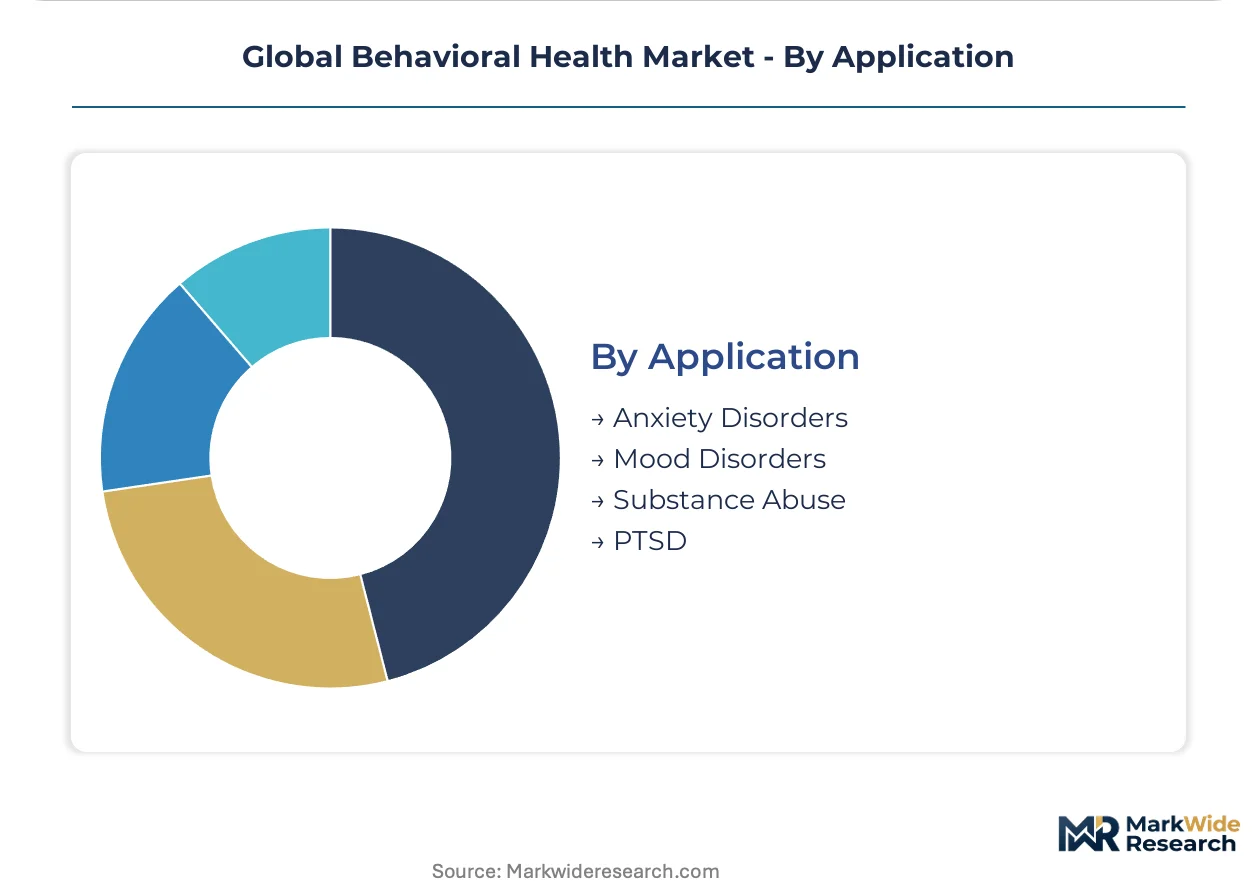
Application:
Diagnostic category determines treatment protocol standardization, with substance abuse interventions facing the most stringent regulatory scrutiny and PTSD protocols showing the strongest evidence base for technology-enabled delivery.
- Anxiety Disorders:Generalized anxiety, panic disorder, and phobia treatment protocols. United States employer mental health parity mandates expand coverage for cognitive behavioral therapy interventions.
- Mood Disorders:Major depression and bipolar spectrum conditions requiring pharmacological management. Germany's statutory health insurance funds reimbursement for transcranial magnetic stimulation in treatment-resistant depression.
- Substance Abuse:Alcohol, opioid, and stimulant use disorder interventions. FDA digital therapeutics pathway accelerates software-based substance use disorder treatment approvals.
- PTSD:Trauma-focused cognitive behavioral therapy and exposure protocols. United States Veterans Health Administration operates the largest specialized PTSD treatment network globally.
Mood Disorders anchor the largest patient volume. Substance Abuse interventions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Behavioral health service production concentrates in the United States and Germany where reimbursement infrastructure and regulatory clarity enable scaled delivery, while consumption growth accelerates in India and Brazil where unmet need and digital penetration outpace local supply capacity.
United States
Employer-sponsored mental health parity mandates and integrated care model adoption drive service utilization across commercial and Medicaid populations. FDA digital therapeutics oversight accelerates software-based intervention approvals for substance use disorders. Academic medical centers in Boston and Stanford anchor specialized PTSD treatment networks deploying exposure therapy protocols.
Germany
Statutory health insurance reimbursement for prescription digital therapeutics and transcranial magnetic stimulation expands access to technology-enabled interventions. The DiGA fast-track approval pathway reimburses mental health apps through statutory health insurance funds. Berlin and Munich host concentrated digital health startup clusters developing algorithmic diagnostic tools.
United Kingdom
NHS Talking Therapies program contracts national teletherapy vendors for stepped-care anxiety and depression treatment. National Institute for Health and Care Excellence guidelines shape evidence requirements for digital therapeutic reimbursement. London's South London and Maudsley NHS Foundation Trust operates Europe's largest mental health research and service delivery cluster.
India
Teletherapy platform expansion addresses psychiatrist supply shortages concentrated in Mumbai, Delhi, and Bangalore metropolitan corridors. The country's national pharmaceutical regulator oversees psychotropic medication distribution while state-level clinical establishment acts govern facility licensing. Hyderabad and Chennai emerge as telehealth operations centers serving domestic and diaspora populations.
Australia
Medicare-subsidized mental health care plans and Better Access initiative drive psychologist and psychiatrist service claims. The Therapeutic Goods Administration regulates prescription digital therapeutics entering clinical use. Melbourne and Sydney concentrate specialized eating disorder and addiction residential treatment capacity serving regional catchment populations.
Global Behavioral Health Market Vendor Landscape
The competitive structure tilts toward facility-based operators with geographic density advantages and payers integrating behavioral-medical claims data. Tiered concentration separates national inpatient psychiatric networks from regional outpatient specialists and digital therapeutic developers. Facility operators execute capacity expansion through de novo site development and strategic partnerships with health systems, while payer-affiliated platforms pursue portfolio diversification into employee assistance and virtual care delivery.
Among facility-based operators, Universal Health Services and Acadia Healthcare exemplify scale-driven archetypes with multi-state inpatient psychiatric and residential treatment footprints. Within the payer-integrated tier, Elevance Health occupies a position combining insurance platform scale with behavioral-medical data integration capabilities. These three anchors represent divergent strategic positions: pure-play facility concentration, specialized addiction and residential focus, and vertical payer-provider integration.
| Leading Market Players |
|---|
| Universal Health Services |
| Acadia Healthcare |
| Magellan Health |
| Elevance Health |
| Centene Corporation |
| Cigna |
| CareTech Holdings |
| Pyramid Healthcare |
| Sevita |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up facility operators dominate inpatient psychiatric capacity across multiple United States states, concentrating supply-side power among Universal Health Services and Acadia Healthcare while enabling disciplined pricing across bundled residential treatment episodes. This ownership pattern shapes procurement behavior as employers and payers unbundle traditional inpatient packages into discrete outpatient and digital components, fragmenting pricing power toward specialized vendors.
Pricing Analysis
Margin tightening in Medicare-reimbursed psychotherapy traces to statutory fee schedule compression that lags private payer rates by substantial spreads. Three-tier pricing structure across premium concierge, standard commercial, and economy Medicaid tiers separates cash-pay executive coaching from employer-sponsored digital therapeutics and publicly funded community mental health. Pricing pressure intensifies in teletherapy as platform scalability enables geographic expansion without facility capital, eroding location-based premiums. Self-insured employers exhibit lowest price sensitivity, prioritizing clinical outcome metrics over per-session costs.
Supply Chain Analysis
United States domestic-content mandates for HIPAA-compliant data infrastructure reshape sourcing toward domestic cloud providers and onshore clinical staffing. Supply concentrates in the United States, Germany, and the United Kingdom where reimbursement infrastructure enables scaled delivery. Raw material dependencies include licensed clinician labor pools, FDA-validated software development capacity, and specialized VR hardware for exposure therapy. Single-source vulnerability clusters around psychiatrist supply bottlenecks in rural corridors. Distribution runs through employer benefits administrators, health system GPOs, and direct-to-consumer app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The behavioral health sector occupies a technology-transition phase as prescription digital therapeutics displace legacy pharmacological-first protocols for insomnia and substance use disorders. This shift restructures competitive positioning toward software-enabled intervention developers with regulatory clearance pathways.
For Market Incumbents: Deploy backward integration into teletherapy platform infrastructure to capture margin pools escaping traditional facility-based delivery. Universal Health Services and Acadia Healthcare must consolidate fragmented outpatient networks before employer purchasers complete direct-to-vendor contracting. Defensive moves require EHR interoperability certification investments that lock in behavioral-medical claims data integration, countering Elevance Health's payer-integrated threat.
For New Entrants and Emerging Players: The premium-economy price-point gap in algorithmic mental health diagnostics creates white-space entry opportunities for FDA-cleared prescription digital therapeutic developers. Target rural United States corridors where psychiatrist supply shortages persist regardless of platform reach. Germany's DiGA fast-track approval pathway offers the most penetrable regulatory geography for mobile app reimbursement through statutory health insurance.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized PTSD treatment networks in academic medical center clusters across Boston and Stanford. Long-term viability hinges on five-to-ten year regulatory clarity for prescription digital therapeutics as clinical evidence standards tighten. Watch FDA enforcement discretion signals for algorithmic diagnostic reclassification as high-risk medical devices under EU AI Act precedent.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Therapeutics Submission | Expedited review pathway accelerates commercialization timelines for software-based substance use interventions. |
| Hospital System Partnership | Elevance Health integrates behavioral-medical claims data through insurance platform scale advantages. |
| Platform Integration | Teletherapy vendors achieve lower overhead than brick-and-mortar equivalents through virtual intake automation. |
| Geographic Expansion | Academic medical centers in Germany and the United States demonstrate VR exposure therapy efficacy for PTSD. |
| Reimbursement Strategy | Germany's statutory health insurance funds reimburse prescription mental health apps through DiGA pathway. |
Methodological Framework
Document review covered FDA digital therapeutics guidance, CMS Medicare reimbursement databases, and EU AI Act regulatory texts, complemented by interviews with behavioral health system executives, teletherapy platform CTOs, employer benefits administrators, and licensed clinical psychologists. Secondary validation drew from hospital procurement databases, GPO contracts, and SEC filings of publicly traded facility operators. Bottom-up service volume estimates triangulated against top-down payer expenditure analysis.
Cross-referencing historical utilization patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include professional credential tier, technology modality, care setting intensity, and diagnostic category application. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points including mental health parity mandate enforcement and prescription digital therapeutic approval velocity. Forecast inputs incorporated clinician supply pipeline constraints and employer benefit unbundling velocity.
Underlying measurement precision varies by segment; teletherapy platform metrics carry tighter precision than emerging VR exposure therapy deployment estimates. Forecasts reflect assumptions around FDA enforcement continuity and statutory reimbursement stability. Regulatory restriction risks including HIPAA compliance burden escalation and interstate licensure reciprocity gaps could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Schizophrenia Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Mental Health Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
US Psychiatry Clinic Market