
 Global Workplace Stress Management Market | 2026-2036
Global Workplace Stress Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Workplace Stress Management Market Foresight
Market Context
Digital biomarkers are decoupling workplace stress management from traditional clinical assessment, replacing paper-based psychological evaluations with real-time physiological monitoring. Headspace Inc. leverages its meditation app infrastructure to anchor enterprise subscriptions across Fortune 500 human resource departments. ComPsych Corporation dominates the employee assistance program channel through its proprietary counselor network and 24-hour crisis intervention protocols. Lyra Health differentiates via its blended care model that integrates coaching, therapy, and medication management through a single benefits platform.
Technical Definition and Segment Structure
Workplace stress management encompasses psychometric instruments, digital therapeutics, and organizational interventions designed to measure, mitigate, and prevent occupational psychological strain, typically incorporating heart rate variability thresholds, cortisol sampling protocols, or validated assessment scales such as the Perceived Stress Scale. The primary commercial purpose centers on reducing absenteeism, lowering disability claims, and preserving cognitive performance in knowledge-intensive work environments. Meditation apps and wellness programs capture the dominant share of product-type revenue, while cloud-based platforms are displacing on-premise solutions as the preferred deployment architecture for multinational employers. Corporate wellness and employee assistance programs represent the most mature application segments, whereas remote workforce support is expanding fastest as distributed work arrangements persist across technology and professional services sectors.
Regulatory Environment
The U.S. Occupational Safety and Health Administration and the EU's Framework Directive on Safety and Health at Work are mandating employer accountability for psychosocial risks, directly expanding procurement of structured stress management services. Japan's Ministry of Health, Labour and Welfare has operationalized stress-check mandates through amended Industrial Safety and Health Act provisions, while Germany's Federal Institute for Occupational Safety and Health issues technical guidance that shapes product certification requirements across Europe. Stakeholders must monitor evolving jurisdictional definitions of employer duty of care, as regulatory fragmentation between prescriptive mandates and voluntary guidelines will determine go-to-market investment priorities and partnership structures for platform providers.
Market Dynamics
The EU's Work-Life Balance Directive is compressing procurement cycles for employer-funded mental health infrastructure, while biometric wearables are automating stress detection and displacing quarterly clinical assessments in Fortune 500 human resource departments.
Growth Catalysts
- Japan's stress-check mandate:Amended Industrial Safety and Health Act provisions require annual psychological evaluations for employers with 50-plus workers, creating guaranteed demand for validated assessment platforms.
- Financial services sector expansion:Trading floors and investment banking divisions are deploying real-time heart rate variability monitoring to preempt burnout-related errors in high-stakes decision environments.
- Cloud migration:Multinational employers are consolidating fragmented on-premise wellness portals into unified SaaS architectures that integrate with existing HRIS systems.
Market Restraints
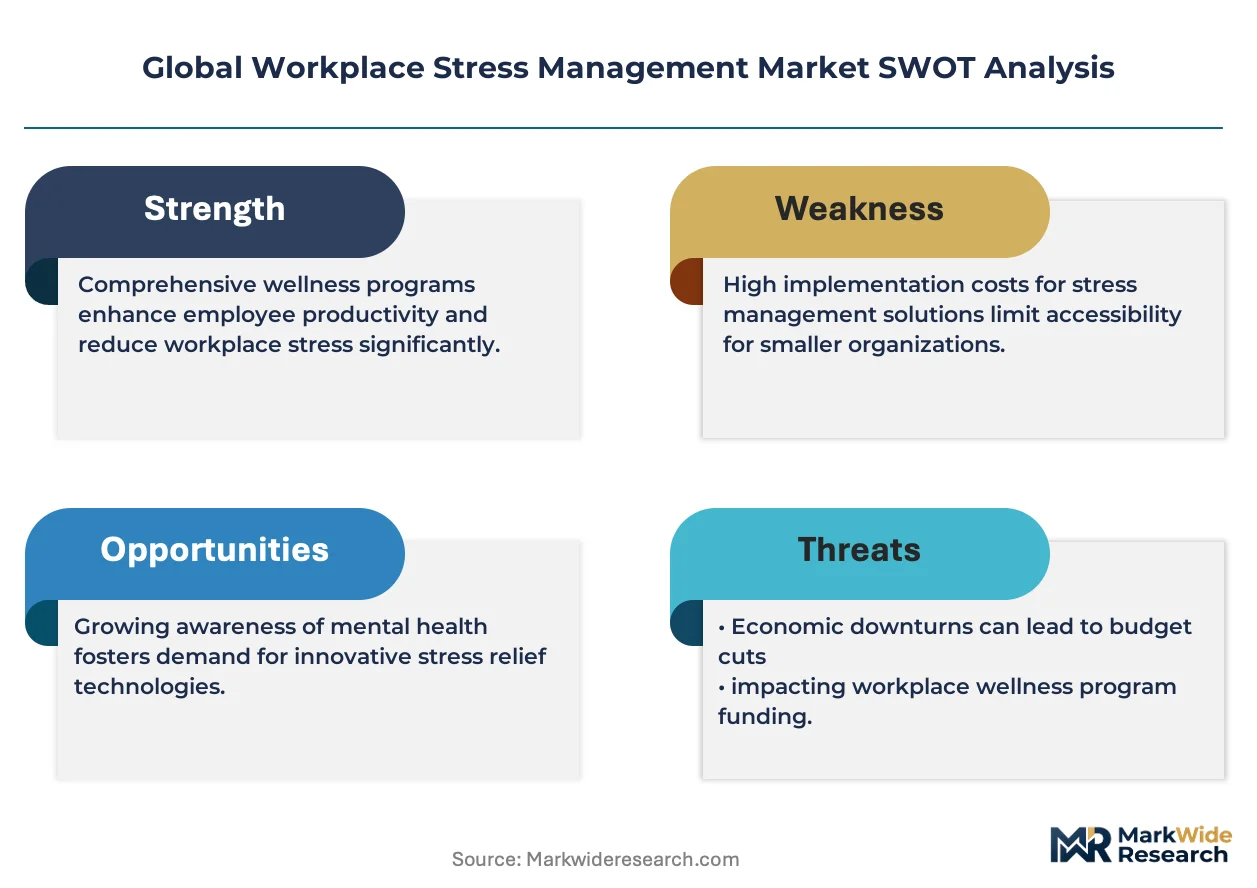
- Biometric data liability exposure:GDPR and emerging US state privacy laws impose strict consent and retention requirements on continuous physiological monitoring, elevating compliance costs for platform operators.
- Clinical validation bottlenecks:FDA and EMA have not established clear 510(k) or CE-marking pathways for digital therapeutics targeting occupational stress, prolonging time-to-market for algorithm-based interventions.
- Employer budget cyclicality:Stress management programs rank as discretionary spend during economic contractions, with procurement freezes historically correlating to tightening credit conditions in the technology sector.
Strategic Opportunities
- German technical guidance leadership:The Federal Institute for Occupational Safety and Health is certifying stress management methodologies, creating first-mover advantage for platforms achieving Baumusterprüfung compliance.
- Remote workforce support:Distributed technology and professional services teams require asynchronous, timezone-agnostic intervention models that replace synchronous EAP hotlines.
- AI-coaching convergence:Natural language processing and sentiment analysis are enabling scalable, personalized cognitive behavioral therapy delivery without proportional counselor headcount expansion.
Industry Challenges
- Behavioral health licensure fragmentation:Cross-border service delivery requires maintaining counselor credentials across 50-plus US state boards and 27 EU national regulators, complicating platform scalability.
- Interoperability with legacy HR systems:SAP and Workday integrations demand custom API development for each enterprise deployment, extending implementation timelines and professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Workplace Stress Management Market |
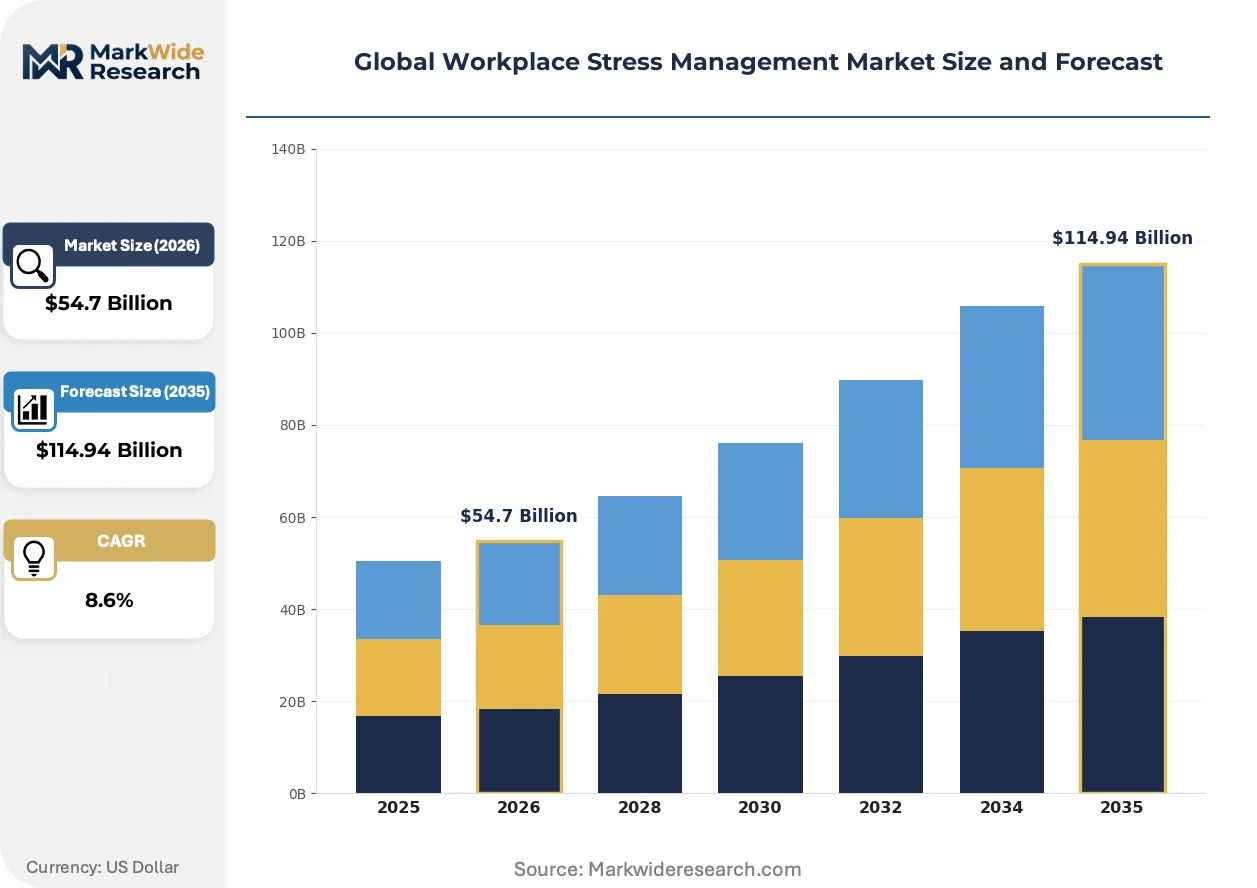
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $114.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stress Assessment Tools, Meditation Apps, Counseling Services, Biofeedback Devices, Wellness Programs Application: Corporate Wellness, Employee Assistance Programs, Remote Workforce Support, Leadership Training, Conflict Resolution End User: Human Resource Departments, Occupational Health Specialists, Entrepreneurs, Team Managers, Freelancers Deployment: Cloud-Based Platforms, On-Premise Solutions, Mobile Applications, Hybrid Models, In-Person Workshops |
| Companies Covered | ComPsych Corporation, CuraLinc Healthcare, Headspace Inc., ActiveHealth Management, Fitbit, Marino Wellness, Truworth Wellness, BetterUp, Lyra Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Workplace Stress Management Market Shifts & Advancements
Biometric sensing and ambient computing are dissolving the boundary between clinical intervention and daily work experience, embedding stress management into the physical and digital infrastructure of knowledge work itself.
Photoplethysmography-enabled wearables are automating cardiovascular stress marker detection through continuous pulse waveform analysis. Technology sector employers in California and Washington are mandating these devices for executive cohorts. The technology is automating the shift from reactive crisis intervention to predictive strain modeling, compressing the window between physiological anomaly and managerial notification.
REACH and the EU AI Act are imposing algorithmic transparency requirements on automated mental health screening tools. Platform providers must now document training data provenance and decision logic for stress classification models. Germany and France are experiencing the steepest compliance cost escalation, with domestic regulators demanding third-party audits of bias in biometric inference systems.
Buyer committees are consolidating vendor relationships from point-solution meditation apps to integrated benefits platforms spanning coaching, therapy, and pharmacy. Human resource departments in the United States are displacing standalone EAP contracts with single-vendor arrangements that bundle utilization analytics. This concentration is most visible in the financial services vertical, where procurement teams prioritize consolidated reporting dashboards over best-of-breed feature depth.
Global Workplace Stress Management Market Segmentation
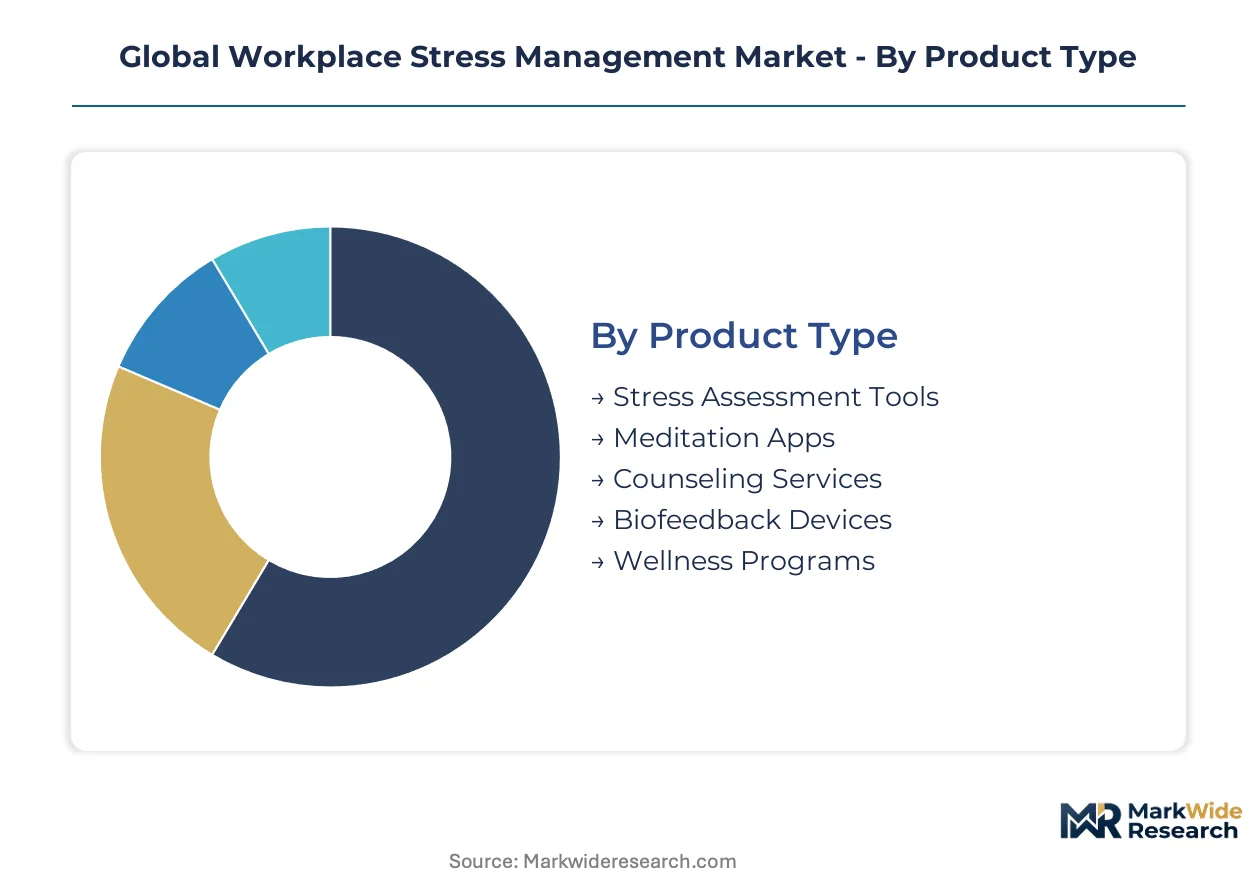
Workplace stress management solutions fragment across intervention modalities, delivery mechanisms, and purchaser hierarchies. Procurement patterns diverge sharply between large employers seeking integrated platforms and smaller organizations purchasing point solutions. Understanding these fault lines reveals where vendor consolidation and feature specialization will concentrate competitive advantage.
Product Type:
Volume concentrates in standardized digital offerings, while premium pricing attaches to human-delivered services and hardware-enabled monitoring.
- Meditation Apps:Subscription-based mindfulness platforms deliver guided breathing exercises, sleep stories, and focus music through smartphone interfaces. Financial services firms in New York and London mandate these for trading floor personnel, with procurement driven by low per-seat costs and zero clinical licensure requirements.
- Wellness Programs:Comprehensive employer-funded initiatives span fitness challenges, nutrition coaching, and resilience training. Technology sector employers in California and Washington deploy these as talent retention instruments, with demand accelerating under OSHA's expanding psychosocial hazard enforcement.
- Stress Assessment Tools:Digital questionnaires and biometric screening protocols validated against clinical standards.
- Counseling Services:Licensed therapist sessions delivered through video, phone, or text channels.
- Biofeedback Devices:Wearable hardware measuring heart rate variability, galvanic skin response, or cortisol markers.
Today's leader: Wellness Programs. Tomorrow's challenger: Biofeedback Devices.
Application:
Corporate buyers prioritize solutions reducing measurable productivity losses, while emerging use cases target prevention and leadership development.
- Corporate Wellness:Organization-wide initiatives embedding stress management into benefits infrastructure and physical workplace design. Germany's Federal Institute for Occupational Safety and Health certifies these programs, creating procurement preference for Baumusterprüfung-compliant vendors serving DAX-listed employers.
- Remote Workforce Support:Asynchronous digital interventions replacing synchronous EAP hotlines for distributed teams. Professional services firms with Asia-Pacific operations drive demand here, requiring timezone-agnostic coaching and multilingual therapist networks.
- Employee Assistance Programs:Traditional crisis intervention and short-term counseling bundled with work-life referral services.
- Leadership Training:Executive coaching targeting stress contagion and team resilience building.
- Conflict Resolution:Mediation and communication training reducing interpersonal stress sources.
Remote Workforce Support is climbing the fastest as distributed arrangements persist across knowledge-intensive sectors.
End User:
Purchasing authority fragments between centralized HR functions and decentralized operational managers with discretionary wellness budgets.
- Human Resource Departments:Centralized procurement of enterprise-wide stress management platforms integrated with existing HRIS systems. These buyers dominate in the United States, where insurance frameworks and OSHA guidelines mandate comprehensive employee support infrastructure.
- Team Managers:Frontline leaders purchasing department-specific interventions without central IT approval. Japan's stress-check mandates for employers with 50-plus workers create guaranteed demand here, as managers seek compliant assessment tools for annual psychological evaluations.
- Occupational Health Specialists:Medical professionals designing clinically validated intervention protocols.
- Entrepreneurs:Small business owners purchasing individual or small-group solutions without employer sponsorship.
- Freelancers:Independent workers accessing direct-to-consumer stress management applications.
Human Resource Departments control today's procurement volume. Team Managers represent tomorrow's expansion vector as regulatory mandates penetrate mid-sized employers.
Deployment:
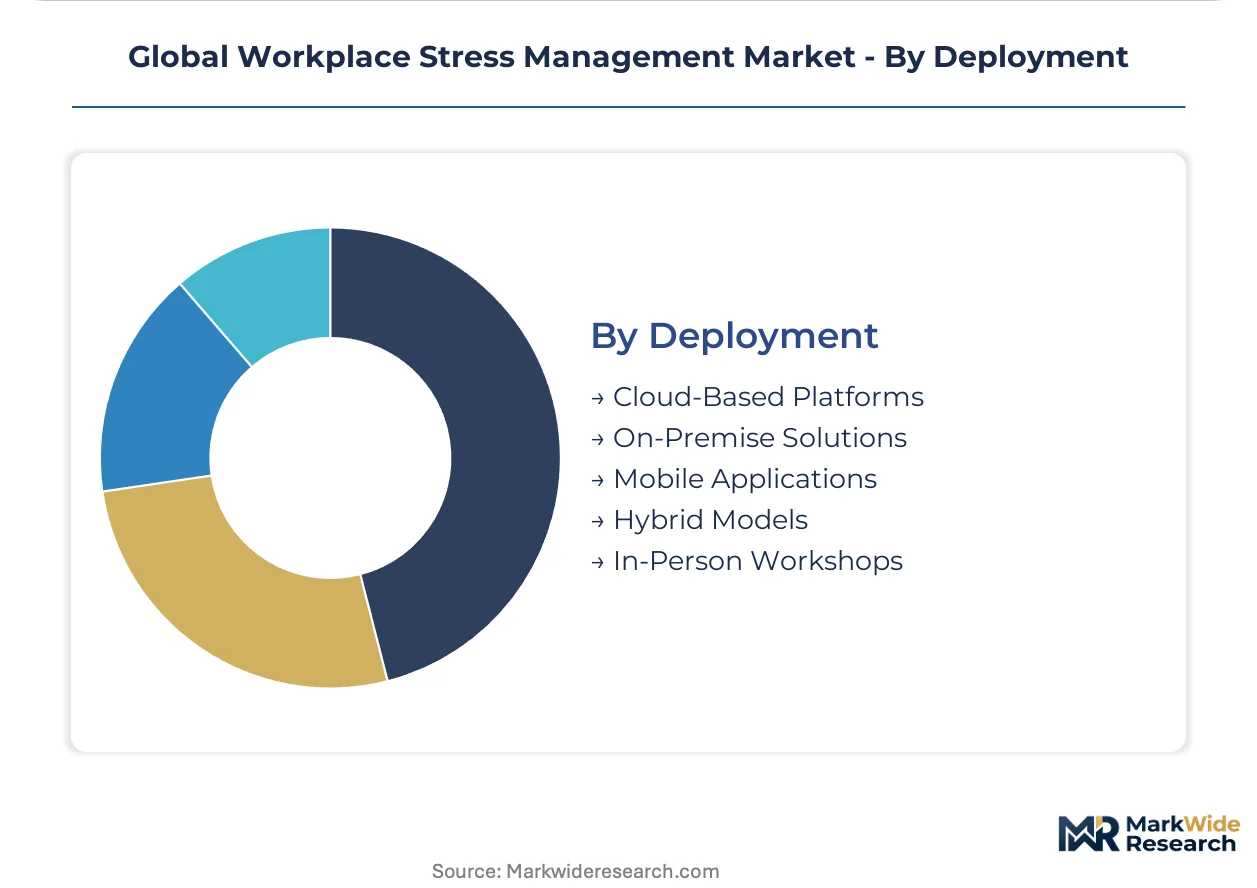
Cloud architectures displace on-premise installations as multinational employers consolidate fragmented wellness portals.
- Cloud-Based Platforms:SaaS-delivered stress management integrating with Workday, SAP, and other HRIS systems through standardized APIs. These solutions dominate procurement cycles at Fortune 500 employers, with GDPR and emerging US state privacy laws elevating compliance costs for platform operators handling biometric data.
- Mobile Applications:Smartphone-native interventions enabling continuous engagement and just-in-time stress reduction. Japan's Ministry of Health, Labour and Welfare has operationalized mobile stress-check compliance, accelerating adoption among employers seeking streamlined mandate fulfillment.
- On-Premise Solutions:Locally hosted software requiring enterprise IT infrastructure and maintenance.
- Hybrid Models:Combinations of digital self-service and scheduled human coaching touchpoints.
- In-Person Workshops:Facilitated group sessions delivered at workplace locations or retreat venues.
Cloud-Based Platforms anchor current investment. Mobile Applications are gaining share fastest as asynchronous engagement models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services clusters in Manhattan and the City of London are deploying biometric stress monitoring at scale, while regulatory mandates across three continents are accelerating employer procurement of validated assessment platforms.
United States
Fortune 500 human resource departments in New York and California are consolidating fragmented wellness portals into unified SaaS architectures. OSHA's expanding psychosocial hazard enforcement is mandating employer accountability for workplace mental health risks. Trading floors on Wall Street are mandating real-time heart rate variability monitoring for executive cohorts to preempt burnout-related decision errors.
Germany
DAX-listed employers are prioritizing Baumusterprüfung-compliant vendors for corporate wellness certification. The Federal Institute for Occupational Safety and Health issues technical guidance that shapes product certification requirements across Europe. Industrial clusters in Bavaria and North Rhine-Westphalia are operationalizing stress-check protocols for manufacturing workforces under EU Framework Directive alignment.
Japan
Employers with 50-plus workers face guaranteed demand for validated assessment platforms under amended Industrial Safety and Health Act provisions. The Ministry of Health, Labour and Welfare has operationalized mobile stress-check compliance, accelerating adoption among mid-sized employers. Technology sector employers in Tokyo and Osaka are deploying asynchronous intervention models for distributed Asia-Pacific teams.
United Kingdom
Professional services firms in the City of London are displacing standalone EAP contracts with integrated benefits platforms bundling utilization analytics. The Health and Safety Executive is aligning enforcement with EU psychosocial risk frameworks post-Brexit. Fintech clusters in Canary Wharf and Manchester are mandating meditation app subscriptions for trading floor personnel.
India
IT services employers in Bangalore and Hyderabad are expanding remote workforce support for asynchronous, timezone-agnostic intervention models. The country's national occupational health regulator is developing technical guidance for psychosocial risk assessment in knowledge-intensive sectors. Business process outsourcing clusters in Pune and Chennai are procuring cloud-based stress management platforms integrated with existing HRIS systems.
Global Workplace Stress Management Market Competitive Landscape
Global majors compete with regional champions across platform architecture and service delivery models, creating a tiered structure where integrated benefits platforms vie with point-solution specialists. The vendor base organizes around three strategic archetypes: meditation app infrastructure providers, employee assistance program incumbents with proprietary counselor networks, and blended care platforms unifying coaching, therapy, and medication management. Competitive intensity is concentrating through M&A consolidation of fragmented wellness portals and strategic partnerships between wearable hardware manufacturers and cloud platform operators.
Within the integrated platform tier, ComPsych Corporation and Lyra Health exemplify divergent approaches to employer benefit consolidation, while Headspace Inc. occupies a position anchoring enterprise subscriptions through consumer-to-business channel migration. These three entities represent the dominant competitive vectors: EAP channel dominance, blended care model integration, and app-based infrastructure leverage.
| Leading Market Players |
|---|
| ComPsych Corporation |
| CuraLinc Healthcare |
| Headspace Inc. |
| ActiveHealth Management |
| Fitbit |
| Marino Wellness |
| Truworth Wellness |
| BetterUp |
| Lyra Health |
| Others |
Supply & Pricing Matrix
Backward integration into proprietary counselor networks anchors pricing power for employee assistance program incumbents, while SaaS-native competitors source coaching capacity through variable-cost subcontracting that compresses margins during demand surges. This structural divergence separates fixed-cost infrastructure players from agile platform operators across the vendor landscape.
Pricing Analysis
Input-cost pass-through from licensed therapist wages and biometric hardware procurement shapes three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle 24-hour crisis intervention and heart rate variability monitoring for financial services buyers in Manhattan and London. Cost compression in the standard tier intensifies because cloud-platform competitors automate assessment delivery without proportional counselor headcount expansion. Human resource departments at Fortune 500 employers show least price sensitivity due to OSHA mandate compliance budgets, while mid-sized technology firms purchasing departmental solutions exhibit highest elasticity.
Supply Chain Analysis
Returns and refurbishment flows for wearable hardware create reverse-logistics complexity as employers cycle through photoplethysmography-enabled devices for annual stress-check compliance in Japan. Manufacturing concentrates in China, South Korea, and Taiwan for sensor components, while clinical content production localizes in the United States, Germany, and India for linguistic and regulatory alignment. Raw material dependencies span lithium-ion cells for device power management, optical-grade polymers for sensor housings, and cloud compute capacity for real-time biometric inference. Single-source vulnerability in semiconductor-grade photodetectors elevates procurement risk for platform operators scaling hardware-enabled monitoring. Distribution runs through employer benefits brokers and direct enterprise sales teams, with channel concentration favoring established EAP incumbents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Japan's stress-check mandate and the EU's Work-Life Balance Directive create guaranteed procurement cycles that insulate vendors from discretionary spend freezes.
For Market Incumbents: Deepen vertical control over multilingual therapist credentialing networks to defend against SaaS-native competitors automating coaching delivery through natural language processing. Consolidate fragmented wellness portals through targeted acquisition of mobile stress-check compliance specialists in Japan and Germany. Certification investment in Baumusterprüfung standards represents the critical lever for DAX-listed employer retention. For New Entrants and Emerging Players: Benefits brokers serving mid-sized employers with 50-200 workers represent the most accessible channel partner type for bypassing incumbent-controlled Fortune 500 procurement committees. White-space concentration in asynchronous remote workforce support for professional services firms with Asia-Pacific operations offers lowest competitive density. A go-to-market angle anchored to GDPR-compliant biometric data architecture addresses the liability exposure blocking employer adoption of hardware-enabled monitoring. For Investors and Strategic Acquirers: Roll-up economics work for blended care platforms because behavioral health licensure fragmentation across 50-plus US state boards and 27 EU national regulators creates artificial scarcity in cross-border service delivery capabilities. Long-term viability favors acquirers consolidating point-solution meditation apps into integrated benefits infrastructure. The signal to watch is FDA establishment of 510(k) pathways for digital therapeutics targeting occupational stress, which would unlock institutional capital deployment into algorithm-based intervention models.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented wellness portals into single-vendor arrangements with consolidated utilization analytics for HR departments. |
| Strategic Partnership | Links wearable hardware manufacturers with cloud platform operators to embed photoplethysmography monitoring into enterprise subscriptions. |
| Acquisition of Specialist Firm | Captures mobile stress-check compliance capabilities for mid-sized Japanese employers under amended Industrial Safety and Health Act. |
| Product Launch | Introduces asynchronous coaching interfaces replacing synchronous EAP hotlines for distributed technology and professional services teams. |
| Geographic Expansion | Establishes Baumusterprüfung-certified service delivery for DAX-listed employers under Federal Institute for Occupational Safety and Health guidance. |
Research Methodology
Direct dialogue with chief human resource officers, benefits procurement managers, occupational health physicians, and digital health platform executives grounded qualitative findings in operational decision-making realities. Secondary validation drew from OSHA enforcement records, EU Framework Directive implementation reports, Japan's Ministry of Health Labour and Welfare stress-check compliance data, and SEC filings of publicly traded wellness platform operators. Bottom-up and top-down triangulation reconciled employer spend estimates with vendor-reported subscription metrics.
Analytical lens alternated between bottom-up aggregation of employer procurement patterns and top-down constraint of total addressable spend by industry vertical. Segmentation dimensions spanned intervention modality, deployment architecture, organization size tier, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to mandate implementation timelines and technology diffusion patterns. Forecast inputs incorporated psychosocial hazard enforcement intensity indices and cloud-platform integration velocity metrics.
Revisions become necessary when regulatory fragmentation intensifies between prescriptive mandates and voluntary guidelines, or when biometric data liability rulings under GDPR and emerging US state privacy laws reshape platform operator cost structures. Forecasts reflect documented assumptions regarding mandate compliance rates and technology substitution elasticities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Agoraphobia Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market