
 Relationship Counselling Market | 2026-2036
Relationship Counselling Market Size, Share, and Industry Trends Forecast 2026-2036
Relationship Counselling Market Insights
The capital-intensity divergence between technology-heavy platforms and clinician-dependent practices is reorganizing competitive dynamics in relationship counselling. BetterHelp LLC leverages its proprietary matching algorithm and subscription infrastructure to dominate direct-to-consumer telehealth. Talkspace Inc. sustains enterprise channel control through employer and health plan partnerships. Amwell Corporation anchors its position via hybrid delivery that integrates virtual sessions with in-person network referrals.
Relationship counselling encompasses structured psychotherapeutic interventions designed to improve interpersonal dynamics, communication patterns, and emotional bonding between intimate partners, typically delivered through 45-90 minute sessions using evidence-based modalities such as emotionally focused therapy or the Gottman Method. Its primary commercial purpose centers on reducing relationship distress, preventing dissolution, and restoring functional partnership dynamics that affect mental health, productivity, and family stability. Couples therapy commands the largest service type segment due to persistent demand from married and cohabiting partners seeking structured conflict resolution. Online counseling represents the fastest-expanding delivery model as asynchronous messaging and video platforms reduce geographic and scheduling barriers for working adults. The hybrid delivery model captures concentrated margin pools by blending insurance-reimbursable in-person intake with lower-cost digital maintenance sessions.
FDA oversight of digital therapeutics and HIPAA privacy requirements shape product standards for platforms incorporating algorithmic mood tracking or AI-assisted intervention recommendations. State-level professional licensing boards govern cross-border telehealth practice, creating fragmented market access that favors multi-state credentialing investments. The Federal Trade Commission monitors advertising claims in direct-to-consumer mental health services, influencing how platforms position outcomes and therapist qualifications. Stakeholders must monitor evolving state compact agreements and digital therapeutic classifications to determine geographic expansion timing and technology development priorities.
Market Dynamics
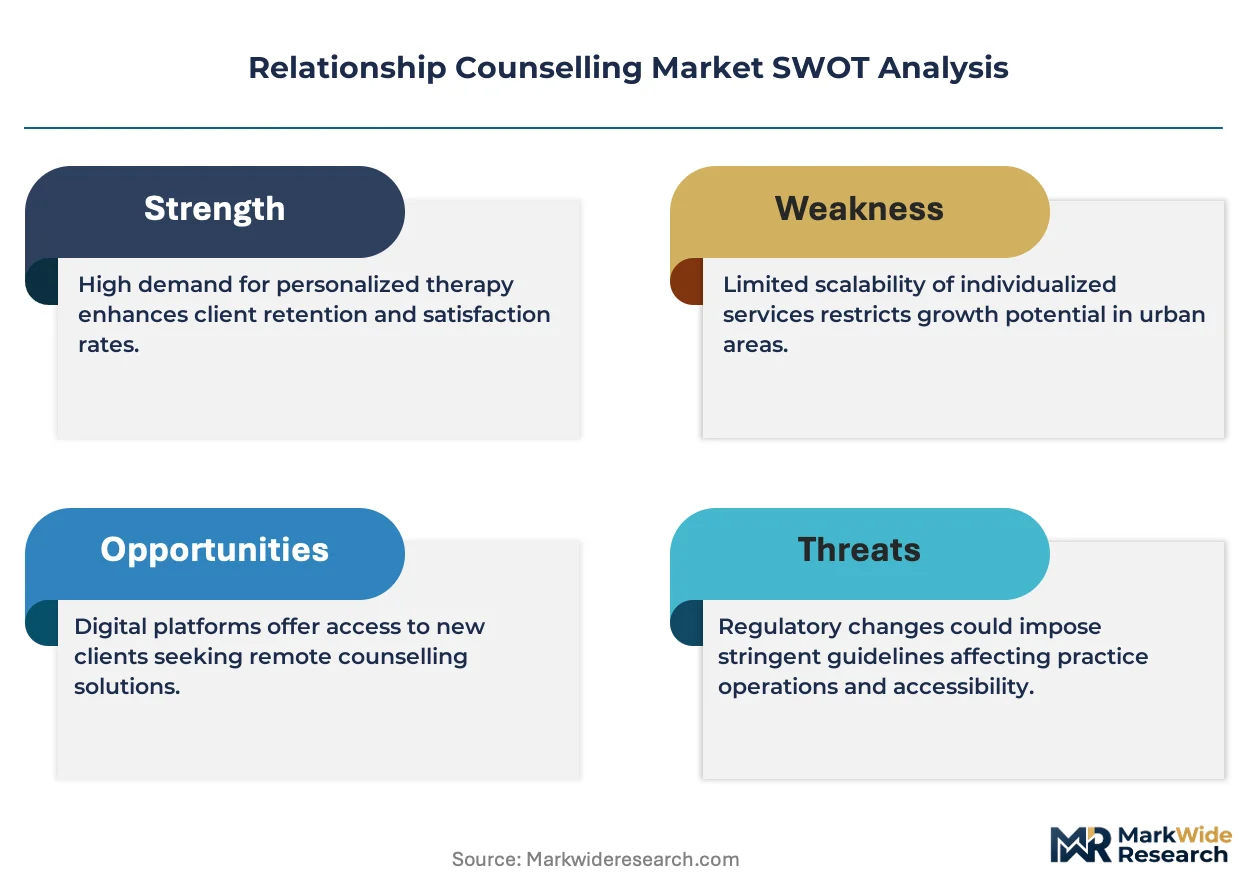
Telehealth licensing fragmentation across US state lines is forcing relationship counselling platforms to build multi-jurisdictional credentialing infrastructure, raising operational complexity while expanding addressable market reach.
Growth Catalysts
- HIPAA-aligned telehealth reforms:State-level regulatory harmonization in the United States is reducing cross-border practice barriers, enabling licensed therapists to serve couples across multiple jurisdictions without physical relocation.
- Employer-sponsored wellness expansion:Corporate employee assistance programs are adding couples therapy to mental health benefits portfolios, creating institutional demand channels that bypass individual payment friction.
- Asynchronous messaging platforms:Text-based therapeutic interventions are capturing working adults who cannot schedule synchronous video sessions, extending service reach beyond traditional appointment constraints.
Market Restraints
- State licensing patchwork:The absence of universal interstate compacts for mental health practitioners creates compliance overhead that limits platform scalability and increases legal exposure.
- Reimbursement rate compression:Insurance carriers are narrowing covered indications for relationship counselling, pushing more cost burden onto out-of-pocket consumers and dampening volume growth.
- Clinician supply concentration:Licensed marriage and family therapists cluster in urban coastal markets, leaving rural and interior regions underserved regardless of platform technology.
Strategic Opportunities
- AI-assisted intake triage:Natural language processing tools are streamlining initial session matching and severity assessment, reducing clinician administrative load and improving session yield.
- Hybrid maintenance protocols:Platforms blending insurance-reimbursable in-person intake with lower-cost digital follow-up sessions are capturing margin pools unavailable to pure-telehealth or pure-in-person competitors.
- Corporate channel penetration:Direct-to-employer contracts bypass consumer acquisition costs and reduce churn through embedded benefit structures.
Industry Challenges
- Credential verification latency:Multi-state licensing boards impose inconsistent background check timelines, delaying therapist onboarding and constraining supply elasticity.
- Platform-therapist relationship governance:Independent contractor classification disputes are creating legal exposure around employment status, benefits obligations, and liability allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Relationship Counselling Market |
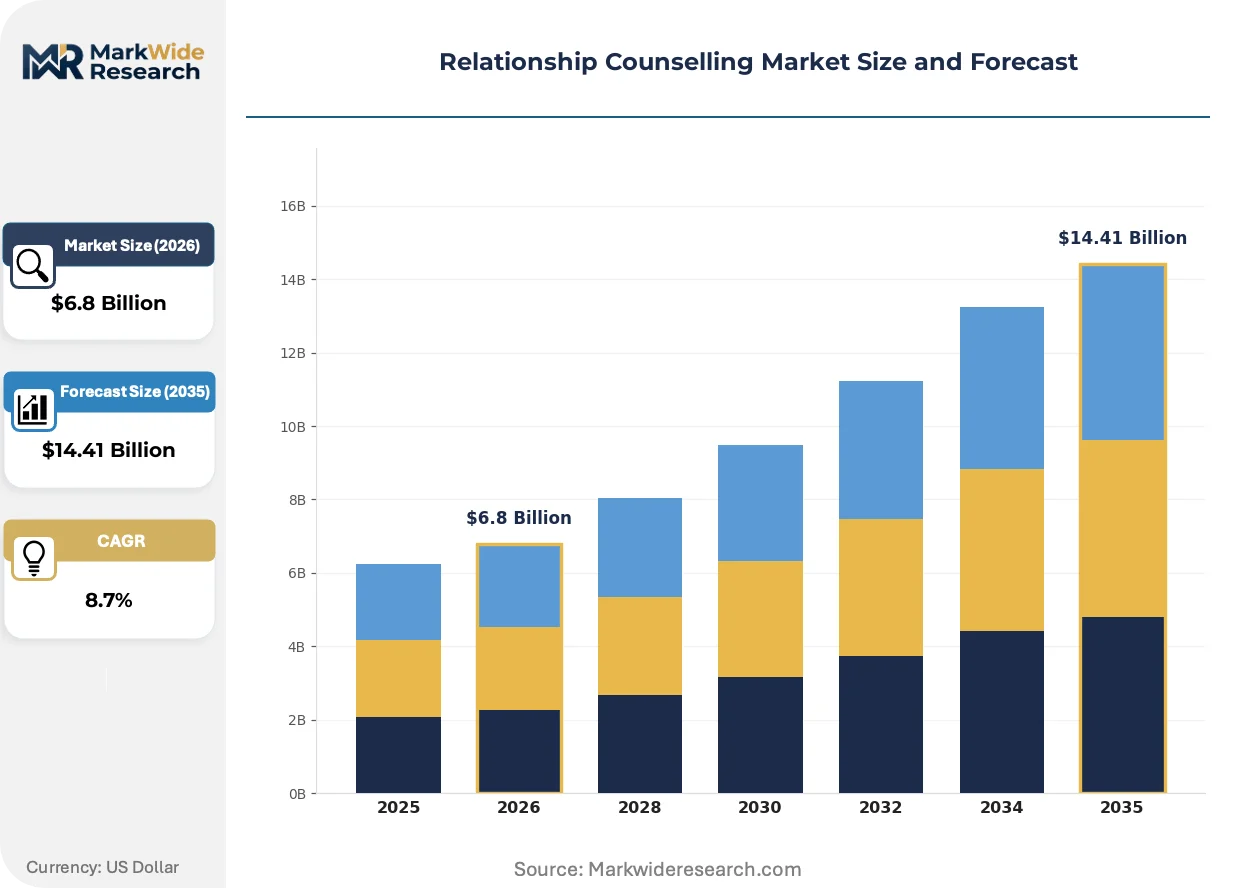
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Individual Therapy, Couples Therapy, Group Therapy, Online Counseling Delivery Model: In-Person, Telehealth, Hybrid, Workshops Client Type: Adults, Teens, Families, Seniors Application: Conflict Resolution, Communication Skills, Emotional Support, Personal Development |
| Companies Covered | BetterHelp LLC, Talkspace Inc., Amwell Corporation, MDLIVE Inc., Calmerry, Couples Therapy Inc., Growing Self, Regain, Lasting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Relationship Counselling Market Trends and Innovations
Algorithmic matching systems and asynchronous care modalities are restructuring how relationship counselling is delivered, accessed, and monetized. Three developments are compressing traditional service architectures.
Natural language processing engines are decomposing the traditional intake interview by automating preliminary conflict-pattern identification and therapist-patient matching. Large employer health plans and direct-to-consumer platforms are deploying these tools to reduce time-to-first-session from weeks to hours. This compression is eliminating geographic proximity as a therapist selection criterion and enabling national talent pools.
The FTC's intensified scrutiny of outcome claims in direct-to-consumer mental health advertising is reshaping platform marketing practices. Enforcement actions against unsubstantiated efficacy assertions are forcing providers to qualify success metrics and disclose limitations. Subscription-based services targeting working-age couples through social media channels face the steepest compliance adjustment costs.
Session unbundling is fragmenting the traditional fifty-minute hour into micro-interactions and messaging threads. Younger cohorts in metropolitan markets are substituting brief asynchronous exchanges for scheduled video blocks, compressing revenue per user while expanding engagement frequency. This pattern concentrates in technology sector employment hubs where schedule fragmentation is most acute.
Relationship Counselling Market Segmentation
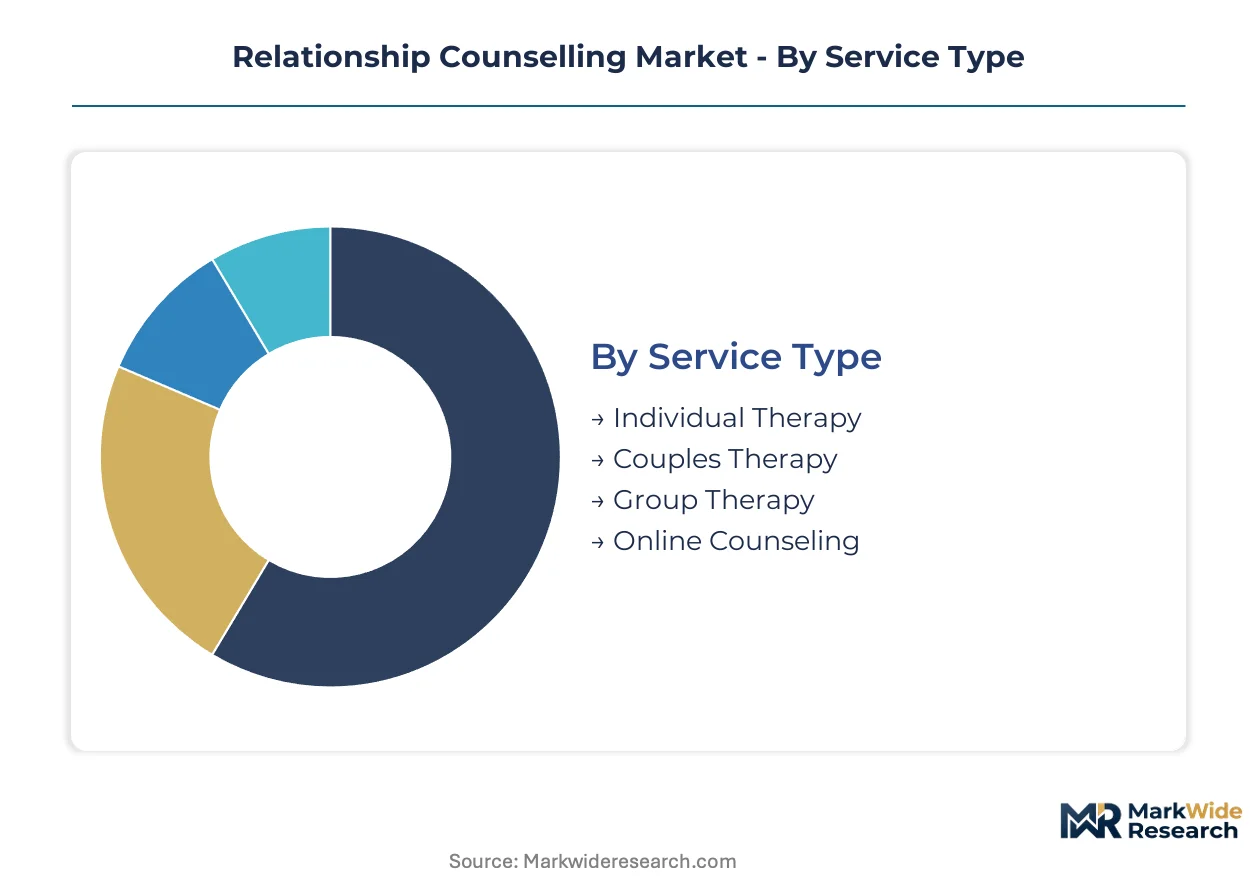
Segmentation in relationship counselling reveals how distinct client needs, service modalities, and delivery constraints create discrete revenue pools. Providers configure staffing, technology investments, and pricing architectures around these boundaries.
Service Type:
Margin concentration follows session reimbursement rates and client retention patterns rather than volume alone.
- Couples Therapy:Structured interventions for intimate partners using evidence-based modalities like emotionally focused therapy or the Gottman Method. Demand clusters among married and cohabiting partners in employer-sponsored wellness programs, where benefits coverage reduces payment friction and extends treatment duration.
- Online Counseling:Asynchronous messaging and synchronous video sessions delivered through proprietary platforms. Working adults in metropolitan employment hubs substitute brief digital exchanges for traditional appointments, compressing revenue per session while expanding engagement frequency.
- Individual Therapy:One-on-one psychotherapeutic treatment addressing personal mental health concerns that intersect with relationship dynamics.
- Group Therapy:Facilitated sessions with multiple participants addressing shared relationship themes or communication patterns.
The dominant share belongs to Couples Therapy, while Online Counseling is closing the gap fastest.
Delivery Model:
Cost tier stratification separates capital-intensive platform investments from clinician-dependent service delivery.
- Hybrid:Insurance-reimbursable in-person intake sessions combined with lower-cost digital maintenance protocols. This configuration captures margin pools unavailable to pure-telehealth or pure-in-person competitors by blending reimbursement rates with operational efficiency.
- Telehealth:Fully remote service delivery via video, audio, or asynchronous messaging. HIPAA-aligned state reforms are reducing cross-border practice barriers, enabling licensed therapists to serve couples across multiple jurisdictions without physical relocation.
- In-Person:Traditional face-to-face sessions in clinical or private practice settings.
- Workshops:Structured group programs delivered in condensed formats, often targeting specific skills or relationship stages.
Hybrid delivery commands premium positioning, while Telehealth is expanding most quickly as licensing fragmentation resolves.
Client Type:
Volume distribution tracks demographic penetration of employer-sponsored mental health benefits and direct-to-consumer subscription adoption.
- Adults:Working-age individuals and couples representing the core commercial base for relationship counselling services. Corporate employee assistance programs concentrate spending here, embedding couples therapy within broader wellness portfolios.
- Families:Multi-generational or parent-child therapeutic configurations addressing systemic relationship patterns.
- Teens:Adolescent clients navigating early romantic relationships and family conflict.
- Seniors:Older adults addressing late-life partnership transitions, caregiving stress, or bereavement.
Adults retain the largest service share, with Families gaining traction through integrated benefits design.
Application:
Customer type differentiation separates acute intervention demand from preventive skill-building markets.
- Conflict Resolution:Structured interventions targeting active relationship distress, infidelity recovery, or dissolution prevention. This application commands the highest per-session rates due to urgency and complexity.
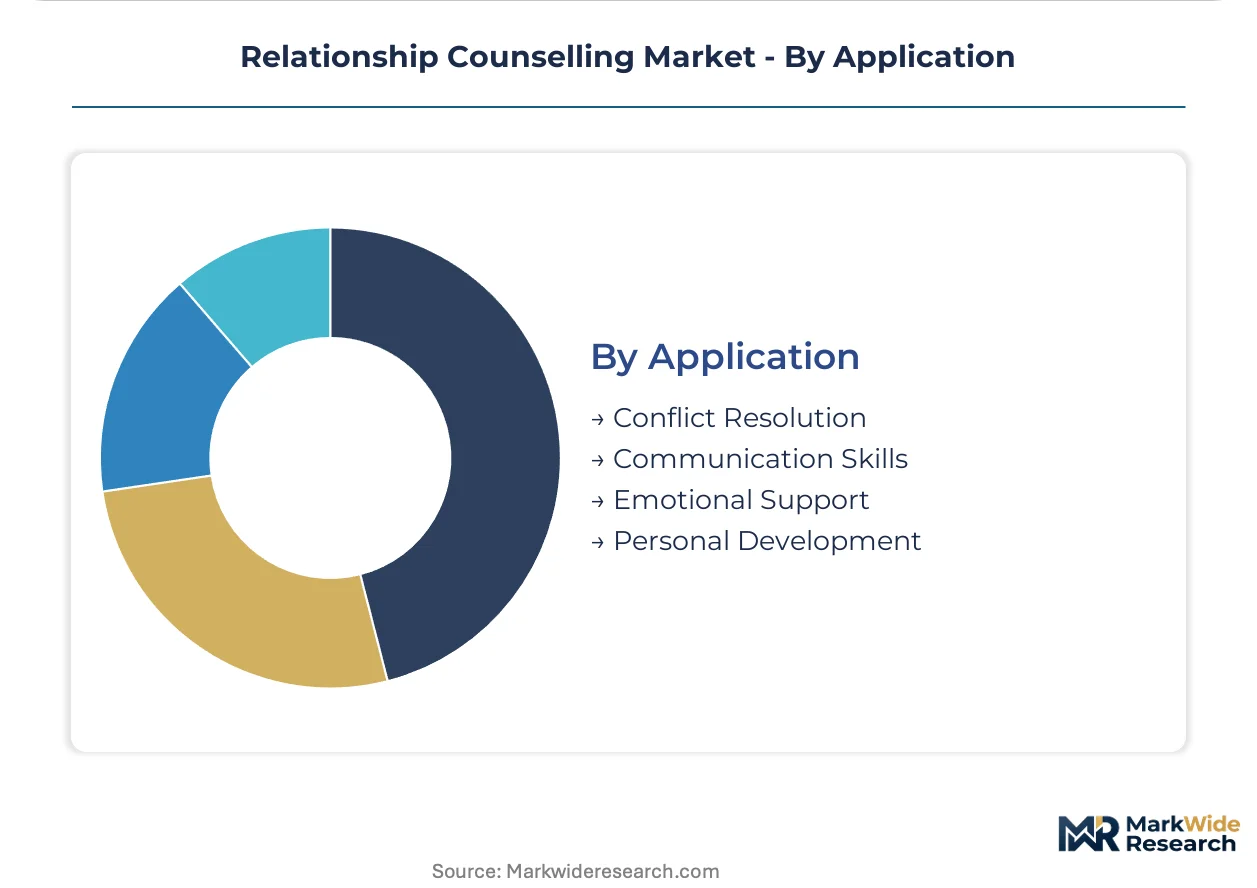
- Communication Skills:Preventive and enhancement-focused training in dialogue techniques, active listening, and negotiation. Younger metropolitan cohorts drive demand here, substituting brief skill-building modules for traditional therapy formats.
- Emotional Support:Sustained therapeutic relationships addressing ongoing mental health needs within partnership contexts.
- Personal Development:Self-improvement oriented work that indirectly benefits relationship functioning.
Conflict Resolution holds the dominant share, while Communication Skills is climbing the fastest as preventive engagement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between employer-sponsored markets where benefits subsidize couples therapy and direct-to-consumer environments where out-of-pocket payment dominates session frequency and modality selection.
United States
Employer-sponsored wellness budgets and HIPAA-aligned telehealth licensing reforms concentrate demand in corporate corridors. State-level professional boards govern cross-border practice, creating compliance overhead that favors multi-state credentialing investments. New York and California employment hubs drive hybrid delivery adoption, blending reimbursable in-person intake with digital maintenance protocols.
Canada
Provincial health plan variations create patchwork coverage for couples therapy, pushing demand toward private pay and employer benefits channels. Health Canada oversight of digital therapeutics shapes platform standards for mood-tracking applications. Toronto and Vancouver metropolitan clusters anchor telehealth platform expansion, serving dispersed rural populations through asynchronous messaging.
Germany
Statutory health insurance reimbursement for couples therapy remains limited, directing commercial activity toward private pay and supplementary insurance markets. BfArM regulation of digital health applications defines approval pathways for algorithmic intervention tools. Berlin and Munich urban centers concentrate clinician supply, while platform operators address East-West service gaps through video delivery.
United Kingdom
NHS Talking Therapies program coverage for relationship counselling varies by integrated care board, fragmenting public access and sustaining private market growth. NICE guidelines influence evidence-based modality selection among accredited practitioners. London and Southeast England dominate practitioner density, with platform operators targeting Midlands and Northern England through remote delivery infrastructure.
Australia
Medicare rebate eligibility for couples therapy hinges on mental health treatment plans, creating administrative friction that platforms address through billing integration. TGA oversight of software-based medical devices applies to diagnostic algorithms embedded in counselling applications. Sydney and Melbourne employment hubs drive corporate wellness program adoption, while Perth and Brisbane expansion addresses interior geographic isolation.
Relationship Counselling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensive platforms commanding subscription infrastructure and algorithmic matching capabilities while clinician-dependent practices retain relationship-intensive service delivery. The competitive terrain separates technology-heavy operators investing in proprietary intake systems from network-based models aggregating licensed practitioners. Two strategic archetypes dominate: direct-to-consumer subscription platforms and enterprise channel specialists embedding services within employer benefits. Competitive moves concentrate on multi-state licensing infrastructure buildout and hybrid protocol development that blends reimbursable in-person sessions with digital maintenance.
Within the platform tier, BetterHelp LLC and Talkspace Inc. exemplify divergent channel strategies, with the former anchoring direct-to-consumer acquisition and the latter representing enterprise partnership models. Amwell Corporation occupies a hybrid position, integrating virtual delivery with in-person network referrals. These three entities collectively illustrate how technology investment, regulatory navigation, and channel selection define competitive positioning in relationship counselling markets.
| Leading Market Players |
|---|
| BetterHelp LLC |
| Talkspace Inc. |
| Amwell Corporation |
| MDLIVE Inc. |
| Calmerry |
| Couples Therapy Inc. |
| Growing Self |
| Regain |
| Lasting |
| Others |
Pricing and Supply Chain Analysis
Subscription-based capacity reservations lock in both clinician supply access and rate visibility for employer-sponsored wellness programs, insulating platforms from spot-market therapist availability swings while compressing margins for pure pay-per-session competitors.
Pricing Analysis
Long-term offtake contracts through corporate employee assistance programs anchor pricing stability for hybrid delivery providers, while direct-to-consumer platforms face spot-market volatility in therapist recruitment costs. Price differentiation hinges on credential tier—licensed marriage and family therapists command premium rates over master's-level counselors—and geographic delivery cost, with urban coastal markets pricing above interior regions. Cost compression in the asynchronous messaging tier intensifies as platforms compete for working adult subscribers through reduced per-session fees. Small private practices exhibit highest price sensitivity due to limited benefits integration, while enterprise channel partners demonstrate lowest sensitivity through embedded wellness budgets.
Supply Chain Analysis
The United States and Canada produce the bulk of credentialed marriage and family therapists, with Australia and the United Kingdom contributing specialist training pipelines for English-language platform expansion. Raw material dependencies center on graduate psychology programs, state licensing board processing capacity, and HIPAA-compliant technology infrastructure. Single-source vulnerability concentrates in multi-state credentialing verification services, where board-specific delays cascade into therapist onboarding bottlenecks. Distribution runs through employer benefits administrators, health plan networks, and direct-to-consumer digital marketing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Relationship counselling sits in early-cycle expansion as employer-sponsored wellness adoption accelerates and telehealth licensing harmonization unlocks cross-border service delivery.
For Market Incumbents: Shield market position by deepening vertical integration into proprietary matching algorithm development and securing exclusive in-person network partnerships in underserved interior states. Regulatory shift toward FTC scrutiny of outcome claims demands defensive investment in clinical validation infrastructure. Channel control through direct-to-employer contracts represents the critical defensive lever against pure-digital entrants. For New Entrants and Emerging Players: Anchor in rural and interior US regions where clinician supply concentration leaves persistent access gaps, and target the preventive communication skills application where younger metropolitan cohorts substitute brief modules for traditional therapy. Corporate channel penetration through benefits administrators offers the most penetrable go-to-market angle, bypassing consumer acquisition cost burdens. For Investors and Strategic Acquirers: Multi-state credentialing infrastructure specialists with hybrid protocol capabilities offer the most compelling acquisition profile for long-term viability across the 5-10 year window. Platform-therapist relationship governance disputes signal inflection risk around employment classification liability. Watch state compact agreement ratification velocity as the primary demand expansion indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Credentialing Infrastructure Buildout | HIPAA-aligned telehealth reforms reduce cross-border practice barriers for licensed therapists. |
| Hybrid Protocol Development | Blending reimbursable in-person intake with digital maintenance captures margin pools unavailable to pure-play competitors. |
| AI-Assisted Intake Triage Deployment | NLP engines automate conflict-pattern identification and compress time-to-first-session from weeks to hours. |
| Corporate Channel Partnership Expansion | Direct-to-employer contracts bypass consumer acquisition costs and reduce churn through embedded benefits. |
| Clinical Validation Investment | FTC enforcement against unsubstantiated efficacy claims demands qualified outcome metrics and disclosed limitations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with platform executives, licensed marriage and family therapists, employer benefits administrators, and health plan contracts managers; and secondary validation against state licensing board filings, HIPAA enforcement actions, FTC advertising guidance documents, and corporate wellness program disclosures. Bottom-up triangulation across therapist supply estimates and top-down reconciliation against employer benefits spending patterns anchored volume and value outputs.
Across the analysis window, the forecasting framework modeled segmentation dimensions including service type, delivery model, client type, and application, with geographic regulatory clusters capturing state-level telehealth compact participation. CAGRs were derived from trend extrapolation of employer-sponsored wellness budget growth and direct-to-consumer subscription adoption curves, cross-referenced against clinician supply pipeline data from accredited graduate programs.
Material uncertainties—state licensing compact ratification delays, FTC enforcement intensity, and platform-therapist classification litigation outcomes—sit outside the modeled envelope. Forecasts reflect assumptions around regulatory harmonization velocity and benefits coverage expansion that could shift materially. Recalibration cycles align with material shifts in state telehealth legislation and employer wellness program design.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Anxiety Disorders and Depression Treatment Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Schizophrenia Market